
 Global Spark Plasma Sintering Market | 2026-2036
Global Spark Plasma Sintering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spark Plasma Sintering Market Foresight
Ultra-high-density specification tiers above 99.5% theoretical density is bifurcating the competitive landscape between premium system builders and mid-range assemblers. Fuji Electric leverages its power electronics heritage to control pulsed-current generator supply chains. FCT Systeme GmbH anchors European demand through precision thermal management engineering. Shanghai Haoyue Furnace Technology competes aggressively on delivery speed for pilot-scale installations across Asian research institutions.
Spark plasma sintering applies pulsed direct current through graphite dies to consolidate powders at temperatures below conventional sintering thresholds, typically achieving full densification in under 30 minutes for ceramics and intermetallics. The technology serves defense, aerospace, and electronics sectors requiring near-net-shape components with minimal grain growth. Lab scale equipment still occupies the widest installed base, though production scale systems are generating the fastest order growth as commercial qualification cycles shorten. Pulsed current technology leads in revenue per unit, while hybrid current architectures are gaining traction where users process alternating ceramic-metal bilayer stacks.
RoHS and REACH compliance in Europe, GB standards enforcement through SAMR in China, and FDA device material qualifications in the United States each tighten traceability requirements on sintered powder feedstocks and die materials. Japan's METI energy-efficiency benchmarks additionally shape generator design specifications for equipment sold into East Asian electronics supply chains. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving powder sourcing rules redraw equipment qualification pathways across major manufacturing jurisdictions.
Market Dynamics
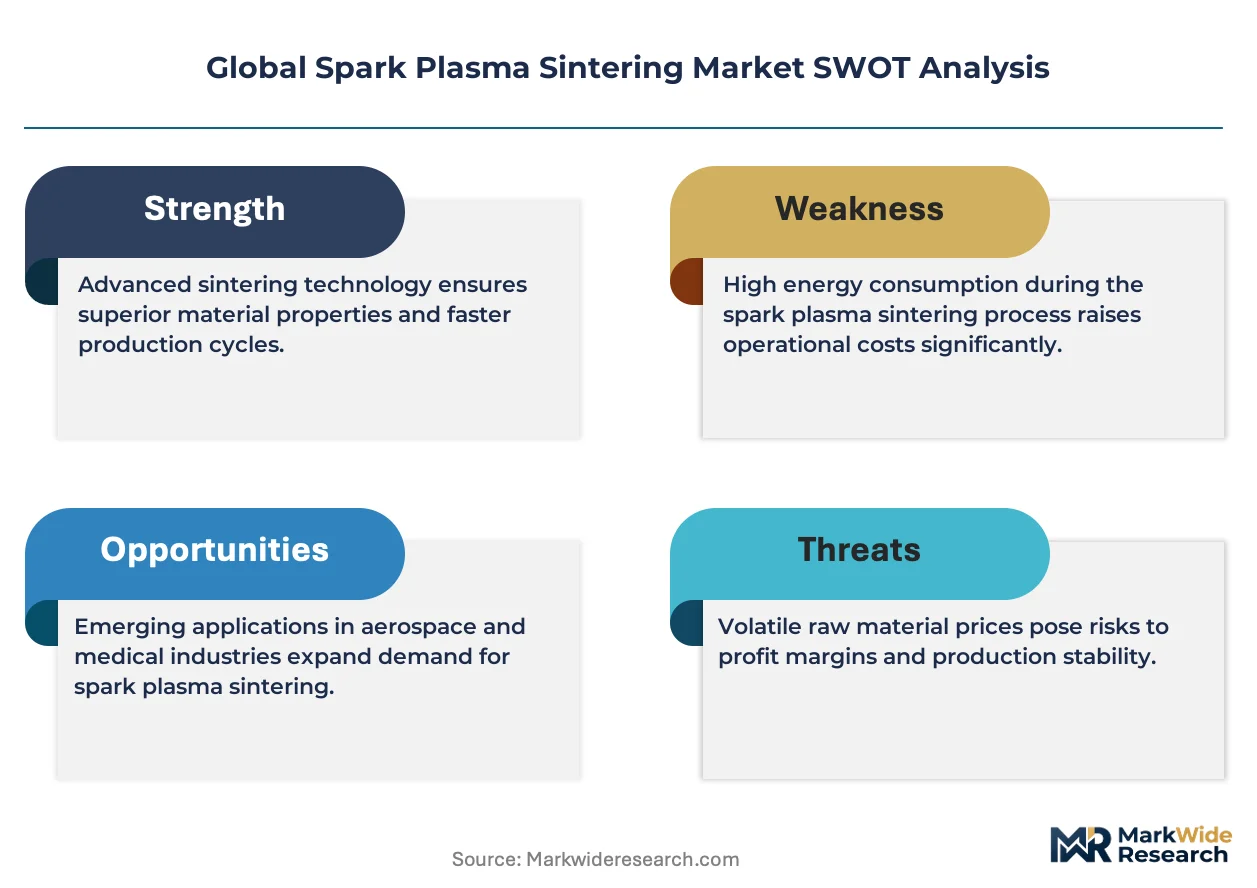
Pulsed-current generator supply chains are consolidating around power electronics specialists, while aerospace fabricators in Germany and Japan drive qualification cycles for turbine blade production. Equipment makers face diverging certification pathways as carbon-border mechanisms and powder traceability rules tighten across manufacturing jurisdictions.
Growth Catalysts
- EU RoHS and REACH material standards:Tightening compliance mandates push manufacturers toward cleaner sintering processes with reduced hazardous substance content.
- Turbine blade production:Aerospace fabricators in Germany and Japan expand procurement of pulsed-current SPS systems for high-temperature alloy consolidation.
- China's eastern manufacturing corridor:Domestic equipment makers displace imported units through faster delivery and localized service networks.
Market Restraints
- Graphite die supply concentration:High-purity graphite sourcing clusters in limited geographies, exposing equipment makers to input cost volatility and export control risks.
- Generator power electronics:IGBT and SiC module supply depends on concentrated semiconductor fabrication capacity, constraining system output scaling.
- Conventional hot isostatic pressing:Established HIP infrastructure in defense supply chains creates substitution friction for SPS qualification.
Strategic Opportunities
- India's defense indigenization:PLI scheme incentives and BIS standards development create entry pathways for production-scale system deployment.
- Solid-state battery electrolyte sintering:Sulfide and oxide ceramic processing demands ultra-rapid densification without grain boundary contamination.
- Hybrid current architectures:Convergence of pulsed DC with programmable AC waveforms enables alternating ceramic-metal bilayer stack processing.
Industry Challenges
- Thermal field simulation expertise:Finite-element modeling of joule heating and spark plasma distribution requires scarce computational materials engineering talent.
- FDA device material qualifications:Extended validation timelines for implantable ceramic components compress commercialization schedules.
- Legacy furnace integration:Retrofitting SPS modules into existing powder metallurgy lines demands custom die handling and atmosphere control adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spark Plasma Sintering Market |
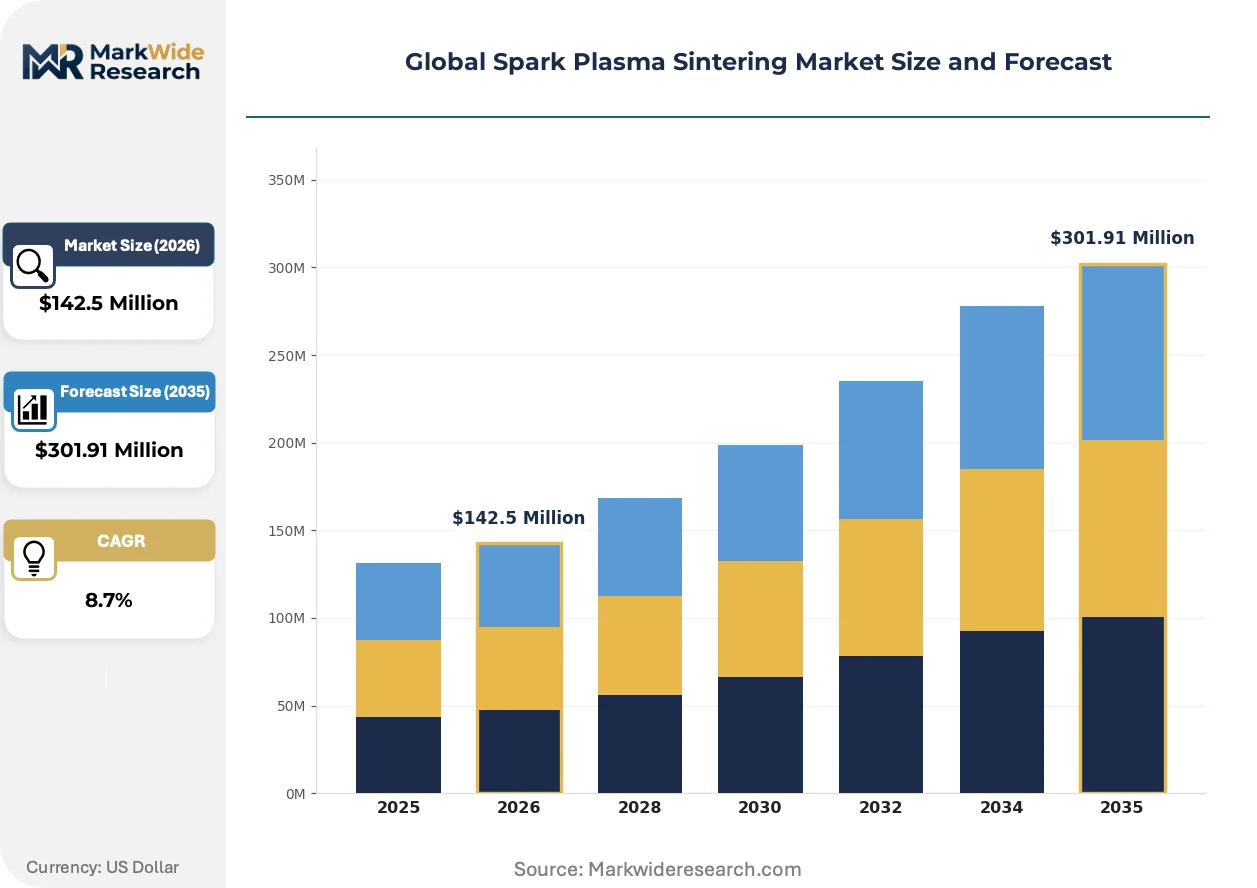
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lab Scale, Pilot Scale, Production Scale, Industrial Scale Technology: Direct Current, Pulsed Current, Alternating Current, Hybrid Current Application: Advanced Ceramics, Metal Matrix Composites, Magnetic Materials, Aerospace Components End User: Research Institutions, Electronics Manufacturers, Aerospace Fabricators, Tooling Companies |
| Companies Covered | Thermal Technology, Fuji Electric, FCT Systeme GmbH, GeniCore, Dr. Fritsch, Shanghai Haoyue Furnace Technology, MTI Corporation, Sintering Technologies, Materials Modification Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spark Plasma Sintering Market Shifts & Advancements
Equipment architecture is bifurcating between premium precision platforms and modular pilot systems, while regulatory pressure on powder traceability reshapes supply chain verification protocols.
Hybrid current SPS architectures is supplanting pure pulsed-DC systems in multi-material processing applications. Research institutions in Japan and South Korea adopt these platforms for functionally graded material development. The technology is supplanting sequential sintering workflows by enabling single-cycle consolidation of dissimilar layers.
China's GB standards enforcement through SAMR tightens powder feedstock documentation requirements for imported sintering equipment. Domestic equipment makers accelerate certification of in-house powder supply chains to maintain market access. European exporters face extended conformity assessment timelines for systems destined for Chinese research institutes.
Equipment procurement is consolidating through multi-year service-embedded contracts rather than discrete capital purchases. Asian research institutions favor vendors offering die refurbishment and powder characterization bundled with system leases. This model is most visible in China's eastern manufacturing corridor, where domestic makers compete on total cost of ownership rather than upfront equipment pricing.
Global Spark Plasma Sintering Market Segmentation
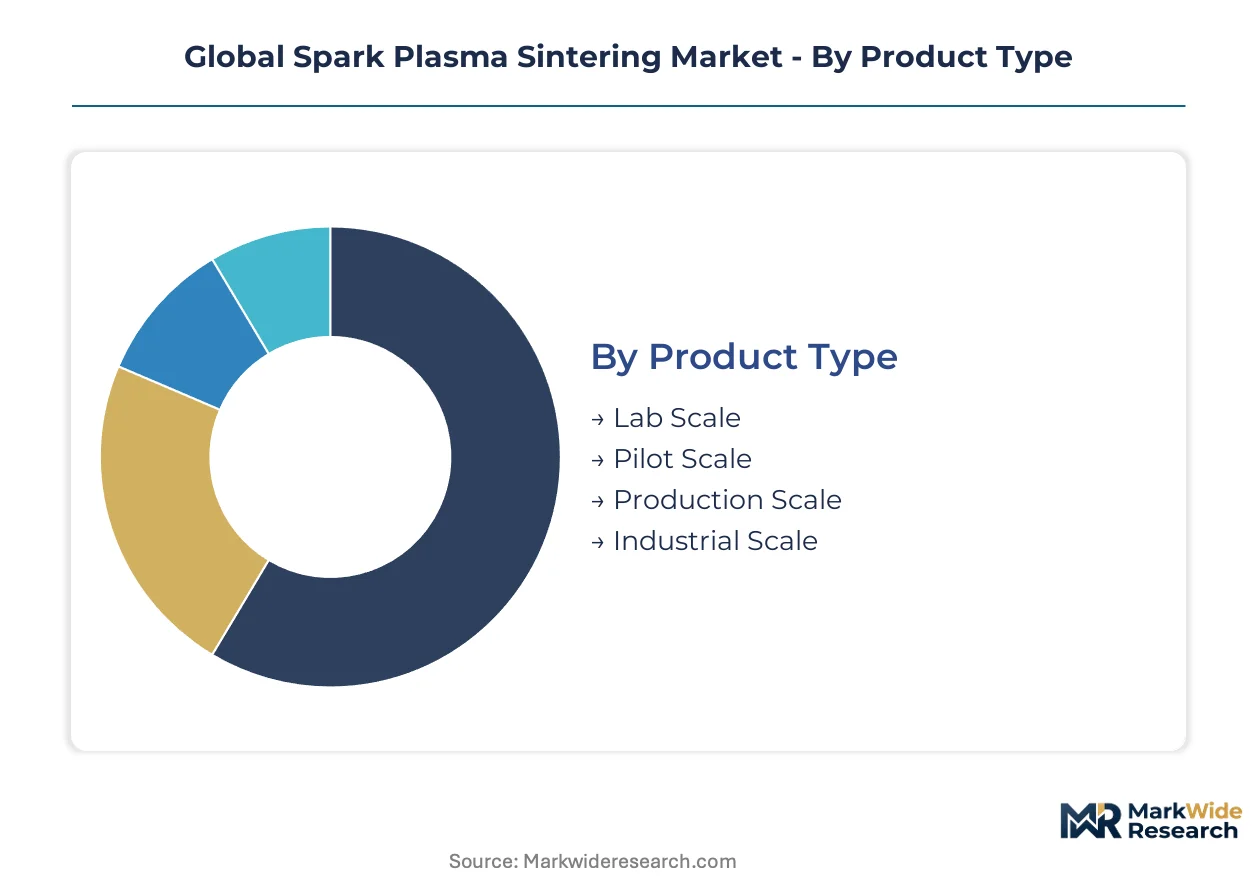
SPS equipment purchasing decisions split sharply between research validation cycles and production throughput requirements. Technology selection and scale configuration determine qualification timelines, maintenance burden, and powder compatibility across defense, aerospace, and electronics supply chains.
Product Type:
Margin pools concentrate in production-scale systems where aerospace fabricators in Germany and Japan pay premiums for thermal uniformity guarantees.
- Lab Scale:Compact units process 10-50mm diameter specimens for material property validation. Research institutions in China's eastern manufacturing corridor drive replacement demand as domestic makers displace imported units through faster delivery.
- Pilot Scale:Intermediate systems bridge proof-of-concept and commercial qualification, typically handling 100-300mm dies. Electronics manufacturers in South Korea deploy these for solid-state battery electrolyte development before committing to production lines.
- Production Scale:High-throughput platforms achieve full densification in under 30 minutes for ceramics and intermetallics. Aerospace fabricators in Germany expand procurement for turbine blade production as pulsed-current generator supply chains consolidate around power electronics specialists.
- Industrial Scale:Continuous-feed architectures integrate with automated powder handling and die refurbishment systems. Tooling companies in Japan leverage these for cemented carbide insert manufacturing under METI energy-efficiency benchmarks.
The dominant share belongs to Lab Scale, while Production Scale is closing the gap fastest.
Technology:
Equipment architecture diverges based on joule heating control precision and multi-material processing flexibility.
- Direct Current:Steady-state DC systems offer simpler generator design and lower capital cost. Research institutions favor these for single-material studies where thermal history repeatability outweighs speed.
- Pulsed Current:Pulsed DC applies intermittent high-current bursts through graphite dies to consolidate powders below conventional sintering thresholds. This architecture leads in revenue per unit as aerospace fabricators in Germany and Japan demand precision thermal management for high-temperature alloy consolidation.
- Alternating Current:AC waveforms reduce electrode degradation in oxide ceramic processing. European equipment makers face extended conformity assessment timelines for these systems destined for Chinese research institutes under SAMR enforcement.
- Hybrid Current:Convergence of pulsed DC with programmable AC waveforms enables single-cycle consolidation of ceramic-metal bilayer stacks. Research institutions in Japan and South Korea adopt these platforms for functionally graded material development, supplanting sequential sintering workflows.
Pulsed Current commands the installed base, though Hybrid Current is gaining share fastest.
Application:
End-use specifications drive die material selection, atmosphere control, and cooling rate programming.
- Advanced Ceramics:Oxide and non-oxide ceramics require ultra-rapid densification without grain boundary contamination. Solid-state battery electrolyte sintering for sulfide and oxide ceramics concentrates demand in South Korea and Japan.
- Metal Matrix Composites:Reinforced aluminum and titanium alloys serve aerospace weight reduction targets. Tooling companies in Germany process these for cutting insert substrates under REACH material standards.
- Magnetic Materials:Rare-earth permanent magnets and soft magnetic composites demand precise grain boundary control. Electronics manufacturers in China's eastern manufacturing corridor scale production for electric drivetrain applications.
- Aerospace Components:Near-net-shape turbine blades and structural brackets require 99.5%+ theoretical density with minimal grain growth. Fabricators in Japan qualify these under METI benchmarks for East Asian electronics supply chains.
Aerospace Components holds the premium tier, while Advanced Ceramics is expanding most quickly.
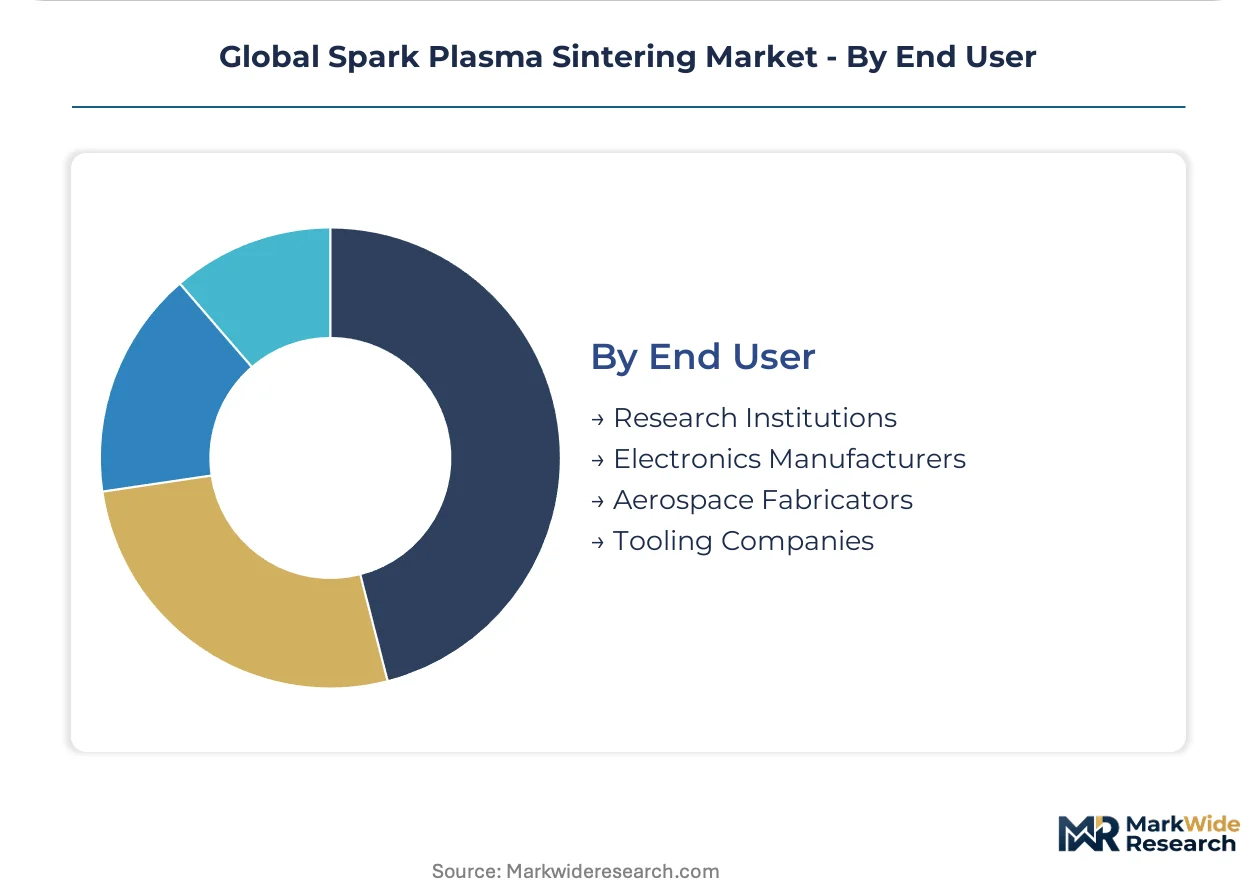
End User:
Procurement models separate capital purchase from service-embedded contracts based on utilization intensity.
- Research Institutions:Universities and national labs prioritize flexibility over throughput. Asian research institutions favor vendors offering die refurbishment and powder characterization bundled with system leases.
- Electronics Manufacturers:Solid-state battery and semiconductor packaging applications demand contamination-free sintering. These users drive hybrid current adoption for ceramic-metal bilayer processing.
- Aerospace Fabricators:Turbine blade production requires qualification cycles spanning multiple years. These stakeholders face diverging certification pathways as carbon-border mechanisms tighten across manufacturing jurisdictions.
- Tooling Companies:Cemented carbide and cermet insert manufacturing values thermal cycle speed. These users concentrate in Germany and Japan where graphite die supply chains face export control risks.
Research Institutions dominate unit volume, though Aerospace Fabricators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics fabrication for SPS generators clusters in Japan and Germany, while equipment assembly concentrates in China's eastern corridor. Demand dispersion follows aerospace qualification hubs and solid-state battery research clusters across three continents.
Germany
Aerospace fabricators in Bavaria and Baden-Württemberg drive pulsed-current system procurement for turbine blade densification. ECHA REACH enforcement tightens graphite die material documentation requirements. The Stuttgart industrial corridor anchors European precision thermal management engineering for high-temperature alloy processing.
Japan
Electronics manufacturers in the Kanto region scale hybrid current adoption for ceramic-metal bilayer stack development. METI energy-efficiency benchmarks shape generator design specifications for equipment sold into East Asian supply chains. Tooling companies in Nagoya deploy industrial-scale systems for cemented carbide insert manufacturing.
China
Solid-state battery electrolyte research concentrates demand in Shanghai and Suzhou research institutes. SAMR GB standards enforcement tightens powder feedstock traceability for imported equipment. Domestic equipment makers in the Yangtze River Delta displace foreign units through faster delivery and localized die refurbishment services.
United States
Defense contractors qualify production-scale systems for near-net-shape intermetallic components under extended procurement cycles. FDA device material requirements compress commercialization timelines for implantable ceramic manufacturers. Research institutions in Greater Boston and the Pacific Northwest favor service-embedded contracts bundling powder characterization with system access.
South Korea
Battery material developers in the Seoul Capital Area pilot sulfide ceramic sintering for solid-state electrolyte applications. National research programs accelerate functionally graded material development through hybrid current platform adoption. Daegu-Gyeongbuk electronics clusters drive contamination-free processing specifications for semiconductor packaging applications.
Global Spark Plasma Sintering Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Premium system builders compete on thermal uniformity guarantees and qualification support, while mid-range assemblers compete on delivery speed and localized service networks. Three archetypes dominate: power electronics specialists controlling generator supply chains, precision thermal engineering firms anchoring regional demand, and domestic equipment makers leveraging geographic proximity. Consolidation pulses through strategic partnerships between generator suppliers and system integrators, alongside capacity expansion in China's eastern manufacturing corridor.
Among power electronics heritage firms, Fuji Electric exemplifies the technology-control archetype through its pulsed-current generator positioning. FCT Systeme GmbH represents the precision-engineering tier anchored in European aerospace supply chains. Shanghai Haoyue Furnace Technology occupies the rapid-delivery position competing aggressively on pilot-scale installation timelines across Asian research institutions.
| Leading Market Players |
|---|
| Thermal Technology |
| Fuji Electric |
| FCT Systeme GmbH |
| GeniCore |
| Dr. Fritsch |
| Shanghai Haoyue Furnace Technology |
| MTI Corporation |
| Sintering Technologies |
| Materials Modification Inc. |
| Others |
Supply & Pricing Matrix
Production-scale system utilization rates above 80 percent anchor price floors for pulsed-current generators, concentrating margin power with Fuji Electric and power electronics specialists while forcing mid-range assemblers toward service-embedded contract structures to defend viability.
Pricing Analysis
EU REACH dictates the pricing tier structure across European aerospace fabricators, separating premium thermal uniformity guarantees from standard qualification support tiers. Price differentiation rests on METI energy-efficiency certification grade and graphite die refurbishment bundling. Cost compression in pilot-scale segments is intensifying because domestic Chinese makers displace imported units through faster delivery. Research institutions in Asia exhibit highest price sensitivity; aerospace fabricators in Germany and Japan show lowest.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European equipment makers sourcing IGBT modules from East Asian semiconductor fabs. High-purity graphite concentrates in China, Japan, and Germany; SiC power electronics and pulsed-current generators draw from Japanese and German fabrication clusters. Single-source vulnerability in isostatic graphite exposes tooling companies to export control risks. Distribution runs through direct OEM relationships and multi-year service-embedded contracts rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finite-element modeling expertise for joule heating simulation represents the critical capability gap, with fewer than two hundred qualified computational materials engineers available globally to support thermal field optimization for production-scale deployments.
For Market Incumbents: Compound generator supply chain control through backward integration into SiC module fabrication or exclusive foundry partnerships, while accelerating METI certification investment to lock out mid-range competitors from East Asian electronics supply chains threatened by hybrid current platform displacement. For New Entrants and Emerging Players: Differentiate on solid-state battery electrolyte sintering application expertise, targeting South Korean and Japanese research institutions with contamination-free processing guarantees as the most penetrable segment; pursue powder characterization bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Power electronics heritage firms with captive generator design capability offer the strongest long-term viability framing across the analysis window; monitor solid-state battery commercialization timelines as the critical inflection signal for production-scale equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Module Fabrication | Captive semiconductor supply secures pulsed-current generator output scaling against foundry allocation constraints. |
| Hybrid Current Platform Launch | Single-cycle ceramic-metal bilayer processing displaces sequential sintering workflows in Japanese research institutions. |
| Die Refurbishment Service Embedding | Asian research institutions favor total cost of ownership models over upfront equipment capital expenditure. |
| REACH Certification Fast-Track | Accelerated graphite die material documentation unlocks European aerospace fabricator procurement cycles. |
| Solid-State Battery Application Partnership | Sulfide ceramic sintering expertise captures emerging demand from South Korean electrolyte developers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with SPS equipment procurement managers, thermal engineering directors, and powder metallurgy R&D leads; and secondary validation through SAMR GB standards filings, METI energy-efficiency benchmark disclosures, and aerospace supplier qualification databases. Bottom-up equipment shipment tallies triangulated against top-down end-use demand estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by system scale, current architecture, and end-use qualification intensity, with CAGRs derived from equipment order pipeline analysis and replacement cycle assumptions. Forecast inputs incorporated carbon-border mechanism implementation timelines and solid-state battery commercialization readiness indicators.
Decision-makers should treat outputs as directional under base assumptions of stable semiconductor fabrication capacity and continued EU REACH enforcement; material deviation in graphite export controls or pulsed-current generator supply would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Mask Alignment Lithography Market