
 Global Semiconductor Machinery Market | 2026-2036
Global Semiconductor Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Machinery Market Outlook
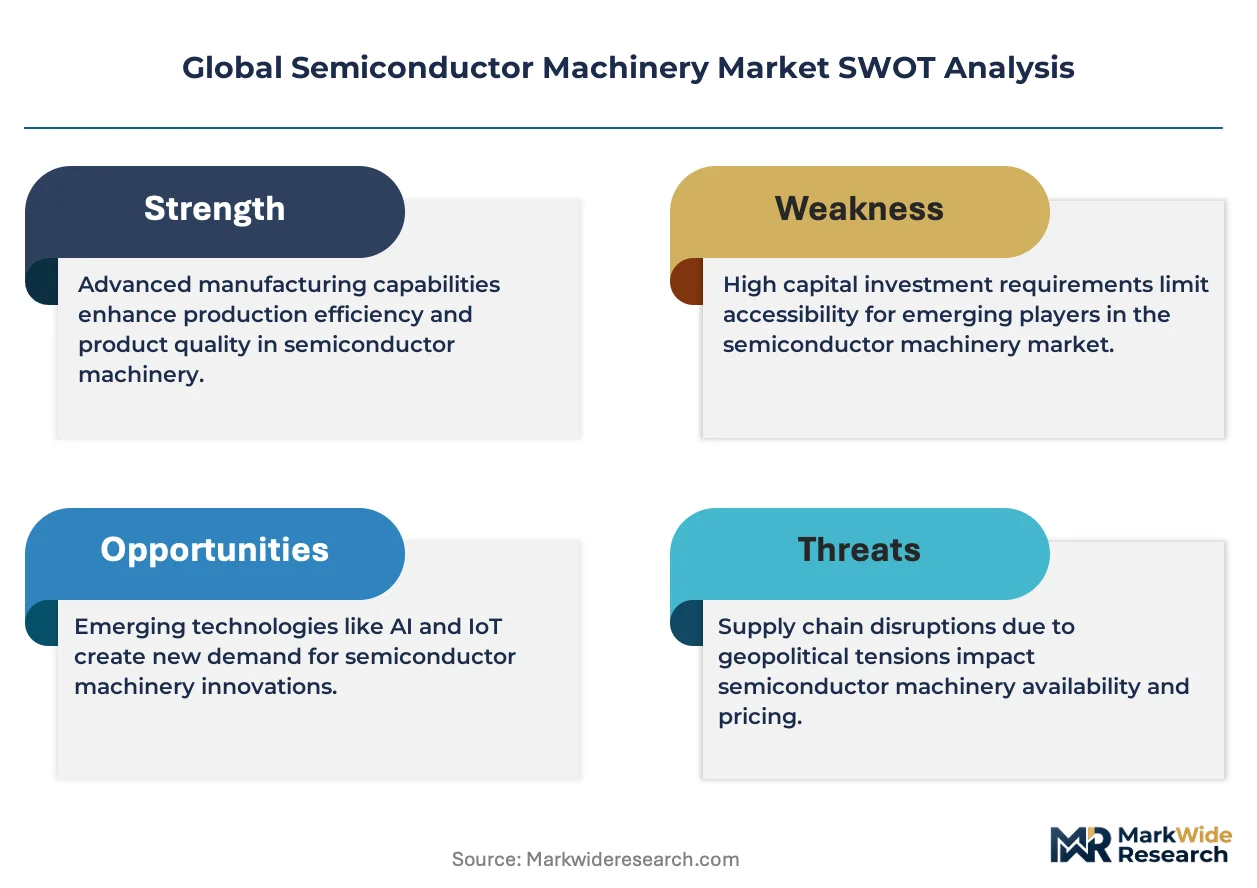
Gallium nitride is pivoting into power electronics applications, displacing silicon in high-frequency and high-voltage contexts where thermal efficiency governs total cost of ownership. Applied Materials leverages its process technology breadth to anchor deposition and etch tool franchises across logic and memory fabs. ASML dominates photolithography with extreme ultraviolet systems that sustain its unmatched position at the leading edge of patterning resolution.
Semiconductor machinery encompasses the capital equipment used to manufacture integrated circuits, spanning processes that operate at nanometer-scale precision with ambient contamination controlled to Class 1 cleanroom standards. This equipment enables the sequential layering, patterning, doping, and metrology steps that transform silicon wafers into functional chips for electronic systems. Wafer fabrication equipment captures the dominant share of capital intensity, with deposition and etching tools representing margin-rich segments where process complexity creates durable supplier relationships. Photolithography systems command premium pricing structures due to their criticality in determining transistor density, while testing equipment segments expand as heterogeneous integration raises quality assurance burdens.
The EU Chips Act, the U.S. CHIPS and Science Act, and Japan's METI semiconductor subsidies are reshaping where fabs locate and which equipment vendors gain preferential access. REACH and RoHS frameworks in Europe constrain material choices in machinery construction and fab chemistry, pushing vendors toward compliant process chemistries. Stakeholders must monitor how subsidy disbursement timelines interact with equipment delivery cycles, as mismatches between fab readiness and tool availability will determine which regional buildouts achieve planned production ramps.
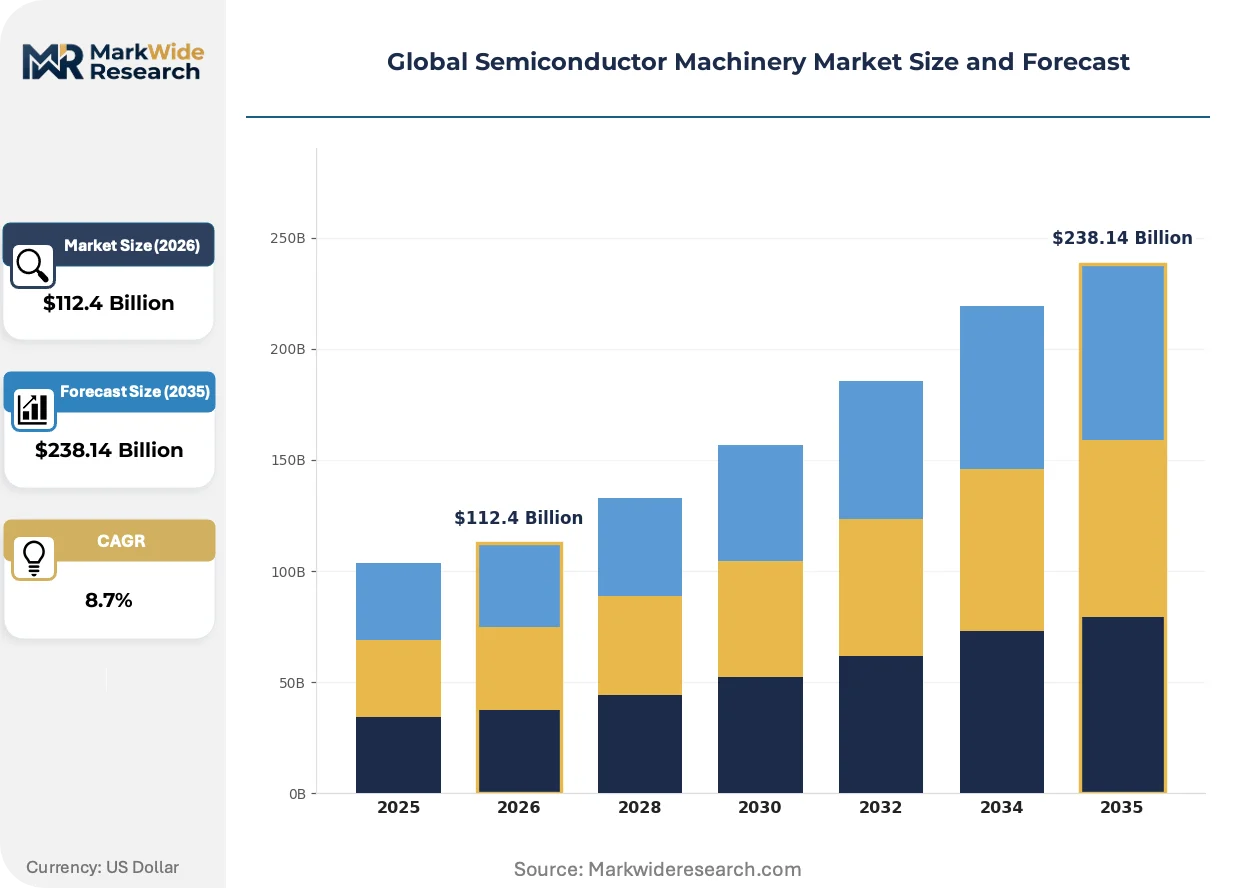
Market Dynamics
Extreme ultraviolet lithography adoption is compressing equipment procurement cycles as foundries race to secure ASML's limited system output, creating a structural bottleneck that ripples through deposition, etch, and metrology tool demand.
Growth Catalysts
- Subsidized Fab Construction:The U.S. CHIPS and Science Act and EU Chips Act are redirecting capital toward domestic wafer fabrication, expanding the installed base of equipment-requiring facilities across multiple continents.
- Heterogeneous Integration:Advanced packaging architectures for AI accelerators and high-bandwidth memory are multiplying process steps per wafer, extending tool utilization rates in packaging-specific equipment segments.
- Silicon Carbide Transition:Automotive power electronics manufacturers are qualifying 200mm SiC production lines, opening new equipment demand outside traditional silicon logic and memory fabs.
Market Restraints
- Neon Gas Supply Concentration:Ukrainian neon purification infrastructure disruption has exposed lithography laser supply vulnerability, forcing fabs to absorb input cost volatility or qualify alternative sourcing.
- Extreme UV System Monopoly:Single-source dependency on Dutch lithography technology creates procurement queue risk that extends lead times beyond planned fab readiness dates.
- REACH Chemical Restrictions:European regulatory constraints on per- and polyfluoroalkyl substances are forcing equipment redesigns for compliant process chemistries in etch and clean applications.
Strategic Opportunities
- India Semiconductor Mission:Central government production-linked incentives for display and fab ecosystems are creating first-mover equipment positioning opportunities in an underpenetrated geography.
- Atomic Layer Deposition Expansion:Gate-all-around transistor architectures are converging with 3D NAND string stacking to multiply ALD chamber intensity per wafer start.
- Metrology Unbundling:Foundries are separating process control tool procurement from integrated platform deals, opening independent sales channels for specialized inspection vendors.
Industry Challenges
- Cleanroom Construction Bottlenecks:Specialized contracting capacity for Class 1 fab shells is lagging equipment delivery schedules, creating site-readiness mismatches that delay revenue recognition.
- Process Engineer Scarcity:Advanced node expertise concentration in Taiwan and South Korea is constraining talent availability for greenfield fab staffing in the United States and Germany.
- Legacy Tool Integration:Brownfield capacity expansions require protocol bridging between 300mm systems and existing 200mm infrastructure, complicating automation architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Machinery Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $238.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer Fabrication Equipment, Assembly Equipment, Packaging Equipment, Testing Equipment Technology: Photolithography, Etching, Deposition, Cleaning End User: Foundries, IDMs, Fabless Companies, Outsourced Semiconductor Assembly Application: Consumer Electronics, Automotive, Telecommunications, Industrial |
| Companies Covered | Applied Materials, ASML, Lam Research, Tokyo Electron, KLA Corporation, SCREEN Holdings, Advantest, ASM International, Hitachi High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Machinery Market Strategic Shifts
Equipment intelligence layers and predictive maintenance architectures are reshaping how fabs negotiate service contracts and uptime guarantees. Process-tool data integration is becoming a competitive differentiator separate from hardware specifications.
Hybrid bonding technology is converging with wafer-to-wafer alignment systems to enable sub-micron pitch 3D stacking for memory-on-logic configurations. DRAM and NAND manufacturers are accelerating adoption timelines to capture AI workload bandwidth requirements. This convergence is compressing the traditional separation between front-end and back-end equipment vendor territories.
EPA fluorinated greenhouse gas regulations are tightening reporting requirements for etch chamber emissions, forcing equipment suppliers to integrate abatement systems as standard configuration rather than optional add-on. Fab operators in the United States face compliance timelines that accelerate replacement cycles for unabated legacy tools. Memory manufacturers with high etch-intensity processes are absorbing the largest compliance cost burdens.
Buying consortium formation among second-tier foundries is consolidating negotiation leverage against equipment vendors, displacing bilateral procurement relationships that dominated prior capex cycles. These pooled purchasing arrangements are emerging most visibly among European automotive-focused fabs seeking to match East Asian volume discounts. The shift is compressing pricing transparency and fragmenting vendor account management structures.
Global Semiconductor Machinery Market Segmentation
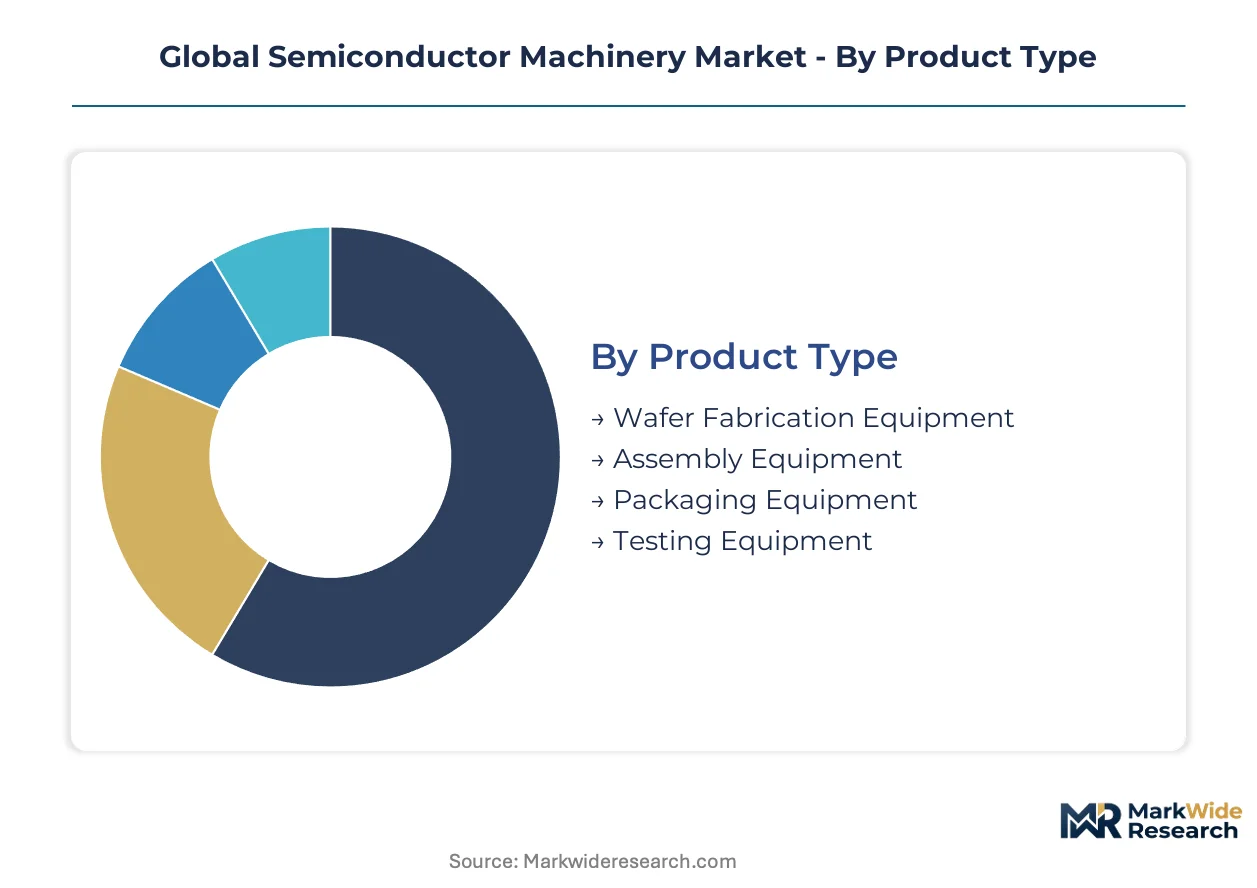
Segmentation in semiconductor machinery reveals how capital intensity concentrates across process steps and how subsidy-driven fab buildouts are reshaping customer composition. Equipment vendors calibrate platform development and service architectures around these divisions.
Product Type:
Technology sophistication and chamber utilization rates vary sharply across the process flow, with front-end systems commanding multiples of back-end equipment pricing.
- Wafer Fabrication Equipment:Lithography, deposition, and etch systems operating at sub-nanometer precision dominate capital expenditure budgets. Foundries in Taiwan and South Korea are expanding EUV procurement cycles, compressing delivery timelines for complementary tools.
- Testing Equipment:Parametric and functional verification systems multiply as heterogeneous integration raises defect detection burdens. Automotive qualification protocols in Germany and Japan are extending test coverage requirements.
- Assembly Equipment:Die bonding and wire bonding platforms bridge front-end wafer processing with packaged device output.
- Packaging Equipment:Flip-chip and fan-out wafer-level packaging tools serve advanced substrate configurations.
Mature deployment sits with wafer fabrication equipment. Newer deployment is concentrated in testing equipment.
Technology:
Process complexity and pattern resolution requirements create divergent supplier concentration profiles across the four core technology domains.
- Photolithography:Extreme ultraviolet and deep ultraviolet systems pattern transistor geometries with single-source dependency on Dutch equipment architecture. ASML's output constraints are extending lead times for logic foundries in the United States and Germany.
- Deposition:Chemical vapor deposition and atomic layer deposition systems build conductive and dielectric films with angstrom-level thickness control. Gate-all-around transistor adoption is multiplying chamber intensity per wafer start.
- Etching:Plasma and wet etch systems remove material selectively between patterned layers.
- Cleaning:Wet bench and single-wafer clean tools remove particulate and chemical contamination between process steps.
Photolithography commands the steepest expansion trajectory as foundries race to secure limited EUV system output.
End User:
Procurement scale and specification authority concentrate differently across organizational models, with capital intensity varying by vertical integration depth.
- Foundries:Merchant wafer manufacturers operating at leading-edge nodes drive the largest equipment procurement volumes. Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding EUV fleet sizes to serve AI accelerator demand.
- IDMs:Integrated device manufacturers retain captive fabrication for differentiated process technologies. Memory IDMs in South Korea are qualifying 200mm silicon carbide lines for automotive power electronics.
- Fabless Companies:Design houses without fabrication assets specify equipment indirectly through foundry partnerships.
- Outsourced Semiconductor Assembly:OSAT providers procure packaging and test equipment to serve multiple fabless customers.
IDMs maintain the deepest installed base. Foundries are gaining share fastest as fabless design proliferation accelerates.
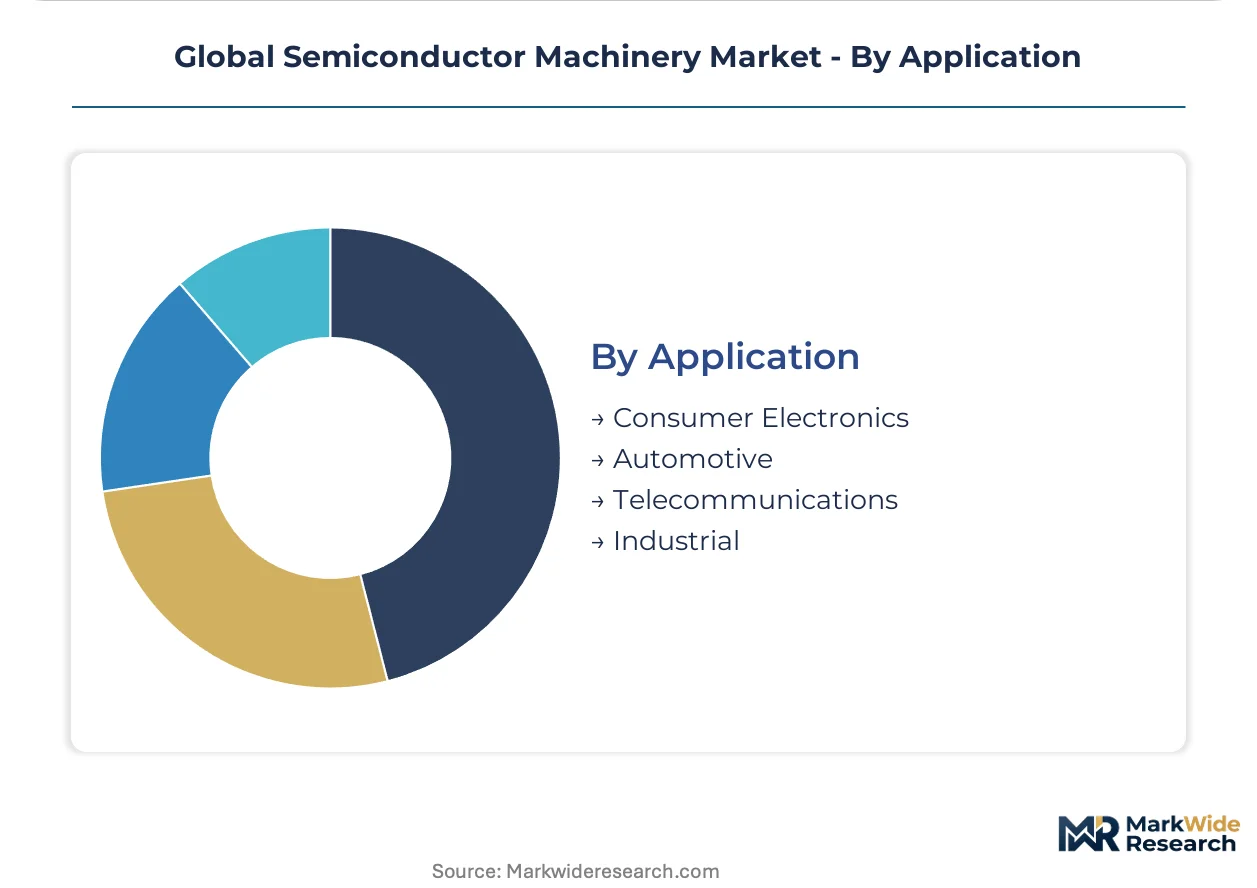
Application:
End-market demand volatility and qualification timelines create divergent equipment utilization profiles across application segments.
- Consumer Electronics:Smartphone and personal computing devices drive high-volume demand for advanced logic and memory. Seasonal demand patterns in this segment create capacity planning challenges for foundry equipment procurement.
- Automotive:Electric vehicle powertrains and advanced driver assistance systems are expanding silicon carbide and sensor chip requirements. EPA emissions regulations are accelerating etch tool abatement system mandates.
- Telecommunications:5G baseband and radio frequency components sustain specialty process equipment demand.
- Industrial:Factory automation and power management applications support mature node equipment utilization.
Consumer electronics anchors current equipment utilization. Automotive is expanding most quickly as electrification multiplies semiconductor content per vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in East Asian manufacturing clusters, with Taiwan and South Korea hosting the densest concentrations of leading-edge foundry capacity. The United States and Germany are accelerating greenfield buildouts as industrial policy redirects capital flows.
United States
CHIPS and Science Act subsidies are unlocking capital for domestic wafer fabrication in Arizona, Texas, and New York. EPA fluorinated greenhouse gas regulations are tightening etch chamber emissions standards, forcing equipment upgrades. The Phoenix-Tucson corridor is attracting multi-billion dollar fab investments from Taiwan Semiconductor Manufacturing and Intel.
Germany
Automotive electrification is driving silicon carbide qualification timelines for power electronics manufacturing. The EU Chips Act is channeling state aid toward Dresden and Magdeburg fab complexes. Saxony's Silicon Saxony cluster anchors Europe's deepest semiconductor equipment supplier ecosystem outside Asia.
South Korea
Samsung Foundry and SK Hynix are expanding EUV fleet sizes to serve AI accelerator and high-bandwidth memory demand. METI-aligned industrial policy supports equipment localization initiatives. The Pyeongtaek-Suwon corridor hosts the world's most concentrated deposition and etch tool installed base.
Japan
Materials and component suppliers are qualifying alternative neon gas sources following Ukrainian supply disruption. METI semiconductor subsidies are accelerating 2-nanometer R&D consortia in Kumamoto and Hokkaido. The Nagoya-Toyota industrial corridor is integrating automotive power electronics with captive fab capacity.
India
Central government production-linked incentives are creating first-mover equipment positioning opportunities in Gujarat and Karnataka. BIS standards alignment is streamlining import certification for deposition and metrology tools. The Dholera Special Investment Region is attracting display and fab ecosystem anchor tenants.
Global Semiconductor Machinery Market Competitive Environment
Capacity expansion dominates the current landscape as foundries race to secure ASML's limited EUV system output. The market exhibits tiered concentration: lithography systems command single-source dependency, while deposition and etch tools sustain oligopolistic competition among three to four platform vendors. Two strategic archetypes prevail: full-flow platform providers spanning multiple process steps, and point-solution specialists dominating single critical technologies. M&A activity and strategic partnerships represent the dominant competitive moves as vendors seek to fill portfolio gaps in advanced packaging and metrology.
Within the platform-provider tier, Applied Materials and Lam Research exemplify full-flow breadth across deposition and etch segments. ASML occupies a singular position as the exclusive EUV lithography supplier. Tokyo Electron represents the Japanese archetype of materials-engineering depth combined with geographic diversification into Asian manufacturing clusters.
| Leading Market Players |
|---|
| Applied Materials |
| ASML |
| Lam Research |
| Tokyo Electron |
| KLA Corporation |
| SCREEN Holdings |
| Advantest |
| ASM International |
| Hitachi High-Tech |
| Others |
Value Chain & Pricing Dynamics
Extreme ultraviolet lithography adoption is compressing equipment procurement cycles as foundries race to secure ASML's limited system output, simultaneously reshaping cost economics for complementary deposition and etch tools while concentrating supply-side power among Dutch lithography architecture holders.
Pricing Analysis
Volume buyers in Taiwan and South Korea command steep discounts through multi-system fleet purchases, while smaller European automotive-focused fabs absorb premium pricing due to fragmented procurement scale. Price differentiation rests on chamber utilization guarantees and predictive maintenance bundling. Cost compression in mature 200mm tool segments is intensifying because buying consortiums are consolidating negotiation leverage. Fabless companies specifying equipment through foundry partnerships exhibit the lowest direct price sensitivity, whereas second-tier IDMs face acute margin pressure from legacy tool refresh cycles.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale buyer demand for EUV systems, while regional distributors serve smaller IDM and OSAT procurement. Manufacturing concentrates in the Netherlands for lithography, the United States for deposition platforms, and Japan for materials-engineering components. Raw material dependencies include neon gas from Ukrainian purification infrastructure, high-purity fluoropolymers for chamber construction, and specialized ceramic components for plasma etch systems. Single-source vulnerability on Dutch lithography technology creates procurement queue risk. Distribution runs through equipment vendor direct sales teams with localized service engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor machinery sector is navigating a technology-transition phase as gate-all-around transistor architectures displace finFET designs, multiplying atomic layer deposition chamber intensity per wafer start and reconfiguring vendor competitive positioning.
For Market Incumbents: Acquire specialized metrology capabilities to capture unbundled process control procurement separating from integrated platform deals. Defend against emerging point-solution specialists by embedding predictive maintenance intelligence layers that raise switching costs. Capacity addition in India through Gujarat and Karnataka fab buildouts anchors long-term service revenue streams. For New Entrants and Emerging Players: The EU Chips Act in Germany opens a window for packaging equipment specialists to establish anchor positions in Dresden and Magdeburg automotive-electronics corridors. White-space targets include hybrid bonding alignment systems for memory-on-logic configurations and abatement-integrated etch tools for EPA-compliant U.S. fabs. A technical partnership with established materials suppliers accelerates qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-flow platform providers seeking to fill advanced packaging portfolio gaps. Long-term viability favors vendors with installed base density in AI accelerator supply chains. The signal to watch is foundry capital expenditure guidance revisions following ASML delivery confirmation delays.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Applied Materials' metrology expansion captures unbundled process control procurement from integrated lithography platforms. |
| Joint Venture | Tokyo Electron's materials-engineering partnerships with South Korean memory IDMs accelerate gate-all-around qualification. |
| Geographic Expansion | Lam Research's India service infrastructure buildout secures first-mover positioning in Gujarat's Dholera Special Investment Region. |
| Product Launch | ASML's high-NA EUV system introduction extends patterning resolution leadership for 2-nanometer logic nodes. |
| Long-term Supply Agreement | Neon gas sourcing contracts with Japanese materials suppliers mitigate Ukrainian purification infrastructure disruption risk. |
Study Parameters
Multi-period observation of foundry capital expenditure cycles, equipment delivery lead times, and process node transition timelines anchored the trend analysis, supplemented by interviews with fab engineering directors, equipment procurement managers, process technology specialists, and aftermarket service heads. Primary fieldwork combined with secondary validation drawing from SEMI equipment market data, SEC 10-K filings, customs import records for lithography systems, and foundry earnings call disclosures. Bottom-up equipment unit forecasts triangulated against top-down wafer capacity expansion projections.
Input-output matrices mapped wafer start growth to chamber intensity requirements across deposition, etch, and metrology segments, with outputs calibrated to technology node-specific equipment mix assumptions. Segmentation dimensions modeled include product type, process technology, end-user organizational model, application vertical, and regional fab buildout cluster. CAGRs were derived from equipment procurement cycle analysis and subsidy disbursement timeline alignment. Forecast inputs incorporated ASML system output constraints, cleanroom construction capacity bottlenecks, and process engineer availability for greenfield fab staffing.
The model assumes a particular technology adoption path; alternative pathways for high-NA EUV or directed self-assembly patterning would alter the outlook for complementary tool demand. Forecasts reflect documented assumptions regarding subsidy disbursement schedules and equipment delivery cycle synchronization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Plasma Etching Equipment Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Reticle Pod Cleaning System Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Wafer Processing Equipment Market