
 Semiconductor Foundry Market | 2026-2036
Semiconductor Foundry Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Foundry Market Intelligence
Taiwanese leading-edge capacity is hardening into the industry's most contested resource as governments compete to localize supply. Taiwan Semiconductor Manufacturing Company anchors the most advanced process nodes, sustaining R&D intensity that outpaces most national semiconductor budgets. Samsung Electronics leverages its memory-to-logic integration to compete for high-performance computing contracts, while Intel Corporation positions its IDM 2.0 strategy to regain process leadership through in-house and foundry production.
A semiconductor foundry operates dedicated fabrication facilities that manufacture integrated circuits on silicon wafers using photolithography, etching, and deposition processes at node sizes ranging from legacy 45nm to advanced 10nm and below, serving fabless chip designers without captive manufacturing. Wafer fabrication commands the largest value pool, though packaging services are gaining structural importance as chiplet architectures and 3D stacking proliferate. The 28nm technology node occupies a sweet spot for automotive and industrial applications, balancing performance with mature yield curves.
The EU Chips Act, US CHIPS and Science Act, and Japan's METI semiconductor subsidies are reshaping where capacity gets built and which firms qualify for capital grants. REACH and RoHS frameworks in Europe constrain material inputs and waste protocols, affecting process chemistry choices and equipment sourcing. Stakeholders must weigh sovereign incentive structures against established cluster ecosystems when siting new fabrication investments.
Market Dynamics
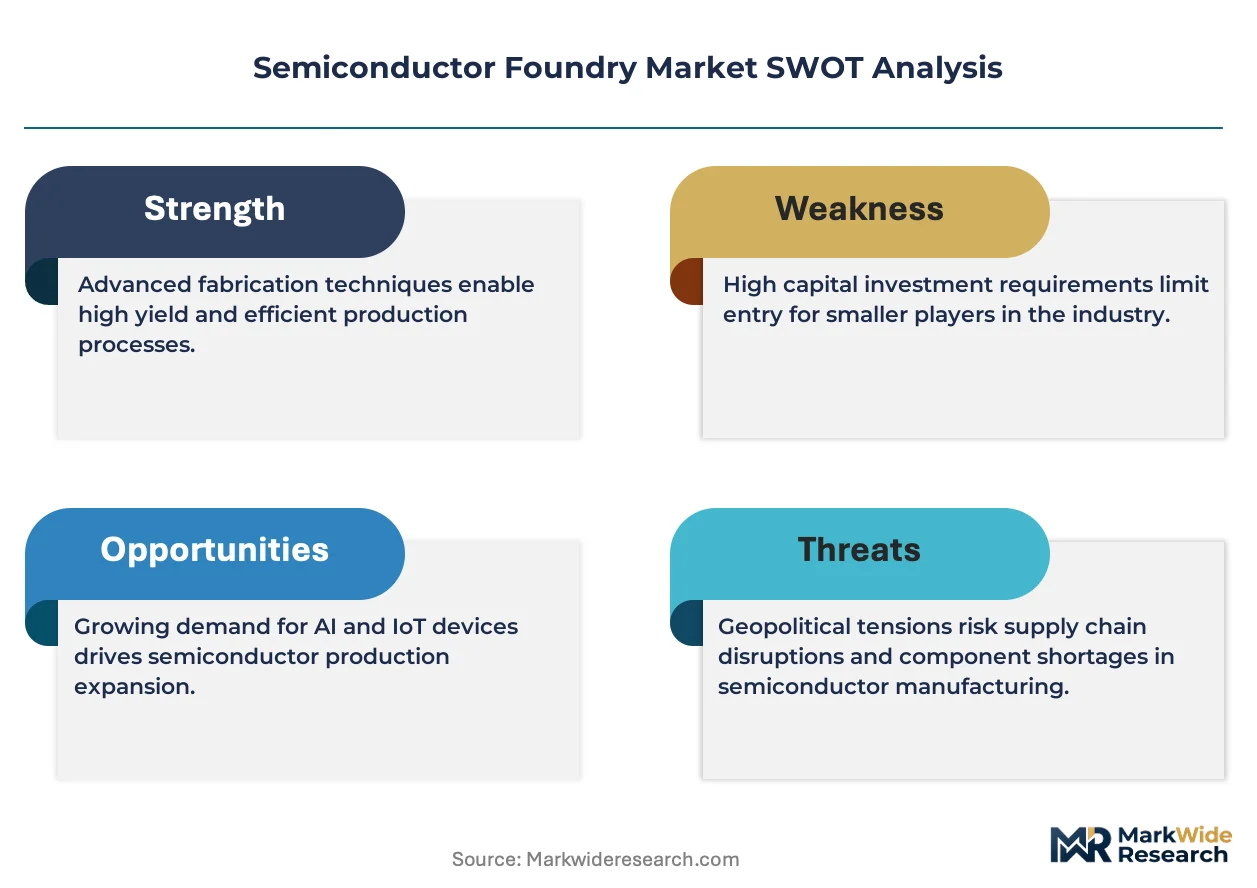
The semiconductor foundry market is being fundamentally restructured by the geographic dispersion of leading-edge capacity as sovereign subsidy programs compete to offset Taiwan's process leadership concentration. Capital allocation decisions now hinge on incentive package comparability across jurisdictions rather than pure ecosystem efficiency.
Growth Catalysts
- US CHIPS and Science Act incentives:Direct capital grants and tax credits for domestic fabrication facilities are accelerating greenfield investments in Arizona and Texas, pulling equipment orders forward by several quarters.
- Automotive silicon content expansion:Electric vehicle powertrains and advanced driver-assistance systems are multiplying die requirements per vehicle, with 28nm and below nodes capturing the majority of incremental wafer demand.
- EUV lithography maturation:High-NA EUV tool availability is enabling 3nm and 2nm process ramps, compressing transistor scaling timelines and sustaining premium pricing for leading-edge capacity.
Market Restraints
- Neon and noble gas supply concentration:Ukrainian and Russian sourcing of purified neon, krypton, and xenon for excimer lasers creates input cost volatility and forced substitution to reclaimed and non-CIS suppliers.
- Extreme ultraviolet tool oligopoly:Single-source dependency on ASML for critical lithography equipment limits capacity expansion velocity and creates queueing bottlenecks for new fab ramps.
- REACH chemical authorization delays:ECHA's substance evaluation timelines for novel photoresists and etchants are extending qualification cycles for European-based fabrication, constraining process chemistry innovation.
Strategic Opportunities
- Japan's Kumamoto-Tsukuba corridor:METI subsidies and existing equipment supplier density are attracting leading-edge joint ventures, creating a viable alternative to Taiwan for 7nm and below risk diversification.
- Chiplet-based heterogeneous integration:2.5D and 3D packaging architectures are converging with advanced interposer technology, opening packaging-centric revenue pools that bypass traditional node scaling economics.
- Carbon border adjustment mechanisms:The EU's CBAM is creating preferential access for fabs with verified low-carbon electricity sourcing, advantaging Nordic and French nuclear-powered facilities in European procurement decisions.
Industry Challenges
- EUV scanner technician scarcity:The specialized skill set for high-NA tool maintenance and overlay optimization is concentrated among fewer than two thousand trained engineers globally, constraining fab utilization rates.
- Legacy node equipment cannibalization:Tool redirection from 200mm to 300mm platforms is disrupting mature node supply for automotive microcontrollers, forcing foundries to balance margin against customer retention.
- Export control license complexity:US Bureau of Industry and Security entity list restrictions are fragmenting customer qualification workflows, requiring separate process flows and IT systems for restricted versus unrestricted end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Foundry Market |
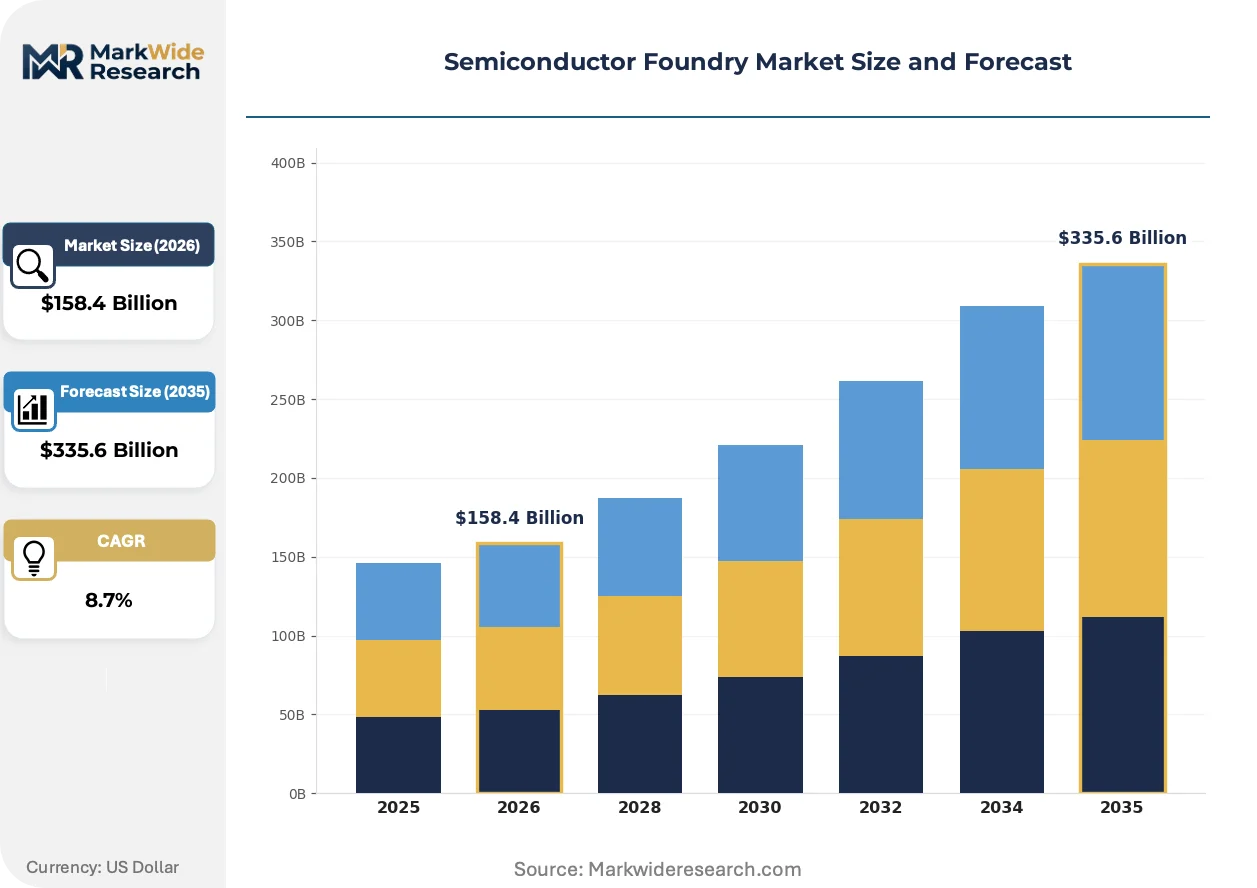
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $335.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer Fabrication, Packaging Services, Test Services, Foundry Services Technology: 45nm, 28nm, 16nm, 10nm End User: Consumer Electronics, Automotive, Telecommunications, Industrial Service Type: Analog, Digital, Mixed Signal, RF |
| Companies Covered | GlobalFoundries, United Microelectronics Corporation, Taiwan Semiconductor Manufacturing Company, VisIC Technologies, Powerchip Semiconductor Manufacturing, Samsung Electronics, SMIC, Tower Semiconductor, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Foundry Market Strategic Shifts & Innovations
Process architecture is bifurcating between transistor-scaling leadership and packaging-centric integration, with customer procurement criteria shifting from node nomenclature to system-level performance metrics. This reorientation is redrawing competitive boundaries between pure-play foundries, IDM captives, and outsourced assembly providers.
Gate-all-around transistor architecture is integrating nanosheet structures to replace finFET designs at 3nm and below, enabling superior electrostatic control and reduced leakage current. High-performance computing and AI accelerator designers are adopting these processes for training workloads despite 15-20% cost premiums over prior nodes. The structural consequence is compressing design-win cycles as foundries pre-validate IP blocks for common accelerator configurations.
The EU AI Act's risk-based classification system is mandating traceability and conformity assessment for chips deployed in high-risk applications, including autonomous systems and critical infrastructure. Foundries serving European automotive and industrial customers must now maintain process documentation and quality management systems that satisfy notified body requirements. Medical device and automotive segments are responding by consolidating supplier relationships to reduce audit burden and ensure regulatory continuity.
Long-term capacity reservation contracts are displacing spot-market wafer purchasing as fabless designers secure allocation amid persistent supply anxiety. Automotive OEMs and defense contractors are locking multi-year agreements with penalty clauses, transferring inventory risk upstream to foundry balance sheets. This pattern is most visible in German and Japanese industrial semiconductor procurement, where just-in-time manufacturing culture is yielding to strategic stockpiling of wafer bank inventory.
Semiconductor Foundry Market Segmentation
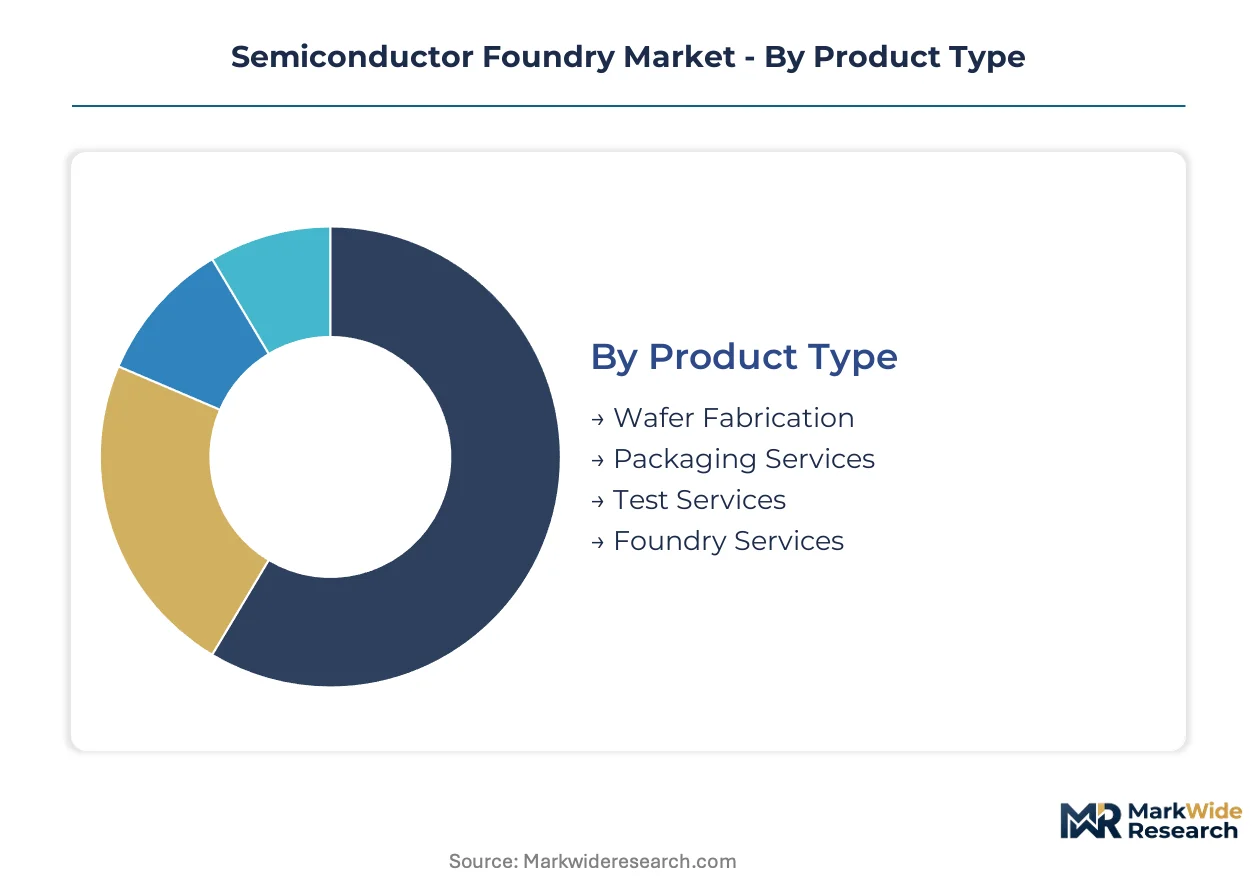
Semiconductor foundry segmentation reveals how process specialization and end-use requirements fragment manufacturing economics across distinct value pools. Customer procurement criteria diverge sharply between leading-edge logic scaling and mature-node reliability applications.
Product Type:
Wafer fabrication commands capital intensity that dwarfs downstream services, while packaging gains structural margin as chiplet architectures proliferate.
- Wafer Fabrication:Photolithography, etching, and deposition processes transform silicon wafers into integrated circuits at node sizes from legacy 45nm to advanced 10nm and below. Automotive OEMs in Germany and Japan are locking multi-year capacity reservations here as EV platforms multiply die requirements per vehicle.
- Packaging Services:2.5D and 3D stacking with advanced interposer technology enables heterogeneous integration of chiplets from different process nodes. TSMC's CoWoS and Intel's Foveros architectures are expanding this segment's addressable market beyond traditional assembly margins.
- Test Services:Wafer-level and final-test verification ensures yield recovery and defect isolation before shipment to fabless customers.
- Foundry Services:Full-turnkey manufacturing combines fabrication, packaging, and test under single-source contracting for mid-size chip designers.
Mature deployment sits with wafer fabrication. Newer deployment is concentrated in packaging services.
Technology:
Node nomenclature masks diverging economics between transistor-scaling leadership and mature-process reliability.
- 45nm:Legacy planar transistor architecture serves industrial microcontrollers and automotive body electronics where reliability validation cycles span years. European automotive suppliers favor this node for powertrain control modules requiring extended temperature ranges.
- 28nm:High-k metal gate technology balances performance with mature yield curves, capturing the majority of incremental automotive wafer demand. This node occupies a sweet spot for ADAS sensor fusion and EV battery management systems across Japanese and German supply chains.
- 16nm:FinFET architecture enables mobile application processors and networking infrastructure with improved power efficiency over planar designs.
- 10nm:Advanced finFET with aggressive scaling targets high-performance computing and premium smartphone SoCs where power-performance density justifies premium wafer pricing.
Volume concentration centers on 28nm. Premium expansion is climbing the fastest at 10nm.
End User:
Automotive qualification requirements are reshaping foundry customer prioritization as silicon content per vehicle multiplies.
- Automotive:Electric vehicle powertrains and autonomous driving systems require zero-defect processes with ISO 26262 functional safety certification. Foundries serving this segment must maintain process documentation that satisfies notified body requirements under the EU AI Act's risk-based classification.
- Consumer Electronics:Smartphone and PC processors drive leading-edge node adoption despite shorter product lifecycles than industrial applications.
- Telecommunications:5G baseband and infrastructure silicon demands mixed-signal capability with RF performance optimization.
- Industrial:Long lifecycle requirements and extended temperature specifications favor mature nodes with proven reliability data.
Procurement scale sits with consumer electronics. Contract duration is extending most significantly in automotive.
Service Type:
Circuit architecture specialization determines equipment configuration and process chemistry requirements across fabrication bays.
- Analog:Precision voltage reference and power management circuits require specialized doping profiles and thick-gate oxide processes. Industrial and automotive power applications in Germany and Japan concentrate demand here.
- Digital:High-density logic gates for microprocessors and memory controllers drive leading-edge lithography utilization and EUV scanner throughput.
- Mixed Signal:Integration of analog and digital blocks on single die serves sensor interfaces and data converters for IoT endpoints.
- RF:High-frequency transistor optimization for wireless communications requires specialized substrate engineering and isolation structures.
Process maturity sits with analog. Technology refresh is accelerating most rapidly in digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity neon from Ukrainian purification facilities historically anchored excimer laser gas supply chains, concentrating critical feedstock in Eastern Europe before supply diversification became a strategic priority.
United States
Electric vehicle powertrains and defense-grade semiconductors are multiplying wafer demand across Texas and Arizona manufacturing corridors. The US CHIPS and Science Act delivers direct capital grants and investment tax credits for domestic fabrication facilities. Intel Corporation is expanding its Arizona operations while TSMC builds advanced nodes in Phoenix, pulling equipment orders forward by several quarters.
Germany
Automotive OEMs in Stuttgart and Munich are locking multi-year capacity reservations for ISO 26262-certified processes as silicon content per vehicle multiplies. The EU Chips Act redirects capital flows toward regional self-sufficiency with subsidy qualification tied to capacity commitments. Dresden's Silicon Saxony cluster anchors European leading-edge ambitions with planned joint ventures for 7nm and below risk diversification.
Japan
Advanced driver-assistance systems and industrial automation controllers are intensifying demand for 28nm reliability-validated wafers. METI semiconductor subsidies under the national semiconductor strategy are attracting leading-edge joint ventures. Kumamoto and Tsukuba are forming a viable alternative corridor to Taiwan for 7nm and below production, leveraging existing equipment supplier density.
Taiwan
High-performance computing and AI accelerator designers are compressing design-win cycles through pre-validated IP blocks for common configurations. Geopolitical risk is dispersing fabrication investments toward alternative jurisdictions despite Taiwan's retained dominance of leading-edge output. Hsinchu Science Park sustains R&D intensity that outpaces most national semiconductor budgets.
China
5G infrastructure and electric vehicle platforms are expanding domestic wafer demand across state-supported industrial programs. Dual carbon goals and import substitution policies are redirecting capital toward captive capacity buildout. Shanghai and Beijing-Tianjin-Hebei clusters are concentrating mature-node expansion as export control restrictions constrain leading-edge tool access.
Semiconductor Foundry Market Key Industry Players
Global majors compete with regional champions across process technology leadership, with market structure consolidating around three dominant archetypes: pure-play foundries with dedicated fabrication facilities, integrated device manufacturers operating captive and merchant foundry services, and memory-to-logic conglomerates leveraging vertical integration. Strategic moves center on sovereign capacity partnerships and advanced packaging technology licensing rather than pure node-scaling competition.
Within the pure-play foundry tier, Taiwan Semiconductor Manufacturing Company and GlobalFoundries occupy positions representing ecosystem concentration and geographic diversification respectively. Samsung Electronics exemplifies the memory-to-logic integration archetype competing for high-performance computing contracts. Intel Corporation sits within the IDM transformation category, repositioning toward merchant foundry services while retaining captive manufacturing. SMIC represents state-supported capacity expansion under technology access constraints.
| Leading Market Players |
|---|
| GlobalFoundries |
| United Microelectronics Corporation |
| Taiwan Semiconductor Manufacturing Company |
| VisIC Technologies |
| Powerchip Semiconductor Manufacturing |
| Samsung Electronics |
| SMIC |
| Tower Semiconductor |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Automotive OEM multi-year capacity reservations are compressing spot-market liquidity and forcing foundries to price long-term offtake contracts below marginal cost recovery thresholds. This procurement shift toward strategic stockpiling transfers inventory risk upstream while locking in wafer bank commitments that constrain pricing flexibility for discretionary orders.
Pricing Analysis
Long-term service bundling separates foundry pricing into bare-wafer manufacturing versus comprehensive packages incorporating yield optimization, failure analysis, and automotive qualification support. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 certification grade and volume scale, with automotive-grade processes commanding substantial premiums over consumer electronics tiers. Cost compression in mature nodes is intensifying because equipment cannibalization for 300mm conversion disrupts 200mm supply continuity. Fabless chip designers without captive manufacturing exhibit highest price sensitivity, while defense contractors and automotive OEMs prioritize allocation security over unit economics.
Supply Chain Analysis
Automotive qualification gating restricts qualified supplier pools to foundries with documented process traceability and notified body certification under EU AI Act risk classifications. Geographic concentration centers on Taiwan, South Korea, and the United States for leading-edge lithography capacity, with Japan's Kumamoto-Tsukuba corridor emerging as a diversification alternative. Raw material dependencies draw from Ukrainian neon purification, ASML's single-source EUV scanner monopoly, and Japanese photoresist chemical supply. Single-source vulnerability for high-NA lithography equipment creates queueing bottlenecks that constrain fab ramp velocity. Distribution runs through direct long-term contracts rather than spot-market exchanges, with fabless designers locking multi-year agreements to secure allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around sovereign-subsidized capacity buildouts, with capital intensity and export control compliance costs forcing sub-scale players toward joint venture absorption or exit.
For Market Incumbents: Lock in automotive qualification relationships through ISO 26262 pre-certification of process variants, insulating against emerging foundry entrants in Japan's METI-subsidized corridor. Deepen backward integration into silicon carbide substrate supply for power electronics applications, capturing margin pools that pure-play competitors cannot access. Prioritize EUV scanner technician training pipelines to sustain utilization rates amid global scarcity of overlay optimization specialists. For New Entrants and Emerging Players: The price-point gap between TSMC's premium leading-edge nodes and GlobalFoundries' mature-process offerings creates white-space opportunity for specialty analog foundries serving German automotive power management demand. Target Japan's Kumamoto-Tsukuba corridor for 28nm automotive capacity, leveraging METI subsidy qualification and existing equipment supplier density. Pursue foundry-service bundling that combines wafer fabrication with automotive-grade test and qualification under single-source contracting to reduce customer audit burden. For Investors and Strategic Acquirers: Re-rating potential sits with analog-focused foundries with established automotive qualification records given EU AI Act traceability mandates that extend design-win cycles and entrench incumbent relationships. Long-term viability favors facilities with verified low-carbon electricity sourcing advantaged under EU CBAM procurement preferences. Monitor ASML high-NA EUV tool delivery schedules as inflection indicator for which greenfield projects achieve commercial ramp versus delayed qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Capacity Joint Venture | METI subsidies in Japan's Kumamoto-Tsukuba corridor attract TSMC partnerships for 7nm diversification. |
| Automotive Qualification Pre-Certification | ISO 26262 process validation compresses design-win cycles for German EV powertrain contracts. |
| High-NA EUV Tool Reservation | ASML scanner queue positions determine which greenfield fabs achieve leading-edge commercial ramp. |
| Chiplet Packaging Technology Licensing | TSMC CoWoS and Intel Foveros architectures expand addressable market beyond traditional node scaling. |
| Low-Carbon Electricity Sourcing Verification | EU CBAM preferential access advantages Nordic and French nuclear-powered facilities in procurement decisions. |
Research Approach
SEC 10-K filings, EIA power sourcing disclosures, and EU Chips Act subsidy award notifications formed the secondary backbone for capacity investment tracking and sovereign incentive comparability analysis. Primary interviews with foundry operations executives, automotive Tier 1 procurement directors, EUV scanner field service engineers, and photoresist chemical supply managers validated equipment lead times and qualification cycle assumptions. Bottom-up wafer demand modeling by node and end-use segment was triangulated against top-down foundry revenue aggregation across the analysis window.
Historical trendline analysis of capital expenditure cycles, equipment utilization rates, and process node migration patterns informed the analytical framework. Segmentation dimensions modeled include technology node tier, end-use application, service type, and regional production cluster. CAGRs were derived from capacity expansion announcements, equipment order backlogs, and automotive silicon content trajectories. Forecast inputs incorporated EUV lithography maturation curves and REACH chemical authorization timelines.
Underlying measurement precision varies by segment; leading-edge node forecasts carry tighter precision than mature-process analog given visibility into ASML tool delivery schedules. Forecasts reflect assumptions regarding sovereign subsidy continuity, export control license processing efficiency, and automotive qualification cycle stability. A model refresh is warranted upon material change in high-NA EUV scanner availability or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market