
 Ion Milling System Market | 2026-2036
Ion Milling System Market Size, Share, and Industry Trends Forecast 2026-2036
Ion Milling System Market Outlook
Argon ion beam technology is tilting toward lower-energy, higher-precision configurations as chipmakers demand atomic-layer surface control. Hitachi High-Tech Corporation leverages its electron microscopy heritage to anchor ion milling systems within integrated materials characterization workflows. JEOL Ltd. competes through specialized sample preparation platforms that serve transmission electron microscopy laboratories. Oxford Instruments differentiates by extending cryogenic ion milling capabilities for temperature-sensitive specimens.
An ion milling system directs a focused beam of inert gas ions—typically argon accelerated at 1–10 keV—to remove material from a substrate surface through physical sputtering, achieving flatness tolerances below one nanometer for electron-transparent sample preparation. Precision ion mills command premium positioning in semiconductor failure analysis labs where defect review demands damage-free cross-sections. Desktop ion mills occupy expanding share in university materials science departments seeking accessible sample prep without cleanroom infrastructure. Sputtering technology leads installed capacity while electron cyclotron resonance sources gain traction for reactive ion milling of compound semiconductors.
FDA device manufacturing standards and EPA hazardous substance protocols shape ion milling system specifications for biomedical implant surface preparation in the United States. REACH chemical restrictions and RoHS substance limits in Europe compel equipment redesigns to eliminate restricted process gases and heavy metals from vacuum chamber components. Semiconductor end users in Taiwan and South Korea must align with local environmental agency effluent controls while scaling atomic-precision manufacturing capacity. Stakeholders should monitor which plasma source technology achieves process qualification at the most advanced logic nodes before committing capital to next-generation platform investments.
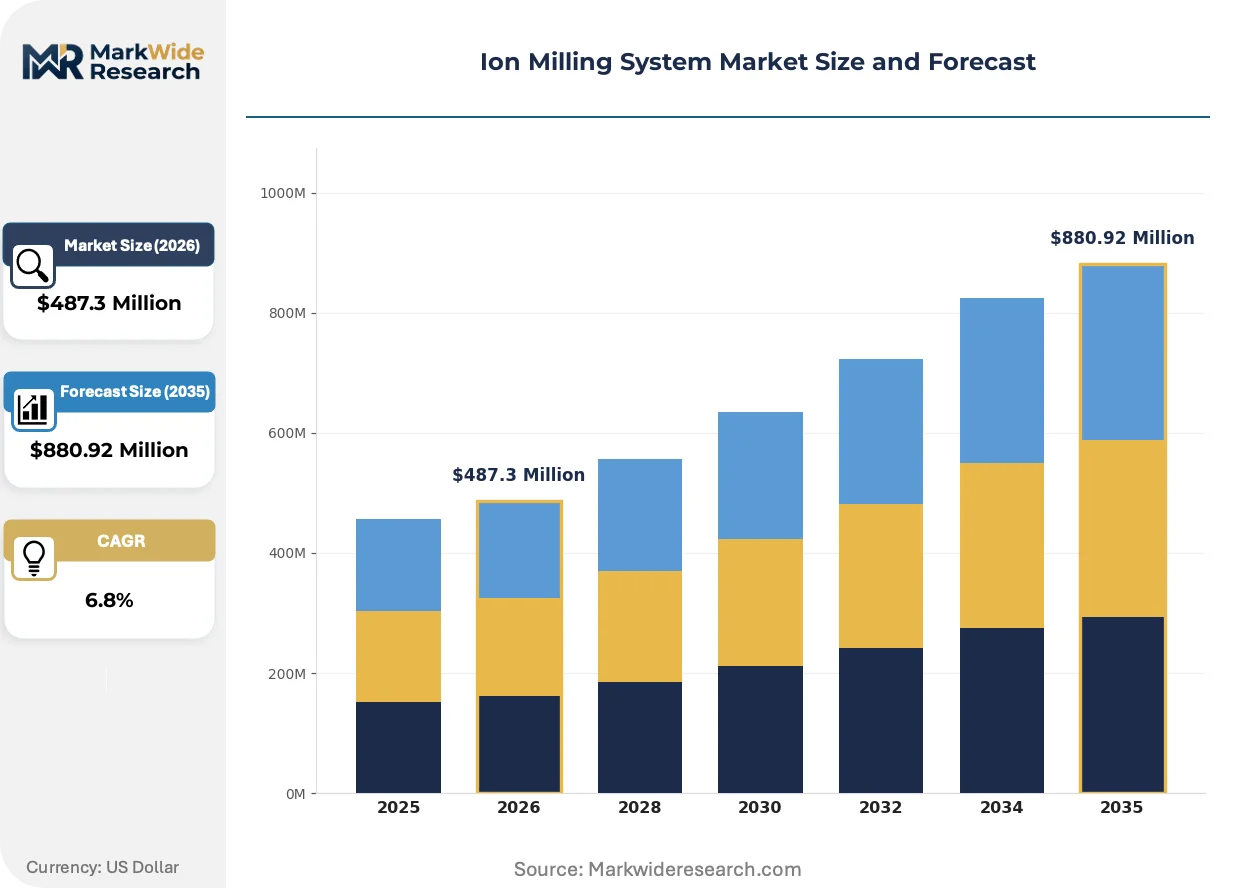
Market Dynamics
Argon ion beam energy reduction is compressing process windows to atomic-layer precision, forcing equipment makers to reconfigure plasma source architectures while foundries in Taiwan and South Korea scale sub-nanometer surface preparation capacity.
Growth Catalysts
- REACH substance restrictions:European ECHA mandates on hazardous process gases are accelerating equipment redesigns toward lower-toxicity chemistries, opening replacement cycles for compliant ion milling platforms.
- Transmission electron microscopy laboratories:Materials characterization demand in university and industrial R&D settings is expanding desktop ion mill installations for electron-transparent sample preparation.
- Atomic-precision manufacturing:Advanced logic node development at foundry clusters in Taiwan and South Korea requires damage-free cross-sectioning capabilities that precision ion mills uniquely deliver.
Market Restraints
- High-purity argon supply concentration:Specialty gas production clusters in the United States and Qatar create input cost volatility and delivery risk for ion milling operations.
- Electron cyclotron resonance source qualification delays:Compound semiconductor manufacturers await process validation at leading-edge nodes before committing to next-generation platform capital.
- Cleanroom infrastructure requirements:Precision ion milling systems demand controlled environments that constrain deployment in budget-constrained academic settings.
Strategic Opportunities
- Cryogenic ion milling extension:Temperature-sensitive specimen preparation in structural biology and soft materials research opens adjacent application expansion beyond semiconductor failure analysis.
- Biomedical implant surface preparation:FDA device manufacturing standards in the United States are mandating atomic-level surface control for cardiovascular and orthopedic implant biocompatibility.
- Electron microscopy workflow integration:Combined sample preparation and characterization platforms reduce handling contamination for battery materials and quantum device research.
Industry Challenges
- Vacuum chamber component redesign:RoHS substance limits in Europe compel engineering teams to eliminate heavy metals from legacy system architectures without compromising vacuum integrity.
- Plasma physicist talent scarcity:Specialized ion source design expertise concentrates at a handful of national laboratories and university programs, constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion Milling System Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Ion Mills, Desktop Ion Mills, Versatile Ion Mills, Precision Ion Mills End User: Semiconductors, Nanotechnology, Materials Science, Aerospace Application: Thin Film Deposition, Surface Analysis, Sample Preparation, Etching Processes Technology: Cathodic Arc, Sputtering, Electron Cyclotron Resonance, Inductively Coupled Plasma |
| Companies Covered | Leica Microsystems, Hitachi High-Tech Corporation, Veeco Instruments Inc., JEOL Ltd., Gatan Inc., AJA International Inc., Intlvac Thin Film Corporation, Oxford Instruments, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion Milling System Market Strategic Shifts
Argon ion beam technology is undergoing energy-precision reconfiguration as chipmakers demand atomic-layer surface control, while regulatory chemistry restrictions and procurement model evolution reshape competitive positioning.
Low-energy ion milling configurations are collapsing the boundary between surface preparation and atomic-layer deposition control. Semiconductor failure analysis labs at leading foundries are adopting sub-keV beam systems for defect review without amorphous layer formation. This energy reduction is collapsing the distinction between ion milling and complementary surface analysis techniques, enabling single-workflow metrology integration.
REACH chemical restrictions and RoHS substance limits in Europe are compelling equipment redesigns to eliminate restricted process gases and heavy metals from vacuum chamber components. Industrial consequence includes extended qualification timelines for next-generation platforms as manufacturers validate alternative materials. Semiconductor end users in Taiwan and South Korea must align with local environmental agency effluent controls while scaling atomic-precision capacity, creating dual-compliance engineering complexity.
After-sales service unbundling is fragmenting traditional capital equipment procurement models. University materials science departments and mid-size contract research organizations are acquiring desktop ion mills through reagent-supply-inclusive leasing arrangements rather than outright purchase. This shift is most visible in North American and European academic clusters where budget constraints favor operational expenditure treatment over capital allocation.
Ion Milling System Market Segmentation
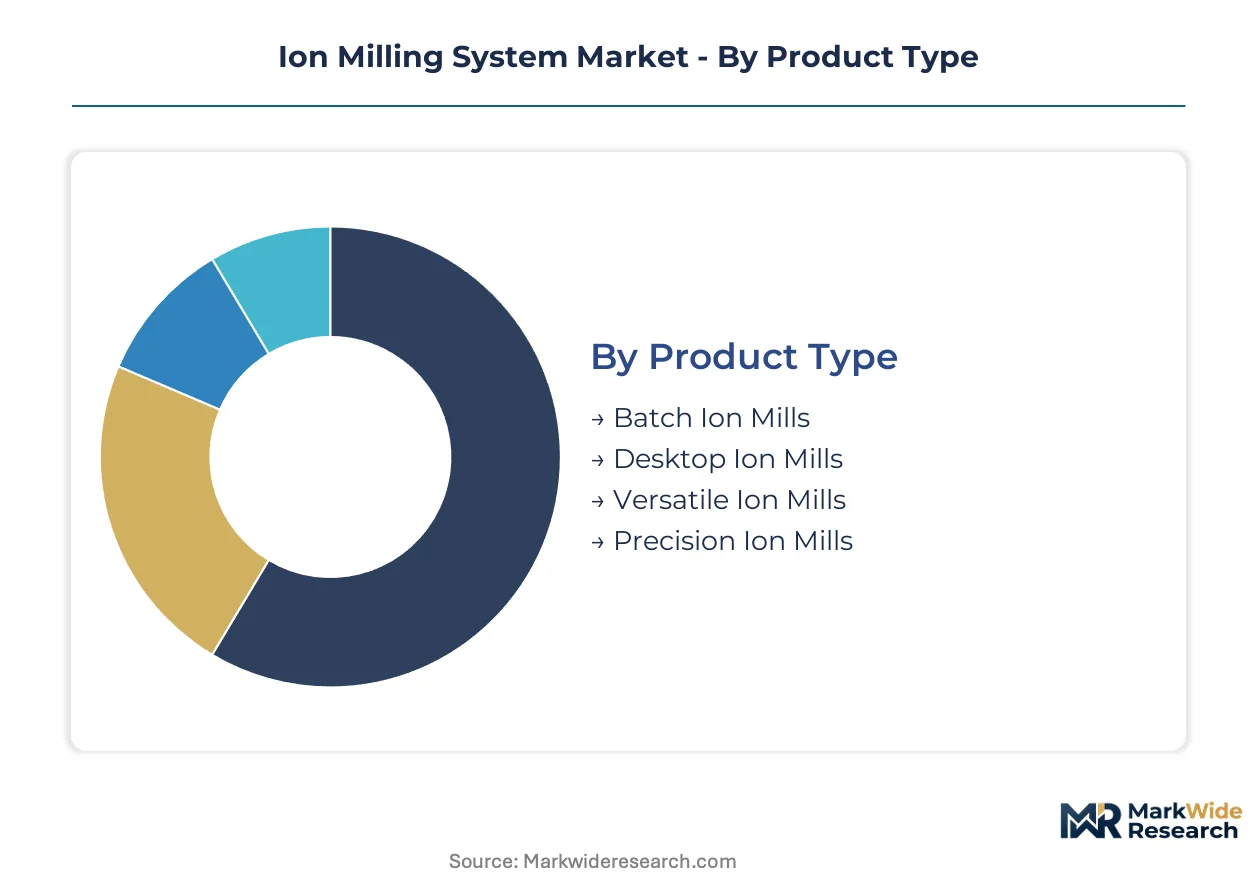
Ion milling systems fragment across multiple technical dimensions where product architecture, end-use precision requirements, and plasma source technology determine equipment selection and capital allocation priorities. Each segmentation axis reveals distinct competitive dynamics between mature installed bases and emerging capability demands.
Product Type:
Mature high-volume platforms coexist with emerging compact configurations as foundry and laboratory procurement models diverge.
- Precision Ion Mills:These systems achieve sub-nanometer flatness tolerances through closed-loop ion beam steering and real-time thickness monitoring. Demand concentrates at Taiwan Semiconductor Manufacturing Company and Samsung Foundry failure analysis labs where defect review requires damage-free cross-sections without amorphous layer formation. ECHA REACH substance restrictions are extending qualification timelines for next-generation vacuum chamber materials in these premium platforms.
- Desktop Ion Mills:Compact footprints under two square meters enable deployment outside cleanroom infrastructure. North American and European university materials science departments are expanding installations through reagent-supply-inclusive leasing arrangements rather than capital purchase. Budget constraints favor operational expenditure treatment over facility infrastructure investment.
- Batch Ion Mills:Multi-sample processing architectures serve high-throughput industrial quality control laboratories with standardized preparation protocols.
- Versatile Ion Mills:Modular source configurations accommodate alternating between argon ion milling and reactive plasma modes for compound semiconductor research.
Precision ion mills retain volume leadership; desktop ion mills hold the steepest expansion curve.
End User:
Customer type segmentation reveals a cost-tier split between capital-intensive fabrication facilities and budget-constrained research institutions.
- Semiconductors:Leading-edge logic and memory manufacturers deploy precision systems for atomic-layer surface control at nodes below three nanometers. South Korean and Taiwanese foundry clusters are scaling capacity in parallel with advanced node development timelines. Local environmental agency effluent controls impose dual-compliance engineering complexity alongside European REACH alignment.
- Materials Science:Battery materials and quantum device research programs demand combined sample preparation and characterization workflows to reduce handling contamination. Oxford Instruments and JEOL are extending cryogenic capabilities for temperature-sensitive specimen classes.
- Nanotechnology:Carbon nanotube and graphene research programs require low-energy configurations to preserve structural integrity during thinning.
- Aerospace:Turbine blade coating analysis and failure investigation drive demand for large-chamber systems accommodating centimeter-scale components.
Semiconductor end users command the highest average selling prices; materials science departments are expanding most quickly through alternative procurement structures.
Application:
Application segmentation tracks the technology frontier from established surface preparation toward integrated metrology workflows.
- Sample Preparation:Transmission electron microscopy laboratories require electron-transparent lamellae with thickness below one hundred nanometers. Hitachi High-Tech leverages electron microscopy heritage to anchor ion milling within integrated characterization workflows. FDA device manufacturing standards are mandating atomic-level surface control for cardiovascular implant biocompatibility in the United States.
- Surface Analysis:Sub-keV beam systems enable single-workflow integration between preparation and complementary surface analysis techniques. This energy reduction collapses the distinction between ion milling and atomic-layer deposition control.
- Thin Film Deposition:Reactive ion milling modes support compound semiconductor heterostructure fabrication with chemical selectivity.
- Etching Processes:Anisotropic material removal for photonic device patterning employs electron cyclotron resonance sources for plasma density enhancement.
Sample preparation retains volume leadership; surface analysis applications are gaining share fastest through metrology integration.
Technology:
Plasma source architecture determines process chemistry flexibility and capital qualification timelines.
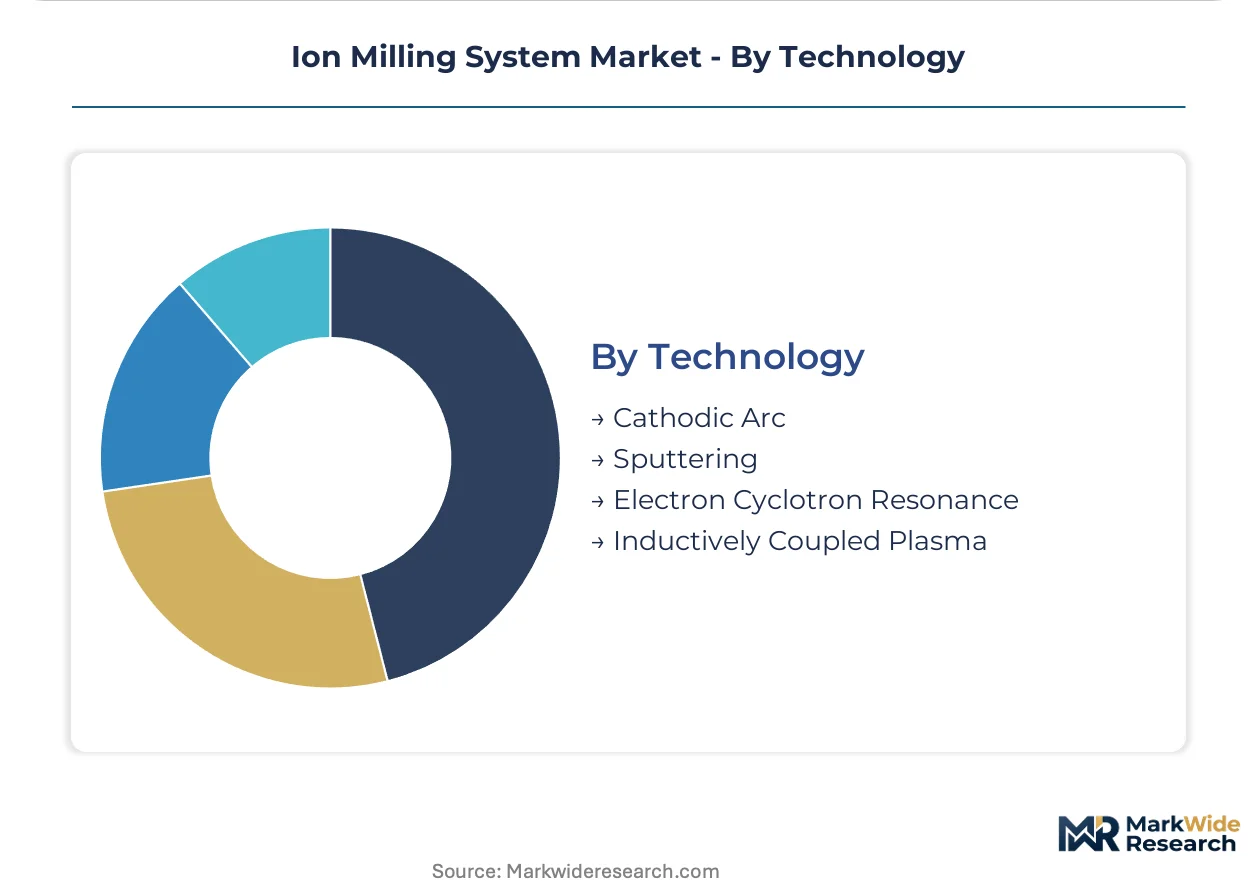
- Sputtering:Inert gas ion bombardment without chemical reaction dominates installed capacity for physical material removal. RoHS substance limits in Europe compel vacuum chamber component redesigns to eliminate heavy metals from legacy architectures. Extended qualification timelines result from alternative material validation.
- Electron Cyclotron Resonance:Microwave-excited high-density plasma enables reactive ion milling of compound semiconductors with enhanced chemical selectivity. Compound semiconductor manufacturers await process validation at leading-edge nodes before committing capital to next-generation platforms.
- Cathodic Arc:Metal ion sources support specialized coating removal and surface modification applications with high ionization efficiency.
- Inductively Coupled Plasma:RF-excited sources offer intermediate plasma density for research environments requiring operational flexibility across multiple material classes.
Sputtering technology retains volume leadership; electron cyclotron resonance sources hold the steepest expansion curve pending node qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry failure analysis labs and university materials science departments concentrate equipment procurement across five distinct national markets, each shaped by local environmental regulations and semiconductor development priorities.
Taiwan
TSMC and United Microelectronics Corporation operate precision ion milling systems at sub-nanometer tolerances for three-nanometer node defect review. The Environmental Protection Administration enforces semiconductor effluent discharge standards that constrain process chemistry selection. Hsinchu Science Park anchors the highest concentration of atomic-precision surface preparation capacity outside South Korea.
South Korea
Samsung Foundry and SK Hynix deploy closed-loop ion beam steering systems for memory chip cross-section analysis. Ministry of Environment regulations on hazardous gas emissions require dual-compliance engineering alongside European REACH alignment. Giheung and Pyeongtaek semiconductor clusters are scaling installation capacity in parallel with advanced logic development timelines.
United States
FDA device manufacturing standards mandate atomic-level surface control for cardiovascular and orthopedic implant biocompatibility. EPA hazardous substance protocols shape equipment specifications for biomedical applications. Greater Boston and Silicon Valley university clusters are expanding desktop ion mill installations through operational expenditure leasing arrangements.
Germany
ECHA REACH substance restrictions and RoHS substance limits compel vacuum chamber component redesigns to eliminate heavy metals from legacy system architectures. Fraunhofer Institute materials characterization programs sustain demand for cryogenic ion milling capabilities. Munich and Dresden industrial research corridors concentrate electron microscopy workflow integration investments.
Japan
METI industrial technology roadmaps prioritize atomic-layer surface control for next-generation quantum device fabrication. JIS standards govern equipment interoperability within integrated materials characterization workflows. Tsukuba and Osaka nanotechnology research centers maintain specialized sample preparation platforms for transmission electron microscopy laboratories.
Ion Milling System Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base clusters around three strategic archetypes: integrated electron microscopy platform providers, standalone ion source specialists, and diversified analytical instrumentation conglomerates. Consolidation pressure intensifies as foundry customers demand single-vendor workflow integration. Dominant competitive moves include strategic partnerships for cryogenic capability extension and portfolio diversification into desktop configurations for academic markets.
Among integrated platform providers, Hitachi High-Tech Corporation and JEOL Ltd. exemplify the electron microscopy heritage archetype, anchoring ion milling systems within broader materials characterization workflows. Oxford Instruments occupies a position representing the specialized cryogenic extension segment. Thermo Fisher Scientific exemplifies the diversified analytical instrumentation conglomerate archetype with broad portfolio coverage across sample preparation and surface analysis categories. These three company types collectively span the competitive spectrum from premium precision systems to accessible desktop configurations.
| Leading Market Players |
|---|
| Leica Microsystems |
| Hitachi High-Tech Corporation |
| Veeco Instruments Inc. |
| JEOL Ltd. |
| Gatan Inc. |
| AJA International Inc. |
| Intlvac Thin Film Corporation |
| Oxford Instruments |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit argon gas cylinder logistics costs directly into precision ion mill price differentiation, amplifying supply concentration effects as Taiwanese foundry clusters negotiate volume contracts against isolated European academic buyers.
Pricing Analysis
Cost-plus contracts indexed to specialty argon spot pricing dominate precision system procurement, with Taiwanese foundry clusters leveraging multi-unit commitments against isolated European laboratory buyers. Three-tier pricing structure across precision, desktop, and batch configurations reflects certification grade and after-sales service bundling. Pricing pressure stems from REACH-compliant vacuum chamber redesigns extending manufacturer qualification timelines. University materials science departments exhibit highest price sensitivity, while semiconductor failure analysis labs absorb premiums for sub-nanometer flatness guarantees.
Supply Chain Analysis
Contract manufacturing concentrates at Hitachi High-Tech Corporation and JEOL Ltd. fabrication facilities in Japan, with secondary capacity at Oxford Instruments UK operations. High-purity argon sourcing draws from United States and Qatar production clusters, while vacuum chamber components rest on German precision engineering and Japanese ceramic supply. Single-source vulnerability concentrates in electron cyclotron resonance source magnet assemblies. Distribution runs through direct OEM sales for precision systems and regional academic distributors for desktop configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Taiwanese and South Korean foundry clusters consolidate procurement through single-vendor workflow integration mandates, fragmenting vendor pricing leverage across tiered equipment categories.
For Market Incumbents: Entrench cryogenic capability extensions at Oxford Instruments and JEOL to defend against emerging desktop specialists. Backward integration into argon recycling systems mitigates specialty gas supply volatility. Anchor precision platforms within electron microscopy workflow bundles to lock out standalone ion source competitors. For New Entrants and Emerging Players: Mid-size contract research organizations in North American university clusters represent the most penetrable entry point, leasing-inclusive procurement models bypassing capital budget constraints. European materials characterization laboratories facing REACH compliance deadlines offer secondary white-space. Target reagent-supply bundling as primary go-to-market mechanism against incumbent capital-sales structures. For Investors and Strategic Acquirers: ECHA substance restriction deadlines reshape the acquisition landscape toward REACH-compliant platform developers. Five-to-ten year viability favors cryogenic extension specialists with semiconductor qualification traction. Monitor electron cyclotron resonance source node validation announcements as inflection signal for next-generation platform capital deployment. Quarterly review of foundry failure analysis lab procurement tenders is advised to detect vendor consolidation patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Capability Extension | Oxford Instruments captures structural biology specimen preparation demand beyond semiconductor failure analysis. |
| REACH-Compliant Chamber Redesign | ECHA mandates force vacuum component material substitutions, extending qualification timelines for premium platforms. |
| Desktop Leasing Model Expansion | North American university clusters shift procurement toward operational expenditure treatment over capital allocation. |
| Electron Microscopy Workflow Integration | Hitachi High-Tech leverages heritage positioning to anchor ion milling within combined preparation-characterization platforms. |
| Argon Supply Security Investment | Specialty gas production concentration in Qatar and the United States creates input cost volatility for operators. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across semiconductor failure analysis labs, university materials science departments, and ion milling system manufacturers. Primary interviews captured procurement officers at TSMC and Samsung Foundry, electron microscopy laboratory directors at Fraunhofer Institute and MIT, and plasma source engineers at national laboratories. Secondary validation drew from EPA hazardous substance protocols, ECHA REACH substance restriction databases, SEMI equipment standards, and customs trade data for high-purity argon flows. Bottom-up equipment shipment tallies and top-down semiconductor capital expenditure estimates were triangulated.
Calibration against historical precision system installations and desktop unit expansion patterns anchored volume projections across the modeling period. Segmentation dimensions modeled include product architecture, end-user precision requirements, plasma source technology, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and foundry node development timelines. Forecast inputs incorporated argon supply concentration risk and electron cyclotron resonance source qualification velocity.
Practitioners should monitor ECHA substance restriction implementation schedules and foundry node qualification announcements for early signals of equipment demand inflection. Forecasts reflect assumptions regarding REACH compliance timeline adherence and specialty gas supply stability. Semiconductor fabrication capacity expansion delays or electron cyclotron resonance source validation failures would revise equipment shipment projections. Quarterly review of foundry capital expenditure disclosures and environmental regulator enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Dicing Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Solar Texturing Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Equipment Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Global Semiconductor Front-End Equipment Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market