
 Deep Reactive Ion Etching (DRIE) Etcher Market | 2026-2036
Deep Reactive Ion Etching (DRIE) Etcher Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Reactive Ion Etching (DRIE) Etcher Market Insights
China's semiconductor equipment capacity build-out is reshaping competitive dynamics in DRIE etcher supply. Applied Materials leverages its installed base in high-aspect-ratio silicon etching to sustain service revenue across mature nodes. Lam Research Corporation anchors its position through proprietary Bosch process modules that dominate 3D NAND fabrication. Tokyo Electron Limited competes via cryogenic etching platforms optimized for sub-7nm logic devices.
Deep Reactive Ion Etching (DRIE) etcher systems deploy fluorine-based plasma chemistries in time-multiplexed or continuous-wave modes to achieve vertical sidewall profiles with aspect ratios exceeding 50:1 in silicon substrates. The equipment typically operates at substrate temperatures between -110°C and +40°C depending on process variant, enabling precise microstructure definition for MEMS, power devices, and advanced packaging interconnects. Single wafer etchers capture the dominant margin pool as foundries prioritize throughput and particle control over batch efficiency. Bosch process technology leads in volume terms due to its established role in 3D sensor and TSV formation, while cryogenic etching represents the fastest-growing segment as logic manufacturers seek reduced sidewall roughness for sub-5nm features.
EPA regulations on perfluorinated compound emissions constrain process gas selection and abatement system design in US-based fabrication facilities. REACH and the F-Gas Regulation in Europe impose phased restrictions on sulfur hexafluoride and nitrogen trifluoride, compelling etcher OEMs to qualify alternative chemistries. China's MIIT and GB standards mandate domestic equipment certification thresholds that shape procurement criteria for local fabs. Stakeholders must monitor evolving fluorinated gas legislation across manufacturing geographies to anticipate retrofit cycles and qualification timelines for next-generation chemistries.
Market Dynamics
The transition from planar to three-dimensional device architectures is compressing etch cycle times and forcing simultaneous upgrades to gas delivery, wafer temperature control, and endpoint detection systems across installed tool bases.
Growth Catalysts
- 3D NAND stacking:Memory manufacturers now exceed 200-layer vertical structures, requiring sequential high-aspect-ratio etching steps that multiply DRIE tool utilization rates per wafer.
- EU F-Gas Regulation phase-down:The 2024-2030 sulfur hexafluoride quota reductions are accelerating qualification of fluorine-nitrogen chemistries that favor newer etcher architectures with advanced abatement integration.
- Automotive MEMS sensors:Tier-1 suppliers in Germany and Japan are expanding inertial measurement unit capacity for autonomous braking and stability control, driving Bosch process tool orders.
Market Restraints
- Helium supply concentration:Cryogenic etching platforms depend on helium for wafer cooling, with Qatar and the United States controlling over 75% of global liquefaction capacity, exposing tool uptime to geopolitical logistics.
- Sub-7nm technical floor:Cryogenic DRIE reaches fundamental limits in sidewall roughness control below 3nm feature sizes, pushing logic manufacturers toward atomic layer etching alternatives for gate-all-around transistors.
- China GB certification timelines:MIIT equipment qualification protocols extend 18-24 months for imported etchers, delaying revenue recognition for non-domestic suppliers in the country's foundry build-out.
Strategic Opportunities
- India semiconductor subsidies:The country's PLI scheme for fabs and ATMP facilities creates first-mover positioning for etcher vendors willing to establish local service infrastructure ahead of 2026-2027 tool procurement waves.
- Glass interposer TSVs:Emerging advanced packaging architectures for photonics and RF modules are opening etch applications in borosilicate substrates, a material segment with limited incumbent process knowledge.
- SF6 alternative mandates:Japan's METI fluorinated gas reduction roadmap is creating regulatory pull for C4F8 and C3F6-based process modules that incumbent vendors can retrofit to extend installed base life.
Industry Challenges
- Plasma physics specialization gap:The intersection of surface chemistry, RF engineering, and vacuum technology required for next-generation cryogenic modules exceeds the training pipeline output from European and North American university programs.
- Legacy tool protocol fragmentation:Proprietary SECS/GEM implementations across 1990s-2010s etcher vintages complicate fab-wide automation upgrades and smart manufacturing integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Reactive Ion Etching (DRIE) Etcher Market |
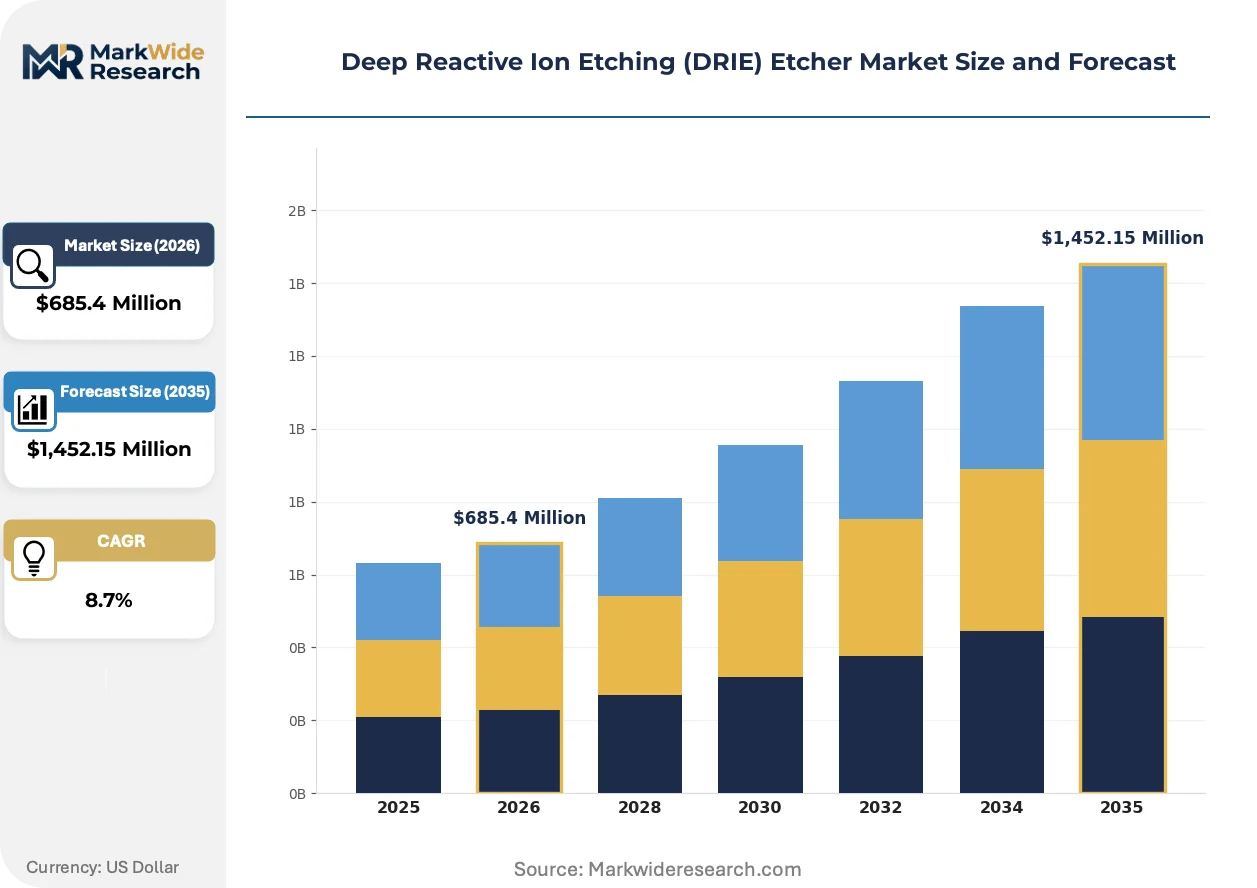
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wafer Etchers, Batch Etchers, Vertical Etchers, Plasma Etchers Technology: Bosch Process, Cryogenic Etching, Silicon Etching, Deep Silicon Etching End User: Semiconductor Manufacturers, MEMS Fabricators, Microelectronics Companies, Research Institutions Application: Microfabrication, Sensor Development, Optoelectronic Devices, Integrated Circuits |
| Companies Covered | Applied Materials, Lam Research Corporation, Tokyo Electron Limited, Plasma-Therm, SPTS Technologies, Hitachi High-Tech, Oxford Instruments, NAURA Technology Group, AMEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Reactive Ion Etching (DRIE) Etcher Market Trends and Innovations
Equipment architecture is converging around modular gas abatement and real-time spectroscopic endpoint detection as environmental compliance and process control tolerances tighten simultaneously across memory and logic fabrication.
Cryogenic etching technology is hybridizing conventional Bosch process hardware with sub-110°C wafer cooling and pulsed plasma modulation to achieve sub-1nm sidewall roughness in silicon. Leading-edge logic foundries in Taiwan and South Korea are adopting these platforms for gate-all-around nanosheet formation. The technology is hybridizing process development timelines by collapsing separate lithography-etch-lithography sequences into single-patterning steps.
REACH restrictions on perfluorinated compound emissions are compelling etcher OEMs to qualify C4F8 and fluorocarbon blends as SF6 replacements in European fabrication facilities. The industrial consequence is a 15-20% reduction in etch rate that must be compensated through higher source power or extended process time. Memory manufacturers with established 3D NAND lines are most affected, responding through selective retrofit of abatement systems rather than full tool replacement.
After-sales service unbundling is separating hardware warranties from process recipe support and gas consumption optimization consulting. Foundry procurement teams in Singapore and Israel now negotiate these elements through distinct vendor relationships, with specialized service firms capturing margin previously retained by original equipment manufacturers. Equipment utilization contracts based on etched wafer throughput rather than scheduled maintenance intervals are gaining traction in high-volume memory fabs seeking to align vendor incentives with yield outcomes.
Deep Reactive Ion Etching (DRIE) Etcher Market Segmentation
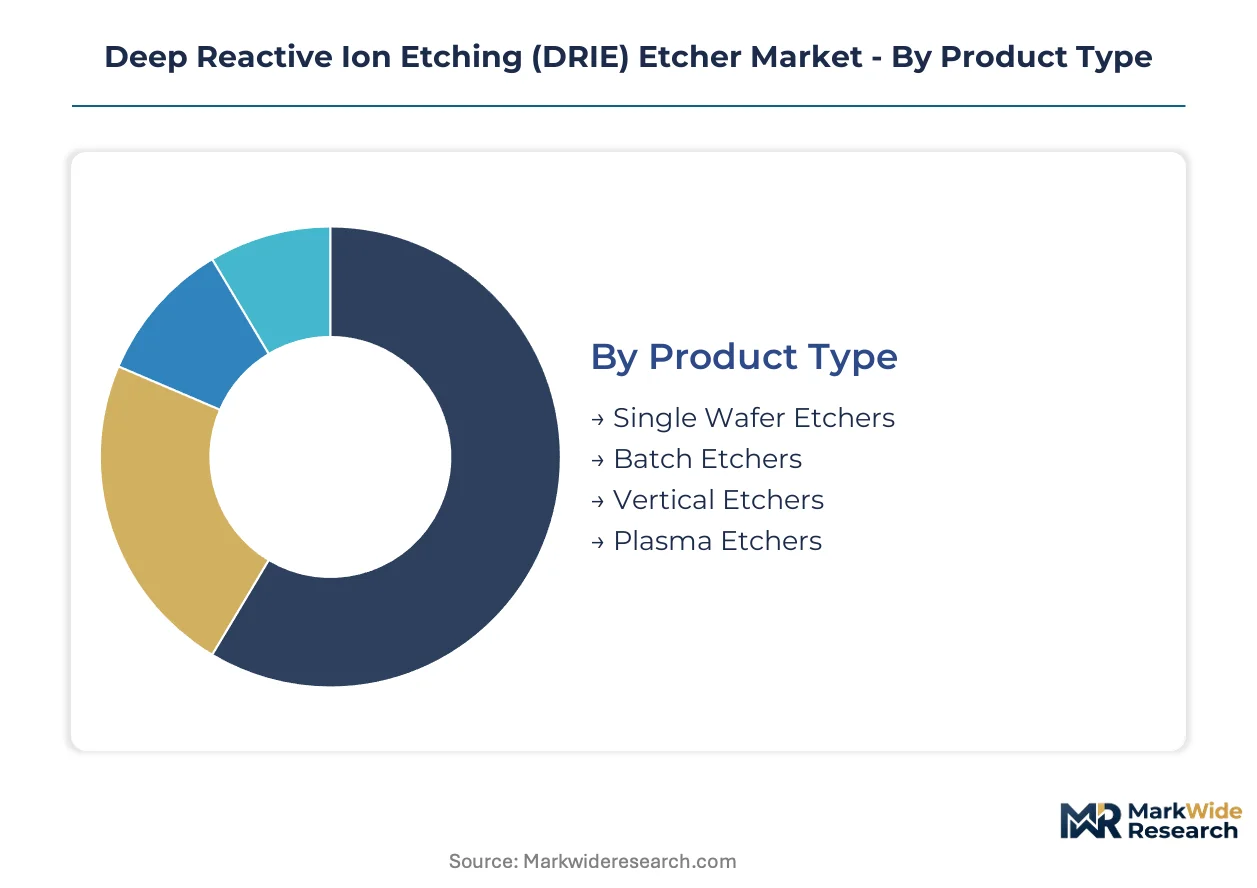
DRIE etcher procurement patterns diverge sharply across product architectures, process technologies, and end-use applications. Equipment specification requirements from memory foundries, MEMS specialists, and research laboratories create distinct demand clusters that shape vendor R&D priorities and regional sales strategies.
Product Type:
Mature high-throughput architectures dominate foundry procurement, while emerging configurations address specialized cooling and batch efficiency requirements.
- Single Wafer Etchers:These systems process one substrate at a time with precision temperature control and advanced endpoint detection. Taiwan and South Korea foundries prioritize single wafer platforms for 3D NAND and advanced packaging where particle contamination risks mandate isolated processing environments.
- Batch Etchers:Multiple wafers etch simultaneously in shared plasma chambers, delivering cost efficiency for mature node production. MEMS fabricators in Germany and Japan leverage batch systems for high-volume inertial sensor manufacturing where throughput outweighs extreme precision requirements.
- Vertical Etchers:Stacked chamber designs minimize fab footprint while maintaining isolation between process steps.
- Plasma Etchers:Continuous-wave plasma systems serve research and pilot line applications requiring flexible chemistry modulation.
Single wafer etchers handle the majority of throughput; cryogenic-enhanced variants are gaining share fastest in sub-7nm logic fabrication.
Technology:
Cost tier differentiation separates established process modules from capital-intensive next-generation platforms requiring specialized gas abatement and ultra-low temperature infrastructure.
- Bosch Process:Time-multiplexed fluorine-based etching alternates between passivation and etch cycles to achieve vertical sidewalls with aspect ratios exceeding 50:1. This mature technology anchors 3D NAND fabrication and TSV formation across Samsung and SK Hynix facilities in South Korea.
- Cryogenic Etching:Sub-110°C wafer cooling combined with pulsed plasma modulation reduces sidewall roughness below 1nm. TSMC and Samsung Foundry deploy these platforms for gate-all-around nanosheet formation where atomic-scale precision determines transistor performance.
- Silicon Etching:Standard fluorine chemistry processes for general-purpose microstructuring applications.
- Deep Silicon Etching:Extended high-aspect-ratio variants optimized for MEMS release structures and through-wafer vias.
Bosch process technology commands the largest installed base; cryogenic etching exhibits the steepest expansion trajectory as logic nodes advance below 5nm.
End User:
Volume concentration varies dramatically across customer types, from high-volume production fabs to fragmented research procurement with distinct specification and service requirements.
- Semiconductor Manufacturers:Integrated device foundries and memory producers operate the largest etcher fleets with 24/7 utilization targets. These buyers negotiate outcome-based service contracts tied to etched wafer throughput rather than scheduled maintenance intervals.
- MEMS Fabricators:Specialized sensor manufacturers prioritize Bosch process tools for accelerometer and gyroscope production. Bosch Sensortec and STMicroelectronics drive capacity expansion for automotive stability control and consumer motion tracking applications.
- Microelectronics Companies:Power device and RF component suppliers with mixed analog-digital process requirements.
- Research Institutions:University cleanrooms and national laboratories with flexible specification tolerance and extended procurement cycles.
Semiconductor manufacturers absorb the dominant equipment volume; MEMS fabricators are expanding procurement most aggressively for automotive sensor build-outs.
Application:
Geography-driven demand clusters emerge from regional specialization in memory, logic, and sensor fabrication ecosystems.
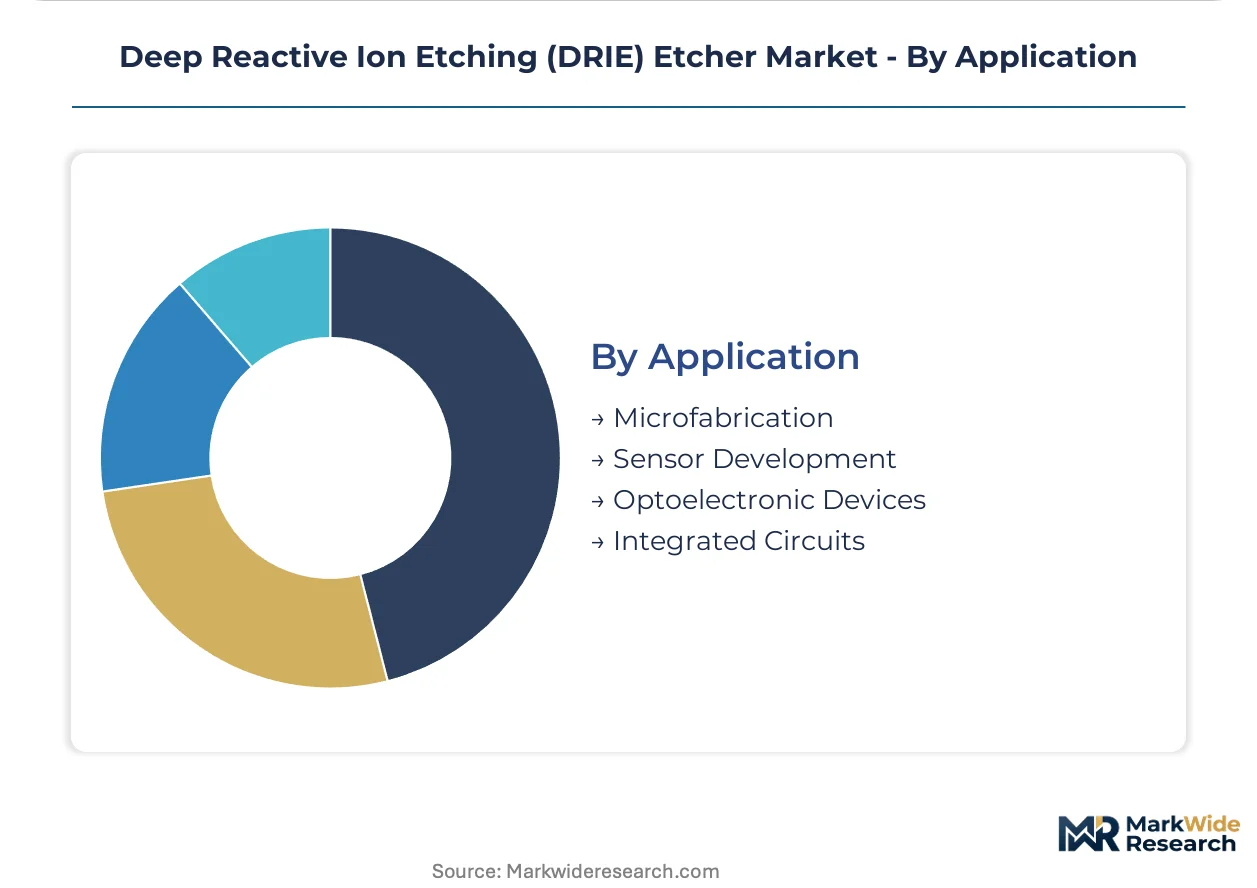
- Microfabrication:General-purpose etching for mechanical structures, fluidic channels, and optical components spans academic and industrial R&D. Singapore and Israel host concentrated microfabrication service bureaus serving photonics and medical device prototyping.
- Sensor Development:Pressure, inertial, and environmental sensor manufacturing requires high-aspect-ratio release etches. German automotive Tier-1 suppliers and Japanese industrial electronics makers anchor this segment with stringent reliability qualification protocols.
- Optoelectronic Devices:VCSELs, photodetectors, and LiDAR components etched for optical cavity definition.
- Integrated Circuits:Logic and memory device fabrication with the most demanding linewidth and roughness specifications.
Integrated circuits applications consume the most etch capacity; sensor development is climbing fastest on expanding automotive MEMS demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taoyuan high-speed rail corridor underwrites Taiwan's dominance in advanced packaging tool procurement, connecting the Hsinchu Science Park to southern foundry clusters within 90 minutes.
United States
Memory manufacturers in Boise and Austin are expanding 3D NAND capacity for data center storage. EPA regulations on perfluorinated compound emissions constrain process gas selection at fabrication facilities in Oregon and Arizona. The Albany Nanotech Complex in New York anchors public-private R&D partnerships for next-generation etch chemistries.
China
Domestic foundries in Shanghai and Beijing are scaling mature-node capacity for power semiconductors and MEMS. MIIT certification protocols extend 18-24 months for imported etchers, delaying revenue recognition for non-domestic suppliers. The Yangtze River Delta cluster concentrates procurement activity as local fabs prioritize equipment with GB standard compliance.
South Korea
Samsung and SK Hynix are exceeding 200-layer vertical NAND structures, multiplying DRIE tool utilization rates per wafer. METI-aligned fluorinated gas reduction roadmaps influence chemistry qualification timelines for Korean memory exports to Japan. The Pyeongtaek-Suwon corridor hosts concentrated etcher deployment for advanced packaging and 3D integration.
Germany
Bosch Sensortec and automotive Tier-1 suppliers are expanding inertial measurement unit capacity for autonomous braking systems. The EU F-Gas Regulation phase-down accelerates qualification of fluorine-nitrogen chemistries favoring newer etcher architectures. Dresden's Silicon Saxony cluster anchors MEMS fabrication with stringent reliability qualification protocols for automotive sensor deployment.
Japan
Industrial electronics makers in Kyoto and Osaka are driving Bosch process tool orders for pressure and environmental sensors. METI's fluorinated gas reduction roadmap creates regulatory pull for C4F8 and C3F6-based process modules. The Tohoku region's materials science infrastructure supports cryogenic etching platform development for sub-7nm logic applications.
Deep Reactive Ion Etching (DRIE) Etcher Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in gas delivery, RF matching networks, and vacuum subsystems. The supplier base consolidates around three to four dominant equipment OEMs with established service infrastructures, while niche players occupy specialized cooling and endpoint detection segments. Two strategic archetypes prevail: full-stack etcher manufacturers with proprietary process modules, and modular subsystem vendors licensing technology to multiple OEMs. Competitive moves concentrate on M&A for cryogenic technology access and geographic expansion into emerging fab locations.
Among North American platform vendors, Applied Materials and Lam Research Corporation exemplify the integrated equipment archetype with extensive installed bases in high-aspect-ratio silicon etching. Tokyo Electron Limited anchors the Asia-Pacific supplier tier, representing the cryogenic specialization vector that logic foundries prioritize for sub-7nm device formation. Oxford Instruments and SPTS Technologies occupy positions in the European and research-oriented equipment segments respectively.
| Leading Market Players |
|---|
| Applied Materials |
| Lam Research Corporation |
| Tokyo Electron Limited |
| Plasma-Therm |
| SPTS Technologies |
| Hitachi High-Tech |
| Oxford Instruments |
| NAURA Technology Group |
| AMEC |
| Others |
Pricing and Supply Chain Analysis
Helium supply concentration in Qatar and the United States determines both the cost spread between cryogenic and conventional etcher tiers and the geographic clustering of advanced tool deployment. Memory foundries in South Korea and Taiwan absorb premium pricing for guaranteed helium allocation, while European and North American buyers face longer lead times and elevated service contract premiums that compress margins on mid-range Bosch process systems.
Pricing Analysis
Volume-discount tiering structures separate contract pricing for memory foundries ordering twenty-plus units annually from spot procurement by research institutions and pilot lines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GB-compliant systems for China commanding premiums over CE-marked European configurations. Cost compression in the standard tier is intensifying because Japanese and Korean OEMs are qualifying alternative fluorocarbon chemistries that reduce consumables costs. Research institutions exhibit the highest price sensitivity due to grant-funded capital cycles, whereas integrated memory manufacturers prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Supplier-financing facilities from Japanese trading houses and Korean equipment lessors extend payment terms to 24-36 months for foundry customers, easing capital burden during fab construction cycles. Critical component manufacturing concentrates in Japan, Germany, and the United States, with RF matching networks and cryogenic chillers drawing from specialized precision engineering clusters. High-purity fluorinated gases and helium for wafer cooling rest on concentrated liquefaction capacity in Qatar and the United States, exposing tool uptime to geopolitical logistics disruption. Distribution runs through direct OEM sales teams for high-volume foundry accounts, while regional distributors serve fragmented MEMS and research segments with localized service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among memory and logic foundries consolidating procurement through multi-year framework agreements, squeezing margin capture from smaller equipment vendors unable to match service infrastructure scale.
For Market Incumbents: Harden installed base retention through captive supply of refurbished process modules and consumables, locking customers into chemistry-optimized service contracts that raise switching costs. Deepen backward integration into cryogenic chiller manufacturing to offset helium supply volatility and capture margin currently flowing to Japanese precision cooling specialists. Prioritize GB certification pre-qualification for China-bound tool shipments to compress the 18-24 month MIIT approval timeline that delays revenue recognition against domestic competitors. For New Entrants and Emerging Players: India's underpenetrated fab infrastructure offers first-mover positioning ahead of PLI scheme procurement waves, particularly for etcher vendors willing to establish local service depots in Gujarat and Karnataka. Target glass interposer TSV applications in photonics and RF modules, where limited incumbent process knowledge in borosilicate substrates creates specification flexibility for new chemistry qualifications. Lead with outcome-based pricing tied to etched wafer throughput rather than capital equipment sale, aligning vendor incentives with foundry yield outcomes and differentiating against established OEM maintenance models. For Investors and Strategic Acquirers: The EU F-Gas Regulation phase-down reshapes the acquisition landscape toward cryogenic technology platforms and alternative chemistry intellectual property that incumbent vendors must retrofit or license. Five-to-ten year viability favors specialists with proven sub-110°C process modules and established abatement integration, as logic manufacturers advance below 3nm feature sizes. Monitor Japan METI fluorinated gas reduction roadmap implementation as the signal for accelerated C4F8 and C3F6 chemistry qualification timelines that would elevate acquisition premiums for compliant technology assets.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Technology Acquisition | Captures logic foundry demand for sub-5nm gate-all-around nanosheet formation in Taiwan and South Korea. |
| Alternative Chemistry Qualification | Positions vendors ahead of EU F-Gas Regulation sulfur hexafluoride quota reductions affecting memory exports. |
| Local Service Infrastructure Buildout | Enables participation in India's PLI scheme fab and ATMP procurement cycles through Gujarat-based technical support. |
| Outcome-Based Contract Structuring | Aligns vendor incentives with foundry yield outcomes via etched wafer throughput pricing rather than scheduled maintenance. |
| Glass Interposer Process Development | Opens etch applications in borosilicate substrates for photonics and RF modules with limited incumbent expertise. |
Research Methodology
Operator-level perspectives from fab process engineers, equipment procurement managers, and aftermarket service directors anchored the qualitative base, supplemented by regulatory affairs specialists tracking fluorinated gas legislation across manufacturing geographies. Primary interview insights triangulated against secondary validation from SEC filings of major OEMs, customs data on etcher import flows into China and India, and MIIT equipment certification databases. Bottom-up unit deployment estimates across foundry clusters combined with top-down market sizing derived from capital expenditure disclosures of Samsung, TSMC, and SK Hynix.
Scenario-bracketing framed optimistic and conservative trajectories based on China domestic equipment substitution rates and helium supply disruption probability. The analytical framework segmented by product architecture, process technology, and end-use application across the projection horizon, with CAGRs derived from tool utilization rate assumptions tied to 3D NAND layer count expansion and MEMS automotive sensor build-outs. Cryogenic platform adoption curves and alternative chemistry qualification timelines served as industry-specific forecast inputs.
Practitioners should monitor regulatory acceleration in fluorinated gas phase-down schedules and geopolitical helium supply disruptions for early signals of demand trajectory revision. Forecasts reflect assumptions regarding memory capital expenditure continuity and logic node advancement pace. Macroeconomic contraction in semiconductor end-markets, regulatory restriction tightening beyond current EU and Japan roadmaps, or breakthrough atomic layer etching displacement of cryogenic DRIE would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Holmium Sputtering Target Market