
 Etchant for FPD Market | 2026-2036
Etchant for FPD Market Size, Share, and Industry Trends Forecast 2026-2036
Etchant for FPD Market Insights
Japan's Chemical Substances Control Law revision is expanding compliance burdens for etchant suppliers serving FPD manufacturers, forcing reformulation investments across the supply base. Tokyo Electron Ltd. leverages its integrated process equipment-etchant bundling to sustain premium positioning in advanced OLED lines. ULVAC Inc. anchors its competitiveness through captive vacuum technology synergies with wet chemical processing. Mitsubishi Gas Chemical specializes in ultra-high-purity acid blends that dominate critical layer patterning for mobile displays.
Etchant for FPD denotes chemically reactive formulations—typically nitric acid, acetic acid, or organic amine blends at controlled molarity and particle counts below 100 ppt—that selectively dissolve metal, oxide, or semiconductor thin films during photolithographic patterning in flat panel display fabrication. Acidic etchants retain the largest volume share in current-generation TFT-LCD and OLED manufacturing due to their established compatibility with indium tin oxide and molybdenum-based interconnects. Alkaline etchants are displacing solvent-based alternatives in copper electrode processing as foundries seek lower-toxicity waste streams. Display Manufacturing absorbs the dominant share of etchant value, while Semiconductor Processing represents the fastest-expanding application segment as chiplet-in-display architectures proliferate.
Japan's METI enforces purity and traceability standards that effectively gate non-domestic suppliers from its display chemical market. South Korea's MFDS and Ministry of Environment jointly regulate etchant discharge limits, compelling closed-loop recycling investments at Samsung Display and LG Display supplier parks. China's MEE implements dual carbon goals that restrict perfluorinated compound emissions from solvent etchant processes. Stakeholders must weigh regional regulatory divergence against the capital efficiency of centralized etchant formulation plants.
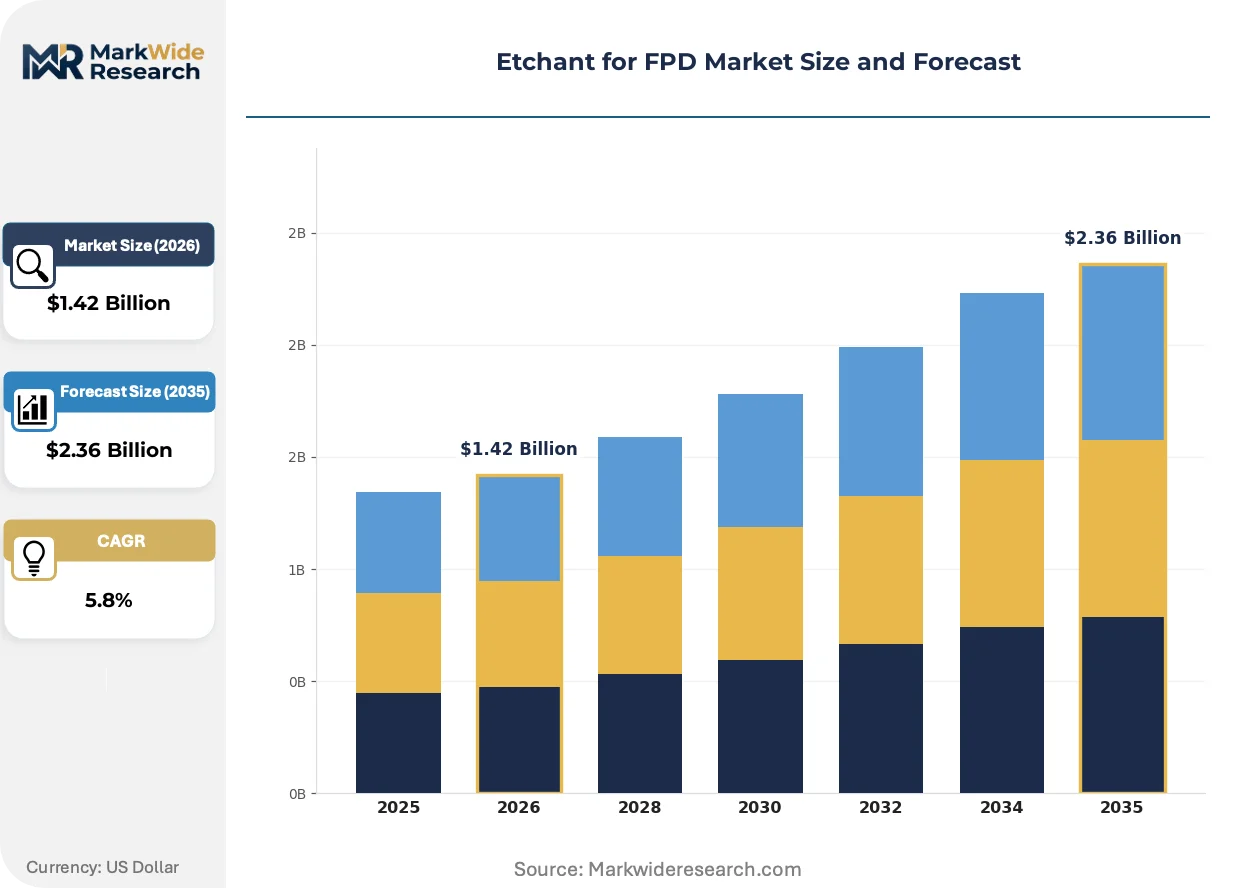
Market Dynamics
OLED panel makers in South Korea and Japan are demanding sub-100 ppt particle counts in etchant formulations, forcing reformulation cycles that compress supplier margins while locking in premium pricing for purity-certified vendors.
Growth Catalysts
- Gen 8.5 OLED capacity expansion:Samsung Display and LG Display are commissioning new vapor deposition lines that require specialized copper-molybdenum etchant blends for finer interconnect patterning.
- METI Chemical Substances Control Law:Japan's tightened traceability mandates for display-grade chemicals are accelerating domestic supplier consolidation and premium-grade qualification.
- Chiplet-in-display architectures:Semiconductor processing applications for etchants are expanding as panel-integrated driver ICs require back-end-of-line metal etching steps.
Market Restraints
- High-purity acid supply concentration:Ultra-grade nitric acid feedstock production clusters in Japan and Germany, creating geographic vulnerability for non-integrated formulators.
- Perfluorinated compound emission ceilings:China's MEE dual carbon goals restrict solvent-based etchant processes, forcing capital-intensive abatement retrofits at older fabs.
- Alternative patterning technologies:Laser ablation and inkjet printing for metal interconnects threaten wet etchant volumes in mid-size OLED panel segments.
Strategic Opportunities
- Closed-loop chemical recycling:South Korea's MFDS discharge limits are compelling supplier park investments in on-site etchant regeneration, creating service-revenue streams.
- MicroLED transfer processing:Emerging microLED display fabrication requires indium gallium zinc oxide etching steps that demand novel organic amine formulations.
- EU F-Gas Regulation phase-down:Fluorinated solvent etchants face substitution pressure, opening market share for aqueous alkaline alternatives in European-bound display exports.
Industry Challenges
- Cleanroom-grade logistics certification:Transporting particle-sensitive etchants requires ISO 14644-1 Class 3-compatible tanker fleets that few regional distributors maintain.
- Legacy TFT-LCD etchant inventory:Amorphous silicon-focused acid blends face obsolescence as panel makers pivot to oxide semiconductor backplanes, stranding formulation assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Etchant for FPD Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acidic Etchants, Alkaline Etchants, Solvent-Based Etchants, Bio-Based Etchants Application: Display Manufacturing, Semiconductor Processing, Solar Cell Production, PCB Fabrication End User: Telecommunications, Consumer Electronics, Automotive Suppliers, Aerospace Packaging Type: Bulk Containers, Bottles, Sachets, Drums |
| Companies Covered | Tokyo Electron Ltd., ULVAC Inc., Shibaura Mechatronics Corp, Samco Inc, Panasonic Holdings Corp., SCREEN Holdings Co., Ltd., Applied Materials Inc., Lam Research Corporation, Mitsubishi Gas Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Etchant for FPD Market Trends and Innovations
Etchant supply relationships are restructuring around captive regeneration services and purity-guaranteed long-term contracts rather than spot chemical purchases, compressing the vendor base while extending supplier tenures.
Inline chemical concentration monitoring using Raman spectroscopy is automating bath-life management in OLED wet-etch stations, reducing unplanned downtime. Samsung Display's Tangjeong fab has deployed these systems across Gen 6 lines, cutting manual sampling labor by half. The technology is automating process control decisions previously requiring on-site chemical engineers, enabling thinner staffing models at new greenfield sites.
Japan's METI is expanding mandatory substance-by-substance reporting under its Chemical Substances Control Law revision, effective for display chemical imports. Formulators must now document supply-chain provenance for every acid lot, adding documentation overhead that favors integrated producers over trading-house intermediaries. South Korean panel makers are responding by pre-qualifying Japanese suppliers with existing METI compliance infrastructure.
Consolidated chemical management contracts are displacing discrete etchant purchases at major display clusters, bundling formulation supply with waste handling and bath analysis. This model concentrates procurement authority at headquarters level, squeezing regional distributors. The shift is most visible in South Korea's Gumi cluster, where LG Display has consolidated three former suppliers into a single five-year integrated services agreement.
Etchant for FPD Market Segmentation
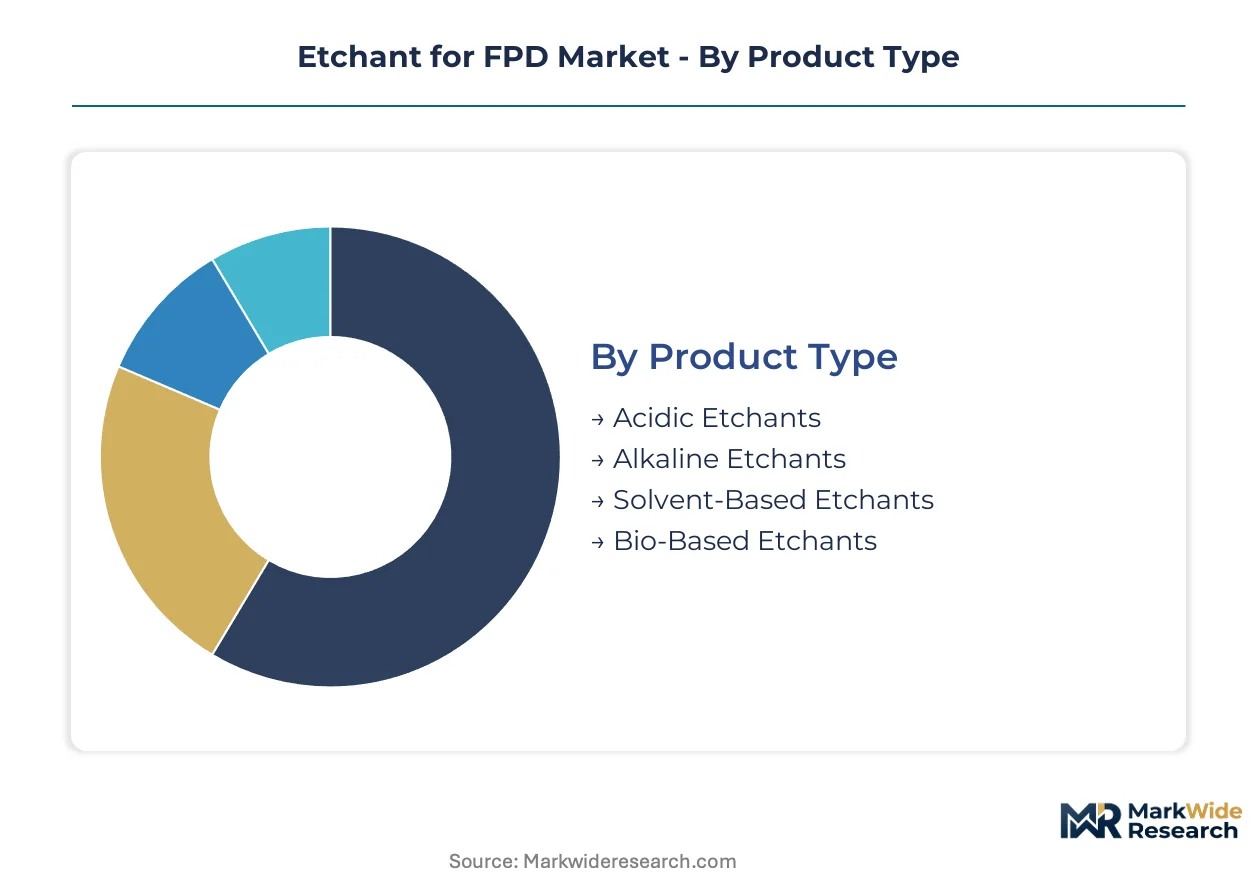
Etchant segmentation tracks directly to the technology transitions reshaping display fabrication. Each category maps to distinct purity specifications, regulatory compliance burdens, and logistics requirements that determine supplier competitiveness.
Product Type:
Upgrade cycles from legacy TFT-LCD to OLED and microLED architectures are forcing reformulation investments across all etchant chemistries. Panel makers now qualify suppliers on particle-count performance rather than acid concentration alone.
- Acidic Etchants:Nitric acid, acetic acid, and phosphoric acid blends at controlled molarity dominate indium tin oxide and molybdenum interconnect patterning. Samsung Display's Tangjeong fab consumes the largest single-site volumes of ultra-high-purity acidic formulations for Gen 6 OLED production, where sub-100 ppt particle specifications gate supplier eligibility.
- Alkaline Etchants:Organic amine and tetramethylammonium hydroxide solutions enable copper electrode processing with lower-toxicity waste profiles. South Korea's MFDS discharge limits are accelerating alkaline substitution for solvent-based alternatives in Gumi cluster supplier parks, compressing qualification timelines for compliant formulators.
- Solvent-Based Etchants:Perfluorinated compound formulations face regulatory pressure from China's MEE dual carbon goals and the EU F-Gas Regulation phase-down, forcing abatement investments at legacy fabs.
- Bio-Based Etchants:Emerging formulations using biodegradable organic acids target sustainability mandates in European-bound display exports, though purity certification lags petrochemical alternatives.
Volume placements concentrate in Acidic Etchants; the faster expansion belongs to Alkaline Etchants.
Application:
Application segmentation reflects the blurring boundary between display panel and semiconductor processing as chiplet-in-display architectures proliferate. Each application carries distinct bath-life requirements and contamination sensitivity thresholds.
- Display Manufacturing:Thin-film transistor patterning for LCD, OLED, and emerging microLED panels absorbs the dominant share of etchant value. Japan's METI Chemical Substances Control Law revision imposes substance-by-substance traceability that favors integrated suppliers over trading-house intermediaries in this high-volume segment.
- Semiconductor Processing:Back-end-of-line metal etching for panel-integrated driver ICs demands novel formulations compatible with fragile organic substrates. This segment is expanding most quickly as foundries adopt chiplet architectures that embed logic dies directly on display backplanes.
- Solar Cell Production:Texturing and edge-isolation etching for photovoltaic manufacturing uses lower-purity acid grades with less stringent particle specifications.
- PCB Fabrication:Printed circuit board etching consumes commodity-grade ferric chloride and cupric chloride solutions outside the high-purity display chemical supply chain.
Display Manufacturing commands the largest absolute volumes; Semiconductor Processing shows the steepest expansion trajectory.
End User:
End-user segmentation tracks etchant demand to the downstream device categories driving panel specification evolution. Each sector imposes distinct reliability and environmental operating requirements that propagate backward to chemical formulation standards.
- Consumer Electronics:Smartphone, tablet, and wearable display production generates the most demanding purity requirements. South Korea's Tangjeong and Gumi clusters supply Apple, Samsung Electronics, and Chinese OEMs with panels requiring etchants certified to sub-50 ppt metal ion specifications for flexible OLED modules.
- Automotive Suppliers:In-vehicle display integration demands etchants compatible with extended temperature cycling and vibration resistance, driving qualification of specialized oxide semiconductor etching chemistries.
- Telecommunications:Base station and network equipment displays use lower-resolution panels with correspondingly relaxed etchant purity tiers.
- Aerospace:Avionics display applications represent a niche segment with extreme reliability certification requirements and limited supplier pools.
Consumer Electronics absorbs the dominant placement volumes; Automotive Suppliers are gaining share fastest as cockpit display penetration deepens.
Packaging Type:
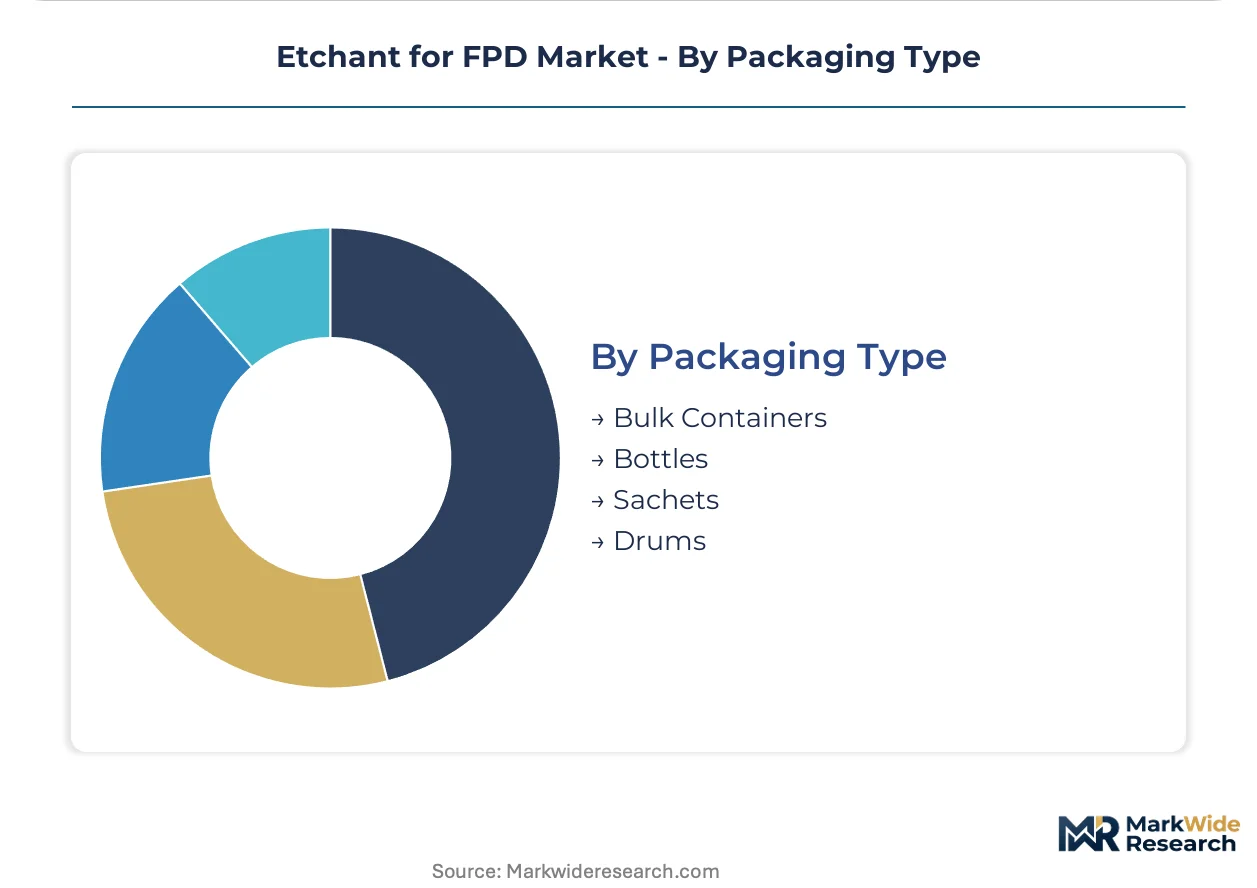
Packaging segmentation determines logistics cost structures and contamination risk exposure throughout the supply chain. The shift toward consolidated chemical management contracts is restructuring procurement authority around packaging standardization.
- Bulk Containers:ISO tank deliveries of 20,000-liter batches serve high-throughput fabs with on-site purification and blending infrastructure. LG Display's Gumi cluster has consolidated three former suppliers into single five-year agreements specifying dedicated bulk tanker fleets with ISO 14644-1 Class 3 cleanroom certification.
- Drums:200-liter steel and polyethylene drums remain the workhorse format for mid-volume fabs without captive regeneration capabilities, though handling labor adds cost.
- Bottles:Laboratory-scale and pilot-line quantities use fluoropolymer bottles for high-value organic amine etchants where contamination sensitivity exceeds bulk logistics feasibility.
- Sachets:Pre-measured single-use pouches target specialty applications and maintenance-of-protocol requirements in aerospace and medical display segments.
Bulk Containers dominate volume economics; Bottles are climbing fastest as microLED pilot lines proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tangjeong and Gumi in South Korea concentrate the highest etchant consumption volumes globally, driven by Samsung Display and LG Display operating massive Gen 8.5 and Gen 6 OLED fabs that demand sub-100 ppt particle specifications.
South Korea
Samsung Display's Tangjeong complex and LG Display's Gumi cluster anchor regional etchant demand through Gen 6 and Gen 8.5 OLED production lines. The Ministry of Environment and MFDS jointly enforce discharge limits that compel closed-loop recycling investments at supplier parks. Gumi's consolidated chemical management contracts now bundle formulation supply with waste handling, squeezing regional distributor margins.
Japan
Domestic panel makers and semiconductor fabricators drive demand for ultra-high-purity acid blends certified to METI's Chemical Substances Control Law. METI's substance-by-substance traceability mandates, effective for display chemical imports, favor integrated producers with existing compliance infrastructure. Tokyo Electron Ltd. and Mitsubishi Gas Chemical leverage captive vacuum technology and ultra-high-purity formulation capabilities to sustain premium positioning in advanced OLED lines.
China
Display panel expansion in the Yangtze River Delta and Pearl River Delta generates growing volumes of etchant consumption for TFT-LCD and emerging OLED fabs. The Ministry of Ecology and Environment implements dual carbon goals that restrict perfluorinated compound emissions from solvent etchant processes, forcing capital-intensive abatement retrofits. Domestic formulators face technical gaps in sub-100 ppt particle control for mobile display applications.
United States
Specialized semiconductor processing applications for chiplet-in-display architectures represent the fastest-expanding etchant demand segment. The EPA regulates hazardous waste streams from wet chemical processing under RCRA, influencing formulation choices at domestic fabs. Arizona and Texas host emerging display backplane fabrication facilities that source high-purity etchants through qualified Japanese and Korean suppliers.
Germany
Automotive display integration and industrial panel applications sustain modest but technically demanding etchant consumption. The EU F-Gas Regulation phase-down pressures fluorinated solvent etchants, opening market share for aqueous alkaline alternatives in European-bound display exports. Bavaria's precision manufacturing clusters maintain ISO 14644-1 Class 3-compatible logistics infrastructure for particle-sensitive chemical deliveries.
Etchant for FPD Market Competitive Landscape
The competitive structure tilts toward integrated equipment-chemical bundling and captive purity certification rather than commodity formulation supply. Three to five Japanese and Korean conglomerates dominate premium-tier positioning through backward integration into ultra-grade feedstock production and in-house vacuum technology synergies. Strategic moves concentrate on long-term integrated services agreements, on-site regeneration capabilities, and METI compliance infrastructure lock-in that extends supplier tenures while compressing the vendor base.
Among Japan-based integrated suppliers, Tokyo Electron Ltd., ULVAC Inc., and Mitsubishi Gas Chemical exemplify the equipment-chemical bundling archetype that sustains premium positioning in advanced OLED lines. Tokyo Electron Ltd. represents the process equipment-etchant integration model, while ULVAC Inc. anchors its competitiveness through captive vacuum technology synergies with wet chemical processing. Mitsubishi Gas Chemical occupies a position as a specialist in ultra-high-purity acid blends for critical layer patterning. These three companies collectively illustrate how METI compliance infrastructure and purity certification capabilities determine supplier eligibility in high-specification display markets.
| Leading Market Players |
|---|
| Tokyo Electron Ltd. |
| ULVAC Inc. |
| Shibaura Mechatronics Corp |
| Samco Inc |
| Panasonic Holdings Corp. |
| SCREEN Holdings Co., Ltd. |
| Applied Materials Inc. |
| Lam Research Corporation |
| Mitsubishi Gas Chemical |
| Others |
Pricing and Supply Chain Analysis
Premium-grade certification divergence between sub-100 ppt particle-qualified suppliers and commodity formulators manifests in both contract value and logistics infrastructure requirements. Japanese METI-compliant producers command long-term integrated services agreements at Samsung Display's Tangjeong fab, while non-certified traders compete on spot pricing for lower-specification TFT-LCD lines.
Pricing Analysis
Yield-guaranteed throughput pricing anchors contract structures, with formulators absorbing bath-life performance risk in exchange for per-panel premiums. Price differentiation rests on METI traceability certification and ISO 14644-1 Class 3 logistics compliance versus standard drum delivery. Cost compression in solvent-based etchants is intensifying because China's MEE dual carbon goals force abatement retrofits. Display Manufacturing buyers show least price sensitivity for mobile OLED specifications, while Solar Cell Production segments negotiate commodity acid grades aggressively.
Supply Chain Analysis
Single-source vulnerability sits with ultra-grade nitric acid feedstock production clustered in Japan and Germany, exposing non-integrated formulators to geographic concentration risk. Raw material dependencies include electronic-grade nitric acid, organic amine precursors, and fluoropolymer packaging materials. Tariff exposure on Japanese chemical imports into South Korea threatens just-in-time delivery schedules at Gumi cluster supplier parks. Distribution runs through dedicated ISO tanker fleets with captive regeneration services at major display complexes.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where oxide semiconductor backplanes displace amorphous silicon architectures, stranding legacy etchant inventories while demanding novel organic amine formulations for copper-molybdenum interconnects.
For Market Incumbents: Anchor premium positioning through backward integration into ultra-grade acid feedstock production and captive vacuum technology synergies. Defend against laser ablation substitution threats by bundling etchant supply with inline Raman spectroscopy monitoring systems. Prioritize METI compliance infrastructure lock-in to extend supplier tenures at Japanese and Korean panel makers.
For New Entrants and Emerging Players: Launch via closed-loop chemical recycling service contracts at South Korea's MFDS-regulated supplier parks, bypassing purity certification barriers through regeneration partnerships rather than formulation competition. Target microLED pilot line bottlenecks in China and the United States where organic amine etchant qualification timelines remain open. Penetrate through technical service differentiation rather than feedstock cost parity.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated equipment-chemical bundling platforms with existing METI infrastructure and Gen 8.5 OLED line qualifications. Long-term viability favors suppliers with demonstrated sub-100 ppt particle control and on-site regeneration capabilities across the analysis window. Watch for chiplet-in-display architecture adoption rates as the inflection signal for semiconductor processing etchant demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultra-Grade Feedstock | Captive nitric acid production secures supply continuity against Japanese and German concentration. |
| Closed-Loop Chemical Recycling Deployment | On-site regeneration at Gumi and Tangjeong supplier parks meets South Korea's MFDS discharge mandates. |
| METI Compliance Infrastructure Investment | Substance-by-substance traceability systems qualify suppliers for Japan's premium display chemical tier. |
| Inline Process Monitoring Integration | Raman spectroscopy bundling automates bath-life management at Samsung Display's Gen 6 OLED lines. |
| MicroLED Etchant Formulation Development | Novel organic amine chemistries address indium gallium zinc oxide patterning in emerging transfer processes. |
Research Methodology
Document review covered customs and trade flow databases, chemical industry association reports, and regulatory filings with Japan's METI and South Korea's MFDS, complemented by interviews with plant managers at major display fabs, procurement leads at panel makers, technical R&D directors at formulators, and distribution channel partners handling ISO tank logistics. Secondary validation drew from SEC filings of listed equipment suppliers, import-export statistics, and patent disclosures in wet chemical processing. Bottom-up volume estimates from individual fab consumption patterns were cross-referenced against top-down market sizing from chemical production data.
Historical capacity expansion patterns were cross-referenced against panel maker capex disclosures and expert panel input on technology transition timelines. The analytical framework modeled segmentation across etchant chemistry type, application tier from Display Manufacturing to Semiconductor Processing, end-user device category, and packaging format throughout the projection horizon. CAGRs were derived from regression analysis of purity specification escalation curves and regulatory phase-in schedules. Industry-specific forecast inputs included Gen 8.5 OLED line commissioning announcements and chiplet-in-display architecture adoption trajectories.
The model assumes a particular technology adoption path where oxide semiconductor backplanes achieve dominant share; alternative pathways for laser ablation or inkjet printing would alter the outlook for wet etchant volumes. Forecasts reflect assumptions about METI enforcement intensity, MFDS discharge limit stringency, and MEE dual carbon implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market