
 Inline Metrology Market | 2026-2036
Inline Metrology Market Size, Share, and Industry Trends Forecast 2026-2036
Inline Metrology Market Analysis
Automotive OEMs is rotating toward fully automated inline inspection cells as electric vehicle platforms demand tighter dimensional tolerances for battery housings and powertrain assemblies. Hexagon AB leverages its software-hardware integration to dominate multi-sensor inspection lines across European and North American assembly plants. KLA Corporation anchors its position in semiconductor-adjacent metrology, extending optical inspection architectures into automotive electronics quality control. KEYENCE Corporation competes through rapid deployment vision systems that reduce integration timelines for tier-one suppliers retooling for EV geometries.
Inline metrology encompasses real-time dimensional verification and surface characterization systems integrated directly into production workflows, typically achieving sub-micron repeatability through laser triangulation, structured light projection, or chromatic confocal sensing to enable immediate process correction without workpiece removal. Coordinate Measuring Machines retain the largest installed base but face margin compression as compact optical sensors capture medium-precision applications at lower capital intensity. Vision Systems within the technology dimension represent the fastest-expanding segment, propelled by embedded GPU processing and deep-learning defect classification that reduces reliance on rule-based algorithm programming.
FDA 21 CFR Part 820 quality system regulations and EU MDR traceability requirements are elevating inline metrology from optional efficiency tool to compliance infrastructure for medical device manufacturers seeking to automate device history record generation. ISO 10360 calibration standards and VDI/VDE 2617 guidelines shape equipment specification protocols, creating certification barriers for entrants lacking accredited laboratory partnerships. Stakeholders must monitor convergence between AI-driven predictive quality platforms and traditional metrology hardware, as software-defined inspection architectures threaten to commoditize sensor hardware while concentrating value in analytics layers.
Market Dynamics
Automotive electrification is compressing dimensional tolerance windows to sub-10-micron levels for battery tray assemblies and thermal management plates, forcing manufacturers to abandon offline CMM sampling in favor of 100% inline verification cycles.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers must automate device history record generation, embedding laser triangulation sensors directly into catheter and implant finishing lines to capture continuous measurement data.
- EV platform retooling cycles:Automotive OEMs in Germany, China, and the United States are rebuilding assembly lines around multi-sensor optical cells that verify battery housing flatness and motor stator concentricity without workpiece removal.
- Deep-learning defect classification:Embedded GPU architectures within vision systems now train on production data streams, eliminating rule-based algorithm development delays that previously stalled inline deployment.
Market Restraints
- Capital intensity of multi-sensor integration:Full production line retrofits for chromatic confocal and structured light systems require 18-24 month payback horizons that deter mid-tier suppliers.
- Optical component supply concentration:High-precision laser diodes and specialized CMOS sensors concentrate among Japanese and German component specialists, creating vulnerability to allocation constraints.
- Calibration infrastructure scarcity:ISO 10360-accredited laboratories capable of certifying sub-micron repeatability remain limited to metropolitan industrial clusters in Stuttgart, Nagoya, and Detroit.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO quality mandate expansions for parenteral drug containers create first-mover advantage for vision system providers establishing local calibration partnerships.
- AI-driven predictive quality convergence:Real-time metrology data streams feeding machine learning models enable pre-emptive process correction before dimensional drift breaches tolerance bands.
- Semiconductor-adjacent automotive electronics:Power module substrate inspection for silicon carbide inverters applies wafer-scale optical architectures to automotive thermal management quality control.
Industry Challenges
- Multi-physics simulation expertise:Integrating thermal, vibrational, and optical models for production environment compensation requires rare cross-disciplinary engineering teams.
- Legacy CMM protocol incompatibility:Existing quality management software architectures resist real-time data ingestion from optical sensors, forcing middleware development or full ERP replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inline Metrology Market |
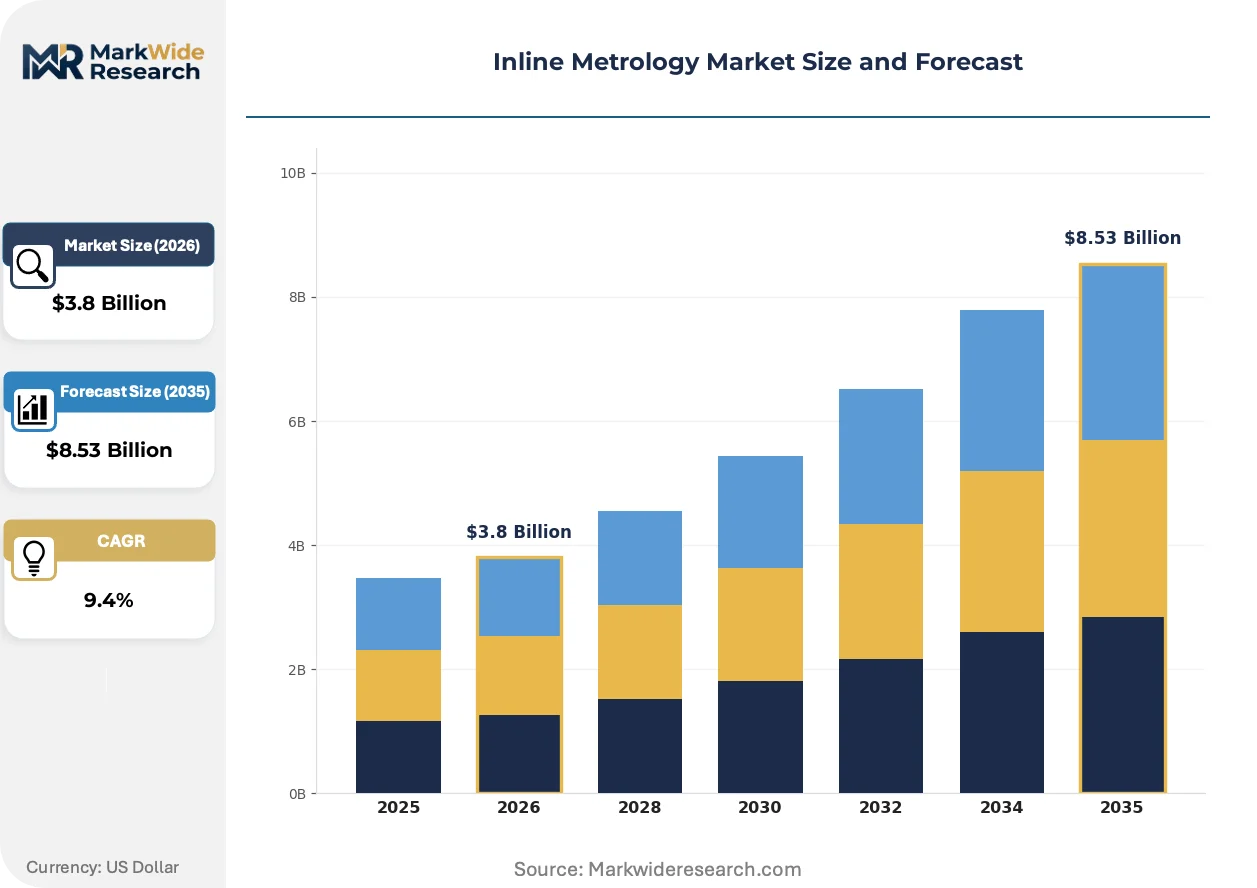
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Optical Sensors, Coordinate Measuring Machines, Ultrasonic Devices End User: Aerospace, Automotive, Electronics, Medical Devices Technology: 3D Imaging, Vision Systems, Thermal Imaging, RFID Application: Quality Control, Process Monitoring, Dimensional Measurement, Surface Profiling |
| Companies Covered | Hexagon AB, Carl Zeiss AG, KLA Corporation, KEYENCE Corporation, Mitutoyo Corporation, FARO Technologies, Inc., Renishaw plc, Nikon Metrology NV, Jenoptik AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inline Metrology Market Emerging Trajectories
Computational imaging and edge AI are collapsing the latency between measurement capture and process correction, enabling closed-loop quality control that was previously confined to laboratory environments.
Chromatic confocal sensors with nanometer-scale Z-axis resolution are displacing contact probes in surface roughness verification for precision-machined aluminum battery trays. Tier-one suppliers in Bavaria and Michigan have compressed inspection cycle times from 45 seconds to sub-3-second intervals. This displacement is eliminating the throughput penalty that previously restricted 100% inspection to critical safety features.
FDA 21 CFR Part 820 quality system regulations now explicitly recognize automated measurement data as equivalent to manual inspection records when systems are validated under IQ/OQ/PQ protocols. Orthopedic implant manufacturers in Warsaw, Indiana and Tuttlingen, Germany are reconfiguring finishing lines to generate continuous surface finish documentation. The regulatory recognition is accelerating capital allocation toward inline systems that simultaneously satisfy compliance and throughput objectives.
Automotive OEMs now specify outcome-based performance contracts where metrology providers guarantee defect escape rates rather than equipment uptime metrics. Tier-one suppliers in the supply base absorb capital deployment risk while vendors retain analytics layer value. This contractual evolution concentrates most visibly among German premium OEMs and their direct machining partners in the Swabian precision engineering corridor.
Inline Metrology Market Segmentation
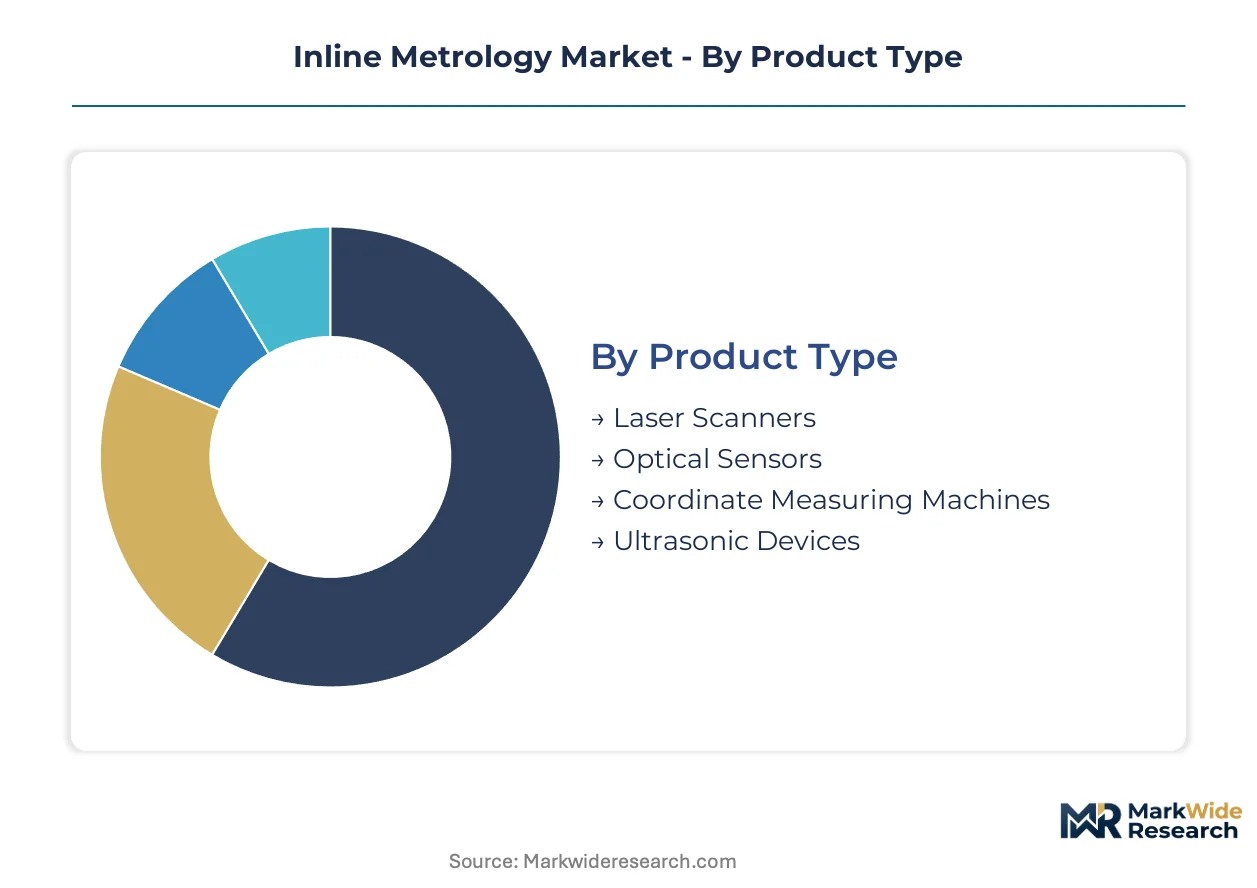
Inline metrology segmentation reveals distinct substitution pressures across hardware categories, with compact optical sensors displacing legacy CMM infrastructure in medium-precision applications. Technology and end-use splits expose diverging margin profiles, from semiconductor-grade vision systems to automotive production-line laser triangulation.
Product Type:
Optical Sensors face the most acute substitution threat as chromatic confocal and structured light architectures capture battery tray inspection workflows previously reserved for contact probes.
- Laser Scanners:These systems deploy triangulation or time-of-flight principles to capture dense point clouds across complex geometries. Automotive OEMs in Germany specify laser scanning cells for EV battery housing flatness verification, driven by sub-10-micron tolerance windows that offline CMM sampling cannot satisfy.
- Optical Sensors:Compact units integrating chromatic confocal or structured light projection achieve nanometer-scale Z-axis resolution without mechanical contact. Bavarian tier-one suppliers have compressed inspection cycles from 45 seconds to under 3 seconds, eliminating throughput penalties that previously restricted 100% inspection coverage.
- Coordinate Measuring Machines:Bridge and gantry configurations retain dominance in final inspection laboratories where ISO 10360 traceability is mandatory.
- Ultrasonic Devices:Thickness gauging and internal defect detection applications concentrate in aerospace composite manufacturing and pipeline welding inspection.
Laser Scanners retains volume leadership; Optical Sensors holds the steepest expansion curve.
End User:
Cost tier stratification separates premium OEMs deploying multi-sensor cells from mid-tier suppliers constrained to single-technology retrofits.
- Automotive:EV platform retooling drives specification of fully automated inline inspection cells across German, Chinese, and US assembly plants. Battery housing dimensional verification and motor stator concentricity checks now demand 100% inline coverage without workpiece removal.
- Medical Devices:FDA 21 CFR Part 820 and EU MDR traceability mandates elevate inline metrology from efficiency tool to compliance infrastructure. Orthopedic implant manufacturers in Warsaw, Indiana and Tuttlingen, Germany reconfigure finishing lines to generate continuous surface finish documentation.
- Aerospace:Turbine blade and structural component inspection maintains reliance on CMM final verification, though optical sensors penetrate composite layup quality control.
- Electronics:Semiconductor-adjacent power module substrate inspection applies wafer-scale optical architectures to silicon carbide inverter thermal management quality control.
Automotive commands the largest installed base; Medical Devices is climbing the fastest.
Technology:
Volume concentration favors embedded GPU architectures that collapsed algorithm development delays previously stalling inline vision deployment.
- Vision Systems:Deep-learning defect classification trained on production data streams eliminates rule-based programming bottlenecks. These systems now expand most quickly across tier-one supplier retooling cycles for EV geometries.
- 3D Imaging:Structured light and stereo correlation methods dominate medium-precision dimensional verification in automotive body-in-white applications.
- Thermal Imaging:Infrared thermography detects subsurface defects in composite materials and validates thermal management component performance.
- RFID:Workpiece tracking and measurement-data association enable automated device history record generation for medical device compliance.
Vision Systems dominates new installation value; 3D Imaging maintains the broadest cross-industry penetration.
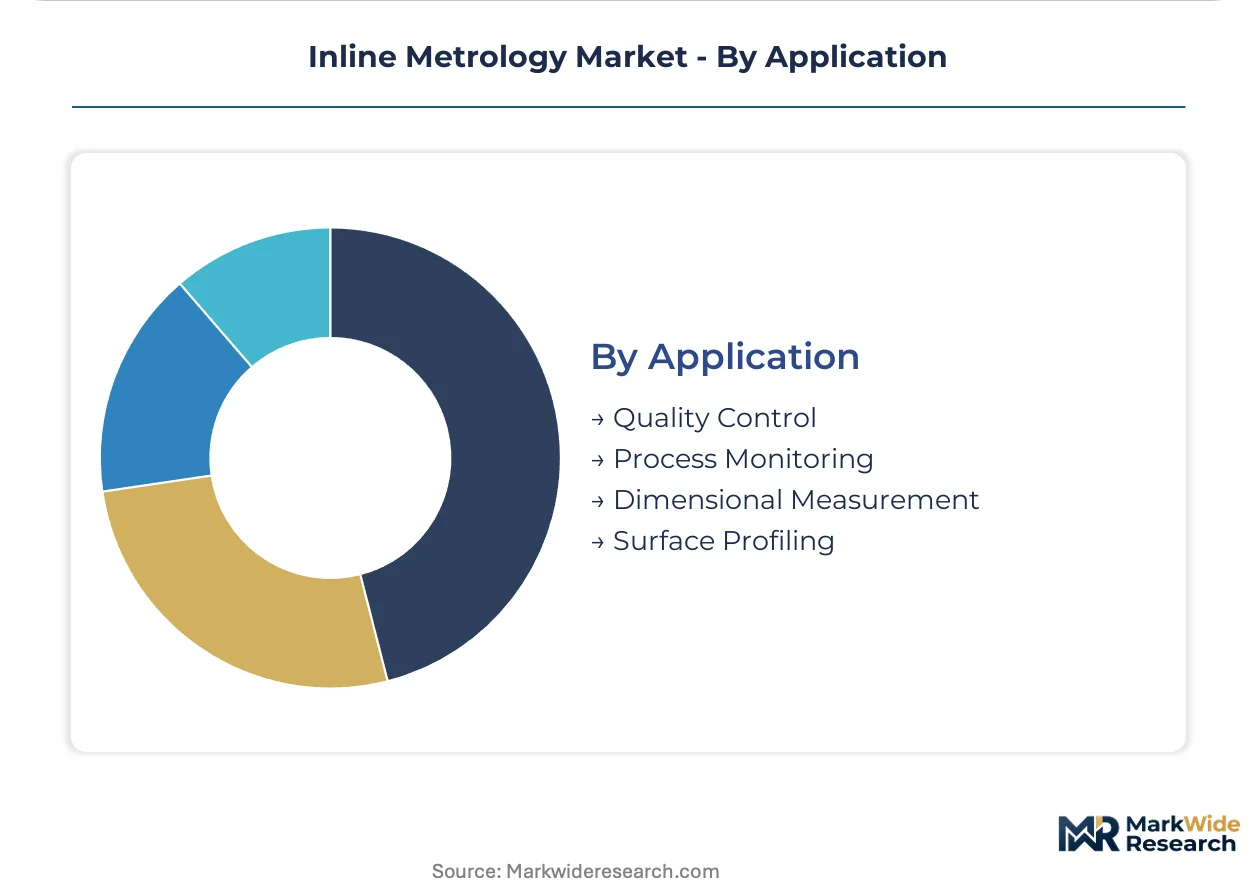
Application:
Customer type divergence splits the market between compliance-driven medical device documentation and throughput-driven automotive process correction.
- Quality Control:Final verification and defect escape prevention concentrate value in automotive safety-critical assemblies and FDA-regulated medical devices. German premium OEMs now specify outcome-based performance contracts guaranteeing defect escape rates rather than equipment uptime.
- Process Monitoring:Real-time dimensional feedback enables closed-loop correction before tolerance breaches occur. AI-driven predictive quality platforms leverage these data streams for pre-emptive process adjustment.
- Dimensional Measurement:Geometric dimensioning and tolerancing verification spans all end-use sectors with varying precision requirements.
- Surface Profiling:Roughness and texture characterization concentrates in orthopedic implant finishing and precision-machined aluminum battery trays.
Quality Control absorbs the majority of capital expenditure; Process Monitoring is gaining share fastest as AI convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense autobahn and rail freight network underwrites its position as the primary deployment zone for inline metrology infrastructure serving automotive and precision engineering value chains.
Germany
Automotive OEM retooling for EV platforms drives specification of multi-sensor optical cells across Swabian precision engineering clusters. EU MDR traceability mandates compel medical device producers in Tuttlingen to embed continuous measurement protocols into implant finishing lines. Stuttgart-based tier-one suppliers have compressed battery tray inspection cycles from 45 seconds to under 3 seconds using chromatic confocal architectures.
United States
FDA 21 CFR Part 820 quality system regulations elevate inline metrology to compliance infrastructure for orthopedic implant manufacturers. IRA clean energy manufacturing incentives accelerate domestic EV battery production, forcing 100% inline verification of thermal management plate flatness. Warsaw, Indiana hosts concentrated implant finishing operations reconfiguring for automated device history record generation.
China
MIIT new energy vehicle production targets and dual carbon goals compress dimensional tolerance requirements for battery housing assemblies. GB standards for automotive safety components increasingly reference continuous inspection protocols. Yangtze River Delta manufacturing hubs deploy laser triangulation cells for motor stator concentricity verification without workpiece removal.
Japan
METI semiconductor revitalization strategies extend wafer-scale optical architectures into automotive power module substrate inspection. JIS calibration standards create certification barriers for non-accredited metrology entrants. Nagoya industrial corridors concentrate high-precision laser diode and specialized CMOS sensor production, feeding allocation-sensitive supply chains.
India
CDSCO quality mandate expansions for parenteral drug containers create first-mover opportunities for vision system providers establishing local calibration partnerships. PLI scheme incentives for automotive component manufacturing accelerate inline inspection adoption among tier-one suppliers retooling for export markets. Maharashtra pharmaceutical packaging clusters increasingly specify embedded GPU vision systems for defect classification.
Inline Metrology Market Vendor Landscape
Concentration sits with diversified metrology conglomerates and specialized optical sensor manufacturers. The vendor base separates into three strategic tiers: precision engineering conglomerates with software-hardware integration capabilities, semiconductor-adjacent inspection specialists extending into automotive electronics, and rapid-deployment vision system providers serving tier-one supplier retooling cycles. Dominant competitive moves include strategic partnerships for calibration infrastructure access and portfolio diversification into AI-driven analytics layers.
Within the diversified conglomerate tier, Hexagon AB and Carl Zeiss AG exemplify integrated software-hardware positioning across European and North American assembly plants. KLA Corporation anchors the semiconductor-adjacent extension archetype, while KEYENCE Corporation occupies the rapid-deployment specialist position serving compressed integration timelines.
| Leading Market Players |
|---|
| Hexagon AB |
| Carl Zeiss AG |
| KLA Corporation |
| KEYENCE Corporation |
| Mitutoyo Corporation |
| FARO Technologies, Inc. |
| Renishaw plc |
| Nikon Metrology NV |
| Jenoptik AG |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month payback horizons for multi-sensor retrofits concentrate pricing power with German and Japanese component specialists who control high-precision laser diode and specialized CMOS sensor allocation. This lead-time band tightens procurement flexibility for mid-tier automotive suppliers while amplifying margin capture upstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 10360-certified multi-sensor cells from single-technology optical units and uncalibrated vision modules. Price differentiation hinges on certification grade and after-sales service bundling, with premium tiers commanding substantial uplifts for IQ/OQ/PQ validation support. Cost compression in the standard tier is intensifying because embedded GPU architectures reduce algorithm development overhead. Mid-tier automotive suppliers exhibit the highest price sensitivity, while FDA-regulated medical device manufacturers prioritize compliance-grade systems regardless of cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Japanese laser diode shipments and German optical component exports. Manufacturing concentration rests on Japan, Germany, and China, with Nagoya and Stuttgart corridors feeding allocation-sensitive supply chains for chromatic confocal sensors and structured light projectors. Raw material dependencies include high-purity optical glass, specialized CMOS sensors, and precision-machined aluminum housings. Single-source vulnerability around Japanese laser diode production creates structural risk. Distribution runs through direct OEM relationships and tier-one supplier integration channels rather than aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—specifically ISO 10360 calibration infrastructure scarcity—protects incumbent positions against price-based competition.
For Market Incumbents: Fortify calibration laboratory partnerships in Stuttgart, Nagoya, and Detroit to lock out non-accredited entrants seeking medical device qualification. Deepen backward integration into specialized CMOS sensor production to reduce allocation vulnerability from Japanese component specialists. Software-hardware integration capabilities represent the critical lever for defending margin position against rapid-deployment vision system competitors. For New Entrants and Emerging Players: CDSCO fast-track partnerships for parenteral drug container vision systems in Maharashtra pharmaceutical clusters offer the most penetrable entry point. White-space concentration appears in India pharmaceutical packaging and semiconductor-adjacent automotive electronics quality control. A calibration-co-development go-to-market angle with local academic laboratories bypasses ISO 10360 accreditation barriers that stall direct competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core metrology divisions lacking AI analytics layer integration. Long-term viability centers on software-defined inspection architectures that commoditize sensor hardware while concentrating value in predictive quality platforms. Watch for FDA 21 CFR Part 820 enforcement intensity as the inflection signal indicating compliance infrastructure spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Partnership | ISO 10360-accredited laboratory access in Stuttgart and Nagoya locks out non-certified competitors from medical device contracts. |
| Embedded GPU Vision System Launch | Deep-learning defect classification trained on production data streams collapses integration timelines for EV retooling cycles. |
| Backward Integration into Optical Components | In-house production of chromatic confocal sensors reduces allocation risk from Japanese laser diode specialists. |
| AI Analytics Platform Development | Predictive quality software layers capture value as sensor hardware faces commoditization pressure. |
| India Pharmaceutical Packaging Expansion | CDSCO mandate expansions for parenteral drug containers create first-mover advantage through local calibration partnerships. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with metrology system engineers, automotive quality directors, medical device regulatory affairs leads, and tier-one supplier procurement managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, MIIT new energy vehicle production disclosures, and SEC filings from diversified metrology conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled technology splits, end-use verticals, and geographic adoption patterns calibrated to EV platform retooling cycles and regulatory enforcement intensity. CAGRs were derived from regression analysis of historical equipment shipment data and forward-looking capital expenditure surveys. Industry-specific forecast inputs included battery housing dimensional tolerance compression rates and FDA inspection observation trends for automated measurement system validation.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification capital deployment or relaxed FDA enforcement postures would require recalibration. Forecasts reflect documented assumptions regarding component allocation stability and calibration infrastructure expansion timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Sound Level Meter Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Advanced Node Wafer Defect Inspection Systems Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Rohs Tester Market