
 Ceramic Tester Market | 2026-2036
Ceramic Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Tester Market Analysis
China's advanced ceramics manufacturing belt is reconfiguring how testing equipment suppliers allocate engineering resources. AMETEK leverages its instrumentation portfolio to serve thermal analysis workflows in aerospace ceramic qualification. Zwick Roell Group anchors mechanical testing demand through its universal testing systems deployed at European ceramic research centers. Shimadzu Scientific Instruments competes on optical and non-destructive testing platforms tailored to electronic substrate manufacturers.
A ceramic tester evaluates the mechanical, thermal, and structural properties of engineered ceramic materials using load frames, thermal analyzers, and optical inspection systems operating at temperatures exceeding 1,600°C and pressures up to 300 MPa. These instruments verify that alumina, zirconia, and silicon nitride components meet specifications for turbine blades, semiconductor substrates, and biomedical implants. Automated testers now lead capital expenditure flows as manufacturers replace manual protocols to reduce cycle times and operator variability. Non-destructive testing technology captures expanding margin pools where semiconductor packaging clients require zero-defect ceramic substrate qualification without sample destruction. Research labs represent a maturing application segment with slower replacement cycles compared to quality control floors at ceramic manufacturers.
FDA device regulations and EPA emissions standards in the United States shape testing requirements for biomedical and industrial ceramic components. China's GB standards and SAMR certification protocols dictate equipment specifications for domestic and export-bound ceramic producers. ECHA REACH compliance in Europe restricts certain raw materials, forcing testers to validate substitute ceramic formulations. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal recalibrate energy-intensive ceramic sintering processes and their associated quality verification needs.
Market Dynamics
Automated testing protocols are compressing qualification cycles for ceramic substrates as semiconductor packaging fabs in Taiwan and Germany's industrial ceramics corridor around Cologne and Düsseldorf demand throughput gains that manual inspection cannot deliver.
Growth Catalysts
- Semiconductor substrate qualification:Taiwan-based packaging fabs are expanding ceramic substrate testing programs to meet advanced packaging roadmaps for high-bandwidth memory and chiplets.
- GB standards compliance:China's SAMR certification protocols mandate automated testing equipment specifications for domestic ceramic producers serving export markets.
- Biomedical implant verification:FDA device regulations for ceramic hip and dental implants require thermal and mechanical property documentation that drives analyzer replacement cycles.
Market Restraints
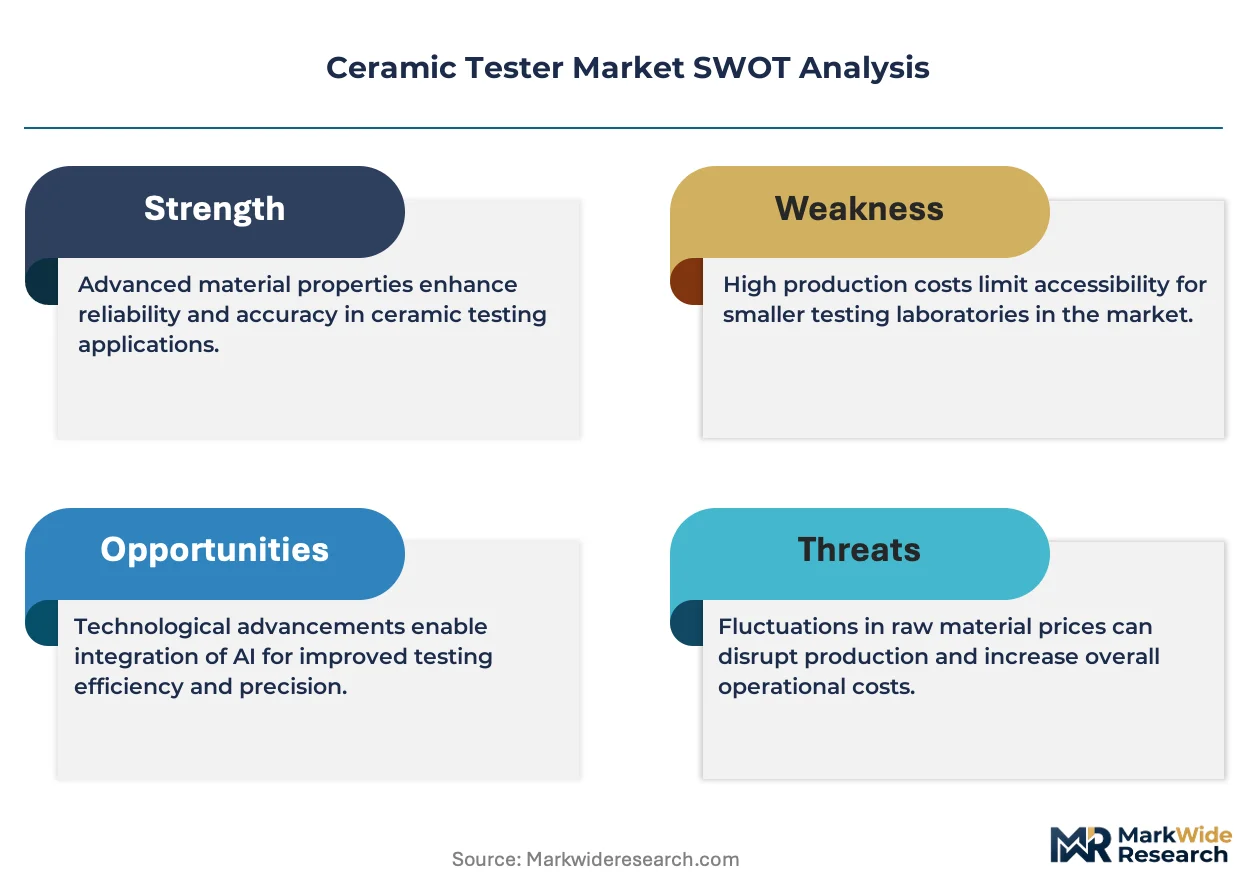
- High-purity alumina supply concentration:Sintered alumina feedstock for test specimens concentrates among Japanese and German specialty chemical suppliers, creating input cost volatility.
- Technical limitation in ultra-high temperature:Thermocouple drift above 1,600°C forces frequent calibration cycles that extend qualification timelines.
- REACH substitution validation:ECHA restrictions on certain ceramic raw materials require reformulation testing that adds protocol complexity without expanding equipment demand.
Strategic Opportunities
- India industrial ceramics corridor:BIS standards adoption and PLI scheme incentives for advanced materials are creating first-mover positions for testing equipment deployment.
- Additive manufacturing qualification:3D-printed ceramic turbine blades and heat exchangers require new non-destructive testing workflows that combine CT scanning with mechanical load frames.
- EU Green Deal carbon accounting:CSRD disclosure requirements for energy-intensive sintering processes are driving demand for thermal analysis equipment that documents process emissions.
Industry Challenges
- Metrologist skill scarcity:Operators capable of interpreting acoustic emission data during ceramic fracture testing are concentrated in Germany and Japan, limiting equipment utilization elsewhere.
- Legacy system integration:Quality control floors at established ceramic manufacturers operate mixed fleets of analog and digital testers that resist unified data architecture deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Tester Market |
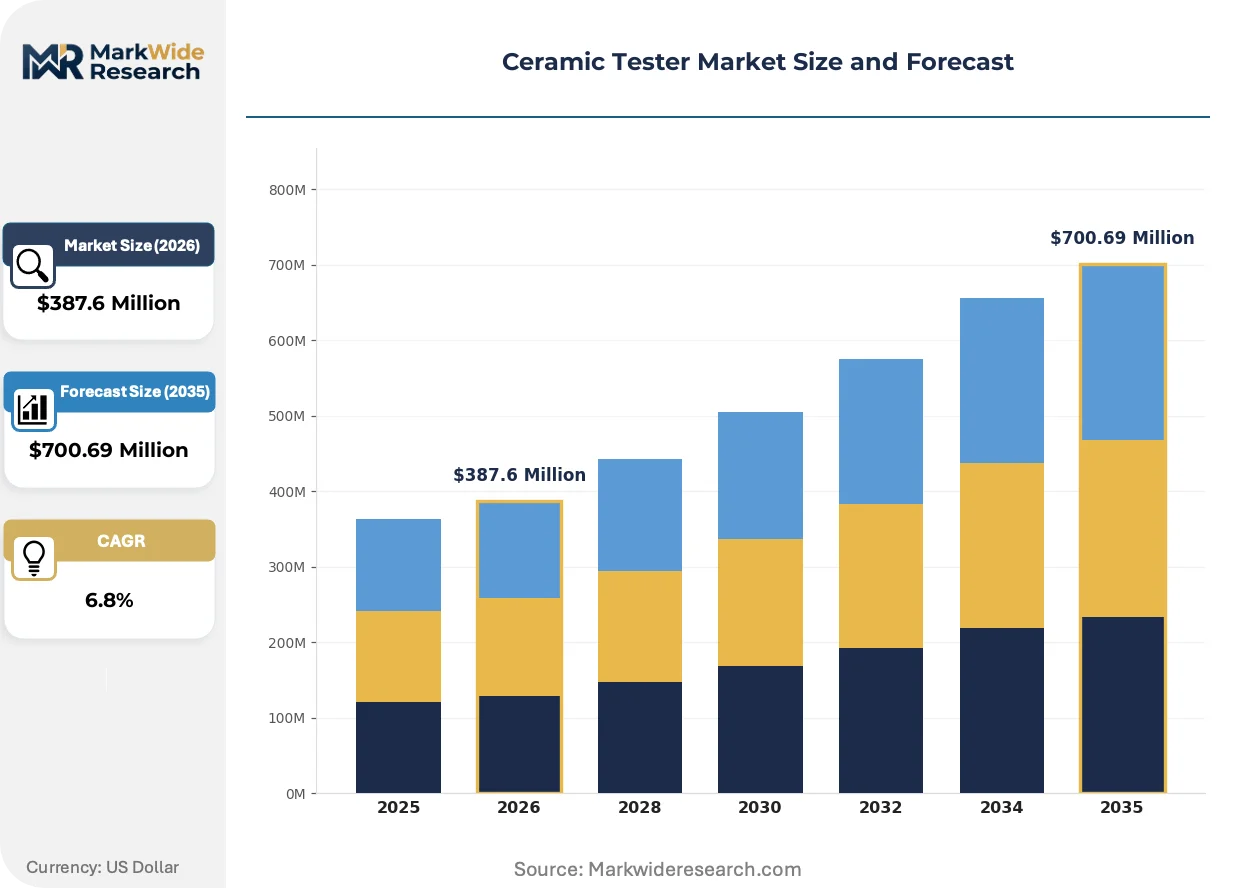
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Testers, Automated Testers, Digital Testers, Portable Testers Application: Quality Control, Product Development, Research Labs, Field Testing End User: Ceramic Manufacturers, Research Institutions, Testing Laboratories, Universities Technology: Non-Destructive Testing, Mechanical Testing, Optical Testing, Thermal Analysis |
| Companies Covered | AMETEK, Zwick Roell Group, Shimadzu Scientific Instruments, Illinois Tool Works, C-tech Instruments, EIE Instruments, E.J. Payne Ltd, OFI Testing Equipment, Aimil Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Tester Market Emerging Trajectories
Digital twin workflows and AI-assisted defect classification are restructuring how ceramic manufacturers validate component reliability, compressing the gap between laboratory qualification and production floor testing.
Laser-induced breakdown spectroscopy for elemental analysis of ceramic coatings is rendering obsolete destructive wet chemistry methods that required sample dissolution. Aerospace turbine blade manufacturers in the United States and Germany are adopting LIBS systems at qualification labs to reduce turnaround from days to hours. The shift is compressing margins for traditional analytical service providers while expanding addressable market for integrated optical platforms.
REACH authorization timelines for silicon carbide processing aids are forcing reformulation of ceramic matrix composites used in brake discs and heat shields. European automotive suppliers must requalify friction materials under ECHA substance restrictions that took effect in 2023. Testing laboratories in Germany's industrial ceramics corridor are expanding thermal shock and wear test capacity to handle substitution validation workloads.
Consolidated procurement by multinational ceramic substrate manufacturers is disintermediating regional equipment distributors. Direct vendor relationships now dominate capital expenditure decisions at semiconductor packaging fabs in Taiwan and display glass ceramic suppliers in South Korea. Equipment suppliers are responding with embedded service contracts that bundle calibration consumables and software updates, capturing recurring revenue streams that previously accrued to third-party maintenance providers.
Ceramic Tester Market Segmentation
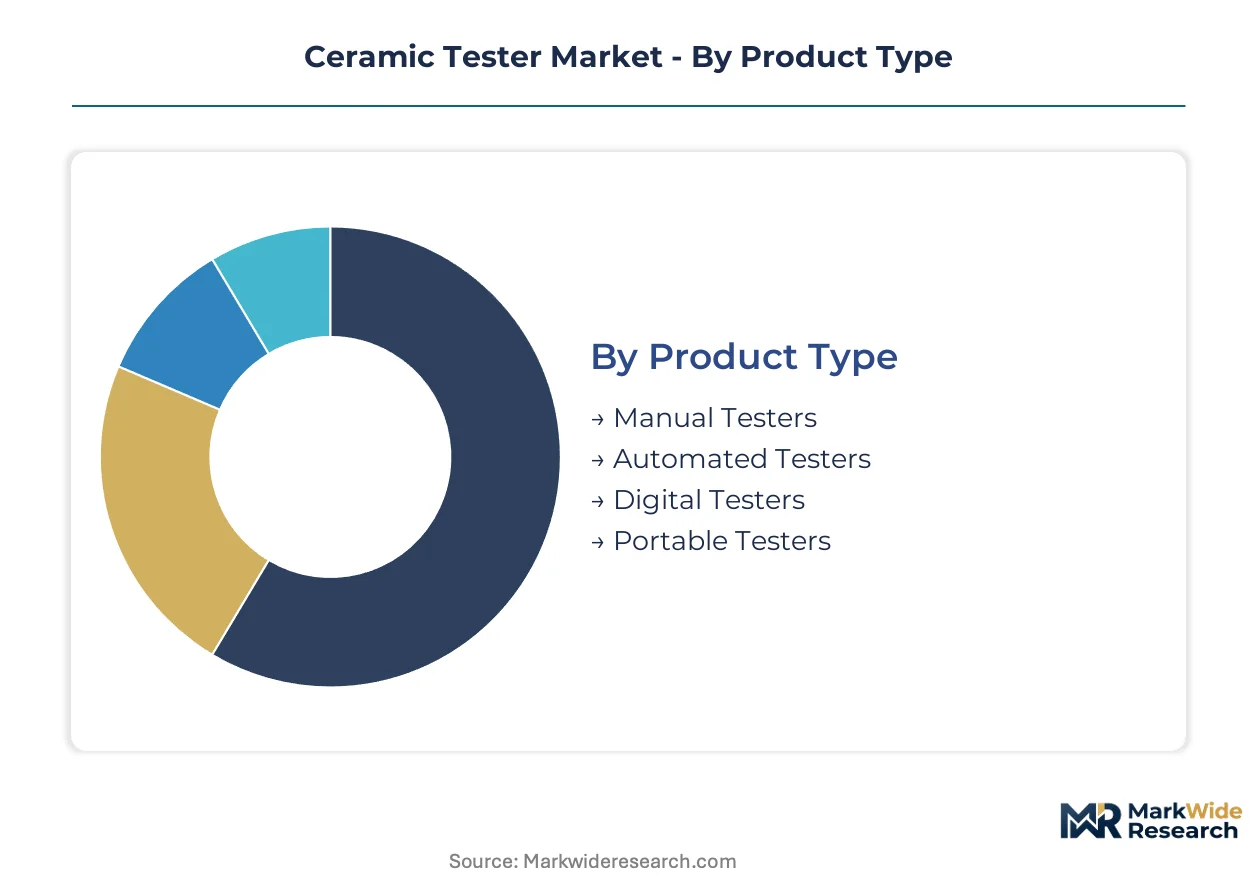
Ceramic tester procurement patterns diverge sharply across product tiers, with automated systems commanding premium service contracts while manual units rely on third-party calibration networks. Application context—quality control floors versus research labs—determines testing protocol complexity and replacement cycle frequency.
Product Type:
After-sales service intensity escalates with automation level, as digital and automated testers require embedded firmware updates and thermocouple calibration programs that manual units rarely need.
- Automated Testers:Robotic load frames and programmable thermal chambers execute multi-step qualification protocols without operator intervention. Taiwan's semiconductor packaging fabs and Germany's industrial ceramics corridor around Cologne and Düsseldorf are standardizing on these systems to compress ceramic substrate qualification cycles.
- Manual Testers:Hand-operated load frames and dial-gauge measurement systems persist at small-batch ceramic manufacturers and university training facilities. China's SAMR certification protocols for export-bound producers are accelerating replacement of these units with automated alternatives.
- Digital Testers:Microprocessor-controlled units with data logging capabilities bridge analog and fully automated workflows.
- Portable Testers:Battery-powered units for field verification of installed ceramic components in aerospace and energy infrastructure.
By volume, Manual Testers leads. By growth pace, Automated Testers is ahead.
Application:
Cost tier stratification separates high-throughput quality control floors from capital-constrained research environments, with field testing representing an emerging premium segment.
- Quality Control:In-line testing stations at ceramic manufacturing facilities verify dimensional tolerances and mechanical properties of sintered alumina and silicon nitride components. FDA device regulations for biomedical implants and EPA emissions standards for industrial ceramics mandate documentation protocols that drive analyzer replacement cycles at US-based manufacturers.
- Research Labs:Multi-technique platforms combining mechanical, thermal, and optical analysis serve materials science departments and government research institutes. Slower replacement cycles characterize this segment compared to quality control floors, as equipment depreciation timelines extend across academic budget cycles.
- Product Development:Iterative testing workflows for new ceramic formulations before production scale-up.
- Field Testing:On-site verification of ceramic turbine blades, heat shields, and biomedical implants after installation.
Quality Control captures the largest revenue pool. Research Labs expands most slowly.
End User:
Customer type determines procurement authority, with ceramic manufacturers consolidating vendor relationships while universities fragment purchases across departmental grants.
- Ceramic Manufacturers:Integrated production facilities from raw material processing through sintering operate dedicated quality control floors with mixed fleets of testing equipment. REACH compliance in Europe and stricter GB standards in China are pushing these users toward automated testing protocols that reduce operator variability.
- Testing Laboratories:Independent certification bodies and contract research organizations serve multiple industrial clients with accredited procedures. ECHA substance restrictions on silicon carbide processing aids are expanding thermal shock and wear test capacity at European labs handling automotive brake disc requalification.
- Research Institutions:National laboratories and materials research institutes with multi-year equipment grants.
- Universities:Academic departments with cyclical capital expenditure tied to grant funding and enrollment patterns.
By installed base, Ceramic Manufacturers dominates. By growth pace, Testing Laboratories is climbing the fastest.
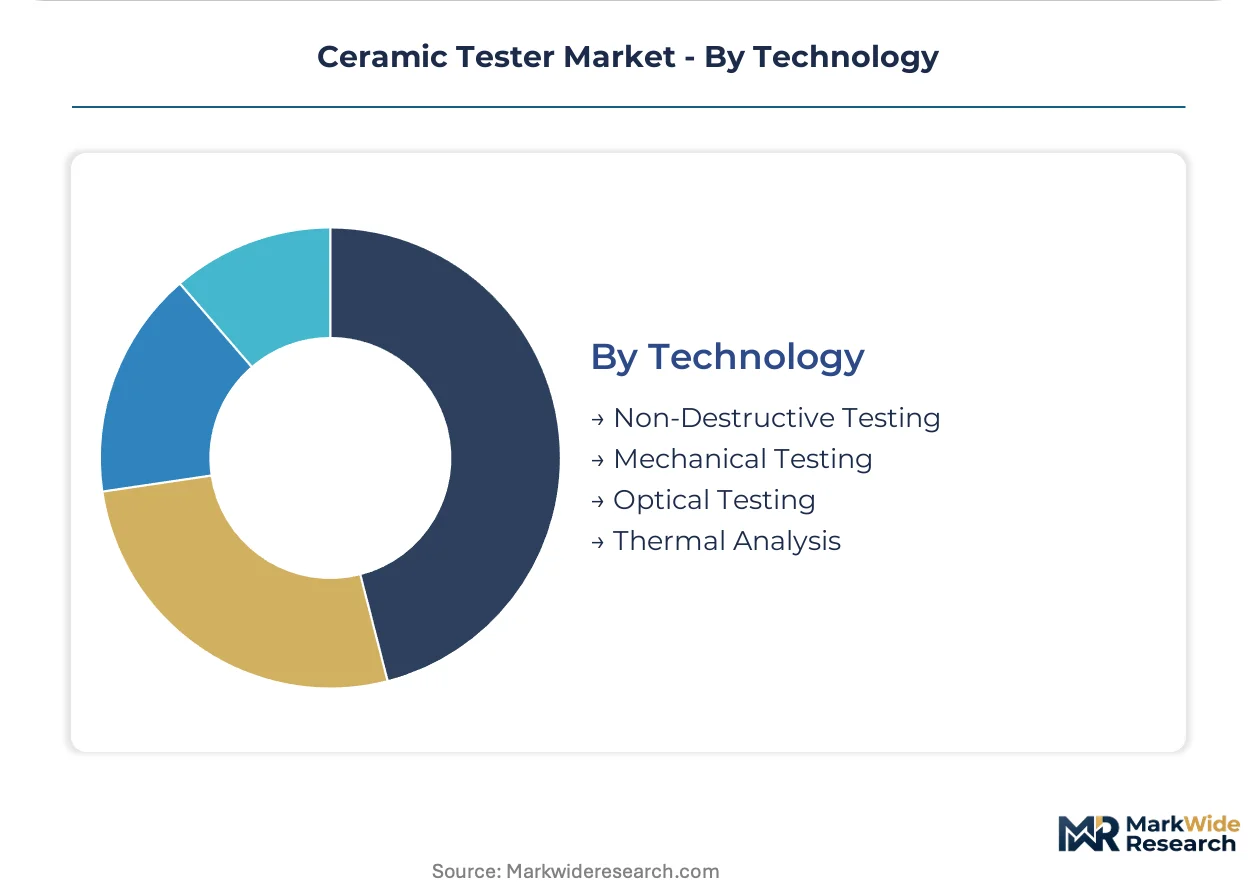
Technology:
Margin concentration aligns with non-destructive capabilities, where semiconductor packaging clients pay premiums for zero-defect substrate qualification without sample destruction.
- Non-Destructive Testing:X-ray computed tomography, ultrasonic inspection, and acoustic emission monitoring detect internal defects in ceramic matrix composites without compromising test specimens. Aerospace turbine blade manufacturers in the United States and Germany are adopting CT-integrated workflows for 3D-printed ceramic heat exchangers.
- Thermal Analysis:Differential scanning calorimetry and thermomechanical analyzers document phase transitions and expansion coefficients up to 1,600°C. Thermocouple drift above this threshold forces frequent calibration cycles that extend qualification timelines and expand recurring service revenue.
- Mechanical Testing:Universal load frames for compression, flexure, and fracture toughness measurement.
- Optical Testing:Laser-induced breakdown spectroscopy for elemental analysis of ceramic coatings replacing destructive wet chemistry methods.
Mechanical Testing holds the largest installed base. Non-Destructive Testing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device regulations and EPA emissions standards in the United States anchor the regulatory framework for biomedical and industrial ceramic testing equipment procurement.
United States
Aerospace turbine blade manufacturers and biomedical implant producers drive thermal analyzer demand. FDA device regulations mandate thermal and mechanical property documentation for ceramic hip and dental implants. California and Arizona host qualification labs adopting laser-induced breakdown spectroscopy for ceramic coating analysis.
Germany
Automotive brake disc requalification under ECHA substance restrictions expands thermal shock test capacity. REACH compliance protocols restrict silicon carbide processing aids, forcing reformulation validation workflows. The industrial ceramics corridor around Cologne and Düsseldorf concentrates testing laboratory expansion for substitution validation.
China
Advanced ceramics manufacturing belt reconfigures engineering resource allocation for testing equipment suppliers. GB standards and SAMR certification protocols mandate automated testing specifications for export-bound producers. Yangtze River Delta ceramic substrate fabs accelerate replacement of manual testers with automated alternatives.
Taiwan
Semiconductor packaging fabs expand ceramic substrate qualification programs for high-bandwidth memory and chiplet roadmaps. Advanced packaging test protocols demand throughput gains beyond manual inspection capabilities. Hsinchu Science Park facilities standardize on robotic load frames for multi-step qualification.
Japan
High-purity alumina feedstock concentration among specialty chemical suppliers creates input cost volatility for test specimen production. METI industrial standards shape thermal analysis equipment specifications. Osaka and Nagoya ceramic research centers deploy universal testing systems for sintered silicon nitride component verification.
Ceramic Tester Market Vendor Landscape
Instrumentation conglomerates and specialized testing equipment fabricators split the market based on automation depth and service bundling intensity. Tiered competitive positioning separates premium-tier vendors with embedded firmware ecosystems from mid-tier suppliers reliant on third-party calibration networks. Two strategic archetypes dominate: diversified instrumentation portfolios serving multi-technique workflows, and focused mechanical testing specialists anchoring universal load frame demand. Competitive moves concentrate on direct vendor relationships replacing regional distributors, plus service contract bundling capturing recurring calibration revenue.
Within the diversified instrumentation tier, AMETEK and Illinois Tool Works exemplify portfolio breadth strategies spanning thermal, mechanical, and optical analysis modalities. Zwick Roell Group anchors the specialized mechanical testing vector through its universal testing systems deployed at European ceramic research centers. Shimadzu Scientific Instruments occupies a position bridging both archetypes with platforms tailored to electronic substrate manufacturers requiring non-destructive and optical testing capabilities.
| Leading Market Players |
|---|
| AMETEK |
| Zwick Roell Group |
| Shimadzu Scientific Instruments |
| Illinois Tool Works |
| C-tech Instruments |
| EIE Instruments |
| E.J. Payne Ltd |
| OFI Testing Equipment |
| Aimil Ltd |
| Others |
Supply Flow & Price Mechanics
Germany's industrial ceramics corridor around Cologne and Düsseldorf concentrates high-throughput testing capacity, creating pricing leverage for automated system vendors serving semiconductor packaging fabs and automotive brake disc requalification programs. This geographic concentration of qualified metrologists and calibration infrastructure feeds into premium service bundling that compresses margins for mid-tier equipment suppliers lacking embedded firmware ecosystems.
Pricing Analysis
Price spreads between automated and manual ceramic testers widen as Taiwan-based packaging fabs consolidate procurement around direct vendor relationships. Three-tier pricing structure across premium, standard, and economy levels separates systems with embedded thermocouple calibration programs from third-party-dependent alternatives. Cost compression in the manual tier intensifies because China's SAMR certification protocols accelerate replacement demand. Small-batch ceramic manufacturers and university training facilities exhibit the highest price sensitivity, while semiconductor substrate fabs prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Japan and Germany dominates supply chain risk planning for high-purity alumina feedstock used in test specimen production. Sintered alumina concentrates among Japanese and German specialty chemical suppliers, with thermocouple components drawing from precision instrumentation clusters in both countries. Single-source vulnerability in ultra-high-temperature sensor calibration creates bottleneck exposure above 1,600°C operating thresholds. Distribution runs through consolidated procurement channels at multinational ceramic substrate manufacturers, disintermediating regional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from laser-induced breakdown spectroscopy systems displacing destructive wet chemistry methods in aerospace turbine blade qualification labs. Incumbents must navigate this optical platform encroachment while defending mechanical testing revenue pools.
For Market Incumbents: Pre-empt LIBS displacement by integrating optical modules into existing universal load frame platforms, capturing hybrid workflow demand at US and German aerospace facilities. Anchor thermal analyzer margins through embedded service contracts bundling thermocouple calibration consumables, neutralizing third-party maintenance providers. Prioritize backward integration into high-purity alumina specimen supply to offset Japanese-German feedstock concentration volatility.
For New Entrants and Emerging Players: Build out additive manufacturing qualification capabilities combining CT scanning with mechanical load frames, targeting 3D-printed ceramic turbine blade and heat exchanger workflows. India's industrial ceramics corridor under BIS standards adoption offers the most penetrable geography for first-mover testing equipment deployment. Lead with CSRD-aligned thermal analysis platforms documenting energy-intensive sintering emissions for EU Green Deal compliance.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified instrumentation portfolios spanning thermal, mechanical, and optical modalities over specialized mechanical testing pure-plays. Long-term viability rests on recurring revenue capture through firmware-embedded service ecosystems rather than transactional equipment sales. Watch ECHA REACH authorization timelines for silicon carbide processing aids as inflection indicators for thermal shock and wear test capacity expansion at European automotive supplier labs.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Service Contract Bundling | Captures recurring calibration revenue from Taiwan semiconductor packaging fabs replacing third-party maintenance providers. |
| Optical Platform Integration | Defends mechanical testing share against LIBS displacement in US aerospace turbine blade qualification workflows. |
| India Corridor First-Mover Deployment | Secures positioning under BIS standards adoption and PLI scheme incentives for advanced materials testing infrastructure. |
| CSRD-Aligned Thermal Analysis Development | Addresses EU Green Deal disclosure requirements for energy-intensive ceramic sintering process emissions documentation. |
| High-Purity Alumina Backward Integration | Reduces input cost volatility from Japanese-German specialty chemical supplier concentration for test specimen production. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with ceramic manufacturer quality control directors, testing laboratory metrologists, semiconductor packaging fab procurement leads, and aerospace turbine blade qualification engineers. Secondary validation drew from SAMR certification protocol documents, ECHA REACH substance restriction filings, FDA device regulation guidance, and customs trade data for testing equipment imports. Bottom-up equipment shipment analysis triangulated against top-down ceramic manufacturing capacity expansion announcements.
Calibration against historical replacement cycles at research labs versus quality control floors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include automation level, application context, end-user procurement authority, and testing technology modality. CAGRs were derived from equipment vendor revenue disclosures and ceramic manufacturer capital expenditure patterns. Forecast inputs incorporated thermocouple drift rates above 1,600°C and REACH-driven reformulation testing protocol complexity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by optical platform specialists or additive manufacturing qualification entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Metrology Software Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Cooling Laser Power Measurement Sphere Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
RF Test Equipment Market