
 Silicon Nitride Market | 2026-2036
Silicon Nitride Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Nitride Market Intelligence
Multi-source procurement for high-purity silicon nitride powder is rebalancing toward qualified Asian suppliers as European energy costs strain in-house nitridation capacity. KYOCERA Corporation anchors Japanese ceramic substrate production through captive powder synthesis and precision sintering operations. CeramTec GmbH competes in medical implant-grade silicon nitride with specialized hot isostatic pressing capabilities. CoorsTek Inc. dominates North American supply for aerospace bearing components through vertically controlled reaction bonding lines.
Silicon nitride is a covalent ceramic compound of silicon and nitrogen with exceptional thermal shock resistance, fracture toughness exceeding alumina, and stability beyond 1200°C, produced via direct nitridation of silicon or carbothermal reduction of silica followed by densification. Its primary industrial purpose centers on load-bearing components, electronic insulation layers, and wear-resistant surfaces where metals fail under thermal or chemical stress. Ceramic components lead product type revenue due to established demand from diesel engine valve trains and hybrid bearing assemblies. Electronic substrates represent the fastest-growing application segment as gallium nitride and silicon carbide power modules require thermally matched insulation layers. Sintering remains the dominant manufacturing method for structural parts, though additive manufacturing of silicon nitride is gaining process validation for complex turbocharger geometries.
FDA regulates silicon nitride medical implants under 510(k) pathways with biocompatibility data requirements that extend development timelines for orthopedic device entrants. EPA emissions standards for heavy-duty diesel engines indirectly shape demand by pushing OEMs toward ceramic hot-zone components that sustain higher combustion temperatures. REACH substance registration in Europe constrains powder import flexibility, favoring suppliers with established EU-based nitridation and milling operations. Stakeholders must monitor evolving semiconductor substrate specifications from JEDEC and IEC as wide-bandgap power electronics redefine thermal management requirements.
Market Dynamics
Wide-bandgap power electronics deployment is electrifying substrate demand specifications, forcing silicon nitride suppliers to recalibrate thermal expansion coefficients and purity grades for gallium nitride and silicon carbide module integration.
Growth Catalysts
- REACH substance registration:European chemical compliance is filtering out non-certified powder importers, creating qualified supplier slots for EU-based nitridation operators with established milling infrastructure.
- Diesel engine hot-zone ceramics:EPA emissions standards for heavy-duty trucks are pushing OEMs toward ceramic valve train components that sustain elevated combustion temperatures without thermal degradation.
- Hot isostatic pressing:Medical implant manufacturers are adopting this densification method for orthopedic bearings, unlocking biocompatible grades with fracture toughness exceeding conventional alumina.
Market Restraints
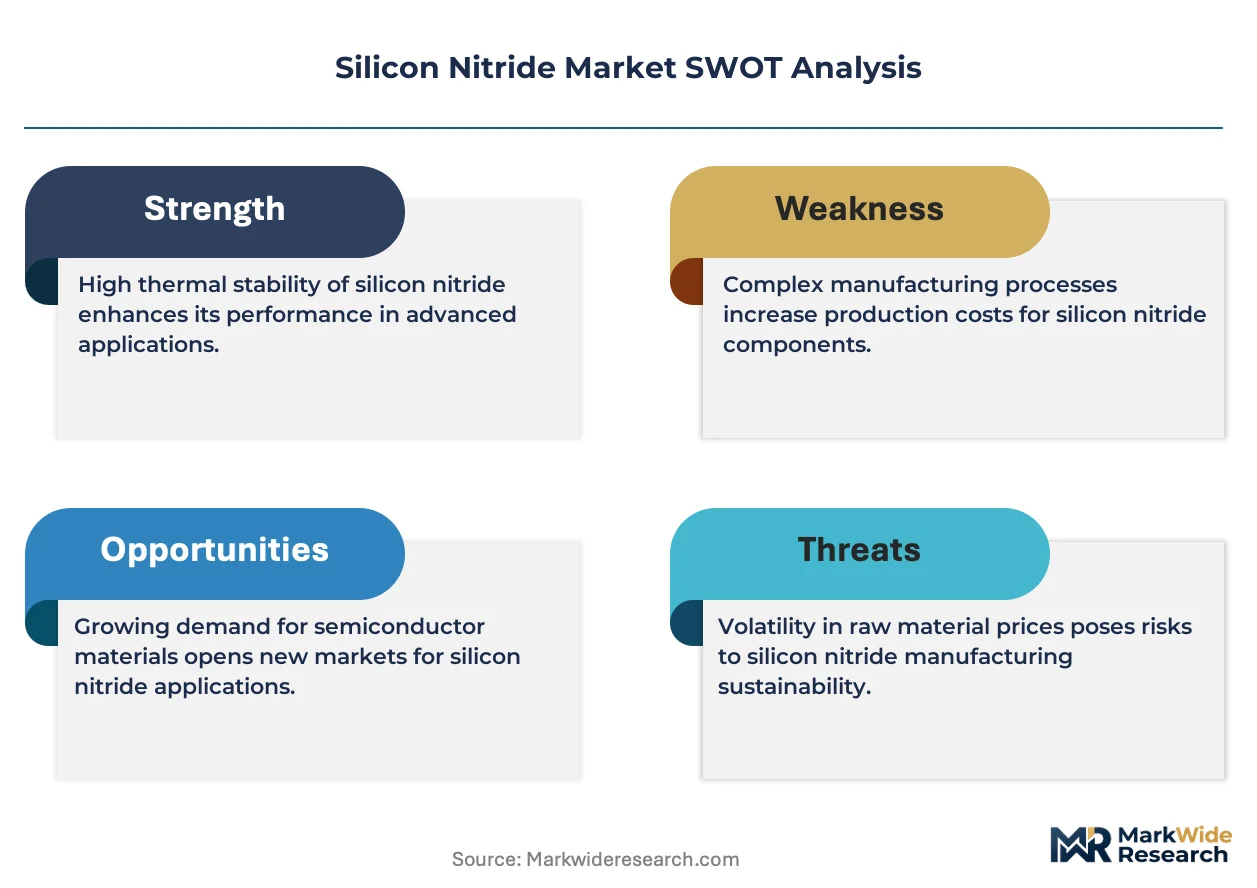
- Energy-intensive nitridation:European electricity pricing volatility is constraining in-house silicon powder conversion capacity, forcing reliance on Asian tolling arrangements.
- Carbide substitution:Silicon carbide bearings compete in moderate-temperature aerospace applications where cost sensitivity outweighs thermal shock resistance requirements.
- REACH import friction:Substance registration timelines extend raw material qualification cycles, delaying new entrant market access by 18-24 months.
Strategic Opportunities
- Additive manufacturing validation:Binder jet and selective laser sintering of silicon nitride are achieving process qualification for complex turbocharger geometries previously machined from solid billets.
- India BIS certification:Domestic standardization for advanced ceramics is creating first-mover advantages for suppliers establishing local testing and distribution partnerships.
- Hybrid bearing assemblies:Rolling element manufacturers are specifying ceramic balls in steel races for electric vehicle drivetrains, opening volume tiers between aerospace and industrial grades.
Industry Challenges
- Precision sintering talent scarcity:Furnace operation and atmosphere control expertise concentrates among aging workforces in Japan and Germany, constraining capacity expansion.
- FDA 510(k) pathway complexity:Biocompatibility data requirements for spinal implants extend development timelines and burn capital before revenue recognition.
- Legacy quality system integration:Medical device manufacturers demand ISO 13485 traceability that conflicts with industrial ceramic batch record practices, forcing dual documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Nitride Market |
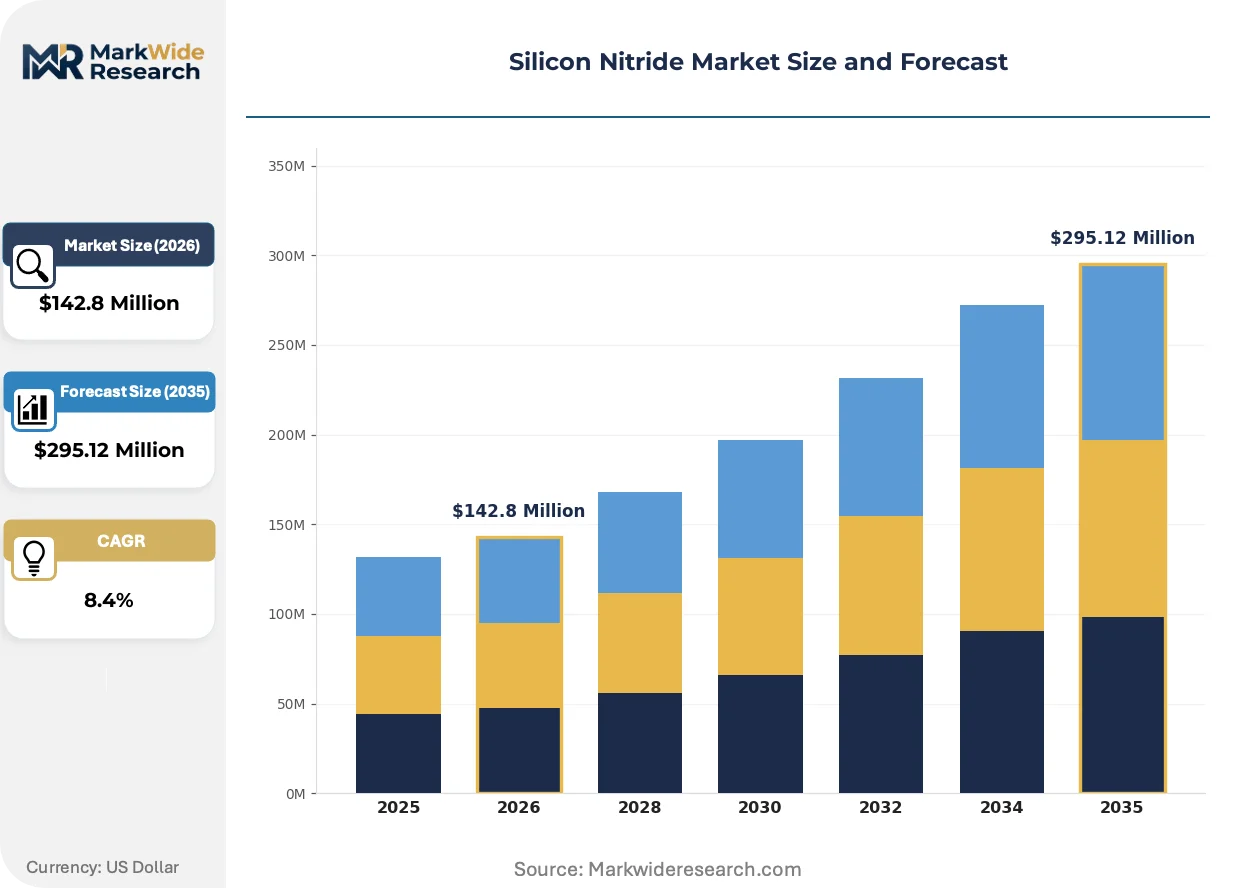
| Market Size in 2026 | $142.8 Million |
| Market Size in 2035 | $295.12 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Ceramic Components, Coatings, Fibers, Thin Films Application: Engine Components, Cutting Tools, Electronic Substrates, Bearings, Medical Implants End User Industry: Aerospace, Electronics Manufacturing, Energy Equipment, Medical Devices, Semiconductors Manufacturing Method: Sintering, Hot Isostatic Pressing, Chemical Vapor Deposition, Reaction Bonding, Additive Manufacturing |
| Companies Covered | KYOCERA Corporation, CeramTec GmbH, 3M Company, CoorsTek Inc., Denka Company Limited, UBE Corporation, Toshiba Materials Co., Ltd., H.C. Starck GmbH, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Nitride Market Strategic Shifts & Innovations
Process innovation and regulatory recalibration are compressing development cycles while fragmenting procurement authority across engineering and sustainability functions.
Gas-pressure sintering is electrifying structural ceramic production by achieving full density without post-sintering hot isostatic pressing. Automotive turbocharger manufacturers are adopting this route for rotor blanks, cutting unit processing time by eliminating secondary densification steps. The method is compressing capital requirements for mid-scale entrants competing against established HIP-dependent suppliers.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas use in ceramic processing atmospheres. Nitrogen-based sintering environments are displacing SF6-containing furnace protocols, requiring retooling of atmosphere control systems and gas recovery infrastructure. European structural ceramic producers are absorbing compliance costs fastest, while Asian exporters face border adjustment exposure.
Direct material qualification by tier-one bearing assemblers is displacing distributor-mediated specification setting. SKF, NSK, and Schaeffler engineers now mandate powder provenance and lot-level fracture toughness data, bypassing traditional trading house intermediaries. This pattern concentrates procurement volume with qualified powder synthesizers in Japan and Germany who maintain captive analytical laboratories.
Silicon Nitride Market Segmentation
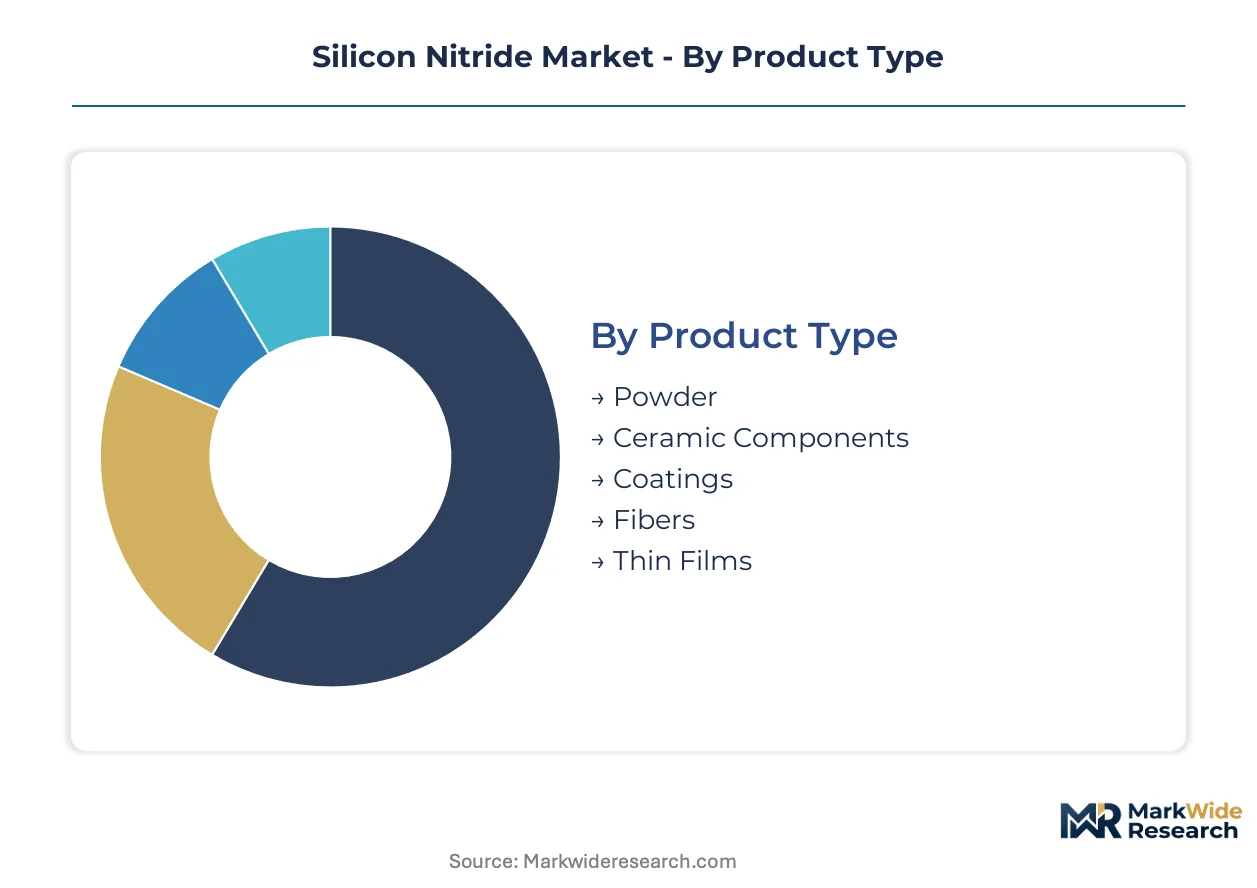
Segmentation in silicon nitride markets tracks how technical specifications diverge across thermal, mechanical, and electrical performance tiers. Procurement patterns split between commodity powder flows and engineered component contracts with divergent qualification cycles.
Product Type:
Upgrade cycles in powder processing equipment are fragmenting supply tiers between toll-nitrided feedstock and captive synthesis operations.
- Ceramic Components:Densified structural parts include bearing races, valve train inserts, and turbocharger rotors requiring fracture toughness exceeding 6 MPa·m½. Demand concentrates in German and Japanese automotive supply chains where SKF and NSK specify lot-level mechanical certification. EPA emissions standards for heavy-duty diesel engines push OEMs toward ceramic hot-zone components.
- Powder:High-purity silicon nitride powder with sub-micron particle distribution serves as feedstock for both structural ceramics and electronic substrates. Japanese suppliers KYOCERA and UBE Corporation anchor captive synthesis capacity, while European tolling arrangements expand amid energy cost pressures.
- Coatings:Plasma-sprayed thermal barrier layers protect turbine blades and combustion chamber walls in aerospace applications.
- Fibers:Continuous filament forms reinforce ceramic matrix composites for high-temperature structural applications.
- Thin Films:Chemical vapor deposited layers provide dielectric isolation in MEMS devices and semiconductor packaging.
Ceramic Components sits at the top of the volume ranking, with Thin Films climbing the fastest.
Application:
Cost tier stratification separates aerospace-qualified grades from industrial bearing specifications with divergent testing protocols.
- Electronic Substrates:Thermally matched insulation layers for gallium nitride and silicon carbide power modules require coefficient of thermal expansion aligned to 3.0–3.5 ppm/K. Demand concentrates in Japanese semiconductor packaging facilities serving wide-bandgap device manufacturers. JEDEC substrate specifications are recalibrating purity grades.
- Bearings:Hybrid ceramic-steel and all-ceramic rolling elements operate in electric vehicle drivetrains, aerospace auxiliary power units, and precision machine tool spindles. NSK and Schaeffler engineers now mandate direct powder provenance verification, bypassing traditional distributor intermediaries.
- Engine Components:Diesel valve train inserts and turbocharger rotors sustain combustion temperatures exceeding 1000°C without thermal degradation.
- Cutting Tools:Indexable inserts machine nickel-based superalloys and hardened steels where carbide tools fail from chemical wear.
- Medical Implants:Spinal spacers and hip bearings require FDA 510(k) biocompatibility certification with fracture toughness exceeding alumina alternatives.
Electronic Substrates represents the fastest-growing trajectory, with Bearings maintaining the largest revenue base.
End User Industry:
Customer type fragmentation splits procurement between OEM direct qualification and distributor-mediated specification setting.
- Electronics Manufacturing:Contract assemblers and original equipment manufacturers source substrate blanks and packaging components for power module integration. Gallium nitride and silicon carbide deployment is recalibrating thermal management requirements across Japanese, German, and US facilities.
- Semiconductors:Foundries and IDMs specify silicon nitride for wafer handling components, chamber liners, and advanced packaging interposers. KYOCERA anchors substrate supply through vertically controlled powder synthesis and precision sintering operations.
- Aerospace:Engine manufacturers and airframe assemblers qualify bearing and hot-section components through FAA-regulated material certification pathways.
- Medical Devices:Orthopedic implant manufacturers navigate FDA 510(k) biocompatibility data requirements that extend development timelines.
- Energy Equipment:Turbine OEMs specify thermal barrier coatings and wear-resistant seals for oil and gas extraction equipment.
Electronics Manufacturing holds the dominant procurement volume, with Semiconductors expanding most quickly.
Manufacturing Method:
Supply concentration in mature densification technologies constrains capacity expansion amid furnace operation expertise scarcity.
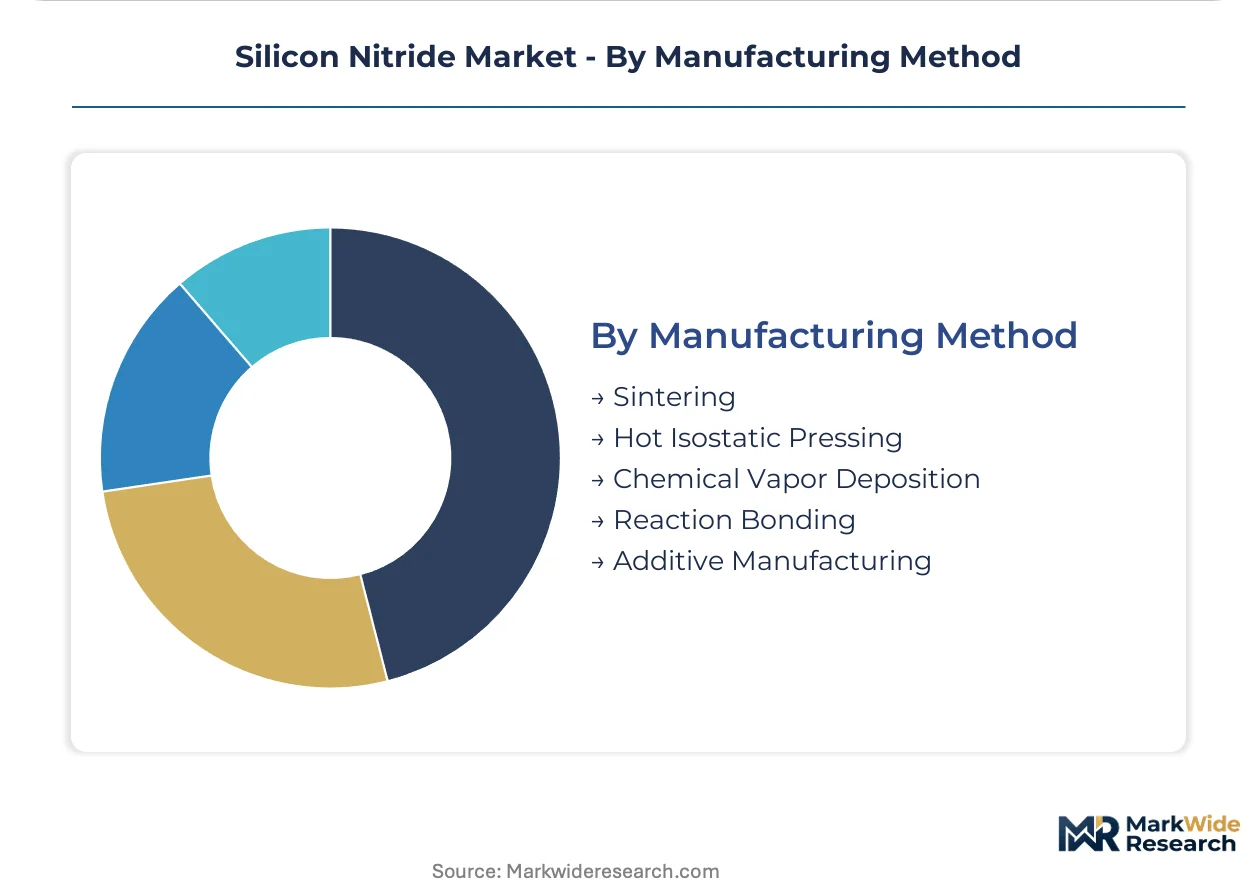
- Sintering:Gas-pressure and pressureless densification routes achieve full structural density for bearing and engine components. Automotive turbocharger manufacturers are adopting gas-pressure sintering to eliminate secondary hot isostatic pressing steps, compressing unit processing time.
- Hot Isostatic Pressing:Medical implant manufacturers specify this method for orthopedic bearings requiring biocompatible grades with uniform microstructure. CeramTec GmbH competes through specialized HIP capabilities for spinal implant applications.
- Reaction Bonding:CoorsTek Inc. dominates North American aerospace bearing supply through vertically controlled reaction bonding lines.
- Chemical Vapor Deposition:Thin film deposition produces conformal coatings for electronic and optical applications.
- Additive Manufacturing:Binder jet and selective laser sintering processes achieve qualification for complex turbocharger geometries previously machined from solid billets.
Sintering commands the highest installed capacity, with Additive Manufacturing gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kyushu industrial corridor anchors global silicon nitride substrate fabrication through vertically integrated powder synthesis and precision sintering operations serving semiconductor packaging facilities.
Japan
Wide-bandgap power electronics deployment drives substrate demand recalibration across Kanto and Kansai manufacturing belts. METI industrial standards govern ceramic powder purity certifications for export-bound components. KYOCERA and UBE Corporation maintain captive nitridation capacity in Fukuoka and Yamaguchi prefectures.
Germany
Automotive turbocharger manufacturers specify gas-pressure sintered rotor blanks from Bavarian and Baden-Württemberg suppliers. REACH substance registration filters non-certified powder importers, favoring EU-based nitridation operators with established milling infrastructure. CeramTec GmbH operates specialized hot isostatic pressing capabilities for medical implant applications from Plochingen.
United States
EPA emissions standards for heavy-duty diesel engines push OEMs toward ceramic valve train components sustaining elevated combustion temperatures. FAA-regulated material certification pathways govern aerospace bearing qualifications. CoorsTek Inc. dominates aerospace bearing supply through reaction bonding lines in Colorado and Arkansas.
China
Domestic gallium nitride and silicon carbide power module expansion recalibrates thermal management substrate specifications across Yangtze River Delta packaging facilities. GB standards for advanced ceramics constrain import-dependent supply chains. Zhengzhou and Luoyang clusters concentrate toll-nitrided powder processing for structural ceramic feedstock.
India
BIS certification requirements for advanced ceramics create first-mover positioning for suppliers establishing local testing partnerships. Electric vehicle drivetrain manufacturers specify hybrid bearing assemblies with ceramic rolling elements. Gujarat and Tamil Nadu industrial corridors attract powder distribution partnerships for automotive and electronics manufacturing.
Silicon Nitride Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing qualification and medical implant biocompatibility certification. The vendor base stratifies across three capability tiers: captive powder synthesis with precision sintering, toll-processed feedstock component fabrication, and specialized coating or thin-film deposition. Strategic archetypes include vertically integrated Japanese conglomerates, European HIP-specialized medical ceramicists, and North American aerospace-focused reaction bonders. Dominant competitive moves encompass gas-pressure sintering capacity expansion and direct material qualification partnerships with tier-one bearing assemblers.
Within the captive synthesis tier, KYOCERA Corporation and UBE Corporation represent integrated powder-to-component operations anchoring Japanese semiconductor substrate supply. Among European medical ceramicists, CeramTec GmbH exemplifies hot isostatic pressing specialization for orthopedic implant applications.
| Leading Market Players |
|---|
| KYOCERA Corporation |
| CeramTec GmbH |
| 3M Company |
| CoorsTek Inc. |
| Denka Company Limited |
| UBE Corporation |
| Toshiba Materials Co., Ltd. |
| H.C. Starck GmbH |
| Saint-Gobain |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation phase-down schedules gate qualified supply access and premium-tier pricing power by mandating nitrogen-based sintering environment retooling that only established European operators have absorbed. Japanese and German producers with captive analytical laboratories command certification premiums while Asian toll-nitrided feedstock competes on cost in industrial bearing grades.
Pricing Analysis
Electricity and fluorinated gas input costs pass through directly to structural ceramic pricing, with European gas-pressure sintered rotors carrying energy-cost premiums against Asian pressureless alternatives. Three-tier pricing structure across semiconductor-grade, medical-implant, and industrial-bearing levels differentiates by purity certification and fracture toughness testing depth. Price erosion runs through toll-nitrided powder tiers as Chinese and Indian capacity expands. Electric vehicle drivetrain manufacturers exhibit highest price sensitivity, prioritizing ceramic ball cost over thermal shock margins, while aerospace OEMs accept premium positioning for FAA-qualified reaction-bonded bearings.
Supply Chain Analysis
Precision sintering furnace operation expertise concentrates among aging workforces in Japan and Germany, constraining capacity expansion despite substrate demand acceleration. Supply draws from Japanese captive synthesis operations, German EU-based nitridation mills, and Chinese toll-processing clusters in Zhengzhou and Luoyang. High-purity silicon metal, nitrogen gas, and yttria sintering aids constitute critical input dependencies. Single-source vulnerability concentrates in sub-micron powder milling equipment controlled by German and Japanese vendors. Distribution runs through direct material qualification partnerships with tier-one bearing assemblers, displacing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by wide-bandgap power electronics deployment recalibrating substrate specifications toward thermally matched premium grades.
For Market Incumbents: Hedge silicon carbide bearing substitution threats in moderate-temperature aerospace applications by deepening hot isostatic pressing specialization for medical implant biocompatibility certification. Secure captive powder synthesis capacity in Fukuoka or Yamaguchi prefectures to defend against Asian toll-nitrided feedstock cost compression. Prioritize gas-pressure sintering capacity expansion for automotive turbocharger rotor contracts. For New Entrants and Emerging Players: Direct-to-OEM digital qualification platforms bypass distributor-mediated specification setting and capture procurement volume from SKF, NSK, and Schaeffler engineers mandating lot-level fracture toughness data. Target additive manufacturing validation services for complex turbocharger geometries as the most penetrable white-space, leveraging binder jet process partnerships with Bavarian automotive suppliers. Pursue India BIS certification first-mover positioning through Gujarat testing partnerships. For Investors and Strategic Acquirers: Roll-up economics work for hot isostatic pressing specialists because FDA 510(k) pathway complexity and ISO 13485 traceability requirements create durable moats against industrial ceramic batch record competitors. Long-term viability centers on orthopedic implant-grade silicon nitride platform consolidation over a five-to-ten year medical device procurement cycle. Watch JEDEC substrate specification evolution as the inflection signal for gallium nitride and silicon carbide power module thermal management demand.| Strategic Initiative | Industry Significance |
|---|---|
| Gas-Pressure Sintering Capacity Expansion | Eliminates secondary HIP steps for automotive turbocharger manufacturers, compressing unit processing time. |
| Backward Integration into Captive Powder Synthesis | Secures semiconductor-grade purity control against REACH import friction and Asian tolling dependence. |
| FDA 510(k) Biocompatibility Certification Investment | Unlocks orthopedic implant market access with fracture toughness premiums exceeding alumina alternatives. |
| Direct Material Qualification Partnerships | Bypasses distributor intermediaries for tier-one bearing assembler procurement volume concentration. |
| Additive Manufacturing Process Validation | Qualifies binder jet and selective laser sintering for complex geometries previously machined from billets. |
Research Approach
Bottom-up power module and bearing assembly modeling reconciled against top-down nitridation capacity tracking forms the analytical core of this study. Primary interviews with ceramic plant managers, OEM procurement leads at diesel engine manufacturers, distribution channel partners, and technical R&D directors at powder synthesizers combined with secondary validation from SEC filings, customs trade data, JEDEC substrate specifications, and EPA emissions compliance records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map silicon metal and nitrogen gas flows through gas-pressure sintering, hot isostatic pressing, and reaction bonding routes across the analysis window. Segmentation dimensions include product type tier, application thermal specification, end-user industry certification requirement, and manufacturing method densification route. CAGRs derive from installed capacity utilization rates against qualified demand growth trajectories. Forecast inputs incorporate REACH substance registration timelines and METI industrial standard evolution for ceramic powder purity.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing of silicon nitride would alter the outlook if binder jet qualification accelerates beyond turbocharger geometries into medical implant production. Forecasts reflect assumptions about wide-bandgap power electronics deployment rates and EPA emissions standard stringency maintenance. Material deviation in JEDEC substrate specification finalization or EU F-Gas Regulation enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Tellurium Market