
 Global Metal and Ceramic Injection Molding Market | 2026-2036
Global Metal and Ceramic Injection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal and Ceramic Injection Molding Market Intelligence
The performance gap between certified, high-purity feedstocks for medical applications and standard-grade powders for consumer goods is expanding. GKN Powder Metallurgy leverages its scale to supply the high-volume automotive sector with standardized components. In contrast, Smith Metal Products specializes in intricate, small-batch parts for specialized industrial and defense customers. INDO-MIM positions itself across multiple end-markets, from electronics to automotive, to balance its production portfolio.
Metal and ceramic injection molding is a process for producing complex, net-shape parts by molding a mixture of fine powder and a binder material. Subsequent debinding and high-temperature sintering steps densify the part, yielding components with superior mechanical properties. Metal parts for the automotive and aerospace industries dominate production volumes. Ceramic components for medical devices, however, represent the fastest-growing product type due to biocompatibility requirements.
Material and process validation is governed by stringent standards, including ISO 13485 for medical devices and specific aerospace certifications. In the United States, FDA regulations for implantable devices and in Europe, the MDR framework, mandate rigorous traceability and biocompatibility testing for ceramic and metal components. Component manufacturers must now decide whether to invest in advanced metrology and quality systems for high-margin regulated markets or focus on volume in industrial applications.
Market Dynamics
The divergence between high-volume industrial part production and specialized, high-margin regulated applications is the central force shaping the market. This creates a strategic choice for manufacturers regarding investment in quality systems versus production scale for specific end-markets.
Growth Catalysts
- Binder Jetting Technology:Innovations in binder jetting are enabling faster production of intricate parts with reduced material waste, accelerating prototyping and small-series manufacturing for industrial machinery and aerospace components.
- Medical Device Sector:Requirements for complex, high-precision components for surgical tools, dental implants, and orthopedic devices drive demand for biocompatible metals and ceramics with superior mechanical properties.
- Automotive Electrification:The transition to electric vehicles creates new applications for injection molded metal parts in motor assemblies, power electronics housing, and battery systems that demand lightweight and complex geometries.
Market Restraints
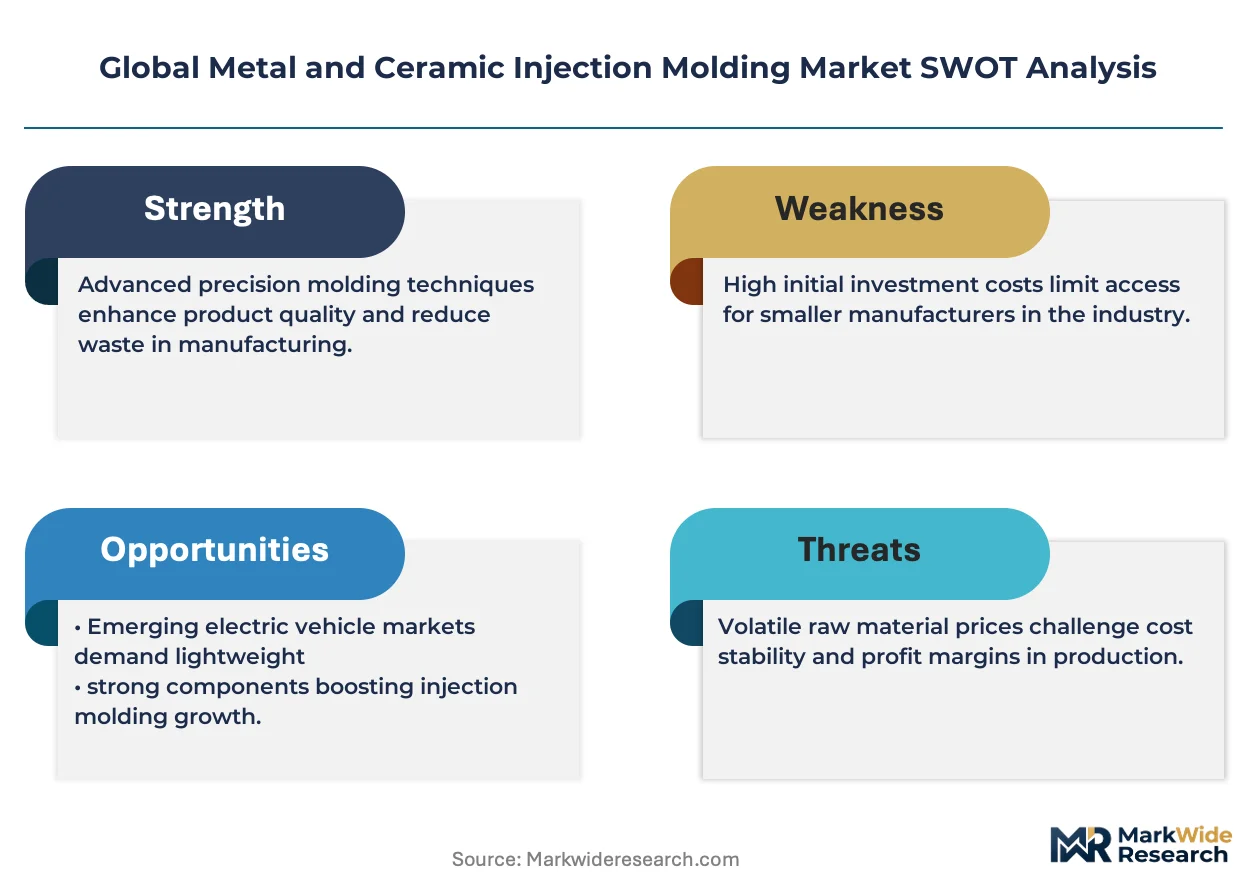
- Feedstock Cost and Purity:The significant price premium and supply volatility of high-purity, non-reactive metal and ceramic powders required for medical and aerospace applications constrain margins and limit broader adoption.
- High Capital Expenditure:The initial investment for molding machines, automated debinding stations, and high-temperature sintering furnaces is substantial, creating a high barrier to entry for new market participants.
- Part Size Limitations:The process is inherently limited in producing very large components due to challenges with uniform sintering, potential for part distortion, and the high cost of large-scale tooling.
Strategic Opportunities
- Manufacturing in Southeast Asia:Establishing production capabilities in emerging manufacturing hubs like Vietnam and Thailand can serve the expanding electronics and automotive supply chains in the region.
- Hydrogen Economy Components:The development of the hydrogen fuel sector presents an opportunity for specialized components like bipolar plates and catalyst supports that require corrosion resistance and complex channel designs.
- Advanced Ceramic Composites:Developing capabilities for ceramic matrix composites opens access to high-value applications in gas turbines and hypersonic systems where extreme temperature and wear resistance are critical.
Industry Challenges
- Process Validation Timelines:Lengthy and costly validation to meet standards like ISO 13485 for medical devices or specific aerospace certifications creates significant barriers for new material and supplier qualification.
- Skilled Labor Scarcity:A shortage of technicians with expertise in powder metallurgy, complex tool design, and sintering science constrains production capacity and process innovation across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal and Ceramic Injection Molding Market |
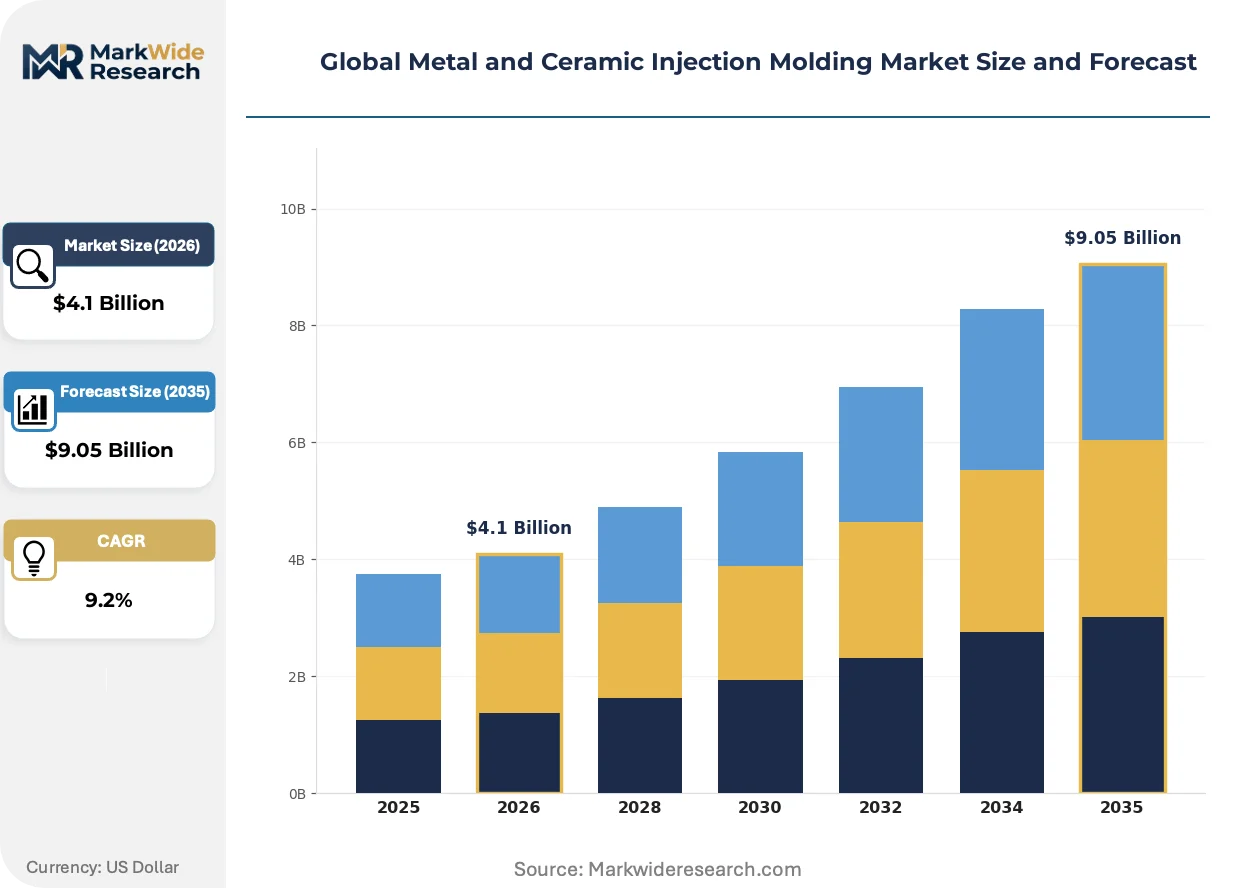
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.05 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Parts, Ceramic Components, Tooling Inserts, Custom Shapes End User: Aerospace, Automotive, Electronics, Medical Devices Technology: Powder Metallurgy, Binder Jetting, Hot Isostatic Pressing, 3D Printing Application: Consumer Goods, Industrial Equipment, Defense, Prototyping |
| Companies Covered | ARC Group Worldwide, Smith Metal Products, GKN Powder Metallurgy, CMG Technologies, Molex, Form Technologies, Advanced Powder Products, ZCMIM, INDO-MIM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal and Ceramic Injection Molding Market Strategic Shifts & Innovations
Process automation for industrial-scale production and advanced material science for high-performance components define the market's dual innovation tracks. This split influences investment strategies, pushing firms toward either volume efficiency or specialized material capabilities to serve distinct customer segments.
Binder jetting technology accelerates the creation of green parts prior to the high-temperature sintering stage. Prototyping labs and small-batch producers in aerospace and medical sectors are rapidly adopting it for complex geometries. This rapid tooling capability is expanding into bridge-to-production scenarios, reducing reliance on expensive hard tooling for initial product launches.
The European Union’s Medical Device Regulation (MDR) imposes stricter lifecycle requirements for component traceability and biocompatibility. This framework mandates that manufacturers provide extensive documentation and testing data for all materials. Medical device component suppliers are most affected, now investing in quality management systems compliant with ISO 13485 to maintain access.
A clear bifurcation in supplier selection is evident, separating volume-focused from specialization-based criteria. Automotive OEMs prioritize suppliers with scale, while defense and medical clients select partners on material expertise and certifications. This procurement pattern is most visible within Germany’s automotive clusters and the US medical device industry.
Global Metal and Ceramic Injection Molding Market Segmentation
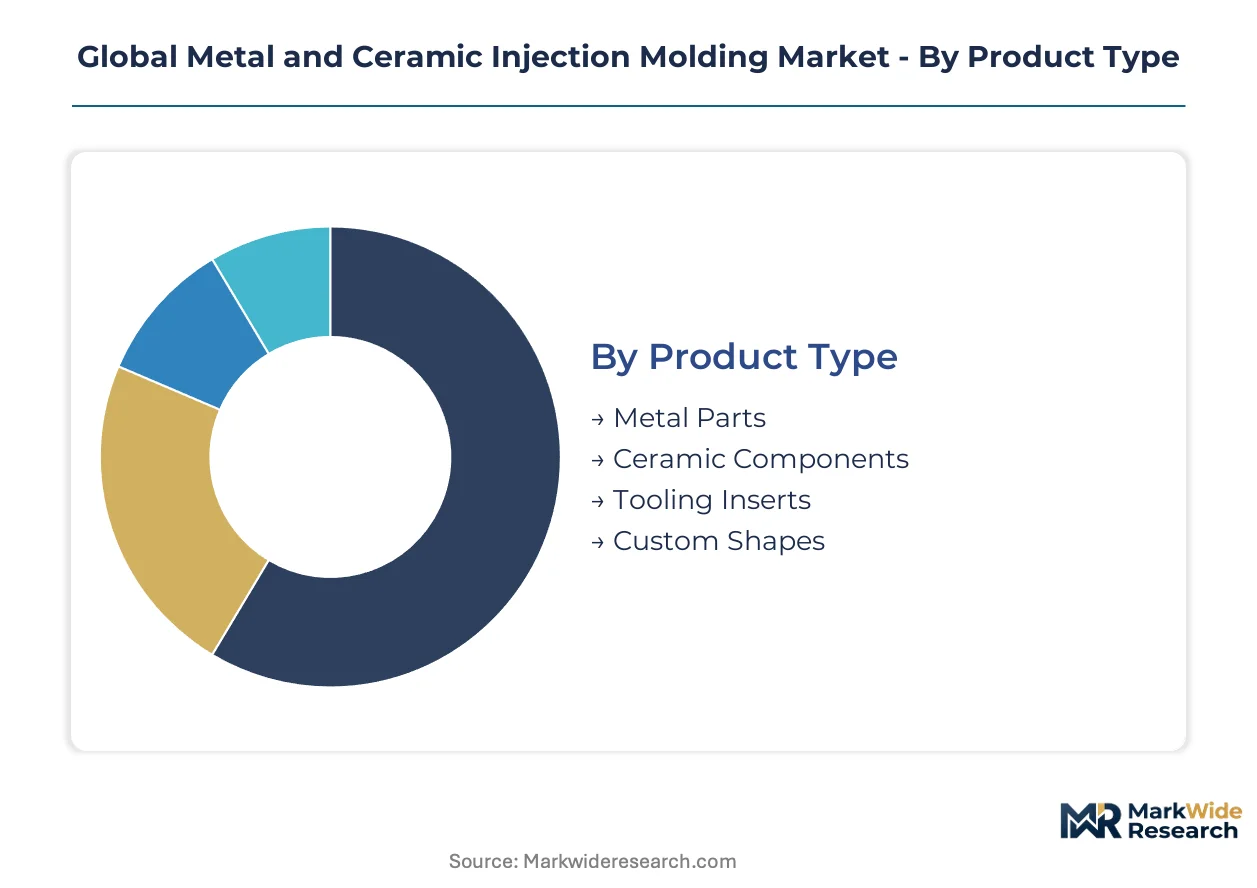
The Metal and Ceramic Injection Molding market exhibits distinct segmentation, reflecting diverse material requirements and performance demands. Understanding these segments is crucial for manufacturers to align production capabilities with specific market needs and regulatory landscapes.
Product Type:
The lifecycle of components in metal and ceramic injection molding dictates material choice, influencing initial design and subsequent replacement cycles. Different product types cater to varying performance and durability.
- Metal Parts:Formed from powdered metals like stainless steel, these offer high strength and complex geometries. Automotive industries drive demand for durable engine components.
- Ceramic Components:Made from fine ceramic powders such as zirconia, these provide exceptional hardness and biocompatibility. The medical devices sector demands them for implants and surgical instruments.
- Tooling Inserts:Precision-machined hard alloy elements, used within molds to create intricate features or improve wear resistance.
- Custom Shapes:Bespoke components tailored to unique customer specifications, often for specialized industrial or defense applications.
Volume placements concentrate in Metal Parts for industrial applications; the faster expansion belongs to Ceramic Components.
End User:
Customer acquisition strategies are segmented by specific end-user industries, each presenting unique technical requirements and procurement patterns. Manufacturers tailor offerings to meet distinct industry standards.
- Medical Devices:This sector demands biocompatible, high-precision components for surgical tools and implants, requiring stringent validation. FDA regulations mandate rigorous traceability.
- Automotive:The automotive industry uses injection molded parts for complex geometries in engine components and EV power electronics. Germany and China drive demand.
- Aerospace:Aerospace applications require lightweight, strong components for turbine parts and structural elements, often from specialized alloys.
- Electronics:The electronics industry uses intricate, small-form-factor metal and ceramic components for connectors, heat sinks, and housings.
Automotive applications command the largest production volumes, while the Medical Devices sector is experiencing the steepest expansion trajectory.
Technology:
The maturity and investment profile of various technologies shape the competitive landscape, influencing production efficiency and part complexity. Firms evaluate these based on precision and scale for target markets.
- Powder Metallurgy:This foundational process molds fine metal or ceramic powders with a binder, followed by debinding and sintering. It underpins conventional industrial production.
- Binder Jetting:An additive manufacturing process, binder jetting rapidly produces green parts by depositing binder onto a powder bed. It enables intricate geometries and accelerated prototyping.
- Hot Isostatic Pressing:This post-processing technique applies high pressure and temperature to sintered parts, eliminating porosity. It is applied to critical defense and medical implants.
- 3D Printing:Broader 3D printing methods are employed for metal and ceramic parts, offering design flexibility for specialized tools and small-batch production.
Powder Metallurgy accounts for the majority of current output, but Binder Jetting is gaining share fastest in advanced manufacturing.
Application:
Diverse applications of metal and ceramic injection molding components drive differentiation in material selection and process optimization, directly impacting product performance and cost structures. Each demands specific properties.
- Industrial Equipment:This segment includes components for machinery and automation systems, where durability, wear resistance, and precision are critical. Manufacturers supply intricate gears and nozzles.
- Prototyping:Utilizing technologies like binder jetting, prototyping allows for rapid iteration and testing, reducing development cycles for complex parts. This supports early-stage product validation.
- Consumer Goods:This category encompasses metal and ceramic parts used in everyday items like electronics enclosures, prioritizing aesthetic quality and cost-effectiveness.
- Defense:The defense sector requires high-strength, lightweight, and heat-resistant components for armaments and communication systems, demanding robust certification.
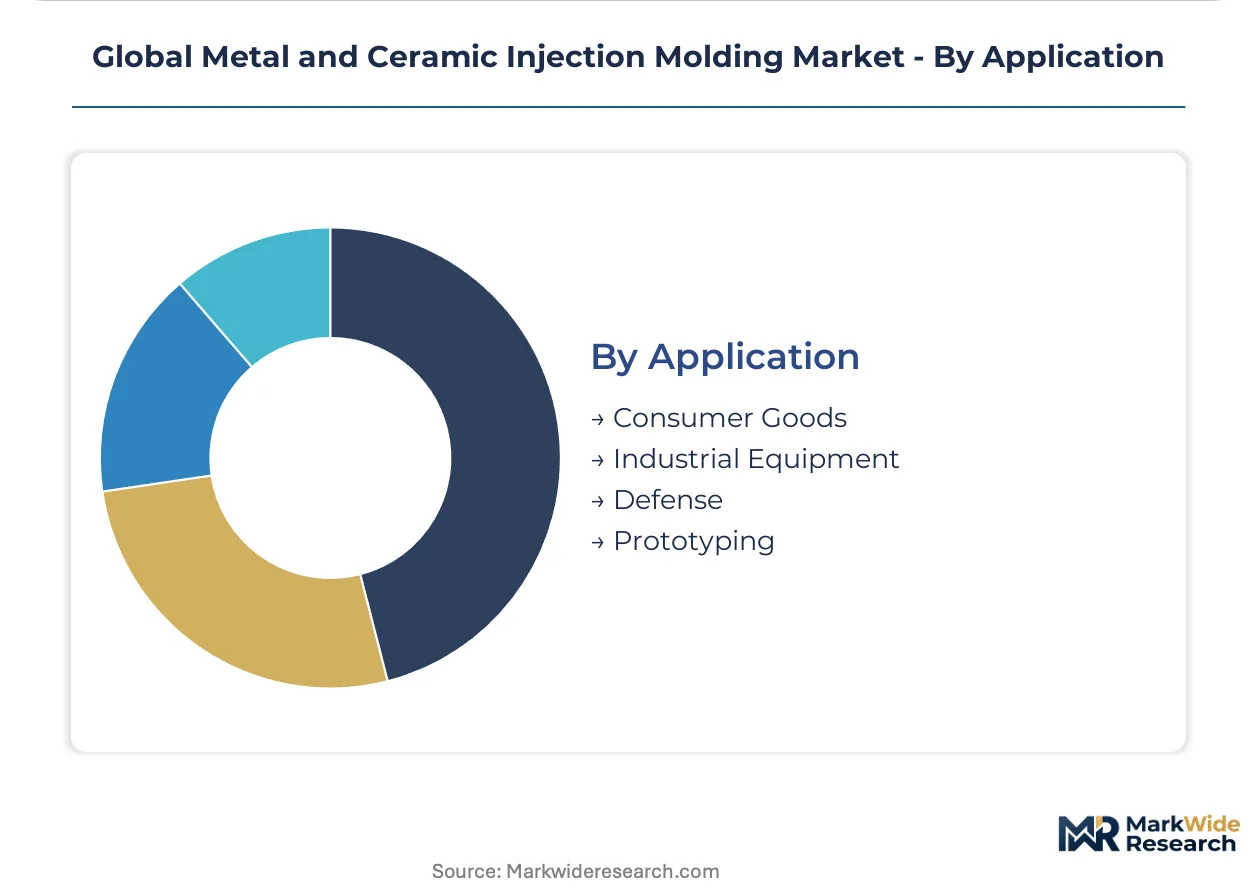
Industrial Equipment represents a substantial volume base, while Prototyping applications are expanding most quickly due to innovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive clusters and medical device manufacturing hubs in the United States drive significant demand for metal and ceramic injection molded components. These regions benefit from established industrial infrastructure and a strong focus on high-precision engineering. The market sees specific country-level dynamics influencing adoption and production capacities across various end-use sectors.
Germany
Automotive electrification and advanced industrial machinery demand complex metal parts in Germany. The country's strict quality standards, including those from the KBA for automotive components, shape manufacturing processes. Production concentrates in Bavaria and Baden-Württemberg, where automotive OEMs and their suppliers require precision components for new vehicle architectures.
China
China's electronics and automotive industries are major consumers of injection molded parts, especially for high-volume applications. The GB standards for material quality and product performance influence local manufacturing practices. Industrial parks in the Yangtze River Delta and Pearl River Delta regions house numerous facilities producing intricate metal and ceramic components for consumer electronics and electric vehicles.
United States
The United States medical device sector drives demand for biocompatible ceramic components and specialized metal implants. FDA regulations for implantable devices mandate rigorous material traceability and performance validation. Major medical device clusters in Massachusetts and Minnesota foster innovation in custom shapes and advanced material applications.
Japan
Japan's precision engineering and electronics sectors require high-performance metal and ceramic components for miniaturized devices and robotics. METI guidelines for industrial innovation support advanced manufacturing technologies like binder jetting. The Kanto region, including Tokyo, remains a hub for electronics manufacturing and specialized prototyping services.
Vietnam
Vietnam is emerging as a critical manufacturing hub, attracting foreign investment for electronics assembly and automotive component production. The government's industrial policies support the growth of high-tech manufacturing and export-oriented industries. Industrial zones near Hanoi and Ho Chi Minh City are expanding capabilities for metal and ceramic injection molding to serve regional supply chains.
Global Metal and Ceramic Injection Molding Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure for metal and ceramic injection molding services. The industry exhibits a clear bifurcation between high-volume manufacturers and specialized component providers. Strategic archetypes include large-scale industrial suppliers, niche medical device specialists, and diversified multi-market players. Dominant competitive moves involve capacity expansion for industrial volumes and targeted technology investments for high-margin applications.
At the scale-driven end, GKN Powder Metallurgy exemplifies a major player leveraging extensive production capabilities for the automotive sector. Smith Metal Products, conversely, occupies a position as a specialist, providing intricate, small-batch components for defense and industrial clients. INDO-MIM represents a diversified approach, balancing its production portfolio across various end-markets from electronics to automotive.
| Leading Market Players |
|---|
| ARC Group Worldwide |
| Smith Metal Products |
| GKN Powder Metallurgy |
| CMG Technologies |
| Molex |
| Form Technologies |
| Advanced Powder Products |
| ZCMIM |
| INDO-MIM |
| Others |
Cost & Logistics Intelligence
Binder jetting technology simultaneously reshapes cost economics by reducing material waste and influences supply concentration by enabling localized, rapid prototyping services. This shift impacts both production efficiency and geographic sourcing strategies across the market.
Pricing Analysis
Value-based pricing anchors component costs to performance outcomes, particularly for critical medical and aerospace applications. The dominant pricing structure is contract-based long-term offtake for high-volume industrial parts, transitioning to project-based models for specialized, low-volume components. Price differentiation stems from certification level, such as ISO 13485 compliance, and the degree of customization required for unique geometries. Cost compression in industrial applications is intensifying due to increasing competition and efforts to standardize components. Automotive and electronics manufacturers exhibit the highest price sensitivity, while medical device and defense sectors prioritize performance over cost.
Supply Chain Analysis
Domestic-content mandates and stringent regulatory frameworks like FDA regulations for implantable devices significantly reshape sourcing decisions. Geographic supply concentrates in Germany for automotive components and the United States for specialized medical devices. Raw material dependencies include high-purity metal powders like stainless steel and fine ceramic powders such as zirconia. A key structural supply chain risk is the supply volatility and price premium associated with specialized, non-reactive feedstocks. Distribution runs through direct sales channels to large original equipment manufacturers (OEMs) and specialized distributors catering to niche industrial and defense customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play, driven by the substantial capital expenditure required for advanced manufacturing and stringent validation processes. Weaker players face increasing pressure from these barriers.
For Market Incumbents: Deploy advanced metrology and quality systems to reinforce market position in regulated sectors. Invest in ISO 13485 compliant facilities, particularly in medical device clusters within the United States, to maintain access to high-margin applications. Expand production capacity in established manufacturing hubs like Germany and China to serve high-volume automotive and electronics sectors. This strategy counters the threat of feedstock cost volatility and new entrants leveraging binder jetting for prototyping.
For New Entrants and Emerging Players: Small-batch, high-complexity medical device startups represent an underserved buyer archetype ready for specialized solutions. Target prototyping applications and custom shapes for the defense sector, leveraging binder jetting's rapid iteration capabilities. Focus on advanced material expertise and rapid process validation as a go-to-market angle. The most penetrable segment for new entrants involves providing specialized components for industrial machinery and early-stage product development in aerospace.
For Investors and Strategic Acquirers: Re-rating potential sits with niche medical device specialists given the stringent regulatory frameworks and high barriers to entry. Focus on firms with established certifications and advanced material science capabilities in ceramic composites or specialized metal alloys. The long-term viability favors entities capable of navigating both high-volume industrial demands and high-precision regulated markets. A key signal to watch is increased M&A activity for companies possessing strong intellectual property in binder jetting or advanced ceramic processing.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in ISO 13485 Certified Production | Ensures compliance for medical devices, securing access to high-margin regulated markets. |
| Expand Binder Jetting Capabilities | Accelerates prototyping and small-series manufacturing, reducing time-to-market for complex parts. |
| Secure Long-Term Feedstock Contracts | Mitigates supply volatility and price premiums for high-purity metal and ceramic powders. |
| Develop Ceramic Matrix Composites | Unlocks high-value applications in gas turbines and hypersonic systems requiring extreme resistance. |
| Establish Production in Southeast Asia | Accesses expanding electronics and automotive supply chains in Vietnam and Thailand. |
Research Approach
Industry association reports, academic journals on powder metallurgy, and government agency publications formed the secondary backbone of this study. This research combined insights from primary interviews with automotive OEM procurement leads, medical device R&D engineers, aerospace material scientists, and regulatory affairs specialists. Bottom-up and top-down triangulation validated market size and growth projections across various segments.
Bottom-up analysis informed the analytical lens, projecting market volumes from individual end-user applications and product types. Segmentation dimensions modeled included product type, end-user industry, technology adoption, and application. Compound annual growth rates were derived from historical data analysis and projected market drivers over the analysis window. Industry-specific forecast inputs included electric vehicle production forecasts and medical device approval rates.
Revisions become necessary when significant shifts in global trade policies or raw material supply dynamics materialize. Forecasts reflect assumptions regarding technological advancements and regulatory stability across key markets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Stoneware Market
Ceramics
North America Ceramic Coatings Market
Ceramics
USA and Canada Alumina Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Ball Clay Market
Ceramics
Graphite Crucibles Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Global Functional Ceramics Market
Ceramics
Cerium Nitride Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Glass Ceramics Market
Ceramics
Ceramic Frit Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Global Industrial Clay Market