
 Metal Alloys Market | 2026-2036
Metal Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Alloys Market Analysis
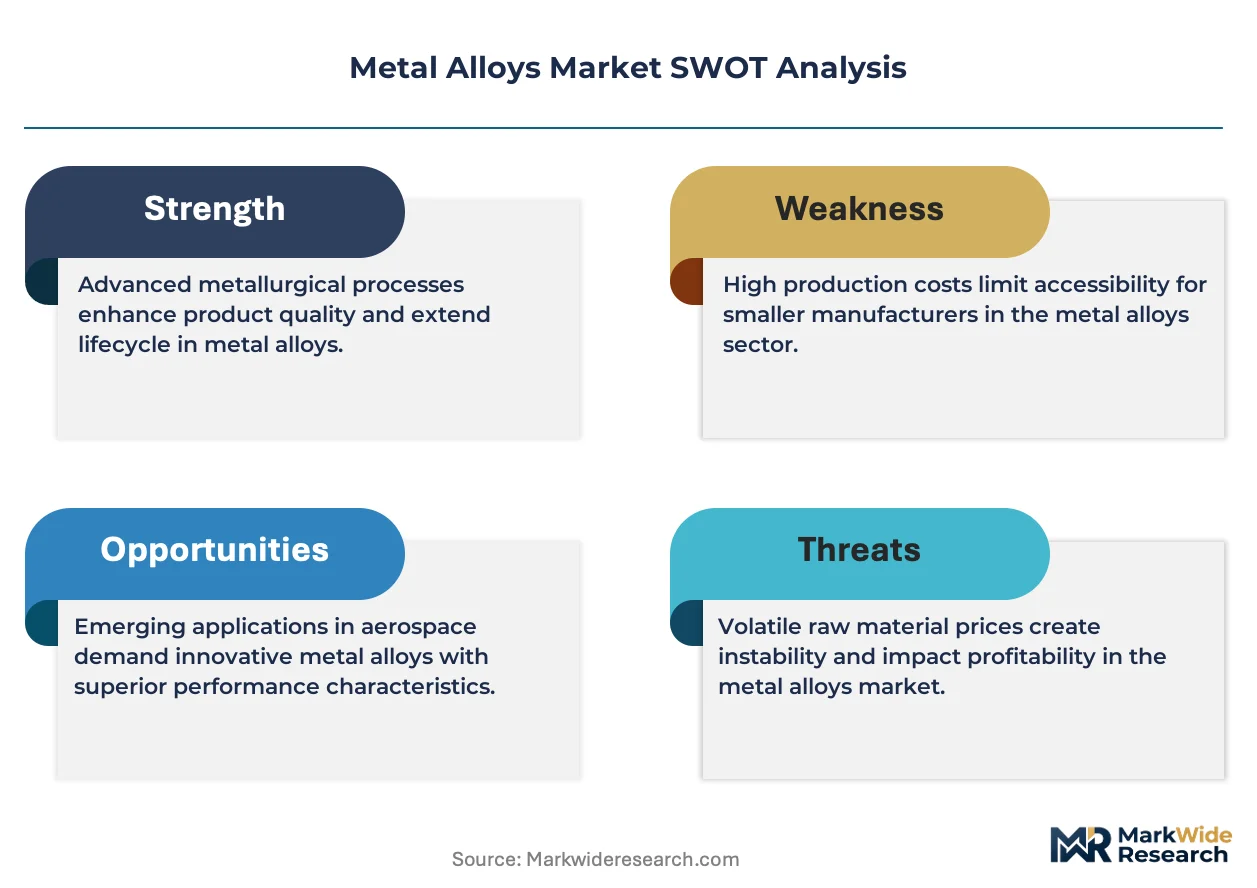
Asset-light leasing models for high-performance melting and forging equipment is reconfiguring competitive entry barriers across the specialty alloys space. Sandvik AB leverages captive powder metallurgy capabilities to dominate superalloy niche supply chains. Thyssenkrupp AG anchors its position through integrated stainless steel production from melt shop to precision strip. VSMPO-AVISMA controls the world's largest titanium sponge-to-mill-product vertical, sustaining aerospace-grade certification depth that few rivals can replicate.
Metal alloys are engineered materials combining two or more metallic elements to achieve specific mechanical, thermal, or corrosion-resistant properties, typically produced through electric arc melting, vacuum induction melting, or powder metallurgy processes with precise control over grain structure and inclusion content. These materials serve as the structural backbone for applications requiring strength-to-weight optimization, high-temperature stability, or electrical conductivity beyond pure metal limits. Steel alloys occupy the largest value pool across structural components and machinery parts, while nickel-based superalloys command the fastest growth trajectory in aerospace and power generation turbine applications. Aluminum alloys in sheet and plate form are consolidating margin share as automotive OEMs lightweight body-in-white architectures, with copper alloys in wire and bar form retaining critical positioning in electrical conductor and heat exchanger supply chains.
REACH and RoHS frameworks in Europe restrict hazardous substance content in alloy formulations, while China's GB standards and MEE environmental enforcement drive smelter consolidation and emissions-linked capacity licensing. The US FAA and NHTSA material qualification protocols govern alloy traceability and mechanical property certification for aerospace and automotive structural applications. Stakeholders must monitor evolving carbon border adjustment mechanisms and scrap circularity mandates that will reshape raw material procurement economics and regional cost competitiveness.
Market Dynamics
Carbon border adjustment mechanisms are redrawing competitive cost curves across the metal alloys value chain, forcing producers to reconfigure energy sourcing and scrap circularity systems ahead of phased tariff implementation.
Growth Catalysts
- Aerospace OEM procurement:Next-generation airframe programs in the US and EU are expanding long-term alloy offtake agreements for titanium and nickel-based superalloys, locking in volume commitments through 2035.
- India's PLI scheme:Production-linked incentives for specialty steel and aluminum value addition are concentrating capacity expansion in Gujarat and Odisha industrial corridors.
- REACH compliance depth:European traceability mandates for critical raw material sourcing are filtering supplier bases and favoring certified producers with established audit trails.
Market Restraints
- Scrap availability volatility:Aerospace-grade titanium scrap supply concentrates in VSMPO-AVISMA's captive recycling network, limiting independent processor feedstock security.
- Energy cost asymmetry:European smelters face structurally higher electricity tariffs than Middle Eastern or Indian competitors, compressing stainless steel margin sustainability.
- Technical qualification timelines:FAA and NHTSA material certification protocols extend 18-36 months for new alloy formulations, freezing incumbent specifications.
Strategic Opportunities
- India's industrial corridor buildout:Underpenetrated precision strip and forging capacity presents white space for specialty stainless and aluminum alloy producers.
- Hydrogen-ready pipeline steel:Emerging demand for high-strength, hydrogen-embrittlement-resistant linepipe alloys is opening specification windows outside traditional API grades.
- Asset-light equipment leasing:Melting and forging equipment leasing models reduce capital barriers for specialty alloy entrants targeting niche superalloy segments.
Industry Challenges
- Vacuum metallurgy talent scarcity:Qualified vacuum induction melting engineers and powder metallurgy technicians command premium compensation, constraining capacity ramp rates.
- Multi-certification complexity:Simultaneous compliance with FAA, EASA, and CAAC qualification protocols fragments quality system investments for aerospace suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Alloys Market |
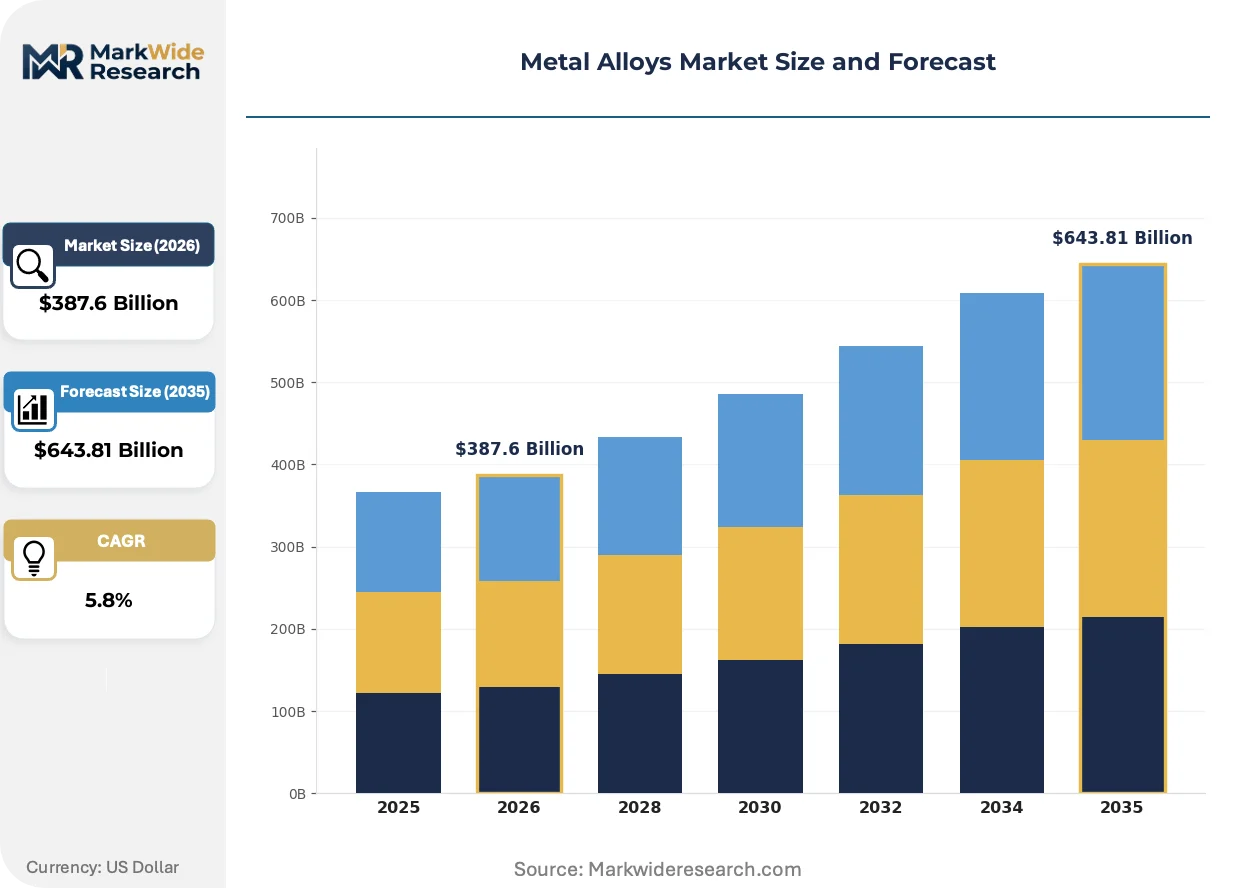
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Copper, Nickel End User: Aerospace, Automotive OEMs, Construction, Marine Application: Structural Components, Electrical Conductors, Machinery Parts, Heat Exchangers Form: Bar, Plate, Sheet, Wire |
| Companies Covered | Sandvik AB, VSMPO-AVISMA, Special Metals Corporation, Thyssenkrupp AG, Aperam, Allegheny Technologies Incorporated, Outokumpu Oyj, Alcoa Corporation, Carpenter Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Alloys Market Emerging Trajectories
Additive manufacturing feedstock specifications are rewriting alloy chemistry requirements, compressing traditional mill product demand while expanding atomized powder and wire demand pools.
Powder metallurgy superalloy production is migrating from conventional cast-and-wrought processing toward direct hot isostatic pressing of pre-alloyed powders. Aerospace turbine blade manufacturers are accelerating adoption for complex geometries impossible through forging. This technology is migrating from prototyping cells into qualified production lines, collapsing lead times for engine program development cycles.
China's GB standards and MEE environmental enforcement are tightening emissions-linked capacity licensing for ferroalloy smelters. Smaller, unlicensed producers are exiting the market, consolidating supply among state-backed integrated mills. The stainless steel segment faces the steepest compliance costs, with Jiangsu and Shandong provinces driving the bulk of closures.
Long-term alloy procurement contracts are displacing spot market purchasing among automotive OEMs. Tier-1 suppliers are absorbing inventory risk through consignment stock arrangements at stamping plants. Germany and Japan exhibit the most advanced contract structuring, with US programs now converging toward similar frameworks.
Metal Alloys Market Segmentation
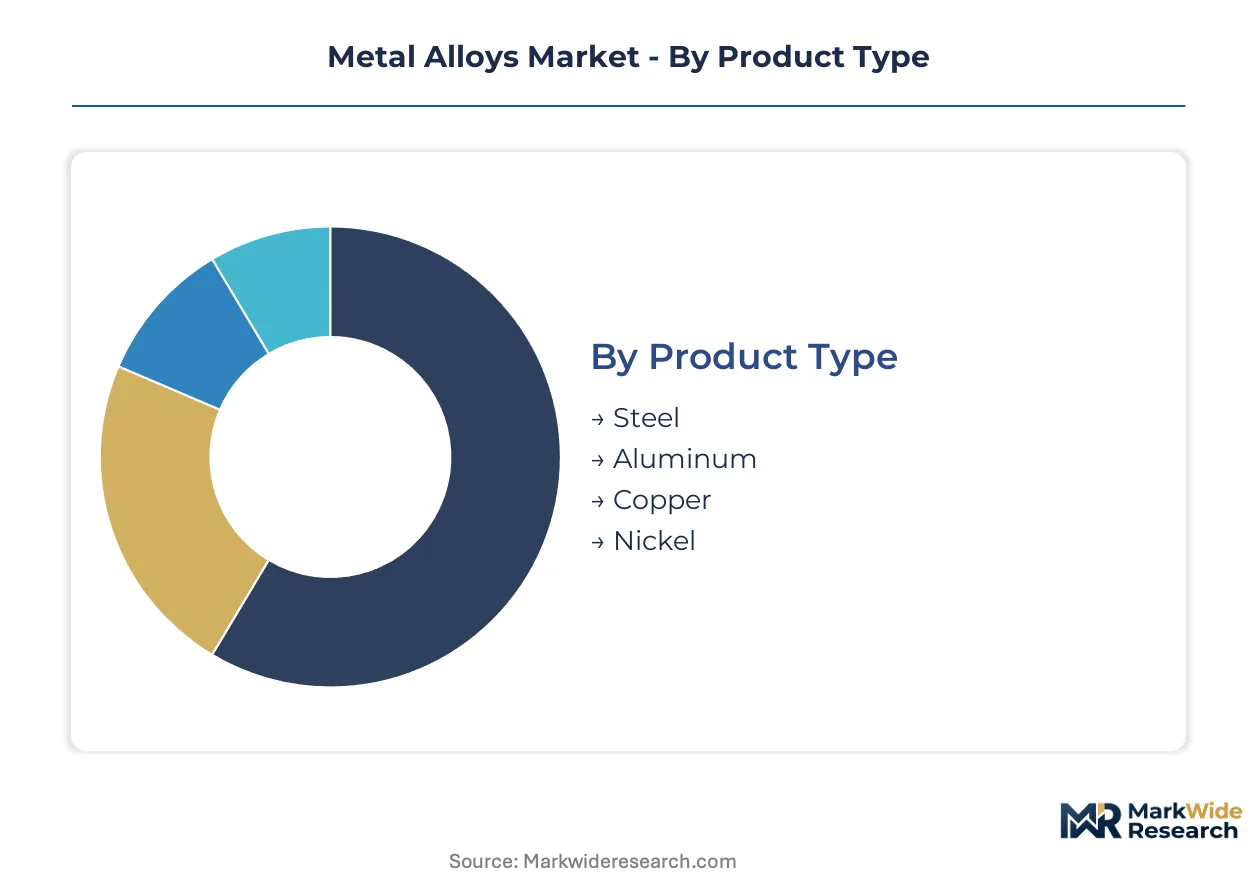
Metal alloys serve divergent performance requirements across load-bearing structures, thermal management systems, and electrical transmission networks. Segmentation reveals how chemistry and form factor decisions cascade through specification hierarchies in aerospace, automotive, and energy infrastructure procurement.
Product Type:
End-use performance demands span corrosion resistance, strength-to-weight optimization, and electrical conductivity, driving alloy selection across industrial verticals.
- Steel:Carbon, alloy, and stainless grades dominate structural machinery and construction reinforcement. India's PLI scheme for specialty steel is concentrating capacity expansion in Gujarat and Odisha corridors, tightening regional supply security for automotive OEMs.
- Aluminum:Lithium-bearing and high-strength 7000-series formulations enable body-in-white lightweighting. Automotive OEMs in Germany and Japan are locking in long-term procurement contracts for sheet and extrusion feedstock, displacing spot market purchasing.
- Copper:Beryllium-copper and phosphor bronze alloys serve electrical contacts and spring applications. BIS certification requirements in India are filtering supplier bases for critical conductor specifications.
- Nickel:Superalloy grades withstand turbine operating temperatures exceeding 1000°C. FAA and EASA qualification protocols govern chemistry and traceability for aerospace blade and disk forgings.
The dominant share belongs to Steel, while Aluminum is closing the gap fastest.
End User:
Customer procurement patterns range from multi-year qualification cycles in aerospace to high-volume consignment arrangements in automotive stamping operations.
- Aerospace:Turbine engine and airframe manufacturers impose 18-36 month material certification timelines. VSMPO-AVISMA's captive titanium sponge-to-mill-product vertical sustains certification depth that independent processors struggle to replicate.
- Automotive OEMs:Stamping plants are absorbing inventory risk through consignment stock arrangements with Tier-1 suppliers. Germany and Japan exhibit the most advanced contract structuring, with US programs converging toward similar frameworks.
- Construction:Rebar and structural beam specifications prioritize yield strength and weldability. China's GB standards and MEE environmental enforcement are consolidating ferroalloy smelter capacity among state-backed integrated mills.
- Marine:Duplex stainless steel resists chloride pitting in offshore platform and ship hull applications. REACH compliance in Europe mandates hazardous substance traceability through supply chains.
Aerospace commands the steepest qualification barriers, while Automotive OEMs drive the highest volume throughput.
Application:
Functional requirements dictate grain structure control, inclusion limits, and surface finish specifications across divergent use cases.
- Structural Components:Load-bearing frames and pressure vessels demand controlled yield strength and fracture toughness. API grades dominate oil and gas linepipe, though hydrogen-embrittlement-resistant specifications are opening new chemistry windows.
- Electrical Conductors:OFHC copper and aluminum alloy wire achieve conductivity thresholds above 100% IACS. Grid infrastructure expansion in India is concentrating demand for high-purity conductor stock.
- Machinery Parts:Gears, shafts, and bearings require hardenability and fatigue resistance. Powder metallurgy is migrating from prototyping into qualified production lines, collapsing lead times for complex geometries.
- Heat Exchangers:Fin-and-tube assemblies exploit aluminum thermal conductivity and copper corrosion resistance. GB standards in China are tightening emissions-linked capacity licensing for smelter operations.
Structural Components anchor volume demand, while Heat Exchangers face accelerating specification pressure from energy efficiency mandates.
Form:
Mill product geometry determines downstream processing economics and scrap recovery rates across forging, machining, and fabrication value chains.
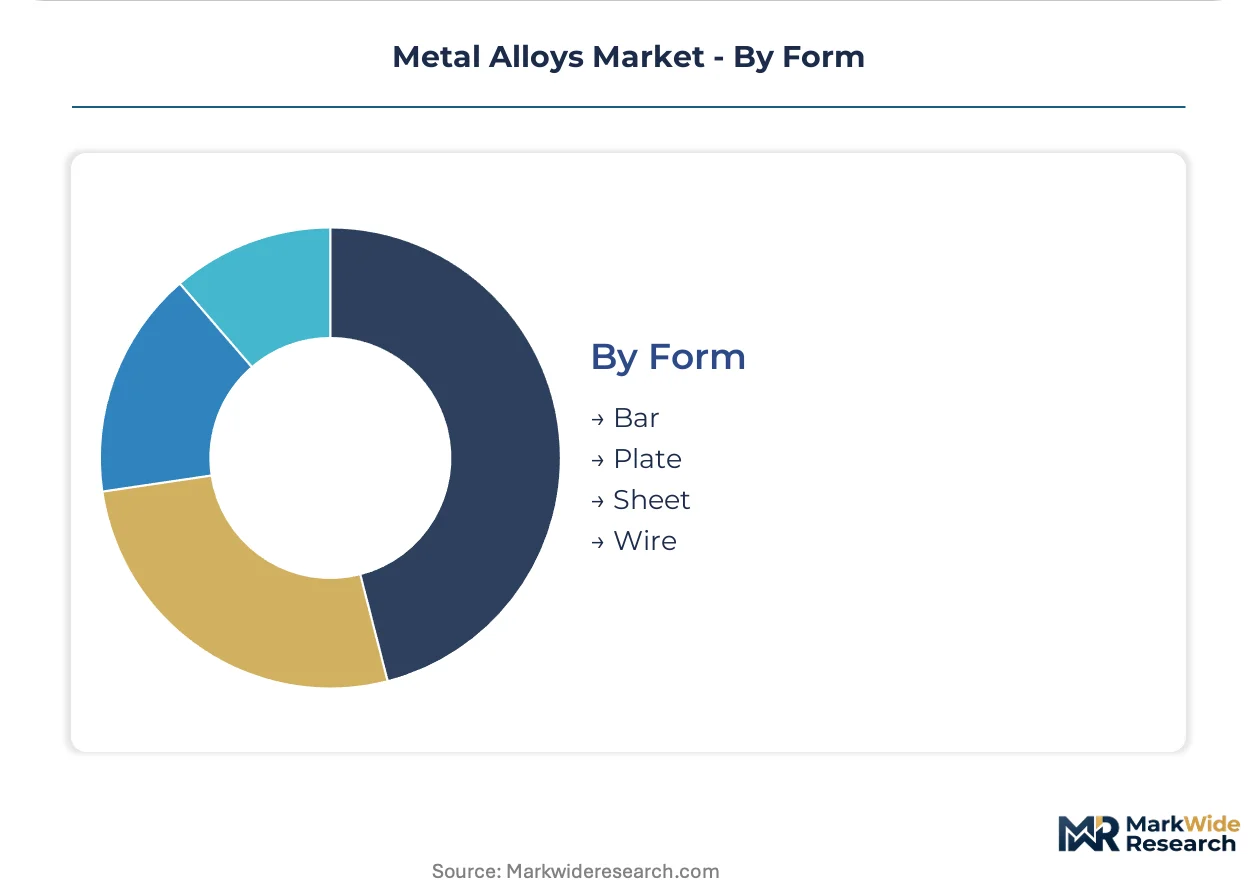
- Bar:Round, hexagonal, and square sections feed CNC machining and forging operations. Sandvik AB leverages captive powder metallurgy capabilities to dominate superalloy bar supply for medical and aerospace precision components.
- Plate:Heavy-gauge plate supports pressure vessel and armor applications. Thyssenkrupp AG anchors its position through integrated stainless steel production from melt shop to precision strip.
- Sheet:Cold-rolled and hot-rolled coils enable stamping and roll-forming processes. Automotive lightweighting programs in the US and EU are expanding long-term offtake agreements for aluminum automotive sheet.
- Wire:Rod and drawn wire serve fastener, spring, and welding electrode production. Asset-light leasing models for melting and forging equipment are reconfiguring competitive entry barriers for specialty wire producers.
Sheet captures the largest value pool from automotive procurement, while Bar commands the highest margin premiums from aerospace qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European smelters absorb electricity tariffs that exceed Indian and Middle Eastern benchmarks by multiples, eroding stainless steel margin sustainability against import competition. This pricing-power asymmetry is redrawing procurement patterns across the metal alloys value chain.
United States
Aerospace OEMs in Seattle and Wichita are expanding long-term offtake agreements for titanium and nickel-based superalloys through 2035. FAA material qualification protocols govern 18-36 month certification timelines for new alloy formulations. The Ohio Valley and Pennsylvania industrial clusters concentrate specialty steel forging capacity serving automotive and energy infrastructure demand.
Germany
Automotive stamping plants in Stuttgart and Wolfsburg are absorbing inventory risk through consignment stock arrangements with Tier-1 suppliers. REACH compliance mandates hazardous substance traceability through supply chains, filtering supplier bases for certified producers. The Ruhr industrial corridor anchors integrated stainless steel production from melt shop to precision strip.
China
GB standards and MEE environmental enforcement are consolidating ferroalloy smelter capacity among state-backed integrated mills in Jiangsu and Shandong provinces. Dual carbon goals are tightening emissions-linked capacity licensing for smaller producers. The Yangtze River Delta concentrates aerospace-grade titanium sponge-to-mill-product vertical integration.
India
PLI scheme incentives for specialty steel and aluminum value addition are concentrating capacity expansion in Gujarat and Odisha industrial corridors. BIS certification requirements filter supplier bases for critical conductor specifications. Grid infrastructure expansion is driving demand for high-purity copper and aluminum alloy wire in Maharashtra and Karnataka.
Japan
METI industrial policy supports advanced powder metallurgy capabilities for aerospace turbine blade applications. JIS standards govern material specifications for automotive and machinery alloy procurement. The Chubu region around Nagoya concentrates precision forging and machining operations serving export markets.
Metal Alloys Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in narrow chemistry niches. The vendor base separates into three tiers: integrated mills with captive raw material supply, mid-scale processors with qualification depth in specific alloy families, and atomization specialists feeding additive manufacturing feedstock demand. Consolidation pressure concentrates among stainless steel producers facing carbon border adjustment exposure, while superalloy segments retain fragmentation due to FAA and EASA certification barriers. Dominant competitive moves include backward integration into titanium sponge and nickel matte production, plus strategic partnerships with aerospace OEMs for long-term volume commitments.
Among European-integrated stainless steel producers, Outokumpu Oyj and Aperam exemplify the mill-to-strip archetype with qualification depth across chemical and architectural specifications. Allegheny Technologies Incorporated and Carpenter Technology Corporation occupy positions within the North American specialty alloy tier, where vacuum induction melting capabilities and powder metallurgy expertise anchor premium positioning. These producers represent the competitive tension between scale-driven integrated operations and qualification-intensive niche specialists.
| Leading Market Players |
|---|
| Sandvik AB |
| VSMPO-AVISMA |
| Special Metals Corporation |
| Thyssenkrupp AG |
| Aperam |
| Allegheny Technologies Incorporated |
| Outokumpu Oyj |
| Alcoa Corporation |
| Carpenter Technology Corporation |
| Others |
Supply Flow & Price Mechanics
Carbon border adjustment exposure determines both pricing tier spreads and supply chain shape across the metal alloys value chain, forcing European smelters to absorb electricity tariffs that exceed Indian and Middle Eastern benchmarks by multiples while compressing margin sustainability against import competition.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with aerospace procurement locking volume commitments through 2035 and automotive stamping plants absorbing inventory risk through consignment arrangements. Price differentiation hinges on certification depth—FAA and EASA qualification tiers command substantial premiums over commercial-grade specifications—and volume scale, with spot market purchasing retreating as long-term agreements displace transactional procurement. Cost compression in stainless steel is intensifying because European energy tariffs erode regional competitiveness against Middle Eastern and Indian imports. Tier-1 automotive suppliers exhibit the highest price sensitivity due to consignment stock obligations, while aerospace OEMs demonstrate the least sensitivity given 18-36 month qualification timelines that freeze incumbent specifications.
Supply Chain Analysis
Export-control restrictions on aerospace-grade titanium sponge and nickel matte limit flows from Russia and China to Western defense-critical supply chains, fragmenting raw material access for independent processors. Geographic supply concentration centers on China for ferroalloy smelting, Russia for titanium sponge-to-mill-product vertical integration, and India for specialty steel and aluminum capacity expansion under PLI incentives. Raw material dependencies rest on nickel matte from Indonesia and the Philippines, titanium sponge from Russia and China, and high-grade scrap from captive aerospace recycling networks. Single-source vulnerability concentrates in VSMPO-AVISMA's captive titanium recycling network, limiting independent processor feedstock security. Distribution runs through mill-direct relationships with aerospace OEMs and Tier-1 automotive suppliers, with consignment stock arrangements at stamping plants displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal alloys market sits at a platform-economics inflection where additive manufacturing feedstock specifications are rewriting alloy chemistry requirements and collapsing traditional mill product demand pools into atomized powder and wire ecosystems.
For Market Incumbents: Pre-empt additive manufacturing feedstock commoditization by locking in aerospace OEM qualification depth for pre-alloyed powder specifications before hot isostatic pressing production lines achieve full scale. Defend margin position through backward integration into titanium sponge and nickel matte production, neutralizing raw material cost volatility that independent processors cannot replicate. Prioritize certification investment in simultaneous FAA, EASA, and CAAC qualification protocols to fragment competitor quality system investments.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated precision strip and forging capacity across Gujarat and Odisha industrial corridors, where PLI scheme incentives reduce capital barriers for specialty stainless and aluminum alloy production. Target hydrogen-ready pipeline steel specifications outside traditional API grades, where emerging demand for hydrogen-embrittlement-resistant linepipe alloys opens chemistry windows unclaimed by incumbents. Pursue asset-light equipment leasing models for melting and forging capacity to reduce capital barriers and accelerate niche superalloy segment entry.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vacuum induction melting specialists with established aerospace certification depth over scale-driven integrated stainless steel producers facing carbon border adjustment exposure. Long-term viability over the next decade hinges on positioning upstream of additive manufacturing feedstock demand migration and downstream of regulatory chokepoints tightening emissions-linked capacity licensing. Watch for inflection signals in FAA qualification protocol acceleration for powder metallurgy superalloys, which would collapse traditional cast-and-wrought incumbent advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Captive supply of aerospace-grade sponge neutralizes VSMPO-AVISMA's raw material chokehold on Western processors. |
| Long-term Supply Agreement with Aerospace OEMs | Volume commitments through 2035 lock in offtake before additive manufacturing displaces traditional mill product demand. |
| Green Manufacturing Transition | Scrap circularity systems and renewable energy sourcing preempt carbon border adjustment tariff exposure in European markets. |
| Joint Venture for Powder Metallurgy Capacity | Hot isostatic pressing partnerships with turbine blade manufacturers collapse lead times for complex geometries impossible through forging. |
| Capacity Expansion in India Industrial Corridors | PLI scheme incentives in Gujarat and Odisha reduce capital barriers for specialty steel and aluminum value addition. |
Methodological Framework
Cross-validation between primary interviews with aerospace procurement directors, automotive Tier-1 supplier executives, vacuum induction melting engineers, and ferroalloy smelter operations managers and secondary validation through customs and trade data, SEC 10-K filings, FAA material qualification databases, and ECHA REACH compliance registries anchors the qualitative findings. Bottom-up and top-down triangulation reconciles mill product shipment volumes with end-use consumption patterns across aerospace, automotive, and energy infrastructure applications.
Calibration against historical capacity utilization rates, qualification timeline distributions, and raw material cost pass-through elasticities shapes the analytical framework across the analysis window. Segmentation dimensions modeled include alloy chemistry family, mill product form, end-use industry vertical, certification tier, and regional production hub. CAGRs derive from regression analysis of procurement contract volumes, capacity expansion announcements, and regulatory compliance cost trajectories, with specific weighting for India's PLI scheme incentive flows and China's MEE environmental enforcement intensity.
Sensitivities concentrate around carbon border adjustment implementation timelines, aerospace OEM program delays, and scrap circularity mandate enforcement. Forecasts reflect assumptions on energy cost trajectories, qualification protocol stability, and additive manufacturing adoption curves. Material shifts in FAA powder metallurgy qualification acceleration or REACH hazardous substance restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
United States Metal Casting Market
Metals
Qatar Metalworking Market
Metals
Aluminium Conductors Market
Metals
Smelting Chemicals Market
Metals
Titanium Powder Market
Metals
Copper and Copper Alloy Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
316 Stainless Steel Container Market
Metals
Global Stretch Spring Wire Market
Metals
Stainless Steel Foil Market
Metals
Metal Forging Parts Market
Metals
High Carbon Bearing Steel Market
Metals
Global Flat Carbon Steel Market
Metals
Global Chromium Market
Metals
Aluminum Smelting Market