
 Sodium Aluminum Silicate Market | 2026-2036
Sodium Aluminum Silicate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Aluminum Silicate Market Analytics
Market Context with Strategic Players
Specialty food additive buyers are redrawing procurement priorities toward high-purity anti-caking and stabilizer grades. Evonik Industries AG leverages its precipitated silicate expertise to anchor supply relationships with European food manufacturers. PQ Corporation competes through vertical integration into raw material sourcing and captive alkali silicate production. Clariant specializes in surface-modified grades that target premium cosmetics and pharmaceutical excipient applications.
Technical Definition and Structural Segments
Sodium aluminum silicate is a synthetic amorphous precipitated compound with the general formula Na2O·Al2O3·nSiO2·xH2O, manufactured via controlled reaction of sodium silicate with aluminum salts under precise pH and temperature conditions to achieve specific surface area and particle size distributions. It functions primarily as a functional additive providing rheology control, moisture absorption, and suspension stability across industrial and consumer formulations. Powder grades dominate volume throughput due to their versatility in dry-blend food systems and coating matrices, while gel and solution forms capture margin pools in pharmaceutical suspensions and high-end cosmetic serums. The thickening agent and anti-caking agent applications lead end-use demand, with stabilizer roles in beverage emulsions representing the fastest-expanding functional segment.
Regulatory Frame and Forward Outlook
FDA food additive regulations, EFSA purity standards under the EU food additives framework, and REACH registration requirements collectively govern market access and product specifications for sodium aluminum silicate. These frameworks elevate compliance costs for new entrants while rewarding incumbent manufacturers with established toxicological dossiers and analytical certification capabilities. Stakeholders must monitor evolving food-contact notifications and pharmaceutical excipient monograph updates to anticipate specification shifts before they disrupt qualified supplier status.
Market Dynamics
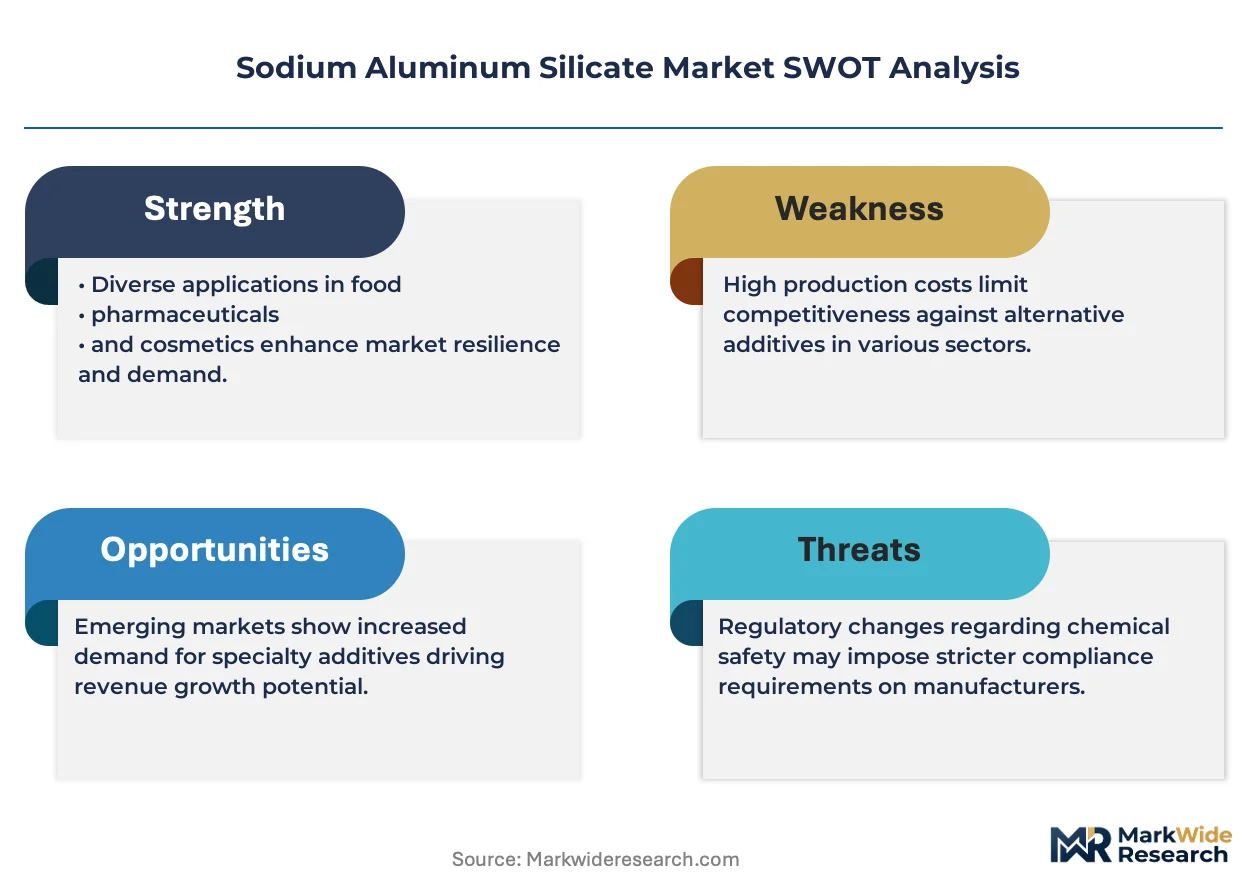
REACH registration requirements and FDA food-contact notifications are compressing supplier qualification timelines, forcing buyers to consolidate procurement around established manufacturers with validated toxicological dossiers.
Growth Catalysts
- EFSA purity standards:European food additive manufacturers are upgrading to high-purity grades to maintain qualified supplier status under tightening EU food additives frameworks.
- Precipitated silicate process innovation:Controlled pH and temperature synthesis methods are expanding surface area customization for cosmetics formulators seeking rheology precision.
- China coatings sector:Domestic architectural and industrial coatings producers are absorbing rising volumes of sodium aluminum silicate for matting and suspension applications.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive alkali silicate production concentrates cost pressure on precipitated silicate margins when natural gas prices spike.
- Natural clay substitution:Kaolin and bentonite grades compete in cost-sensitive coating applications where optical performance specifications allow mineral alternatives.
- REACH compliance burden:Registration dossier costs and analytical certification requirements create structural barriers for new entrants lacking established toxicological data packages.
Strategic Opportunities
- Pharmaceutical excipient monographs:USP and EP grade certifications open premium pricing pools for manufacturers investing in GMP production lines and endotoxin-controlled processing.
- India personal care expansion:Domestic cosmetics brands are localizing supply chains under Make in India incentives, creating import substitution demand for precipitated silicates.
- Surface modification chemistry:Hydrophobic and organophilic silane treatments enable penetration into solvent-based coating systems and high-end sunscreen formulations.
Industry Challenges
- Particle size distribution control:Tightening specifications for D50 and span values in food and pharma grades require capital-intensive milling and classification equipment upgrades.
- Cross-contamination prevention:Multi-product silicate plants face validation complexity when switching between industrial and food-contact grades under HACCP and FSSC 22000 protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Aluminum Silicate Market |
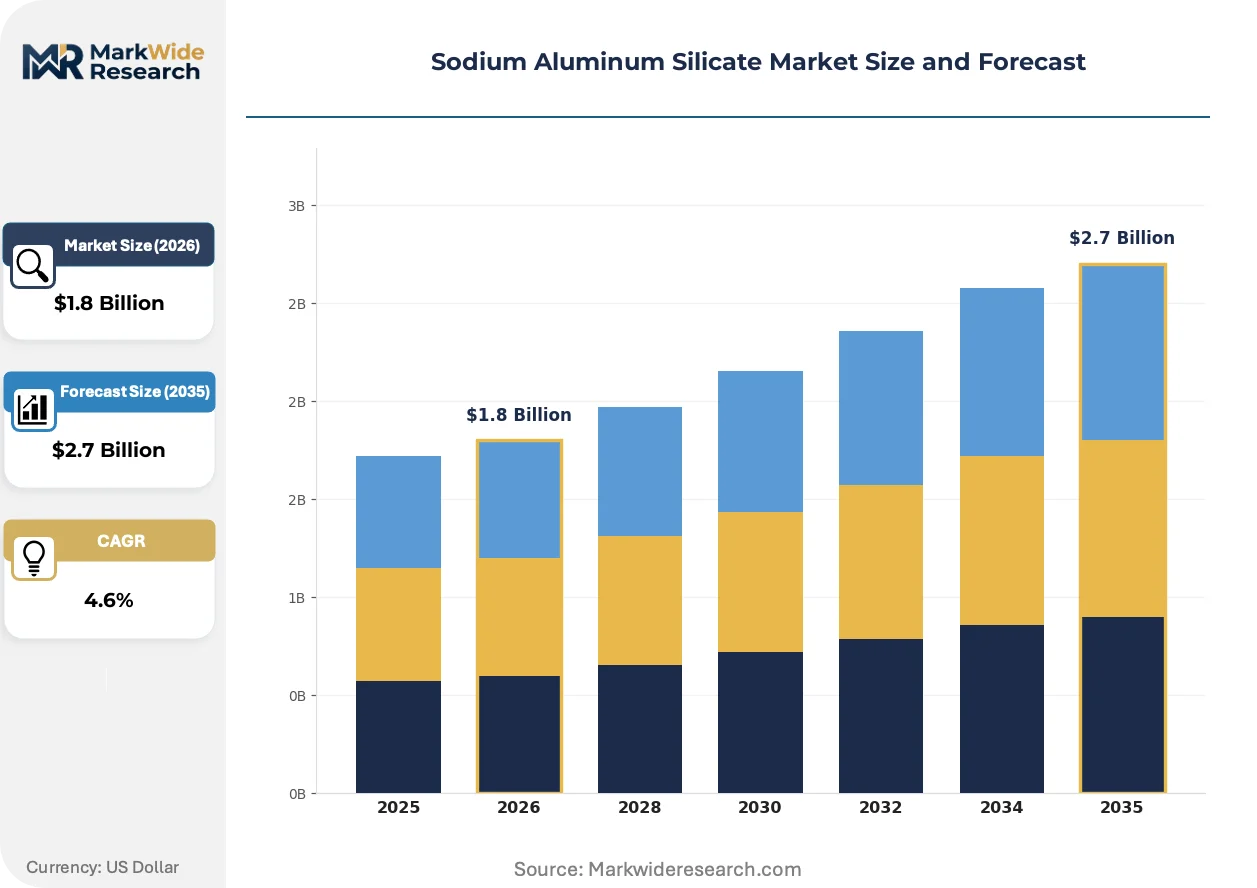
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Solution, Gel End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Paints Application: Thickening Agent, Stabilizer, Anti-Caking Agent, Filler Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Evonik Industries AG, AkzoNobel, BASF SE, PQ Corporation, Mitsui Chemicals, Dow, Clariant, DuPont, W.R. Grace & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Aluminum Silicate Market Evolving Landscape
Manufacturing technology and regulatory specification are diverging market tiers, separating commodity precipitated grades from certified excipient and food-additive categories with divergent investment requirements.
Surface-functionalized sodium aluminum silicate is bifurcating the market between standard hydrophilic powders and organophilic derivatives. Cosmetic formulators in South Korea and Japan are adopting silane-treated grades for anhydrous sunscreen and color cosmetic applications. This technology is compressing margins on unmodified silicates in premium personal care while opening formulation flexibility in solvent-based industrial coatings.
REACH Annex XV dossier updates are restricting residual heavy metal thresholds in synthetic silicates destined for food-contact and cosmetic applications. European manufacturers are retrofitting precipitation lines with enhanced washing and ion-exchange purification stages. The pharmaceutical excipient segment faces the steepest compliance cost escalation as EMA and USP monograph alignment tightens elemental impurity specifications.
Direct procurement relationships between sodium aluminum silicate producers and multinational food manufacturers are displacing distributor intermediaries in North America and Western Europe. Large bakery and seasoning compounders are consolidating qualified supplier lists to three or fewer manufacturers per geography. This concentration is most visible in the United States, where FDA Food Safety Modernization Act traceability requirements favor vertically integrated silicate producers with captive analytical laboratories.
Sodium Aluminum Silicate Market Segmentation
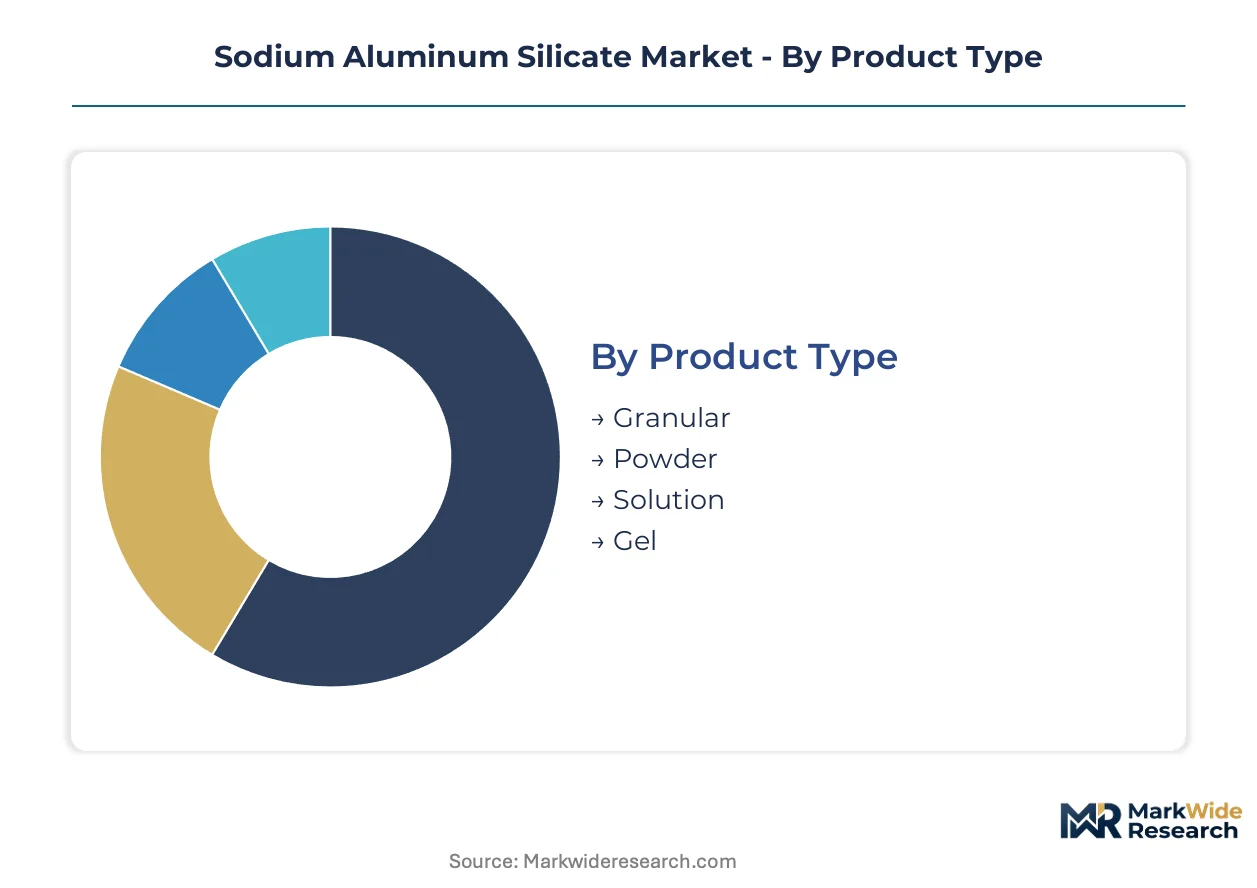
Sodium aluminum silicate specifications diverge sharply across end-use applications, with food-grade and pharmaceutical-grade certifications commanding substantial price premiums over industrial grades. Segmentation by physical form, functional application, and procurement channel determines which manufacturers capture margin pools versus competing on volume throughput.
Product Type:
Powder and granular grades concentrate the highest margin capture due to their dominance in qualified-supplier food additive contracts and pharmaceutical excipient certifications.
- Powder:Amorphous precipitated particles with controlled D50 distributions between 5-15 microns serve dry-blend food systems, seasoning compounds, and coating matrices. European food manufacturers under EFSA purity standards are consolidating procurement around established powder-grade suppliers with validated toxicological dossiers.
- Granular:Agglomerated forms with lower dusting characteristics and improved flow properties target automated dosing systems in large-scale bakery and savory applications. China coatings producers are absorbing rising granular volumes for architectural matting agents where suspension stability requirements are less stringent than food-grade specifications.
- Solution:Colloidal dispersions in aqueous media enable direct incorporation into liquid detergent and beverage emulsion formulations without dry-mixing equipment.
- Gel:Higher viscosity semisolid preparations capture pharmaceutical suspension and high-end cosmetic serum applications requiring rheology precision.
The dominant share belongs to Powder, while Gel is closing the gap fastest through pharmaceutical excipient monograph expansions.
End Use Industry:
Application-specific purity requirements separate premium-certified segments from commodity industrial absorption, with food and pharmaceutical channels rewarding manufacturers who have invested in GMP production lines and endotoxin-controlled processing.
- Food & Beverage:Anti-caking and thickening functions in bakery, dairy, and seasoning applications demand EFSA-compliant purity grades with restricted heavy metal thresholds. FDA Food Safety Modernization Act traceability requirements in the United States favor vertically integrated producers with captive analytical laboratories.
- Pharmaceuticals:USP and EP grade certifications for tablet disintegrants and suspension stabilizers open premium pricing pools. EMA and USP monograph alignment is tightening elemental impurity specifications, escalating compliance costs for new entrants.
- Cosmetics:Surface-modified grades for anhydrous sunscreen and color cosmetic applications in South Korea and Japan are displacing unmodified silicates in premium personal care.
- Paints:Matting and suspension applications in architectural and industrial coatings compete with natural clay substitutes where optical performance specifications allow mineral alternatives.
Food & Beverage holds the volume base, though Pharmaceuticals is expanding most quickly through excipient certification investments.
Application:
Functional performance specifications determine qualification complexity, with stabilizer roles in beverage emulsions and pharmaceutical suspensions requiring more stringent particle size control than filler applications.
- Anti-Caking Agent:Moisture absorption and flow improvement in powdered food ingredients, seasonings, and bakery mixes. REACH Annex XV dossier updates are restricting residual heavy metal thresholds, forcing European manufacturers to retrofit precipitation lines with enhanced washing stages.
- Thickening Agent:Rheology control in sauces, dressings, and personal care formulations. Precipitated silicate process innovation around controlled pH and temperature synthesis is expanding surface area customization for cosmetics formulators.
- Stabilizer:Emulsion maintenance in beverages and pharmaceutical suspensions represents the steepest expansion trajectory as beverage manufacturers seek clean-label alternatives to synthetic gums.
- Filler:Cost-driven volume applications in coatings and construction materials where performance specifications permit lower-purity grades.
Anti-Caking Agent maintains the largest installed base, while Stabilizer is gaining share fastest through beverage formulation shifts.
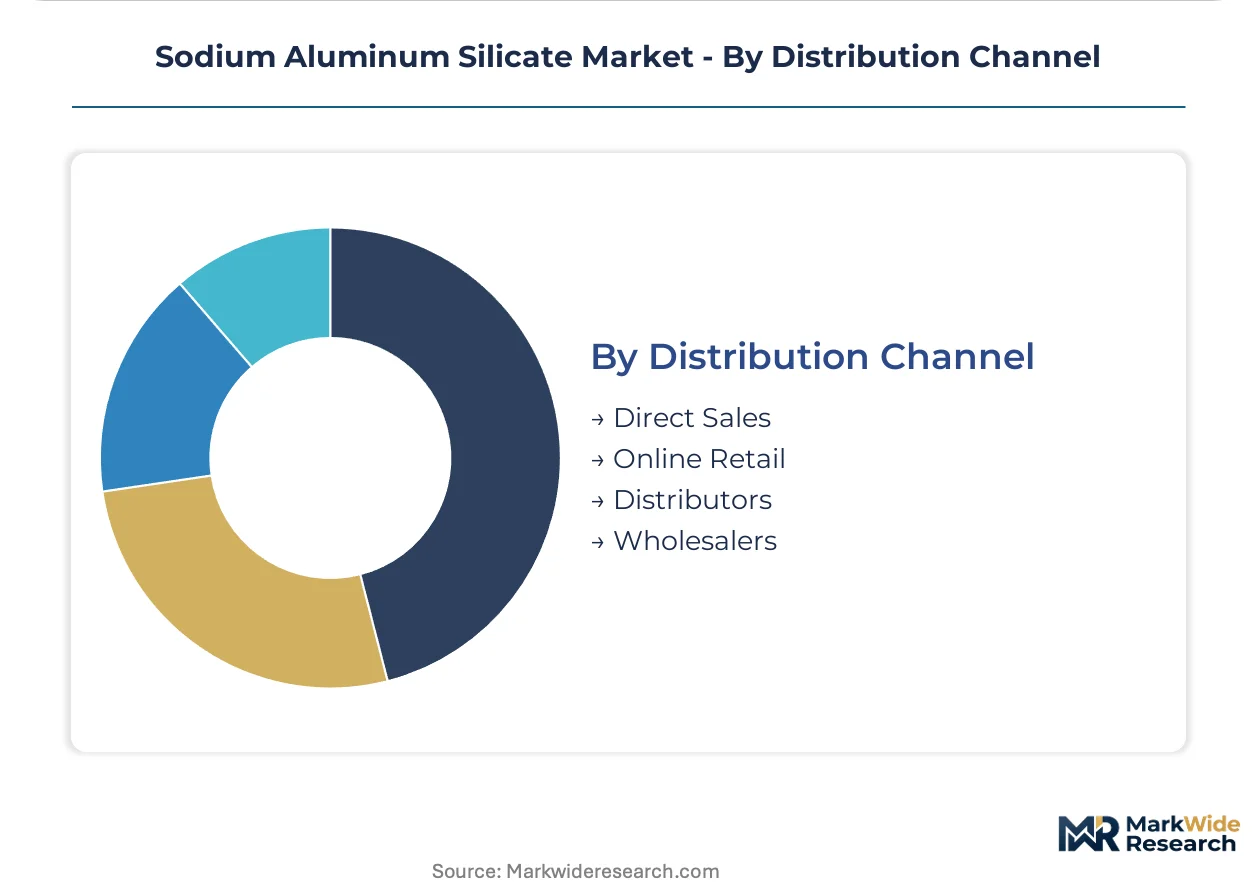
Distribution Channel:
Channel selection reflects buyer scale and qualification burden, with multinational food manufacturers bypassing intermediaries to secure direct supplier relationships under tightening regulatory traceability mandates.
- Direct Sales:Long-term contracts between sodium aluminum silicate producers and large bakery, seasoning, and coatings compounders. FDA food-contact notification requirements and REACH registration compliance compress supplier qualification timelines, consolidating procurement around established manufacturers.
- Distributors:Regional intermediaries serving mid-tier food processors and specialty chemical buyers lacking volume leverage for direct negotiation. Margin compression is accelerating as qualified supplier lists narrow.
- Wholesalers:Bulk volume channels for industrial-grade applications in coatings and construction with less stringent certification requirements.
- Online Retail:Emerging channel for small-batch cosmetics formulators and research-scale pharmaceutical developers seeking rapid sample procurement.
Direct Sales commands the dominant position, though Online Retail is climbing the fastest among emerging procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese sodium aluminum silicate producers dominate export flows into European food additive and coatings markets, while domestic absorption accelerates across Asia-Pacific personal care and pharmaceutical sectors.
China
Domestic coatings manufacturers in Shanghai and Jiangsu provinces absorb rising precipitated silicate volumes for architectural matting applications. NMPA pharmaceutical excipient standards are tightening elemental impurity thresholds, forcing precipitation line upgrades. The Yangtze River Delta cluster anchors production capacity expansion for both food-grade and industrial grades.
United States
Large bakery and seasoning compounders consolidate qualified supplier lists under FDA Food Safety Modernization Act traceability mandates. EPA industrial chemical reporting requirements intersect with state-level California Proposition 65 compliance for residual heavy metals. Gulf Coast petrochemical corridors supply captive alkali silicate feedstock to precipitated silicate manufacturers.
Germany
REACH registration dossiers and EFSA purity standards compress supplier qualification timelines for food additive procurement. ECHA Annex XV restrictions on residual heavy metals are retrofitting precipitation lines with enhanced washing stages. The North Rhine-Westphalia chemical belt concentrates surface-modified silicate production for premium cosmetics applications.
India
Domestic cosmetics brands localize supply chains under Make in India incentives, creating import substitution demand for precipitated silicates. FSSAI food additive regulations are aligning with Codex Alimentarius standards for anti-caking agent specifications. Maharashtra and Gujarat industrial corridors host expanding precipitated silicate capacity for pharmaceutical excipient certifications.
Japan
Cosmetic formulators in Osaka and Tokyo metropolitan areas adopt silane-treated grades for anhydrous sunscreen applications. METI chemical substance regulations govern synthetic silicate purity specifications under industrial safety frameworks. The Kansai region anchors specialty silicate R&D for surface-modified derivatives targeting premium personal care.
Sodium Aluminum Silicate Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capabilities, with consolidated procurement patterns favoring manufacturers possessing validated toxicological dossiers. The supplier base stratifies between vertically integrated alkali silicate producers and precipitation-focused specialists. Three archetypes dominate: captive feedstock integrators, surface-modification specialists, and pharmaceutical-grade certification holders. Capacity expansion and strategic partnerships represent the dominant competitive moves as buyers narrow qualified supplier lists.
Among German chemical conglomerates, Evonik Industries AG and BASF SE exemplify the vertically integrated archetype with captive alkali silicate production. PQ Corporation anchors the North American supplier tier. Specialty positioning is represented by Clariant, whose surface-modified grades target premium cosmetics and pharmaceutical excipient applications requiring rheology precision.
| Leading Market Players |
|---|
| Evonik Industries AG |
| AkzoNobel |
| BASF SE |
| PQ Corporation |
| Mitsui Chemicals |
| Dow |
| Clariant |
| DuPont |
| W.R. Grace & Co. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day qualified supplier qualification timelines compress buyer negotiating leverage and anchor pricing power with established manufacturers possessing validated REACH dossiers and FDA food-contact notifications. This lead-time rigidity reinforces contract-based offtake structures and penalizes spot-market procurement for food-grade and pharmaceutical-certified grades.
Pricing Analysis
Process-generation pricing gaps separate legacy precipitation lines from advanced surface-modified grades, with silane-treated derivatives commanding substantial premiums over unmodified hydrophilic powders. Three-tier pricing structure across pharmaceutical-excipient, food-additive, and industrial grades reflects certification burden and endotoxin-control investment. Pricing pressure stems from natural gas volatility feeding into captive alkali silicate production costs. Mid-tier food processors exhibit highest price sensitivity, while multinational cosmetics brands demonstrate lowest sensitivity due to formulation-lock-in effects.
Supply Chain Analysis
Strategic stockpile preferences dominate qualified food-grade procurement, with large bakery and seasoning compounders maintaining ninety-day inventory buffers against supply disruption risks. Production gravity centers on China, Germany, and the United States, with the Yangtze River Delta and North Rhine-Westphalia chemical belts anchoring capacity expansion. Sodium silicate feedstock and aluminum salt reagents constitute critical input dependencies. Single-source vulnerability concentrates in European REACH-registered supply for pharmaceutical excipient grades. Distribution runs through direct sales channels for certified grades, with regional distributors serving industrial absorption applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium aluminum silicate demand tracks coatings and personal care capital expenditure cycles, with architectural matting agent procurement recovering as construction activity rebounds across Asia-Pacific and European markets.
For Market Incumbents: Fortify qualified supplier status by retrofitting precipitation lines with enhanced ion-exchange purification to meet tightening EMA and USP elemental impurity specifications. Deepen backward integration into captive alkali silicate production to offset natural gas feedstock volatility. Natural clay substitution in cost-sensitive coatings applications represents the primary demand erosion threat requiring defensive certification investment.
For New Entrants and Emerging Players: Rapid sample fulfillment for small-batch cosmetics formulators represents a service-layer gap where established manufacturers under-serve research-scale buyers. Target Indian domestic personal care brands localizing supply chains under Make in India incentives. Pursue surface-modification chemistry partnerships with South Korean and Japanese cosmetic formulators seeking anhydrous sunscreen grades.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-optimized precipitated silicate divisions lacking pharmaceutical-grade certification infrastructure. Five-to-ten-year viability hinges on excipient monograph alignment and GMP production line scalability. Monitor NMPA pharmaceutical excipient standard updates as inflection indicators for China capacity repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkali Silicate | Captive sodium silicate production insulates margin compression from Gulf Coast natural gas volatility. |
| Pharmaceutical Excipient Certification | USP and EP grade investments unlock premium pricing pools in endotoxin-controlled tablet disintegrant applications. |
| Surface Modification Chemistry Partnership | Silane-treated grade development penetrates South Korean anhydrous sunscreen and color cosmetic formulations. |
| Direct Procurement Relationship Expansion | FDA FSMA traceability compliance favors vertically integrated producers with captive analytical laboratories. |
| India Capacity Localization | Maharashtra and Gujarat production lines capture import substitution demand under Make in India incentives. |
Research Methodology
Initial hypotheses were tested against primary input from precipitation plant managers, procurement leads at multinational food manufacturers, cosmetics formulators, coatings compounders, and pharmaceutical excipient quality directors and refined through secondary validation against customs trade data, SEC chemical company filings, ECHA registration databases, and food additive regulatory submissions. Bottom-up volume estimates triangulated with top-down market sizing across grade tiers and end-use applications.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by grade tier, end-use industry, physical form, and regional production hub. CAGRs derive from segmented growth rate synthesis with cross-validation against macroeconomic drivers. Forecast inputs incorporate coatings sector capital expenditure cycles, personal care formulation shifts, and regulatory specification evolution.
Underlying assumptions cover REACH registration stability, FDA food-contact notification continuity, and natural gas feedstock price band persistence, with deviation risk concentrated in pharmaceutical excipient monograph alignment timing and China environmental enforcement intensity. Revision becomes warranted when EMA or USP elemental impurity thresholds cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Automotive Ceramics Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Diatomite Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Porous Ceramic Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Cement Castables Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
India Kaolin Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Ceramic Setter Plate Market