
 Stoneware Market | 2026-2036
Stoneware Market Size, Share, and Industry Trends Forecast 2026-2036
Stoneware Market Analytics
Modular dinnerware sets that mix and match individual pieces rather than fixed-place settings is shifting how home chefs and hospitality buyers configure purchases. Villeroy & Boch AG leverages its German manufacturing heritage to sustain premium positioning across European and Asian markets. Heath Ceramics anchors its competitive stance through California-based artisan production that commands design-conscious residential segments. Churchill China dominates commercial foodservice supply through dedicated kiln capacity and direct wholesale channel control.
Stoneware denotes vitrified ceramic ware fired at temperatures between 1,100°C and 1,300°C, yielding dense, non-porous bodies suitable for oven, microwave, and dishwasher exposure; iron-rich clays and feldspathic glazes produce the characteristic earthy coloration and thermal shock resistance valued in both domestic and professional kitchens. Plates and baking dishes occupy the largest volume share within product type segments, reflecting entrenched replacement cycles in residential and restaurant settings. Mugs represent the fastest-growing product category, driven by specialty coffee culture expansion and gift-market velocity through online retail channels. The hospitality industry end-user segment commands the highest margin pools, as professional chefs and institutional buyers prioritize durability certification and batch consistency over unit price sensitivity.
REACH regulation through ECHA governs heavy-metal migration limits in ceramic glazes sold across European Union member states, while FDA compliance dictates lead and cadmium thresholds for stoneware distributed in the United States. ISO 6486 testing protocols for ceramic food-contact articles create de facto market access requirements for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving state-level disclosure mandates in California and emerging extended producer responsibility frameworks in the European Union that could reshape packaging and end-of-life obligations for ceramic goods.
Market Dynamics
REACH compliance through ECHA and evolving FDA food-contact standards are compressing supplier qualification timelines while simultaneously fragmenting the qualified vendor base across European and North American markets. These dual regulatory pressures are forcing heritage manufacturers to reformulate glaze chemistries and rebuild kiln protocols from raw material sourcing through finished-goods testing.
Growth Catalysts
- Specialty coffee culture expansion:Third-wave café operators in Japan and the United States are sourcing branded stoneware mugs as merchandise extensions, driving repeat purchase velocity through direct-to-consumer channels.
- REACH heavy-metal migration limits:ECHA's tightened cadmium and lead thresholds are accelerating replacement cycles in European foodservice operations as institutional buyers retire non-compliant inventory.
- Iron-rich clay deposits:Concentrated sourcing from specific Appalachian and Rhine River basin quarries is enabling heritage producers to market provenance narratives that command residential premium positioning.
Market Restraints
- Natural gas kiln dependency:European manufacturers face structural input cost volatility as continental energy markets remain exposed to supply disruption from Norwegian and Algerian pipeline sources.
- Feldspathic glaze supply concentration:Three Turkish mining cooperatives control the majority of high-grade nepheline syenite exports, creating single-source vulnerability for mid-tier producers.
- Thermal shock resistance ceiling:Current iron-rich clay formulations cannot exceed 350°C delta without micro-fracturing, limiting oven-to-freezer product claims against glass-ceramic substitutes.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging EU packaging and end-of-life mandates for ceramic goods will reward producers with established take-back infrastructure and closed-loop material recovery.
- Induction-compatible ferromagnetic stoneware:Convergence of ferrite-doped clay bodies with residential induction cooktop penetration in Germany and South Korea opens replacement demand from stainless steel cookware.
- Artisanal hospitality procurement:Independent restaurant groups in Melbourne, Copenhagen, and Mexico City are bypassing traditional wholesale channels to commission limited-batch studio production directly.
Industry Challenges
- ISO 6486 testing backlog:Certification laboratory capacity constraints in Asia-Pacific export hubs are extending market access timelines from twelve to twenty-four weeks for new glaze formulations.
- Legacy kiln operator attrition:Retirement waves among German and Japanese master kiln technicians are compressing tacit knowledge transfer windows before automated firing protocols achieve equivalent output consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stoneware Market |
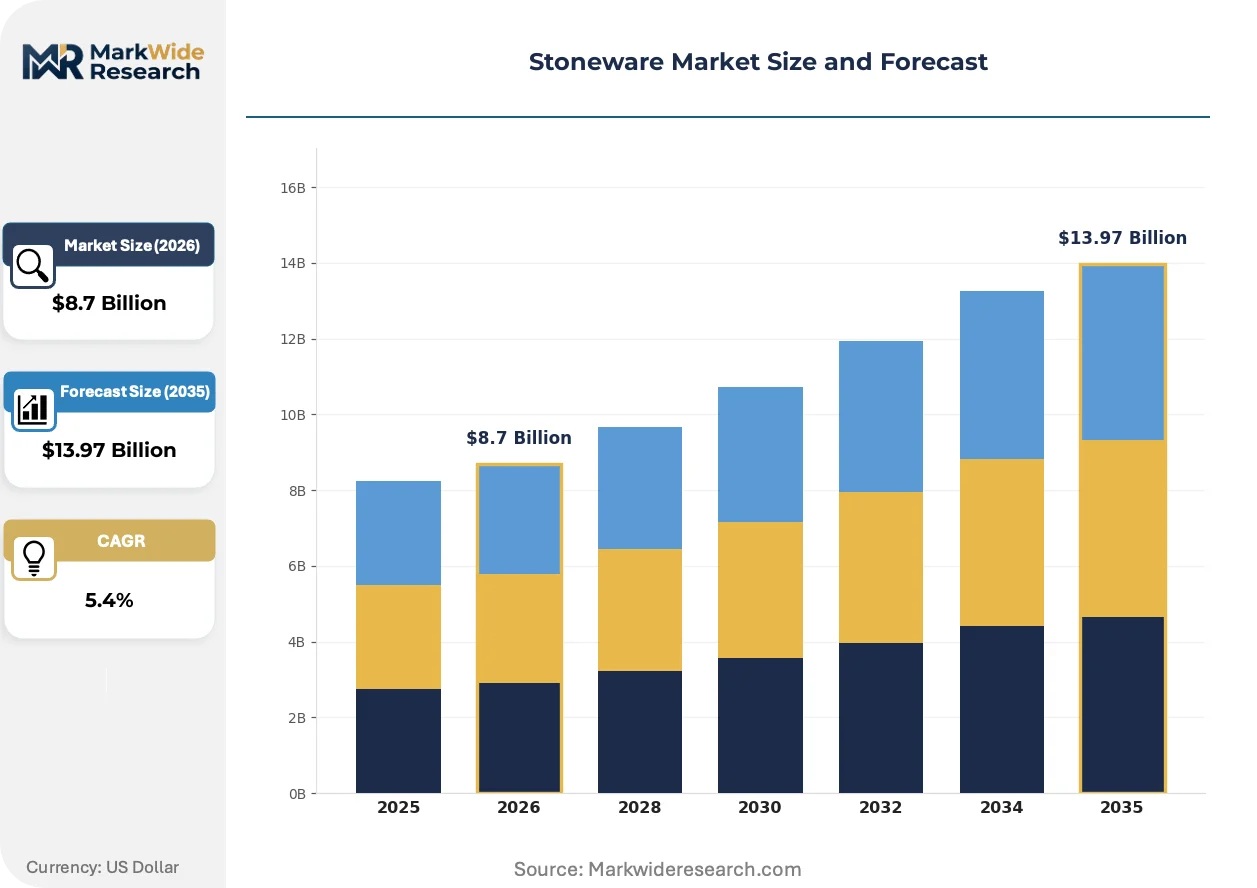
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Dishes, Plates, Mugs, Bowls Application: Residential Use, Restaurants, Catering, Foodservice End User: Home Chefs, Professional Chefs, Hospitality Industry, Retailers Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | Denby Pottery Company, Corelle Brands, Lenox Corporation, Villeroy & Boch AG, Rosenthal GmbH, The Fiesta Tableware Company, Gibson Homewares, Churchill China, Heath Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stoneware Market Evolving Landscape
Production technology and procurement patterns are fragmenting the traditional fixed-place setting model while regulatory chemistry requirements and direct-to-consumer channels reshape how value accumulates across the value chain.
Digital kiln control systems paired with variable-frequency drive burners are modularizing batch-size economics for heritage manufacturers. Small-batch producers in California and North Rhine-Westphalia are adopting these systems to offer customized glaze palettes at minimum order quantities below fifty units. This technology is modularizing the barrier between artisan studio output and mid-volume commercial supply, enabling previously craft-bound producers to serve hospitality procurement without sacrificing design differentiation.
REACH Annex XVII amendments through ECHA are mandating stricter documentation of heavy-metal content in ceramic glazes sold across European Union member states. Manufacturers must now submit migration test data through the SCIP database for articles containing candidate list substances above threshold concentrations. German and French foodservice distributors are responding by consolidating supplier relationships toward vertically integrated producers with in-house analytical laboratories, compressing the qualified vendor base by an estimated two-thirds in institutional channels.
Collector behavior among residential buyers is fragmenting toward individual piece acquisition rather than complete set purchases. Home chefs in the United States and United Kingdom are curating mismatched oven-to-table collections through Instagram-native retailers and maker-market direct sales. This pattern is most visible in urban coastal markets where design-conscious consumers prioritize provenance storytelling over brand consistency, forcing heritage manufacturers to unbundle traditional place-setting configurations into single-SKU online offerings with elevated per-unit margins.
Stoneware Market Segmentation
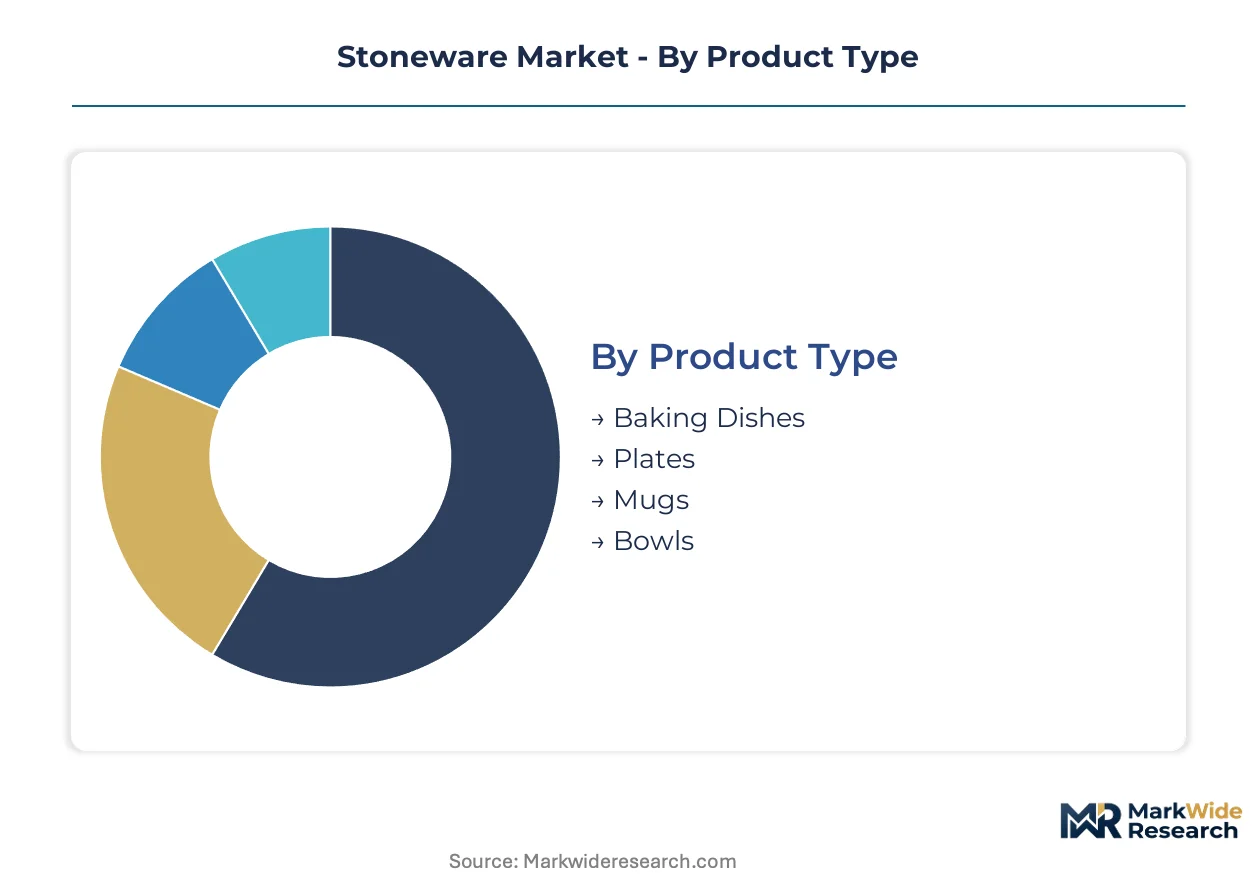
Stoneware segmentation reveals divergent margin structures across product categories and procurement channels. Volume concentration in foodservice applications contrasts with premium capture in residential direct-to-consumer sales. Understanding these splits enables targeted positioning against regulatory compliance costs and kiln capacity constraints.
Product Type:
Volume leadership resides in oven-to-table staples, while premium expansion concentrates in beverage-focused formats driven by café culture merchandise strategies.
- Plates:Standard dinner and salad plates fired at 1,200°C with feldspathic glazes constitute the baseline volume driver across institutional procurement. Demand concentrates in United States and German foodservice operations where replacement cycles align with durability certification renewals under FDA and REACH protocols.
- Mugs:Handle-bearing vessels with thermal shock resistance to 300°C delta are expanding most quickly through specialty coffee retail channels in Japan and the United States. Third-wave café operators commission branded runs as merchandise extensions, bypassing traditional wholesale markups.
- Baking Dishes:Rectangular and oval ovenware with reinforced rim construction serves residential replacement demand in North American markets.
- Bowls:Nesting soup and serving bowls with stackable profiles dominate catering procurement for event rental operators.
Mature deployment sits with Plates. Newer deployment is concentrated in Mugs.
Application:
Margin capture inverses across the volume-premium divide: high-throughput channels sacrifice per-unit profitability for kiln utilization efficiency.
- Foodservice:Institutional cafeterias, hospitals, and corporate dining operations prioritize ISO 6486-compliant batch consistency over design variation. German and French distributors are consolidating supplier relationships toward vertically integrated producers with in-house analytical laboratories.
- Restaurants:Independent dining groups in Copenhagen and Melbourne commission limited-batch studio production directly, bypassing traditional wholesale channels for provenance differentiation.
- Residential Use:Home chefs curate mismatched oven-to-table collections through Instagram-native retailers, prioritizing provenance storytelling over brand consistency.
- Catering:Event rental operators demand stackable profiles and chip-resistant rims for high-rotation deployment.
Established procurement patterns dominate Foodservice. Direct commissioning is accelerating fastest in Restaurants.
End User:
Technical specification authority varies sharply between users who control glaze chemistry requirements and those who delegate compliance verification.
- Hospitality Industry:Hotel and resort procurement teams mandate durability certification and batch consistency, absorbing premium pricing for reduced breakage rates in high-throughput service environments.
- Professional Chefs:Restaurant operators with direct supplier relationships specify custom glaze palettes and minimum order quantities below fifty units using digital kiln control systems.
- Home Chefs:Design-conscious residential buyers in urban United States and United Kingdom coastal markets acquire individual pieces rather than complete sets.
- Retailers:Department store and boutique buyers curate assortments balancing heritage brand recognition with artisan studio exclusivity.
Institutional procurement maturity centers on Hospitality Industry. Specification autonomy is expanding most quickly among Professional Chefs.
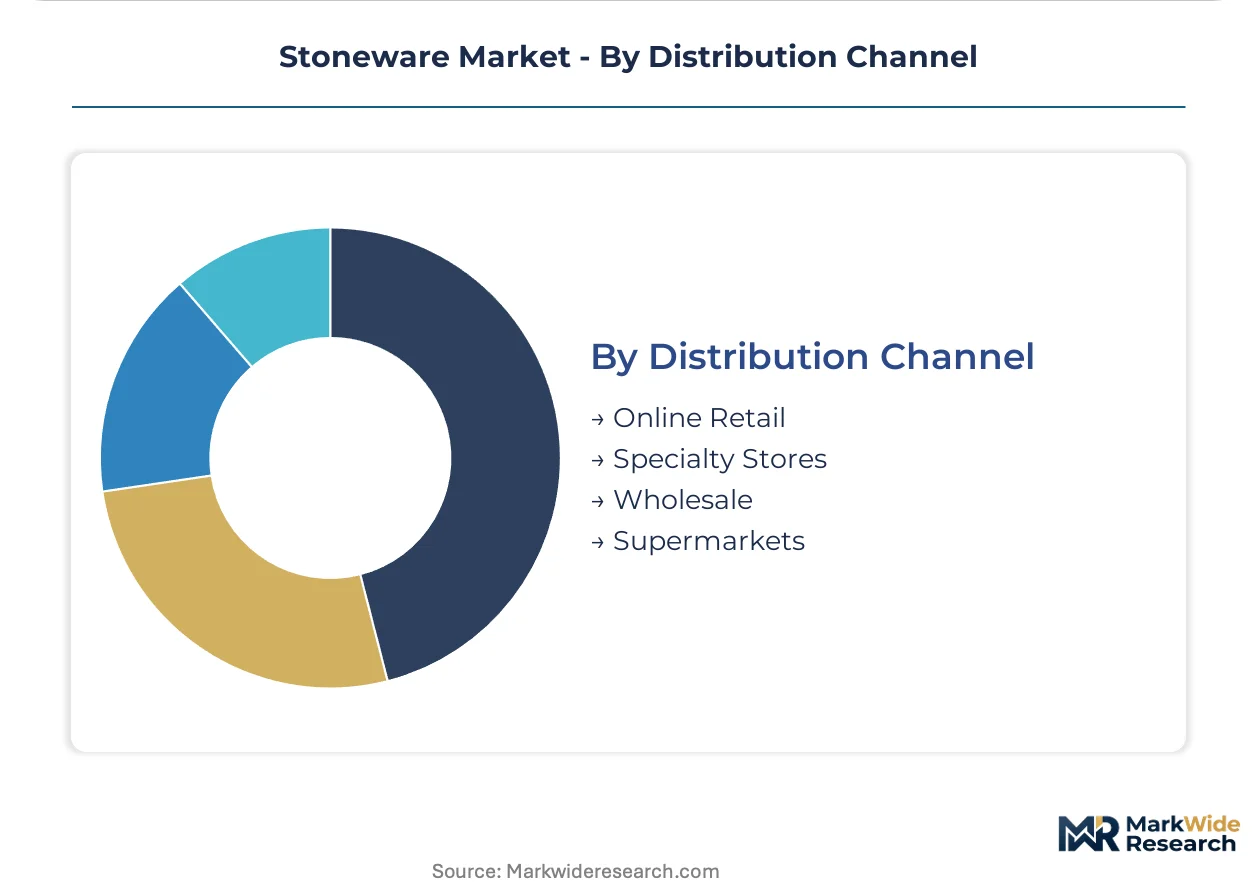
Distribution Channel:
Channel selection determines margin retention versus reach tradeoffs, with direct channels capturing value lost to wholesale markups.
- Online Retail:Direct-to-consumer platforms enable single-SKU offerings with elevated per-unit margins, serving collector behavior in United States and United Kingdom urban markets.
- Wholesale:Dedicated foodservice distributors control institutional access, compressing qualified vendor bases by two-thirds as REACH documentation requirements intensify.
- Specialty Stores:Design-focused retailers anchor premium positioning through California and North Rhine-Westphalia artisan production narratives.
- Supermarkets:Mass-market retail channels move standardized place settings at volume price points with limited glaze variation.
Concentrated infrastructure investment characterizes Wholesale. Disintermediation is proceeding fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the Rhine-Neckar Metropolitan Region concentrate German stoneware production through tax-advantaged logistics infrastructure. Heritage manufacturers cluster near these zones to minimize export documentation costs while maintaining proximity to feldspathic glaze suppliers in the Upper Rhine Valley.
United States
Specialty coffee retail expansion in Portland and Seattle drives stoneware mug demand through direct-to-consumer channels. FDA food-contact standards enforce lead and cadmium thresholds that disqualify non-compliant imports. Appalachian clay deposits in Kentucky and Tennessee supply iron-rich raw material to heritage producers marketing provenance narratives.
Germany
REACH Annex XVII amendments through ECHA mandate SCIP database submission for ceramic articles containing candidate list substances. North Rhine-Westphalia hosts vertically integrated producers with in-house analytical laboratories serving institutional foodservice procurement. Hohenberg an der Eger maintains traditional kiln technician apprenticeship programs.
Japan
Third-wave café operators in Tokyo and Osaka commission branded stoneware as merchandise extensions bypassing wholesale markups. METI industrial standards govern ceramic food-contact safety alongside voluntary JIS certification. Mashiko and Shigaraki ceramic clusters supply artisanal production to design-conscious residential segments.
United Kingdom
Independent restaurant groups in London and Manchester source limited-batch studio production directly for provenance differentiation. HSE guidance aligns with REACH heavy-metal migration limits for imported ceramic goods. Stoke-on-Trent retains concentrated kiln capacity though master technician retirement compresses knowledge transfer windows.
France
Extended producer responsibility frameworks under EU packaging mandates reshape end-of-life obligations for ceramic goods. Auvergne-Rhône-Alpes hosts foodservice distributors consolidating supplier relationships toward REACH-compliant producers. Limoges maintains decorative ceramic heritage while industrial stoneware concentrates near Lyon logistics hubs.
Stoneware Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base compresses vertically toward producers with captive laboratory capacity as REACH documentation requirements intensify. Three archetypes dominate: heritage manufacturers leveraging geographic provenance, commercial foodservice specialists controlling dedicated kiln infrastructure, and artisan studios serving direct commissioning channels. Competitive moves concentrate on M&A consolidation of analytical capabilities and strategic partnerships with specialty coffee retailers for branded merchandise programs.
Within the heritage manufacturer tier, Villeroy & Boch AG and Denby Pottery Company exemplify European producers anchoring premium positioning through manufacturing provenance narratives. Churchill China occupies a position representing commercial foodservice supply concentration through wholesale channel control. Heath Ceramics sits within the artisan studio archetype, exemplifying California-based production serving design-conscious residential segments through direct-to-consumer platforms.
| Leading Market Players |
|---|
| Denby Pottery Company |
| Corelle Brands |
| Lenox Corporation |
| Villeroy & Boch AG |
| Rosenthal GmbH |
| The Fiesta Tableware Company |
| Gibson Homewares |
| Churchill China |
| Heath Ceramics |
| Others |
Value Network & Pricing Analysis
Natural gas kiln energy costs cascade from European pipeline markets through German and French foodservice pricing tiers, compressing margins for mid-volume producers while concentrating pricing power with vertically integrated heritage manufacturers holding captive analytical laboratory capacity.
Pricing Analysis
Margin tightening in mid-tier institutional channels reflects REACH compliance documentation burdens and feldspathic glaze raw material volatility. Three-tier pricing structure across premium artisan, standard commercial, and economy mass-market levels separates producers by certification grade and kiln control sophistication. Cost-down pressure on standard commercial tiers accelerates because German and French distributors are consolidating qualified vendor bases toward REACH-compliant producers with in-house testing capacity. Foodservice procurement teams exhibit lowest price sensitivity, prioritizing ISO 6486 batch consistency over unit cost, while supermarket mass-market channels drive hardest bargain for standardized place settings.
Supply Chain Analysis
Single-source vulnerability sits with Turkish mining cooperatives controlling high-grade nepheline syenite exports for feldspathic glazes. Raw material sourcing draws from Appalachian iron-rich clay deposits in Kentucky and Tennessee, Upper Rhine Valley feldspar processors, and Anatolian nepheline syenite quarries. Supply chain risk centers on energy price volatility exposing European kiln operations to Norwegian and Algerian pipeline disruption. Distribution runs through dedicated foodservice wholesalers in Germany and France, direct-to-consumer platforms in United States and United Kingdom urban markets, and specialty design retailers curating California and North Rhine-Westphalia artisan narratives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory documentation burdens are compressing the qualified vendor base by two-thirds in European institutional channels, forcing consolidation toward producers with captive analytical capacity and vertically integrated kiln operations.
For Market Incumbents: Anchor defensive positioning through backward integration into feldspathic glaze supply and certification laboratory capacity expansion in North Rhine-Westphalia. Counter emerging artisan studio competition by deploying digital kiln control systems to offer sub-fifty-unit minimum order quantities without sacrificing batch consistency. Prioritize channel control over foodservice distributors consolidating supplier relationships under REACH Annex XVII pressure. For New Entrants and Emerging Players: Launch via direct-to-consumer platforms targeting United Kingdom and United States coastal urban collectors curating mismatched oven-to-table acquisitions. Exploit white space in induction-compatible ferromagnetic stoneware for German and South Korean residential replacement demand. Commission limited-batch production for independent restaurant groups in Copenhagen and Melbourne bypassing traditional wholesale channels. For Investors and Strategic Acquirers: REACH laboratory capacity acquisition announcements are the leading indicator that vendor base consolidation is accelerating beyond organic growth capture. Frame long-term viability around five-to-ten-year regulatory compliance moats rather than volume scale. Target acquisition archetypes: mid-tier producers with established kiln infrastructure lacking in-house testing capacity, positioned for rapid compliance retrofit.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feldspathic Glaze Supply | Captive nepheline syenite sourcing neutralizes Turkish cooperative pricing power and supply interruption risk. |
| Digital Kiln Control System Deployment | Variable-frequency drive burner technology enables sub-fifty-unit batch economics without quality variance. |
| REACH Compliance Laboratory Buildout | In-house ISO 6486 testing capacity secures institutional foodservice procurement consolidation benefits. |
| Direct-to-Consumer Platform Launch | Single-SKU online offerings capture elevated per-unit margins from collector behavior fragmentation. |
| Induction-Compatible Ferromagnetic Formulation | Ferrite-doped clay bodies unlock replacement demand from stainless steel cookware in German and South Korean markets. |
Research Methodology
Independent corroboration across primary interviews with kiln operations managers, foodservice procurement directors, ceramic glaze chemists, and specialty coffee retail buyers underwrites the qualitative findings. Secondary validation draws from ECHA SCIP database submissions, FDA food-contact guidance documents, ISO 6486 testing protocol records, and German industrial ceramics association publications. Bottom-up segment sizing triangulates against top-down market envelope estimates derived from kiln capacity utilization surveys and feldspathic glaze trade flow analysis.
Comparable-period anchoring to historical production volume and trade flow data establishes baseline calibration across the projection horizon. Segmentation dimensions modeled include product type, application channel, end-user specification authority, and distribution format. CAGRs derive from regression analysis against kiln capacity expansion announcements, regulatory implementation timelines, and specialty coffee retail footprint growth. Industry-specific forecast inputs incorporate natural gas price scenario modeling and REACH Annex XVII amendment implementation pace assumptions.
Energy market disruption, ECHA regulatory amendment acceleration, and artisan studio production capacity scaling are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions about kiln technology adoption curves and distributor consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Calcined Bauxite Market
Ceramics
United States Ceramics Tableware Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Advanced Ceramics Market
Ceramics
North America Ceramic Coatings Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Pottery Ceramics Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Ceramic Additives Market
Ceramics
Wollastonite Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Automotive Ceramics Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
China Ceramic Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
Magnesia Carbon Bricks Market