
 Injection Molding Market | 2026-2036
Injection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Molding Market Intelligence
Capital-intensity divergence between large-scale machine builders and digital manufacturing platforms is rotating competitive advantage toward asset-light, software-integrated production networks. Engel Austria GmbH leverages its Austrian engineering heritage to sustain premium positioning in precision thermoplastic systems. Milacron anchors North American aftermarket service revenue through extensive spare parts distribution. Xometry competes via cloud-based quoting algorithms that aggregate dispersed injection molding capacity across independent shops.
Injection molding is a manufacturing process wherein molten material—typically thermoplastic polymer heated to 150–400°C—is forced under high pressure into a precision-machined metal mold cavity, then cooled to form complex three-dimensional parts with tight dimensional tolerances. The technique enables mass production of identical components with cycle times often under one minute, serving industries from automotive interiors to medical instruments. Plastics dominates product type volume due to decades of resin formulation refinement and recyclability infrastructure, while bioplastic molding is gaining structural attention as brand owners face Scope 3 emissions scrutiny. Among end users, healthcare devices commands elevated margin pools because FDA-validated cleanroom production and traceability requirements create qualification barriers that limit supplier proliferation.
FDA 21 CFR Part 820 quality system regulations govern medical device injection molding in the United States, compelling molders to maintain validated processes and batch records that extend project timelines but protect incumbent qualified suppliers. REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy metal additives, redirecting formulation R&D toward compliant bio-based alternatives. ISO 13485 certification has become a de facto market access requirement for medical instrument molders across Germany, Switzerland, and the United States. Stakeholders must monitor how evolving extended producer responsibility legislation in multiple jurisdictions reshapes resin selection criteria and mold design for recyclability.
Market Dynamics
Automotive OEMs are forcing a recalibration of injection molding capacity toward lightweight structural polymers as electrification erodes traditional powertrain component demand. This demand pivot collides with tightening EU F-Gas Regulation limits on fluorinated polymer feedstocks, compressing formulation flexibility for molders serving cross-border supply chains.
Growth Catalysts
- REACH compliance mandates:European chemical safety frameworks are redirecting R&D investment toward bio-based plasticizers, creating first-mover advantage for compounders with validated alternative formulations.
- Medical instrument clusters:Precision tooling ecosystems in southern Germany are absorbing elevated capital flows as FDA-validated cleanroom capacity becomes a bottleneck for global device supply.
- Cloud-based capacity aggregation:Digital manufacturing platforms are compressing quoting cycles from weeks to hours, unlocking idle machine time across fragmented independent shop networks.
Market Restraints
- Petrochemical feedstock volatility:Crude-linked resin pricing swings of 30-40% within single quarters destabilize contract margins for fixed-price automotive supply agreements.
- Tooling supply concentration:Ultra-precision mold fabrication capacity concentrates in Osaka and Aachen, exposing medical device launch timelines to single-source geographic risk.
- Biopolymer performance gaps:Polylactic acid and starch-based alternatives exhibit inferior heat deflection temperatures, limiting deployment in under-hood automotive applications.
Strategic Opportunities
- India PLI scheme for medical devices:Production-linked incentives are attracting mold qualification investments for export-oriented diagnostic instrument manufacturing.
- Closed-loop recycling mandates:Extended producer responsibility legislation in France and Italy is creating certified recycled-content premiums for packaging molders with traceable regrind systems.
- Micro-molding convergence with MEMS:Integration of precision polymer processing with semiconductor fabrication is opening sub-millimeter component categories for implantable sensors.
Industry Challenges
- Multi-cavity tool validation timelines:FDA 21 CFR Part 820 process qualification protocols extend medical device mold approval cycles to 18-24 months, freezing capacity allocation decisions.
- Legacy ERP integration friction:Shop-floor data collection systems from the 1990s resist API connectivity with modern manufacturing execution platforms, delaying digital twin deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Molding Market |
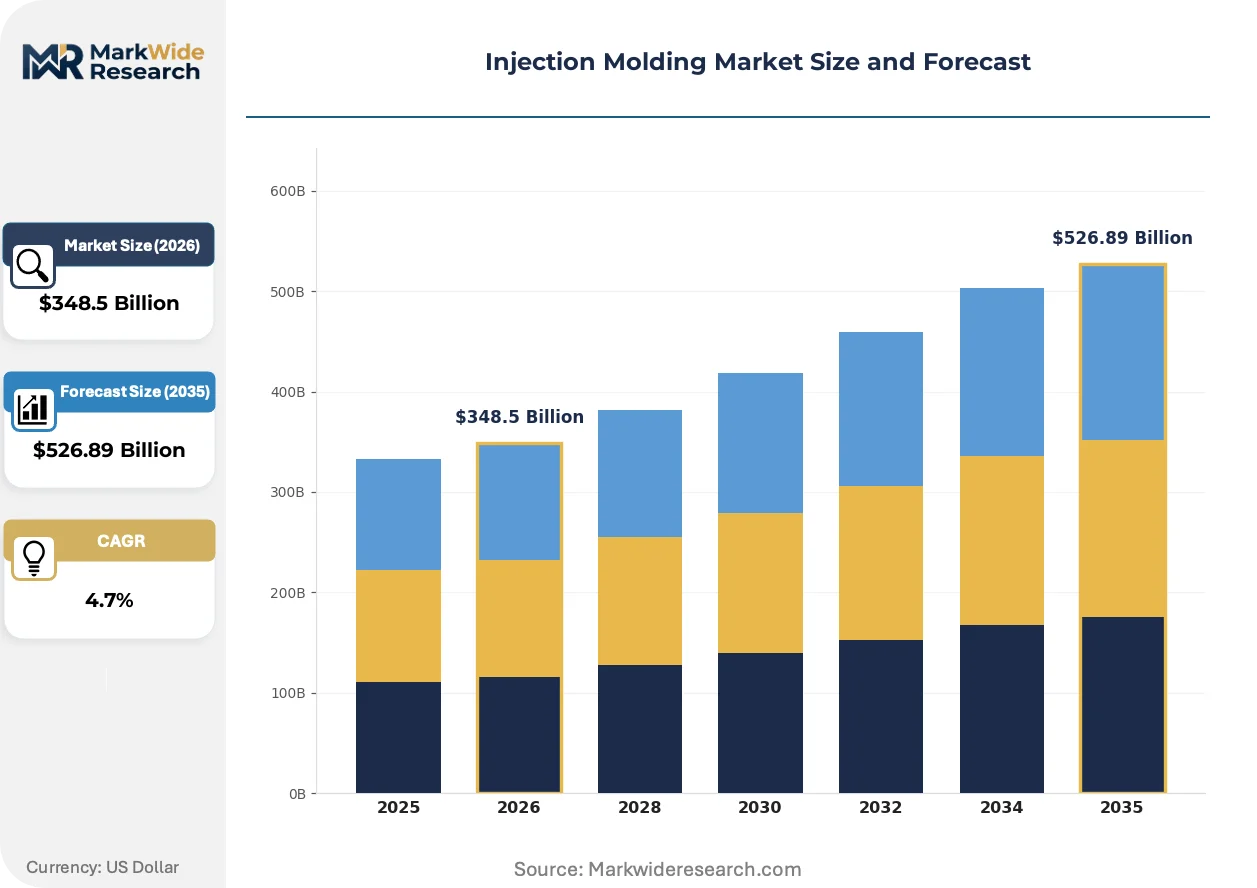
| Market Size in 2026 | $348.5 Billion |
| Market Size in 2035 | $526.89 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Metals, Ceramics, Composites End User: Automotive Parts, Consumer Goods, Packaging, Healthcare Devices Technology: 2K Molding, 3D Printing Integration, Micro Molding, Bioplastic Molding Application: Automotive Interiors, Medical Instruments, Appliances, Electronics Components |
| Companies Covered | Haitian International Holdings Limited, Chen Hsong Holdings Ltd., Engel Austria GmbH, Sumitomo Heavy Industries Limited, Hillenbrand, Inc., Berry Global, Inc., Protolabs, Xometry, Milacron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Molding Market Strategic Shifts & Innovations
Process intelligence layers are displacing pure mechanical engineering as the primary competitive differentiator in injection molding. Real-time cavity pressure monitoring and predictive maintenance algorithms are compressing defect rates while extending asset utilization curves.
Micro-cellular foaming technology is miniaturizing wall thicknesses in automotive interior panels without sacrificing stiffness. Tier-1 suppliers in Stuttgart and Detroit are adopting MuCell processes at scale for instrument cluster housings. This density reduction is compressing shipping costs and enabling consolidated part geometries that previously required multiple subcomponents.
The EU F-Gas Regulation phase-down schedule is forcing refrigerant-grade polymer formulations toward hydrofluoroolefin compatibility. Compounders serving HVAC component molders are reformulating barrier layers to maintain permeation resistance with reduced GWP blowing agents. German heat pump manufacturers are accelerating validation timelines to secure supply ahead of 2027 quota restrictions.
Automotive procurement departments are unbundling tooling ownership from piece-price contracts, treating precision molds as capital assets with residual value guarantees. Tier-2 molders in Michigan and Ontario are responding with tool lease-back structures that preserve cash flow while transferring obsolescence risk. This financialization is most advanced in electric vehicle battery enclosure programs where mold complexity justifies separate asset tracking.
Injection Molding Market Segmentation
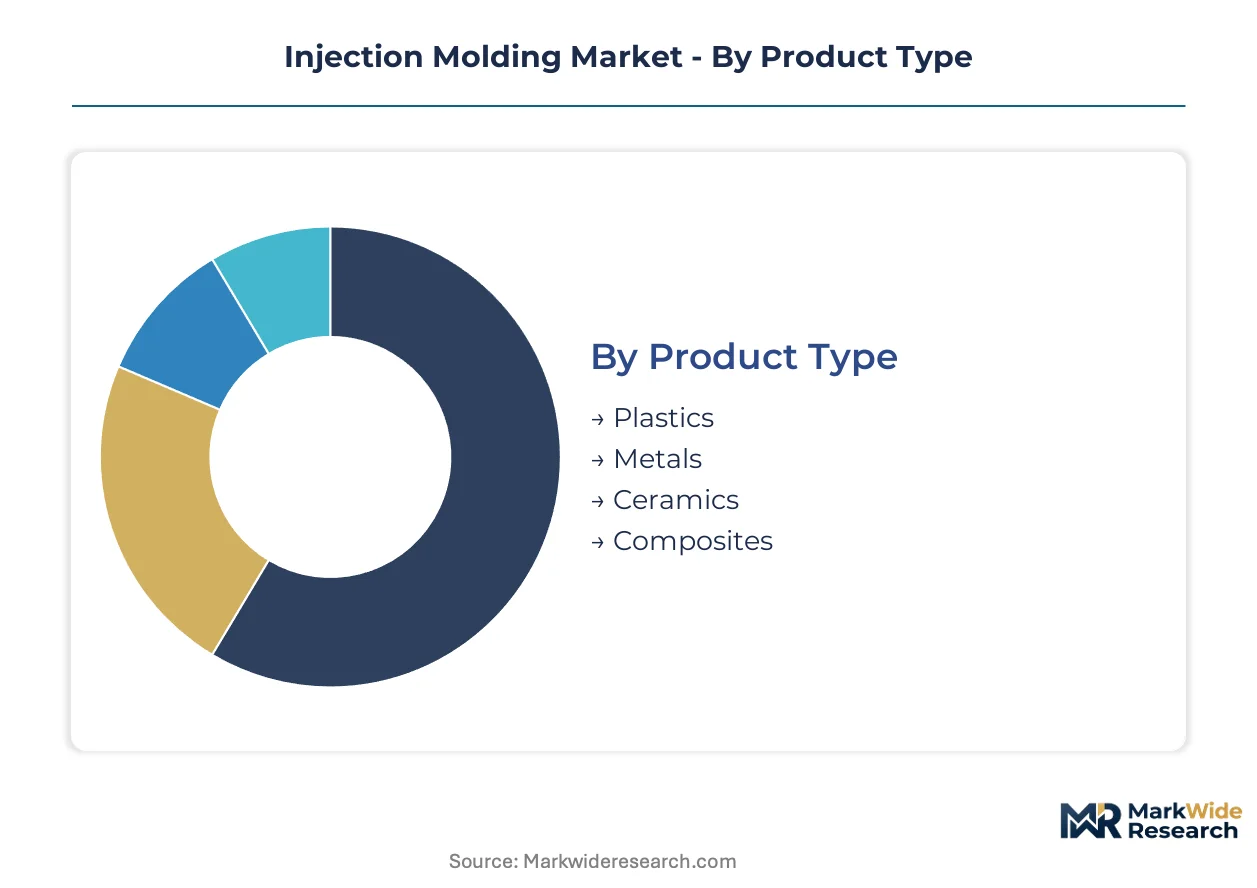
Segmentation reveals how substitution pressures from additive manufacturing and thermoforming concentrate risk in specific material and application tiers. Understanding these fracture lines helps suppliers allocate capital toward defensible process moats.
Product Type:
Thermoset composites and advanced ceramics face acute substitution threat from metal additive processes in aerospace and medical implant niches, while commodity thermoplastics defend scale through cycle-time economics that powder-bed fusion cannot match.
- Plastics:Thermoplastic polymers—polypropylene, ABS, polycarbonate—dominate throughput with sub-60-second cycle times and established recyclability infrastructure. Automotive interior panels in Stuttgart and Detroit absorb the highest volume flows as OEMs consolidate multi-part assemblies into single-shot components.
- Metals:Powder injection molding of stainless steel and titanium serves firearm components and orthodontic brackets where net-shape precision eliminates machining. MIM capacity concentrates in Pennsylvania and Osaka, with medical instrument qualification timelines extending 18-24 months under FDA 21 CFR Part 820 protocols.
- Ceramics:Alumina and zirconia feedstocks target spark plug insulators and surgical cutting tools requiring dielectric stability. Sintering shrinkage control limits part complexity relative to metal alternatives.
- Composites:Long-fiber-reinforced thermoplastics bridge stiffness and moldability for powertrain brackets in hybrid vehicles. Carbon fiber loading above 40% by weight introduces fiber attrition risks in high-shear screw designs.
Plastics anchors the volume base while composites gain share at the steepest rate as powertrain electrification redirects structural load paths.
End User:
Cost-tier stratification separates price-tolerant medical qualification premiums from automotive piece-price compression, with packaging molders caught between resin volatility and brand-owner sustainability mandates.
- Automotive Parts:Under-hood components and interior trim consume the largest resin tonnage as electrification eliminates engine blocks while adding battery enclosure complexity. Tier-1 suppliers in Ontario and Michigan are consolidating 50+ interior fasteners into integrated clip-in modules.
- Healthcare Devices:FDA-validated cleanroom molding commands 3-5x standard piece prices for diagnostic cartridges and surgical instruments. ISO 13485 certification requirements in Germany and Switzerland limit supplier proliferation to incumbent qualified molders.
- Consumer Goods:Appliance housings and power tool shells prioritize surface aesthetics and UV stability over dimensional precision. Asian contract manufacturers dominate this tier through scale economies in 500+ ton machines.
- Packaging:Thin-wall containers and closure systems face EU extended producer responsibility mandates requiring 30%+ recycled content traceability. French and Italian molders are retrofitting regrind-handling systems to capture certified-content premiums.
Automotive parts generates the highest absolute resin demand while healthcare devices delivers the steepest margin expansion trajectory.
Technology:
Application complexity determines technology selection, with multi-material and micro-scale processes defending premium positioning against commodity single-shot competition.
- 2K Molding:Dual-barrel machines inject rigid substrates followed by soft-touch TPE overmolds in single cycles, eliminating secondary assembly for power tool grips and medical device housings. Engel Austria and KraussMaffei dominate precision 2K system supply.
- Micro Molding:Sub-gram shot weights and 0.01mm tolerances serve implantable sensors and microfluidic diagnostic chips. Tooling fabrication concentrates in Aachen and Singapore, with cavity machining requiring diamond-turned surfaces.
- 3D Printing Integration:Hybrid cells combine printed conformal cooling channels with machined mold bases, compressing cycle times 15-25% in high-cavitation packaging tools. Adoption concentrates in prototype and bridge-tooling phases.
- Bioplastic Molding:Polylactic acid and starch-based compounds target food-service disposables under corporate Scope 3 emissions targets. Heat deflection temperature limitations below 60°C restrict deployment in automotive under-hood applications.
2K molding anchors current installed capacity while micro molding climbs fastest as MEMS convergence opens implantable sensor categories.
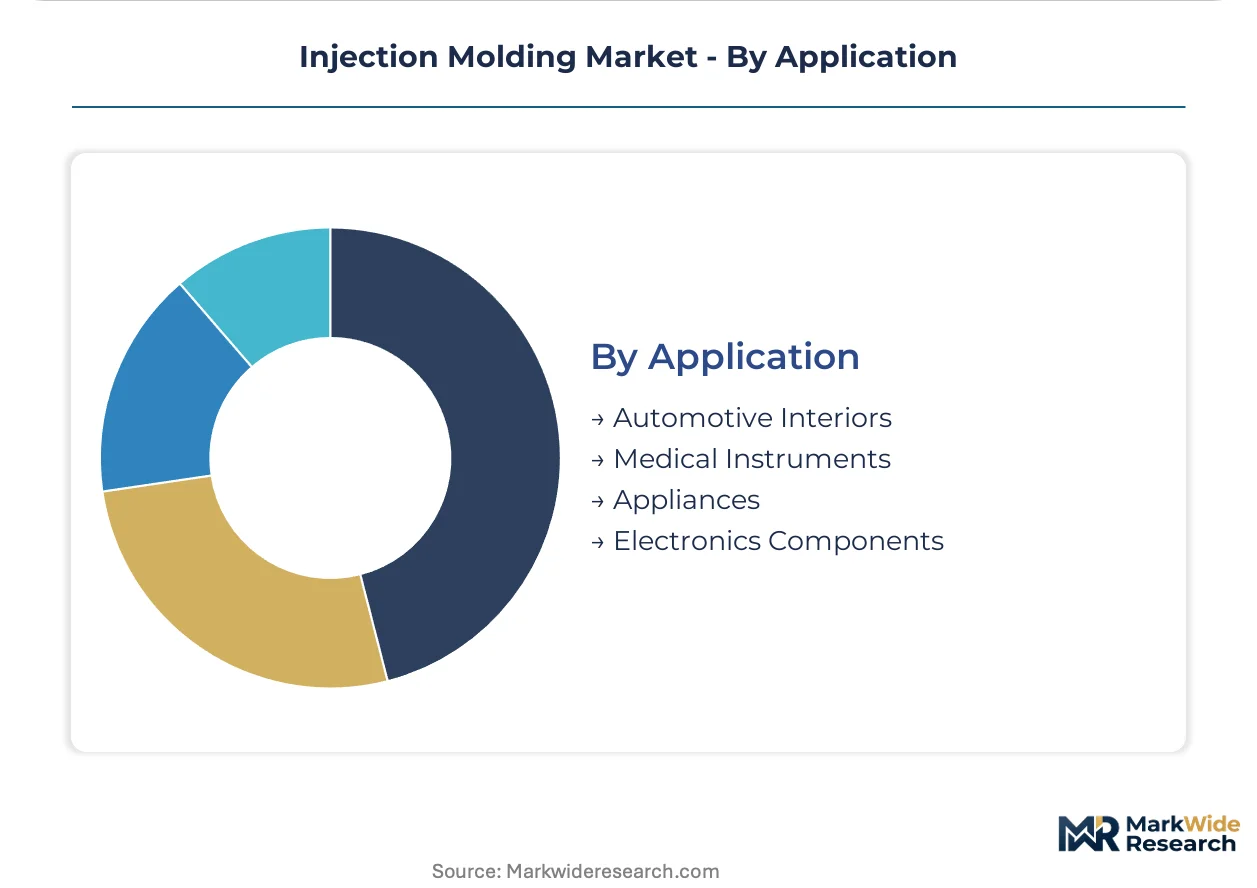
Application:
Geographic clustering of OEM engineering centers shapes application-level demand concentration, with medical and electronics applications concentrating in German-speaking precision manufacturing corridors.
- Automotive Interiors:Instrument cluster housings and door panels absorb MuCell foaming adoption for 15-20% weight reduction without stiffness loss. Stuttgart-based Tier-1s are validating foamed PP grades for 2027 model year consolidation.
- Medical Instruments:Surgical device handles and diagnostic cartridge bodies require ISO 13485 traceability and biocompatible resin grades. Cleanroom capacity in southern Germany and Switzerland operates at 90%+ utilization.
- Appliances:Refrigerator liners and washing machine drums prioritize chemical resistance and dimensional stability over tight tolerances. Chinese white-goods manufacturers drive volume through 1,000+ ton machines.
- Electronics Components:Connector housings and smartphone midframes demand flame-retardant V-0 grades with tight weld-line control. Precision tooling clusters in Shenzhen and Seoul serve consumer electronics launch cycles.
Automotive interiors commands the largest tooling investment flows while medical instruments expands most quickly on qualification barriers and aging demographic demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany absorb resin price premiums without volume elasticity, while Chinese packaging molders operate on razor-thin spreads that amplify petrochemical volatility. Healthcare device buyers in Switzerland and the United States pay qualification premiums that insulate suppliers from commodity cycles.
United States
FDA 21 CFR Part 820 protocols extend medical mold qualification timelines to 18-24 months, freezing capacity allocation for diagnostic cartridge suppliers. Michigan and Ontario-based Tier-1s consolidate interior fasteners into integrated clip-in modules for electric vehicle programs. Precision tooling clusters in Detroit serve battery enclosure mold complexity that justifies separate asset tracking.
Germany
EU F-Gas Regulation phase-down schedules force refrigerant-grade polymer formulations toward hydrofluoroolefin compatibility by 2027. REACH compliance redirects R&D investment toward bio-based plasticizers, creating first-mover advantage for compounders with validated alternatives. Stuttgart-based precision tooling ecosystems absorb elevated capital flows as FDA-validated cleanroom capacity bottlenecks global device supply.
China
White-goods manufacturers drive volume through 1,000+ ton machines for refrigerator liners and washing machine drums. MIIT industrial upgrading programs accelerate adoption of real-time cavity pressure monitoring systems. Shenzhen and Seoul precision tooling clusters serve consumer electronics connector housings with flame-retardant V-0 grades and tight weld-line control.
Japan
METI carbon neutrality roadmaps pressure molders to retrofit energy-efficient servo-hydraulic systems. Osaka concentrates ultra-precision mold fabrication capacity for medical device launch timelines. Nagoya-based automotive suppliers adopt MuCell foaming processes for instrument cluster housings to achieve 15-20% weight reduction without stiffness loss.
India
PLI scheme production-linked incentives attract mold qualification investments for export-oriented diagnostic instrument manufacturing. CDSCO medical device regulations tighten traceability requirements for polymer feedstocks. Maharashtra and Gujarat contract manufacturers scale 500+ ton machines for appliance housings serving domestic and Middle Eastern markets.
Injection Molding Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with asset-light digital platforms disrupting traditional quoting mechanics. Engel Austria and Sumitomo Heavy Industries anchor the precision thermoplastics segment through Austrian engineering heritage and Japanese industrial conglomerate scale. Three archetypes dominate: legacy machine builders with extensive spare parts networks, cloud-based capacity aggregators, and mid-tier molders pursuing tool lease-back structures. Consolidation runs through aftermarket service expansion and digital manufacturing platform partnerships.
Among Austrian and German precision specialists, Engel Austria GmbH exemplifies premium positioning in thermoplastic systems through its engineering heritage. Haitian International Holdings Limited and Chen Hsong Holdings Ltd. represent the scale-driven Chinese fabricator archetype, occupying positions in high-throughput machine supply for commodity applications. Xometry sits within the digital disruptor tier, aggregating dispersed capacity across independent shop networks through cloud-based quoting algorithms.
| Leading Market Players |
|---|
| Haitian International Holdings Limited |
| Chen Hsong Holdings Ltd. |
| Engel Austria GmbH |
| Sumitomo Heavy Industries Limited |
| Hillenbrand, Inc. |
| Berry Global, Inc. |
| Protolabs |
| Xometry |
| Milacron |
| Others |
Cost & Logistics Intelligence
Machine utilization rates above 85% in precision thermoplastic systems create scale advantages that compress per-unit fixed costs while elevating price floors for mid-tier competitors. This capacity concentration in German and Austrian engineering clusters allows incumbent molders to capture premium positioning through validated process documentation, while fragmented independent shops in North America compete on spot pricing for commodity automotive contracts.
Pricing Analysis
Aftermarket spare parts and service contracts generate lifetime value multiples exceeding original equipment sales for machine builders like Milacron. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and cleanroom validation depth. Cost compression in automotive piece-price contracts is intensifying because electrification programs demand mold complexity without proportional volume guarantees. Healthcare device buyers in Switzerland and Germany exhibit the lowest price sensitivity due to FDA-validated qualification barriers, while Asian packaging molders face acute margin pressure from resin volatility.
Supply Chain Analysis
Strategic stockpiling of precision mold bases and specialty steel feedstocks dominates over just-in-time preferences given 16-20 week fabrication lead times. Ultra-precision tooling capacity concentrates in Germany, Japan, and Switzerland, drawing from Swedish tool steel and Japanese hot-runner component supplies. Single-source geographic vulnerability in Aachen and Osaka exposes medical device launch timelines to disruption. Distribution runs through OEM-direct channels for large machine sales and independent distributor networks for spare parts fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory tightening across EU F-Gas and REACH frameworks is accelerating material formulation disruption, creating first-mover advantage windows for compounders with validated bio-based alternatives.
For Market Incumbents: Shield medical device margin pools by deepening ISO 13485-certified cleanroom capacity in southern Germany and Switzerland before qualification bottlenecks harden. Acquire distressed automotive tooling assets in Michigan and Ontario to capture electric vehicle battery enclosure programs with tool lease-back structures that transfer obsolescence risk. For New Entrants and Emerging Players: FDA 21 CFR Part 820 fast-track pathways offer entry into diagnostic cartridge molding where incumbent capacity is frozen in 18-24 month validation cycles. Target India's PLI scheme for medical devices with export-oriented diagnostic instrument qualifications. Lead with cloud-based capacity aggregation platforms that compress quoting cycles from weeks to hours for prototype and bridge-tooling demand. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision micro-molding specialists with MEMS convergence capabilities over commodity thermoplastic scale players. Five-to-ten year viability hinges on process intelligence layer integration rather than pure mechanical engineering heritage. Watch for predictive maintenance algorithm deployment rates as the inflection signal separating digital-advanced from legacy-anchored molders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Compounding | REACH-compliant bio-based plasticizer formulations secure first-mover positioning in EU medical device supply chains. |
| Cleanroom Capacity Expansion | FDA-validated production lines in Stuttgart absorb elevated capital flows as global diagnostic cartridge demand outstrips qualified supply. |
| Predictive Maintenance Platform Deployment | Real-time cavity pressure monitoring algorithms compress defect rates while extending asset utilization curves for tier-1 automotive contracts. |
| Tool Lease-Back Financialization | Separating mold ownership from piece-price contracts preserves cash flow for tier-2 molders serving electric vehicle battery enclosure programs. |
| Cloud-Based Capacity Aggregation Partnership | Digital manufacturing platforms unlock idle machine time across fragmented independent shop networks with sub-hour quoting cycles. |
Research Approach
A spread of perspectives from injection molding plant managers, OEM procurement leads at automotive tier-1 suppliers, medical device regulatory affairs directors, and aftermarket service heads converged on the working assumptions. Primary interview insights combined with secondary validation from SEC 10-K filings, EU F-Gas Regulation implementation documents, FDA 510(k) submission databases, and customs trade data for polymer feedstock flows. Bottom-up machine installation counts and top-down resin consumption estimates underwent triangulation to anchor volume assumptions.
Segmentation dimensions modeled span product type, end-user industry, technology tier, and application complexity across the projection horizon. CAGRs derive from fitted growth curves against historical capacity utilization patterns and announced expansion pipelines. Industry-specific forecast inputs include electrification-driven automotive lightweighting targets and extended producer responsibility legislation timelines in France and Italy.
Decision-makers should treat outputs as directional under assumptions of stable EU regulatory implementation and no acute petrochemical supply disruption; material deviation would warrant model refresh. Revision becomes warranted when biopolymer heat deflection temperature performance crosses automotive under-hood application thresholds or when cleanroom capacity utilization in German-speaking clusters falls below 80%.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Modified Wood Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Metal Molds Market