
 Ceramic Frit Market | 2026-2036
Ceramic Frit Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Frit Market Outlook
Aftermarket technical service revenue is reconfiguring how frit suppliers capture lifetime value from tile producers. Ferro Corporation leverages its global color-matching laboratories to sustain premium relationships with large-format tile manufacturers. Colorobbia anchors Southern European supply through vertically controlled raw-material sourcing in Italy and Spain. Esmalglass-Itaca competes on digital ink compatibility, extending its frit formulations into inkjet decoration systems.
Ceramic frit denotes a prefused glassy material, typically composed of silica, alumina, fluxing oxides, and colorants, that is milled into a fine powder and applied to ceramic bodies before firing to create durable, decorative, or functional surfaces. The material melts at 900–1200°C to form an impermeable, chemically resistant coating that protects substrates from abrasion, corrosion, and staining in architectural and sanitary applications. Porcelain-grade frits command the deepest margin pools due to stringent whiteness and thermal-expansion specifications required by thin large-format tiles. Glazes for sanitaryware represent the fastest-growing application segment as water-efficiency regulations and design premiumization drive replacement cycles in commercial and residential bathrooms.
REACH registration and the EU Green Deal are forcing European frit producers to reformulate lead-free and cadmium-free color systems, raising R&D barriers for smaller compounders. China's MEE enforces dual carbon goals that tighten energy-intensity limits on frit smelting operations, pressuring manufacturers to adopt electric melting or waste-heat recovery. India's BIS certification for ceramic tiles indirectly shapes frit quality benchmarks by mandating surface abrasion and chemical resistance thresholds. Stakeholders must monitor how divergent regional compliance timelines reshape sourcing strategies and whether backward integration into zircon and feldspar mining becomes a decisive cost-control lever.
Market Dynamics
REACH compliance and China's dual carbon goals are forcing simultaneous reformulation of heavy-metal color systems and energy-intensive smelting processes, compressing margins for compounders lacking captive raw-material access or electric-melting capabilities.
Growth Catalysts
- India's housing infrastructure push:Government schemes and commercial construction are accelerating ceramic tile consumption, directly expanding frit demand for durable surface finishes.
- Sanitaryware water-efficiency mandates:Regulatory pressure on flush volumes and design premiumization in commercial bathrooms are shortening replacement cycles for glazed fixtures.
- Digital inkjet decoration convergence:Frit formulations compatible with inkjet systems are enabling single-fire production and complex pattern replication at reduced kiln throughput.
Market Restraints
- Zircon supply concentration:Sporadic mining disruptions in key producing regions create input cost volatility for opacifier-dependent frit grades.
- Lead-free color system R&D barriers:REACH and evolving GB standards are raising technical thresholds that smaller compounders cannot finance.
- Thin large-format tile thermal-expansion tolerances:Porcelain-grade specifications reject frit batches failing stringent whiteness and expansion coefficients.
Strategic Opportunities
- Aftermarket technical service unbundling:Global color-matching laboratories and formulation support are creating recurring revenue streams detached from commodity frit sales.
- Waste-heat recovery technology adoption:MEE enforcement of energy-intensity limits rewards early movers retrofitting smelting operations with thermal capture systems.
- Large-format tile premiumization:Architectural specification of thin porcelain slabs for facade cladding is expanding addressable frit volume per square meter of installed surface.
Industry Challenges
- Reformulation timeline compression:Divergent regional compliance deadlines for cadmium-free and lead-free systems force parallel R&D tracks without harmonized test protocols.
- Raw-material qualification bottlenecks:BIS certification for Indian ceramic tiles mandates surface abrasion and chemical resistance thresholds that require extended frit-batch validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Frit Market |
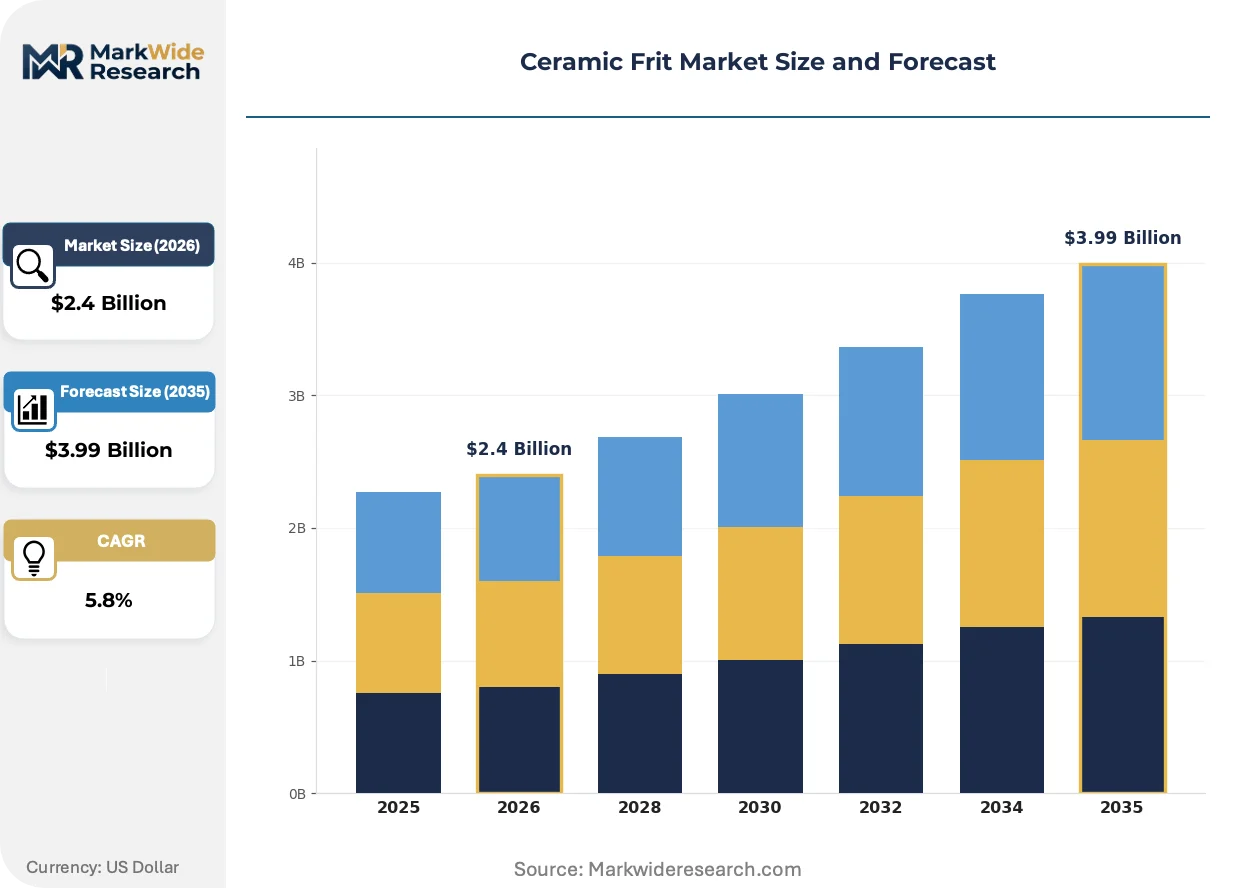
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Stoneware, Earthenware, Glazes Application: Tiles, Tableware, Sanitaryware, Decorative Items End User: Building Materials, Consumer Goods, Artisans, Manufacturers Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Ferro Corporation, Colorobbia, Esmalglass-Itaca, Torrecid Group, QuimiCer, Fusion Ceramics, TOMATEC, Johnson Matthey, T&H GLAZE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Frit Market Strategic Shifts
Digital decoration systems and environmental compliance frameworks are simultaneously elevating performance specifications and reconfiguring how frit suppliers capture value beyond commodity powder sales.
Low-temperature frit formulations are hybridizing with inkjet deposition systems to enable single-fire production of large-format tiles. Architectural specification teams in Italy and Spain are specifying these hybrid systems for facade projects requiring complex gradient patterns. This convergence is compressing traditional two-fire glazing cycles and displacing conventional screen-printing capacity in Southern European manufacturing clusters.
REACH registration deadlines and the EU Green Deal are accelerating lead-free and cadmium-free color system mandates across decorative glaze applications. European compounders are reformulating chrome-tin pinks and zircon vanadium blues to meet ECHA thresholds. Sanitaryware producers serving German and French markets are qualifying alternative opacifier packages ahead of anticipated regulatory tightening.
Tile manufacturers are unbundling technical service contracts from frit supply agreements to secure dedicated color-matching and kiln optimization support. Large-format producers in India and Italy are purchasing standalone formulation consulting rather than bundled material-plus-service packages. This disintermediation is visible most acutely in premium porcelain slab segments where surface defect tolerance approaches zero.
Ceramic Frit Market Segmentation
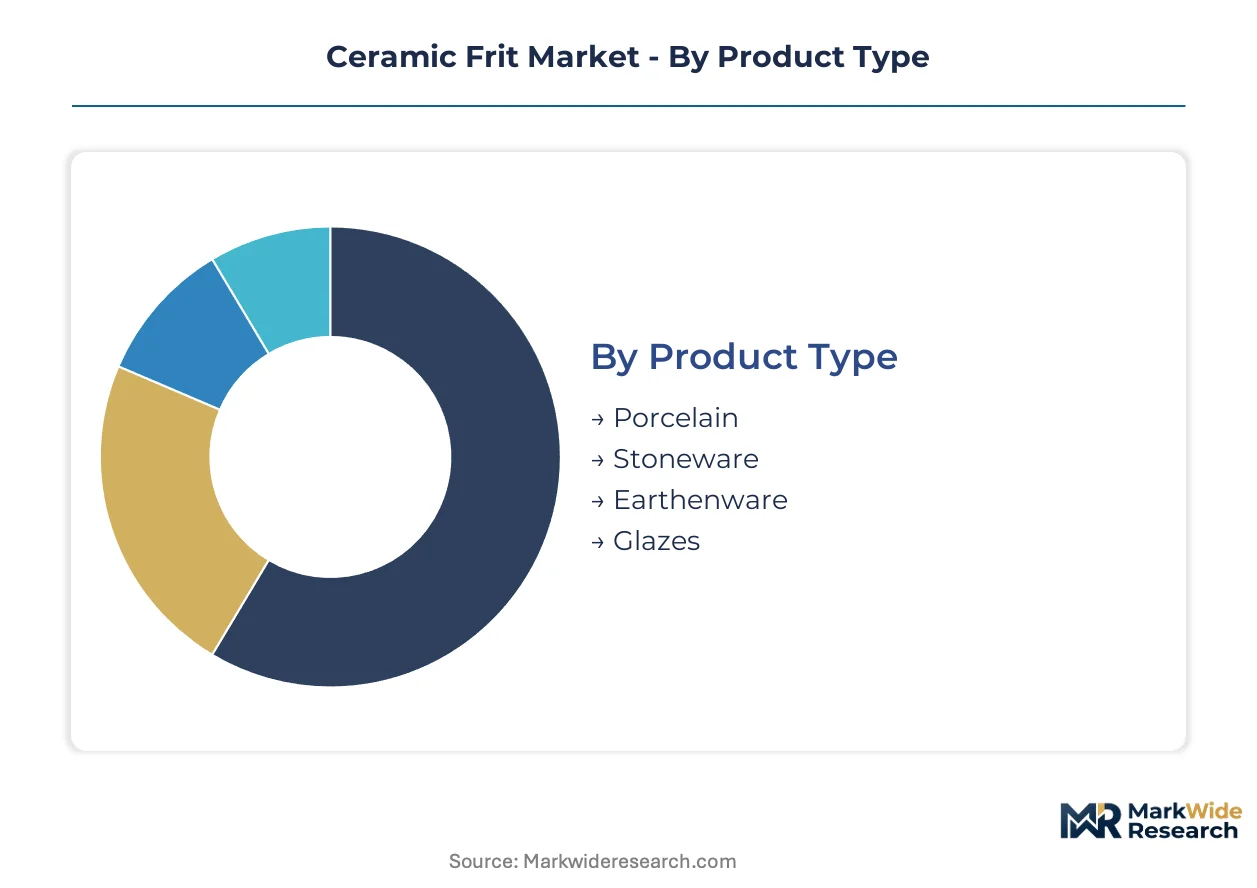
Ceramic frit segmentation reveals divergent technical service requirements across substrate types and end-use specifications. Architectural tile producers demand intensive color-matching support, while sanitaryware manufacturers prioritize glaze durability validation. Understanding these segment-specific service intensities shapes how suppliers configure their technical resource deployment and pricing architectures.
Product Type:
After-sales service intensity varies sharply across frit grades, with porcelain commanding dedicated laboratory support and earthenware operating through standardized distribution.
- Porcelain:Ultra-low thermal expansion coefficients and whiteness specifications above 90% L-value define this grade. Thin large-format tile manufacturers in Italy and Spain require batch-specific expansion matching and defect-free surface guarantees, driving premium service bundling.
- Glazes:Functional coatings for sanitaryware and tableware incorporate fluxing oxides tuned to single-fire or double-fire cycles. Water-efficiency mandates in Germany and France are accelerating replacement demand for glazed fixtures with certified chemical resistance.
- Stoneware:Mid-range thermal expansion tolerances serve dinnerware and heavy-traffic flooring applications through distributor-managed technical support.
- Earthenware:Lower firing temperatures and broader specification bands enable commodity pricing with minimal aftermarket service attachment.
By volume, earthenware leads. By growth pace, porcelain is ahead.
Application:
Cost tier differentiation separates specification-grade architectural applications from volume-driven consumer segments.
- Tiles:Architectural facade and flooring specifications demand frits with abrasion resistance above 1500 revolutions and stain resistance to ISO 10545-14. India's housing infrastructure schemes are expanding addressable square footage for durable glazed surfaces.
- Sanitaryware:Glazed ceramic fixtures for commercial bathrooms require flush-volume compliance and premium design aesthetics. Regulatory pressure on water consumption in European markets is compressing replacement cycles for certified low-flow fixtures.
- Tableware:Food-contact safety certifications and decorative color stability define this mid-tier segment with moderate technical service requirements.
- Decorative Items:Artisan and giftware applications tolerate wider specification bands, operating through retail and online channels with limited formulation support.
By installed base, tiles dominate. By margin expansion, sanitaryware is climbing the fastest.
End User:
Customer type determines procurement sophistication, with building materials distributors negotiating long-term formulation contracts against spot-market artisan purchases.
- Building Materials:Large-format tile and facade system integrators procure frit through annual supply agreements with embedded technical service. India's commercial construction acceleration is concentrating procurement volume with pan-national distributors capable of BIS certification documentation.
- Manufacturers:Sanitaryware and tableware OEMs operate integrated glaze shops requiring just-in-time frit delivery and kiln optimization consulting.
- Consumer Goods:Branded dinnerware producers balance design differentiation with food-contact safety compliance through mid-tier service relationships.
- Artisans:Studio potters and small-batch producers purchase through retail channels with minimal technical support beyond standard specification sheets.
By contract value, building materials leads. By relationship stickiness, manufacturers are gaining share fastest.
Distribution Channel:
Supply concentration in raw-material sourcing regions shapes channel economics, with direct sales capturing premium formulation accounts and wholesale managing commodity volume.
- Direct Sales:Global tile manufacturers maintain dedicated frit supply relationships with embedded color-matching laboratories and kiln troubleshooting. REACH-compliant European producers leverage direct channels to manage reformulation timelines for lead-free color systems.
- Wholesale:Regional distributors aggregate demand from mid-tier sanitaryware and tableware producers, managing inventory buffers against zircon supply volatility.
- Retail:Artisan and small-batch producers purchase through specialty ceramic supply stores with limited technical consultation.
- Online:Standard-grade frits for hobbyist and educational markets operate through e-commerce platforms with specification documentation only.
By revenue concentration, direct sales leads. By channel expansion, wholesale shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the highest demand elasticity as government housing schemes drive volume procurement, while Italy and Spain maintain price-inelastic premium segments through specification-grade architectural relationships.
India
Commercial construction acceleration and Pradhan Mantri Awas Yojana housing schemes are expanding ceramic tile consumption across tier-2 and tier-3 cities. BIS certification mandates for surface abrasion and chemical resistance are tightening frit quality benchmarks for imported and domestic supply. Morbi in Gujarat anchors national production, with cluster manufacturers qualifying frit batches against accelerated certification timelines.
China
Large-format tile producers in Foshan and Zibo are retrofitting glaze shops for digital inkjet compatibility. MEE enforcement of dual carbon goals is pressuring smelters toward electric melting or waste-heat recovery systems. The Pearl River Delta concentration is fragmenting as energy-intensity limits push capacity toward western provinces with lower grid-carbon intensity.
Italy
Sassuolo ceramic district manufacturers specify ultra-low thermal expansion frits for thin porcelain slab facade systems. REACH registration deadlines are accelerating lead-free color system reformulation among compounders serving German and French export markets. Color-matching laboratory density in Emilia-Romagna sustains premium technical service relationships with global tile brands.
Spain
Castellón ceramic cluster producers are qualifying low-temperature frit formulations for single-fire architectural tile production. EU Green Deal thresholds on cadmium-free decorative glazes are compressing reformulation timelines for chrome-tin pink alternatives. Mediterranean facade specification teams are sourcing complex gradient patterns from hybrid inkjet-frit systems.
Germany
Sanitaryware OEMs serving commercial bathroom retrofits demand certified low-flow fixture glazes with verified chemical resistance. ECHA thresholds on heavy-metal content are eliminating residual lead-bearing color systems from supply chains serving French and Benelux markets. North Rhine-Westphalia industrial glaze shops are integrating just-in-time frit delivery with kiln optimization consulting contracts.
Ceramic Frit Market Competitive Environment
Capability concentration sits with specialized compounders commanding premium technical service relationships; scale advantage sits with diversified materials conglomerates feeding commodity-grade volume. The market structures around three tiers: global color-matching laboratories serving specification-grade architectural accounts, regional smelters optimizing for distributor-managed mid-tier supply, and captive glaze shops integrated with large-format tile OEMs. Dominant competitive moves include unbundling aftermarket technical service from material sales and backward integration into zircon and feldspar sourcing to dampen input volatility.
Within the laboratory-anchored tier, Ferro Corporation and Colorobbia exemplify archetypes built on embedded formulation support and vertically controlled raw-material sourcing respectively. Esmalglass-Itaca occupies a position bridging frit supply with digital decoration system convergence. These three represent distinct strategic postures: Ferro leverages global laboratory density for premium relationship stickiness, Colorobbia anchors Southern European supply through captive mineral access, and Esmalglass-Itaca competes on inkjet compatibility extension.
| Leading Market Players |
|---|
| Ferro Corporation |
| Colorobbia |
| Esmalglass-Itaca |
| Torrecid Group |
| QuimiCer |
| Fusion Ceramics |
| TOMATEC |
| Johnson Matthey |
| T&H GLAZE |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Pearl River Delta smelters is compressing spot-market frit quotations while tightening margins for electric-melting retrofits. This utilization imbalance forces European compounders to defend premium positioning through REACH-compliant reformulation services rather than volume competition.
Pricing Analysis
Long-term offtake agreements dominate procurement between large-format tile manufacturers and European compounders, embedding color-matching laboratory access within multi-year supply contracts. Pricing stratifies across premium, standard, and economy tiers based on whiteness specifications and thermal-expansion tolerances. Cost compression in porcelain-grade segments is intensifying because thin-slab producers reject batches failing 90% L-value thresholds. Building materials distributors exhibit highest price sensitivity, while architectural specification teams in Italy and Spain prioritize defect-free surface guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning as BIS certification timelines delay imported frit qualification. Production concentrates in China, Italy, and Spain, with Morbi in Gujarat emerging as India's qualification hub. Raw material sourcing draws from zircon mining in Australia, feldspar deposits in Turkey, and fluxing oxide suppliers in Germany. Single-source vulnerability in zircon opacifiers creates input cost volatility for whiteware grades. Distribution runs through direct sales for premium architectural accounts and wholesale networks for mid-tier sanitaryware producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic frit demand sits in early-cycle expansion as digital inkjet decoration convergence accelerates single-fire adoption across large-format tile production. India's housing infrastructure push and sanitaryware water-efficiency mandates provide twin tailwinds for sustained volume growth.
For Market Incumbents: Build captive technical service moats by embedding color-matching laboratories within annual supply agreements for thin porcelain slab producers. Defend against emerging Indian compounders by securing BIS certification documentation capabilities ahead of accelerated validation timelines. Prioritize electric-melting capacity additions in western China provinces to satisfy MEE energy-intensity limits while maintaining Pearl River Delta customer access. For New Entrants and Emerging Players: Build out formulation consulting capabilities unbundled from material sales to capture standalone technical service revenue in India's tier-2 and tier-3 ceramic clusters. Target sanitaryware glaze segments where water-efficiency mandates compress replacement cycles and certification barriers remain surmountable. Pursue joint development agreements with digital inkjet equipment manufacturers to ensure frit-ink compatibility from formulation stage. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemicals consolidation play because technical service intensity and regulatory compliance barriers favor scaled compounders with laboratory density. Acquisition candidates include regional smelters with captive zircon or feldspar access and demonstrated REACH reformulation capabilities. Watch for inflection when India's BIS certification mandates extend beyond abrasion thresholds to heavy-metal content specifications, accelerating import substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zircon Sourcing | Captive mineral access dampens opacifier cost volatility for whiteware grades. |
| Electric Melting Retrofit Program | MEE energy-intensity compliance preserves Chinese smelter operating licenses. |
| Digital Inkjet Compatibility Certification | Frit-ink convergence enables single-fire production for large-format facade systems. |
| Long-term Technical Service Agreement | Embedded laboratory support locks in premium relationships with specification-grade buyers. |
| Joint Venture with Regional Distributor | Pan-Indian coverage accelerates BIS qualification timelines for imported formulations. |
Study Parameters
Desk research of trade flow databases, ceramic industry association publications, and regulatory filing repositories preceded structured interviews with frit plant managers, procurement leads at tile OEMs, technical R&D directors, and distribution channel partners. Primary fieldwork combined telephone interviews and site visits to Sassuolo, Castellón, Morbi, and Foshan ceramic clusters. Secondary validation drew from customs records, BIS certification registries, MEE enforcement notices, and ECHA REACH registration data. Bottom-up volume estimates triangulated against top-down construction spending correlations.
Assumptions held fixed include current REACH and GB standard heavy-metal thresholds, MEE dual carbon enforcement intensity, and digital inkjet penetration rates in large-format tile production. The analytical framework segmented by product grade, application, end-user procurement sophistication, and distribution channel across the analysis window. Modeled dimensions included thermal-expansion coefficient tiers, single-fire versus double-fire cycle compatibility, and regional regulatory cluster alignment. CAGRs derived from regression against construction value-added indices and ceramic tile production capacity forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-supported Chinese compounders or unexpected BIS certification accelerations would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Ceramic Pigments Market
Ceramics
Transparent Ceramics Market
Ceramics
Cement Castables Market
Ceramics
Ceramic Binders Market
Ceramics
Potassium Silicate Market
Ceramics
Pottery Ceramics Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Lithium Silicate Market
Ceramics
Calcium Oxide Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
North America Ceramic Coatings Market