
 Ball Clay Market | 2026-2036
Ball Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Ball Clay Market Intelligence
Technical advisory and formulation support is hardening the value proposition beyond raw material supply. Global leader Imerys leverages its extensive reserve base and processing capabilities to serve diverse end-markets. Sibelco differentiates through its focus on high-purity grades for specialized ceramic applications. Ashapura Minechem Ltd anchors its competitive position in the rapidly expanding Indian domestic market.
Ball clay is a fine-grained, highly plastic sedimentary clay, primarily composed of kaolinite, mica, and quartz. Its key properties include high plasticity and significant unfired strength, which makes it an essential plasticizer in ceramic formulations. Within product types, air-floated clay remains the workhorse grade for general ceramic applications, while granular clay gains traction for automated dosing systems. The sanitaryware application segment commands a substantial share of consumption, driven by construction activity in developing economies.
Regulatory frameworks like the EU's REACH and standards from the US EPA govern mineral sourcing, workplace safety, and processing emissions. In China, national GB standards for ceramics impose strict limits on heavy metal content, influencing raw material selection for manufacturers. Future competitiveness will depend on securing long-term reserves and developing formulations that meet increasingly stringent environmental and performance criteria.
Market Dynamics
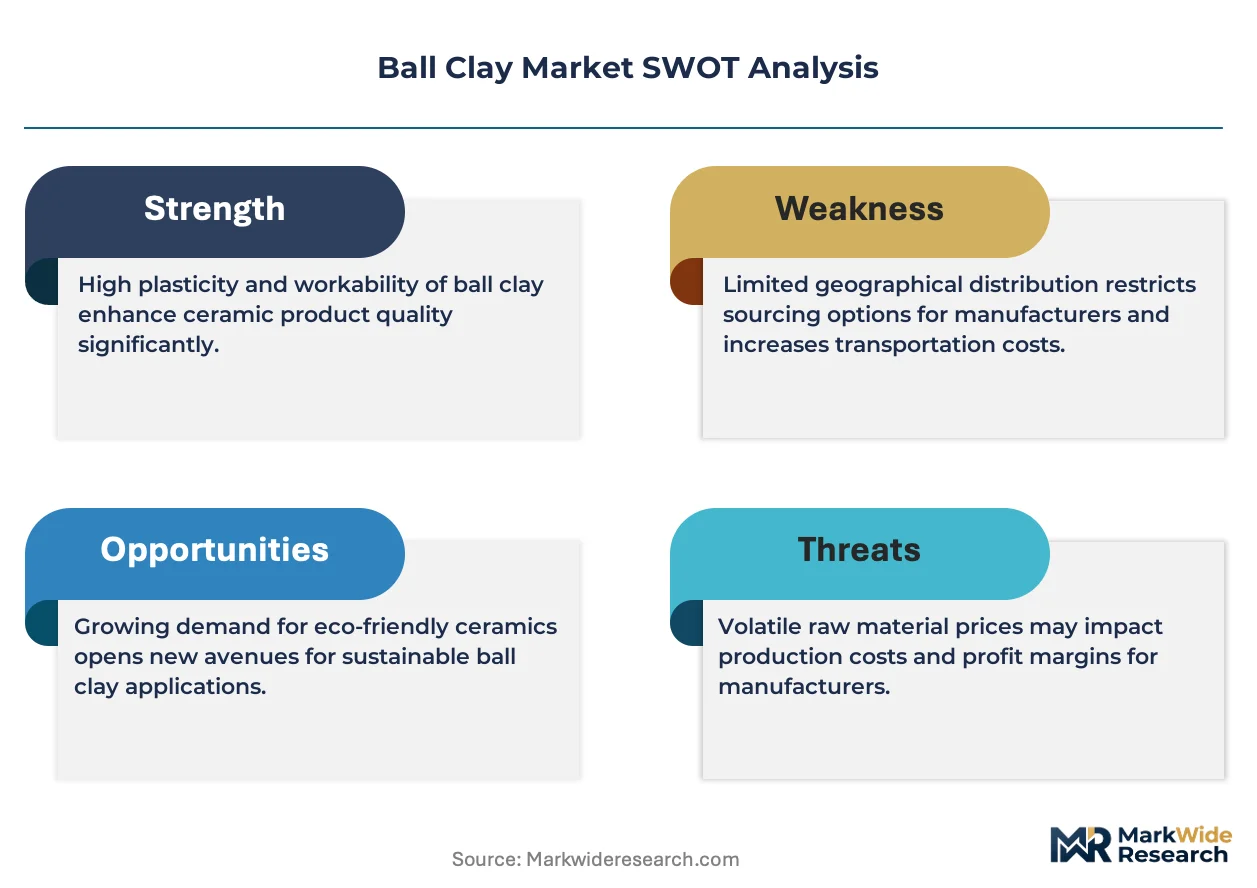
The market's central dynamic involves a structural tension between the escalating performance requirements of the sanitaryware and technical ceramics sectors and the concurrent tightening of environmental regulations governing mineral extraction and processing, such as those from China's MEE.
Growth Catalysts
- Indian Construction:Rapid urbanization and government-backed housing initiatives in India are accelerating consumption for sanitaryware and ceramic tiles, which are primary end-uses for ball clay.
- Sanitaryware Formulation:The push for lighter, more complex sanitaryware designs requires ball clay grades that offer superior plasticity and unfired strength for improved casting rates.
- Automated Manufacturing:Granular clay grades are seeing increased adoption in ceramic plants that utilize automated dosing systems for enhanced process control, consistency, and reduced dust.
Market Restraints
- Energy Costs:The high energy consumption of drying and calcining processes makes producers highly vulnerable to volatile natural gas and electricity prices, impacting gross margins.
- Logistical Hurdles:High-quality reserves are geographically concentrated in specific regions, leading to significant transportation costs and supply chain risks for distant end-markets.
- Regulatory Compliance:Adherence to regulations like the EU's REACH framework creates significant administrative and testing burdens, acting as a barrier for smaller or non-compliant suppliers.
Strategic Opportunities
- High-Purity Grades:There is an opportunity to develop specialized, high-purity ball clays for non-ceramic applications, including as functional fillers in advanced polymers and coatings.
- Low-Carbon Processing:Investing in processing technologies that reduce the carbon footprint of calcination can create a premium product for environmentally-conscious buyers under corporate ESG mandates.
- Southeast Asian Infrastructure:Emerging infrastructure and construction projects in countries like Vietnam and Indonesia present new geographic growth frontiers for ball clay consumption outside of traditional markets.
Industry Challenges
- Capital Intensity:Modernizing extraction equipment and processing kilns to meet new emissions standards from regulators like the US EPA requires substantial, long-term capital investment.
- Formulation Expertise:A shortage of ceramic engineers and geologists capable of developing novel formulations that balance performance with regulatory compliance is a key operational constraint.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ball Clay Market |
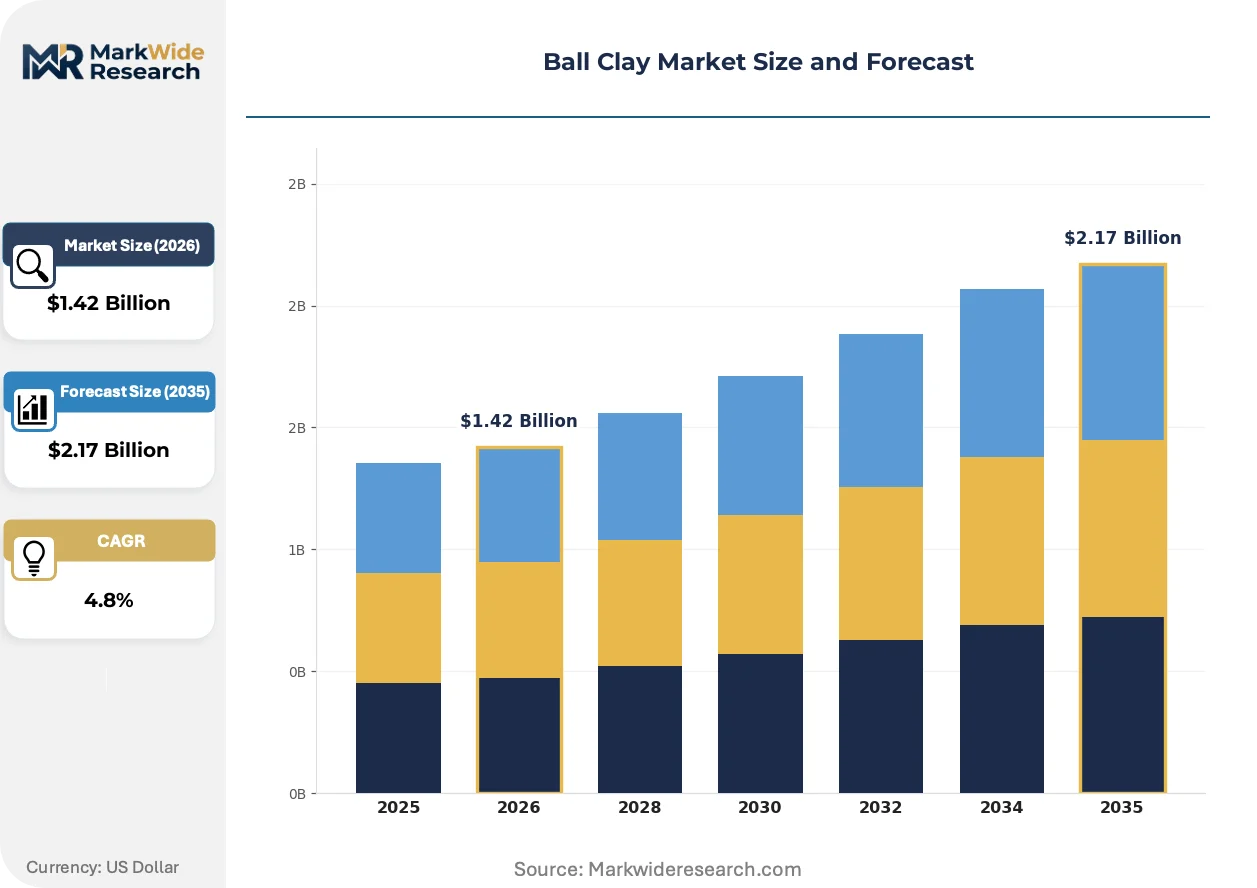
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Floated Clay, Granular Clay, Filter Press Clay, Raw Ball Clay Application: Ceramics, Pottery, Tiles, Sanitaryware End User: Manufacturers, Craftsmen, Retailers, Distributors Distribution Channel: Online, Direct Sales, Wholesalers, Retail Outlets |
| Companies Covered | Imerys, Sibelco, Ashapura Minechem Ltd, Old Hickory Clay Company, Stephan Schmidt KG, Amarnath Industries, Ashok Alco-Chem Limited, Kothari Minerals, G&W Mineral Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ball Clay Market Strategic Shifts & Innovations
The evolution of the ball clay market is defined by a push towards greater material intelligence and sustainability. This shift is driven by advancements in processing technology and stricter global environmental standards, altering product value propositions beyond the raw material itself.
Automated on-site blending technology provides ceramic manufacturers with precise control over body formulations. Large sanitaryware and tile producers are adopting these systems to create custom mixes tailored to specific production lines. This trend is decentralizing formulation development from central R&D labs to the factory floor, enabling faster product adjustments and process optimization.
China's national GB standards for ceramics impose stringent limits on heavy metal content, particularly lead and cadmium. This regulation directly impacts raw material selection, forcing suppliers targeting the Chinese market to invest in enhanced purification techniques and rigorous quality control. Consequently, producers of sanitaryware and tableware must provide extensive documentation on material provenance and purity.
A transition from transactional purchasing to partnership-based sourcing is becoming more common. Large-scale consumers in the technical ceramics and sanitaryware industries are demanding integrated formulation support and technical advisory services alongside raw material supply. This trend is most visible in Europe and North America, where manufacturers seek to optimize complex, high-value production processes.
Ball Clay Market Segmentation
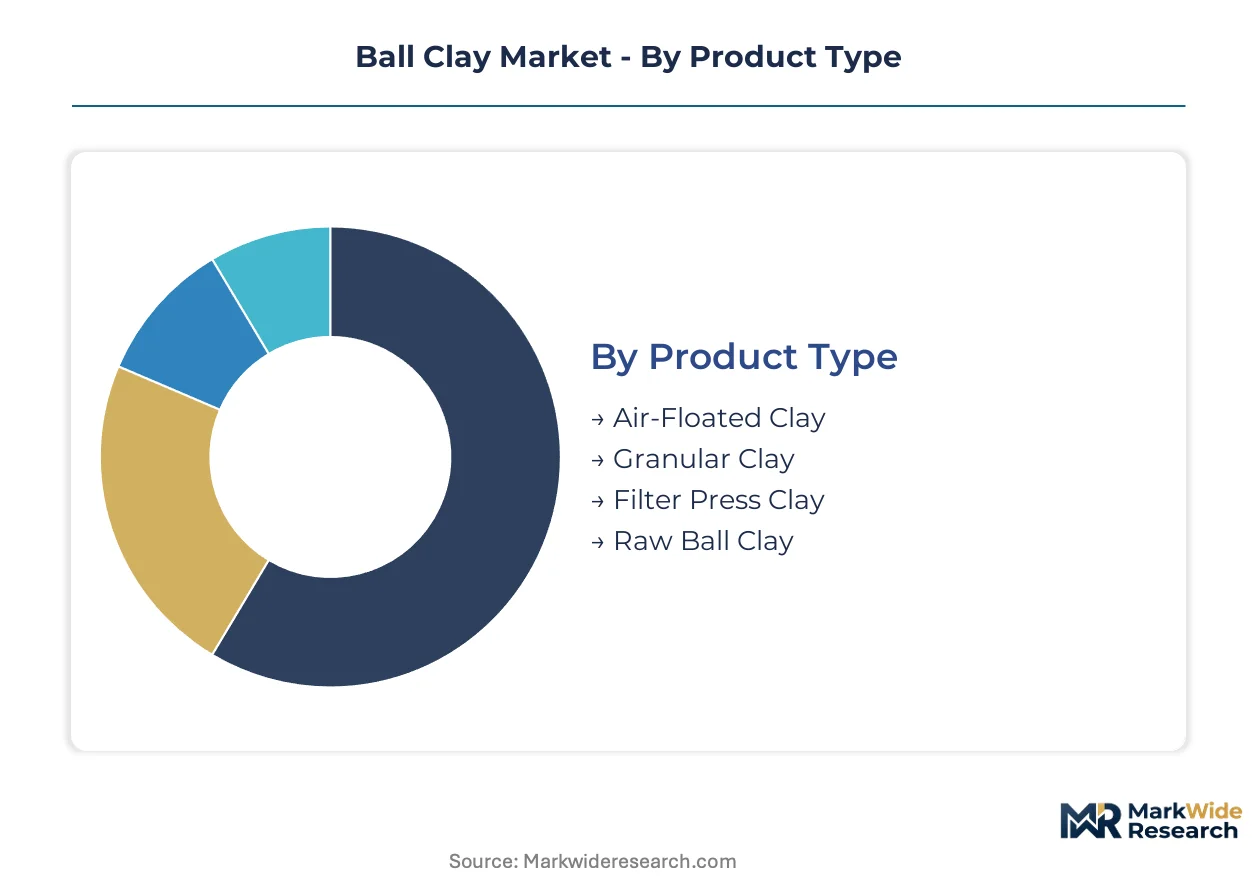
The Ball Clay Market segments across various dimensions, reflecting the diverse requirements of industrial users and the specialized nature of its applications. Understanding these classifications is crucial for producers to tailor product offerings and for consumers to optimize material selection for specific manufacturing processes.
Product Type:
The product type segmentation highlights the varying degrees of processing and customization ball clay undergoes to meet diverse industrial requirements.
- Air-Floated Clay:This fine-grained, dried, and pulverized ball clay offers consistent particle size for general ceramic applications. Demand concentrates in the ceramics sector due to its widespread use in traditional formulations.
- Granular Clay:Consisting of larger, uniform particles, granular clay is designed for automated dosing systems in modern ceramic plants. Its adoption is accelerating in sanitaryware production for enhanced process control and reduced dust.
- Filter Press Clay:This dewatered clay, often in cake form, minimizes transportation costs by reducing moisture content for specific industrial users.
- Raw Ball Clay:Unprocessed clay directly from the mine, raw ball clay is typically used by manufacturers with in-house processing capabilities.
Leading the category by volume: Air-Floated Clay. Growing fastest: Granular Clay.
Application:
Applications for ball clay range from traditional ceramic arts to highly engineered industrial products, each demanding specific material properties.
- Sanitaryware:This segment demands ball clay for its superior plasticity and unfired strength, crucial for complex designs and improved casting rates in toilet bowls and sinks. Consumption is driven by construction activity in developing economies like India.
- Ceramics:As a broad category, ceramics utilize ball clay as a key plasticizer in various formulations, including tableware, electrical insulators, and refractories. The segment values its contribution to material strength and workability.
- Tiles:Ball clay improves the plasticity and green strength of tile bodies, reducing breakage during manufacturing and enhancing finished product quality.
- Pottery:Traditional pottery relies on ball clay for its excellent workability and ability to hold shape, supporting artisanal and small-scale production.
Sanitaryware applications command the largest share, with general ceramics representing a foundational and diverse demand base.
End User:
End users vary significantly in their scale of operation and procurement strategies, influencing the supply chain for ball clay.
- Manufacturers:Large-scale ceramic, sanitaryware, and tile producers are primary end users, requiring consistent supply and often seeking technical advisory for specialized formulations. Their demand drives bulk purchasing and partnership-based sourcing.
- Distributors:These intermediaries play a critical role in reaching smaller manufacturers and diverse markets, managing inventory and logistics between producers and various end-use customers. They often provide localized supply.
- Craftsmen:Individual artists and small workshops utilize ball clay for pottery and artistic ceramics, typically purchasing in smaller quantities.
- Retailers:Retail outlets serve a niche market of hobbyists and small-scale producers, offering packaged ball clay for accessibility.
Manufacturers represent the dominant purchasing power, with distributors facilitating broader market access.
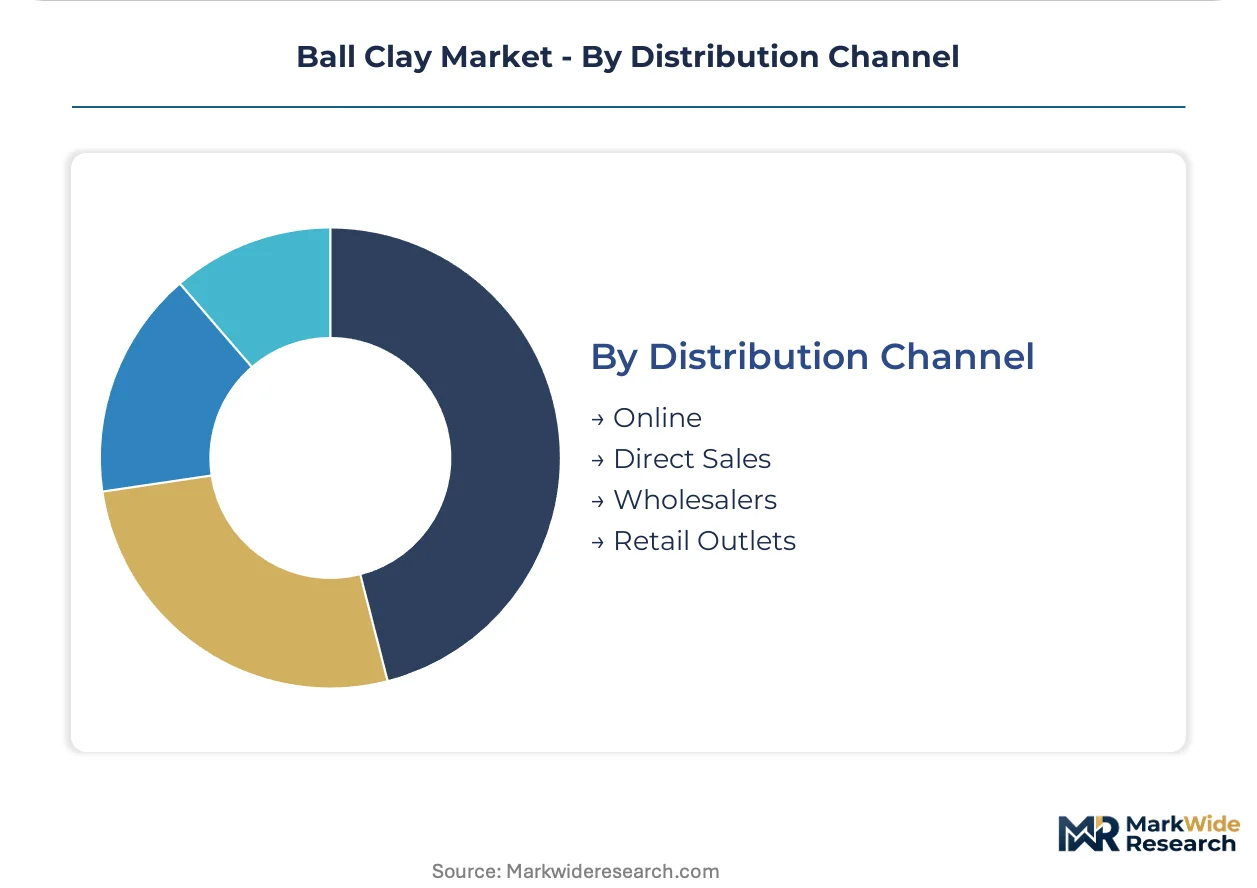
Distribution Channel:
The distribution channels reflect the industry's need for both high-volume direct supply and broad market penetration for various customer sizes.
- Direct Sales:Major ball clay producers engage in direct sales with large industrial manufacturers, fostering long-term partnerships and providing integrated technical support and customized supply agreements. This channel ensures efficient bulk delivery.
- Wholesalers:Wholesalers manage bulk purchases from producers and distribute to a wider network of smaller manufacturers, retailers, and craftsmen. They provide logistical efficiency and localized inventory management across regions.
- Retail Outlets:Physical retail stores cater to hobbyists and small-scale ceramic artists, offering convenient access to smaller quantities of ball clay.
- Online:E-commerce platforms are gaining traction for smaller orders and specialized grades, offering convenience and broader reach for niche customer segments.
Direct sales remain critical for large-scale industrial clients, while online channels are expanding their reach for smaller orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's expanding urban development projects drive significant demand for sanitaryware, a key application for ball clay. India's government-backed housing initiatives further accelerate consumption in construction. This creates a substantial market for ball clay suppliers.
India
India's rapid urbanization fuels robust demand for ceramic tiles and sanitaryware. The PLI scheme for manufacturing incentivizes domestic production, boosting raw material consumption. In Gujarat, ceramic manufacturing clusters require consistent, high-quality ball clay for their expanding facilities.
China
China's stringent GB standards for ceramics directly influence raw material selection, forcing suppliers to enhance purification techniques. The Ministry of Ecology and Environment (MEE) regulations on mineral extraction impact local supply availability. Jingdezhen, a historic ceramic hub, adapts its material sourcing to meet evolving environmental performance criteria.
United States
United States construction activity, particularly in residential and commercial sectors, sustains consistent demand for ceramic products. Environmental Protection Agency (EPA) regulations govern mining practices and processing emissions for domestic producers. The Ohio Valley region, with its ceramic industry presence, focuses on specialized clay formulations for technical applications.
Germany
Germany's advanced ceramic sector, including high-value technical ceramics, requires specialized ball clay grades for performance applications. The EU's REACH framework imposes strict chemical safety requirements on all imported and domestically processed materials. Bavaria, a hub for industrial ceramics, invests in sustainable processing technologies to meet market demands.
Vietnam
Vietnam's burgeoning infrastructure and housing projects generate new demand for sanitaryware and ceramic tiles. The government's industrialization policies encourage foreign investment in manufacturing, including ceramic production. In Binh Duong province, new ceramic factories seek reliable ball clay supplies to support their expanding capacities.
Ball Clay Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the ball clay market. The industry exhibits a tiered structure, with large integrated miners operating alongside specialized processors. Strategic archetypes include global raw material suppliers and regional niche players. Competitive moves involve capacity expansion and the development of specialized grades.
Within the global supply chain, Imerys and Sibelco exemplify leading positions through extensive reserve bases and specialized processing capabilities. Imerys, a global materials company, leverages its scale across diverse end-markets. Sibelco, a Belgian industrial minerals group, differentiates by focusing on high-purity grades for specialized ceramic applications. Ashapura Minechem Ltd anchors its competitive position in the rapidly expanding Indian domestic market.
| Leading Market Players |
|---|
| Imerys |
| Sibelco |
| Ashapura Minechem Ltd |
| Old Hickory Clay Company |
| Stephan Schmidt KG |
| Amarnath Industries |
| Ashok Alco-Chem Limited |
| Kothari Minerals |
| G&W Mineral Resources |
| Others |
Cost & Logistics Intelligence
China's MEE regulations on mineral extraction are forcing ball clay suppliers to invest in enhanced purification, directly impacting production costs and driving upward price adjustments for compliant grades. This regulatory shift reshapes supply chain dynamics.
Pricing Analysis
Pricing pressure intensifies for standard ball clay grades as energy costs for drying and calcining processes escalate. The market primarily operates on contract-based long-term agreements for large manufacturers, with transactional pricing for smaller buyers. Price differentiation stems from high-purity grades for specialized ceramic applications and the inclusion of technical advisory services. Large sanitaryware and technical ceramics manufacturers prioritize performance, exhibiting lower price sensitivity compared to smaller pottery workshops.
Supply Chain Analysis
Dual-sourcing requirements are becoming more common among large ceramic manufacturers to mitigate supply chain risks. Ball clay reserves concentrate geographically in countries like India, China, and the United States, creating logistical hurdles for distant end-markets. The supply chain relies on consistent extraction of kaolinite, mica, and quartz. A structural risk involves commodity price volatility for energy inputs. Distribution runs through direct sales channels for major industrial clients and wholesalers serving smaller manufacturers and retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ball clay market is undergoing a technology-driven transition, as automated dosing systems for granular clay replace traditional manual blending methods in ceramic production. This shift demands new product forms and processing capabilities.
For Market Incumbents: Acquire long-term reserve bases in key geographies to ensure supply security against increasing regulatory restrictions. Incumbents should invest in low-carbon processing technologies, particularly for calcination, to meet corporate ESG mandates and counter volatile energy costs. Developing specialized, high-purity grades with integrated technical advisory services strengthens competitive positioning against emerging performance requirements. This strategy defends market share from new entrants focused solely on raw material supply.
For New Entrants and Emerging Players: Enter via specialized granular clay grades tailored for automated dosing systems in rapidly industrializing regions. New players can target the expanding Southeast Asian infrastructure market, particularly countries like Vietnam, which have new ceramic factories. Focus on non-ceramic applications, such as functional fillers in advanced polymers, to capture high-value niches. Offering integrated formulation expertise alongside supply provides a differentiation angle for smaller manufacturers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate regional processing capabilities over the next 5-10 years. Focus on mid-sized ball clay producers with strong, certified reserve bases and advanced processing intellectual property. These targets offer insulation against raw material scarcity and regulatory shifts. A key signal to watch is the accelerating adoption rate of automated dosing systems in large-scale ceramic manufacturing plants.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases supply to meet growing demand from Indian construction. |
| Low-Carbon Processing Investment | Reduces energy costs and appeals to environmentally conscious buyers. |
| High-Purity Grade Development | Addresses performance needs for technical ceramics and non-ceramic uses. |
| Long-Term Supply Agreements | Secures consistent raw material flow for major sanitaryware manufacturers. |
| Technical Advisory Service Integration | Differentiates offerings beyond raw material supply for complex formulations. |
Research Approach
Independent corroboration across industry association reports, government mineral surveys, and company financial filings underwrites the qualitative findings. Primary interviews with ceramic engineers, procurement managers, geologists, and R&D directors provided granular insights. Secondary validation involved comprehensive data from trade publications and regulatory body releases, like those from China's MEE. A bottom-up and top-down triangulation approach ensured robust market sizing and segmentation.
Historical market performance across comparable periods anchored the forecast window, informing baseline projections. The analytical framework modeled demand across product type, application, end-user, and distribution channel dimensions. Compound Annual Growth Rates were derived through statistical regression analysis, further refined by expert consensus. Key inputs included global construction activity indices and regional sanitaryware production volumes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme energy price volatility or new environmental regulations. Forecasts reflect assumptions regarding sustained construction activity and consistent raw material supply. Deviation in global economic growth would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Strontium Carbonate Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Vaterite Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Nanoceramic Powder Market
Ceramics
North America Barium Carbonate Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Colloidal Alumina Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Engineering Ceramics Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Global Ceramic Tube Market