
 USA and Canada Alumina Market | 2026-2036
USA and Canada Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Alumina Market Analytics
Asset-light tolling arrangements and third-party refining contracts are reshaping competitive entry in the USA and Canada Alumina Market. Alcoa Corporation leverages captive bauxite-to-alumina integration across its US Gulf Coast operations. Rio Tinto Group anchors its position through proprietary low-carbon refining technology deployed in Quebec. South32 competes via long-haul logistics optimization between Australian feedstock and North American smelters.
Alumina comprises aluminum oxide (Al₂O₃) extracted from bauxite through the Bayer process, typically yielding purity grades from 99.5% metallurgical grade to 99.99% high-purity specialty variants for electronic substrates. Its primary purpose is serving as the feedstock for aluminum smelting via Hall-Héroult electrolysis, while specialty grades enable ceramic, refractory, and polishing applications demanding controlled particle size and alpha-phase content. Metallurgical alumina dominates volume flows into primary aluminum production, though specialty alumina commands superior margin pools in aerospace and electronics end uses. Refractories and ceramic manufacturing segments are absorbing higher-purity calcined grades as US steelmakers modernize furnace linings.
The EPA enforces National Emission Standards for Hazardous Air Pollutants (NESHAP) that constrain refinery particulate and fluoride outputs, while OSHA mandates workplace exposure limits that elevate capital intensity for brownfield upgrades. Canadian provincial regulators in Quebec apply carbon intensity benchmarks that favor hydro-powered refineries over fossil-dependent competitors. Stakeholders must monitor evolving cross-border carbon border adjustment mechanisms and smelter power purchase agreements to assess long-term cost positioning.
Market Dynamics
Carbon border adjustment mechanisms and provincial carbon pricing frameworks are forcing refiners to decarbonize Bayer process operations or face margin erosion on cross-border shipments. The divergence between Quebec's hydro-powered refineries and fossil-dependent US Gulf Coast assets is widening competitive cost positions.
Growth Catalysts
- Texas Petrochemical Cluster Expansion:Integrated alumina-aluminum complexes along the US Gulf Coast are capturing economies of scale from shared utilities and logistics infrastructure. Downstream smelter investments are pulling metallurgical grade demand.
- EPA NESHAP Compliance Upgrades:Stricter particulate and fluoride emission limits are accelerating capital deployment into wet scrubbing and dry sorbent injection systems. Brownfield modernization is extending asset lifecycles.
- Specialty Alumina in Aerospace:Controlled particle size alpha-phase variants are penetrating ceramic matrix composite applications for turbine components. US Great Lakes aerospace suppliers are qualifying domestic calcined grades.
Market Restraints
- Bauxite Import Dependency:North American refiners source over ninety percent of feedstock from Guinea, Australia, and Brazil. Concentrated seaborne supply exposes margins to freight volatility and port congestion.
- Natural Gas Price Sensitivity:Calcination energy intensity ties US Gulf Coast refinery economics to Henry Hub pricing. Thermal costs comprise a material share of cash production costs.
- Fluoride Handling Constraints:Red mud residue management and fluoride byproduct disposal face tightening state-level hazardous waste classifications. Liability costs are escalating for legacy pond sites.
Strategic Opportunities
- Quebec Low-Carbon Premium:Hydro-powered refineries in Saguenay-Lac-Saint-Jean can certify sub-two-tonne CO₂ per tonne alumina output. Carbon-intensity labeling commands price premiums from European smelter customers.
- Refractory Grade Substitution:US steelmaker furnace rebuilds are absorbing higher-purity tabular alumina. Domestic supply reduces reliance on Chinese refractory imports.
- Digital Twin Process Control:Real-time Bayer digester optimization using machine learning is migrating from pilot to commercial deployment. Yield improvements of two to four percent are achievable.
Industry Challenges
- Hydrometallurgical Engineering Talent Scarcity:Specialized expertise in Bayer circuit design and red mud chemistry is concentrated among retiring cohorts. University programs are not replenishing technical pipelines.
- Legacy Asset Retrofit Complexity:Pre-1990 refineries face structural constraints integrating modern emissions controls. Foundation loadings and spatial layouts limit scrubber installation options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Alumina Market |
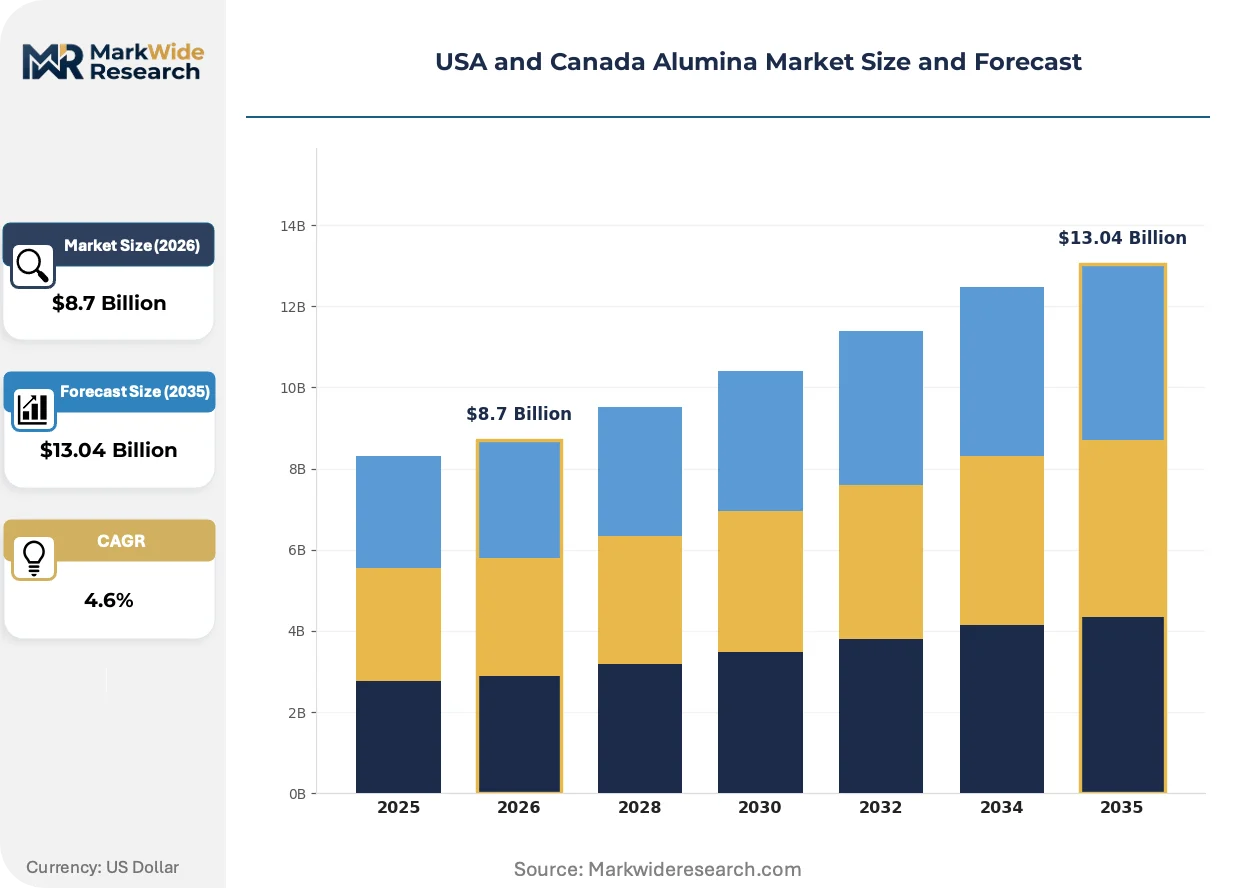
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallurgical Alumina, Calcined Alumina, Specialty Alumina, Hydrated Alumina Application: Aluminum Production, Ceramic Manufacturing, Refractories, Water Treatment End User: Aerospace, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Alcoa Corporation, Rio Tinto Group, South32, Norsk Hydro ASA, Century Aluminum, Aluminerie Alouette, Alcoa Canada, Polar Sapphire, Sasol Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Alumina Market Evolving Landscape
Process intensification and digitalization are converging to reshape alumina refining economics. Technology migration is favoring low-carbon configurations and precision-grade outputs over commodity scale.
Flash calcination technology is migrating from conventional rotary kiln systems toward stationary vertical shaft designs that halve thermal energy requirements. Specialty refractory producers in Ohio and Pennsylvania are adopting these calcined grades for high-temperature ceramic applications. The technology is migrating from niche pilot installations to mainstream commercial contracts as energy costs compress margins on legacy processes.
Canadian federal carbon pricing and Quebec's cap-and-trade system are tightening cost differentials between hydro-powered and fossil-fuel refineries. Refiners in Alberta and British Columbia face accelerating compliance costs that favor relocation or retirement. The policy shift is concentrating investment in Quebec's Saguenay corridor where existing hydro infrastructure anchors cost-competitive expansion.
Buyers in aerospace and electronics verticals are consolidating supplier qualifications around ISO-certified particle size distribution and alpha-phase consistency. Long-term offtake agreements are displacing spot market transactions for specialty grades. Texas and Quebec integrated clusters are capturing these contract structures first due to proximity to downstream qualification laboratories.
USA and Canada Alumina Market Segmentation
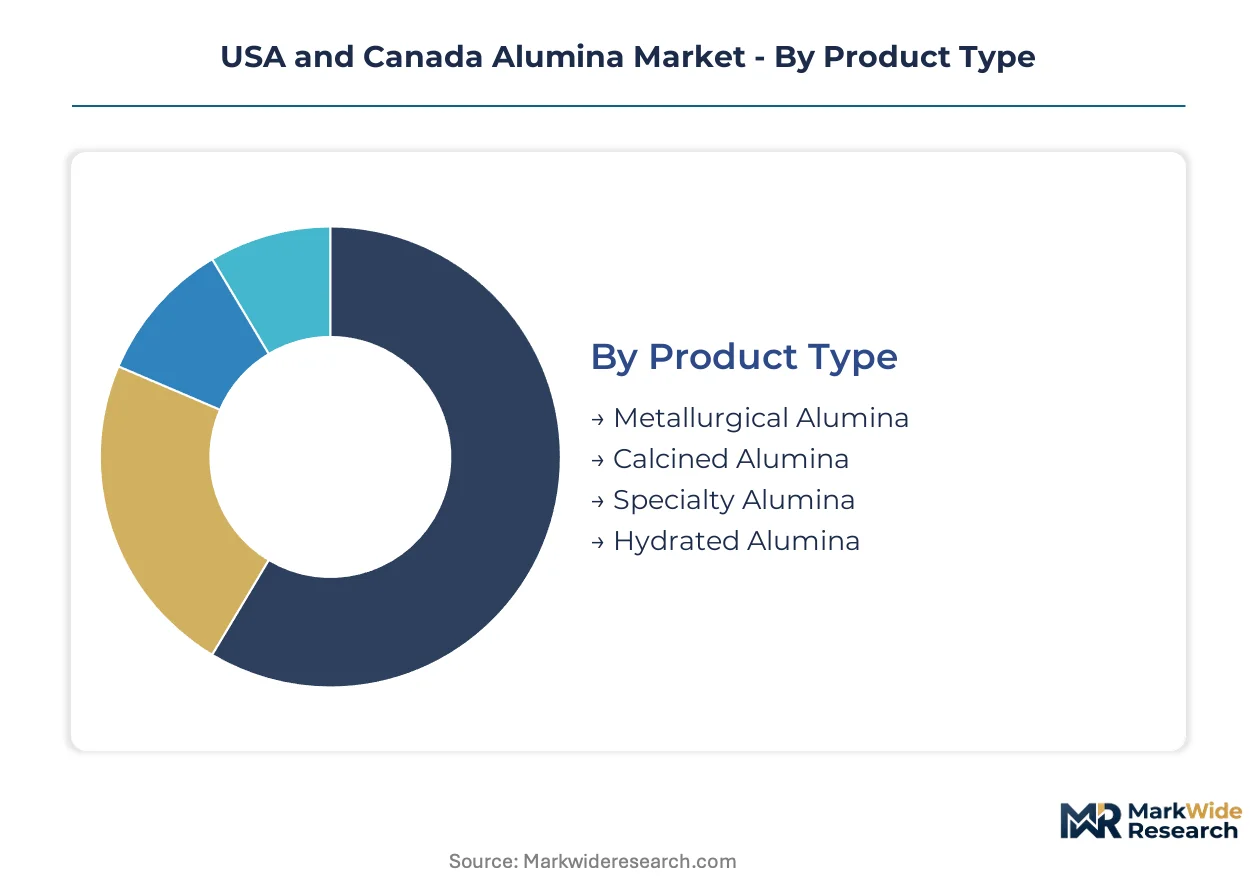
Alumina markets fragment across technical specifications that determine downstream compatibility and pricing power. Product purity, calcination state, and particle morphology create distinct commercial tiers with divergent margin structures and customer qualification requirements.
Product Type:
Cost tier differentiation separates commodity-scale metallurgical flows from premium specialty grades commanding technical certification premiums.
- Metallurgical Alumina:Smelter-grade material at 99.5% purity serves Hall-Héroult electrolysis feedstock. Texas Gulf Coast smelters absorb the bulk of domestic volume under long-term tolling arrangements tied to aluminum output.
- Specialty Alumina:Controlled alpha-phase content and sub-micron particle distributions enable ceramic matrix composites for aerospace turbine components. Great Lakes aerospace suppliers are qualifying domestic calcined grades to reduce import dependency.
- Calcined Alumina:High-temperature rotary kiln processing yields dense, low-porosity grains for refractory brick manufacturing.
- Hydrated Alumina:Precipitated gibbsite form supplies flame retardant polymer applications and water treatment chemical feedstocks.
Metallurgical Alumina holds installed capacity. Specialty Alumina is rotating up the share rankings.
Application:
End-use concentration patterns reveal divergent demand drivers across industrial verticals and geographic clusters.
- Aluminum Production:Primary smelting consumes metallurgical grade via Hall-Héroult cells. Quebec hydro-powered refineries supply low-carbon intensity material to European smelters facing carbon border adjustment exposure.
- Refractories:Tabular and fused alumina grades line steelmaking furnaces, ladles, and cement kilns. US steelmaker modernization programs are absorbing higher-purity domestic calcined material.
- Ceramic Manufacturing:Technical ceramics for electronics substrates and wear components require precise particle size distribution control.
- Water Treatment:Hydrated alumina functions as coagulant and adsorbent in municipal and industrial wastewater systems.
Aluminum Production anchors volume throughput. Refractories is climbing the fastest as steelmaker furnace rebuilds accelerate.
End User:
Customer type determines specification stringency, contract duration, and supplier qualification complexity.
- Aerospace:Ceramic matrix composite turbine components demand ISO-certified particle consistency and traceable alpha-phase content. Long-term offtake agreements are displacing spot transactions for qualified material.
- Electronics:Substrate and packaging applications require 99.99% high-purity grades with controlled surface area.
- Automotive:Lightweight aluminum structural components and EV battery enclosures drive metallurgical grade consumption.
- Construction:Architectural glass and cement additives absorb lower-purity hydrated alumina volumes.
Aerospace holds qualification barriers. Electronics is expanding most quickly as domestic semiconductor packaging reshoring proceeds.
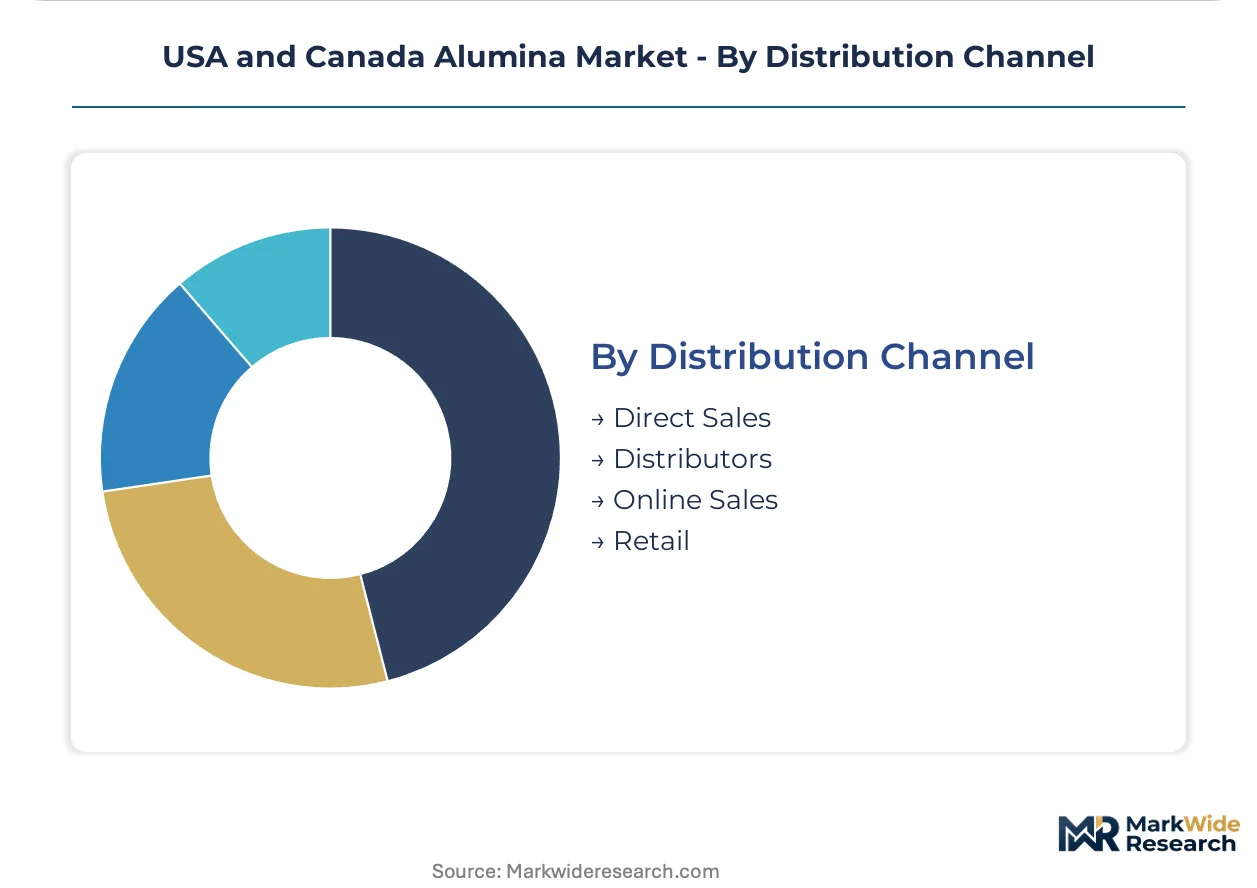
Distribution Channel:
Channel structure reflects customer scale, technical service requirements, and geographic concentration of demand.
- Direct Sales:Integrated aluminum producers and major aerospace contractors procure via long-term supply agreements with dedicated technical service support. Quebec and Texas cluster proximity enables just-in-time delivery coordination.
- Distributors:Regional stocking points serve fragmented refractory and ceramic fabricators requiring smaller lot sizes and blending services.
- Online Sales:Hydrated alumina for water treatment and specialty chemical applications migrates to digital procurement platforms.
- Retail:Small-volume polishing and hobbyist ceramic markets absorb packaged consumer grades.
Direct Sales commands contract value. Distributors is gaining share fastest as mid-tier refractory demand fragments geographically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows between the United States and Canada dominate North American alumina trade, with Quebec hydro-powered refineries supplying low-carbon material to European smelters while Texas Gulf Coast complexes absorb metallurgical grade from Australian and Guinean bauxite. Cross-border logistics integration and divergent carbon pricing frameworks are reshaping regional competitive positioning.
Texas Gulf Coast
Petrochemical cluster expansion drives metallurgical alumina demand from integrated aluminum smelters in Corpus Christi and Point Comfort. EPA NESHAP compliance upgrades accelerate capital deployment into wet scrubbing systems at legacy refineries. Shared utilities infrastructure enables just-in-time delivery coordination with downstream Hall-Héroult cell operations.
Quebec Saguenay-Lac-Saint-Jean
Hydro-powered refineries near Alma and Jonquière certify sub-two-tonne CO₂ per tonne alumina output for carbon-intensity labeling. Provincial cap-and-trade systems tighten cost differentials against fossil-fuel competitors. Rio Tinto Group anchors proprietary low-carbon refining technology deployment across the Saguenay corridor.
Ohio-Pennsylvania Rust Belt
Specialty alumina qualification for aerospace ceramic matrix composites concentrates around Cleveland and Pittsburgh manufacturing clusters. US steelmaker furnace rebuilds absorb higher-purity tabular alumina from domestic calcination facilities. Refractory grade substitution reduces import dependency on Chinese supply.
Alberta Industrial Heartland
Fossil-dependent refining assets near Fort Saskatchewan face accelerating carbon compliance costs under federal pricing frameworks. Natural gas price sensitivity ties calcination economics to AECO Hub volatility. Asset retirement or relocation pressure favors Quebec hydro infrastructure for long-term expansion.
British Columbia Pacific Gateway
Seaborne bauxite import logistics concentrate at Vancouver and Prince Rupert port facilities. Red mud residue management and fluoride byproduct disposal face tightening provincial hazardous waste classifications. Legacy pond site liability costs escalate for pre-1990 refinery infrastructure.
USA and Canada Alumina Market Competitive Landscape
On the supply side, the industry is consolidating around integrated bauxite-to-alumina operators and specialty-grade specialists with ISO-certified particle control capabilities. Strategic archetypes span captive feedstock integrators, tolling arrangement platforms, and low-carbon technology licensors. Dominant competitive moves include brownfield emissions retrofit deployment and long-term offtake agreement restructuring for carbon-intensity certification.
Among North American integrated producers, Alcoa Corporation and Rio Tinto Group exemplify divergent positioning strategies. Alcoa anchors Gulf Coast metallurgical supply through captive bauxite integration. Rio Tinto occupies a position within Quebec's hydro-powered low-carbon tier. South32 represents the long-haul logistics optimization archetype, bridging Australian feedstock supply with North American smelter demand.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Rio Tinto Group |
| South32 |
| Norsk Hydro ASA |
| Century Aluminum |
| Aluminerie Alouette |
| Alcoa Canada |
| Polar Sapphire |
| Sasol Limited |
| Others |
Value Network & Pricing Analysis
Guinea-Australia-Brazil bauxite concentration upstream funnels margin capture toward integrated refiners with captive logistics contracts, while downstream smelters absorb cost pass-through volatility through long-term tolling structures. Metallurgical grade pricing tracks Henry Hub thermal costs and seaborne freight indices, whereas specialty alumina commands ISO-certified premiums decoupled from commodity benchmarks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the USA and Canada Alumina Market. Three-tier pricing structure across premium specialty, standard metallurgical, and economy hydrated grades separates carbon-intensity certification from volume scale from basic chemical purity. Cost compression in Gulf Coast metallurgical tiers is intensifying because natural gas calcination economics face AECO Hub volatility. Smelter procurement teams show highest price sensitivity to thermal cost pass-throughs, while aerospace qualification programs absorb premium spreads without volume negotiation.
Supply Chain Analysis
Export-control regimes on flash calcination technology and proprietary low-carbon refining IP constrain equipment flows into competing jurisdictions. Feedstock draws from Guinea, Australia, and Brazil; calcination energy rests on Henry Hub and AECO Hub pricing; specialty grade qualification hinges on Great Lakes aerospace laboratory proximity. Single-source vulnerability concentrates at Conakry port congestion points and Panama Canal transit bottlenecks. Distribution runs through direct sales to integrated aluminum producers and regional distributors serving fragmented refractory fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical pipeline gaps in Bayer circuit hydrometallurgy and red mud chemistry constrain expansion velocity, with university programs failing to replenish retiring cohort expertise. This capability scarcity rewards early movers who secure specialized engineering talent through apprenticeship structures or acquisition.
For Market Incumbents: Pre-empt specialty grade certification lock-in by accelerating ISO particle distribution qualifications with Great Lakes aerospace suppliers before rival low-carbon entrants capture offtake agreements. Defend margin position through backward integration into captive bauxite logistics contracts that insulate against Conakry port congestion volatility. Prioritize brownfield scrubber retrofits at pre-1990 Gulf Coast assets to extend asset lifecycles under tightening EPA NESHAP enforcement. For New Entrants and Emerging Players: Build out tolling arrangement platforms serving mid-tier refractory fabricators in Ohio-Pennsylvania corridors where distributor fragmentation creates white-space entry. Target digital twin process control deployment for Bayer digester optimization, offering yield improvement contracts rather than capital equipment sales. Lead with machine learning pilot programs that demonstrate two-to-four percent efficiency gains before requesting long-term service agreements. For Investors and Strategic Acquirers: Capital is best deployed toward Quebec hydro-powered refinery archetypes with sub-two-tonne CO₂ certification and established European smelter offtake relationships. Long-term viability across the analysis window favors assets with carbon-intensity labeling already qualified for EU carbon border adjustment exposure. Watch for inflection signals in European smelter power purchase agreement renegotiations that would accelerate low-carbon premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Logistics | Captive supply contracts insulate Alcoa and Rio Tinto from Conakry port congestion volatility. |
| Low-Carbon Certification Program | Quebec hydro-powered refineries qualify sub-two-tonne CO₂ output for European carbon border adjustment premiums. |
| Digital Twin Process Control Deployment | Machine learning optimization of Bayer digesters yields two-to-four percent efficiency improvements for adopters. |
| Long-Term Supply Agreement Restructuring | Carbon-intensity clauses displace spot transactions as aerospace buyers consolidate qualified supplier pools. |
| Brownfield Emissions Retrofit Investment | Wet scrubbing and dry sorbent injection systems extend pre-1990 asset lifecycles under EPA NESHAP enforcement. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, aerospace procurement directors, EPA compliance officers, and tolling arrangement specialists and refined through secondary validation. Trade data from USGS mineral commodity summaries, Canadian international merchandise trade databases, SEC 10-K filings from integrated producers, and EPA enforcement and compliance history online records anchored quantitative baselines. Bottom-up capacity modeling and top-down demand absorption analysis triangulated volume estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeled across product purity tiers, calcination states, end-use industries, and regional production clusters. CAGRs were derived from regression analysis against aluminum smelter capacity expansion schedules and aerospace qualification timelines. Forecast inputs incorporated Henry Hub natural gas price scenarios and European carbon border adjustment implementation pacing.
Stress conditions across bauxite freight rates, Quebec hydroelectric output variability, and EPA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about smelter power purchase agreement structures and specialty grade qualification timelines. Material shifts in EU carbon border adjustment scope or Chinese refractory export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Activated Alumina Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Lithium Zirconate Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Ceramic Substrate Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Global Ceramic Tube Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Zeolite 4A Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
Ceramics Packaging Market
Ceramics
Barium Carbonate Powder Market