
 Feldspar and Nepheline Syenite Market | 2026-2036
Feldspar and Nepheline Syenite Market Size, Share, and Industry Trends Forecast 2026-2036
Feldspar and Nepheline Syenite Market Analysis
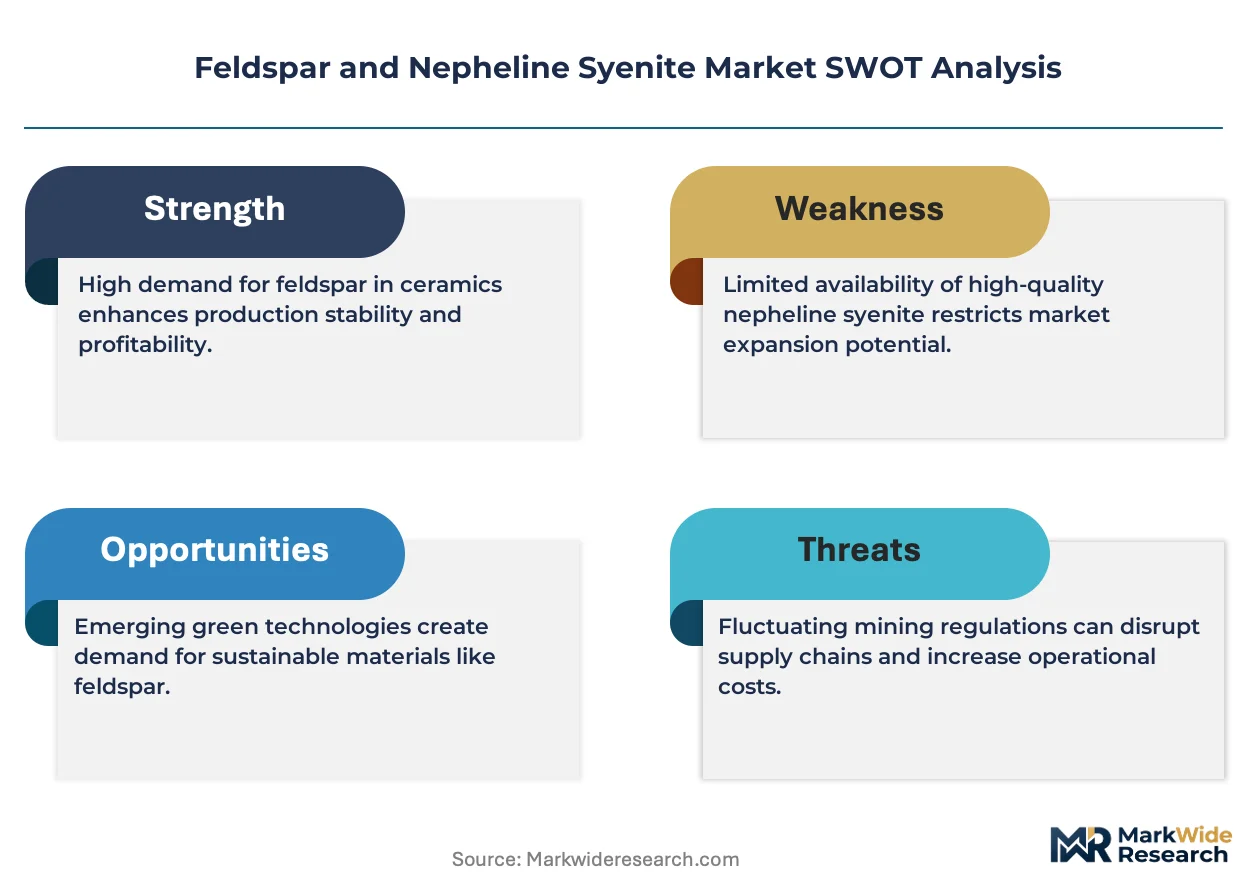
Raw material beneficiation is tilting margin pools toward higher-purity processing streams. Covia Holdings LLC leverages Appalachian deposit quality to sustain North American supply leadership. SCR-Sibelco NV anchors European ceramics demand through integrated logistics networks across Belgium and France.
Feldspar comprises alkali aluminosilicate minerals with typical K2O content between 10% and 12%, functioning as fluxing agents that lower glass and ceramic melting temperatures. Nepheline syenite delivers lower silica and higher alumina ratios than standard feldspar, making it preferable for reduced-iron glass formulations. The ceramics end-use segment dominates volume consumption through tile and sanitaryware manufacturing. Glass applications capture premium pricing through optical-grade nepheline syenite specifications. Powder form leads distribution due to pneumatic handling efficiency in continuous kiln operations.
EPA mining waste standards shape US extraction permitting timelines, while REACH registration requirements in Europe constrain importer qualification pathways. China's GB standards for ceramic raw materials set export-quality benchmarks that non-Chinese suppliers must meet for Asian market access. Stakeholders should monitor alumina-to-silica ratio specifications as glass furnace energy efficiency regulations tighten across multiple jurisdictions.
Market Dynamics
Glass furnace energy efficiency mandates are compressing alumina-to-silica ratio tolerances, forcing beneficiation investments that favor integrated processors with captive nepheline syenite reserves.
Growth Catalysts
- REACH registration pathways:European ceramics manufacturers face restricted importer qualification, creating captive demand for ECHA-registered domestic processors.
- Tile manufacturing clusters:India's ceramic belt around Morbi drives alkali feldspar consumption for vitrified tile fluxing requirements.
- Reduced-iron glass formulations:Optical-grade nepheline syenite specifications command premium placement in display glass applications.
Market Restraints
- Energy cost volatility:Natural gas prices govern continuous kiln economics, compressing margins for powder-form distributors without long-term fuel hedging.
- Deposit concentration:Appalachian high-purity reserves concentrate North American supply leverage among integrated holding structures.
- Silica substitution pressure:Synthetic fluxing agents threaten standard-grade feldspar in cost-sensitive sanitaryware segments.
Strategic Opportunities
- Turkey glass corridor:Turkish manufacturers expand float glass capacity, creating uncontracted nepheline syenite demand for European suppliers with Bosphorus logistics access.
- Optical-grade specifications:Premium nepheline syenite for lithium-aluminosilicate glass substrates opens specialty chemical distribution channels.
- EU Green Deal alignment:Carbon border adjustment mechanisms favor low-carbon beneficiation routes from Nordic anorthosite-nepheline deposits.
Industry Challenges
- Beneficiation engineering talent:Magnetic separation and flotation process design expertise concentrates among aging technical specialists without formal knowledge transfer protocols.
- Permitting timeline compression:EPA mining waste standards extend extraction authorization cycles, freezing capital deployment for greenfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feldspar and Nepheline Syenite Market |
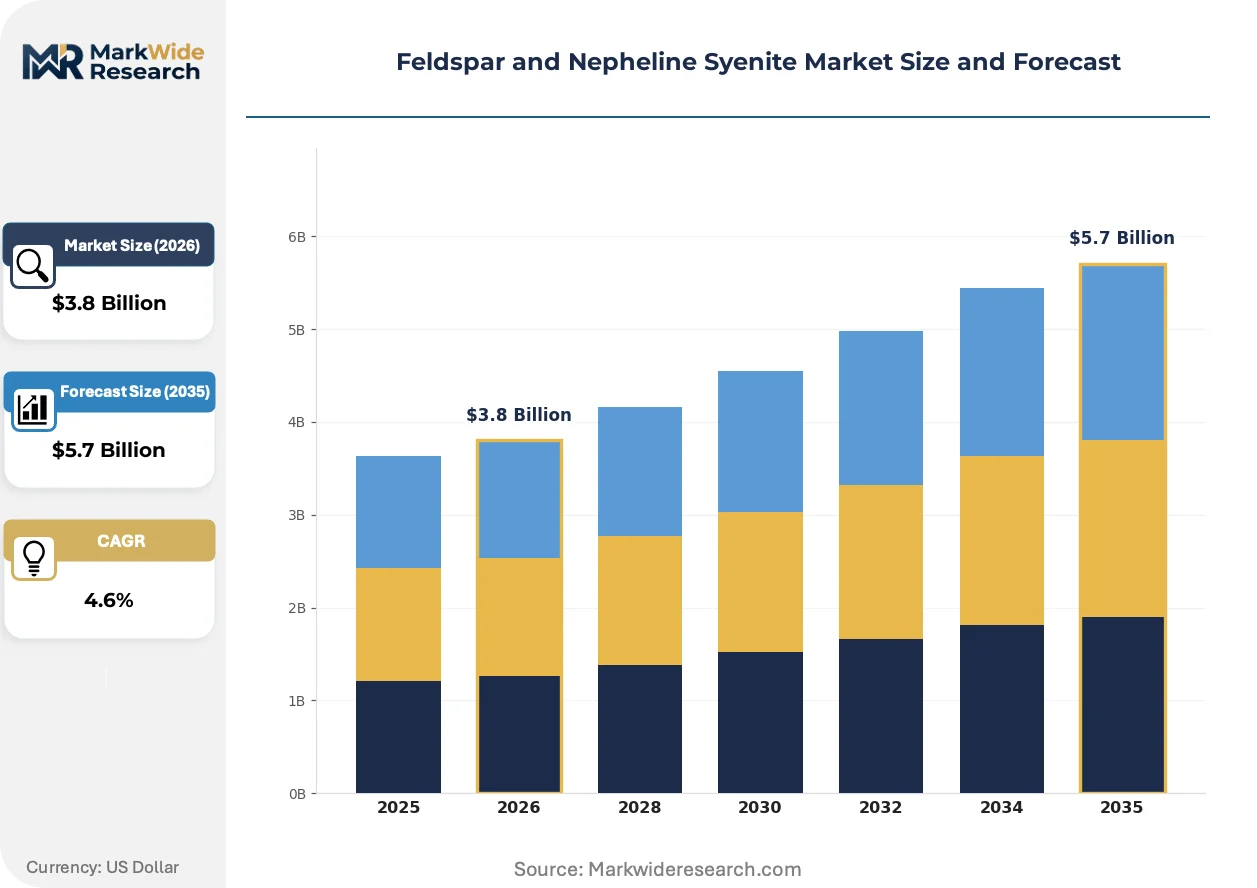
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feldspar, Nepheline Syenite, Quartz, Clay End Use Industry: Ceramics, Glass, Paints, Plastics Form: Powder, Granules, Lumps, Slurries Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Covia Holdings LLC, Pacer Minerals, SCR-Sibelco NV, Minerali Industriali S.r.l., FINETON Industrial Minerals Limited, Imerys, I-Minerals Inc, Anglo Pacific Minerals, The QUARTZ Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feldspar and Nepheline Syenite Market Emerging Trajectories
Digital process control and regulatory carbon accounting are rewriting specification standards across glass and ceramics value chains, compressing traditional quality premiums.
Dry magnetic separation coupled with sensor-based ore sorting is hybridizing traditional wet beneficiation flowsheets. Mid-tier processors in Belgium and France deploy these retrofits to meet optical-grade nepheline syenite contracts. The technology is hybridizing margin structures, separating automated operations from manual sorting-dependent competitors.
REACH authorization requirements for crystalline silica content are tightening occupational exposure thresholds across EU member states. Ceramic tile manufacturers face reformulation pressures to reduce respirable quartz in workplace environments. Spanish and Italian producers accelerate nepheline syenite substitution in body compositions to preempt ECHA restriction proposals.
Specification-driven purchasing contracts now dominate glass manufacturer procurement, displacing spot-market feldspar sourcing. Turkish float glass producers lock multi-year nepheline syenite offtake with guaranteed alumina floors. This contracting shift concentrates volume allocation among integrated logistics networks with dedicated silo infrastructure.
Feldspar and Nepheline Syenite Market Segmentation
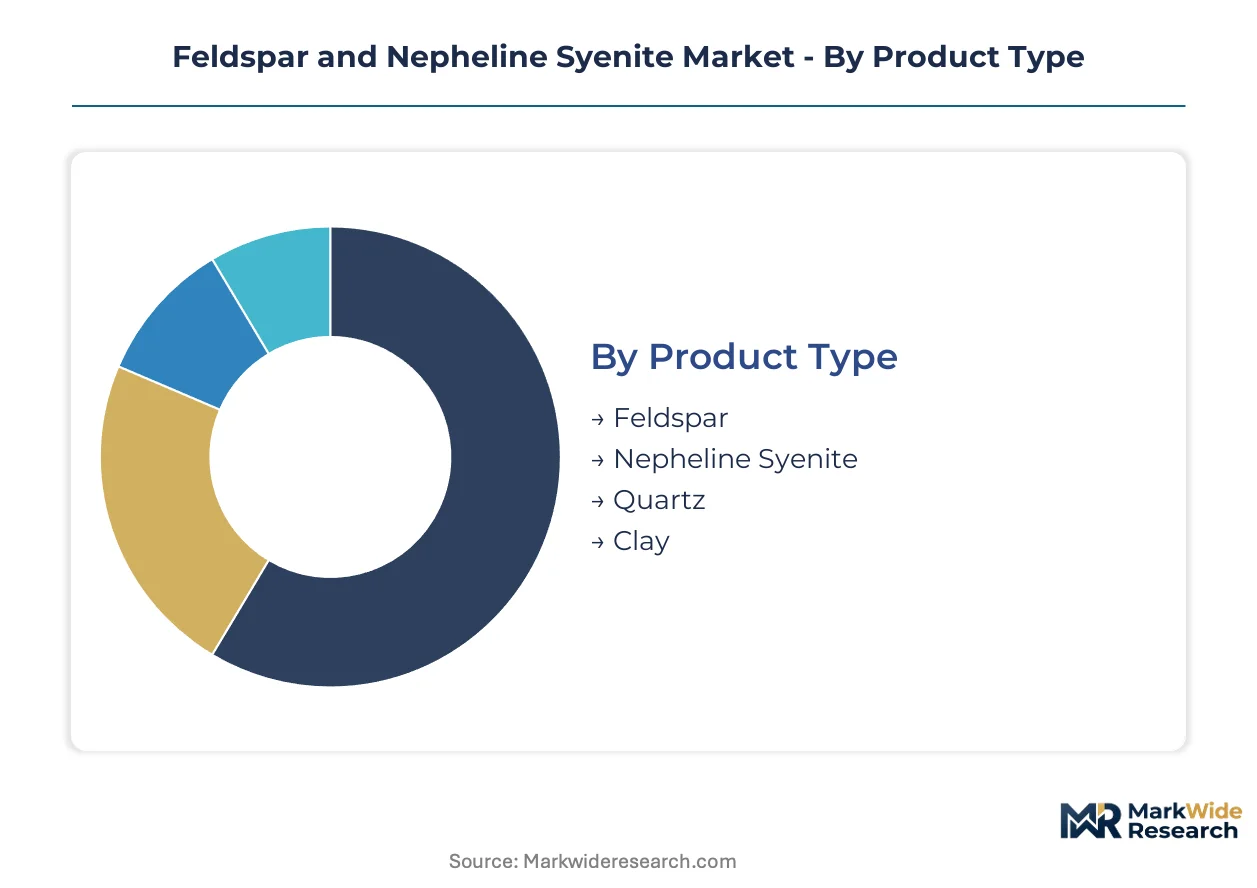
Segmentation in feldspar and nepheline syenite markets separates specification-driven glass contracts from commodity ceramic fluxing. Technical purity requirements and pneumatic handling constraints create divergent margin structures across product grades and delivery forms.
Product Type:
After-sales service intensity concentrates around beneficiation technical support and REACH registration maintenance for European ceramic manufacturers.
- Feldspar:Alkali aluminosilicate minerals with K2O content between 10% and 12% function as primary fluxing agents. Indian tile manufacturers around Morbi drive consumption for vitrified tile production where sodium feldspar lowers vitrification temperatures.
- Nepheline Syenite:Lower silica and higher alumina ratios than standard feldspar suit reduced-iron glass formulations. Turkish float glass producers lock multi-year offtake contracts with alumina floor guarantees for furnace energy efficiency compliance.
- Quartz:High-purity silica source for specialty glass and engineered stone applications.
- Clay:Kaolinitic and illitic varieties serve ceramic body plasticity requirements.
By volume, feldspar leads. By growth pace, nepheline syenite is ahead.
End Use Industry:
Application-specific beneficiation costs determine margin tiering across end-use segments.
- Ceramics:Tile and sanitaryware manufacturing consumes standard-grade feldspar as fluxing agents in continuous kiln operations. India's Morbi ceramic belt concentrates alkali feldspar demand for vitrified tile production.
- Glass:Optical-grade nepheline syenite specifications command premium placement in display glass and lithium-aluminosilicate substrates. Turkish manufacturers expanding float glass capacity create uncontracted demand for European suppliers with Bosphorus logistics access.
- Paints:Extender and filler applications in industrial coatings.
- Plastics:Functional filler for engineering polymer reinforcement.
Ceramics dominates volume throughput. Glass captures the steepest expansion trajectory.
Form:
Handling infrastructure investments separate automated pneumatic systems from manual batch operations.
- Powder:Pneumatic conveying efficiency in continuous kiln operations makes this the default for large-scale ceramic and glass manufacturers. Mid-tier processors in Belgium and France deploy dry magnetic separation retrofits to meet optical-grade nepheline syenite powder contracts.
- Granules:Controlled particle size distribution suits specialty glass batching where segregation resistance matters.
- Lumps:Raw feed for captive beneficiation at integrated ceramic plants.
- Slurries:Pumpable form for wet process ceramic body preparation.
Powder form leads volume. Granules gain share fastest in premium glass specifications.
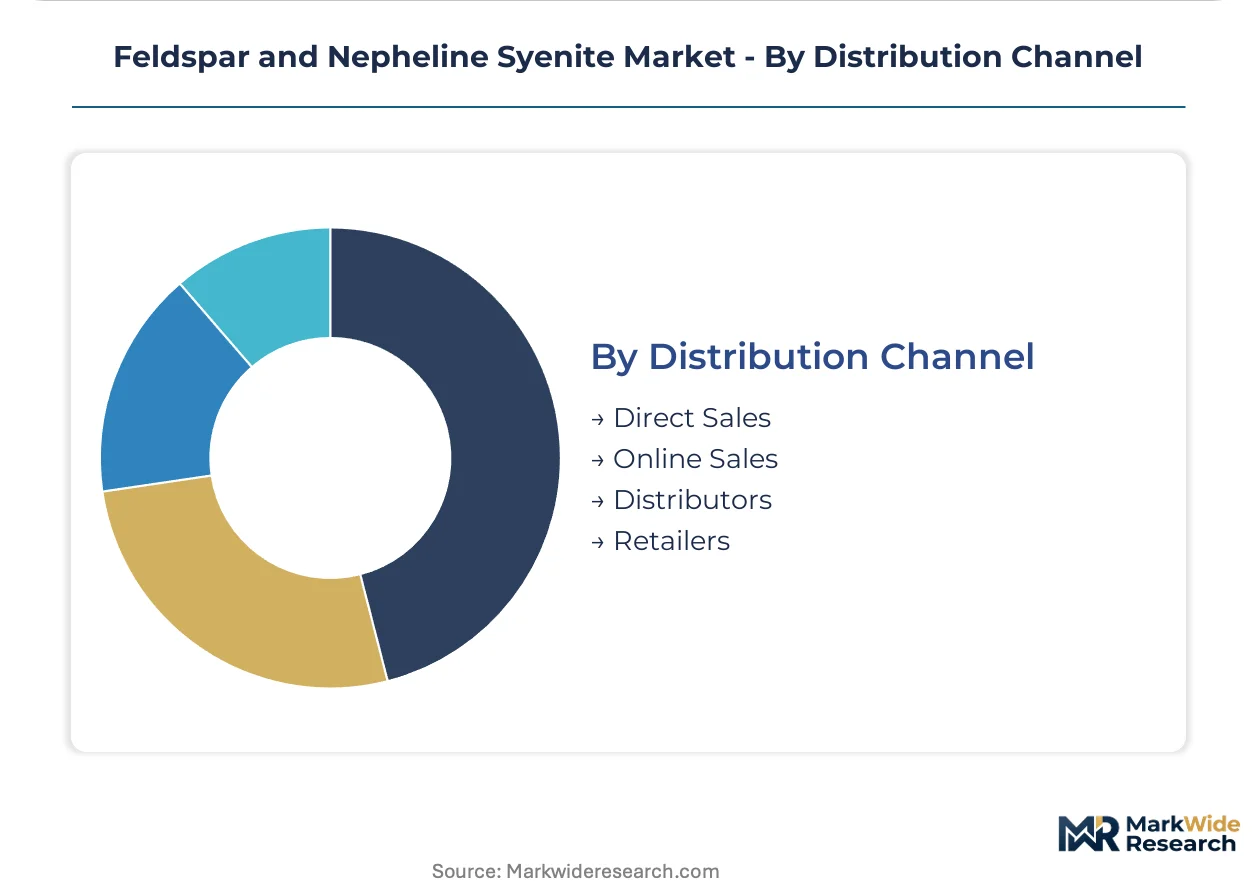
Distribution Channel:
Customer scale and specification complexity dictate channel selection across procurement tiers.
- Direct Sales:Multi-year specification-driven contracts with guaranteed alumina floors now dominate glass manufacturer procurement. Turkish float glass producers bypass spot markets for integrated logistics networks with dedicated silo infrastructure.
- Distributors:Regional stocking points serve mid-tier ceramic producers without captive storage.
- Online Sales:Limited to standard-grade technical specifications with certified analysis documentation.
- Retailers:Small-lot sales for artisanal ceramics and specialty applications.
Direct sales commands volume leadership. Distributors show the fastest channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Turkish glass manufacturers favor nepheline syenite for furnace efficiency compliance, while Indian ceramic clusters drive alkali feldspar volumes for vitrified tile production. European REACH registration requirements reshape sourcing decisions.
Turkey
Float glass capacity expansion along the Bosphorus corridor drives uncontracted nepheline syenite demand. Turkish manufacturers lock multi-year offtake agreements with alumina floor guarantees to meet furnace energy efficiency mandates. The Izmir industrial zone concentrates glass batching operations requiring premium fluxing materials.
India
The Morbi ceramic belt in Gujarat consumes substantial alkali feldspar volumes for vitrified tile fluxing. Bureau of Indian Standards certification requirements tighten raw material quality benchmarks for export-oriented manufacturers. Rajasthan's mining districts supply sodium feldspar to continuous kiln operations across western India.
United States
Appalachian high-purity feldspar deposits sustain North American glass and ceramics supply. EPA mining waste standards extend extraction permitting timelines, freezing capital deployment for greenfield projects. Pennsylvania and North Carolina processing facilities serve domestic manufacturers with pneumatic powder handling infrastructure.
Belgium
Integrated logistics networks anchor European ceramics demand through ECHA-registered processing streams. REACH authorization requirements for crystalline silica content tighten occupational exposure thresholds across EU member states. The Antwerp-Rotterdam port complex facilitates bulk nepheline syenite distribution to German and French tile manufacturers.
China
GB standards for ceramic raw materials set export-quality benchmarks that non-Chinese suppliers must meet for Asian market access. Lithium-aluminosilicate glass substrate production drives optical-grade nepheline syenite consumption in eastern provinces. Shandong and Jiangsu beneficiation facilities supply domestic float glass and display panel manufacturers.
Feldspar and Nepheline Syenite Market Vendor Landscape
Capability concentration sits with integrated processors holding captive nepheline syenite reserves; scale advantage sits with diversified mineral conglomerates with multi-site logistics networks. The market structures around three archetypes: Appalachian deposit holders with high-purity feldspar leverage, European ceramics-integrated processors with REACH registration maintenance, and Nordic anorthosite-nepheline specialists serving carbon-accounted supply chains. Dominant competitive moves include dry magnetic separation retrofits for optical-grade specifications and dedicated silo infrastructure investments for multi-year glass contracts.
Among North American deposit holders, Covia Holdings LLC exemplifies integrated supply leadership through Appalachian reserve quality. European ceramics demand flows through SCR-Sibelco NV, which occupies a position within ECHA-registered processing networks across Belgium and France. Imerys represents the diversified mineral conglomerate archetype with multi-commodity logistics scale serving glass and ceramics manufacturers.
| Leading Market Players |
|---|
| Covia Holdings LLC |
| Pacer Minerals |
| SCR-Sibelco NV |
| Minerali Industriali S.r.l. |
| FINETON Industrial Minerals Limited |
| Imerys |
| I-Minerals Inc |
| Anglo Pacific Minerals |
| The QUARTZ Corp |
| Others |
Supply Flow & Price Mechanics
Appalachian high-purity feldspar deposits concentrate North American supply leverage among integrated processors, compressing margin pools toward beneficiation technical support and REACH registration maintenance downstream. Turkish glass manufacturers lock multi-year offtake agreements with alumina floor guarantees, displacing spot-market pricing power for powder-form distributors without dedicated silo infrastructure.
Pricing Analysis
Long-term offtake contracts with guaranteed alumina specifications now dominate glass manufacturer procurement, displacing spot-market feldspar sourcing. Price differentiation hinges on optical-grade nepheline syenite certification for display glass applications and pneumatic handling infrastructure for continuous kiln operations. Pricing pressure stems from synthetic fluxing agent substitution in cost-sensitive sanitaryware segments. Mid-tier ceramic producers exhibit highest price sensitivity; premium glass manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities concentrate working capital burdens on mid-tier processors without integrated logistics networks. Raw material sourcing draws from Appalachian feldspar reserves, Nordic anorthosite-nepheline deposits, and Rajasthan sodium feldspar districts. Beneficiation equipment dependencies include magnetic separation systems and sensor-based ore sorting technology. Single-source vulnerability concentrates around aging magnetic separation engineering expertise without formal knowledge transfer protocols. Distribution runs through Antwerp-Rotterdam port complexes for European ceramics manufacturers and Bosphorus logistics corridors for Turkish glass producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-driven procurement platforms are redefining competitive moats around REACH registration databases and pneumatic handling infrastructure interoperability. ECHA-registered processing networks function as gatekeeper platforms, with data portability between ceramic tile body formulation systems becoming the ecosystem inflection point.
For Market Incumbents: Entrench platform control by deepening ECHA registration maintenance capabilities and deploying dry magnetic separation retrofits for optical-grade nepheline syenite contracts. Synthetic fluxing agent substitution in sanitaryware segments threatens standard-grade feldspar volumes; backward integration into captive nepheline syenite reserves in Nordic deposits secures alumina-to-silica ratio compliance for furnace energy efficiency mandates.
For New Entrants and Emerging Players: Pursue uncontracted demand from Turkish float glass capacity expansion along the Bosphorus corridor, where European suppliers with dedicated silo infrastructure face logistics constraints. The Morbi ceramic belt in India offers penetrable white space for alkali feldspar distributors with Bureau of Indian Standards certification capabilities. A technical service-led go-to-market approach around beneficiation process design addresses the talent scarcity among aging magnetic separation specialists.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated processors with captive nepheline syenite reserves and established ECHA-registered logistics networks across Belgium and France. Long-term viability over the coming decade rests on carbon-accounted beneficiation routes from Nordic anorthosite-nepheline deposits aligning with EU Green Deal carbon border adjustment mechanisms. The signal to monitor is EPA mining waste standard enforcement tightening, which would extend extraction permitting timelines and freeze greenfield capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Appalachian and Nordic deposit control secures alumina specification compliance for glass furnace mandates. |
| REACH Registration Network Expansion | ECHA-registered processing streams in Belgium and France create captive demand from restricted importer qualification pathways. |
| Dry Magnetic Separation Retrofit Deployment | Automated beneficiation technology in Belgian and French mid-tier processors meets optical-grade nepheline syenite contracts. |
| Dedicated Silo Infrastructure Investment | Pneumatic powder handling systems lock multi-year offtake agreements with Turkish float glass manufacturers. |
| Carbon-Accounted Beneficiation Route Development | Low-carbon processing from Nordic anorthosite-nepheline deposits aligns with EU Green Deal carbon border adjustments. |
Methodological Framework
A spread of perspectives from glass furnace operations managers, ceramic tile plant engineers, ECHA regulatory affairs specialists, and nepheline syenite procurement directors converged on the working assumptions around specification-driven contract structures. Primary fieldwork combined with secondary validation from SEC filings of integrated mineral processors, USGS mineral commodity summaries, ECHA registration databases, and Turkish Statistical Institute glass production data. Bottom-up volume modeling across product grades and end-use segments triangulated against top-down macroeconomic drivers.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product type, end-use industry, form factor, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for furnace energy efficiency mandate acceleration and synthetic fluxing substitution elasticity. Forecast inputs incorporated alumina-to-silica ratio specification tightening and pneumatic handling infrastructure deployment rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified mineral conglomerates or rapid EPA permitting timeline compression would shift outcomes. Macroeconomic deviation in natural gas pricing, ECHA crystalline silica restriction acceleration, or breakthrough synthetic fluxing cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Iran Ceramic Tiles Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Ceramics Packaging Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Aluminium Nitride Market
Ceramics
White Fused Alumina Market
Ceramics
Earthenware Market
Ceramics
India Kaolin Market
Ceramics
Mullite Market
Ceramics
Kaolin Market
Ceramics
Potassium Feldspar Market
Ceramics
Calcite Market
Ceramics
Cerium Carbonate Market
Ceramics
Advanced Ceramics Market