
 South Korea Ceramic Sanitaryware Market | 2026-2036
South Korea Ceramic Sanitaryware Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Ceramic Sanitaryware Market Analytics
Aftermarket service revenue is fragmenting across installation, maintenance, and replacement scheduling as manufacturers compete for recurring customer touchpoints. Daelim Bath leverages its domestic production network to sustain rapid fulfillment timelines for Seoul-area contractors. Roca Sanitario S.A anchors its position through European design positioning while Corona competes on value-engineered product lines for mid-market residential developers.
South Korea ceramic sanitaryware encompasses vitreous china and porcelain fixtures manufactured through slip casting, high-pressure casting, and glazing processes fired above 1,200°C, primarily serving bathroom sanitation and hygiene functions in built environments. The toilets segment dominates volume as water-efficiency mandates from Korea's Ministry of Environment drive replacement of legacy high-flow models, while the commercial end-user category leads value growth through premium specification in hospitality and healthcare projects where durability standards exceed residential thresholds.
MFDS oversees material safety compliance for ceramic glazes and surface coatings, while KTL certification governs quality benchmarks for fixture performance and longevity, and the Ministry of Land, Infrastructure and Transport enforces building code provisions that dictate sanitaryware specifications in new construction and major renovations. Stakeholders must monitor how tightening water-efficiency thresholds and green building certification expansion reshape procurement criteria across South Korea's construction value chain.
Market Dynamics
Water-efficiency mandates from Korea's Ministry of Environment are compressing replacement cycles across Seoul's aging high-rise housing stock, forcing manufacturers to reconfigure product portfolios toward low-flow vitreous china designs.
Growth Catalysts
- MFDS glaze safety protocols:Stricter material compliance requirements for ceramic surface coatings are eliminating substandard imports and protecting domestic manufacturer margins.
- Seoul metropolitan redevelopment:Accelerated high-rise residential reconstruction in Gangnam and Yeongdeungpo districts is generating concentrated fixture replacement demand.
- KTL performance certification:Quality benchmarking for fixture longevity creates procurement preference hierarchies that favor certified domestic producers in public housing tenders.
Market Restraints
- Kaolin supply concentration:Dependence on specific clay deposits creates input cost volatility when mining disruptions occur in primary sourcing regions.
- Legacy high-flow inventory:Existing stockpiles of pre-mandate toilet designs create channel friction as distributors clear non-compliant units.
- Technical glazing limitations:Current surface coating chemistry restricts color range expansion for premium residential specifications.
Strategic Opportunities
- Busan-Ulsan corridor:Underpenetrated commercial construction in Korea's southeastern industrial belt offers hospitality and healthcare specification growth.
- Smart fixture convergence:Integration of sensor-activated flush mechanisms with ceramic bases creates premium positioning in luxury residential developments.
- Green building certification expansion:Ministry of Land, Infrastructure and Transport incentives for zero-energy buildings drive specification of water-efficient sanitaryware in new commercial projects.
Industry Challenges
- Artisan caster scarcity:Skilled slip-casting technicians are aging out faster than vocational training programs replenish the workforce.
- Kiln modernization capex:Transitioning from traditional tunnel kilns to energy-efficient roller-hearth systems demands substantial capital commitment from mid-tier producers.
- MFDS certification timelines:Extended testing protocols for new glaze formulations delay product launch windows by multiple quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Ceramic Sanitaryware Market |
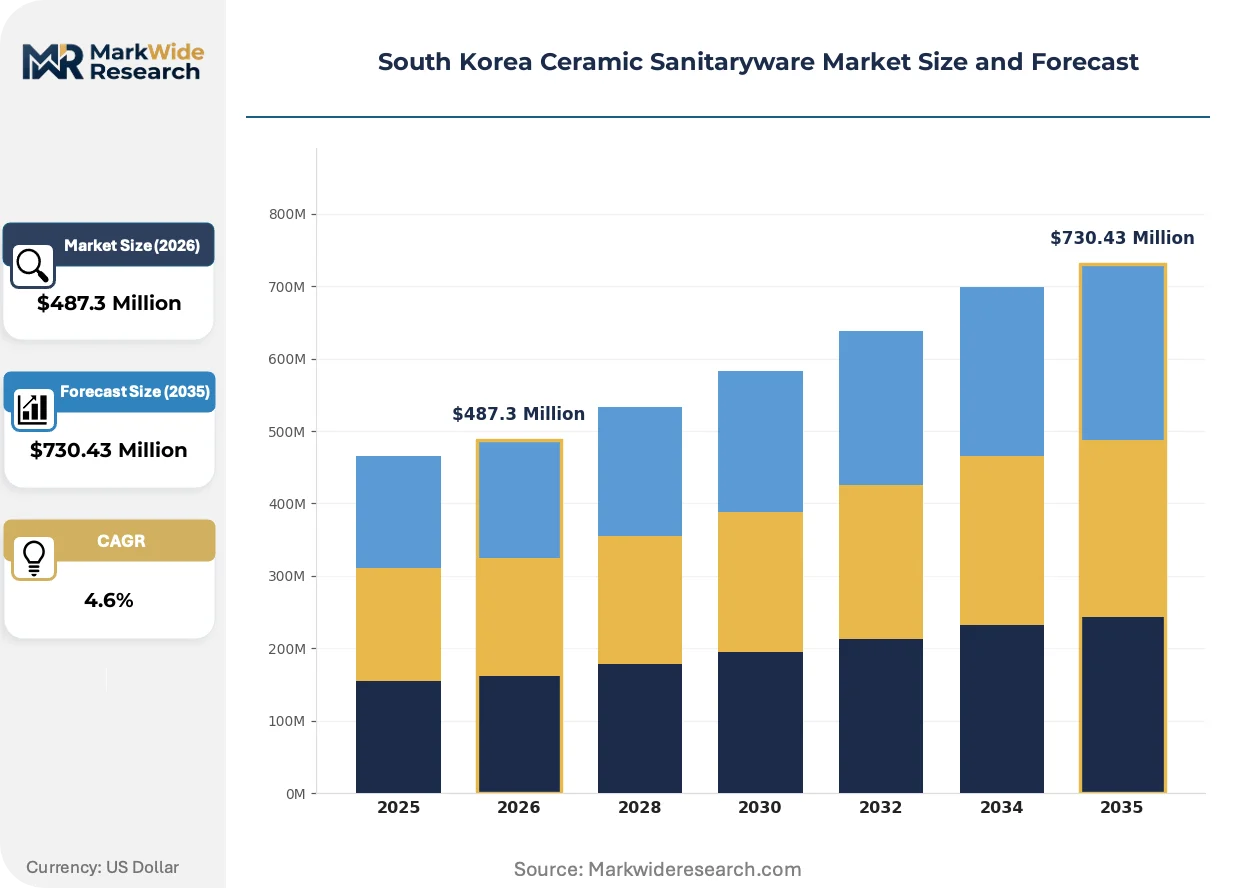
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Sinks, Bidets, Urinals End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Online, Retail, Wholesale, Direct Sales Design Style: Modern, Traditional, Contemporary, Minimalist |
| Companies Covered | Corona, Saturn Bath Co. Ltd., American Standard, Daelim Bath, Acrofluid, Jaquar Group, CERA Sanitaryware Limited, Roca Sanitario S.A, Inus Bath, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Ceramic Sanitaryware Market Evolving Landscape
Digital design tools and connected fixture technologies are reconfiguring how Korean manufacturers prototype, produce, and position sanitaryware across residential and commercial channels.
High-pressure casting automation is virtualizing the traditional slip-casting workflow by replacing manual mold-filling with computer-controlled pressure injection. Large-scale producers in Gyeonggi Province are adopting these systems to compress production cycles and reduce dimensional variance. The technology is virtualizing quality control checkpoints by embedding real-time thickness sensors that eliminate post-fire inspection bottlenecks.
Korea's Ministry of Environment has tightened water-efficiency labeling thresholds, requiring all new toilet installations to meet stricter liter-per-flush standards. Manufacturers must redesign trapway geometries and bowl profiles to maintain performance at reduced flow rates. The regulation most affects mid-market residential developers who previously specified transitional-efficiency models.
Aftermarket service unbundling is fragmenting the traditional supply relationship as contractors seek separate installation, maintenance, and replacement scheduling contracts. Seoul-area property management firms are consolidating vendor relationships around full-lifecycle service providers. This pattern concentrates in the capital's dense apartment complexes where fixture failure rates accelerate replacement demand.
South Korea Ceramic Sanitaryware Market Segmentation
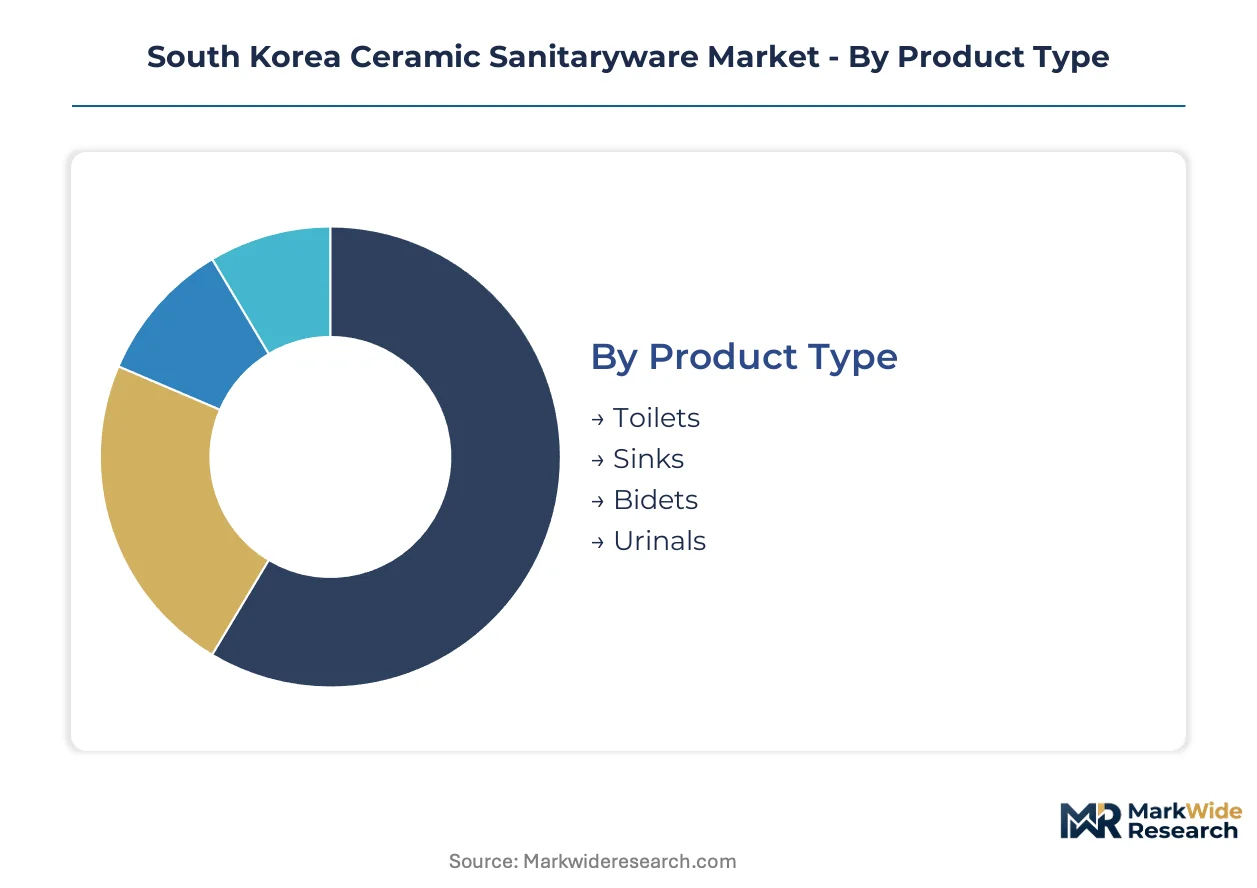
South Korea's ceramic sanitaryware market fragments across four distinct dimensions, each reflecting different procurement hierarchies and specification drivers. Product type segmentation tracks water-efficiency compliance cycles, while end-user categories separate volume-driven residential replacement from premium commercial specification.
Product Type:
Functional requirements span the full bathroom fixture spectrum, from high-frequency flush mechanisms to specialized hygiene appliances.
- Toilets:Vitreous china bowls with trapway geometries engineered for Ministry of Environment liter-per-flush mandates dominate Seoul's high-rise redevelopment pipeline. Gangnam district contractors specify these units in volume for aging apartment complex renovations where legacy high-flow models face mandatory replacement.
- Sinks:Countertop and wall-mounted basins manufactured through high-pressure casting processes serve both residential vanity installations and commercial restroom specifications. Demand concentrates in Yeongdeungpo district hospitality retrofits where European design influences drive premium vessel sink adoption.
- Bidets:Integrated ceramic-electronic hybrid fixtures combine heated seating with water spray functionality for residential wellness positioning.
- Urinals:Wall-hung vitreous china units with sensor-activated flush systems target commercial and institutional specifications where water conservation benchmarks exceed residential thresholds.
Established volume favors Toilets; emerging adoption favors Bidets.
End User:
Procurement authority separates individual homeowners from institutional specification committees with divergent performance criteria.
- Residential:Individual homeowners and apartment owner associations drive replacement cycles through bathroom renovation projects. MFDS glaze safety protocols and KTL certification requirements filter product eligibility for Seoul metropolitan area housing stock upgrades.
- Commercial:Office building developers and facility managers specify durability-rated fixtures for high-traffic restrooms. This category captures the steepest expansion trajectory as Busan-Ulsan corridor hospitality and healthcare construction accelerates premium sanitaryware procurement.
- Hospitality:Hotel operators and resort developers prioritize design differentiation alongside water-efficiency compliance for guest bathroom specifications.
- Healthcare:Hospital construction consortia mandate infection-control surface finishes and hands-free operation for clinical and patient restroom environments.
Volume procurement concentrates in Residential; specification value climbs fastest in Commercial.
Distribution Channel:
Channel selection reflects purchase scale, technical consultation needs, and delivery timeline constraints across the construction value chain.
- Online:E-commerce platforms serve individual homeowners researching water-efficiency ratings and design options for small-scale replacement purchases. Seoul's dense apartment population drives concentrated demand for direct-to-consumer fixture delivery with installation service bundling.
- Retail:Showroom networks provide tactile product evaluation for residential renovation contractors and owner-occupiers. Gyeonggi Province retail clusters anchor mid-market specification where visual merchandising influences design selection.
- Wholesale:Distributor networks aggregate volume procurement for multi-unit residential developers and commercial general contractors.
- Direct Sales:Manufacturer field teams engage large-scale project developers with customized specification support and lifecycle service contracts.
Transaction volume flows through Retail; contract value concentrates in Direct Sales.
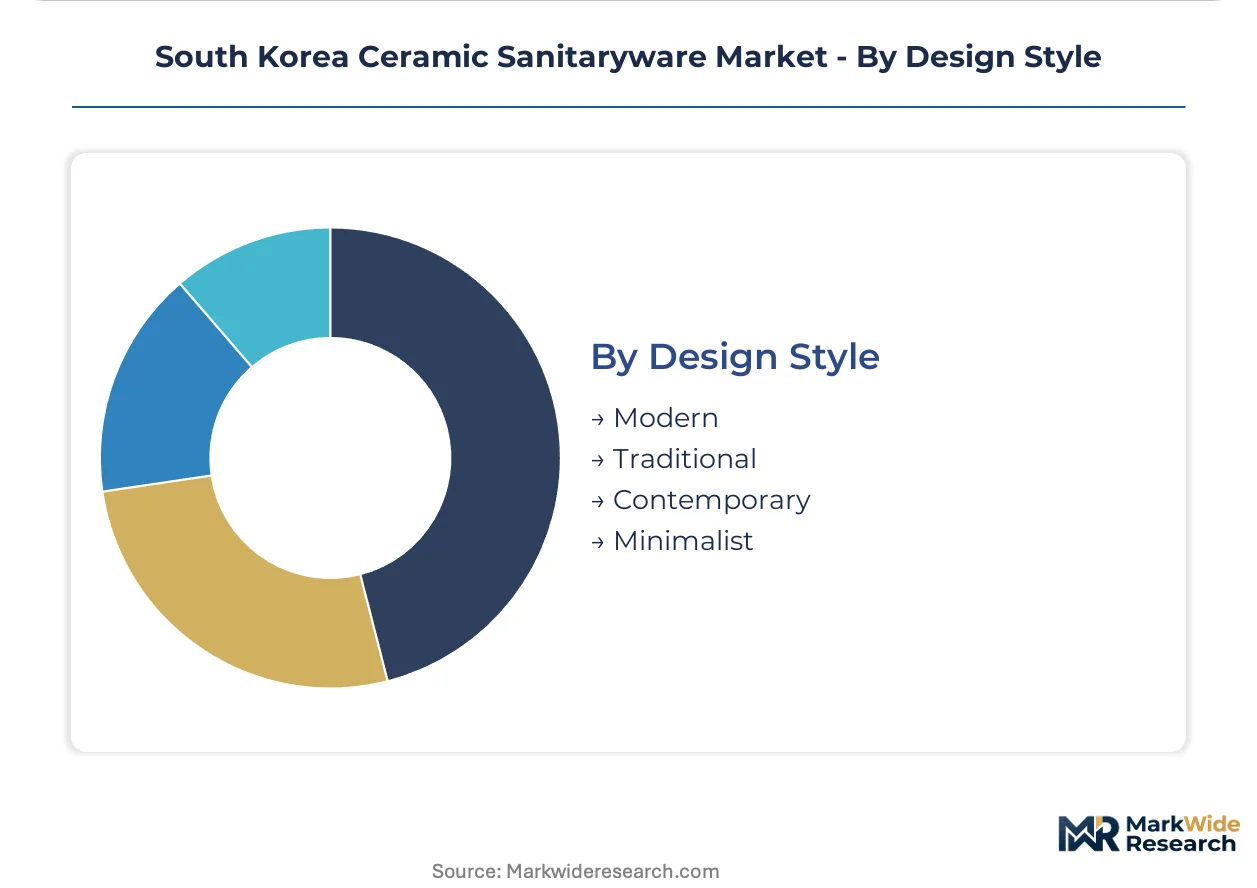
Design Style:
Aesthetic positioning separates premium specification opportunities from commodity replacement demand in Seoul's design-conscious construction market.
- Modern:Clean-lined geometries with concealed mounting systems and monochromatic finishes dominate Gangnam luxury residential developments. European-influenced positioning commands specification preference in high-end apartment reconstruction projects.
- Contemporary:Transitional forms blending softened edges with functional minimalism serve mid-market residential developers seeking broad appeal.
- Traditional:Ornate pedestal designs and decorative detailing retain niche specification for heritage property restoration and conservative institutional clients.
- Minimalist:Extreme reduction of visual mass with wall-hung configurations and integrated controls targets boutique hospitality and architect-driven residential projects.
Specification frequency favors Modern; margin expansion potential sits with Minimalist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South Korea's ceramic sanitaryware market. Seoul's luxury apartment reconstruction commands premium specifications with minimal buyer resistance, while mid-market residential developers in secondary cities face acute margin pressure from water-efficiency compliance costs.
Seoul Capital Area
Gangnam and Yeongdeungpo districts drive concentrated replacement demand through high-rise apartment reconstruction projects. MFDS glaze safety protocols filter product eligibility for bathroom renovation tenders. Domestic manufacturers cluster in Gyeonggi Province to maintain rapid fulfillment timelines for Seoul-area contractors.
Busan-Ulsan Corridor
Hospitality and healthcare construction in Korea's southeastern industrial belt generates premium specification opportunities. Ministry of Land, Infrastructure and Transport building code provisions mandate water-efficient sanitaryware in new commercial developments. Local distributors serve Busan's port-adjacent hotel construction pipeline with imported European design lines.
Daegu-Gyeongbuk
Mid-market residential developers in this manufacturing-heavy region prioritize cost-engineered fixtures for apartment complex construction. KTL certification requirements shape procurement hierarchies in public housing tenders. Daegu-based contractors source from regional distribution hubs to minimize logistics costs on volume projects.
Daejeon-Sejong
Government administrative relocation to Sejong City stimulates institutional construction with standardized fixture specifications. Ministry of Environment water-efficiency labeling thresholds apply uniformly to public building procurement. Daejeon serves as a logistics node connecting Gyeonggi production to central region construction sites.
Gwangju-Honam
Agricultural economy constraints limit premium penetration in this southwestern region. Residential renovation activity concentrates in aging urban housing stock rather than new construction. Gwangju-based retailers stock economy-tier products aligned with local purchasing power and replacement-driven demand patterns.
South Korea Ceramic Sanitaryware Market Competitive Landscape
Domestic production specialists and European design importers split the market along price-performance vectors. The vendor base concentrates around three strategic tiers: scale-driven domestic manufacturers with captive distribution, European design-positioned importers serving premium specification, and value-engineered specialists targeting mid-market residential developers. Competitive moves center on aftermarket service unbundling and smart fixture technology licensing rather than capacity expansion.
Among domestic producers, Daelim Bath and Inus Bath occupy positions as scale-driven specialists with established Gyeonggi Province manufacturing footprints. Roca Sanitario S.A anchors the European design-imported tier. Corona exemplifies value-engineered positioning for mid-market residential developers. These three represent distinct competitive archetypes rather than overlapping strategic profiles.
| Leading Market Players |
|---|
| Corona |
| Saturn Bath Co. Ltd. |
| American Standard |
| Daelim Bath |
| Acrofluid |
| Jaquar Group |
| CERA Sanitaryware Limited |
| Roca Sanitario S.A |
| Inus Bath |
| Others |
Value Network & Pricing Analysis
Kaolin supply concentration in specific clay mining regions creates input cost volatility that compresses margin spreads across premium, standard, and economy fixture tiers while forcing manufacturers toward captive sourcing or long-term offtake arrangements. This mineral dependency shapes procurement hierarchies as domestic producers absorb freight premiums to secure grade-consistent inputs, while importers face tariff exposure on finished goods that widens price differentials with locally certified alternatives.
Pricing Analysis
Aftermarket service contracts covering installation, maintenance, and replacement scheduling drive lifetime value capture beyond initial fixture sales. Three-tier pricing structure across premium, standard, and economy levels reflects KTL certification status and glaze safety compliance tier rather than raw material cost alone. Cost compression in the economy tier is intensifying because mid-market residential developers face acute margin pressure from Ministry of Environment water-efficiency retrofit mandates. Individual homeowners in Seoul's apartment reconstruction pipeline show least price sensitivity, while Daegu-Gyeongbuk volume contractors exhibit highest bid responsiveness.
Supply Chain Analysis
Tariff exposure between European design importers and South Korean distributors dominates supply chain risk assessment for premium specification channels. Domestic production draws from Gyeonggi Province manufacturing clusters, Chinese ceramic glaze component suppliers, and Southeast Asian kaolin deposits. Single-source vulnerability concentrates in specialized slip-casting mold fabrication where artisan technician scarcity limits supplier switching. Distribution runs through Seoul-area wholesale networks for volume projects, direct manufacturer field teams for large-scale developers, and retail showroom clusters for renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart fixture convergence with sensor-activated flush mechanisms and connected maintenance platforms is reconfiguring this market toward ecosystem economics where interoperability standards determine competitive survival. The shift from transactional fixture sales to lifecycle service contracts demands platform investments that few mid-tier producers can self-fund.
For Market Incumbents: Entrench market position by deepening backward integration into ceramic glaze formulation capabilities that shorten MFDS certification timelines, while consolidating installation service networks in Seoul's Gangnam and Yeongdeungpo reconstruction zones to capture recurring revenue streams. Artisan caster scarcity threatens production scaling; vocational training partnerships with Gyeonggi Province technical institutes represent the critical workforce lever. For New Entrants and Emerging Players: Mid-market commercial buildings in the Busan-Ulsan corridor represent the most penetrable entry point given underdeveloped hospitality specification networks and Ministry of Land, Infrastructure and Transport green building incentives. Healthcare construction consortia seeking infection-control surface finishes offer second-tier opportunity. A specification-led go-to-market approach partnering with EPC contractors on zero-energy building tenders bypasses entrenched wholesale channel control. For Investors and Strategic Acquirers: Domestic manufacturers with captive KTL-certified production and established Seoul metropolitan distribution density offer the strongest acquisition profile for portfolio exposure to replacement-cycle acceleration. Long-term viability hinges on smart fixture technology licensing capabilities and aftermarket service infrastructure. The signal to monitor is Ministry of Environment water-efficiency threshold tightening frequency, which compresses replacement cycles and expands addressable market volume.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Fixture Technology Licensing | Sensor-activated flush integration with ceramic bases commands premium positioning in Gangnam luxury developments. |
| Aftermarket Service Infrastructure Buildout | Full-lifecycle contracts with Seoul property management firms consolidate vendor relationships and recurring revenue. |
| Backward Integration into Glaze Formulation | In-house ceramic coating development accelerates MFDS compliance timelines and protects margin from input volatility. |
| High-Pressure Casting Automation Deployment | Gyeonggi Province producers compress production cycles while reducing dimensional variance through computer-controlled injection. |
| Green Building Certification Partnership | Collaboration with Ministry of Land, Infrastructure and Transport zero-energy building programs secures commercial specification preference. |
Research Methodology
Cross-validation between manufacturer production data and distributor inventory records anchors the qualitative findings on replacement cycle timing and specification preferences. Primary interviews with ceramic sanitaryware plant managers, Seoul-area renovation contractors, Gyeonggi Province retail showroom operators, and Ministry of Environment compliance officers combined with secondary validation from KTL certification databases, MFDS glaze safety filings, and Korea Institute of Construction Technology building permit records. Bottom-up demand modeling from apartment reconstruction unit counts and top-down market sizing from trade flow analysis were reconciled through iterative triangulation.
Calibration against historical water-efficiency mandate implementation patterns and high-rise residential reconstruction permit trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user category, distribution channel, and design style tier, with regional sub-cluster differentiation for Seoul metropolitan versus Busan-Ulsan corridor demand patterns. CAGRs were derived from regression analysis of replacement cycle compression rates and green building certification adoption curves, incorporating kiln capacity utilization rates and artisan workforce demographics as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, central bank policy rates affecting mortgage refinancing volumes, or kaolin commodity price spikes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology adoption S-curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Kilns Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Automotive Ceramics Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Cordierite Market
Ceramics
Vaterite Market
Ceramics
United States Ceramic Tiles Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
ME K-Feldspar Market
Ceramics
Zirconia Ceramics Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Transparent Ceramics Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Barium Carbonate Powder Market