
 Global Functional Ceramics Market | 2026-2036
Global Functional Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Ceramics Market Analysis
Market Context
Japan's electronic ceramics corridor is narrowing the supply gap for advanced dielectric components. Kyocera Corporation leverages decades of multilayer ceramic capacitor expertise to anchor premium sensor applications. Murata Manufacturing Co. Ltd dominates high-frequency ceramic filters for 5G infrastructure. CoorsTek Inc sustains North American supply security through captive alumina and silicon carbide processing.
Technical Definition and Segment Structure
Functional ceramics are engineered inorganic non-metallic materials formulated with precise stoichiometric control to deliver targeted electrical, magnetic, optical, or biological responses, typically fired at temperatures exceeding 1300°C to achieve full densification and phase purity. These materials serve as critical enabling substrates in semiconductor packaging, implantable medical devices, and energy conversion systems where metals and polymers fail. Electroceramics command the largest revenue pool due to ubiquity in capacitors and insulators, while bioceramics represent the fastest-expanding margin segment driven by orthopedic and dental implant demand. Ceramic matrix composites in aerospace thermal protection systems concentrate value through low-volume, high-certification-barrier supply relationships.
Regulatory Environment
The EU REACH regulation and RoHS directives restrict hazardous substances in electronic ceramics, compelling reformulation of lead-based piezoelectric compositions. Japan's METI enforces JIS standards for medical-grade bioceramics, while China's NMPA and GB standards govern implantable device materials. The US FDA and EPA jointly shape market access through biocompatibility testing mandates and emissions controls on ceramic powder processing. Stakeholders must monitor divergence between EU and Asian material certification timelines to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Electric vehicle power electronics is compressing thermal management requirements and forcing ceramic substrate suppliers to densify firing protocols. Material certification timelines under divergent regulatory regimes now determine inventory positioning more than production capacity.
Growth Catalysts
- EU Green Deal emissions mandates:Stricter automotive efficiency standards are compelling automakers to replace metal heat sinks with silicon carbide ceramic substrates in inverter modules.
- 5G infrastructure densification:Base station deployments across Japan and South Korea are pulling high-frequency dielectric ceramics for millimeter-wave filter arrays.
- China's dual carbon goals:Industrial furnace retrofits are accelerating demand for thermal shock-resistant alumina linings in steel and cement processing.
Market Restraints
- Raw material concentration:High-purity rare earth oxide supply chains concentrate in China's Jiangxi and Inner Mongolia processing zones.
- Energy cost volatility:Natural gas-fired tunnel kilns in Germany's ceramics corridor face input cost swings tied to EU energy market fluctuations.
- Technical substitution limits:Polymer-based thermal interface materials underperform above 200°C, locking ceramics into high-temperature niches but capping volume expansion in mid-range applications.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic ceramic substrate manufacturing incentives are opening captive supply opportunities for semiconductor packaging vendors.
- Additive manufacturing convergence:Binder jetting of technical ceramics is enabling complex geometries impossible with traditional isostatic pressing.
- US IRA clean energy credits:Advanced manufacturing tax provisions are subsidizing domestic silicon carbide wafer processing for grid-scale inverters.
Industry Challenges
- Pyrometallurgical expertise scarcity:Qualified kiln operators and ceramic engineers are retiring faster than vocational programs in Germany and Japan can replenish talent pipelines.
- Cross-border certification lag:EU REACH substance dossiers and China's GB standards update on asynchronous cycles, stranding reformulated piezoelectric compositions in customs.
- Legacy ERP integration friction:Digital twin adoption for firing process optimization requires bridging 1980s-era kiln control systems with modern MES platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Ceramics Market |
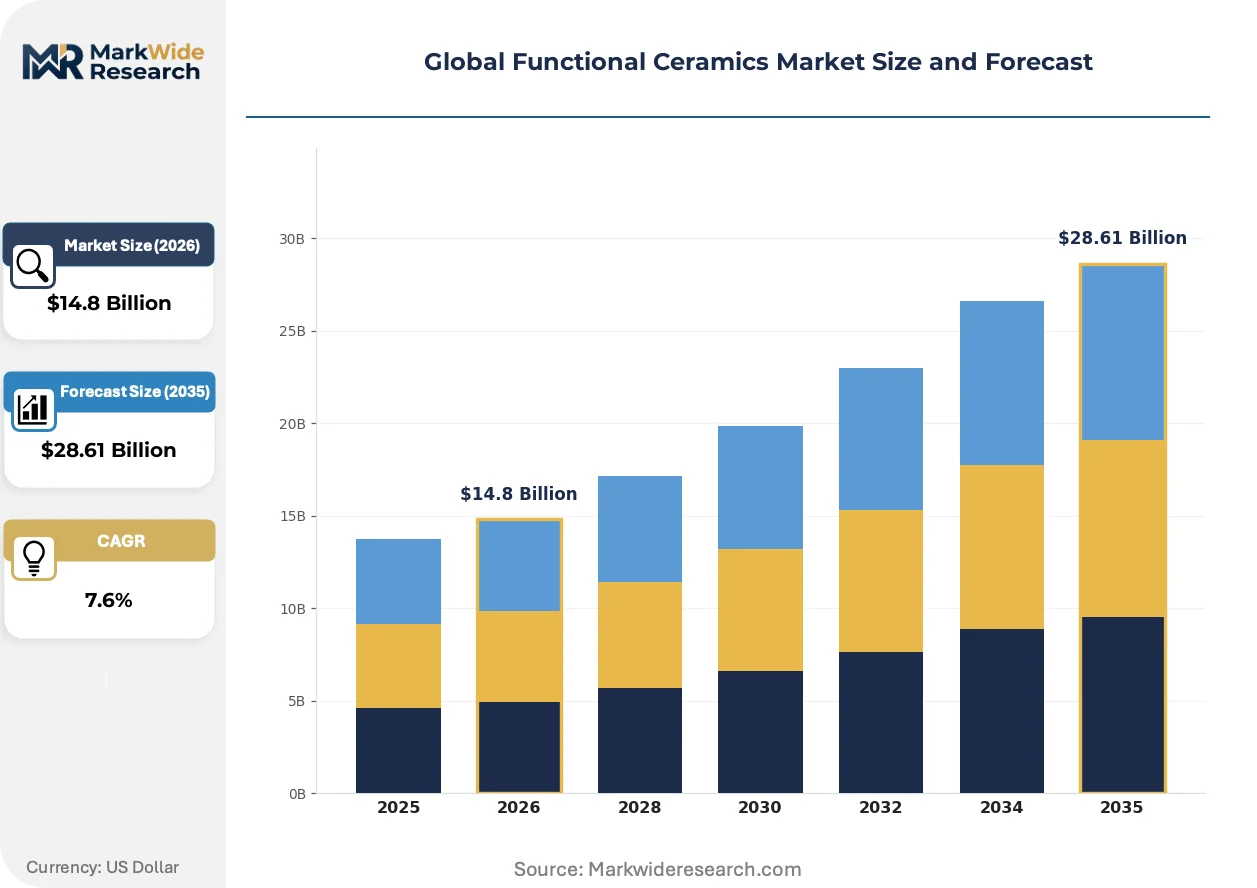
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroceramics, Bioceramics, Piezoelectric Ceramics, Magnetic Ceramics End Use Industry: Electronics, Aerospace, Healthcare, Automotive Form: Powder, Ceramic Matrix Composites, Thin Films, Coatings Technology: 3D Printing, Injection Molding, Pressing, Tape Casting |
| Companies Covered | 3M Company, NGK Spark Plug Co. Ltd, Morgan Advanced Materials, Saint-Gobain Ceramic Materials, CeramTec GmbH, Kyocera Corporation, AGC Ceramics Co Ltd, Murata Manufacturing Co. Ltd, CoorsTek Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Ceramics Market Emerging Trajectories
Process instrumentation and quality control systems are digitizing ceramic manufacturing from batch art to precision industry. Three developments are compressing development cycles and reshaping competitive positioning.
Machine vision and spectroscopic in-line monitoring is digitizing defect detection during sintering. Automotive power module suppliers in Japan are adopting real-time density mapping to reduce post-fire inspection waste. This capability is compressing qualification timelines for new substrate formulations from months to weeks.
REACH authorization requirements for lead-containing piezoelectrics are forcing reformulation of actuator ceramics across EU supply chains. Industrial automation OEMs are accelerating sodium bismuth titanate and potassium sodium niobate alternatives. Medical device manufacturers face the steepest compliance cost due to biocompatibility re-certification requirements.
Consolidated procurement through long-term offtake agreements is displacing spot purchasing for high-purity alumina powders. Japanese capacitor manufacturers are locking three-year supply contracts directly with Australian bauxite refiners. This pattern is most visible in electroceramic feedstocks where price volatility and quality consistency outweigh transaction flexibility.
Global Functional Ceramics Market Segmentation
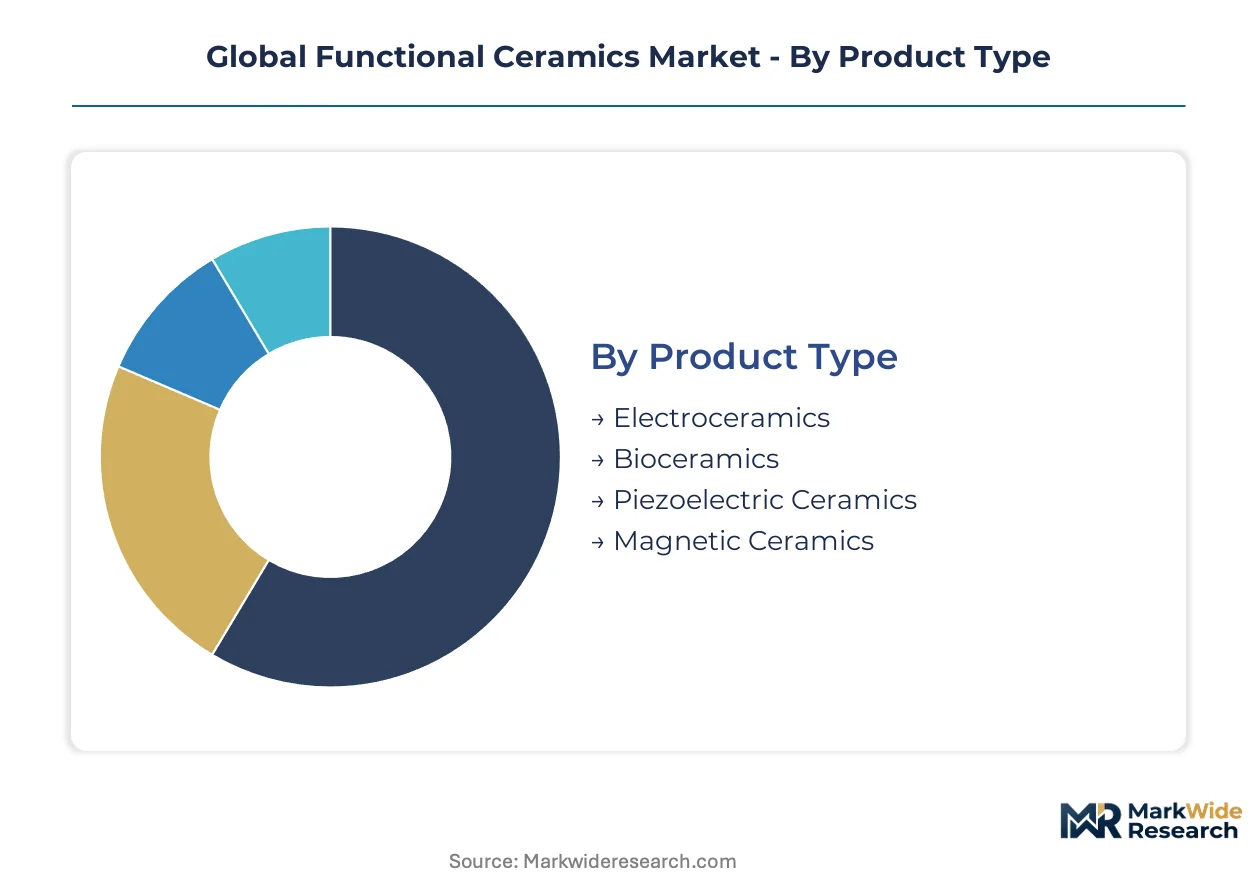
Segmentation in functional ceramics reveals how material specifications diverge across thermal, electrical, and biological performance requirements. Each dimension—product chemistry, end-use severity, physical form, and manufacturing precision—creates distinct competitive arenas with unique certification barriers and margin structures.
Product Type:
Mature electroceramic platforms anchor volume throughput while emerging bioceramic formulations capture accelerating medical device demand.
- Electroceramics:Dielectric and insulating compositions dominate multilayer capacitor and substrate applications. Demand concentrates in Japan's electronic component belt where 5G base station rollouts pull high-frequency formulations. Kyocera and Murata manufacturing ecosystems sustain premium pricing through proprietary firing protocols.
- Bioceramics:Hydroxyapatite and zirconia compositions serve orthopedic and dental implant applications. Japan's METI JIS standards and US FDA biocompatibility mandates create steep certification moats. Aging demographics in Germany and Japan are expanding joint replacement volumes faster than general industrial ceramics.
- Piezoelectric Ceramics:Lead zirconate titanate and emerging lead-free alternatives drive precision actuation in industrial automation and medical ultrasound.
- Magnetic Ceramics:Ferrite compositions enable inductors and transformers in power electronics and telecommunications infrastructure.
Electroceramics handle the majority of throughput; bioceramics is the fastest mover on share.
End Use Industry:
Cost tier stratification separates aerospace qualification premiums from automotive volume pricing and healthcare regulatory complexity.
- Electronics:Semiconductor packaging and passive component substrates demand sub-micron dimensional tolerance. Taiwan and South Korea foundry expansion is pulling high-purity alumina and silicon nitride substrates. Thermal management requirements in AI accelerator chips are densifying substrate architectures.
- Automotive:Silicon carbide power modules in EV inverters require thermal shock resistance above 300°C operating temperatures. EU Green Deal emissions mandates are accelerating ceramic heat sink adoption across German and French OEM supply chains. US Southeast manufacturing hubs are localizing substrate production to secure IRA clean energy credits.
- Aerospace:Ceramic matrix composites in thermal protection systems command low-volume, high-certification premiums. NASA and ESA qualification protocols create decade-long supplier lock-in.
- Healthcare:Implantable bioceramics face FDA, EMA, and Japan PMDA convergence pressures on biocompatibility testing timelines.
Electronics commands the widest supplier base; automotive is expanding most quickly as EV power electronics scale.
Form:
Supply concentration in high-purity powder processing creates upstream margin capture that downstream composite and coating fabricators must navigate.
- Powder:High-purity oxide and carbide precursors concentrate in China's Jiangxi rare earth processing zones and Australian bauxite refining corridors. Japanese capacitor manufacturers are locking three-year offtake agreements directly with refiners to secure consistency.
- Ceramic Matrix Composites:Carbon fiber-reinforced silicon carbide serves aerospace thermal protection and brake systems. Low-volume, high-certification production in Germany and US defense supply chains sustains premium positioning.
- Thin Films:Sputtered dielectric layers enable miniaturized MEMS and sensor applications in South Korean and Taiwanese electronics manufacturing.
- Coatings:Thermal barrier and wear-resistant layers extend component life in industrial turbine and tooling applications.
Powder handles the majority of throughput; ceramic matrix composites is the fastest mover on share.
Technology:
Customer type stratification separates precision medical and aerospace batch production from automotive and electronics volume manufacturing.
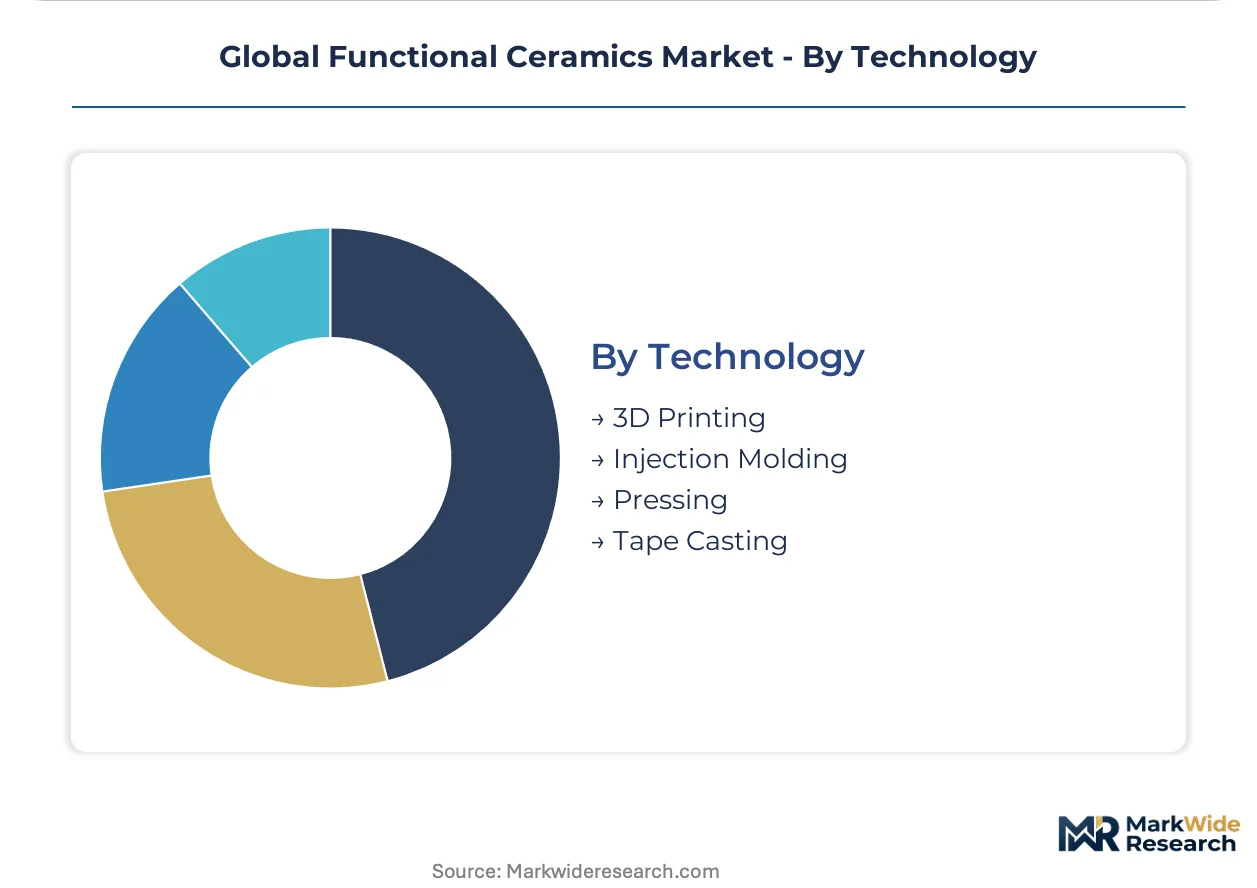
- 3D Printing:Binder jetting and stereolithography of technical ceramics enable geometries impossible with conventional forming. Complex cooling channels in aerospace turbine vanes and patient-specific orthopedic implants are early adoption centers. Germany's Fraunhofer institutes and US national laboratories anchor process development.
- Injection Molding:High-volume production of precision electroceramic components for automotive sensors and consumer electronics. Tooling amortization across millions of units creates steep economies of scale.
- Pressing:Isostatic and uniaxial compaction remain dominant for standard substrate and insulator geometries. German and Japanese equipment suppliers control precision press architecture.
- Tape Casting:Continuous sheet production enables multilayer capacitor and substrate lamination. Thickness uniformity below 10 micrometers separates premium from commodity supply tiers.
Pressing handles the majority of throughput; 3D printing is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's enforcement of JIS standards for medical-grade bioceramics anchors Japan's position in precision electroceramic manufacturing. Demand concentrates in Germany's industrial ceramics corridor, Japan's electronic component belt, and the US Southeast manufacturing hub.
United States
EV power electronics and AI accelerator chips are pulling silicon carbide substrates and high-purity alumina. The IRA's clean energy credits subsidize domestic silicon carbide wafer processing. The US Southeast manufacturing hub is localizing substrate production to secure supply chains for automotive OEMs.
Germany
Automotive efficiency mandates under the EU Green Deal are accelerating ceramic heat sink adoption in inverter modules. REACH authorization requirements for lead-containing piezoelectrics force reformulation of actuator ceramics. The industrial ceramics corridor faces energy cost volatility from natural gas-fired tunnel kilns.
China
Dual carbon goals are driving industrial furnace retrofits for thermal shock-resistant alumina linings. The NMPA and GB standards govern implantable device materials alongside emissions controls on ceramic powder processing. Jiangxi and Inner Mongolia processing zones concentrate high-purity rare earth oxide supply chains.
Japan
5G base station rollouts pull high-frequency dielectric ceramics for millimeter-wave filter arrays. METI enforces JIS standards for medical-grade bioceramics, creating steep certification moats. The electronic component belt sustains premium pricing through proprietary firing protocols at Kyocera and Murata manufacturing ecosystems.
South Korea
Foundry expansion for semiconductor packaging is pulling high-purity alumina and silicon nitride substrates. Thermal management requirements in AI accelerator chips are densifying substrate architectures. Seoul Capital Area electronics manufacturers concentrate demand for sub-micron dimensional tolerance components.
Global Functional Ceramics Market Vendor Landscape
Diversified industrial conglomerates and specialized ceramic fabricators split the market across distinct value capture tiers. Japanese electronics-focused manufacturers anchor premium electroceramic segments through captive material science expertise. German precision engineering houses dominate medical and industrial certification-intensive applications. Competitive moves center on backward integration into high-purity powder processing and geographic expansion into India PLI-subsidized electronics manufacturing zones.
Within the diversified conglomerate tier, 3M Company and Saint-Gobain Ceramic Materials occupy positions spanning multiple end-use verticals through broad material portfolios. Kyocera Corporation exemplifies the electronics-anchored specialist archetype with decades of multilayer ceramic capacitor expertise. CoorsTek Inc represents the North American supply security model through captive alumina and silicon carbide processing capabilities.
| Leading Market Players |
|---|
| 3M Company |
| NGK Spark Plug Co. Ltd |
| Morgan Advanced Materials |
| Saint-Gobain Ceramic Materials |
| CeramTec GmbH |
| Kyocera Corporation |
| AGC Ceramics Co Ltd |
| Murata Manufacturing Co. Ltd |
| CoorsTek Inc |
| Others |
Supply Flow & Price Mechanics
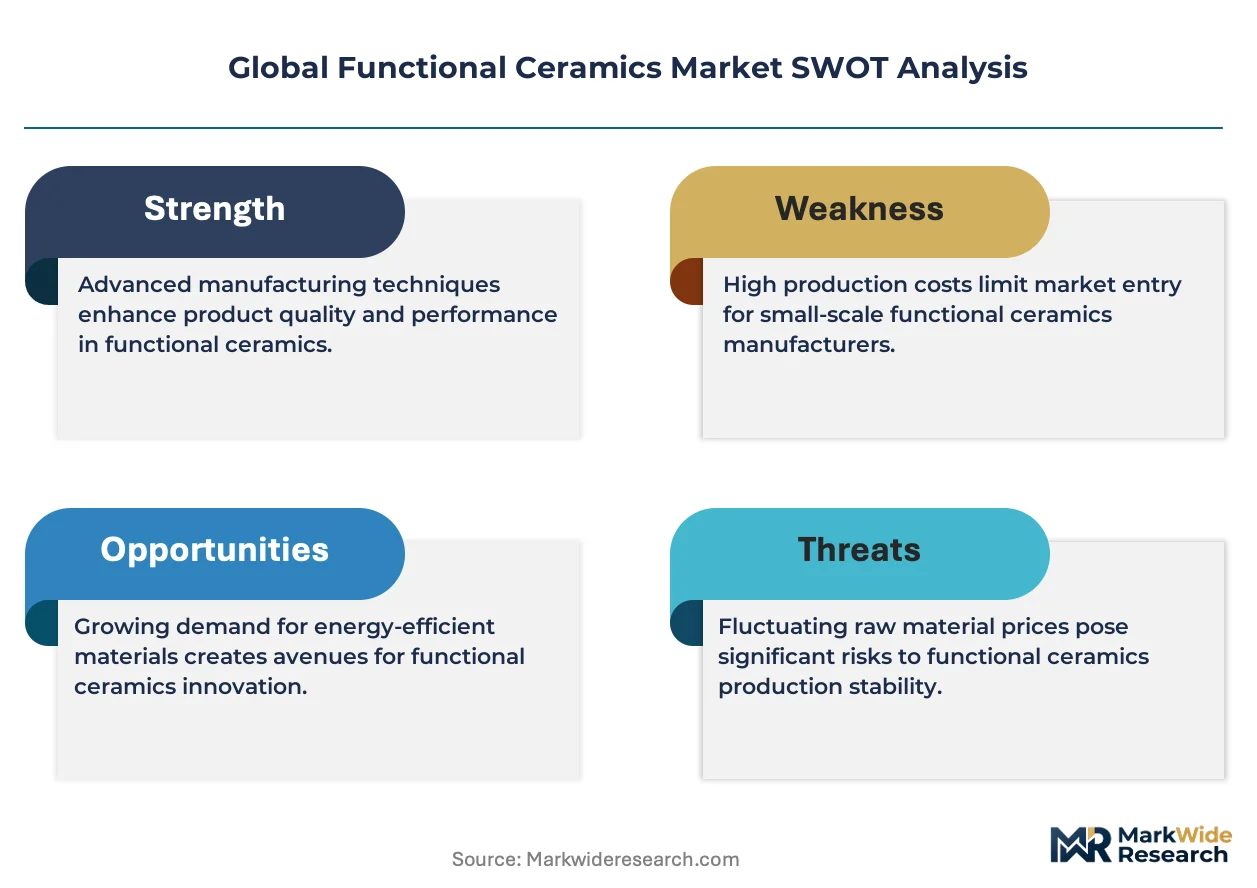
Undercapacity in Germany's natural gas-fired tunnel kilns is compressing supplier margins and forcing selective pricing discipline across electroceramic substrate tiers. This utilization squeeze interacts with raw material concentration in China's Jiangxi processing zones to create asymmetric pricing power between powder refiners and downstream fabricators.
Pricing Analysis
Price spreads between Japanese electronic component belt suppliers and German industrial ceramics corridor producers reflect divergent energy cost structures and certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA/EMA biocompatibility-certified bioceramics from commodity alumina substrates. Cost compression in standard-grade electroceramics is intensifying because Japanese capacitor manufacturers are locking three-year offtake agreements with Australian bauxite refiners. Automotive OEMs exhibit the highest price sensitivity due to volume procurement mandates under EU Green Deal emissions standards, while medical device manufacturers absorb premium pricing to secure JIS and FDA qualification pathways.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for rare earth oxide-dependent piezoelectric formulations. High-purity alumina supply concentrates in Australia's bauxite refining corridors, China's Jiangxi processing zones, and Germany's captive chemical synthesis facilities. Ceramic matrix composite production draws from carbon fiber feedstocks anchored in Japan's Toray supply ecosystem and silicon carbide precursors from US Southeast manufacturing hubs. Single-source vulnerability in high-purity rare earth oxide separation creates chokepoint exposure for lead-free piezoelectric alternatives. Distribution runs through long-term offtake agreements displacing spot purchasing, with Japanese capacitor manufacturers and German automotive Tier 1s locking direct refinery relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among Japanese automotive OEMs and South Korean semiconductor foundries, compressing supplier margins and favoring scale players with captive powder processing capabilities.
For Market Incumbents: Insulate margin position through backward integration into high-purity alumina and silicon carbide powder synthesis, particularly in the US Southeast manufacturing hub where IRA clean energy credits subsidize domestic processing. Accelerate METI JIS and FDA biocompatibility certification pipelines to defend premium bioceramic positioning against emerging sodium bismuth titanate competitors. Lock three-year offtake agreements with Australian bauxite refiners before procurement consolidation accelerates. For New Entrants and Emerging Players: Pursue India's PLI scheme for electronics manufacturing as the most penetrable white-space opportunity, targeting domestic ceramic substrate production for semiconductor packaging vendors. Exploit additive manufacturing convergence in aerospace thermal protection systems where low-volume, high-certification production sustains premium positioning. Establish partnerships with Germany's Fraunhofer institutes for binder jetting process development to bypass legacy isostatic pressing equipment barriers. For Investors and Strategic Acquirers: Long-term, this sits as a materials-scarcity play because pyrometallurgical expertise scarcity in Germany and Japan is retiring faster than vocational programs can replenish talent pipelines. Target mid-cap specialists with captive kiln operations and established regulatory dossiers under EU REACH and China's GB standards. Watch for inflection signals in India's domestic electronics manufacturing incentives and US IRA clean energy credit utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Powder Processing | Kyocera and Murata manufacturing ecosystems sustain premium pricing through captive alumina and silicon carbide synthesis. |
| Long-term Supply Agreement with Rare Earth Refiners | Japanese capacitor manufacturers lock three-year offtake contracts with Australian bauxite processors to secure consistency. |
| Regulatory Certification Investment | FDA biocompatibility and METI JIS compliance create decade-long supplier lock-in for orthopedic implant bioceramics. |
| Additive Manufacturing Process Development | Germany's Fraunhofer institutes anchor binder jetting capabilities for complex aerospace turbine vane geometries. |
| Geographic Manufacturing Footprint Expansion | US Southeast hub localization secures IRA clean energy credits for silicon carbide wafer processing in automotive supply chains. |
Methodological Framework
Desk research of SEC 10-K filings, EU REACH substance dossiers, and Japan METI industrial production statistics preceded structured interviews with ceramic plant managers, OEM procurement leads at automotive Tier 1 suppliers, biomedical engineers at implantable device manufacturers, and distribution channel partners in Germany's industrial ceramics corridor. Primary fieldwork with kiln operators and ceramic engineers in Japan's electronic component belt validated firing protocol evolution and pyrometallurgical expertise scarcity patterns. Bottom-up volume modeling across electroceramic, bioceramic, and piezoelectric product tiers triangulated against top-down macro demand indicators from EU Green Deal emissions mandates and China's dual carbon goals.
Assumptions held fixed include regulatory enforcement timelines under EU REACH authorization requirements and Japan METI JIS standards, while energy cost volatility in German natural gas markets and rare earth oxide supply concentration in China's Jiangxi processing zones were modeled as scenario variables. Segmentation dimensions spanned product chemistry, end-use severity across electronics and healthcare, physical form from powder to ceramic matrix composites, and manufacturing precision from isostatic pressing to binder jetting additive manufacturing. CAGRs derived from historical production data and forward capacity announcements across the projection horizon incorporated AI accelerator chip thermal management densification and EV power electronics substrate adoption curves as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in EU energy market pricing, China's dual carbon policy enforcement intensity, or US IRA clean energy credit allocation would shift the trajectory for silicon carbide and high-purity alumina demand. Forecasts reflect assumptions about regulatory synchronization between EU REACH and China's GB standards update cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Ceramic Additives Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Ceramics Packaging Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Ceramic Frit Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Kaolin Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Advanced Ceramics Market
Ceramics
Potassium Silicate Market
Ceramics
Refractory Material Market
Ceramics
Active Calcium Silicate Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market