
 Oxygen Barrier Films Market | 2026-2036
Oxygen Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Barrier Films Market Analytics
Performance-based service contracts for barrier film calibration and shelf-life validation is broadening what converters sell beyond commodity rolls. Amcor leverages its global technical service network to lock in multi-year supply agreements with protein processors. Berry Global Inc. anchors North American capacity through integrated resin-to-film operations in Kentucky and Wisconsin. Toppan Inc. differentiates via proprietary transparent vapor-deposited barrier layers for organic electronics encapsulation.
Oxygen barrier films are multilayer polymer structures, typically incorporating ethylene vinyl alcohol copolymer or metallized polyethylene terephthalate at thicknesses between 10 and 50 microns, engineered to maintain oxygen transmission rates below 1 cc per square meter per day. These films preserve oxidative stability in packaged goods ranging from retort-ready meals to lithium battery cell wraps. Ethylene vinyl alcohol commands the premium tier due to its superior gas barrier and thermoformability, while polyethylene dominates volume in cost-sensitive snack and frozen food applications. Roll stock remains the foundational delivery mode, though pre-formed pouches capture expanding margin pools in ready-to-eat and pharmaceutical unit-dose formats.
The FDA enforces oxygen permeability thresholds for sterile pharmaceutical packaging under USP <1207>, while the EPA's emerging per- and polyfluoroalkyl substances restrictions are forcing reformulation of legacy barrier coatings. The EU Green Deal's packaging recyclability targets and California's extended producer responsibility framework are converging to demand mono-material or chemically recyclable barrier constructions. Stakeholders must decide whether to prioritize capital deployment into solventless lamination and advanced coextrusion, or to absorb compliance costs as regulatory divergence between jurisdictions intensifies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to redesign multilayer structures for chemical recyclability, compressing development cycles and reallocating capital from capacity expansion to pilot lines for mono-material alternatives.
Growth Catalysts
- Biologics cold-chain expansion:Pharmaceutical distributors are specifying high-barrier laminates for temperature-sensitive biologics, widening the addressable market beyond traditional food packaging.
- REACH compliance deadlines:European converters accelerating solventless lamination investments to meet volatile organic compound reduction mandates ahead of enforcement windows.
- EVOH copolymer thermoformability:Meat processors in Germany's Ruhr corridor are adopting deeper-draw barrier trays for case-ready proteins, displacing modified atmosphere packaging with vacuum skin formats.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Three Japanese and Korean suppliers control over seventy percent of global EVOH supply, exposing converters to allocation risk during petrochemical turnarounds.
- Metallized PET technical ceiling:Vacuum-deposited aluminum layers cannot achieve oxygen transmission rates below 0.5 cc/m²/day, excluding the technology from ultra-high-barrier pharmaceutical applications.
- Per- and polyfluoroalkyl substances regulatory friction:EPA restrictions on legacy fluorinated barrier coatings are forcing reformulations that degrade moisture barrier performance in humid climates.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO enforcement of USP <1207> equivalency standards for sterile barrier systems is opening import substitution opportunities for domestic laminate producers.
- Transparent barrier convergence:Vapor-deposited silicon oxide layers combined with plasma-enhanced chemical vapor deposition are enabling see-through packaging for premium confectionery display cases.
- California extended producer responsibility:The state's packaging fee structures incentivize mono-material barrier constructions, rewarding early movers with compliance cost advantages.
Industry Challenges
- Barrier metrology skill scarcity:Calibration of coulometric oxygen transmission rate instruments requires specialized technicians that converters struggle to recruit in secondary packaging hubs.
- Coextrusion line reconfiguration capex:Shifting from seven-layer to eleven-layer architectures for recyclable barrier films demands extruder replacements exceeding fifteen million dollars per line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Barrier Films Market |
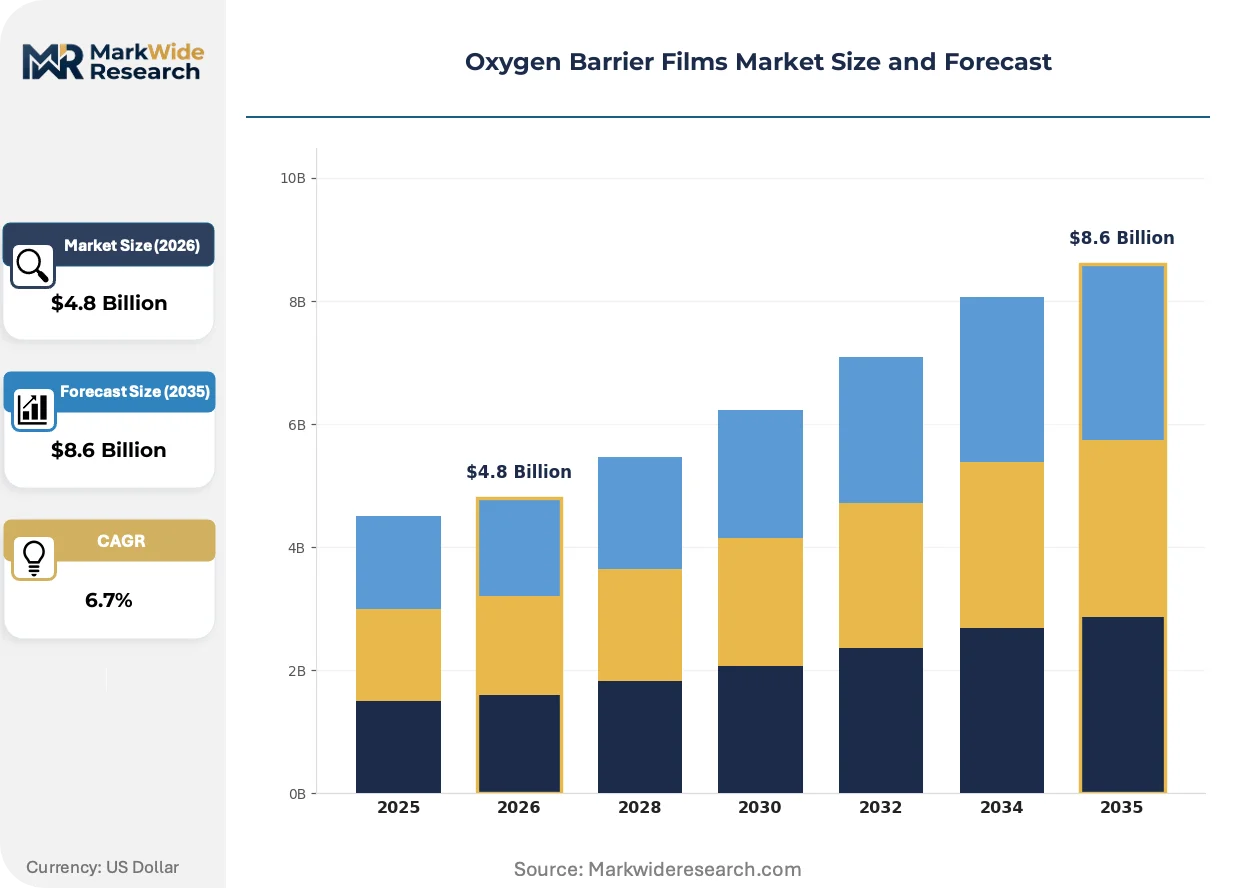
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Ethylene Vinyl Alcohol End Use Industry: Food Packaging, Pharmaceutical, Electronics, Agriculture Delivery Mode: Roll Stock, Pouches, Bags, Laminated Films Thickness: Below 10 Microns, 10-30 Microns, 30-50 Microns, Above 50 Microns |
| Companies Covered | Amcor, Berry Global Inc., Sealed Air, Mondi, Dupont Teijin Films, Uflex Limited, Cosmo Films, Huhtamaki Oyj, Toppan Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Barrier Films Market Evolving Landscape
Barrier film technology is converging toward mono-material compatibility, regulatory compliance automation, and service-contract bundling that redefines converter-customer relationships beyond commodity supply.
Advanced coextrusion with tie-layer optimization is unifying oxygen and moisture barrier functions within single-polymer families, typically polypropylene or polyethylene. European meat packers in the Netherlands and Denmark are piloting these structures for thermoformed trays, compressing the competitive window for multilaterial laminates as recyclability audits intensify.
EMA guidance on sterile barrier system validation is compelling pharmaceutical converters to implement automated permeability testing protocols with electronic batch records. The industrial consequence is capital migration from production equipment to quality infrastructure. Parenteral packaging lines in Germany and Switzerland are responding by integrating in-line oxygen transmission verification, eliminating offline laboratory bottlenecks.
Protein processors are consolidating specification authority at headquarters level, displacing plant-level procurement of commodity roll stock. Centralized technical teams at major meatpackers now mandate barrier performance thresholds and recyclability certifications, compressing the supplier base to converters with integrated R&D capabilities. This concentration is most visible in the US Midwest, where three beef processors account for barrier film specifications across thirty-plus fabrication facilities.
Oxygen Barrier Films Market Segmentation
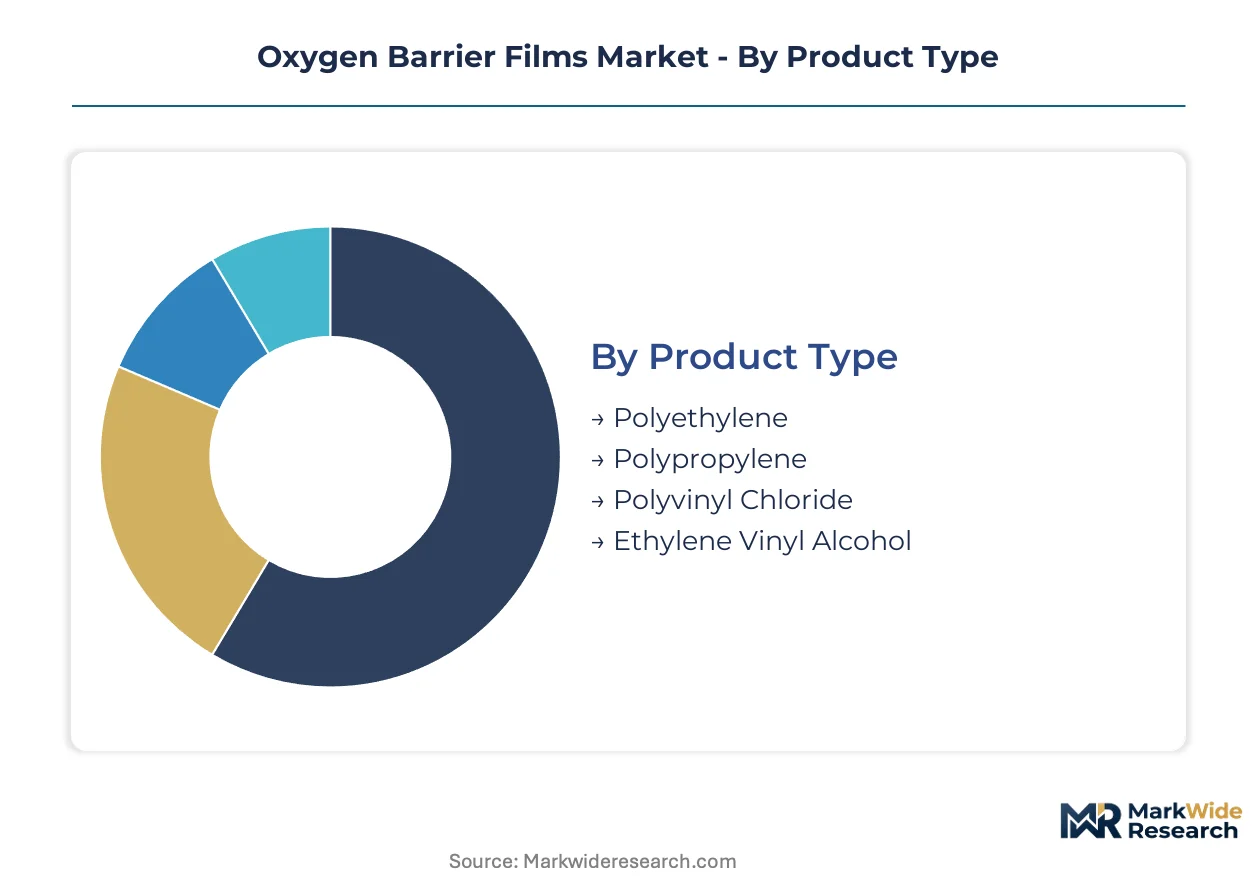
Converters configure their asset base around thickness precision and resin selection, while end-use specifications increasingly mandate recyclability certifications alongside barrier performance. Segmentation discipline separates commodity volume plays from premium laminate specialists.
Product Type:
Customization intensity ranges from off-the-shelf polyethylene grades to coextruded EVOH structures requiring resin-to-film technical partnerships.
- Polyethylene:Linear low-density and metallocene grades dominate frozen food and snack applications where cost floors matter more than ultra-low oxygen transmission. Volume concentrates in North American retail-ready protein formats driven by Walmart and Kroger sustainable packaging mandates.
- Ethylene Vinyl Alcohol:Copolymer grades with ethylene content between 32% and 44% deliver oxygen transmission rates below 1 cc/m²/day together with deep-draw thermoformability. German meat processors in the Ruhr corridor specify EVOH for vacuum skin trays displacing modified atmosphere packaging.
- Polypropylene:Cast and biaxially oriented structures serve retort pouch and microwaveable tray applications requiring thermal stability above 120°C.
- Polyvinyl Chloride:Shrink-wrap and blister pack formats persist in pharmaceutical unit-dose packaging despite recyclability headwinds under EU Green Deal targets.
Leading the category by volume: Polyethylene. Growing fastest: Ethylene Vinyl Alcohol.
End Use Industry:
Margin capture varies sharply across end-use segments, with pharmaceutical validation protocols commanding 3-4x the technical service intensity of food packaging.
- Food Packaging:Case-ready meat, cheese, and ready-to-eat meals absorb the majority of global barrier film tonnage. Dutch and Danish retailers are piloting mono-material polypropylene trays to preempt Extended Producer Responsibility compliance costs.
- Pharmaceutical:Biologics cold-chain expansion is widening specification authority for high-barrier laminates with temperature excursion indicators. CDSCO enforcement of USP 1207 equivalency in India is opening import substitution opportunities for domestic converters.
- Electronics:Lithium battery cell wraps and organic electronics encapsulation demand transparent vapor-deposited barriers with moisture transmission rates below 0.1 g/m²/day.
- Agriculture:Silage wrap and greenhouse films utilize medium-barrier coextrusions where oxygen exclusion prolongs forage preservation.
Food Packaging generates the largest revenue pool. Pharmaceutical delivers the steepest expansion trajectory.
Delivery Mode:
Customer supply chain integration determines whether converters ship commodity roll stock or capture downstream margin through pre-formed formats.
- Roll Stock:Unprinted or surface-printed webs remain the foundational delivery mode, enabling brand owners to maintain in-house forming and filling flexibility. Protein processors in the US Midwest specify roll stock centrally across thirty-plus fabrication facilities.
- Pouches:Pre-formed stand-up and flat pouches capture expanding margin pools in ready-to-eat and pharmaceutical unit-dose formats. Swiss and German parenteral packaging lines are integrating in-line oxygen transmission verification to eliminate offline laboratory bottlenecks.
- Bags:Side-gusseted and quad-seal configurations serve bulk pharmaceutical ingredients and specialty agriculture chemicals.
- Laminated Films:Multi-ply solventless and adhesive-laminated structures combine oxygen barrier with puncture resistance for sharp-edged medical devices.
Roll Stock dominates tonnage. Pouches are gaining share fastest.
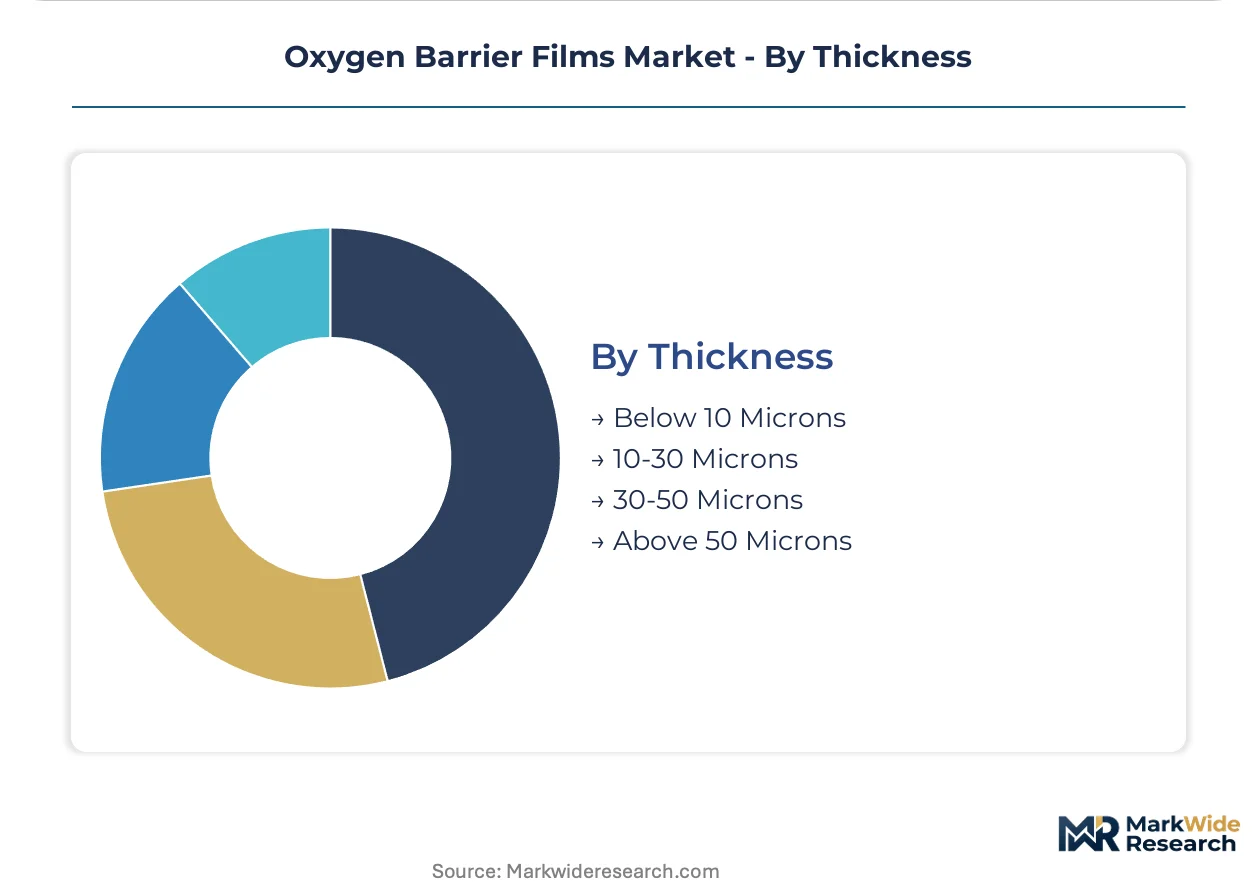
Thickness:
Equipment retrofit requirements and resin consumption economics create distinct competitive terrains across thickness bands.
- 10-30 Microns:This band captures the majority of flexible food packaging applications, balancing barrier performance with material efficiency. Japanese and Korean EVOH suppliers allocate resin preferentially to this thickness range during petrochemical turnarounds.
- 30-50 Microns:Deep-draw thermoformed trays for case-ready proteins require this thickness to maintain barrier integrity across draw ratios exceeding 3:1. German converters around Düsseldorf and Hamburg anchor European capacity.
- Below 10 Microns:Ultra-thin metallized PET and silicon oxide coatings serve electronics encapsulation where weight and flexibility constrain design.
- Above 50 Microns:Heavy-gauge structures address industrial chemical containment and agricultural silage applications where puncture resistance overrides oxygen transmission precision.
10-30 Microns leads by volume. 30-50 Microns is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese resin corridors while consumption spreads across protein-processing clusters and pharmaceutical hubs in North America, Europe, and Asia. This geographic mismatch creates freight-cost arbitrage and inventory positioning challenges for converters serving just-in-time packaging lines.
United States
Midwest beef processors centralize barrier film specifications across thirty-plus fabrication facilities, compressing supplier diversity. FDA enforcement of USP 1207 for sterile pharmaceutical packaging tightens validation protocols for parenteral formats. Kentucky and Wisconsin host integrated resin-to-film operations serving North American retail protein markets.
Germany
Ruhr corridor meat processors adopt deep-draw EVOH trays for vacuum skin packaging, displacing modified atmosphere formats. REACH compliance deadlines accelerate solventless lamination investments ahead of volatile organic compound reduction mandates. The Düsseldorf-Hamburg flexible packaging corridor anchors European converter capacity for pan-regional food and pharma clients.
Japan
Domestic suppliers control over seventy percent of global EVOH resin production, exposing downstream converters to allocation risk during petrochemical turnarounds. METI guidelines on packaging recyclability push mono-material development timelines. Tokyo-Osaka industrial zones concentrate vapor-deposited barrier technology for organic electronics encapsulation.
India
CDSCO enforcement of USP 1207 equivalency standards for sterile barrier systems opens import substitution opportunities for domestic laminate producers. FSSAI packaging safety notifications tighten migration limits for food-contact multilayer structures. Maharashtra and Gujarat pharmaceutical packaging clusters expand cold-chain infrastructure for biologics distribution.
Switzerland
Swissmedic validation requirements for sterile barrier systems drive automated permeability testing with electronic batch records. The country's precision manufacturing heritage supports parenteral packaging lines integrating in-line oxygen transmission verification. Basel-Zurich corridor facilities serve as technical reference sites for European pharmaceutical converters.
Oxygen Barrier Films Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the oxygen barrier films sector. Integrated resin-to-film operators in North America and Asia command supply security premiums, while European specialists capture value through technical service bundling and validation support. Three archetypes dominate: multinational converters with global technical service networks, regional integrated producers with captive resin supply, and niche specialists in transparent vapor-deposited barriers. Competitive moves concentrate on solventless lamination capacity additions and multi-year performance-based service contracts that displace commodity roll stock procurement.
Among Asia-Pacific-based fabricators, Toppan Inc. exemplifies the transparent barrier specialist archetype through its proprietary vapor-deposited layer technologies. Uflex Limited and Cosmo Films occupy positions within the integrated film producer tier, leveraging South Asian manufacturing scale for cost-sensitive flexible packaging applications. Amcor anchors the multinational converter category with technical service networks spanning protein processing and pharmaceutical validation requirements across multiple continents.
| Leading Market Players |
|---|
| Amcor |
| Berry Global Inc. |
| Sealed Air |
| Mondi |
| Dupont Teijin Films |
| Uflex Limited |
| Cosmo Films |
| Huhtamaki Oyj |
| Toppan Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging recyclability mandates gate qualified supply access and premium-tier pricing for converters demonstrating mono-material barrier competence. Buyers without certified circularity credentials face exclusion from pan-European protein processor and pharmaceutical tender pools.
Pricing Analysis
Margin tightening in standard-grade polyethylene reflects Walmart and Kroger sustainable packaging mandates compressing commodity roll stock premiums. Three-tier pricing structure across premium EVOH laminates, certified mono-material mid-tier, and economy polyethylene separates converters by validation depth and resin integration. Cost-down pressure on metallized PET accelerates as transparent vapor-deposited alternatives capture pharmaceutical display applications. Frozen food processors exhibit highest price sensitivity, while biologics cold-chain distributors prioritize barrier performance over unit cost.
Supply Chain Analysis
EVOH resin supply rests on Japanese and Korean petrochemical producers controlling over seventy percent of global output, exposing converters to allocation risk during turnaround seasons. Raw material dependencies center on ethylene vinyl alcohol copolymer, metallized polyethylene terephthalate substrates, and plasma-enhanced chemical vapor deposition precursors. Single-source vulnerability concentrates in the 30-50 micron EVOH tray segment where German meat processors lack qualified alternative suppliers. Distribution runs through Düsseldorf-Hamburg flexible packaging corridor hubs serving pan-European just-in-time lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters are racing to secure captive resin supply and in-line validation capabilities as barriers to premium-tier pricing access harden.
For Market Incumbents: Hedge EVOH allocation exposure through long-term offtake agreements with Japanese and Korean resin producers before petrochemical turnaround seasons. Deepen backward integration into solventless lamination pilot lines to preempt REACH volatile organic compound enforcement windows. Consolidate technical service bundling around USP 1207 validation support to lock in multi-year pharmaceutical supply agreements. For New Entrants and Emerging Players: Begin with India's CDSCO-equivalent sterile barrier market where domestic laminate producers face limited qualified competition. Target Maharashtra and Gujarat pharmaceutical packaging clusters expanding cold-chain infrastructure for biologics distribution. Lead with automated permeability testing protocols and electronic batch records as differentiation against legacy commodity converters. For Investors and Strategic Acquirers: Japanese EVOH supplier allocation announcements are the leading indicator that downstream converter margin compression will accelerate. Five-to-ten year viability favors integrated resin-to-film operators with captive supply security over asset-light designers. Watch for CDSCO enforcement acceleration in India as signal for import substitution opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Solventless Lamination Capacity Expansion | REACH compliance deadlines in Germany accelerate capital migration from adhesive-based lines. |
| Backward Integration into EVOH Resin | Japanese and Korean supply concentration creates captive supply premiums for integrated operators. |
| Mono-Material Pilot Line Investment | California extended producer responsibility fee structures reward early recyclability certification. |
| In-Line Oxygen Transmission Verification | Swissmedic validation requirements drive capital migration from production to quality infrastructure. |
| Multi-Year Performance-Based Service Contracts | US Midwest beef processor consolidation favors converters bundling shelf-life validation with roll stock supply. |
Research Methodology
Document review covered customs and trade data, SEC and ECHA regulatory filings, and pharmaceutical packaging validation databases, complemented by interviews with flexible packaging plant managers, protein processor procurement leads, pharmaceutical technical service directors, and barrier film R&D specialists. Secondary sources included FDA USP 1207 guidance documents, EU Packaging and Packaging Waste Regulation drafts, and EVOH resin supplier allocation disclosures. Bottom-up segment sizing triangulated against top-down market value reconstruction across product type, end use industry, delivery mode, and thickness dimensions.
Segment-level revenue estimates and volume projections across the modeling period derived from resin consumption modeling, equipment capacity utilization assumptions, and end-use demand elasticity parameters. The analytical framework incorporated oxygen transmission rate performance tiers, recyclability certification penetration curves, and regional regulatory enforcement timelines as industry-specific forecast inputs. CAGRs were computed from year-over-year growth rate reconciliation across independent demand-side and supply-side estimation approaches.
Petrochemical turnaround schedules, REACH enforcement acceleration, and CDSCO equivalency ruling timing are the dominant revision risks to barrier film demand forecasts. Forecasts reflect assumptions regarding EVOH resin allocation continuity and solventless lamination technology maturation curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Membrane Separation Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Nanoporous Membranes Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market