
 Graphite Crucibles Market | 2026-2036
Graphite Crucibles Market Size, Share, and Industry Trends Forecast 2026-2036
Graphite Crucibles Market Foresight
Multi-source procurement among foundries and battery material producers is pivoting toward vertically integrated graphite suppliers. SGL Carbon leverages captive needle coke refining to secure feedstock consistency. Graphite India Limited anchors South Asian supply through dedicated electrode-grade graphite operations. Tokai Carbon Co. Ltd. differentiates via ultra-high-purity isostatic products for semiconductor applications.
Graphite crucibles are refractory containers manufactured from isostatic, molded, or vibration-formed graphite with thermal conductivity exceeding 100 W/m·K, engineered to contain molten metals and alloys at temperatures surpassing 3,000°C in vacuum or inert atmospheres. Isostatic crucibles command premium positioning in semiconductor crystal pulling due to uniform density and minimal porosity. High-temperature rated products represent the fastest-expanding temperature tier, driven by silicon carbide ingot growth and rare earth metal processing. Steel production applications remain the largest volume category, though margin pools have shifted toward laboratory and electronics-grade segments.
China's MEE enforces dual carbon targets that constrain coal-based synthetic graphite expansion, redirecting investment toward electric-arc and renewable-powered graphitization. The EU's REACH and CSRD frameworks impose full supply chain disclosure for imported graphite, elevating compliance costs for non-European producers. Japan's METI maintains JIS standards for crucible dimensional tolerance and oxidation resistance that filter market access. Stakeholders must monitor feedstock certification regimes and carbon border adjustments as determinants of competitive viability.
Market Dynamics
Electric vehicle battery anode production is concentrating demand for ultra-high-purity graphite crucibles, while China's dual carbon goals under MEE are forcing coal-powered synthetic graphite capacity offline and redirecting investment toward electric-arc graphitization.
Growth Catalysts
- Silicon carbide ingot manufacturing:Wide-bandgap semiconductor crystal pulling requires isostatic crucibles rated above 2,000°C. SiC substrate producers in Japan and Germany are expanding furnace fleets.
- EU Battery Regulation traceability mandates:Full supply chain disclosure requirements for imported graphite are elevating certified crucible premiums. European anode material plants are qualifying dedicated suppliers.
- Rare earth metal processing resurgence:Separation and reduction of neodymium and dysprosium in inert atmospheres demands oxidation-resistant crucible linings. Lynas Rare Earths and MP Materials are expanding molten salt electrolysis capacity.
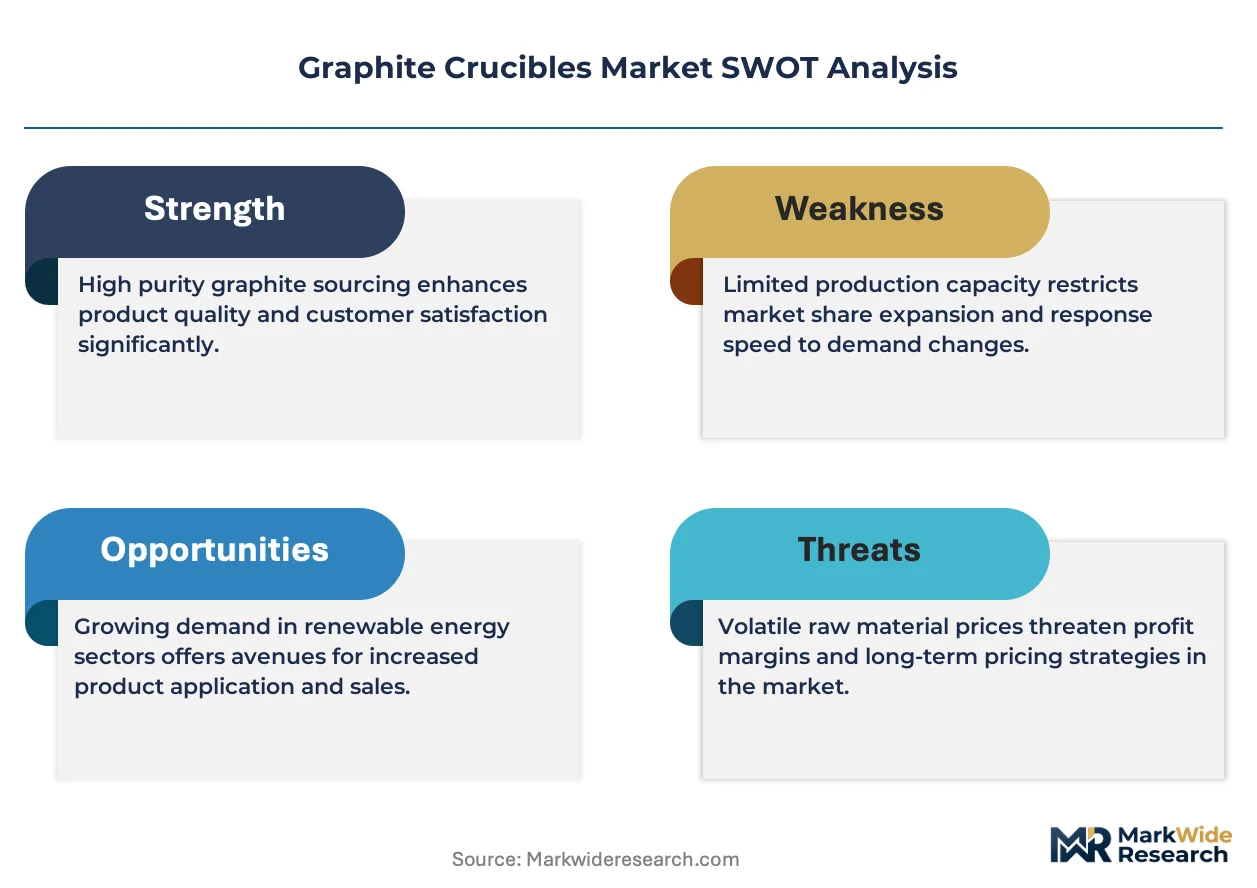
Market Restraints
- Needle coke feedstock volatility:Oil refinery byproduct supply constrains synthetic graphite crucible output. Premium needle coke prices fluctuate with fluid catalytic cracking unit operating rates.
- Single-country supply concentration:Over 70% of synthetic graphite crucible manufacturing clusters in China's Jiangsu and Shandong provinces. Geopolitical friction or export licensing disruptions propagate rapidly.
- Refractory ceramic substitution in steel ladle applications:Alumina-carbon and magnesia-carbon linings displace graphite crucibles in basic oxygen furnace secondary metallurgy. Cost-sensitive foundries in India and Brazil are converting.
Strategic Opportunities
- North American anode material localization:US IRA production tax credits incentivize domestic graphite purification and spheronization. Crucible suppliers can co-locate with emerging Tennessee and North Carolina processing hubs.
- Semiconductor equipment service contracts:Crucible replacement cycles in silicon crystal pullers generate recurring revenue. OEMs are unbundling consumables from furnace sales.
- Japan METI green innovation funding:Grants for low-carbon graphitization technology support renewable-powered furnace retrofits. Domestic crucible producers are qualifying biomass-derived binder systems.
Industry Challenges
- Isostatic press operator scarcity:Cold isostatic pressing of fine-grained graphite requires specialized mold-filling and densification expertise. Training programs lag equipment installation timelines.
- Multi-jurisdiction certification stacking:REACH, CSRD, and JIS standards impose overlapping documentation burdens. Compliance timelines extend customer qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphite Crucibles Market |
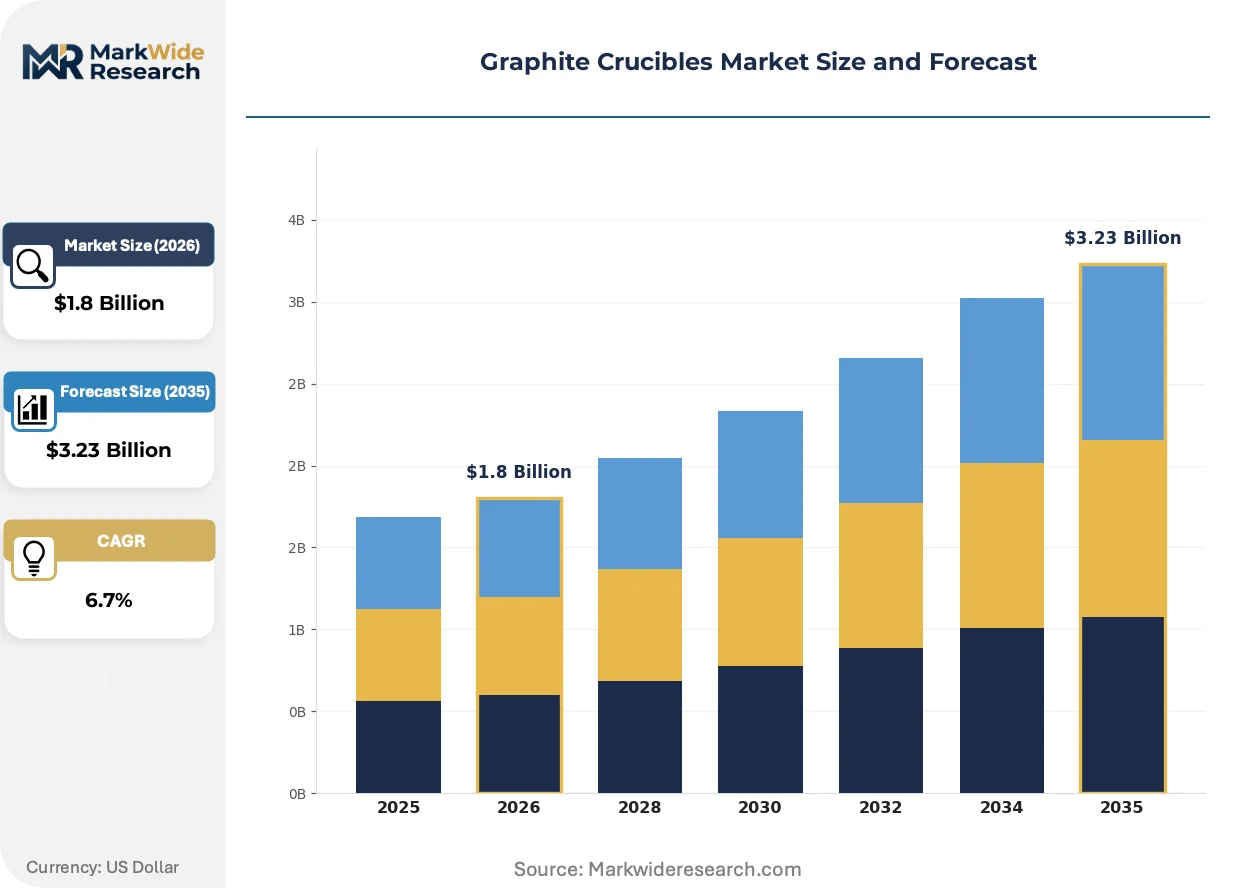
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isostatic, Molded, Vibration, Machined Application: Metal Casting, Jewelry Making, Laboratory Use, Steel Production End User: Manufacturers, Research Institutions, Foundries, Artisans Temperature Rating: High-Temperature, Ultra-High-Temperature, Standard-Temperature, Medium-Temperature |
| Companies Covered | SGL Carbon, Graphite India Limited, Morgan Advanced Materials, Weaver Industries, Inc., Tokai Carbon Co. Ltd., Mersen Group, NIPPON CRUCIBLE CO., LTD., Ouzheng Carbon, Toyo Tanso Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphite Crucibles Market Shifts & Advancements
Graphite crucible manufacturing is absorbing digital process control and alternative feedstock processing, while end-use specifications diverge between commodity steel applications and precision semiconductor crystal growth.
Ultra-high-purity isostatic graphite is absorbing contamination-sensitive semiconductor and photovoltaic ingot growth. Taiwan Semiconductor Manufacturing and Shin-Etsu Chemical are specifying sub-5 ppm ash content for silicon crystal pullers. This material grade is absorbing margin pools from standard electrode-grade products as qualification barriers harden.
China's MEE dual carbon enforcement is accelerating electric-arc furnace adoption for synthetic graphite production. Coal-based graphitization capacity faces emissions quotas and carbon intensity audits. Battery anode material producers are qualifying crucible suppliers with renewable-powered or natural gas-electric hybrid furnace configurations.
Long-term supply agreements are displacing spot procurement for EV battery material producers. Anode manufacturers in South Korea and Germany are locking five-year crucible supply contracts with volume guarantees and fixed-price escalators. This pattern concentrates procurement leverage among vertically integrated graphite processors with captive needle coke refining.
Graphite Crucibles Market Segmentation
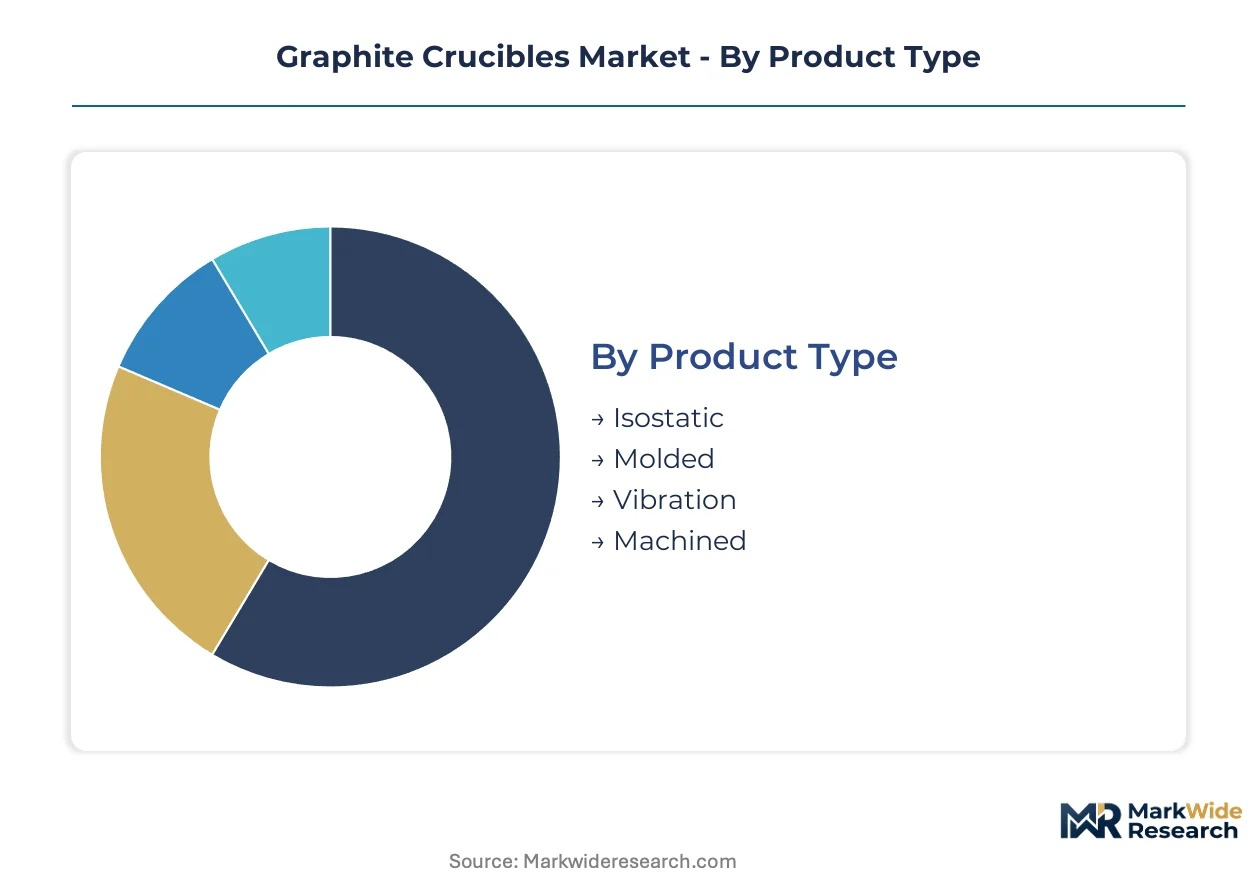
Graphite crucible procurement patterns diverge sharply between commodity metal casting operations and precision semiconductor manufacturing. Segment boundaries reflect thermal performance thresholds, purity specifications, and integration depth into automated furnace systems.
Product Type:
Isostatic products embed directly into automated crystal pullers and vacuum furnaces, while molded and vibration-formed variants serve standalone foundry applications.
- Isostatic:Manufactured through cold isostatic pressing of fine-grained graphite to achieve uniform density below 5% porosity. Semiconductor crystal pullers in Taiwan and Germany specify sub-5 ppm ash content for silicon ingot growth. Ultra-high-purity grades absorb margin pools from standard electrode products as qualification barriers harden.
- Molded:Formed under unidirectional pressure with resin binders for general-purpose metal containment. Steel foundries in India and Brazil prioritize molded crucibles for basic oxygen furnace secondary metallurgy where cost sensitivity dominates specification rigor.
- Vibration:Densified through vibrational compaction for large-diameter crucibles exceeding 500 mm inner diameter. Rare earth metal processors deploy vibration-formed linings for molten salt electrolysis of neodymium and dysprosium.
- Machined:Custom-milled from graphite blocks for specialized geometries and repair applications. Laboratory equipment OEMs source machined components for retrofitting legacy furnace fleets.
Isostatic grades lead volumes today; vibration-formed products are gaining share fastest in rare earth processing expansion.
Application:
Cost tiers separate high-frequency replacement consumables from capital-integrated systems with extended service intervals.
- Metal Casting:General ferrous and non-ferrous alloy melting in foundries. Aluminum die-casters in China's Jiangsu province drive standardized crucible procurement through volume contracting.
- Jewelry Making:Precious metal melting for artisan and commercial production. Small-batch goldsmiths in Turkey and Italy specify medium-temperature rated products with rapid thermal cycling tolerance.
- Laboratory Use:Research-scale synthesis and materials testing. Universities and national laboratories in Germany and Japan qualify crucibles for inert atmosphere synthesis of novel ceramics.
- Steel Production:Secondary metallurgy and ladle refining operations. Integrated mills in South Korea are converting to alumina-carbon linings in basic oxygen furnace applications, compressing graphite crucible demand in this segment.
Steel production anchors volume today; laboratory use is climbing the fastest on semiconductor materials research expansion.
End User:
Customer type determines procurement leverage, with integrated manufacturers locking long-term supply against spot-market artisans.
- Manufacturers:Battery anode material producers and semiconductor equipment OEMs. South Korean anode manufacturers are executing five-year crucible supply contracts with volume guarantees and fixed-price escalators.
- Research Institutions:National laboratories and university materials science departments. Japan's METI green innovation funding supports renewable-powered furnace retrofits at domestic research facilities.
- Foundries:Commercial metal casting operations serving automotive and machinery sectors. Indian foundries are multi-sourcing molded crucibles to mitigate single-country supply concentration risks.
- Artisans:Independent jewelry makers and small-scale metalworkers. Italian goldsmith clusters in Arezzo and Valenza maintain specialized supplier relationships for precious metal containment.
Manufacturers lead volumes today; research institutions are expanding procurement most quickly on federal funding cycles.
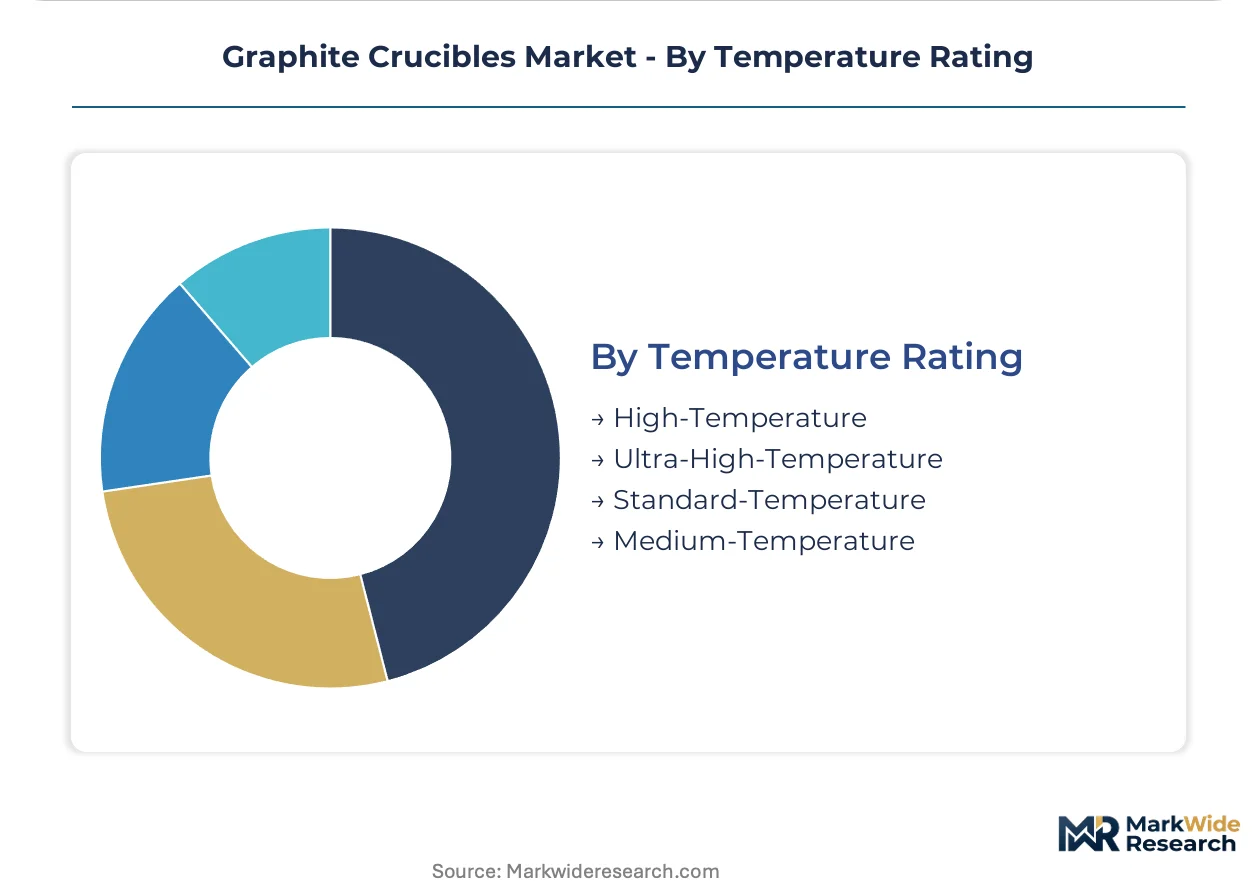
Temperature Rating:
Maturity gradients separate established standard-temperature supply from emerging ultra-high-temperature qualification requirements.
- High-Temperature:Rated for sustained operation above 2,000°C in inert or vacuum atmospheres. Silicon carbide ingot producers in Japan and Germany are expanding furnace fleets requiring high-temperature isostatic crucibles.
- Ultra-High-Temperature:Engineered for excursions exceeding 3,000°C in specialized reduction processes. Rare earth metal separation facilities specify oxidation-resistant ultra-high-temperature linings for molten salt electrolysis.
- Standard-Temperature:Optimized for aluminum and copper melting below 1,200°C. General foundry applications in Brazil and India concentrate demand for standard-temperature molded products.
- Medium-Temperature:Targeting precious metal and specialty alloy processing between 1,200°C and 2,000°C. Jewelry manufacturing clusters in Turkey deploy medium-temperature crucibles for gold and platinum group metal containment.
Standard-temperature products dominate volume today; ultra-high-temperature grades are on the steepest expansion trajectory from wide-bandgap semiconductor growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong provinces anchor graphite crucible manufacturing capacity, hosting synthetic graphite production clusters that supply battery anode and semiconductor foundries across three continents.
China
Electric vehicle battery anode production and silicon carbide ingot growth drive crucible consumption in Jiangsu and Shandong provinces. The MEE enforces dual carbon targets that constrain coal-based synthetic graphite expansion and redirect investment toward electric-arc graphitization. Qingdao and Xuzhou manufacturing clusters are qualifying renewable-powered furnace configurations for export markets.
Japan
Wide-bandgap semiconductor crystal pulling and rare earth metal processing sustain demand for ultra-high-purity isostatic products. METI maintains JIS standards for crucible dimensional tolerance and oxidation resistance that filter market access. Nagoya and Kyushu industrial corridors host SiC substrate producers expanding furnace fleets.
Germany
EU Battery Regulation traceability mandates elevate certified crucible premiums for anode material plants. The ECHA REACH framework imposes full supply chain disclosure for imported graphite. Saxony and Bavaria semiconductor equipment clusters are qualifying dedicated crucible suppliers with renewable energy credentials.
United States
IRA production tax credits incentivize domestic graphite purification and spheronization capacity. Tennessee and North Carolina processing hubs are emerging as anode material localization centers. EPA emissions standards and state-level clean energy procurement rules shape supplier qualification requirements.
South Korea
Battery anode manufacturers are executing five-year crucible supply contracts with volume guarantees and fixed-price escalators. The MFDS maintains material safety documentation requirements for imported refractory containers. Gyeonggi-do and Chungcheongnam-do industrial zones concentrate anode material production capacity.
Graphite Crucibles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue semiconductor-grade specialization and renewable-powered manufacturing. The vendor base stratifies across captive needle coke refiners, isostatic pressing specialists, and regional molded product fabricators. Three archetypes dominate: vertically integrated graphite processors with upstream feedstock control, precision isostatic specialists serving contamination-sensitive applications, and cost-optimized molded crucible suppliers for foundry markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers locking long-term supply agreements to secure procurement leverage.
Within the precision-tier segment, SGL Carbon and Tokai Carbon Co. Ltd. exemplify isostatic specialists targeting semiconductor crystal pulling applications. Graphite India Limited anchors South Asian supply through dedicated electrode-grade operations. These three occupy positions that reflect divergent strategic postures: European and Japanese incumbents emphasize ultra-high-purity qualification barriers, while Indian producers leverage scale economics in standardized product categories.
| Leading Market Players |
|---|
| SGL Carbon |
| Graphite India Limited |
| Morgan Advanced Materials |
| Weaver Industries, Inc. |
| Tokai Carbon Co. Ltd. |
| Mersen Group |
| NIPPON CRUCIBLE CO., LTD. |
| Ouzheng Carbon |
| Toyo Tanso Co., Ltd. |
| Others |
Supply & Pricing Matrix
Isostatic press operator scarcity in Japan and Germany widens labor-cost differentials between precision-tier and commodity-tier crucible pricing. Premium isostatic grades absorb margin pools from standard electrode products as qualification barriers harden and renewable-powered furnace configurations command certification premiums.
Pricing Analysis
Input-cost pass-through from needle coke feedstock volatility anchors contract-based long-term offtake as the dominant pricing model. Price differentiation rests on certification grade—sub-5 ppm ash content for semiconductor applications versus electrode-grade tolerances—and volume scale commitments from battery anode producers. Cost compression in molded foundry tiers intensifies because alumina-carbon refractory substitution erodes graphite crucible volumes in steel ladle applications. Indian foundries exhibit highest price sensitivity; semiconductor equipment OEMs show least sensitivity due to contamination-risk aversion and unbundled consumables strategies.
Supply Chain Analysis
Certification and qualification gating through EU REACH, Japan JIS, and China MEE dual carbon audits filters supplier access to premium segments. Geographic supply concentration centers on China, Japan, and Germany, with Jiangsu and Shandong provinces hosting over seventy percent of synthetic graphite crucible manufacturing. Raw material dependencies draw from petroleum needle coke, biomass-derived binders, and ultra-high-purity graphite feedstock. Single-country supply concentration propagates rapid disruption from export licensing friction or emissions quota enforcement. Distribution runs through vertically integrated graphite processors with captive needle coke refining and dedicated logistics to anode material plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in graphite crucibles rests on premium-tier qualification barriers hardening and renewable-powered furnace retrofits reducing carbon-intensity compliance costs. The shift from spot procurement to five-year supply contracts with volume guarantees concentrates procurement leverage among certified suppliers.
For Market Incumbents: Deepen backward integration into captive needle coke refining to secure feedstock consistency against oil refinery byproduct volatility. Expand electric-arc and renewable-powered graphitization capacity in Qingdao and Xuzhou manufacturing clusters to meet EU Battery Regulation traceability mandates. Lock long-term supply agreements with South Korean anode manufacturers before qualification cycles extend further. For New Entrants and Emerging Players: Begin with laboratory-use and research-institution segments where federal funding cycles accelerate procurement and certification barriers remain lower than semiconductor-grade tiers. Target North American anode material localization hubs in Tennessee and North Carolina where US IRA production tax credits incentivize domestic graphite purification capacity. Pursue co-location partnerships with emerging processing hubs rather than standalone manufacturing scale-up. For Investors and Strategic Acquirers: Battery anode material producers are the most active acquirer in this space, seeking to secure crucible supply through vertical integration. Long-term viability over the coming decade hinges on renewable energy credentials and sub-5 ppm ash content qualification for silicon carbide ingot growth. Watch for inflection in Japan METI green innovation funding disbursement rates as signal of low-carbon graphitization technology maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Refining | SGL Carbon secures feedstock consistency against fluid catalytic cracking unit volatility. |
| Renewable-Powered Furnace Retrofit | Qingdao manufacturers qualify for EU Battery Regulation carbon intensity audits. |
| Long-Term Supply Agreement | South Korean anode producers lock volume guarantees with fixed-price escalators. |
| Ultra-High-Purity Qualification | Tokai Carbon differentiates via sub-5 ppm ash content for TSMC crystal pullers. |
| Co-Location with Anode Hub | Weaver Industries positions adjacent to Tennessee spheronization capacity. |
Research Methodology
Coverage spans China, Japan, Germany, United States, and South Korea, with primary inputs from each market. The analysis combines primary interviews with isostatic press operators, procurement leads at battery anode plants, semiconductor equipment OEMs, and rare earth metal processors with secondary validation. Secondary sources include customs and trade data, SEC filings from graphite processors, ECHA REACH registration databases, and Japan METI green innovation funding disclosures. Bottom-up crucible volume estimates triangulate against top-down synthetic graphite production capacity assessments.
Rate-of-change decomposition separates volume growth from price-mix shifts across the projection horizon. The analytical framework models segmentation dimensions including product type, application, end user, temperature rating, and regional production hub. CAGRs derive from regression against EV battery anode production forecasts, silicon carbide ingot furnace expansion plans, and rare earth metal processing capacity builds. Industry-specific inputs include needle coke price indices and renewable energy penetration rates in graphitization operations.
Several conditions sit outside the modeled scope, including geopolitical export licensing disruptions, abrupt refractory ceramic substitution acceleration, and unanticipated needle coke supply shocks from refinery operating rate collapses. Forecasts reflect documented assumptions about dual carbon enforcement intensity and qualification timeline extensions. A model refresh is warranted upon material change in EU carbon border adjustment implementation or Japan METI funding disbursement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
China Ceramic Market
Ceramics
Calcite Market
Ceramics
China Ceramic Tiles Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Technical Ceramics Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Calcium Silicate Market
Ceramics
Global Barium Carbonate Market
Ceramics
Medical Ceramics Market
Ceramics
Europe Activated Alumina Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Zirconium Dioxide Market