
 Global Industrial Clay Market | 2026-2036
Global Industrial Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Clay Market Outlook
ISO 14001 environmental management certification is unwinding competitive access across the industrial clay supply base, raising compliance costs for smaller quarry operators. Imerys SA leverages captive kaolin reserves across Georgia and Cornwall to sustain margin stability against volatile freight rates. Sibelco NV anchors its position through controlled distribution networks spanning Brazil and Western Europe. Thiele Kaolin Company specializes in high-brightness water-washed grades for coating paper applications.
Industrial clay encompasses naturally occurring aluminosilicate minerals—primarily kaolinite, montmorillonite, and illite—extracted through open-pit mining and processed via crushing, slurrying, centrifugation, and thermal treatment to achieve specified particle size distributions and brightness levels above ISO brightness 80. These materials serve as functional fillers, binders, and rheology modifiers across manufacturing processes where thermal stability and chemical inertness prove critical. Kaolin dominates value generation in paper coating applications where surface gloss and printability command premium pricing, while bentonite accelerates fastest in drilling fluids and foundry sand bonding where swelling capacity and green compression strength differentiate suppliers. Ceramics applications retain mature volume scale but face margin compression from energy-intensive kiln operations.
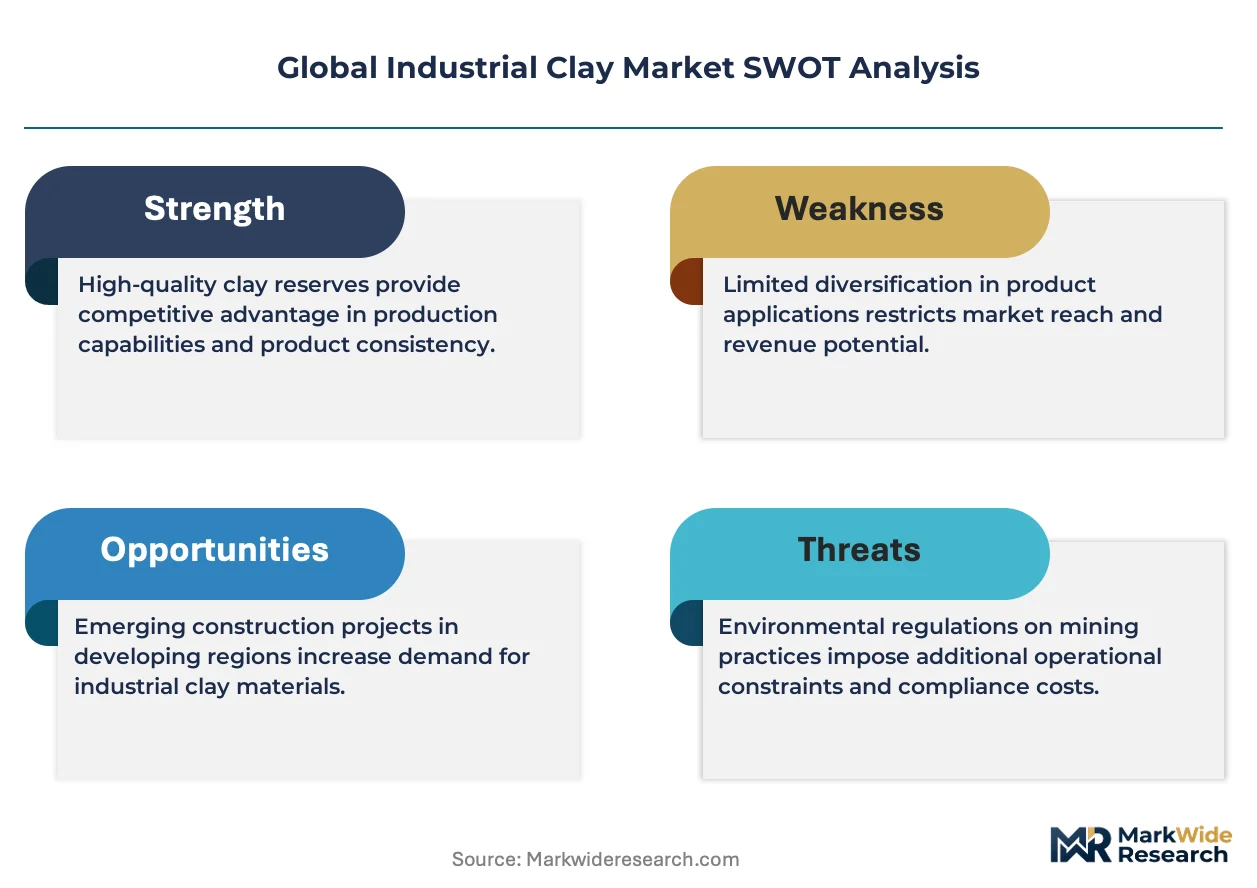
REACH registration requirements in Europe, EPA mining waste standards in the United States, and China's MEE ecological redline policies collectively constrain greenfield expansion and elevate remediation liabilities for clay producers. EMA and EFSA frameworks indirectly shape demand through pharmaceutical-grade and food-contact purity specifications that filter downstream to raw material sourcing criteria. Stakeholders must monitor how carbon border adjustment mechanisms and evolving tailings management codes reshape the cost structure of long-haul clay trade flows.
Market Dynamics
Energy-intensive kiln operations across ceramics manufacturing are compressing margins and accelerating supplier consolidation, while carbon border adjustment mechanisms threaten long-haul clay trade economics between extraction basins and consumption centers.
Growth Catalysts
- China's refractories corridor:Steel production capacity expansion in Hebei and Shanxi provinces sustains demand for high-alumina fireclay and calcined kaolin inputs used in blast furnace linings.
- REACH registration thresholds:ECHA compliance requirements for kaolin and bentonite derivatives are filtering out unregistered suppliers and concentrating volume among certified producers with established dossiers.
- Calcination technology advances:Flash calcination systems are improving thermal efficiency and brightness consistency in metakaolin production for pozzolanic cement applications.
Market Restraints
- Natural gas price volatility:Thermal processing of kaolin and bentonite requires sustained high-temperature firing, exposing producers to input cost swings that resist full pass-through to paper and ceramics buyers.
- Georgia kaolin belt concentration:Premium water-washed grades depend heavily on sedimentary deposits in the southeastern United States, creating geographic supply risk for coating paper manufacturers in Asia and Europe.
- Calcium carbonate substitution:Ground and precipitated calcium carbonate continues displacing kaolin in paper filling applications where brightness and opacity requirements permit lower-cost mineral alternatives.
Strategic Opportunities
- India's sanitaryware belt:Morbi and Thangadh manufacturing clusters are expanding vitreous china and ceramic sanitaryware output, generating unmet demand for plastic ball clay and feldspathic fluxes.
- EU Green Deal construction mandates:Embodied carbon regulations for building materials are creating preference for locally sourced clay additives in geopolymer cements and alkali-activated binders.
- Drilling fluids specification tightening:API and OCMA standards for oilfield bentonite are elevating barrier-to-entry for uncertified suppliers and rewarding producers with in-house quality verification laboratories.
Industry Challenges
- ISO 14001 certification timelines:Quarry operators face 12-18 month implementation cycles for environmental management systems, delaying access to European automotive and packaging supply chains.
- Legacy slurry pipeline infrastructure:Water-washed kaolin operations in Cornwall and Georgia depend on aging pipeline networks for slurry transport, requiring capital-intensive rehabilitation to maintain throughput reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Clay Market |
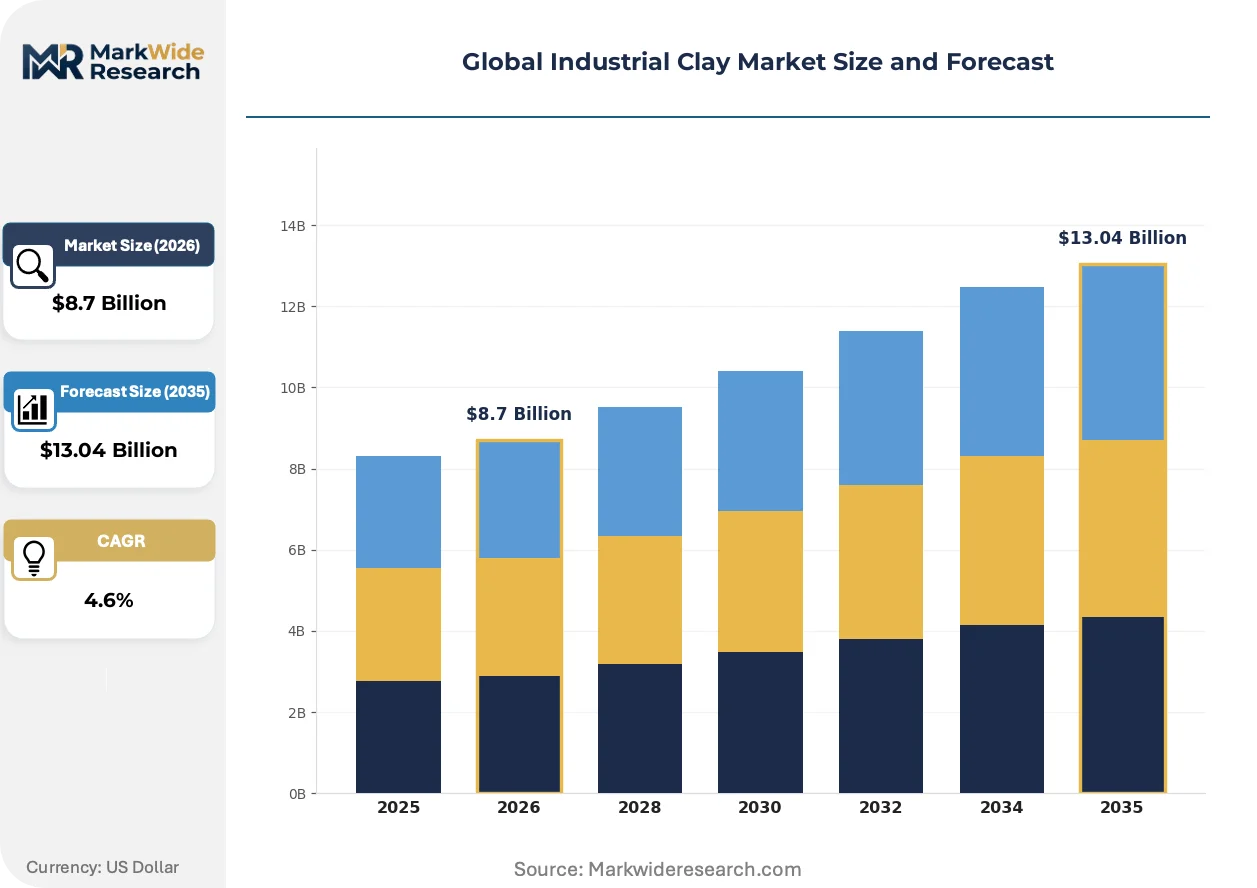
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kaolin, Bentonite, Fuller's Earth, Ball Clay Application: Ceramics, Paper, Paints, Cosmetics End User: Construction, Personal Care, Automotive, Agriculture Grade: Standard, High Purity, Natural, Synthetic |
| Companies Covered | Imerys SA, Sibelco NV, BASF SE, Minerals Technologies Inc., KaMin LLC, Thiele Kaolin Company, Ashapura Minechem Ltd, EP Minerals, Quarzwerke Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Clay Market Strategic Shifts
Dry-grinding and spray-drying technologies are reshaping particle engineering capabilities, while regulatory pressure on embodied carbon is redirecting R&D investment toward lower-temperature processing routes and alternative flux chemistries.
Metakaolin production is bifurcating between high-purity flash-calcined grades for ultra-high-performance concrete and lower-cost rotary-kiln outputs for mass-market cement replacement. Infrastructure contractors in the Netherlands and Germany are specifying the premium tier for marine exposure applications, while volume buyers in residential construction absorb economy grades. This split is compressing mid-range positioning and forcing producers to commit to single-tier process investments.
ECHA's evolving requirements for nanomaterial characterization are extending registration timelines for delaminated kaolin and surface-modified bentonite products. Manufacturers must now submit granular dissolution and ecotoxicity data previously exempt under bulk substance rules. Specialty coating applications in food-contact packaging face the steepest compliance burden, with several European compounders accelerating qualification of non-nano alternatives.
Buyers in the foundry sand sector are consolidating supplier relationships and demanding integrated technical service support for mold-making optimization. Tier-one automotive casting operations in Germany and Japan now specify clay suppliers based on joint R&D capability rather than commodity pricing alone. This preference shift favors producers with application laboratories co-located near major foundry clusters, disadvantaging distant exporters reliant on distributor technical support.
Global Industrial Clay Market Segmentation
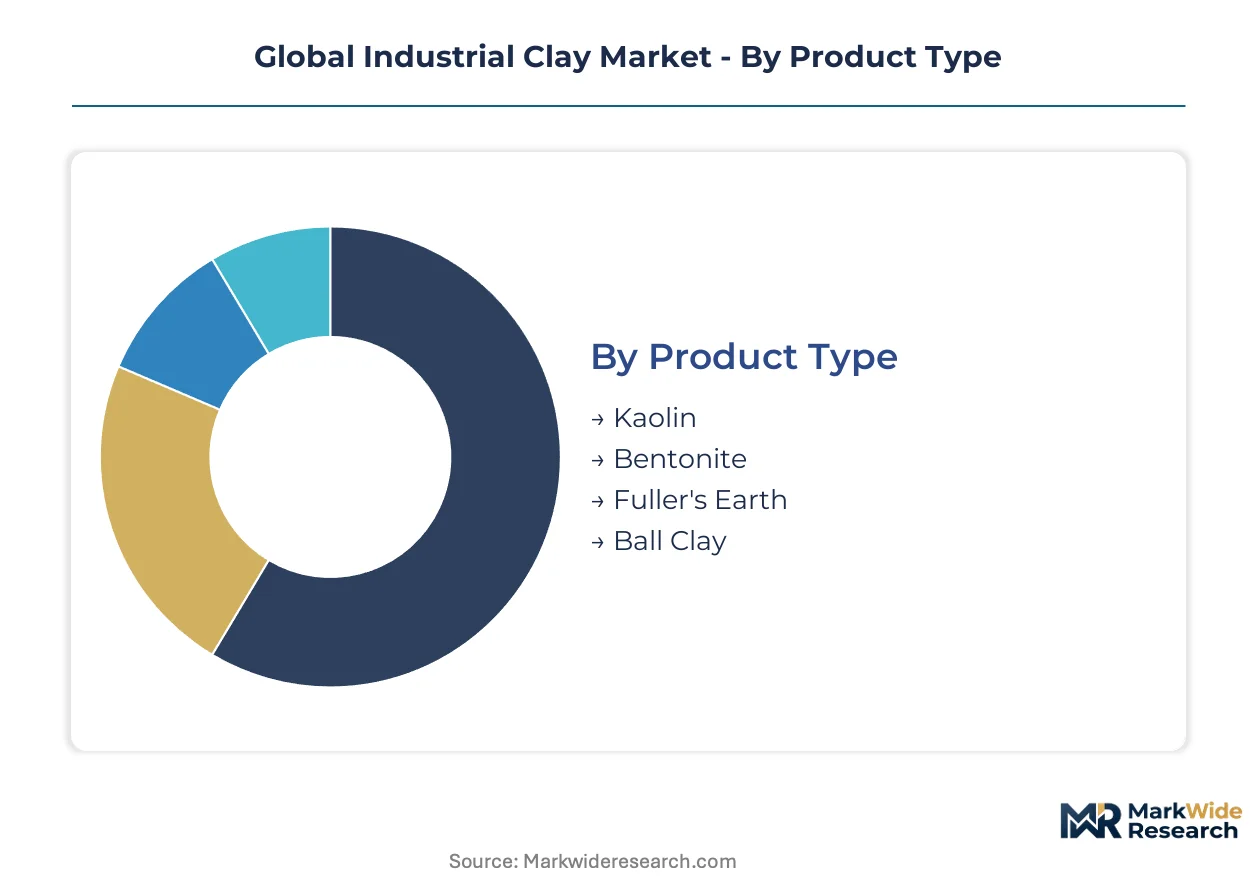
Industrial clay markets fragment across mineralogy, processing intensity, and end-use specifications that determine pricing power. Each segmentation axis reveals distinct margin architectures and competitive entry barriers.
Product Type:
Kaolin commands the widest margin dispersion, with water-washed brightness grades separating premium coating applications from commodity filler markets.
- Kaolin:Aluminosilicate mineral processed through slurrying, centrifugation, and thermal treatment to achieve ISO brightness thresholds above 80. Paper coating manufacturers in Japan and Germany specify high-brightness hydrous grades where surface gloss and printability justify cost premiums against calcium carbonate substitutes.
- Bentonite:Swelling clay dominated by montmorillonite content, graded by sodium versus calcium exchange capacity. Oilfield drilling fluid specifications from API and OCMA are concentrating procurement among producers with in-house quality verification laboratories in Texas and the Middle East.
- Fuller's Earth:Attapulgite-sepiolite clays valued for adsorptive capacity in edible oil refining and pet litter applications.
- Ball Clay:Fine-grained sedimentary kaolinite-illite mixtures prized for plasticity and unfired strength in ceramic sanitaryware.
Kaolin holds installed capacity. Bentonite is rotating up the share rankings.
Application:
Application segments diverge sharply on energy intensity, with ceramics retaining volume scale while paper coating defends value concentration.
- Ceramics:Tile, sanitaryware, and refractory manufacturing consumes ball clay and fireclay for plasticity and thermal stability. Morbi and Thangadh clusters in India are expanding vitreous china output, generating unmet demand for plastic ball clay imports.
- Paper:Coating and filling applications specify particle size distribution and brightness for surface finish and opacity. Ground calcium carbonate continues displacing kaolin in filling applications where brightness requirements permit lower-cost mineral alternatives.
- Paints:Extender and rheology modifier functions leverage kaolin and bentonite for scrub resistance and sag control.
- Cosmetics:Talc-substitute and absorbent applications demand heavy metal testing and microbiological certification.
Ceramics anchors volume throughput. Paper coating preserves value density against substitution pressure.
End User:
End-user concentration tracks construction cycle exposure and regulatory certification burden, with personal care and automotive demanding the steepest purity documentation.
- Construction:Geopolymer cements, alkali-activated binders, and ceramic infrastructure absorb metakaolin and calcined clay volumes. EU Green Deal embodied carbon regulations are creating preference for locally sourced clay additives in the Netherlands and Germany.
- Personal Care:Pharmaceutical-grade and food-contact purity specifications from EMA and EFSA frameworks filter downstream to raw material sourcing criteria for talc-free formulations.
- Automotive:Foundry sand bonding for engine block casting specifies bentonite green compression strength and thermal durability.
- Agriculture:Carrier applications for pesticides and animal feed supplements utilize attapulgite and bentonite for controlled release.
Construction commands tonnage scale. Personal care is climbing the fastest on certification premiums.
Grade:
Grade stratification reflects processing depth, with synthetic and high-purity tiers capturing margin expansion from specification tightening.
- Standard:Run-of-mine or minimally processed clays for bulk filler and construction applications where functional performance tolerates natural variability.
- High Purity:Acid-washed, magnetic separation, or selective mining products for pharmaceutical, food-contact, and electronics applications. ECHA nanomaterial characterization requirements are extending registration timelines for delaminated kaolin and surface-modified bentonite.
- Natural:Unmodified mineralogies for organic-certified cosmetics and traditional ceramics markets.
- Synthetic:Engineered layered double hydroxides and pillared clays for catalysis and advanced polymer nanocomposites.
High Purity captures specification premiums. Synthetic grades are gaining share fastest on advanced materials demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper coating manufacturers in Japan and Germany concentrate procurement of high-brightness hydrous kaolin, while ceramics fabricators across India and China drive bulk volume absorption of ball clay and fireclay grades.
United States
Sedimentary kaolin deposits in Georgia supply water-washed brightness grades above ISO 80 for coating paper applications. EPA mining waste standards constrain greenfield expansion and elevate remediation liabilities for quarry operators. The southeastern pipeline networks transport slurry to Savannah port facilities serving Asian and European buyers.
China
Steel production capacity expansion in Hebei and Shanxi provinces sustains demand for high-alumina fireclay and calcined kaolin in blast furnace linings. MEE ecological redline policies restrict extraction permits and force rehabilitation bonding for open-pit operations. The Yangtze River Delta hosts refractories fabricators integrating domestic clay with imported bauxite.
Germany
Foundry sand bonding for automotive engine block casting specifies bentonite green compression strength and thermal durability. ECHA REACH registration requirements for kaolin and bentonite derivatives filter out unregistered suppliers from automotive supply chains. The Ruhr industrial corridor concentrates tier-one automotive casting operations demanding joint R&D capability from clay suppliers.
India
Morbi and Thangadh manufacturing clusters expand vitreous china and ceramic sanitaryware output, generating unmet demand for plastic ball clay and feldspathic fluxes. BIS certification timelines for construction materials delay access to government infrastructure contracts. Gujarat's ceramics belt imports ball clay from Indonesia and Thailand to supplement domestic deposits.
Brazil
Attapulgite-sepiolite deposits in the northeast supply adsorptive clays for edible oil refining and pet litter applications. ANVISA pharmaceutical-grade purity specifications filter downstream to raw material sourcing criteria for cosmetics manufacturers. São Paulo state concentrates compounders serving Latin American personal care markets with certified clay additives.
Global Industrial Clay Market Competitive Environment
Player mix skews toward integrated mineral processors with captive reserves and controlled distribution networks. Tier-one producers leverage backward integration into quarry operations to sustain margin stability against volatile freight rates. Mid-cap specialists occupy positions in high-purity grades for pharmaceutical and food-contact applications. Competitive moves center on M&A for reserve base expansion and capacity expansion in flash calcination systems for metakaolin production.
Within the integrated processor tier, Imerys SA and Sibelco NV exemplify archetypes combining captive reserves with multi-regional distribution footprints. Thiele Kaolin Company occupies a position among North American specialists in water-washed brightness grades. These three entities represent distinct strategic postures: European-based multi-mineral conglomerates, Belgian-controlled distribution-anchored operators, and United States-based single-mineral specialists.
| Leading Market Players |
|---|
| Imerys SA |
| Sibelco NV |
| BASF SE |
| Minerals Technologies Inc. |
| KaMin LLC |
| Thiele Kaolin Company |
| Ashapura Minechem Ltd |
| EP Minerals |
| Quarzwerke Group |
| Others |
Value Chain & Pricing Dynamics
REACH registration dossiers for kaolin and bentonite derivatives gate both European market access and price stratification, compressing unregistered suppliers into spot-market tiers while certified producers capture contract premiums through automotive and packaging supply chain qualification.
Pricing Analysis
Long-term offtake contracts with natural gas indexation dominate thermal processing tiers, separating flash-calcined metakaolin premiums from rotary-kiln economy outputs. Price differentiation hinges on ISO brightness certification above 80 and ECHA nanomaterial characterization compliance. Cost compression in standard-grade ball clay intensifies as Indonesian imports undercut domestic Indian supply. Paper coating manufacturers in Japan exhibit lowest price sensitivity, prioritizing surface gloss consistency over filler substitution economics.
Supply Chain Analysis
The United States, China, and Brazil anchor extraction for water-washed kaolin, high-alumina fireclay, and attapulgite-sepiolite deposits respectively. Processing draws from natural gas feedstock for calcination, diesel for open-pit mining operations, and specialized flocculants for slurry refinement. Single-source vulnerability concentrates in Georgia's sedimentary belt, where aging pipeline infrastructure to Savannah port facilities creates throughput risk. Distribution runs through controlled networks of integrated mineral processors with captive reserves and co-located technical service laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial clay markets sit in early-cycle expansion as EU Green Deal embodied carbon mandates accelerate specification-grade metakaolin adoption in geopolymer cement formulations across Dutch and German infrastructure procurement.
For Market Incumbents: Secure captive reserves in India's expanding sanitaryware belt through long-term ball clay supply agreements with Morbi and Thangadh clusters. Deepen backward integration into flash calcination systems to defend margin stability against natural gas price volatility threatening rotary-kiln operators. For New Entrants and Emerging Players: Anchor in pharmaceutical-grade bentonite purification, where ANVISA and EMA certification barriers filter out commodity suppliers and reward specialized entrants with laboratory-scale magnetic separation capabilities. Target white-space demand from Brazilian cosmetics compounders seeking talc-substitute attapulgite with heavy metal documentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-purity grade processing as ECHA nanomaterial characterization extends registration timelines and forces dedicated ecotoxicity testing infrastructure. Acquisition targets with established dossiers and in-house quality verification laboratories offer superior long-term viability. Monitor API drilling fluid specification tightening as inflection signal for oilfield bentonite consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Imerys SA and Sibelco NV leverage Georgia and Cornwall deposits to insulate margin stability from volatile freight rates. |
| Flash Calcination Capacity Expansion | Metakaolin producers in Germany and the Netherlands capture EU Green Deal preference for lower-embodied-carbon cement additives. |
| Long-term Supply Agreement with Foundry Clusters | Tier-one automotive casting operations in Germany's Ruhr corridor now specify suppliers based on joint R&D capability. |
| Pharmaceutical-grade Certification Investment | EMA and EFSA purity specifications filter downstream to raw material sourcing criteria for talc-free personal care formulations. |
| Joint Venture in India's Sanitaryware Belt | Morbi and Thangadh clusters generate unmet demand for plastic ball clay imports from Indonesia and Thailand. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with quarry operators, ceramics plant managers, and paper coating procurement leads; and secondary validation through customs trade records, SEC 10-K filings of listed mineral processors, and ECHA registration dossiers. Bottom-up volume estimates from extraction site capacities reconciled with top-down demand absorption across construction, paper, and foundry end-use segments.
Across the analysis window, forecasts triangulate mineralogy-grade segmentation with processing intensity tiers and geographic production hub clustering. CAGRs derive from elasticity modeling against steel output trajectories in Hebei and Shanxi, sanitaryware capacity buildout in Gujarat, and paper coating substitution rates by calcium carbonate. Key inputs include natural gas price scenarios for thermal processing and REACH compliance timeline assumptions for nanomaterial characterization.
Underlying assumptions cover sustained infrastructure investment in China's refractories corridor and EU Green Deal implementation pace, with deviation risk concentrated in carbon border adjustment mechanism scope expansion and legacy slurry pipeline rehabilitation delays. Recalibration cycles align with material shifts in ECHA guidance documents and MEE ecological redline policy enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Refractory Material Market
Ceramics
Global Ceramic Foams Market
Ceramics
Ceramic Frit Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Ceramic Pigments Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
ME K-Feldspar Market
Ceramics
Industrial Ceramics Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Wollastonite Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Zirconium Dioxide Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Glazed Bricks Market
Ceramics
Titanates Market