
 Ceramic Injection Molding Market | 2026-2036
Ceramic Injection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Injection Molding Market Intelligence
Multi-material mold design with conformal cooling channels is reshaping how ceramic injection molders achieve dimensional tolerances below 25 micrometers. CoorsTek Inc sustains vertical integration from powder synthesis to finished medical implants across its North American and Asian plants. Morgan Advanced Materials plc dominates high-purity alumina feedstock supply for aerospace thermal barrier coatings. Indo-MIM Pvt Ltd leverages India's cost base to compete on complex zirconia dental and industrial components at scale.
Ceramic injection molding forms complex-shaped technical ceramic parts by injecting a thermoplastic binder loaded with ceramic powder into precision molds, followed by debinding and sintering to achieve densities exceeding 95% theoretical. The process serves industries requiring extreme hardness, thermal stability, and corrosion resistance in net-shape geometries impractical for conventional machining. Medical Devices and Aerospace represent the fastest-expanding application segments, driven by patient-specific implant geometries and turbine engine efficiency mandates. Conventional Injection Molding retains the largest volume share, while Additive Manufacturing of ceramic feedstock is gaining traction for prototype-to-production workflows in research-intensive end user segments.
EMA's Medical Device Regulation and FDA's 21 CFR Part 820 quality system requirements impose biocompatibility and traceability standards that filter out non-specialized molders from medical supply chains. REACH restrictions on heavy-metal stabilizers in polymer binders are forcing reformulation of feedstock systems across European manufacturing bases. EPA air emissions rules for debinding ovens affect plant siting decisions in the US industrial ceramics corridor. Stakeholders must monitor how evolving powder recycling regulations and energy-intensive sintering costs reshape geographic competitiveness between established European suppliers and emerging Asian precision ceramic hubs.
Market Dynamics
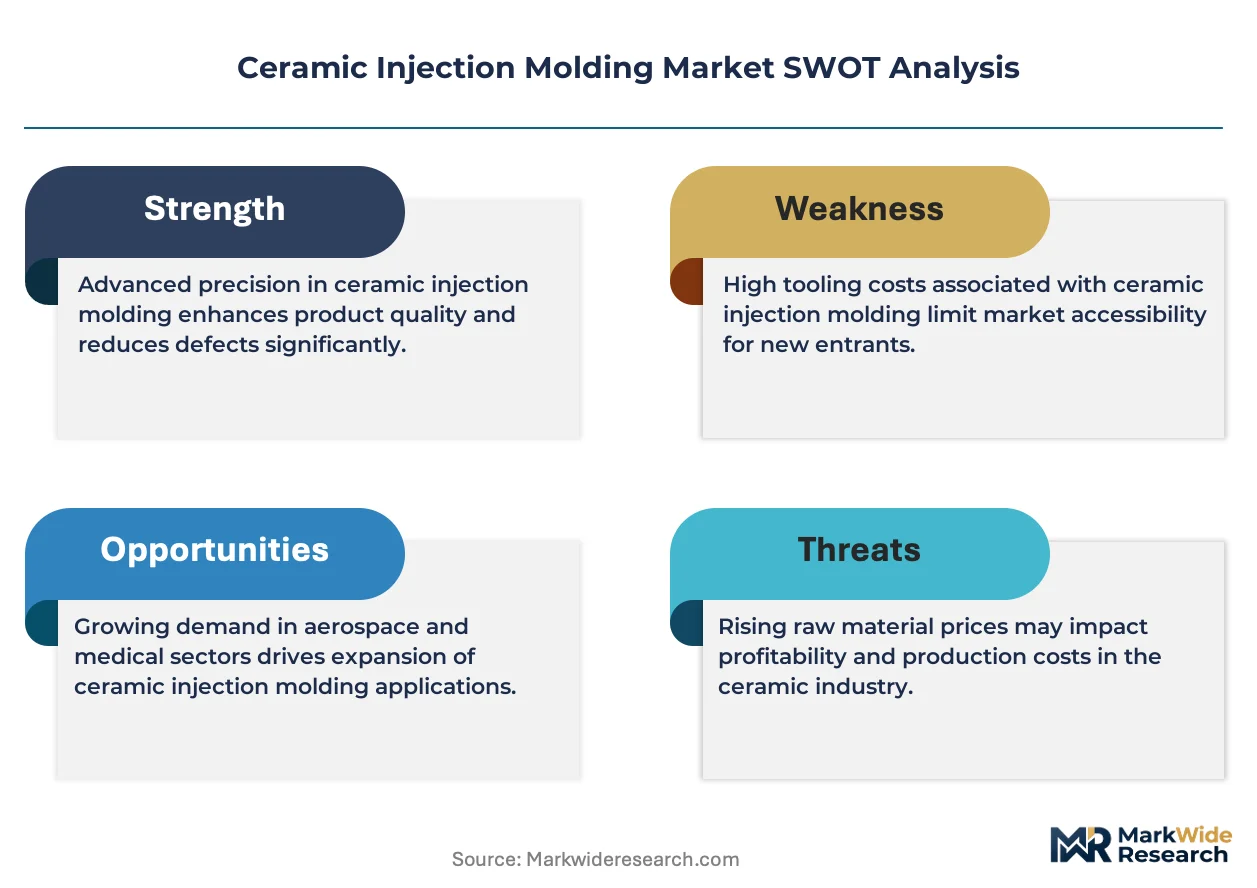
REACH restrictions on heavy-metal stabilizers in polymer binders are forcing feedstock reformulation across European manufacturing bases, while aerospace turbine blade manufacturers expand procurement of alumina and zirconia injection-molded components.
Growth Catalysts
- EMA Medical Device Regulation:Biocompatibility and traceability standards filter out non-specialized molders from medical supply chains, concentrating demand among certified European suppliers.
- Aerospace thermal barrier coatings:Turbine engine efficiency mandates drive demand for high-purity alumina feedstock in net-shape geometries impractical for conventional machining.
- Germany's precision ceramics cluster:Specialized moldmakers and research institutes co-locating around Munich and Stuttgart accelerate prototyping-to-production cycles.
Market Restraints
- Energy-intensive sintering costs:Natural gas and electricity price volatility compress margins for European producers operating high-temperature furnaces.
- Feedstock supply concentration:High-purity alumina and zirconia powder production concentrates among limited specialty chemical suppliers, creating input bottlenecks.
- EPA air emissions rules:Debinding oven regulations restrict plant siting decisions in the US industrial ceramics corridor, limiting greenfield expansion options.
Strategic Opportunities
- India's cost-competitive manufacturing base:Complex zirconia dental and industrial components production scales at lower unit economics than European equivalents.
- Additive Manufacturing convergence:Ceramic feedstock 3D printing enables prototype-to-production workflows in research-intensive medical and aerospace segments.
- EU Green Deal industrial decarbonization incentives:Electrified sintering and renewable-powered debinding qualify for green manufacturing subsidies.
Industry Challenges
- Multi-material mold design expertise gap:Conformal cooling channel engineering requires computational fluid dynamics specialists scarce in traditional ceramics regions.
- FDA 21 CFR Part 820 certification timelines:Quality system documentation and biocompatibility testing extend medical implant supplier qualification periods.
- Debinding-sintering process integration:Thermal profile mismatches between legacy batch ovens and continuous sintering lines disrupt yield consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Injection Molding Market |
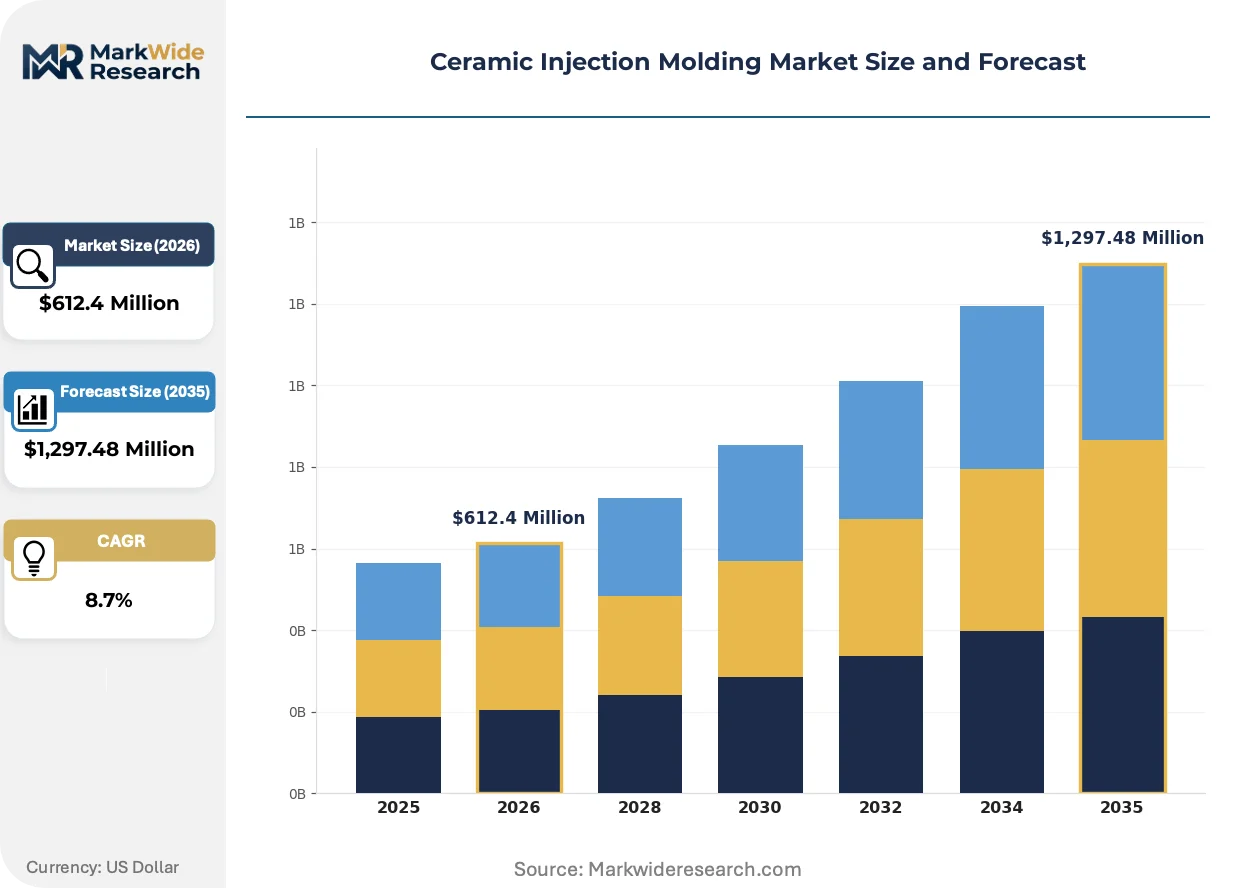
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Molds, Injection Machines, Feedstock, Auxiliary Equipment Application: Aerospace, Medical Devices, Electrical Insulators, Automotive Components End User: Manufacturers, Research Institutions, OEMs, Tier-1 Suppliers Technology: Hot Isostatic Pressing, Conventional Injection Molding, Additive Manufacturing, Extrusion |
| Companies Covered | ARBURG GmbH + Co KG, CoorsTek Inc, Ortech Advanced Ceramics, OECHSLER AG, Morgan Advanced Materials plc, Indo-MIM Pvt Ltd, Micro Kläger Spritzguss GmbH & Co KG, Nishimura Advanced Ceramics, Paul Rauschert GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Injection Molding Market Strategic Shifts & Innovations
Digital process control and regulatory harmonization are compressing development cycles while reshaping how ceramic injection molders qualify for medical and aerospace supply chains.
Real-time thermal monitoring systems with machine learning feedback loops are digitizing debinding and sintering parameter optimization. Medical implant manufacturers in Germany and Switzerland adopt these systems fastest, reducing defect rates and batch-to-batch variation. The technology is digitizing quality documentation for FDA and EMA submissions, shortening certification timelines.
REACH restrictions on heavy-metal stabilizers in polymer binders are eliminating legacy feedstock formulations across European manufacturing bases. Compounders must certify alternative binder chemistries through ECHA notification procedures, raising R&D costs. Medical device and dental implant segments face the steepest compliance burdens, accelerating supplier consolidation toward vertically integrated feedstock producers.
Patient-specific implant geometries are displacing standard catalog sizes in orthopedic and dental applications. Hospital procurement groups and specialized distributors now specify lot-size-one production capabilities, compressing traditional volume-based pricing models. Germany, Switzerland, and Japan exhibit the strongest demand rotation toward customization, rewarding molders with rapid tooling changeover systems.
Ceramic Injection Molding Market Segmentation
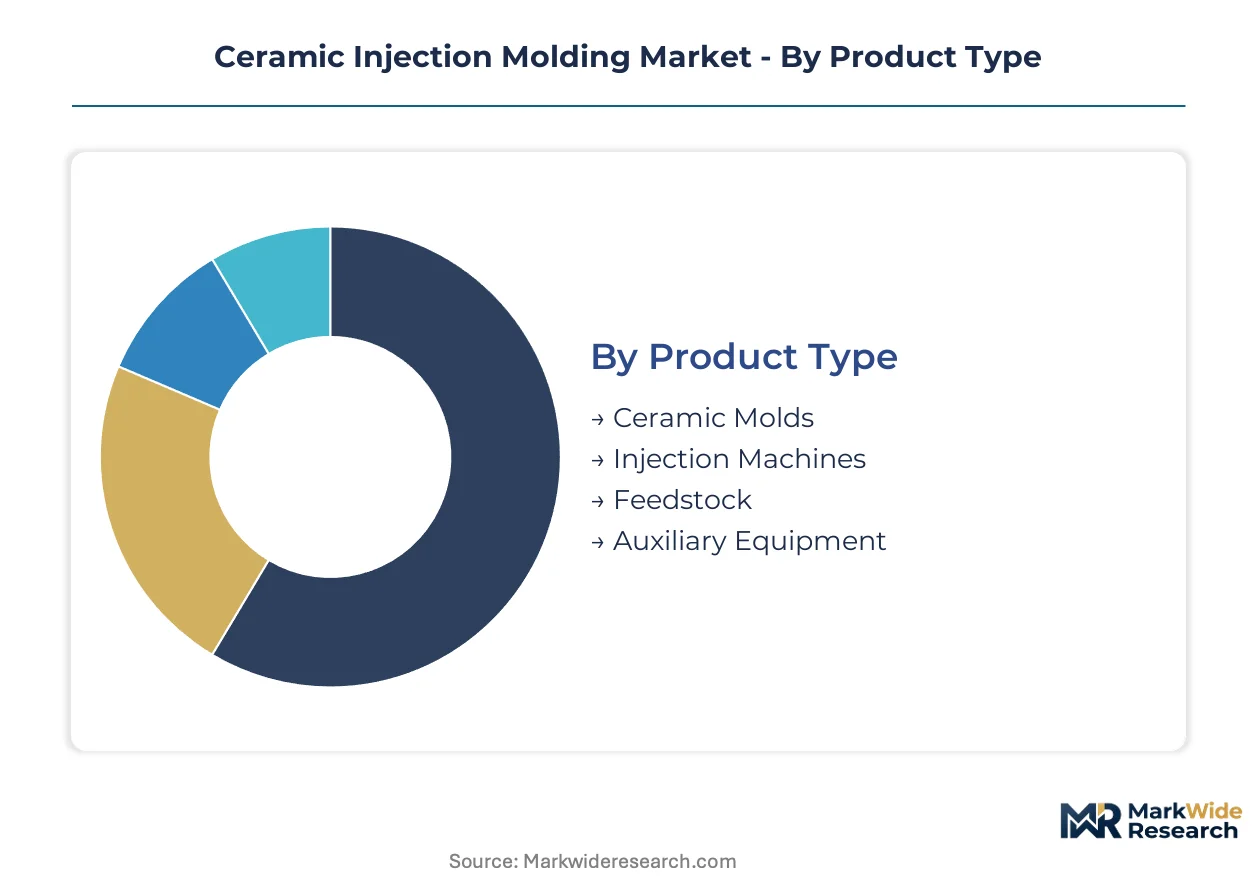
Ceramic injection molding market segmentation reveals how equipment specifications, application requirements, and technology choices reshape procurement patterns across medical, aerospace, and industrial supply chains. Understanding these dimensions exposes where margin pools concentrate and which customer types drive capacity expansion decisions.
Product Type:
Equipment and materials segmentation tracks capital intensity tiers from precision tooling to consumable feedstock, mapping where recurring revenue concentrates against one-time infrastructure investments.
- Ceramic Molds:Multi-cavity tooling with conformal cooling channels achieves dimensional tolerances below 25 micrometers for medical implant geometries. Demand clusters in Germany's precision ceramics corridor around Munich and Stuttgart, where moldmakers co-locate with research institutes to compress prototyping cycles. Aerospace turbine blade manufacturers are expanding procurement of alumina and zirconia-compatible mold systems.
- Injection Machines:Servo-electric clamping systems with real-time pressure feedback dominate medical-grade production lines requiring lot-size-one flexibility. EMA Medical Device Regulation compliance filters procurement toward European machine builders with integrated traceability documentation. Energy-efficient models qualify for EU Green Deal industrial decarbonization subsidies.
- Feedstock:Thermoplastic binder systems loaded with high-purity alumina or zirconia powder achieve densities exceeding 95% theoretical after sintering. REACH restrictions on heavy-metal stabilizers are forcing reformulation across European manufacturing bases.
- Auxiliary Equipment:Debinding ovens and thermal monitoring systems complete integrated production cells. EPA air emissions rules restrict plant siting decisions in the US industrial ceramics corridor.
Injection machines hold installed capacity. Feedstock is rotating up the share rankings as REACH compliance extends reformulation cycles and captive supply strategies.
Application:
End-use segmentation captures how patient-specific geometries, turbine efficiency mandates, and electrical miniaturization reshape volume-mix and certification requirements.
- Aerospace:Thermal barrier coating components in net-shape geometries impractical for conventional machining address turbine engine efficiency mandates. High-purity alumina feedstock from Morgan Advanced Materials plc dominates this segment. FAA certification timelines and material traceability requirements filter supplier bases.
- Medical Devices:Patient-specific orthopedic and dental implants displace standard catalog sizes, compressing traditional volume-based pricing models. FDA 21 CFR Part 820 quality system requirements and EMA Medical Device Regulation impose biocompatibility standards that concentrate demand among certified European suppliers. Germany, Switzerland, and Japan exhibit the strongest demand rotation toward customization.
- Electrical Insulators:Miniaturized ceramic housings for high-voltage applications serve power electronics and semiconductor equipment manufacturers. BIS standards in India and JIS standards in Japan shape regional specification divergence.
- Automotive Components:Sensors, spark plug insulators, and exhaust system parts leverage thermal stability and corrosion resistance. Cost pressures favor Indo-MIM Pvt Ltd's Indian manufacturing base for complex zirconia components at scale.
Medical devices command premium pricing tiers. Aerospace is climbing the fastest as turbine blade procurement expands and thermal barrier coating specifications tighten.
End User:
Customer type segmentation distinguishes between integrated producers capturing margin across the value chain versus specialized purchasers relying on external molders for complex geometries.
- Manufacturers:Vertically integrated ceramic producers like CoorsTek Inc sustain operations from powder synthesis through finished medical implants across North American and Asian plants. These entities internalize mold design expertise and captive feedstock supply to defend margin positions.
- Research Institutions:University and national laboratory users drive additive manufacturing of ceramic feedstock adoption for prototype-to-production workflows. Germany's Fraunhofer institutes and Switzerland's materials science clusters accelerate technology transfer.
- OEMs:Original equipment manufacturers in medical implant and aerospace turbine supply chains specify lot-size-one capabilities and rapid tooling changeover systems. Procurement groups now mandate digital quality documentation for FDA and EMA submissions.
- Tier-1 Suppliers:Specialized molders serving automotive and industrial markets compete on complex zirconia dental and industrial components at scale, with Indo-MIM Pvt Ltd leveraging India's cost base.
Manufacturers hold process control advantages. Research institutions are gaining influence fastest as additive manufacturing convergence accelerates.
Technology:
Process technology segmentation tracks the shift from established batch methods toward digitized, continuous, and additive alternatives reshaping yield consistency and certification timelines.
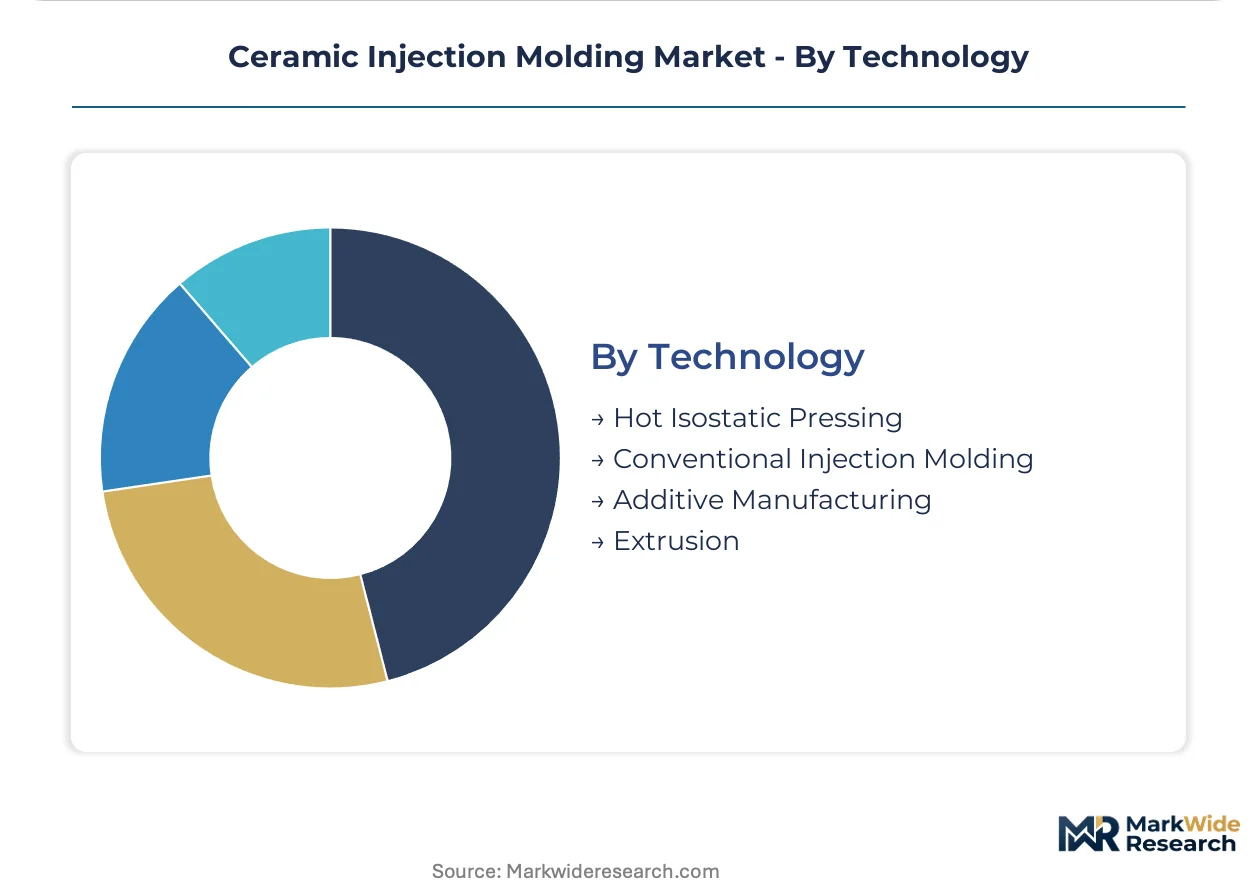
- Conventional Injection Molding:Retains the largest volume share through thermoplastic binder injection into precision molds followed by debinding and sintering. Legacy batch ovens face thermal profile mismatches with continuous sintering lines that disrupt yield consistency.
- Additive Manufacturing:Ceramic feedstock 3D printing enables prototype-to-production workflows in research-intensive medical and aerospace segments. Real-time thermal monitoring with machine learning feedback loops is digitizing parameter optimization fastest in Germany and Switzerland.
- Hot Isostatic Pressing:Post-sintering densification achieves near-theoretical density for critical aerospace and medical components. Gas and electricity price volatility compress margins for European producers operating high-temperature equipment.
- Extrusion:Continuous profile production serves electrical insulator and structural ceramic applications with simpler geometries. Lower capital requirements attract entry-level producers in emerging Asian precision ceramic hubs.
Conventional injection molding anchors volume. Additive manufacturing is expanding most quickly as digital process control shortens medical implant certification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision moldmakers export alumina and zirconia components to aerospace turbine manufacturers in the United States and Japan. India's Indo-MIM Pvt Ltd ships complex zirconia dental implants to European distributors under EMA Medical Device Regulation frameworks. Trade corridors link specialized ceramics clusters across three continents.
United States
FAA certification timelines and turbine blade procurement from domestic aerospace OEMs drive alumina feedstock consumption. EPA air emissions rules for debinding ovens restrict plant siting in the industrial ceramics corridor. Greater Boston hosts medical implant startups qualifying suppliers under FDA 21 CFR Part 820 quality systems.
Germany
EMA Medical Device Regulation biocompatibility standards concentrate demand among certified molders serving orthopedic and dental segments. REACH restrictions on heavy-metal stabilizers force polymer binder reformulation across Bavarian manufacturing bases. Munich and Stuttgart co-locate specialized moldmakers with Fraunhofer research institutes to compress prototyping cycles.
Japan
METI industrial standards and patient-specific implant geometries reshape procurement toward lot-size-one production capabilities. JIS certification requirements filter supplier bases for electrical insulator applications. The Kansai region around Osaka maintains precision ceramics heritage serving semiconductor equipment manufacturers.
India
BIS standards for electrical insulators and cost-competitive zirconia component production attract dental implant distributors from Europe and North America. PLI scheme incentives support precision ceramics capacity expansion in Gujarat and Tamil Nadu. Indo-MIM Pvt Ltd leverages this manufacturing base for complex geometries at scale.
Switzerland
Swissmedic medical device regulations and orthopedic implant traceability requirements reward molders with digital quality documentation systems. Research institutions in the materials science cluster accelerate additive manufacturing technology transfer. Swiss buyers specify rapid tooling changeover systems for patient-specific geometries.
Ceramic Injection Molding Market Key Industry Players
On the supply side, the industry is bifurcated between vertically integrated powder-to-implant producers and specialized molders serving external OEMs. Three strategic archetypes dominate: captive feedstock manufacturers controlling alumina and zirconia supply chains, precision mold engineering specialists achieving sub-25-micrometer tolerances, and cost-optimized scale producers leveraging emerging-market manufacturing bases. Competitive moves center on backward integration into high-purity powder synthesis and geographic expansion to qualify for regional regulatory frameworks.
Within the vertically integrated tier, CoorsTek Inc and Morgan Advanced Materials plc occupy positions spanning powder synthesis through finished component delivery. Indo-MIM Pvt Ltd exemplifies the scale-driven archetype, leveraging India's manufacturing base for complex zirconia geometries. ARBURG GmbH + Co KG anchors the precision equipment segment, supplying servo-electric injection systems to medical-grade production lines requiring lot-size-one flexibility. These three entities represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| ARBURG GmbH + Co KG |
| CoorsTek Inc |
| Ortech Advanced Ceramics |
| OECHSLER AG |
| Morgan Advanced Materials plc |
| Indo-MIM Pvt Ltd |
| Micro Kläger Spritzguss GmbH & Co KG |
| Nishimura Advanced Ceramics |
| Paul Rauschert GmbH & Co KG |
| Others |
Cost & Logistics Intelligence
High-purity alumina and zirconia powder production concentrates among limited specialty chemical suppliers in Germany and Japan, anchoring margin capture in feedstock formulation while downstream molders face cost pass-through pressure from energy-intensive sintering operations.
Pricing Analysis
Conventional injection molding systems, additive manufacturing platforms, and hot isostatic pressing equipment occupy distinct pricing tiers based on capital intensity and certification documentation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical-grade production lines from industrial ceramic runs and prototype-scale extrusion systems. Pricing pressure stems from REACH-driven feedstock reformulation costs in Europe, with certified European molders least price-sensitive due to regulatory barrier protection while automotive tier-1 suppliers in India compete aggressively on unit economics.
Supply Chain Analysis
Upstream feedstock supply draws from high-purity alumina refineries in Germany, zirconia processors in Japan, and specialty binder compounders in Switzerland. Critical dependencies include ceramic powder particle size distribution, thermoplastic binder rheology, and mold steel thermal conductivity. Single-source vulnerability concentrates in aerospace-certified alumina feedstock where Morgan Advanced Materials plc dominates thermal barrier coating specifications. Distribution runs through direct OEM contracts for medical implants and specialized ceramics distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic injection molding incumbents face substitution pressure from metal additive manufacturing in turbine blade prototyping and polymer 3D printing in dental surgical guides, requiring active defense of net-shape geometry advantages in thermal and corrosion-critical applications.
For Market Incumbents: Pre-empt feedstock supply disruption by securing captive alumina and zirconia powder synthesis capacity or long-term offtake agreements with REACH-compliant European compounders. Accelerate FDA 21 CFR Part 820 and EMA MDR certification documentation to maintain exclusionary positioning against Asian cost competitors in medical implant supply chains.
For New Entrants and Emerging Players: Pursue additive manufacturing convergence opportunities in research-intensive medical and aerospace segments where prototype-to-production workflows remain underdeveloped. Target India's precision ceramics capacity expansion zones in Gujarat and Tamil Nadu for complex zirconia dental components, leveraging PLI scheme incentives and BIS standards familiarity to qualify for European distributor procurement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision mold engineering specialists achieving sub-25-micrometer tolerances in Germany's Munich-Stuttgart corridor. Long-term viability hinges on electrified sintering adoption qualifying for EU Green Deal subsidies. Watch for inflection in powder recycling regulation stringency reshaping geographic competitiveness between European and Asian manufacturing bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captive alumina supply from Morgan Advanced Materials plc secures aerospace thermal barrier coating margins against feedstock bottlenecks. |
| EMA MDR Certification Investment | Biocompatibility documentation filters non-specialized molders from European orthopedic implant procurement concentrating demand. |
| Electrified Sintering Conversion | Renewable-powered furnace upgrades qualify for EU Green Deal industrial decarbonization subsidies in Bavarian manufacturing bases. |
| Additive Manufacturing Platform Launch | Ceramic feedstock 3D printing enables lot-size-one production for patient-specific geometries in German hospital procurement. |
| India Manufacturing Footprint Expansion | Gujarat and Tamil Nadu precision ceramics clusters leverage PLI scheme incentives for complex zirconia dental component scale. |
Research Approach
A standing panel of ceramic injection molding plant managers, aerospace OEM procurement leads, medical device regulatory affairs directors, and dental implant distributor category buyers provided ongoing calibration. Primary interview insights combined with secondary validation from ECHA REACH registration databases, FDA 510(k) submission records, SEC 10-K filings of listed ceramics producers, and German Fraunhofer institute technology transfer reports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include product type (molds, machines, feedstock, auxiliary equipment), application (aerospace, medical devices, electrical insulators, automotive), end user archetype (manufacturers, research institutions, OEMs, tier-1 suppliers), and technology generation (conventional, additive, post-processing). CAGRs derived from regression analysis against historical capacity expansion announcements and regulatory compliance cost trajectories. Industry-specific inputs included natural gas price volatility coefficients for European sintering operations and EMA MDR certification timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, aerospace OEM production rates, or dental implant reimbursement policies would shift the trajectory. Cross-checking against customs trade data for alumina and zirconia powder shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Barium Carbonate Powder Market
Ceramics
North America Barium Carbonate Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Ceramic Binders Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Wollastonite Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Technical Ceramics Market
Ceramics
China Ceramic Market
Ceramics
White Fused Alumina Market
Ceramics
Global Alumina Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Traditional Ceramic Market