
 Global Dental Zirconia Block Market | 2026-2036
Global Dental Zirconia Block Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Zirconia Block Market Foresight
China is narrowing its reliance on imported zirconia blanks as domestic sintering capacity scales across Zhejiang and Guangdong provinces. Ivoclar Vivadent leverages proprietary multi-layer shading technology to sustain premium positioning in European dental laboratories. Dentsply Sirona anchors North American distribution through integrated CAD/CAM system sales, while Yucera competes aggressively on cost for standard monolithic blocks in emerging Asian markets.
Dental zirconia blocks are pre-sintered or fully sintered ceramic blanks composed primarily of yttria-stabilized tetragonal zirconia polycrystal (Y-TZP), engineered for subtractive CAD/CAM milling into permanent prosthetic restorations. These blocks achieve flexural strengths exceeding 900 MPa after final sintering, making them suitable for posterior crown applications where occlusal load tolerance is critical. Multi-layer zirconia dominates value capture due to gradient translucency that mimics natural dentin-enamel transitions, while high translucency zirconia grows fastest among anterior-focused cosmetic procedures. Dental crowns anchor volume demand across all manufacturing technology tiers, though 3D printing-compatible block formulations represent an emerging structural shift in fabrication economics.
FDA 510(k) clearance pathways govern zirconia block commercialization in the United States, while the EU Medical Device Regulation (MDR) and CE marking requirements enforce post-market surveillance and clinical evidence standards across European member states. ISO 13356 specifies the chemical and physical benchmarks for surgical-grade zirconia ceramics, directly influencing procurement specifications at dental laboratory chains and hospital-based prosthodontic departments. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital dentistry guidance updates to anticipate certification bottlenecks that could reshape competitive access timelines.
Market Dynamics
The dental zirconia block market pivots on digital workflow adoption, where intraoral scanning and chairside milling compress turnaround times from weeks to hours. Laboratories in Germany and China are racing to integrate these systems, while regulatory documentation burdens in the EU and US reshape supplier qualification requirements.
Growth Catalysts
- CAD/CAM chairside systems:Dental clinics in Japan deploy compact milling units that eliminate laboratory outsourcing for single-unit restorations. This shortens patient visits and captures margin previously lost to external fabrication.
- EU Medical Device Regulation post-market surveillance:MDR enforcement elevates documentation standards for biocompatibility traceability. Suppliers with pre-emptive clinical data packages secure faster notified body approvals and preferred supplier status at hospital-based prosthodontic departments.
- Domestic sintering networks:Zhejiang and Guangdong provinces in China scale captive zirconia blank production. Local milling centers reduce import dependency and slash logistics lead times for domestic dental chains.
Market Restraints
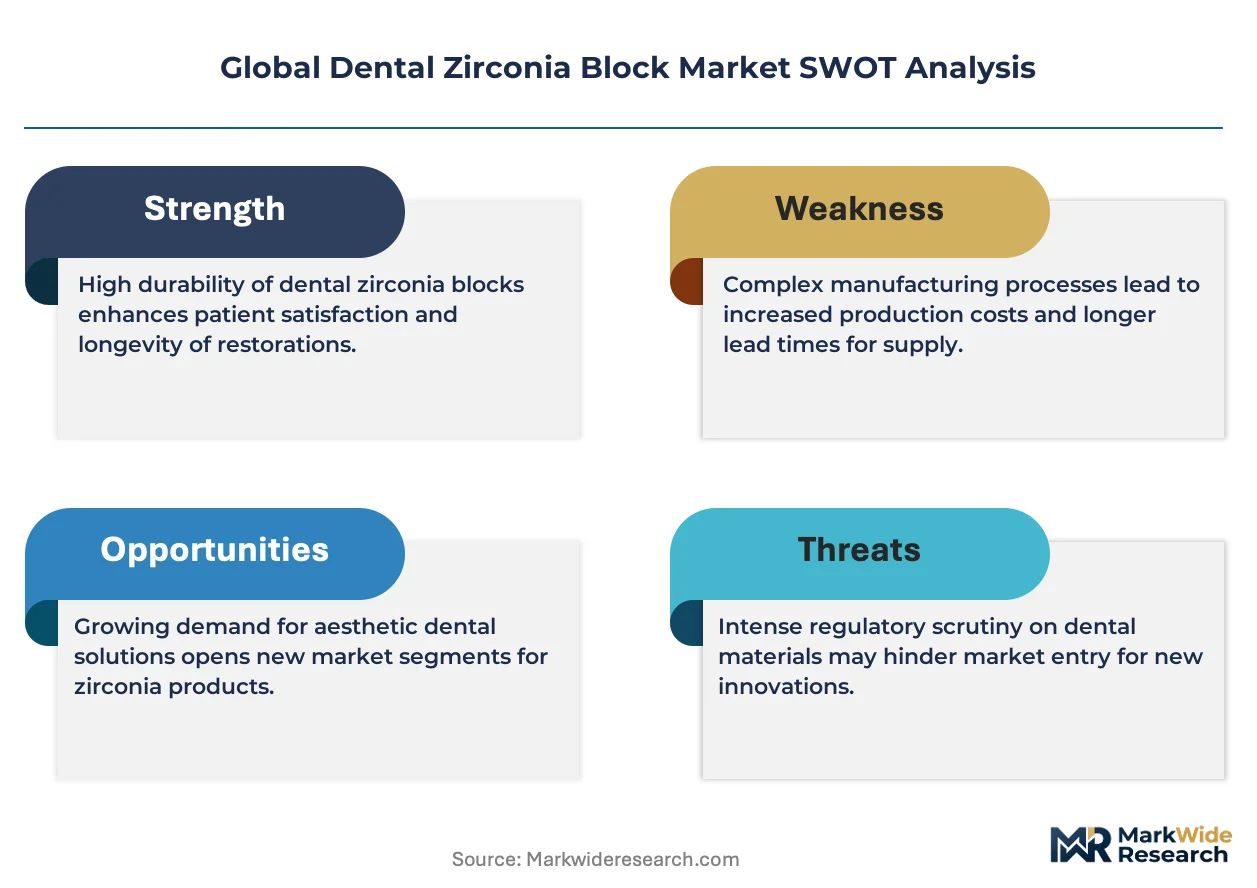
- Yttria feedstock price volatility:Rare earth processing concentration in China creates input cost instability. Block manufacturers face margin compression when yttrium oxide spot prices spike without corresponding end-product pricing power.
- Notified body capacity constraints:EU MDR implementation bottlenecks certification timelines. Smaller European laboratories delay new material adoption as supplier recertification queues extend beyond 18 months.
- Hybrid ceramic substitutes:Lithium disilicate glass-ceramics compete for anterior aesthetic cases. These materials offer superior translucency in thin sections, limiting zirconia penetration in veneer and anterior crown segments.
Strategic Opportunities
- Brazilian private dental insurance expansion:Middle-class coverage growth drives demand for premium prosthetics. Local distributors can establish direct milling center partnerships bypassing traditional import-heavy supply chains.
- 3D printing-compatible block formulations:Photopolymerizable zirconia resins enable additive fabrication of complex geometries. Convergence of stereolithography and ceramic densification opens chairside production of multi-unit bridge frameworks.
- India's PLI scheme for medical devices:Production-linked incentives attract zirconia blank manufacturing investment. Domestic production qualifies for tax benefits and preferential procurement at government dental colleges.
Industry Challenges
- CAD/CAM technician certification gaps:Laboratory workflows demand operators proficient in both design software and material science. Training programs in South Korea and Italy struggle to graduate sufficient certified technicians for expanding digital capacity.
- ISO 13356 testing backlog:Third-party validation for flexural strength and chemical purity creates pre-market delays. Manufacturers queue at accredited laboratories for certification data required by procurement departments at dental laboratory chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Zirconia Block Market |
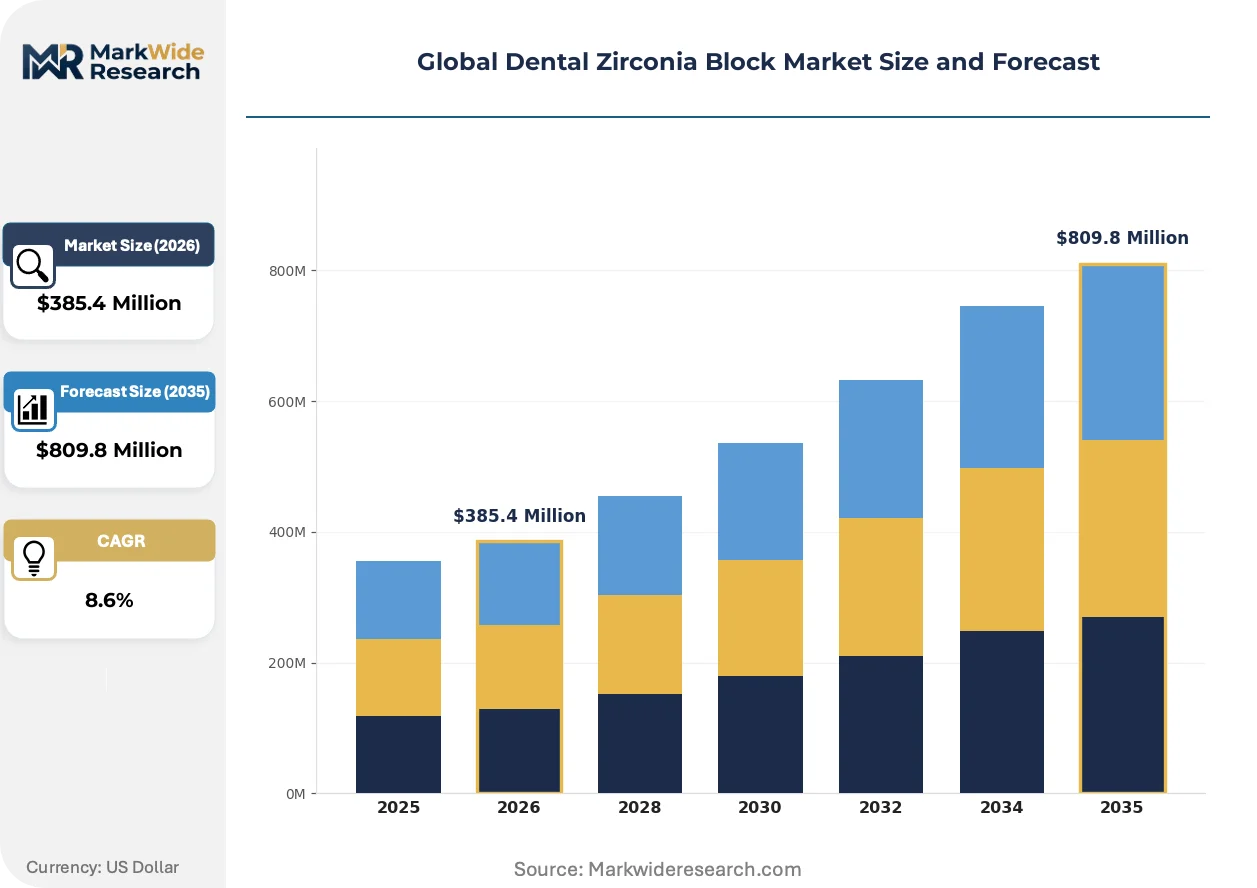
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $809.8 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic Zirconia, High Translucency Zirconia, Multi-Layer Zirconia, Pre-Shaded Zirconia Application: Dental Crowns, Dental Bridges, Implant Abutments, Orthodontic Devices, Inlays & Onlays End User: Dental Laboratories, Dental Clinics, Prosthodontists, Oral Surgeons Manufacturing Technology: CAD/CAM Milling, 3D Printing, Injection Molding, Sintering, Laser Processing |
| Companies Covered | 3M ESPE, Ivoclar Vivadent, Dentsply Sirona, VITA Zahnfabrik, GC Corporation, Kuraray Noritake Dental, Zirkonzahn, Yucera, Argen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Zirconia Block Market Shifts & Advancements
Multi-layer gradient technology is redefining aesthetic performance benchmarks while regulatory digitization and procurement centralization compress traditional supply relationships. These forces collectively shift value capture toward integrated solution providers.
Multi-layer zirconia blocks with gradient translucency from cervical to incisal zones are virtualizing the need for hand-layered veneering ceramics. Dental laboratories in Switzerland and the United States adopt these pre-shaded blanks to eliminate labor-intensive staining and glazing steps. The technology compresses fabrication time by 40% while reducing technician skill requirements for aesthetic matching.
EU MDR Article 10 clinical evidence requirements are tightening post-market surveillance obligations for zirconia block manufacturers. Notified bodies now demand systematic literature reviews and PMCF study protocols as conditions of CE marking renewal. High-translucency product lines face disproportionate scrutiny due to their newer market entry and limited long-term clinical track records.
Consolidated procurement at German and Japanese dental laboratory chains is displacing fragmented supplier relationships. Group purchasing organizations negotiate multi-year frame contracts with tiered performance specifications. Smaller regional distributors lose shelf access as central warehouses mandate direct manufacturer relationships and volume-based rebate structures.
Global Dental Zirconia Block Market Segmentation
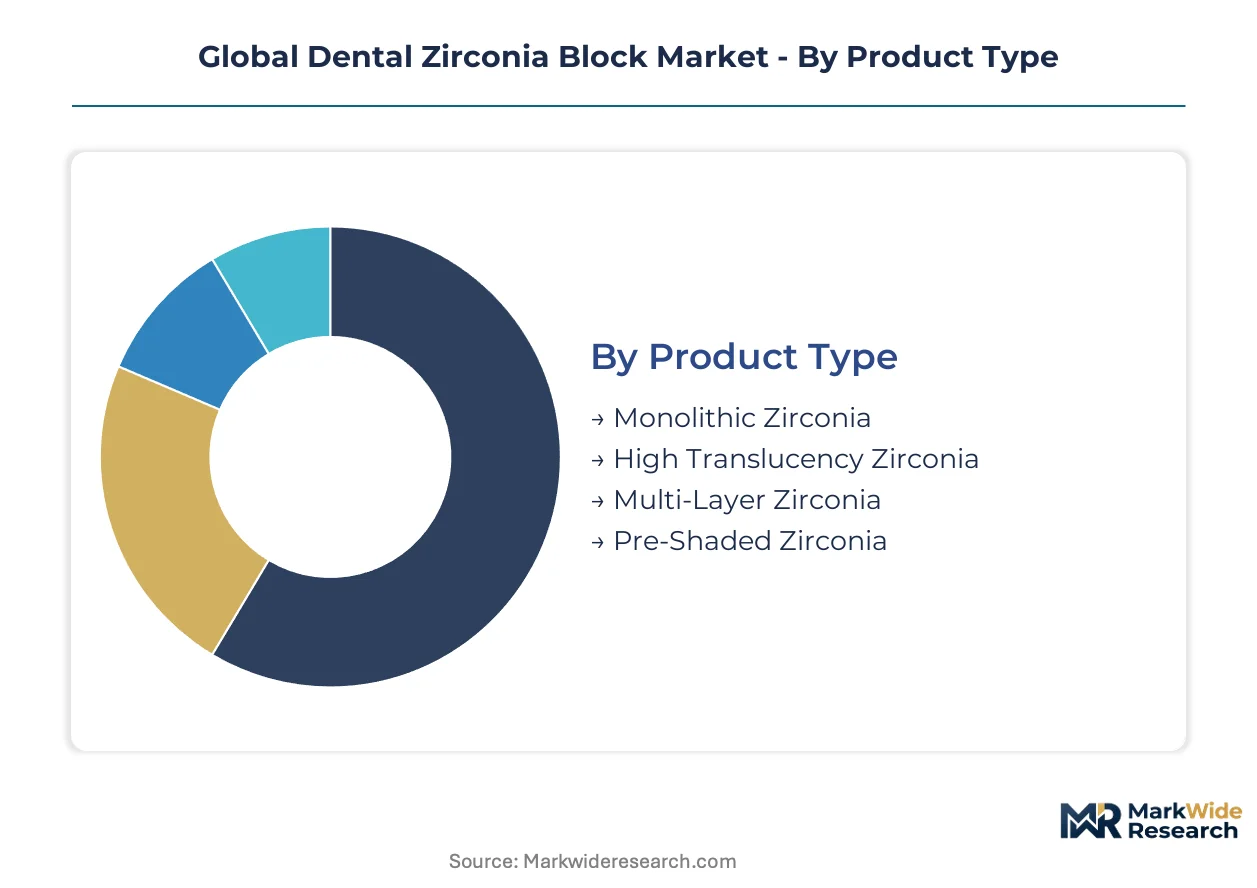
Dental zirconia block segmentation reveals how fabrication economics and aesthetic demands split procurement patterns across laboratory tiers. Product formulation and manufacturing method together determine which suppliers capture margin in chairside versus centralized production environments.
Product Type:
Mature monolithic formulations dominate posterior load-bearing applications, while gradient technologies redefine anterior aesthetic workflows.
- Monolithic Zirconia:Single-shade Y-TZP blanks deliver flexural strengths exceeding 900 MPa for posterior crowns. German dental laboratories specify these for molar replacements where occlusal forces peak, prioritizing mechanical reliability over translucency matching.
- Multi-Layer Zirconia:Gradient shading transitions from opaque cervical zones to translucent incisal edges, eliminating hand-layered veneering. Swiss laboratories adopt these blanks to compress crown fabrication time by 40 percent while reducing technician skill requirements for natural aesthetic outcomes.
- High Translucency Zirconia:Yttria-enriched formulations sacrifice some strength for dentin-like light transmission. Demand concentrates in Japanese cosmetic clinics performing anterior restorations where optical properties outweigh mechanical specifications.
- Pre-Shaded Zirconia:Chromatic presets reduce post-milling staining steps for high-volume laboratories. Chinese milling centers favor these blocks to accelerate throughput for domestic dental chains.
Monolithic zirconia retains volume leadership; multi-layer zirconia holds the steepest expansion curve.
Application:
Restoration complexity dictates block specification, with single-unit solutions commanding fundamentally different procurement economics than multi-tooth frameworks.
- Dental Crowns:Single-unit restorations anchor absolute demand volume across all manufacturing tiers. Brazilian private insurance expansion drives premium crown adoption as middle-class coverage broadens access to CAD/CAM-fabricated prosthetics.
- Dental Bridges:Multi-span frameworks demand higher fracture toughness and connector dimension precision. Italian laboratories specify high-strength zirconia for three-unit posterior bridges where flexural load concentrates at pontic connectors.
- Implant Abutments:Custom-milled interface components require biocompatibility certification under FDA 510(k) and EU MDR pathways. South Korean implant manufacturers source specialized blanks with pre-machined connection geometries.
- Orthodontic Devices:Clear aligner buttons and temporary anchorage devices utilize lower-cost zirconia grades. Indian orthodontic chains drive volume through price-sensitive procurement of non-aesthetic block formulations.
- Inlays & Onlays:Conservative restorations compete with direct composite resins for small cavity coverage. French dental clinics specify these for patients rejecting amalgam but seeking minimally invasive alternatives to full crowns.
Dental crowns capture the widest procurement base; implant abutments are climbing fastest as osseointegration rates improve.
End User:
Customer type stratifies by technical capability, with chairside operators demanding pre-sintered convenience while centralized laboratories optimize for material yield.
- Dental Laboratories:Centralized fabrication hubs in Germany and China manage multi-clinic contracts requiring ISO 13356-certified traceability. These operators negotiate volume rebates with direct manufacturer relationships, displacing regional distributors.
- Dental Clinics:Chairside milling installations in Japan and the United States compress patient visits by eliminating external outsourcing. Compact CAD/CAM units demand pre-sintered blocks compatible with rapid in-office sintering cycles.
- Prosthodontists:Hospital-based specialists in EU member states face heightened MDR documentation requirements for biocompatibility evidence. These practitioners specify suppliers with pre-emptive clinical data packages to accelerate procurement approval.
- Oral Surgeons:Implant-focused practices require immediate-load provisional restorations. Australian surgical centers source high-strength blanks compatible with same-day implant placement protocols.
Dental laboratories retain procurement volume leadership; dental clinics are expanding fastest as chairside system costs decline.
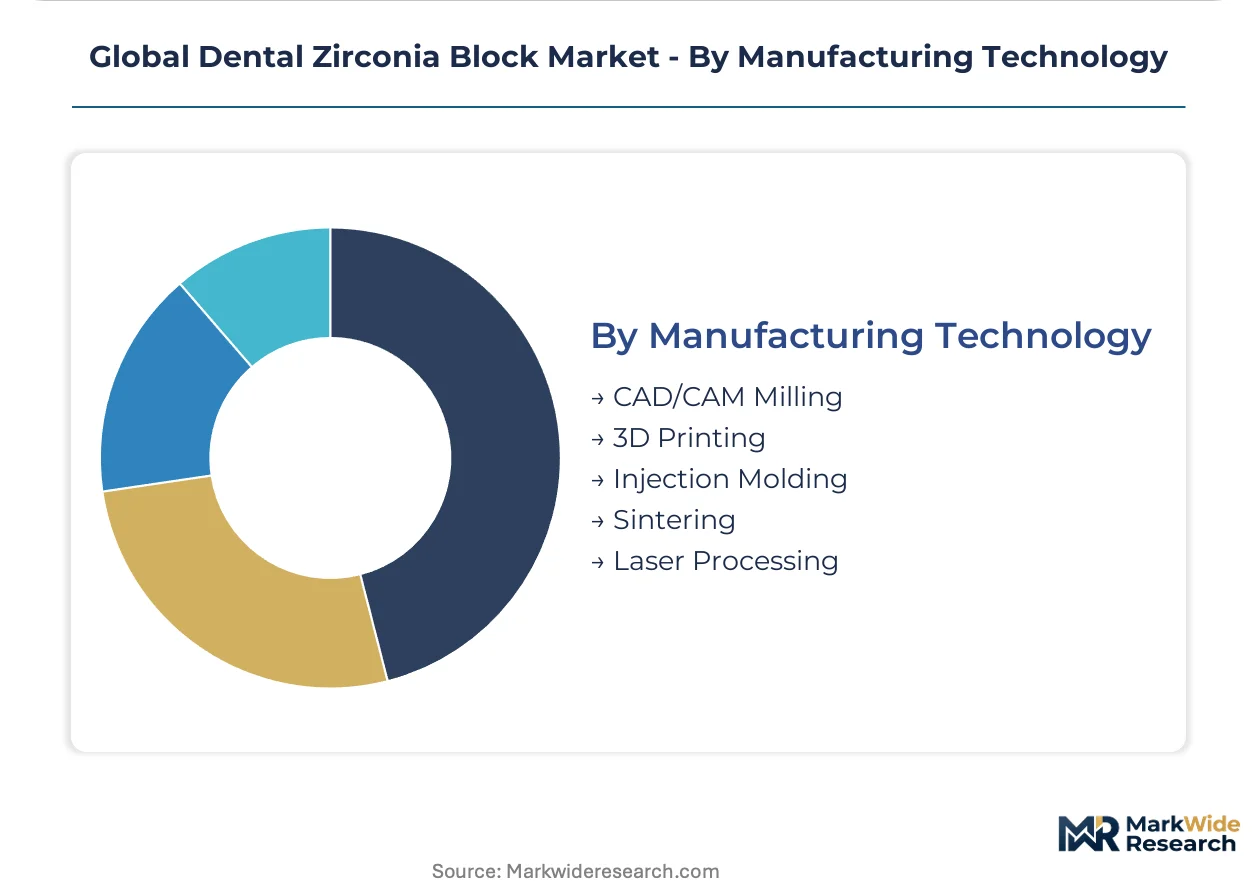
Manufacturing Technology:
Production method determines geometric precision, material density, and economic scalability for different restoration categories.
- CAD/CAM Milling:Subtractive machining from pre-sintered or fully sintered blanks dominates current production. German equipment manufacturers anchor North American and European distribution through integrated system-and-material sales.
- 3D Printing:Photopolymerizable zirconia resins enable additive fabrication of complex bridge frameworks. Japanese research institutions pioneer stereolithography-ceramic densification convergence for chairside multi-unit production.
- Injection Molding:Pressure-forming of zirconia powders suits high-volume standard geometries. Chinese manufacturers utilize this method for economy-grade blocks serving domestic price-sensitive segments.
- Sintering:Thermal densification after green-state shaping determines final mechanical properties. Zhejiang and Guangdong provinces scale captive sintering capacity to reduce import dependency for domestic milling networks.
- Laser Processing:Selective laser sintering and laser-assisted machining enable micro-feature precision. Italian specialty laboratories employ these methods for implant abutment customization requiring sub-50-micron tolerances.
CAD/CAM milling retains production dominance; 3D printing is expanding most quickly as resin formulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China consume dental zirconia blocks through fundamentally different workflows. German laboratories prioritize multi-layer gradient technology for aesthetic crown fabrication, while Chinese milling centers optimize for high-throughput monolithic production serving domestic dental chains.
United States
FDA 510(k) clearance pathways govern zirconia block commercialization, with chairside CAD/CAM adoption accelerating in California and Texas dental clinics. The FDA issues periodic digital dentistry guidance updates that reshape supplier qualification timelines. Compact milling unit installations in the Pacific Northwest compress patient visits from weeks to same-day service.
Germany
Dental laboratories in Bavaria and North Rhine-Westphalia expand digital workflows for crown fabrication, driving premium multi-layer zirconia procurement. The EU Medical Device Regulation tightens material biocompatibility documentation requirements for CE marking renewal. Stuttgart-based equipment manufacturers anchor integrated system-and-material distribution across European markets.
China
Domestic milling center networks proliferate across Zhejiang and Guangdong provinces, narrowing reliance on imported zirconia blanks. The National Medical Products Administration oversees surgical-grade ceramic standards under GB specifications. Captive sintering capacity in the Pearl River Delta reduces logistics lead times for domestic dental chains.
Japan
Cosmetic clinics in Tokyo and Osaka deploy compact chairside milling units for single-unit restorations, favoring high-translucency formulations. The Ministry of Health, Labour and Welfare enforces biocompatibility standards through PMDA oversight. Japanese research institutions pioneer stereolithography-ceramic densification convergence for additive fabrication.
Brazil
Private dental insurance expansion drives demand for premium prosthetics among São Paulo and Rio de Janeiro middle-class patients. ANVISA regulates medical device commercialization with post-market surveillance requirements. Local distributors establish direct milling center partnerships, bypassing traditional import-heavy supply chains.
Global Dental Zirconia Block Market Competitive Landscape
Capability concentration sits with integrated solution providers; scale advantage sits with regional fabrication specialists. The vendor base stratifies across three tiers: multinational dental conglomerates with proprietary shading technology, mid-cap regional manufacturers with captive sintering networks, and emerging Asian suppliers competing on standard block economics. Dominant competitive moves include backward integration into yttria feedstock sourcing and strategic partnerships with CAD/CAM equipment manufacturers to lock in system-and-material bundles.
Among European-based fabricators, Ivoclar Vivadent and VITA Zahnfabrik exemplify the premium-tier archetype through proprietary multi-layer technology. Dentsply Sirona anchors North American distribution positioning. Yucera represents the scale-driven Asian specialist competing aggressively on cost for standard monolithic blocks.
| Leading Market Players |
|---|
| 3M ESPE |
| Ivoclar Vivadent |
| Dentsply Sirona |
| VITA Zahnfabrik |
| GC Corporation |
| Kuraray Noritake Dental |
| Zirkonzahn |
| Yucera |
| Argen Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese sintering facilities compresses export pricing power while elevating margin pressure on European manufacturers lacking captive yttria feedstock. This utilization imbalance forces tiered supplier responses: domestic Chinese mills absorb volume through aggressive spot pricing, while German and Swiss specialists defend premium positioning via ISO 13356 certification bundling and multi-layer technology exclusivity.
Pricing Analysis
Long-term offtake contracts dominate procurement between German dental laboratory chains and premium-tier suppliers, insulating volume commitments from yttrium oxide spot volatility. Price differentiation separates CE-marked multi-layer blocks with PMCF documentation from economy monolithic grades lacking notified body surveillance. Pricing pressure stems from Brazilian and Indian distributors negotiating direct manufacturer relationships that bypass traditional import markups. Hospital-based prosthodontists in EU member states exhibit lowest price sensitivity due to reimbursement pass-through structures, while Chinese domestic dental chains drive hardest bargain through consolidated procurement at captive milling centers.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts established zirconia blank trade flows, prompting Southeast Asian transhipment strategies. Supply concentrates in China for yttria-stabilized powder processing, Germany for precision milling equipment integration, and Switzerland for gradient shading technology. Raw material dependencies include yttrium oxide from Chinese rare earth processors, zircon sand from Australian and South African mines, and photopolymerizable resin precursors from Japanese chemical specialists. Single-source vulnerability sits with yttrium oxide refining concentration in Inner Mongolia processing zones. Distribution runs through German and Japanese equipment manufacturers bundling system-and-material packages, displacing independent regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chairside CAD/CAM penetration remains below saturation across Japanese and US dental clinics, creating runway for hardware-material bundle expansion before competitive commoditization accelerates.
For Market Incumbents: Entrench premium positioning through backward integration into yttria feedstock sourcing and exclusive CAD/CAM equipment partnerships that lock out independent block suppliers. Ivoclar Vivadent and Dentsply Sirona archetypes should accelerate PMCF study investment ahead of EU MDR recertification waves to secure notified body priority queue placement. Defend against Yucera-led price erosion by embedding multi-layer shading patents into equipment firmware, rendering competitor blocks technically incompatible. For New Entrants and Emerging Players: Establish a beachhead in India's government dental college procurement channel, where PLI scheme tax benefits offset incumbent scale advantages. Target Brazilian private insurance reimbursement networks with pre-shaded monolithic blocks priced below Ivoclar Vivadent premium tiers. White-space exists in 3D printing-compatible resin formulations for chairside bridge fabrication, where Japanese research institutions hold early technical leads but lack commercial scale. Go-to-market through direct milling center partnerships bypasses distributor margin stacking. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among German and Japanese dental laboratory chains with multi-year frame contracts and volume-based rebate structures. Long-term viability favors mid-cap specialists with captive sintering in Zhejiang or Guangdong provinces, positioned for domestic Chinese demand expansion and potential Southeast Asian export pivot. Acquisition target archetype: regional manufacturers with ISO 13356 certification backlog clearance and underutilized sintering capacity. Signal to watch is FDA digital dentistry guidance expansion into AI-assisted crown design, which would reshape software-hardware-material bundle economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttria Feedstock | Secures input cost stability against Chinese rare earth processing concentration volatility. |
| PMCF Study Investment for EU MDR | Accelerates notified body approval timelines and secures hospital procurement preference. |
| CAD/CAM Equipment Partnership Lock-in | Creates technical incompatibility barriers against low-cost block competitors. |
| 3D Printing Resin Formulation Development | Captures additive fabrication shift for complex bridge geometries in Japanese clinics. |
| Direct Milling Center Distribution | Eliminates distributor margin stacking in Brazilian and Indian price-sensitive segments. |
Research Methodology
Initial hypotheses were tested against primary input from dental laboratory operations managers, CAD/CAM equipment sales directors, notified body certification auditors, and hospital prosthodontic department heads, then refined through secondary validation. Primary fieldwork combined structured interviews with German and Chinese milling center operators and Japanese cosmetic clinic technicians. Secondary sources included FDA 510(k) clearance databases, EU MDR notified body certification registries, ISO 13356 testing laboratory accreditation records, and customs trade data for yttrium oxide and zirconia block shipments. Bottom-up demand modeling from restoration procedure volumes was triangulated against top-down manufacturer capacity disclosures.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by product formulation tier, application complexity, end-user technical capability, and manufacturing technology maturity. CAGRs were derived from procedure volume elasticity to CAD/CAM adoption curves and material substitution thresholds. Industry-specific forecast inputs included EU MDR recertification queue projections and Chinese domestic sintering capacity utilization surveys.
Stress conditions across yttrium oxide price spikes, notified body capacity constraints, and hybrid ceramic substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on digital workflow adoption velocity and regulatory enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Toothpaste Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Global Dental Cements Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Dental Resins Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Composites Market
Dental Materials
Dental Impression Material Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Dental Alginate Market