
 North America Ceramic Coatings Market | 2026-2036
North America Ceramic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceramic Coatings Market Analytics
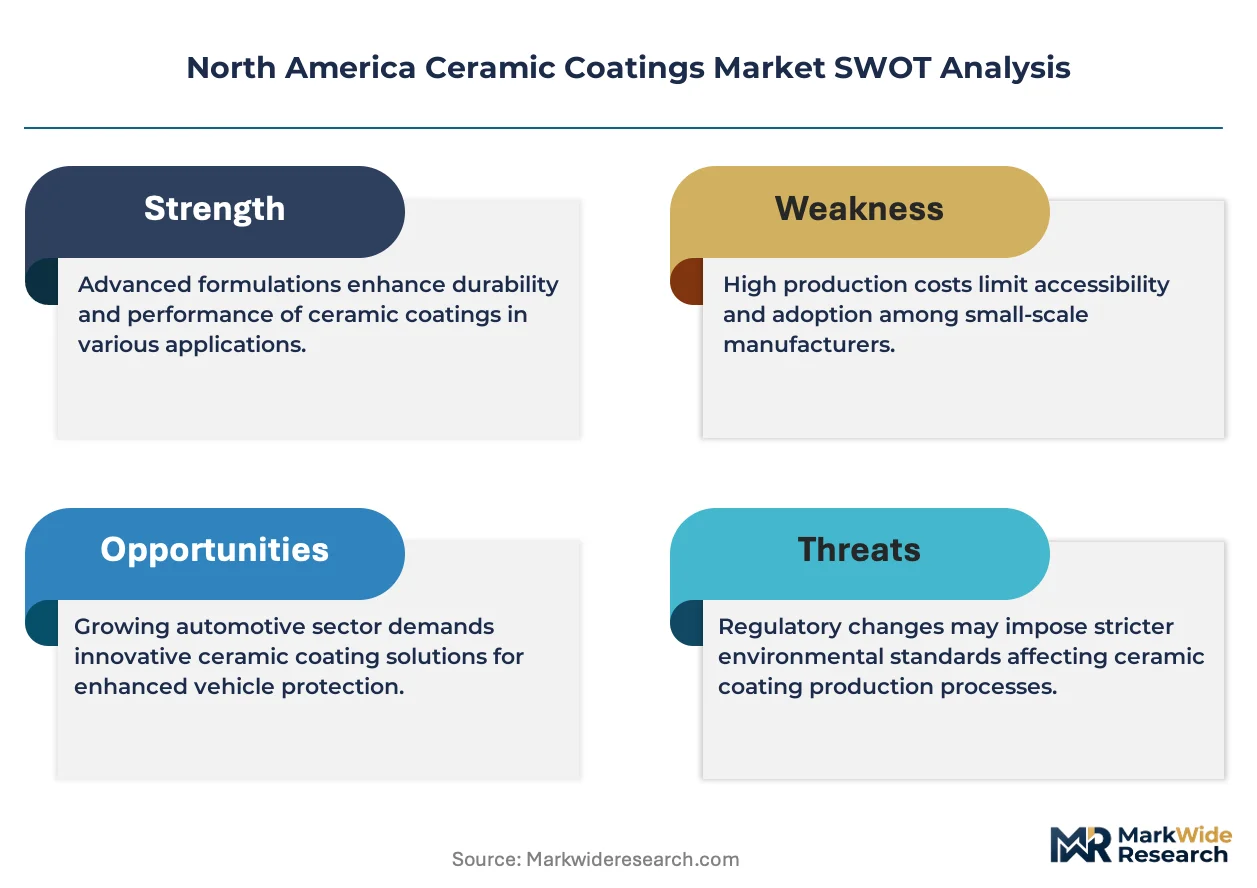
A capital-intensity divergence between plasma-spray infrastructure owners and liquid-applicator specialists is bifurcating competitive returns across the North America Ceramic Coatings Market. Praxair Surface Technologies leverages its captive gas supply chain and thermal spray installation base to dominate aerospace blade coating contracts. Saint-Gobain anchors its position through fused ceramic grain verticality and long-term supply agreements with US power generation operators. Bodycote competes via its distributed service center network, offering quick-turn thermal barrier restoration without OEM part replacement.
North America ceramic coatings comprise inorganic, non-metallic layers deposited through thermal spray, sol-gel, or liquid ceramic processes, typically formulated from alumina, zirconia, or silicon carbide to achieve hardness exceeding 9 Mohs and operating temperatures above 1,200°C for oxidation and wear protection. Thermal spray coatings occupy the largest value share due to entrenched use in aviation turbine maintenance, though nano coatings represent the fastest-expanding margin pool as semiconductor fabricators adopt atomic-layer precision for wafer processing equipment. Liquid coatings sustain stable demand from automotive OEMs seeking cost-effective exhaust manifold protection, while sol-gel formulations penetrate medical device manufacturers requiring biocompatible implant surfaces.
The EPA enforces NESHAP standards that mandate reduced hexavalent chromium in aerospace finishing, directly elevating demand for chrome-free ceramic alternatives, while the FAA's airworthiness directives on engine hot-section durability tighten coating thickness and adhesion testing protocols for commercial aviation suppliers. OSHA permissible exposure limits for refractory ceramic fibers further shape workplace handling requirements and protective equipment specifications across US manufacturing facilities. Stakeholders must monitor how Mexico's SEMARNAT environmental enforcement evolution and Canada's proposed Clean Fuel Regulations will alter cross-border coating chemistry approvals and production location decisions.
Market Dynamics
Plasma-spray equipment ownership concentrates among a handful of thermal spray specialists across the US Great Lakes corridor, creating a two-tier competitive structure where capital-heavy incumbents capture aerospace blade contracts while liquid-applicator specialists serve cost-sensitive automotive exhaust programs.
Growth Catalysts
- EPA NESHAP hexavalent chromium restrictions:Aerospace finishing operations in Michigan and California face mandated phase-outs of chrome plating, redirecting specification engineers toward alumina-zirconia thermal barrier formulations for turbine hot-section components.
- Semiconductor capital equipment refresh cycles:Atomic-layer deposition chambers in Arizona and Oregon fabrication facilities require nano-precision ceramic coatings on wafer handling robotics, pulling specialty sol-gel formulations into front-end process equipment supply chains.
- Querétaro aerospace cluster expansion:Mexican MRO facilities serving Gulf Coast and Latin American airline fleets are certifying local thermal spray capacity, reducing turnaround times for engine blade restoration without cross-border part shipment.
Market Restraints
- Refractory ceramic fiber input volatility:OSHA permissible exposure limits on airborne ceramic fibers have compressed domestic manufacturing of alumina-silicate feedstock, forcing coating applicators toward pricier synthetic mullite substitutes.
- Plasma-spray equipment oligopoly:Thermal spray system production concentrates among three specialized OEMs in Ohio and Connecticut, extending delivery lead times for new coating capacity installations beyond eighteen months.
- Thin-film PVD substitution in medical devices:Orthopedic implant manufacturers in Indiana and Massachusetts are pivoting toward physical vapor deposition titanium nitride for articulating surfaces, displacing biocompatible hydroxyapatite ceramic coatings in hip and knee applications.
Strategic Opportunities
- Baja California medical device manufacturing:Tijuana and Mexicali contract manufacturers serving California-based OEMs lack local ceramic coating capacity for surgical instrument sterilization trays, creating white space for sol-gel service center investment.
- FAA airworthiness directive compliance services:Independent testing laboratories in Texas and Florida can capture recurring revenue streams by offering coating thickness verification and adhesion testing for regional airline MRO providers.
- Canada Clean Fuel Regulations:Proposed carbon intensity standards for transportation fuels will tighten exhaust system thermal efficiency requirements, elevating ceramic coating specifications for Ontario-based automotive Tier-1 suppliers.
Industry Challenges
- Thermal spray technician certification gaps:AWS C2.23 certification programs for plasma-arc operators operate at insufficient throughput across US community colleges, constraining workforce expansion for aerospace coating contractors.
- Multi-layer coating system integration:Engine OEMs in Detroit require seamless bonding between metallic bond coats and ceramic topcoats, demanding process control expertise that smaller applicators struggle to replicate.
- SEMARNAT chemical approval timelines:Mexican environmental regulators average fourteen months for new coating chemistry registration, delaying product launches for US formulations seeking Querétaro aerospace qualification.
Report Scope
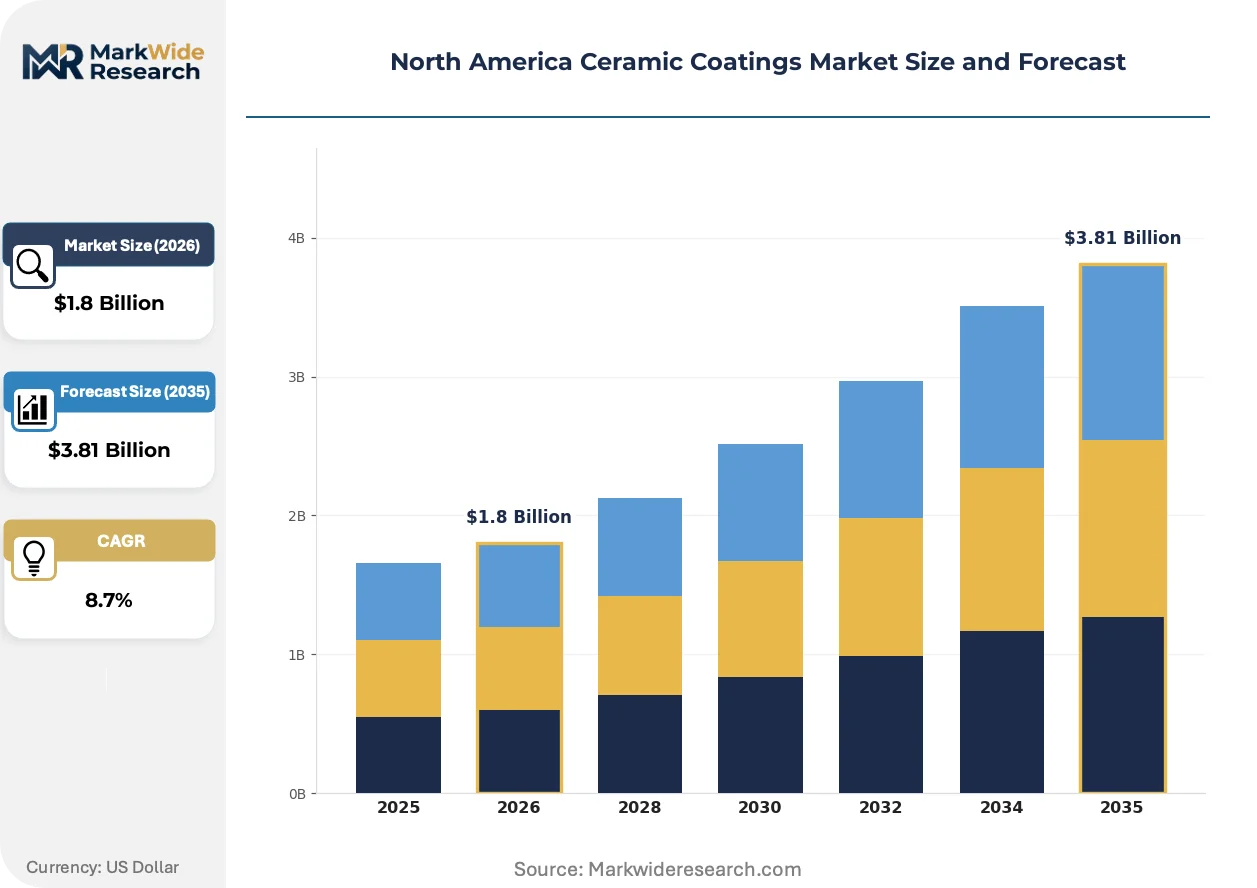
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceramic Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Spray Coatings, Liquid Coatings, Sol-Gel Coatings, Nano Coatings Application: Aerospace, Automotive OEMs, Medical Devices, Electronics Material: Zirconia, Alumina, Silicon Carbide, Others Customer Type: Manufacturers, End Users, Contractors, Distributors |
| Companies Covered | A&A Thermal Spray Coatings, APS Materials, Inc., Praxair Surface Technologies, Saint-Gobain, Bodycote, Aremco Products, Inc., PPG Industries, Inc., OC Oerlikon Management AG, Fosbel Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceramic Coatings Market Evolving Landscape
Nano-structured coating deposition methods are compressing thickness tolerances while expanding addressable applications beyond traditional thermal barrier protection. Three interconnected developments are redirecting competitive investment priorities.
Atomic layer deposition is miniaturizing ceramic film control to sub-nanometer precision, enabling conformal coating of semiconductor wafer processing chambers with alumina and yttria formulations. Arizona fabrication facilities have adopted this technology for plasma etch equipment, reducing particle contamination incidents. Equipment suppliers are now scaling deposition systems from R&D benchtop units to production-scale batch processing, compressing cost per wafer pass to parity with sputtered alternatives.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is eliminating hexavalent chromium conversion coatings from aerospace supply chains. California and Michigan finishing operations have accelerated qualification of trivalent chrome-free ceramic alternatives for landing gear and engine components. Coating formulators are responding with modified sol-gel pretreatments that achieve equivalent corrosion resistance without hazardous air pollutant classification.
Aftermarket service unbundling is fragmenting traditional OEM-captive coating relationships. Regional MRO providers in Texas and Florida now source independent thermal spray restoration for turbine blades rather than accepting manufacturer exchange programs. This procurement pattern shift compresses turnaround times from weeks to days while pressuring OEMs to license coating specifications or risk volume erosion in the installed base.
North America Ceramic Coatings Market Segmentation
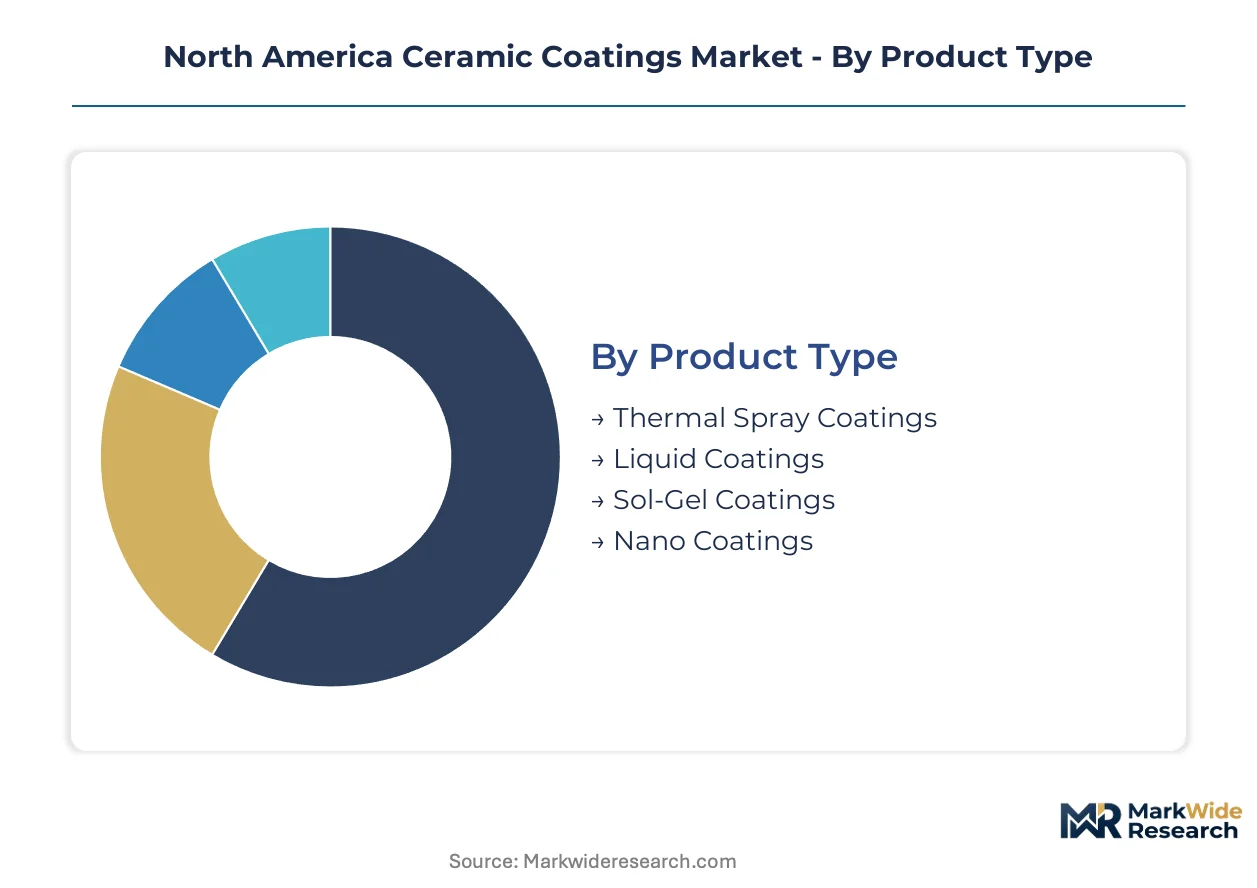
Segmentation in the North America ceramic coatings market reveals how capital intensity, regulatory pressure, and end-use specifications fragment procurement patterns across the US Great Lakes corridor, Mexican aerospace clusters, and Canadian automotive manufacturing zones.
Product Type:
Domestic consumption concentrates in thermal spray and liquid formulations, while nano coatings serve export-oriented semiconductor equipment manufacturers in Arizona and Oregon.
- Thermal Spray Coatings:Alumina-zirconia composites deposited via plasma-arc or HVOF processes achieve 1,200°C+ operating temperatures and 9+ Mohs hardness. Michigan and Ohio aerospace contractors dominate demand for turbine blade restoration, driven by FAA airworthiness directive compliance requirements and EPA NESHAP hexavalent chromium restrictions.
- Liquid Coatings:Solvent-borne or water-based ceramic suspensions cure at lower temperatures, enabling field application without specialized equipment. Detroit automotive OEMs specify these for exhaust manifold thermal barriers, balancing performance against line-speed integration constraints and tier-1 supplier cost targets.
- Sol-Gel Coatings:Colloidal silica or alumina precursors form thin, conformal films through dip or spin coating.
- Nano Coatings:Atomic-layer deposition achieves sub-nanometer thickness control for semiconductor wafer processing chambers.
Thermal spray coatings hold the largest share; momentum sits with nano coatings.
Application:
Aerospace and automotive OEMs drive volume, while medical devices and electronics represent margin-accretive niches with specialized certification requirements.
- Aerospace:Turbine hot-section components require thermal barrier coatings with engineered porosity for strain tolerance. Praxair Surface Technologies and Bodycote service centers across Texas and Florida capture MRO demand from regional airlines seeking faster turnaround than OEM exchange programs permit.
- Automotive OEMs:Exhaust valves, manifolds, and turbocharger housings specify ceramic coatings to meet EPA emission standards and thermal efficiency targets. Ontario-based tier-1 suppliers face additional pressure from Canada's proposed Clean Fuel Regulations.
- Medical Devices:Orthopedic implants and surgical instruments utilize hydroxyapatite or biocompatible oxide coatings.
- Electronics:Semiconductor fabrication equipment and printed circuit board substrates require dielectric or wear-resistant ceramic films.
Aerospace commands premium pricing; electronics shows steepest expansion trajectory.
Material:
Zirconia and alumina formulations anchor Great Lakes manufacturing, while silicon carbide penetrates specialized electronics and defense applications.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal (Y-TZP) delivers thermal shock resistance critical for aviation turbine blades. Saint-Gobain's fused ceramic grain verticality secures supply chain position for US power generation and aerospace contractors.
- Alumina:Alpha-alumina coatings provide cost-effective wear and corrosion protection across automotive and industrial applications. OSHA permissible exposure limits on refractory ceramic fibers have compressed domestic feedstock availability, elevating synthetic mullite substitute pricing.
- Silicon Carbide:CVD or reaction-bonded SiC coatings achieve extreme hardness for semiconductor etch chambers and armor applications.
- Others:Chromia, titania, and rare-earth oxide formulations serve niche thermal barrier and environmental barrier coating functions.
Alumina maintains volume leadership; silicon carbide is climbing the fastest.
Customer Type:
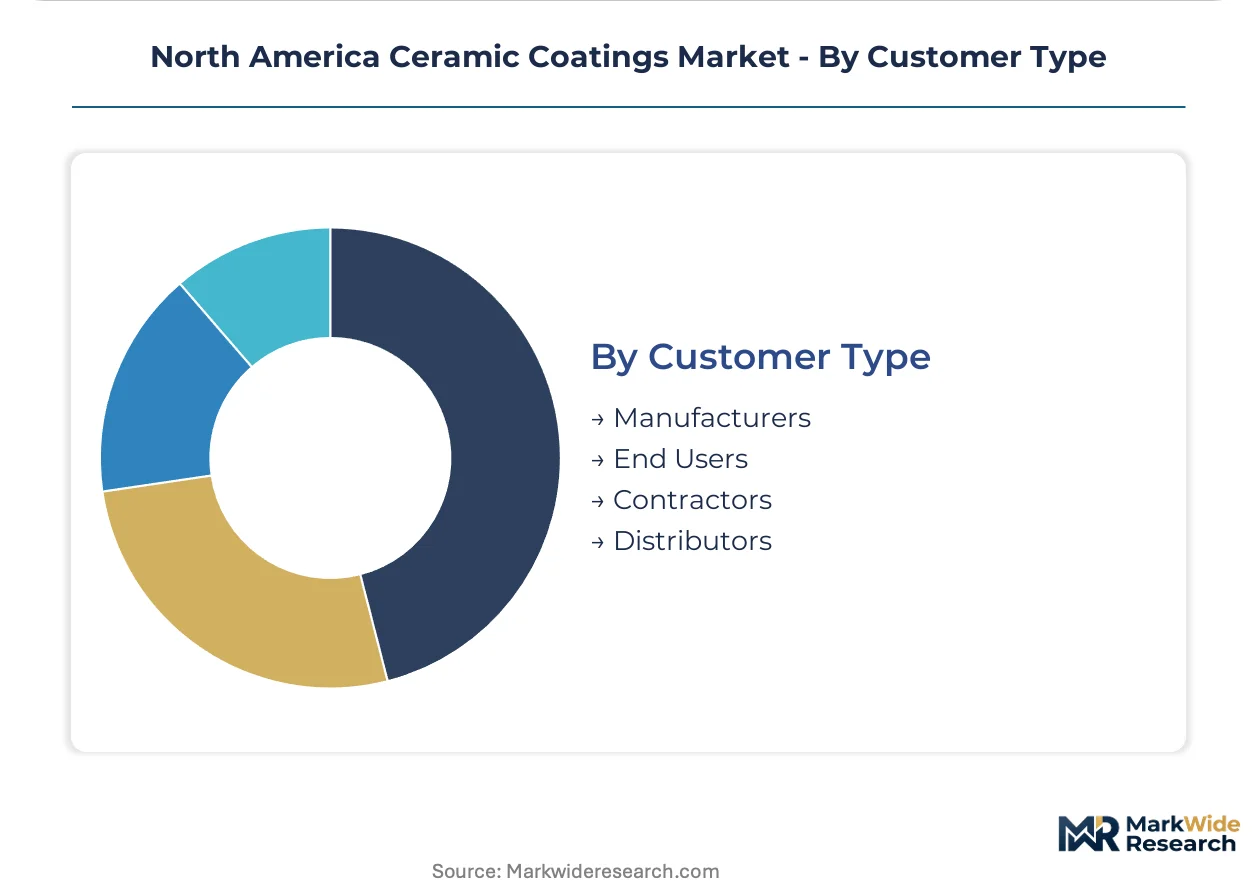
Manufacturers and contractors concentrate procurement in the US and Mexico, while distributors bridge fragmented end-user demand across smaller fabrication shops.
- Manufacturers:OEM captive coating operations in Detroit and Querétaro maintain in-house thermal spray capacity for production-line integration and quality control. These facilities prioritize process consistency over per-unit cost minimization.
- Contractors:Independent service providers like Bodycote offer quick-turn restoration without part replacement, capturing aftermarket volume from regional airlines and power plant operators.
- End Users:Maintenance departments at industrial facilities and smaller MRO shops purchase coatings for in-house application or spot repair.
- Distributors:Chemical and industrial supply houses stock liquid ceramic formulations for automotive aftermarket and general industrial maintenance.
Manufacturers represent the largest procurement volume; contractors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mexican aerospace clusters exhibit the highest price elasticity, sourcing quick-turn restoration to avoid OEM exchange premiums, while US semiconductor fabricators accept steep nano-coating costs to minimize wafer contamination downtime.
United States
EPA NESHAP enforcement and FAA airworthiness directives drive specification shifts toward chrome-free ceramic alternatives in Michigan and California finishing operations. OSHA permissible exposure limits on refractory ceramic fibers compress domestic alumina-silicate feedstock availability. Texas and Florida service centers capture regional airline MRO demand through independent thermal spray restoration.
Canada
Proposed Clean Fuel Regulations tighten exhaust system thermal efficiency requirements for Ontario automotive Tier-1 suppliers. Health Canada and PMRA oversight shapes biocompatible coating approvals for orthopedic implant manufacturers. Quebec power generation operators maintain long-term supply agreements for fused ceramic grain thermal barriers.
Mexico
SEMARNAT chemical approval timelines averaging fourteen months delay US formulation launches for Querétaro aerospace qualification. Mexican MRO facilities serving Gulf Coast and Latin American fleets certify local thermal spray capacity to reduce cross-border part shipment delays. Baja California medical device contract manufacturers lack local ceramic coating capacity for surgical instrument sterilization trays.
North America Ceramic Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-heavy plasma-spray infrastructure owners capturing aerospace blade contracts while liquid-applicator specialists serve cost-sensitive automotive exhaust programs. The competitive terrain splits between captive gas supply chain operators, fused ceramic grain verticalists, and distributed service center networks. Two dominant competitive moves are reshaping positioning: strategic partnerships between coating formulators and semiconductor equipment OEMs, and geographic expansion of thermal spray capacity into Mexican aerospace clusters.
Within the integrated industrial tier, Praxair Surface Technologies and Saint-Gobain exemplify divergent vertical integration strategies, while Bodycote occupies a position as the distributed service archetype. Aremco Products, Inc. and APS Materials, Inc. represent specialist formulators targeting niche thermal barrier applications. These five entities collectively illustrate how competitive returns bifurcate between capital-intensive infrastructure owners and agile application specialists across the North American landscape.
| Leading Market Players |
|---|
| A&A Thermal Spray Coatings |
| APS Materials, Inc. |
| Praxair Surface Technologies |
| Saint-Gobain |
| Bodycote |
| Aremco Products, Inc. |
| PPG Industries, Inc. |
| OC Oerlikon Management AG |
| Fosbel Inc. |
| Others |
Value Network & Pricing Analysis
Long-term supply agreements between fused ceramic grain producers and US power generation operators lock in multi-year price visibility while securing feedstock access against OSHA-driven refractory ceramic fiber shortages. These contracts insulate aerospace contractors from spot market volatility in alumina-zirconia thermal spray powders while exposing automotive exhaust coating programs to more fluid liquid ceramic pricing.
Pricing Analysis
Aftermarket blade restoration services generate lifetime value multiples exceeding original equipment coating sales for thermal spray specialists. Three-tier pricing structure across FAA-certified, OEM-licensed, and independent service tiers reflects certification grade and adhesion testing protocol differentiation. Cost compression in liquid automotive exhaust coatings is intensifying because Detroit Tier-1 suppliers face line-speed integration penalties. Regional airline MRO providers in Texas and Florida exhibit highest price sensitivity, while Arizona semiconductor fabricators accept premium nano-coating costs to minimize wafer contamination downtime.
Supply Chain Analysis
Eighteen-month delivery lead times for plasma-spray equipment from Ohio and Connecticut OEMs constrain capacity expansion timelines across the Great Lakes corridor. Feedstock supply draws from US fused ceramic grain production, Canadian alumina refining, and Mexican mullite substitute manufacturing. Single-source vulnerability concentrates in thermal spray system OEMs, with no qualified second-source for aerospace blade coating certification. Distribution runs through captive OEM service networks, independent Bodycote service centers, and direct chemical supply to automotive production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward regional airline MRO providers as they consolidate procurement away from OEM exchange programs toward independent thermal spray restoration, fragmenting traditional captive coating relationships.
For Market Incumbents: Shield aerospace blade coating margins by deepening captive gas supply chain control and accelerating FAA airworthiness directive compliance certification investments. Defend against independent MRO encroachment by licensing coating specifications to regional service centers under royalty-bearing agreements rather than ceding volume entirely. For New Entrants and Emerging Players: Quick-turn sol-gel service capacity for Baja California medical device sterilization trays represents the most penetrable white space, given fourteen-month SEMARNAT approval barriers delay incumbent launches. Target Tijuana and Mexicali contract manufacturers with mobile coating units and California OEM validation partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Independent thermal spray laboratories with FAA adhesion testing accreditation offer acquisition exposure to aftermarket service unbundling trends. Long-term viability hinges on nano-coating atomic layer deposition scaling cost parity with sputtered alternatives across the semiconductor capital equipment refresh cycle. Watch Arizona fabrication facility expansion announcements as inflection indicators for specialty sol-gel formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mexican Aerospace Clusters | Querétaro MRO certification reduces cross-border engine blade shipment delays for Gulf Coast airlines. |
| Backward Integration into Fused Ceramic Grain | Saint-Gobain's captive supply secures Y-TZP thermal barrier feedstock against OSHA fiber exposure limits. |
| Chrome-Free Coating Formulation Launch | EPA NESHAP compliance elevates alumina-zirconia alternatives for Michigan landing gear finishing operations. |
| Joint Venture with Semiconductor Equipment OEMs | Atomic layer deposition chamber partnerships pull Arizona fabrication facilities toward production-scale nano coating. |
| Geographic Expansion of Service Center Networks | Bodycote's distributed model captures Texas and Florida regional airline MRO demand without OEM part replacement. |
Research Methodology
A spread of perspectives from thermal spray equipment OEMs, aerospace MRO procurement managers, automotive Tier-1 supplier engineers, and ceramic coating formulators converged on the working assumptions driving this analysis. Primary interviews with EPA compliance officers and FAA certification specialists were cross-validated against SEMARNAT regulatory filings, OSHA permissible exposure limit documentation, and Canadian Clean Fuel Regulation proposals. Bottom-up coating volume estimates from Great Lakes manufacturing facilities were triangulated with top-down aerospace and automotive production forecasts.
Segmentation dimensions modeled include coating deposition technology, end-use application, ceramic material composition, and customer procurement archetype across the projection horizon. CAGRs were derived from installed base expansion rates, capital equipment replacement cycles, and regulatory-driven material substitution elasticities. Forecast inputs incorporated semiconductor fabrication facility buildout pipelines and Mexican aerospace cluster foreign direct investment flows.
Underlying assumptions cover EPA NESHAP enforcement continuity, FAA airworthiness directive adoption timelines, and OSHA refractory ceramic fiber exposure limit stability, with deviation risk concentrated in SEMARNAT chemical approval acceleration or Canada Clean Fuel Regulation implementation delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Europe Ceramic Tiles Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Optical Ceramics Market
Ceramics
Diatomite Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Cordierite Market
Ceramics
Calcined Bauxite Market
Ceramics
Ceramic Additives Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Fire Clay Market
Ceramics
Global Ceramic Tube Market
Ceramics
Glazed Bricks Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Ceramic Solid End Mills Market