
 North America Machined Seals Market | 2026-2036
North America Machined Seals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Machined Seals Market Analytics
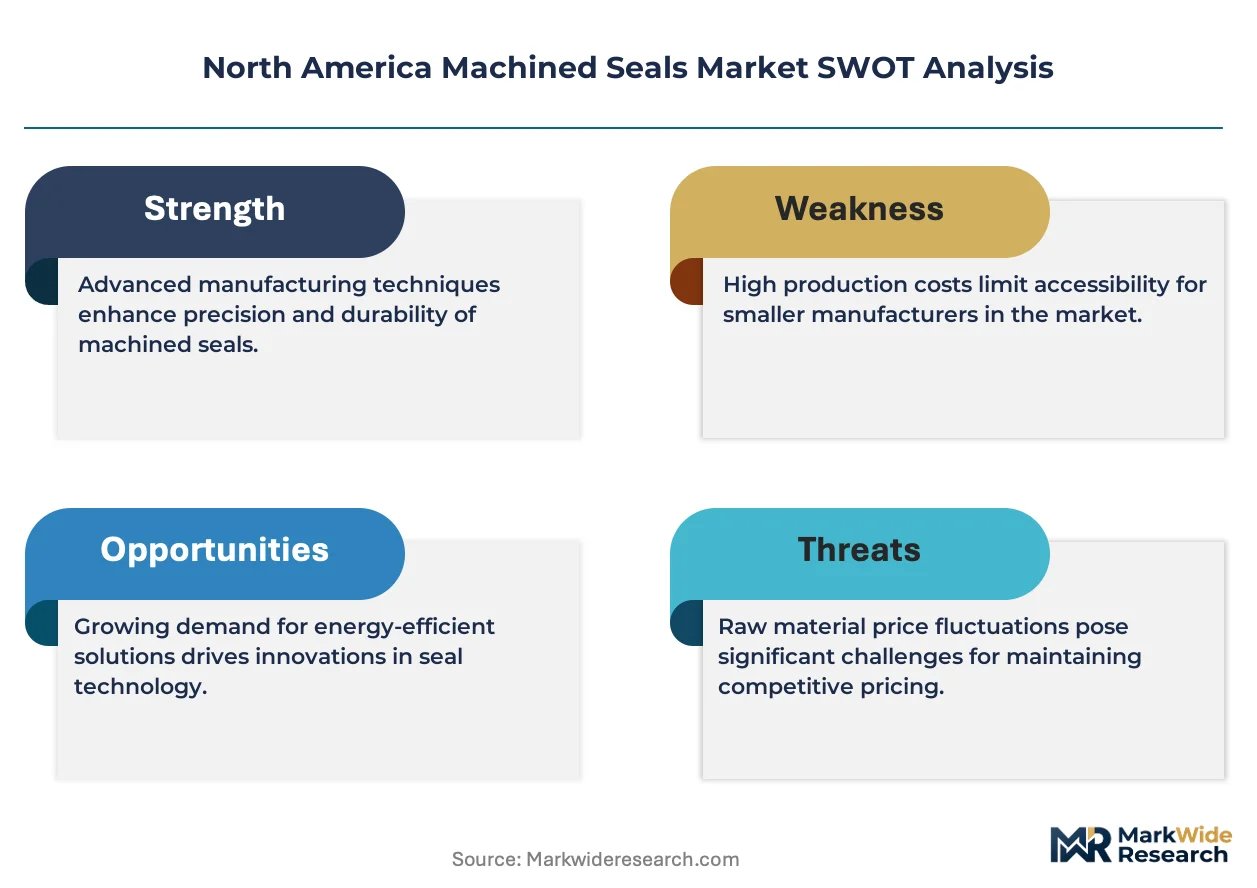
The North American machined seals landscape is decoupling along a sharp fault line between aerospace-grade fluoropolymer precision components and commodity elastomeric replacements for general industrial service. Flowserve Corporation leverages its integrated manufacturing footprint across Texas and Louisiana to dominate aftermarket supply for oil and gas infrastructure. John Crane anchors its position through deep specialization in engineered sealing systems for rotating equipment in hydrocarbon processing. SKF competes by extending its bearing-seal bundling strategy into aerospace OEM channels, where specification lock-in creates durable revenue streams.
Machined seals are precision-manufactured sealing elements produced by CNC machining, grinding, or lathing from solid polymer billets rather than molded, enabling tight dimensional tolerances and complex geometries for extreme-pressure or chemically aggressive environments. PTFE and polyurethane formulations dominate where temperature excursions exceed 200°C or where resistance to aromatic hydrocarbons is mandatory. Custom seals command the deepest margin pools due to engineering-intensive specification work and low substitution risk, while O-rings face price compression from commoditized Asian supply. Aerospace and oil and gas applications lead volume absorption, with food processing representing the fastest trajectory as FDA compliance requirements tighten on extractable and leachable profiles.
The EPA enforces leak detection and repair protocols that mandate seal performance verification in refineries and chemical plants, directly elevating replacement specifications and documentation burdens on seal suppliers. FDA 21 CFR Part 177 compliance for food-contact elastomers restricts material formulations and drives reformulation costs that favor established compounders with validated supply chains. NHTSA durability standards for automotive underhood applications extend validation timelines and raise barriers for unproven entrants. Stakeholders must monitor how the SEC's emerging climate disclosure rules reshape capital allocation toward lower-emission seal technologies in carbon-intensive end markets.
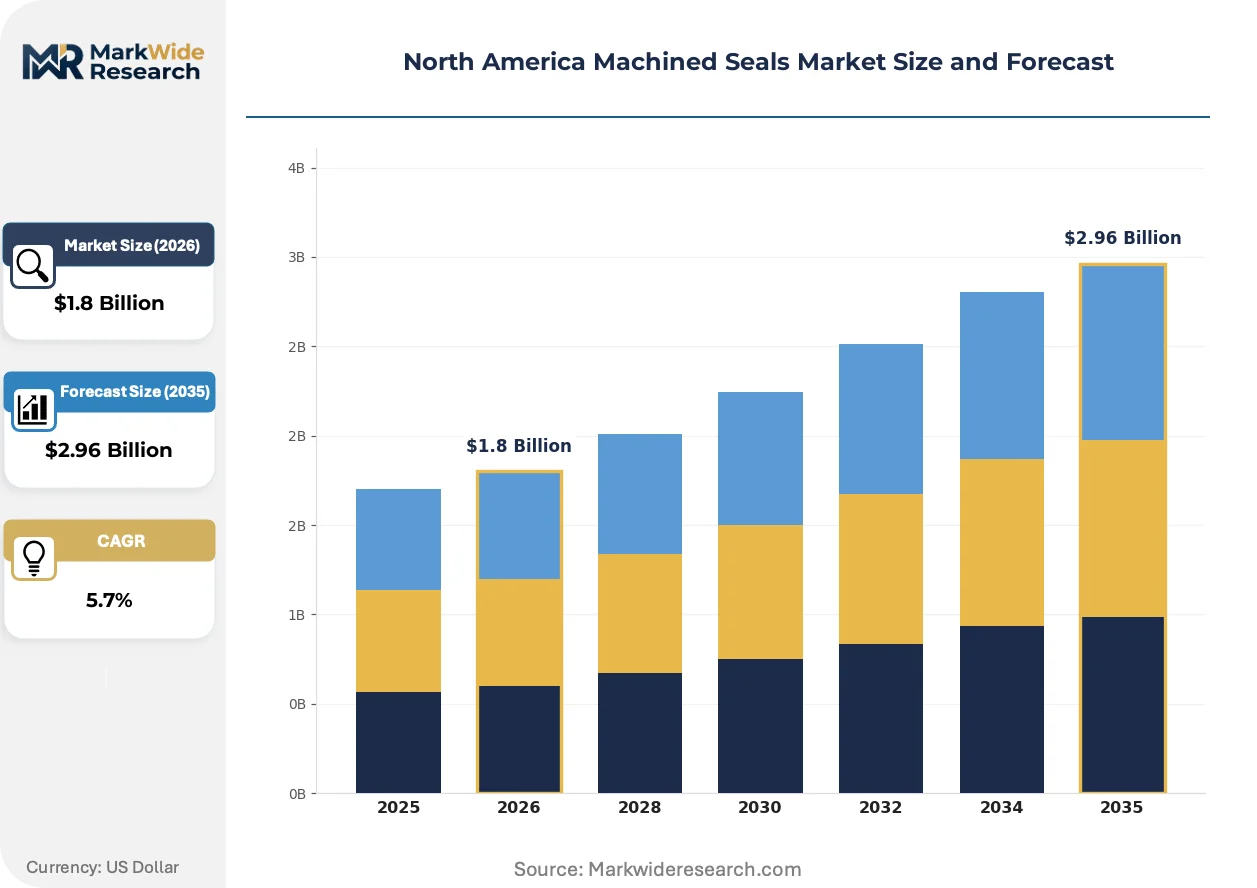
Market Dynamics
The North America machined seals market is bifurcating between aerospace-grade fluoropolymer precision and commodity elastomeric replacements, driven by EPA emissions enforcement that mandates verified seal performance documentation in refineries and chemical processing facilities.
Growth Catalysts
- EPA Clean Air Act enforcement:Oil and gas operators across Texas and Louisiana face escalating fugitive emission control mandates, forcing systematic replacement of legacy seal architectures with advanced machined alternatives that deliver verified leak-tight performance under pressure cycling.
- Aerospace OEM thermal tolerance requirements:Original equipment manufacturers specify fluoropolymer sealing systems for hydraulic assemblies operating above 200°C, creating specification-locked demand channels resistant to price-based substitution.
- Texas petrochemical cluster density:Concentrated refinery maintenance cycles along the Gulf Coast generate sustained procurement volume for custom seal fabricators serving turnaround contractors and reliability engineering teams.
Market Restraints
- Fluoropolymer raw material concentration:PTFE resin supply concentrates among a limited cohort of chemical compounders, exposing fabricators to feedstock allocation risk and extended lead times during capacity constraints.
- Commodity O-ring import pressure:Molded elastomeric seals from Asian manufacturers compress pricing power in general industrial applications, eroding margin pools for domestic producers lacking aerospace or oil and gas certification.
- FDA 21 CFR Part 177 compliance burden:Food-contact seal validation requires extensive extractable and leachable testing, extending commercialization timelines and favoring established compounders with validated supply chains over new entrants.
Strategic Opportunities
- Canadian oil sands extraction expansion:Bitumen processing facilities in Alberta require high-tolerance seals for steam-assisted gravity drainage systems, creating demand for PTFE-based architectures resistant to thermal cycling and abrasive particulate loading.
- SEC climate disclosure rules:Emerging mandates for Scope 1 and Scope 2 emissions reporting redirect capital allocation toward lower-leakage seal technologies in carbon-intensive end markets, privileging suppliers with documented emission reduction credentials.
- Hybrid manufacturing convergence:Integration of precision CNC machining with additive polymer deposition enables rapid prototyping of complex seal geometries, compressing custom specification cycles from months to weeks for aerospace prototyping programs.
Industry Challenges
- Multi-axis CNC programming expertise scarcity:Complex fluoropolymer machining requires specialized spindle speed and feed rate optimization that conventional metalworking technicians cannot transfer without extensive retraining, constraining production scaling.
- NHTSA automotive validation timelines:Underhood seal qualification for temperature and pressure durability extends development cycles, raising capital requirements for testing infrastructure and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Machined Seals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Backup Rings, Custom Seals Material: PTFE, Nitrile, Silicone, Polyurethane Application: Aerospace, Automotive, Oil & Gas, Food Processing End User: Manufacturers, Distributors, Retailers, OEMs |
| Companies Covered | Flowserve Corporation, John Crane, A.W. Chesterton Company, Garlock Sealing Technologies, Freudenberg Sealing Technologies, SKF, Parker Hannifin Corporation, EagleBurgmann, Trelleborg, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Machined Seals Market Evolving Landscape
Material science advances and regulatory disclosure mandates are restructuring competitive advantage around verified performance documentation rather than unit economics alone.
PTFE composite formulations reinforced with glass fiber and carbon graphite are electrifying seal performance benchmarks in aerospace hydraulic systems. OEM specification teams at tier-one suppliers now mandate these architectures for landing gear and flight control actuators. The technology is compressing qualification cycles for alternative elastomeric candidates while locking in multi-year supply agreements.
EPA leak detection and repair protocols under the Clean Air Act impose mandatory seal performance verification documentation on refineries and chemical plants. Operators must maintain auditable records of seal installation dates, pressure test results, and replacement intervals. Hydrocarbon processing facilities in Texas and Louisiana are responding by consolidating supplier relationships with fabricators offering integrated compliance documentation packages.
Specification-driven procurement now dominates aerospace and oil and gas channels, displacing spot-market purchasing for critical sealing applications. Engineering teams embed preferred seal architectures into equipment bills of material during design phases, creating vendor lock-in that extends across decades of aftermarket replacement demand. This pattern concentrates procurement authority among reliability engineering functions rather than traditional purchasing departments, most visibly in Gulf Coast petrochemical complexes and California aerospace manufacturing corridors.
North America Machined Seals Market Segmentation
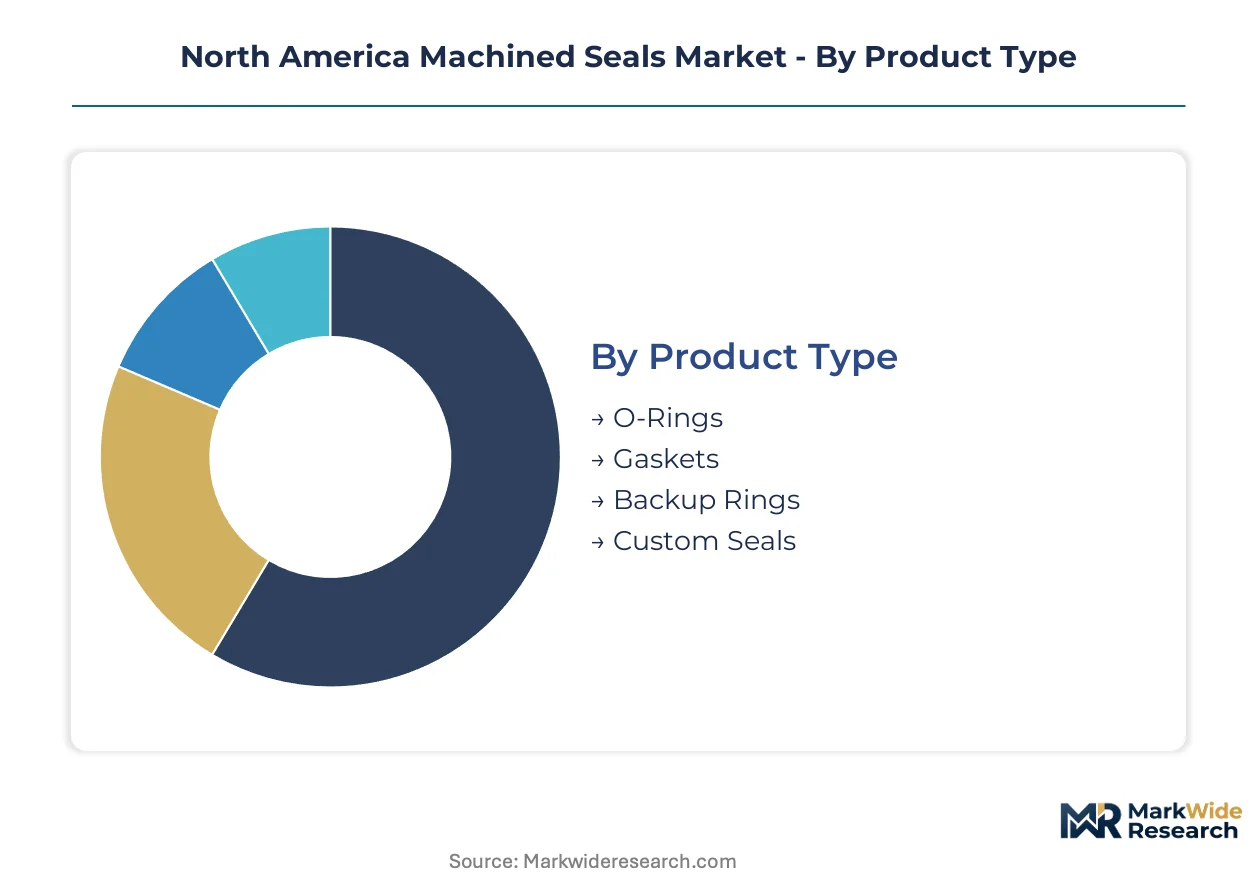
Machined seals serve divergent performance regimes across North America, from aerospace hydraulic systems demanding sub-micron tolerances to commodity industrial replacements. Material selection and fabrication geometry determine capital requirements, certification burdens, and margin capture potential for fabricators operating in this market.
Product Type:
Capital intensity escalates sharply with geometric complexity and tolerance specifications, separating precision-machined architectures from molded commodity alternatives.
- Custom Seals:CNC-machined from solid polymer billets to client-specific geometries with tight dimensional tolerances. Demand concentrates in Texas petrochemical clusters and California aerospace corridors where engineering-intensive specification work creates durable vendor relationships and pricing power resistant to Asian import pressure.
- O-Rings:Molded elastomeric seals produced through compression or injection molding rather than machining. Volume absorption concentrates in general industrial maintenance channels across the US Midwest, though margin compression from commoditized Asian supply erodes domestic producer economics.
- Gaskets:Flat-sealing elements machined from sheet stock or solid billets for flange interfaces in pressure vessels and piping systems.
- Backup Rings:Anti-extrusion devices installed adjacent to primary seals in high-pressure hydraulic assemblies.
Most installed capacity flows through O-Rings. Expansion is steepest in Custom Seals.
Material:
Raw material cost tiers stratify competitive positioning, with fluoropolymer formulations commanding premium pricing against commodity elastomers.
- PTFE:Fluoropolymer resin delivering temperature tolerance above 200°C and chemical resistance to aromatic hydrocarbons. Procurement concentrates in aerospace OEM hydraulic systems and Gulf Coast refinery applications where EPA Clean Air Act enforcement mandates verified emission control performance.
- Nitrile:Acrylonitrile-butadiene rubber offering cost-effective oil resistance for general industrial service. Demand clusters in automotive underhood applications and hydraulic maintenance across the US Southeast, constrained by NHTSA durability validation timelines that extend supplier qualification cycles.
- Silicone:Elastomeric formulation with wide temperature range and FDA-compliant grades for food-contact service.
- Polyurethane:Thermoplastic or thermoset polymer combining abrasion resistance with load-bearing capacity in dynamic sealing applications.
Volume leadership sits with Nitrile. Value capture concentrates in PTFE.
Application:
End-use sector selection determines regulatory exposure, with aerospace and hydrocarbon processing facing the most stringent performance verification mandates.
- Oil & Gas:Downstream refining, midstream transportation, and upstream extraction equipment requiring pressure-rated sealing architectures. Procurement volume concentrates along the Texas and Louisiana Gulf Coast where refinery turnaround cycles and EPA leak detection protocols drive systematic replacement of legacy seal inventories.
- Aerospace:OEM and aftermarket demand for hydraulic actuators, landing gear systems, and flight control mechanisms. Specification lock-in at tier-one suppliers in California and Washington State creates multi-year supply agreements resistant to price-based competition.
- Automotive:Underhood sealing for engines, transmissions, and thermal management systems.
- Food Processing:FDA 21 CFR Part 177 compliant seals for processing equipment and packaging machinery.
Revenue concentration favors Oil & Gas. Food Processing is gaining share fastest.
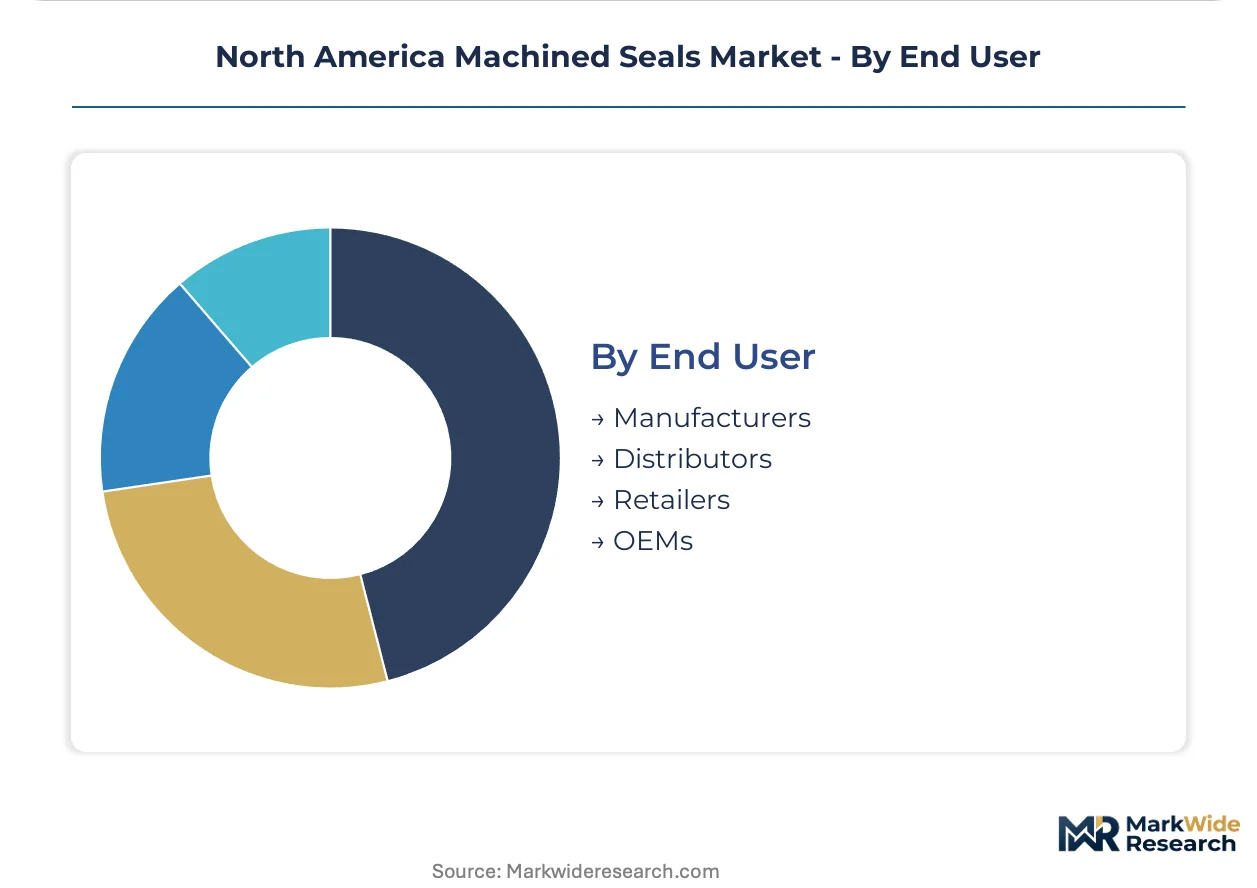
End User:
Channel structure shapes margin distribution, with direct OEM relationships capturing engineering fees absent from distributor-mediated transactions.
- OEMs:Original equipment manufacturers integrating seals into capital equipment during design phases. Aerospace OEMs in California and automotive OEMs in Michigan embed preferred seal architectures into bills of material, creating specification-driven procurement with decade-long aftermarket tails.
- Manufacturers:Industrial equipment fabricators sourcing seals for process skids, pumps, and compressors. Demand clusters in Texas petrochemical engineering firms and Ohio industrial machinery builders where reliability engineering functions control supplier selection.
- Distributors:Industrial supply intermediaries serving maintenance, repair, and operations procurement.
- Retailers:Point-of-sale channels for small-volume replacement and consumer-grade applications.
Transaction volume flows through Distributors. Margin capture concentrates with OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized machinists and polymer engineers concentrate along the Gulf Coast and Great Lakes corridors, anchoring North American fabrication capacity for precision sealing systems.
United States
Texas petrochemical clusters and California aerospace corridors absorb the majority of custom seal procurement. EPA Clean Air Act enforcement mandates systematic replacement of legacy seals in Gulf Coast refineries. Houston and Pasadena host dense networks of turnaround contractors sourcing PTFE architectures for emission control upgrades.
Canada
Alberta oil sands extraction drives demand for high-tolerance seals in steam-assisted gravity drainage systems. Health Canada and PMRA oversight of industrial chemical exposure shapes material selection protocols. Edmonton and Calgary engineering firms specify PTFE-composite seals for bitumen processing equipment facing thermal cycling and abrasive loading.
Mexico
Automotive OEM assembly expansion in Nuevo León and Bajío states creates procurement volume for underhood sealing components. Mexican environmental regulators enforce progressively tighter fugitive emission standards at maquiladora facilities. Querétaro and Guanajuato industrial parks attract seal distributors serving tier-one automotive suppliers.
North America Machined Seals Market Competitive Landscape
Top-tier vendors anchor specification-driven aerospace and oil and gas channels, while mid-tier fabricators compete on turnaround speed for maintenance procurement. The vendor base stratifies across three tiers: integrated multinational suppliers with captive polymer compounding, regional specialists with deep customer engineering relationships, and commodity distributors serving spot-market replacement demand. Dominant competitive moves include backward integration into PTFE resin sourcing and strategic partnerships with turnaround contractors to secure refinery maintenance schedules.
Within the integrated multinational tier, Flowserve Corporation, John Crane, and SKF exemplify divergent strategic positioning. Flowserve leverages its Texas-Louisiana manufacturing footprint to dominate aftermarket supply for hydrocarbon infrastructure. John Crane anchors its position through engineered sealing systems specialization for rotating equipment in chemical processing. SKF extends its bearing-seal bundling strategy into aerospace OEM channels where specification lock-in creates durable revenue streams resistant to price-based competition.
| Leading Market Players |
|---|
| Flowserve Corporation |
| John Crane |
| A.W. Chesterton Company |
| Garlock Sealing Technologies |
| Freudenberg Sealing Technologies |
| SKF |
| Parker Hannifin Corporation |
| EagleBurgmann |
| Trelleborg |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in the Texas Gulf Coast machining corridor now control substantial custom seal fabrication capacity, tightening pricing discipline through consolidated procurement of PTFE resin and captive engineering talent pools. Their ownership structures reward margin expansion over volume capture, reinforcing premium pricing for specification-locked aerospace and EPA-mandated refinery applications while compressing commodity O-ring economics.
Pricing Analysis
Bundled compliance documentation services versus unbundled component supply splits the pricing architecture across the North American machined seals landscape. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales engineering support, with aerospace-grade fluoropolymer seals commanding the deepest margin pools. Cost compression in commodity elastomeric tiers is intensifying because of molded O-ring imports from Asian manufacturers. Maintenance procurement teams at Gulf Coast refineries show least price sensitivity due to EPA enforcement liability, while Midwest industrial distributors face acute pressure from spot-market alternatives.
Supply Chain Analysis
Single-source vulnerability sits with domestic PTFE resin compounders serving aerospace specification channels. Raw material procurement draws from United States, Germany, and Japan for high-grade fluoropolymer feedstocks, with machined billet supply anchored in Texas, California, and Ohio fabrication clusters. Tariff exposure on Chinese-molded commodity imports creates intermittent supply disruption for price-sensitive maintenance channels. Distribution runs through authorized distributors for OEM specification work and direct mill relationships for turnaround contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America machined seals market reads as a late-cycle quality story. Procurement authority has migrated from purchasing departments to reliability engineering functions, privileging suppliers with documented emission reduction credentials and verified performance histories.
For Market Incumbents: Anchor position through backward integration into PTFE resin sourcing and captive multi-axis CNC programming academies. The scarcity of qualified fluoropolymer machinists threatens production scaling. Lock in decade-long aftermarket tails by embedding preferred seal architectures into aerospace OEM bills of material during design phases. For New Entrants and Emerging Players: Capture white space in Canadian oil sands extraction expansion and hybrid manufacturing convergence for rapid aerospace prototyping. Alberta bitumen processing facilities present the most penetrable geography for PTFE-composite seal suppliers lacking Gulf Coast incumbency. Lead with integrated compliance documentation packages that satisfy EPA leak detection protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with deep customer engineering relationships but limited aerospace certification. The five-to-ten-year viability framing favors fabricators with demonstrated FDA 21 CFR Part 177 validation and NHTSA automotive qualification timelines already absorbed. Watch for inflection in SEC climate disclosure rule implementation redirecting capital toward lower-leakage seal technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTFE Resin | Captive supply of aerospace-grade fluoropolymer feedstock insulates margin from allocation risk during capacity constraints. |
| Hybrid Manufacturing Convergence | Integration of CNC machining with additive polymer deposition compresses custom specification cycles for aerospace prototyping programs. |
| Compliance Documentation Packaging | Integrated EPA leak detection protocol records consolidate supplier relationships with Gulf Coast refinery turnaround contractors. |
| Multi-Axis CNC Programming Academy | In-house technician training addresses spindle speed optimization scarcity constraining fluoropolymer production scaling. |
| Aerospace OEM Specification Lock-In | Embedding preferred architectures into tier-one supplier bills of material creates decade-long aftermarket replacement revenue tails. |
Research Methodology
Direct dialogue with plant engineers at Texas petrochemical facilities, procurement leads at aerospace OEMs, aftermarket service heads at rotating equipment specialists, and reliability engineering directors at Gulf Coast refineries grounded the qualitative foundation. Secondary validation drew from EPA enforcement action databases, FDA 21 CFR Part 177 compliance filings, SEC climate disclosure rulemaking records, and customs trade data on fluoropolymer resin imports. Bottom-up fabrication capacity modeling triangulated against top-down end-use demand segmentation across oil and gas, aerospace, automotive, and food processing verticals.
Market size and growth trajectory outputs emerged from integrated demand-side and supply-side calibration across the projection horizon. Segmentation dimensions modeled include product type complexity tier, material formulation grade, application regulatory intensity, and end-user channel structure. CAGRs were derived from elasticity-adjusted replacement cycle analysis and capital expenditure pipeline tracking in hydrocarbon processing and aerospace manufacturing. Industry-specific forecast inputs incorporated EPA enforcement intensity indices and aerospace OEM platform development schedules.
Raw material price volatility, regulatory enforcement timing shifts, and aerospace platform development delays are the dominant revision risks to the forecast envelope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Couplings Market
Industrial Materials
Fly Ash Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Bamboo Products Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
High Purity Quartz Market