
 Controlled Pore Metal Oxide Market | 2026-2036
Controlled Pore Metal Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Controlled Pore Metal Oxide Market Analytics
REACH registration requirements for nanoscale metal oxides is consolidating the European supplier base around producers with in-house toxicology dossiers. Evonik Industries AG leverages its integrated sol-gel manufacturing network to sustain certification across multiple purity grades. American Elements anchors North American supply through vertically controlled rare-earth and transition-metal precursor streams. Nanophase Technologies Corporation differentiates via plasma-processed nanoparticle architectures that navigate tightening EPA reporting thresholds for engineered nanomaterials.
Controlled pore metal oxides are ceramic or metalloid materials engineered with uniform, tunable pore distributions typically spanning 2 to 50 nanometers, manufactured through sol-gel, hydrothermal, or chemical vapor deposition routes to deliver high surface-area substrates for catalytic, adsorptive, or ion-conductive functions. Silica dominates current volume owing to mature chromatography infrastructure, while titanium dioxide captures expanding margin pools in photocatalytic environmental remediation systems. Energy storage applications represent the fastest-growing demand vector as solid-state battery developers specify zirconia-based electrolyte scaffolds with sub-10-nanometer pore uniformity.
EMA pharmaceutical quality guidelines, EPA nanomaterial reporting rules, and REACH Annex XIV authorization lists collectively elevate compliance costs for non-integrated producers while creating preferential market access for certified suppliers. The EU Green Deal industrial emissions benchmarks further redirect procurement toward metal oxide catalysts with demonstrated lifecycle carbon footprints. Stakeholders must monitor evolving classification debates at OECD and ISO levels that could redefine nanomaterial thresholds and trigger additional jurisdictional registration obligations.
Market Dynamics
Sol-gel manufacturing scale-up constraints are compressing lead times for pharmaceutical-grade alumina substrates while REACH Annex XIV authorization timelines force dual-sourcing strategies across European chromatography supply chains.
Growth Catalysts
- Solid-state battery electrolyte scaffolds:Zirconia-based architectures with sub-10-nanometer pore uniformity are pulling capacity investments from German and Japanese precision ceramics producers.
- EMA pharmaceutical quality guidelines:Tightening purity thresholds for chromatography substrates are disqualifying second-tier suppliers and consolidating procurement around certified producers.
- Photocatalytic environmental remediation:Titanium dioxide demand from municipal water treatment infrastructure in Japan and South Korea is expanding margin pools beyond traditional silica applications.
Market Restraints
- Rare-earth precursor volatility:Neodymium and yttrium oxide price swings are compressing margins for non-integrated producers dependent on spot-market sourcing.
- German supply concentration:Dense supplier networks around specialty chemical clusters create single-point vulnerability for North American pharmaceutical procurement.
- Sub-5-nanometer pore uniformity:Technical limitations in hydrothermal synthesis yields are capping output for solid-state battery electrolyte specifications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO quality guidelines are creating first-mover advantage for producers establishing local certification dossiers ahead of domestic chromatography substrate demand.
- EU Green Deal industrial emissions benchmarks:Lifecycle carbon footprint mandates are redirecting catalyst procurement toward metal oxide suppliers with verified low-carbon production routes.
- Plasma-processed nanoparticle convergence:Integration of atmospheric plasma synthesis with continuous sol-gel lines is enabling real-time pore-size tuning for custom catalyst architectures.
Industry Challenges
- REACH toxicology dossier compilation:Nanoscale metal oxide registration timelines are extending 18-24 months and requiring dedicated regulatory affairs functions absent at mid-scale producers.
- Legacy chromatography infrastructure retrofit:Integration complexity with existing HPLC systems is slowing adoption of next-generation mixed-metal-oxide stationary phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Controlled Pore Metal Oxide Market |
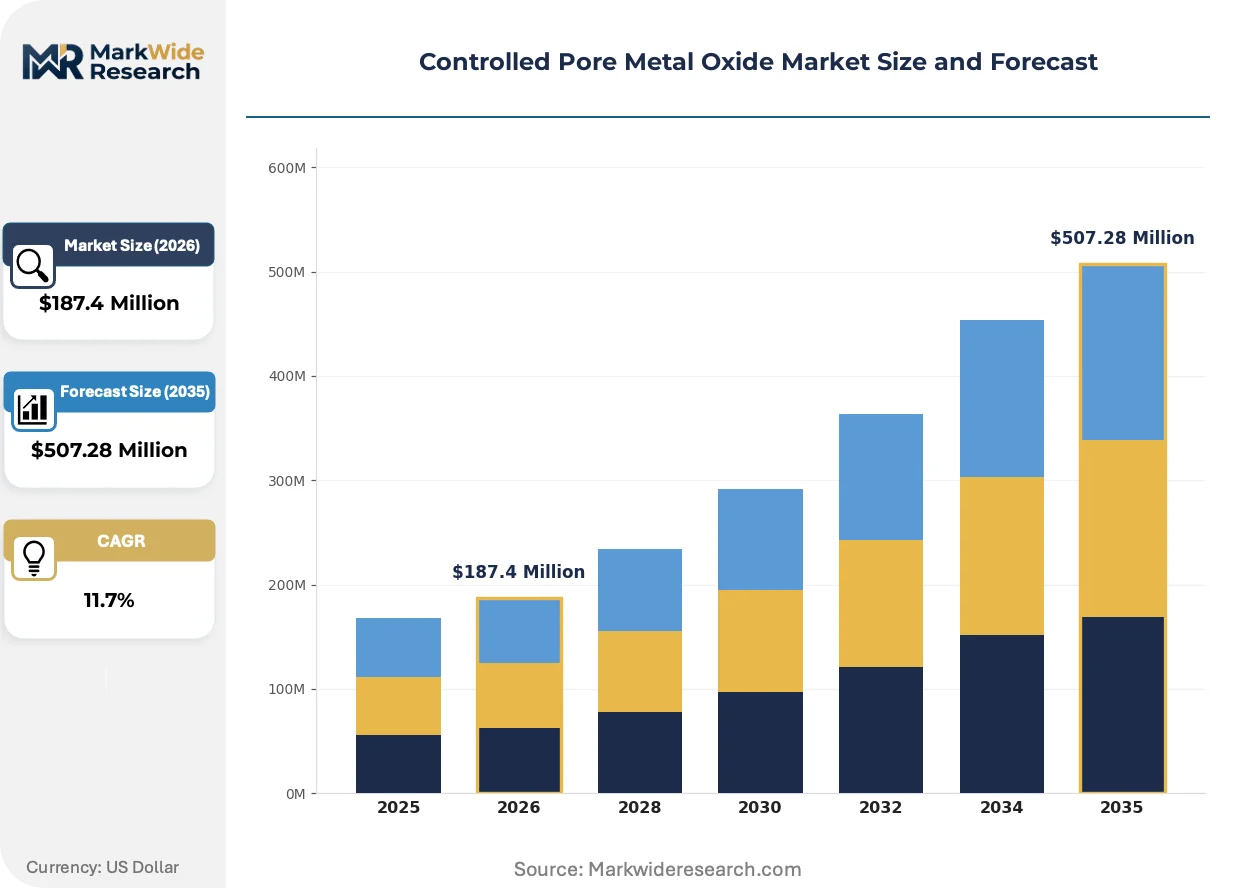
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Alumina, Titanium Dioxide, Zirconia Application: Catalysis, Adsorption, Energy Storage, Environmental Remediation End User: Pharmaceuticals, Electronics, Automotive, Chemical Manufacturing Technology: Sol-Gel, Hydrothermal, Mechanical, Chemical Vapor Deposition |
| Companies Covered | Evonik Industries AG, American Elements, Solvay S.A., Nanophase Technologies Corporation, Baikowski, Inframat Advanced Materials, Nanoshel LLC, US Research Nanomaterials Inc., Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Controlled Pore Metal Oxide Market Evolving Landscape
Atomic layer deposition integration with sol-gel processing is enabling angstrom-level pore-wall control, compressing the performance gap between research-grade and production-scale metal oxide substrates.
Atomic layer deposition is rewriting competitive positioning in high-purity alumina manufacturing. Solid-state battery developers in Germany and Japan are specifying ALD-coated zirconia scaffolds for prototype solid electrolyte interfaces. This precision coating technology is compressing qualification timelines for sub-10-nanometer pore architectures previously achievable only in laboratory batch synthesis.
REACH Annex XIV authorization lists for nanoscale metal oxides are extending compliance timelines to 36 months for new substance entries. European catalyst producers are absorbing these costs through dedicated regulatory subsidiaries. Chromatography substrate suppliers face the steepest burden, as dual-use classifications trigger both pharmaceutical and industrial chemical registration pathways.
Certification-driven procurement consolidation is concentrating pharmaceutical-grade substrate awards among producers with pre-submitted ECHA dossiers. Direct contracting between German chromatography column manufacturers and certified metal oxide producers is displacing distributor intermediaries. This channel compression is most visible in North American procurement, where FDA drug master file cross-referencing favors suppliers with established European regulatory histories.
Controlled Pore Metal Oxide Market Segmentation
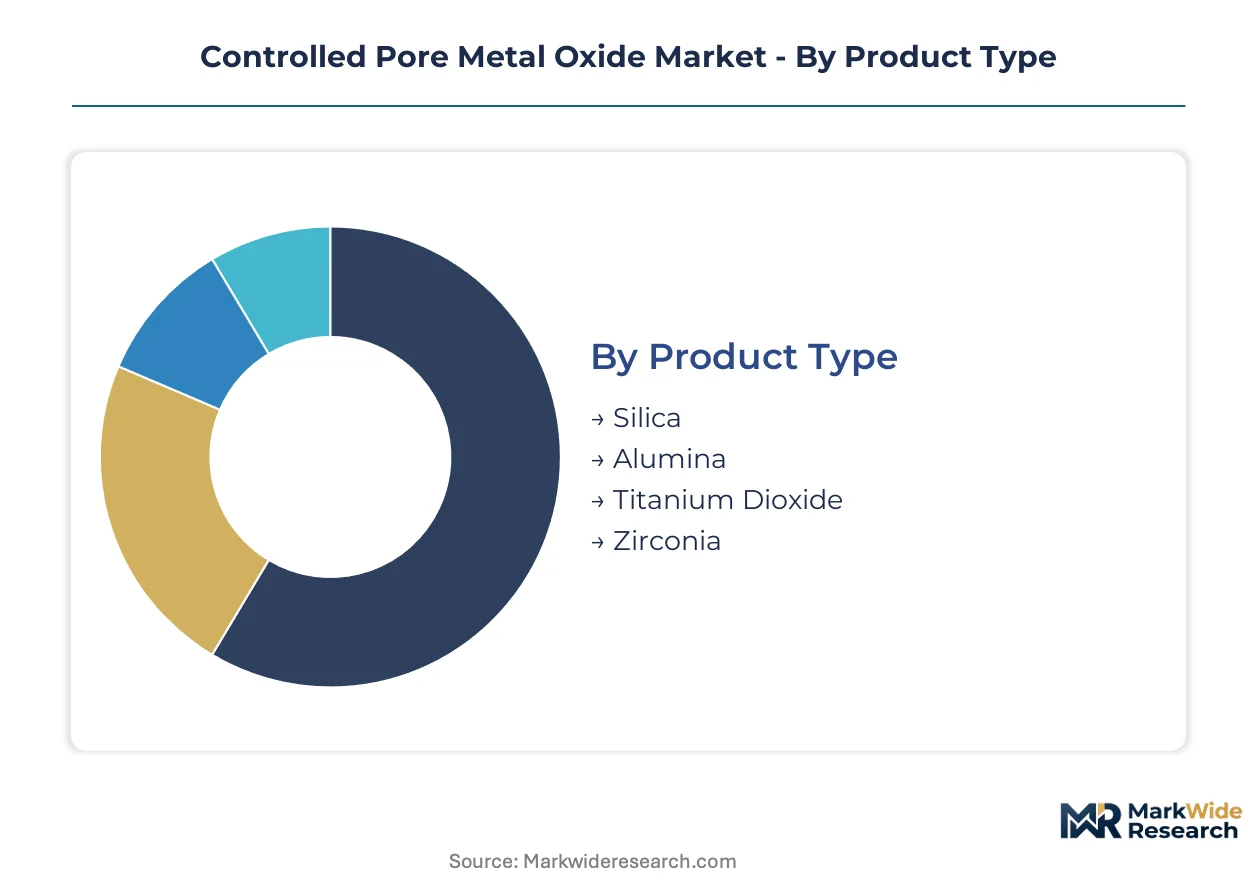
Segmentation in controlled pore metal oxides tracks how pore architecture, surface chemistry, and manufacturing precision align with end-use certification requirements. Each axis reveals distinct margin structures and regulatory exposure profiles.
Product Type:
Pore uniformity specifications and surface area targets differentiate material selection across catalytic and chromatographic applications.
- Silica:Amorphous silicon dioxide matrices with tunable 2-50 nanometer pore distributions dominate chromatography substrate procurement. Pharmaceutical manufacturers in Germany and the United States specify high-purity grades for HPLC stationary phases under tightening EMA and FDA purity thresholds.
- Alumina:Gamma-phase aluminum oxide scaffolds deliver thermal stability above 1000°C for petrochemical catalysis. Demand concentrates in fluid catalytic cracking units across the US Gulf Coast refining corridor, where EPA emissions benchmarks favor regenerable catalyst architectures.
- Titanium Dioxide:Anatase-phase structures with photocatalytic surface activation serve municipal water treatment infrastructure.
- Zirconia:Tetragonal-phase electrolyte scaffolds with sub-10-nanometer pore uniformity target solid-state battery prototypes.
Silica leads on scale; zirconia leads on momentum.
Application:
Functional performance requirements determine pore-size distribution tolerances and surface modification protocols.
- Catalysis:Heterogeneous catalyst supports require 5-20 nanometer mesopore networks for reactant diffusion control. Refinery operators in Japan specify alumina and silica-alumina composites under METI industrial emissions guidelines.
- Energy Storage:Solid-state electrolyte scaffolds demand angstrom-level pore-wall uniformity for lithium-ion conductivity. German battery developers source zirconia substrates with plasma-processed surface architectures.
- Adsorption:Gas separation membranes exploit 2-5 nanometer micropore selectivity for carbon capture applications.
- Environmental Remediation:Photocatalytic water treatment systems deploy titanium dioxide coatings with engineered bandgap activation.
Catalysis commands volume concentration; energy storage commands investment intensity.
End User:
Certification depth and quality documentation requirements stratify procurement relationships across customer categories.
- Pharmaceuticals:Chromatography substrate procurement requires drug master file cross-referencing and EMA/FDA audit trails. Column manufacturers in Switzerland and Germany maintain dual-source contracts with REACH-registered metal oxide producers.
- Electronics:Semiconductor polishing slurries and dielectric layers specify sub-5-nanometer particle size distributions with trace metal contamination below 10 parts per billion.
- Automotive:Catalytic converter washcoats integrate ceria-zirconia mixed oxides for oxygen storage capacity under Euro 7 and EPA Tier 3 emissions standards.
- Chemical Manufacturing:Process catalyst regeneration cycles favor mechanically robust alumina spheres with controlled macropore networks for pressure drop management.
Pharmaceuticals lead on certification premiums; electronics leads on specification stringency.
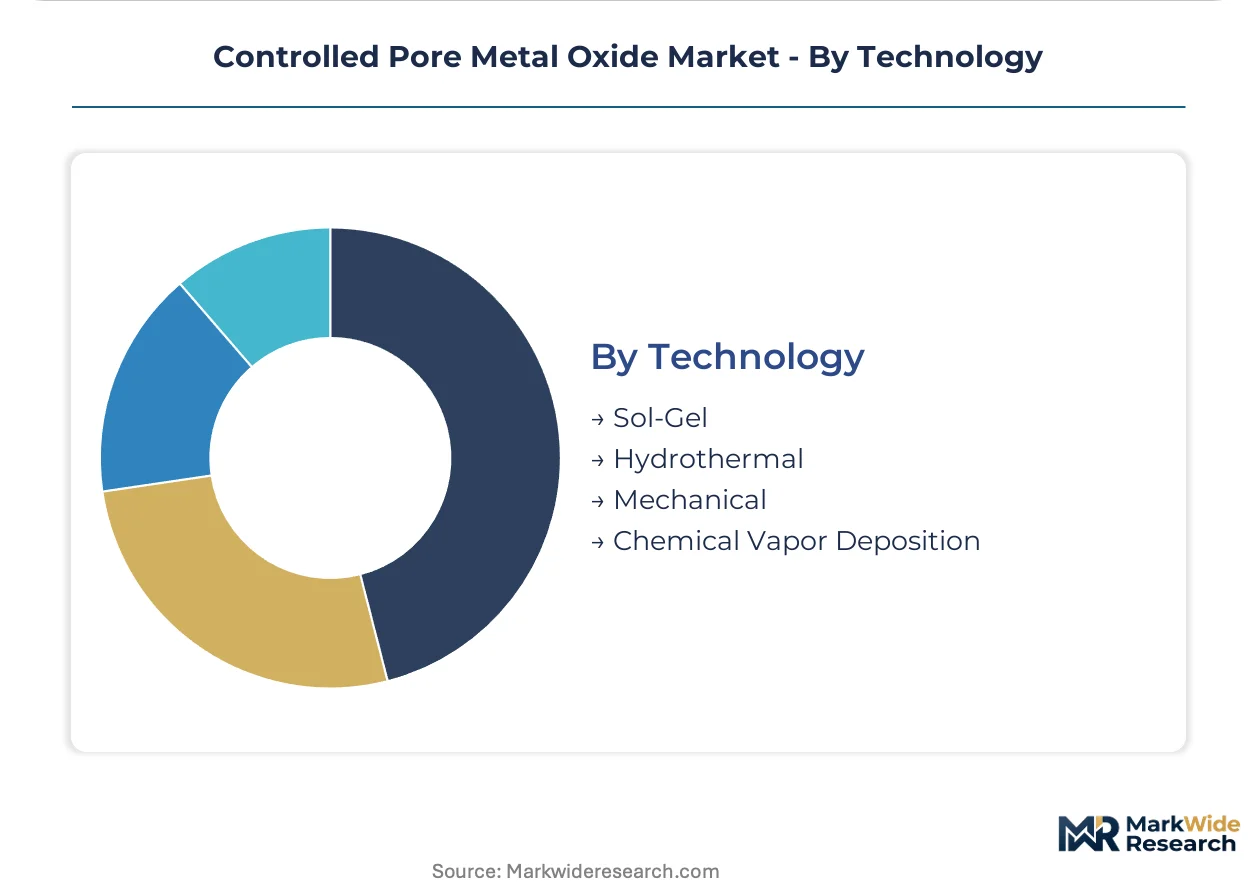
Technology:
Manufacturing route selection governs pore-size distribution width, batch-to-batch reproducibility, and regulatory registration pathways.
- Sol-Gel:Alkoxide hydrolysis and condensation chemistry enables continuous production of spherical particles with narrow pore-size distributions. Evonik Industries AG operates integrated sol-gel networks across Germany to sustain REACH dossier compliance for multiple purity grades.
- Hydrothermal:High-temperature aqueous synthesis yields crystalline metal oxide phases with tunable aspect ratios. Japanese producers favor this route for battery-grade zirconia with controlled tetragonal phase stability.
- Mechanical:Spray drying and calcination of precursor slurries produces robust spheres for fluidized bed applications.
- Chemical Vapor Deposition:Gas-phase precursor decomposition deposits conformal coatings with atomic-layer thickness control.
Sol-gel leads on production scale; chemical vapor deposition leads on precision enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramics engineers and precision materials scientists concentrate in German industrial clusters, Japanese precision manufacturing hubs, and US Gulf Coast chemical corridors, anchoring regional production capabilities for high-purity substrates.
Germany
Solid-state battery developers and chromatography column manufacturers drive zirconia and alumina substrate procurement. REACH Annex XIV authorization timelines force dual-sourcing strategies across European supply chains. The Rhine-Ruhr and Bavarian chemical clusters host integrated sol-gel production networks serving pharmaceutical-grade certification requirements.
United States
Refinery operators along the Gulf Coast specify alumina catalyst supports under EPA emissions benchmarks, while pharmaceutical manufacturers scale HPLC substrate procurement. FDA drug master file cross-referencing favors suppliers with established regulatory histories. Houston and Baton Rouge anchor petrochemical catalyst regeneration cycles with controlled macropore network specifications.
Japan
Precision ceramics producers supply battery-grade zirconia with sub-10-nanometer pore uniformity for solid-state electrolyte prototypes. METI industrial emissions guidelines direct refinery catalyst procurement toward regenerable architectures. The Nagoya and Kansai manufacturing belts concentrate hydrothermal synthesis capacity for tetragonal-phase stability control.
Switzerland
Chromatography equipment manufacturers maintain dual-source contracts with REACH-registered metal oxide producers for pharmaceutical-grade silica substrates. Swissmedic quality guidelines align with EMA purity thresholds for HPLC stationary phases. The Basel pharmaceutical cluster drives direct contracting patterns that displace distributor intermediaries.
India
Domestic pharmaceutical manufacturing expansion creates substrate demand ahead of local certification infrastructure. CDSCO quality guidelines are prompting first-mover investments in regulatory dossier compilation. The Hyderabad and Mumbai pharmaceutical corridors attract producers establishing local chromatography substrate supply capabilities.
Controlled Pore Metal Oxide Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply segments. The vendor base organizes around three strategic archetypes: integrated chemical majors with captive precursor streams, specialized nanoparticle architects with plasma-processing capabilities, and regional distributors with certification brokerage functions. Capacity expansion and regulatory dossier compilation represent the dominant competitive moves as REACH timelines extend.
Among Germany-based integrated producers, Evonik Industries AG exemplifies the diversified chemical major archetype with sol-gel manufacturing networks sustaining multiple purity grades. American Elements occupies a position representing North American vertical control over rare-earth and transition-metal precursor streams. Nanophase Technologies Corporation sits within the specialized architect tier, anchoring plasma-processed nanoparticle capabilities that navigate EPA reporting thresholds for engineered nanomaterials.
| Leading Market Players |
|---|
| Evonik Industries AG |
| American Elements |
| Solvay S.A. |
| Nanophase Technologies Corporation |
| Baikowski |
| Inframat Advanced Materials |
| Nanoshel LLC |
| US Research Nanomaterials Inc. |
| Cabot Corporation |
| Others |
Value Network & Pricing Analysis
Specialized ceramics engineers concentrated in Germany's Rhine-Ruhr corridor and Japan's Nagoya manufacturing belt create labor-cost differentials that widen pricing spreads between pharmaceutical-grade certification tiers and industrial-standard grades. REACH dossier compilation costs and EPA nanomaterial reporting thresholds further stratify procurement economics across buyer segments.
Pricing Analysis
Bundled certification-and-substrate contracts dominate pharmaceutical procurement, while unbundled spot transactions persist in industrial catalyst applications. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels reflects purity thresholds and EMA/FDA audit trail completeness. Cost compression in technical-grade alumina is intensifying because rare-earth precursor volatility compresses margins for non-integrated producers. Contract research organizations exhibit highest price sensitivity; solid-state battery developers show lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Freight costs for hydrothermally synthesized zirconia from Japan to German battery developers run through specialized temperature-controlled logistics networks. Supply concentrates in Germany, Japan, and the United States, with dense supplier networks around specialty chemical clusters creating single-point vulnerability. Production draws from rare-earth oxide precursors, high-purity alkoxides, and plasma-processed nanoparticle feedstocks. Tariff exposure on Chinese rare-earth imports presents structural risk. Distribution runs through direct contracting between column manufacturers and certified producers, displacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The controlled pore metal oxide market functions as a stable compounder anchored by irreversible regulatory ratchets in pharmaceutical quality and environmental emissions that perpetually tighten purity thresholds and certification requirements.
For Market Incumbents: Lock in regulatory dossier advantages by accelerating REACH Annex XIV pre-submissions ahead of competitor timelines. Deepen captive precursor control through backward integration into rare-earth oxide streams, insulating margin structures from spot-market volatility that threatens non-integrated producers. For New Entrants and Emerging Players: CDSCO quality guidelines in India open a window for first-mover establishment of local certification infrastructure ahead of domestic pharmaceutical manufacturing expansion. Target chromatography substrate supply to Hyderabad and Mumbai corridors, leveraging regulatory dossier compilation as primary go-to-market credential. For Investors and Strategic Acquirers: Diversified chemical majors with captive sol-gel networks are the most active acquirer in this space, consolidating fragmented mid-scale producers lacking dedicated regulatory affairs functions. Five-to-ten-year viability hinges on certification infrastructure depth rather than capacity scale alone. Watch for EMA guideline revisions on nanomaterial thresholds as inflection indicator for additional registration obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Precursors | Captive neodymium and yttrium oxide supply secures margin stability against spot-market volatility. |
| REACH Dossier Pre-Submission | Early ECHA registration locks in preferred supplier status for European pharmaceutical procurement. |
| Plasma-Processing Capacity Addition | Atmospheric plasma synthesis enables real-time pore-size tuning for custom solid-state battery architectures. |
| Indian Regulatory Dossier Compilation | CDSCO certification infrastructure establishes first-mover position in expanding domestic chromatography market. |
| Long-Term Supply Agreement with Battery Developers | Contracted offtake for sub-10-nanometer zirconia scaffolds de-risks capacity investment in precision ceramics. |
Research Methodology
Direct dialogue with plant managers at German and Japanese precision ceramics facilities, procurement leads at pharmaceutical column manufacturers, regulatory affairs directors navigating REACH timelines, and technical R&D heads at solid-state battery developers grounded qualitative assessments. Secondary validation drew from ECHA registration databases, FDA drug master file cross-references, SEC filings of diversified chemical majors, and METI industrial emissions reports. Bottom-up capacity assessments and top-down demand segmentation were triangulated to constrain estimate variance.
Output spans product type, application, end user, technology, and geographic production hub across the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and supply-constraint analysis. Key inputs included REACH authorization timeline probabilities, solid-state battery prototype qualification rates, and refinery catalyst regeneration cycle frequencies.
Revisions become necessary when OECD nanomaterial classification debates trigger additional jurisdictional registration obligations, or when rare-earth export restrictions disrupt precursor supply. Forecasts reflect assumptions about regulatory ratchet continuity and certification cost absorption capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Solid-Ion Conductors Market
Ceramics
Methyl Silicate Market
Ceramics
Calcined Kaolin Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Zirconia Ceramics Market
Ceramics
Europe Activated Alumina Market
Ceramics
Calcium Silicate Market
Ceramics
Clay Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Pottery Ceramics Market
Ceramics
Calcined Bauxite Market
Ceramics
Ceramic Additives Market
Ceramics
Ceramic Lining Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Global Zirconia Oxygen Sensors Market