
 Cerium Nitride Market | 2026-2036
Cerium Nitride Market Size, Share, and Industry Trends Forecast 2026-2036
Cerium Nitride Market Insights
Technical support and process optimization subscriptions for cerium nitride deposition equipment is pivoting vendor revenue models from one-time powder sales to recurring service contracts. American Elements leverages its vertical integration from rare earth oxide through nitridation to control purity grades for semiconductor clients. Lynas Rare Earths Ltd anchors supply security through its Mount Weld concentrate and Malaysian processing assets. Mitsui Mining & Smelting Co., Ltd. differentiates via precision nanoparticle synthesis for magnetic thin-film applications.
Cerium nitride is a refractory ceramic compound of cerium and nitrogen with a cubic crystal structure and high thermal stability exceeding 2000°C, produced through direct nitridation of cerium metal or carbothermic reduction under ammonia atmosphere. Its primary commercial purpose centers on serving as a functional coating material for extreme-environment components and as a precursor in rare-earth permanent magnet manufacturing. Powder formulations dominate current revenue due to established metallurgical demand, while nanoparticle grades represent the fastest-expanding margin pool driven by precision electronics specifications. Semiconductor manufacturing applications command premium pricing relative to catalyst end uses, reflecting tighter purity thresholds and qualification barriers.
China's MEE enforces wastewater and tailings standards on rare earth nitride facilities, while REACH in Europe mandates registration and hazard communication for imported cerium compounds. The US EPA oversees emissions from nitridation processes under Clean Air Act provisions, creating differentiated compliance costs across production geographies. Japan's METI coordinates strategic stockpiling policies that influence regional availability through JOGMEC allocations. Stakeholders must monitor evolving rare earth export licensing frameworks and deposition equipment technology roadmaps to anticipate supply constraints and qualification windows.
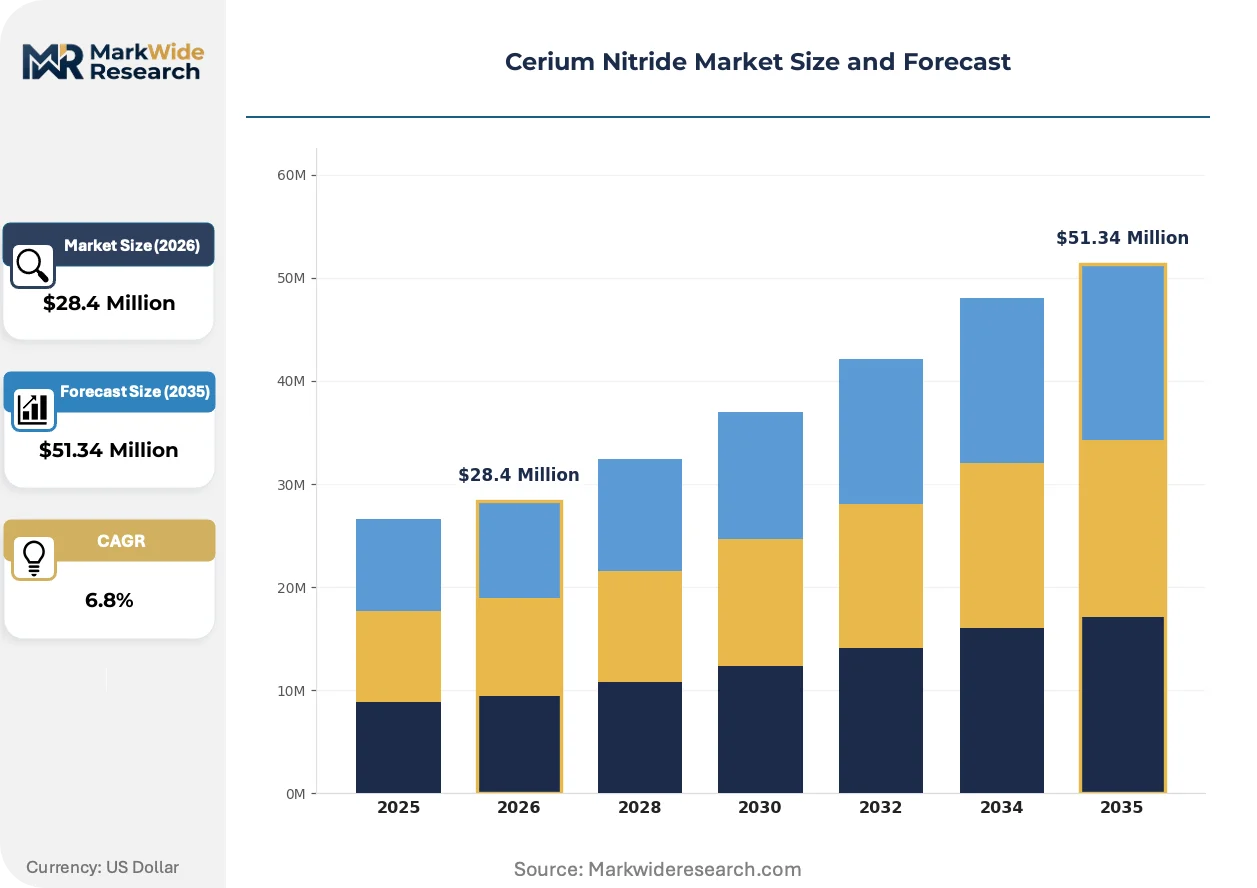
Market Dynamics
Semiconductor lithography mask coatings are concentrating demand for ultra-high-purity cerium nitride around East Asian manufacturing clusters, tightening qualification windows and compressing supplier lead times for deposition-grade material.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement of wastewater standards on rare earth processing is accelerating facility upgrades that yield cleaner nitride output suitable for semiconductor qualification.
- Extreme ultraviolet lithography:EUV mask blank manufacturing in Taiwan and South Korea is consuming cerium nitride films for protective capping layers on multilayer mirrors.
- Permanent magnet precursors:NdFeB sintering operations are incorporating cerium nitride as a grain boundary diffusion source to reduce heavy rare earth dependence.
Market Restraints
- Input cost volatility:Cerium oxide concentrate pricing fluctuates with Chinese export quota announcements, squeezing nitridation margins for non-integrated processors.
- Supply concentration risk:Over 80% of rare earth nitride capacity sits within China's Inner Mongolia and Jiangxi processing corridors, exposing buyers to single-jurisdiction disruption.
- Substitution threat:Lanthanum nitride and yttrium nitride are qualifying for select mask coating applications at 15-20% cost discounts.
Strategic Opportunities
- Malaysian processing expansion:Lynas Rare Earths' Gebeng facility offers non-Chinese nitridation feedstock for Western semiconductor supply chains seeking origin diversification.
- Quantum computing substrates:Superconducting qubit fabrication is testing cerium nitride buffer layers for lattice-matched heterostructures.
- Japan's METI stockpiling:JOGMEC strategic reserve allocations are creating offtake guarantees for qualified rare earth nitride suppliers.
Industry Challenges
- Deposition technician scarcity:Physical vapor deposition operators with rare earth nitride experience command 40% wage premiums in Hsinchu and Seoul corridors.
- Qualification timeline compression:TSMC and Samsung mask blank qualification cycles now demand 18-month stability data, extending working capital cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cerium Nitride Market |
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $51.34 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cerium Nitride Powder, Cerium Nitride Coatings, Cerium Nitride Films, Cerium Nitride Nanoparticles End Use Industry: Aerospace, Automotive, Electronics, Renewable Energy Application: Catalysts, Magnetic Materials, Optical Devices, Semiconductor Manufacturing Form: Granules, Pellets, Suspensions, Solutions |
| Companies Covered | American Elements, Lynas Rare Earths Ltd, Mitsui Mining & Smelting Co., Ltd., Shepherd Chemical Company, Sichuan Wonaixi New Material Technology Co., Ltd., China Northern Rare Earth Group, Avalon Advanced Materials, IREL (India) Limited, Canada Rare Earth Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cerium Nitride Market Trends and Innovations
Plasma-enhanced nitridation and atomic layer deposition are rewriting process economics for thin-film cerium nitride, while regulatory pressure on rare earth supply chains is forcing transparency upgrades across the value chain.
Atomic layer deposition of cerium nitride is rewriting thickness control standards for sub-nanometer mask coatings. Samsung Foundry and Intel Mask Operations are qualifying ALD precursors for EUV pellicle substrates. This precision is compressing tolerance bands to single-atom-layer specifications, disqualifying conventional sputtering equipment.
REACH registration requirements for cerium compounds are forcing European importers to document full substance lifecycle hazard profiles. ECHA's 2024 updated guidance on rare earth metal nitrides is extending dossier preparation timelines. German and French chemical distributors are consolidating sourcing to pre-registered suppliers, raising barriers for Chinese direct exporters.
Subscription-based deposition process support is displacing traditional equipment-and-consumables sales. Applied Materials and TEL are bundling cerium nitride target replacement with real-time plasma monitoring analytics. This model is most visible in Taiwan's Hsinchu Science Park, where foundries prefer operational expenditure structures over capital-heavy target procurement.
Cerium Nitride Market Segmentation
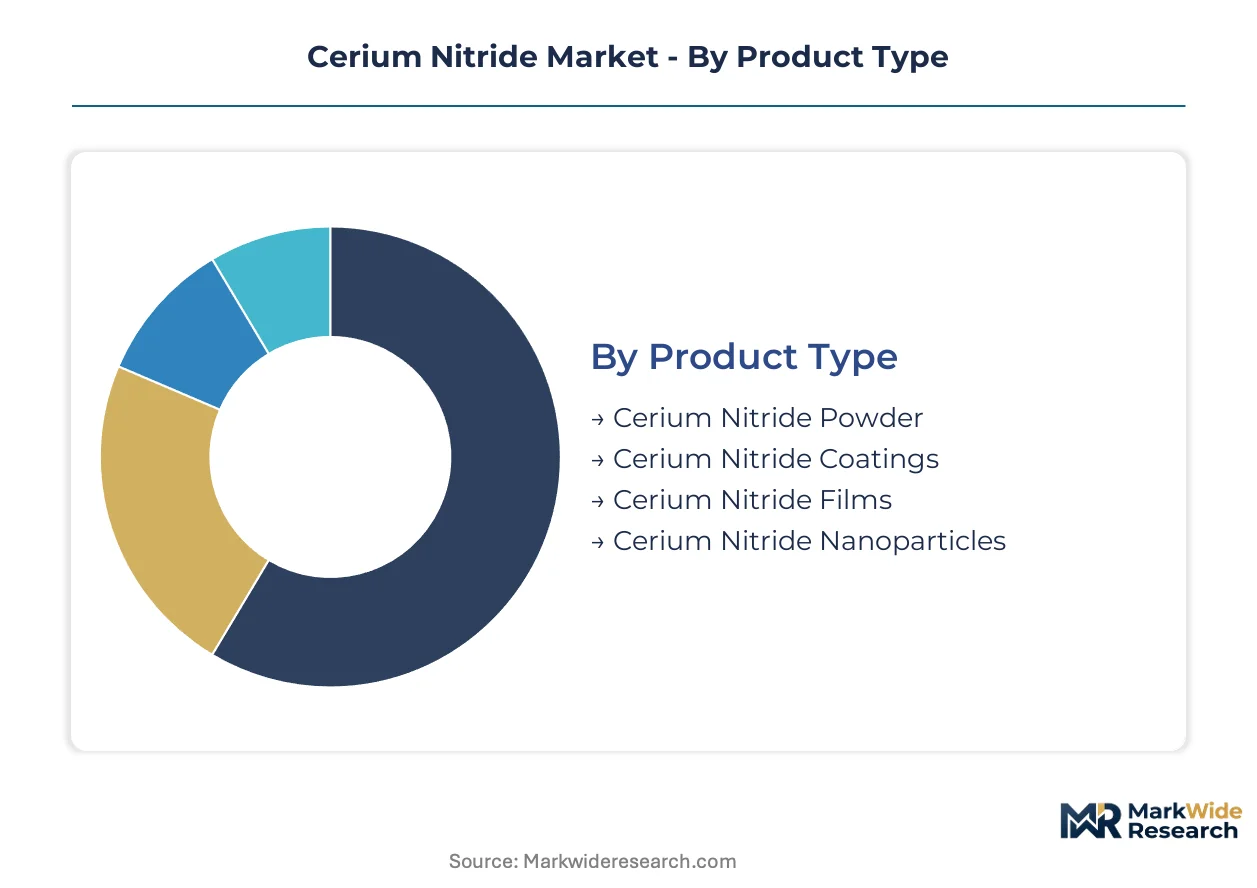
Cerium nitride's value chain splits sharply between commodity metallurgical inputs and precision deposition materials for semiconductor fabrication. Segmentation reveals where pricing power concentrates and which qualification barriers protect margins.
Product Type:
Standalone powder formulations serve established metallurgical demand, while embedded thin-film systems capture premium pricing in lithography equipment supply chains.
- Cerium Nitride Powder:Metallurgical-grade material with 99.5% purity specifications dominates volume shipments to NdFeB magnet manufacturers. Procurement concentrates in Chinese Inner Mongolia processing corridors where carbothermic reduction yields cost-competitive output for grain boundary diffusion applications.
- Cerium Nitride Films:Physical vapor deposition targets for EUV mask blank capping layers command the widest price spreads. TSMC and Samsung Foundry qualification requirements in Hsinchu and Seoul metropolitan clusters enforce 18-month stability documentation that locks out unqualified suppliers.
- Cerium Nitride Coatings:Thermal spray formulations for aerospace turbine components.
- Cerium Nitride Nanoparticles:ALD precursor grades for sub-nanometer thickness control.
Volume placements concentrate in powder formulations; the faster expansion belongs to nanoparticle grades serving atomic layer deposition roadmaps.
End Use Industry:
Cost tier stratification separates defense-aerospace premiums from automotive scale economies and electronics precision pricing.
- Electronics:Semiconductor lithography and magnetic storage applications drive the steepest margin expansion. Taiwan's Hsinchu Science Park and South Korea's Giheung cluster anchor demand for deposition-grade material with purity thresholds above 99.99%.
- Aerospace:Refractory coatings for turbine blades and hypersonic leading edges tolerate lower purity but require thermal cycling certification. US Department of Defense offtake through DLA strategic stockpiling insulates this segment from commercial price volatility.
- Automotive:Catalytic converter washcoat formulations and sensor applications.
- Renewable Energy:Permanent magnet precursors for direct-drive wind turbine generators.
Electronics commands the highest unit pricing; renewable energy is climbing fastest on wind turbine installation ramps.
Application:
Application maturity determines whether specifications are locked by incumbent qualification or remain open to new process technologies.
- Semiconductor Manufacturing:EUV pellicle substrates and mask blank protective layers represent the most demanding qualification environment. Intel Mask Operations and Samsung Foundry are jointly specifying ALD precursor purity grades that exceed legacy sputtering target standards by an order of magnitude.
- Magnetic Materials:NdFeB grain boundary diffusion sources reduce heavy rare earth terbium and dysprosium dependence. Japanese magnet producers in Aichi and Fukuoka prefectures are qualifying cerium nitride as a terbium displacement strategy under METI resource security guidelines.
- Catalysts:Automotive exhaust treatment and petrochemical refining applications.
- Optical Devices:Infrared window coatings and laser system components.
Semiconductor manufacturing locks in the longest qualification cycles; magnetic materials is expanding most quickly on rare earth substitution economics.
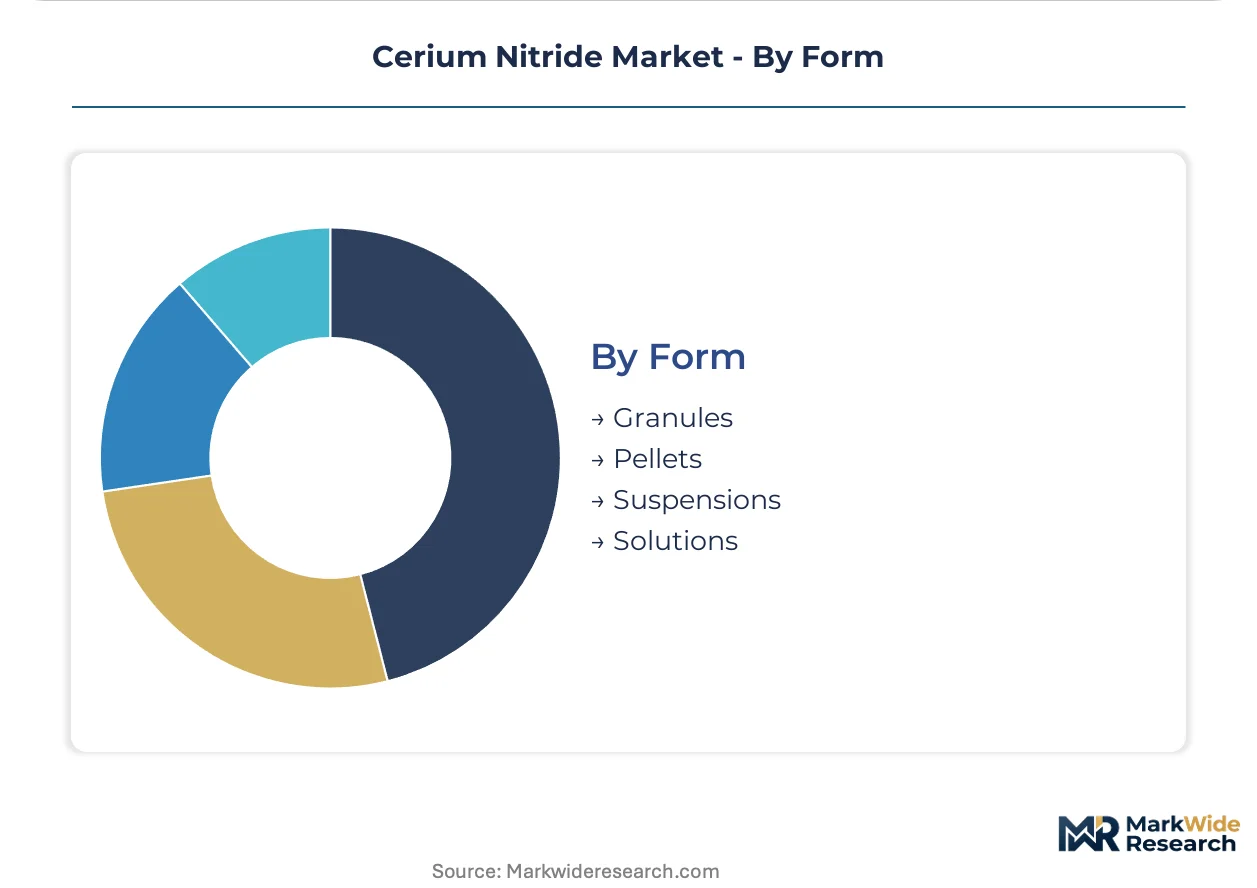
Form:
Supply chain configuration separates bulk granular shipments from precision-formulated suspensions for deposition equipment integration.
- Pellets:Pressed and sintered forms for physical vapor deposition target manufacturing. Japanese suppliers in Saitama and Osaka prefectures dominate high-density pellet production for TEL and Applied Materials equipment compatibility.
- Suspensions:Colloidal dispersions for spin-coating and dip-coating processes in optical device fabrication. German and French chemical distributors are consolidating procurement around REACH-registered supply chains per ECHA guidance.
- Granules:Metallurgical feedstock for nitridation furnace charging.
- Solutions:Soluble precursors for chemical bath deposition and electroplating.
Pellet shipments dominate current revenue; suspensions are gaining share fastest on coating process automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces over four-fifths of rare earth nitride feedstock, yet Taiwan and South Korea consume the highest-purity deposition grades for semiconductor manufacturing. This geographic split between upstream processing and downstream precision demand shapes trade flows and qualification requirements.
China
Inner Mongolia and Jiangxi processing corridors dominate carbothermic nitridation output for metallurgical-grade powder. MEE wastewater enforcement under dual carbon goals is upgrading facility environmental compliance. Baotou rare earth industrial parks are consolidating smaller nitride producers to meet tightening tailings standards.
Taiwan
Hsinchu Science Park fabs anchor procurement for EUV mask blank capping layers at 99.99% purity thresholds. The National Science and Technology Council coordinates strategic material stockpiling for semiconductor supply security. TSMC mask operations are compressing supplier qualification cycles to eighteen-month stability documentation windows.
South Korea
Giheung and Pyeongtaek semiconductor clusters drive demand for physical vapor deposition targets. Samsung Foundry and SK Hynix are jointly specifying atomic layer deposition precursor grades. The Ministry of Trade, Industry and Energy classifies cerium nitride under critical mineral security frameworks.
Japan
Aichi and Fukuoka prefecture magnet manufacturers are qualifying cerium nitride for terbium displacement in NdFeB grain boundary diffusion. METI coordinates JOGMEC strategic reserve allocations for rare earth nitrides. Osaka and Saitama suppliers dominate high-density pellet production for deposition equipment compatibility.
United States
Department of Defense offtake through DLA strategic stockpiling insulates aerospace refractory coating demand from commercial price swings. EPA Clean Air Act oversight of nitridation emissions creates compliance cost differentiation versus Asian production. Mountain Pass adjacent processing discussions remain preliminary for nitride value chain extension.
Cerium Nitride Market Competitive Landscape
Top-tier vendors anchor deposition-grade material supply, while commodity powder processors compete on carbothermic reduction scale. The market structures around three tiers: integrated rare earth miners with nitridation capabilities, specialized chemical processors serving semiconductor qualification, and regional metallurgical suppliers for magnet applications. Strategic moves concentrate on backward integration into rare earth concentrate supply and forward integration into deposition equipment service contracts.
Within the integrated mining tier, American Elements and Lynas Rare Earths Ltd represent archetypes of upstream control strategies—American Elements through oxide-to-nitride vertical integration, Lynas through Mount Weld concentrate and Malaysian processing assets. Mitsui Mining & Smelting Co., Ltd. occupies a position among precision chemical specialists, exemplifying nanoparticle synthesis capabilities for magnetic thin-film applications. These three companies illustrate the competitive spectrum from bulk metallurgical supply to semiconductor-grade qualification.
| Leading Market Players |
|---|
| American Elements |
| Lynas Rare Earths Ltd |
| Mitsui Mining & Smelting Co., Ltd. |
| Shepherd Chemical Company |
| Sichuan Wonaixi New Material Technology Co., Ltd. |
| China Northern Rare Earth Group |
| Avalon Advanced Materials |
| IREL (India) Limited |
| Canada Rare Earth Corporation |
| Others |
Pricing and Supply Chain Analysis
Physical vapor deposition technicians with rare earth nitride expertise in Hsinchu and Seoul corridors command 40% wage premiums, compressing margins in premium-grade deposition services while widening spreads between qualified and commodity-tier suppliers. Labor-cost differentials across East Asian semiconductor clusters directly feed into three-tier pricing stratification across deposition-grade, metallurgical-grade, and catalyst-grade cerium nitride.
Pricing Analysis
Margin tightening in deposition-grade tiers reflects TSMC and Samsung's compressed eighteen-month qualification windows that lock out unqualified competitors. Three-tier pricing structure across premium, standard, and economy levels separates EUV mask blank capping layers from NdFeB grain boundary diffusion sources and automotive catalyst washcoats. Price differentiation traces to purity thresholds and REACH registration status for European buyers. Catalyst end-use buyers exhibit highest price sensitivity; semiconductor fabs accept premium positioning for qualified supply security.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale foundry demand in Taiwan and South Korea, while distributor networks serve fragmented catalyst and magnet manufacturers. Raw material flows draw from Chinese Inner Mongolia and Jiangxi processing corridors for oxide concentrate, Malaysian Gebeng facility for non-Chinese feedstock, and Japanese Osaka and Saitama pellet production. Single-jurisdiction concentration risk exceeds 80% for carbothermic nitridation capacity. Distribution runs through equipment vendor bundling agreements in Hsinchu Science Park.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atomic layer deposition is displacing legacy sputtering equipment for sub-nanometer mask coatings, compressing supplier qualification timelines and rewriting process economics. Incumbents and entrants must position around this equipment-transition inflection.
For Market Incumbents: Anticipate lanthanum nitride and yttrium nitride substitution threats by deepening rare earth oxide-to-nitride captive supply and pre-qualifying alternative precursor chemistries. Secure JOGMEC strategic reserve allocations through METI coordination. Investment in plasma-enhanced nitridation R&D protects deposition equipment service contract renewals against ALD equipment vendors.
For New Entrants and Emerging Players: E-commerce chemical distribution platforms offer low-friction entry into REACH-registered European supply chains underserved by direct Chinese exporters. Target colloidal suspension formulations for optical device spin-coating automation in German and French chemical distributor networks. White-space opportunity sits in quantum computing substrate buffer layer qualification programs.
For Investors and Strategic Acquirers: Re-rating potential sits with Malaysian processing assets given China's MEE enforcement tightening and Western semiconductor supply chain origin diversification mandates. Long-term viability hinges on deposition equipment vendor bundling relationships. Monitor JOGMEC allocation announcements as inflection signal for qualified supplier scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Concentrate | Mount Weld and similar assets secure nitridation feedstock against Chinese export quota volatility. |
| Plasma-Enhanced Nitridation Capacity Expansion | Applied Materials and TEL equipment roadmaps favor cleaner output for semiconductor qualification. |
| REACH Registration Dossier Completion | ECHA compliance enables German and French distributor consolidation into pre-registered supply chains. |
| ALD Precursor Formulation Development | Intel Mask Operations and Samsung Foundry joint specifications exceed legacy sputtering purity thresholds. |
| Strategic Stockpiling Partnership with JOGMEC | METI allocations create offtake guarantees insulating qualified suppliers from price volatility. |
Research Methodology
Document review covered rare earth trade flow databases, SEC filings from deposition equipment vendors, and ECHA registration dossiers, complemented by interviews with physical vapor deposition equipment specialists, rare earth processing plant managers, and semiconductor procurement leads at foundry operations. Primary fieldwork across Hsinchu Science Park and Giheung semiconductor clusters validated secondary data on qualification timelines. Bottom-up volume estimates from nitridation furnace capacity and top-down demand triangulation from EUV lithography equipment deployment trajectories were cross-referenced.
Segment-level outputs across the modeling period reflect disaggregated projections by product form, end-use industry, and geographic production hub. CAGRs were derived from equipment vendor capex disclosures and foundry build-out schedules. Forecast inputs incorporated MEE enforcement intensity scenarios, JOGMEC stockpile allocation patterns, and ALD precursor adoption curves.
The model holds under stable rare earth export licensing frameworks; deviation in Chinese dual carbon goal enforcement timelines or Taiwan Strait logistics disruptions would shift supply availability assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Iran Ceramic Tiles Market
Ceramics
Ceramic Ware Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Alumina Slurry Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Global Ceramic Tube Market
Ceramics
Medical Ceramics Market
Ceramics
Methyl Silicate Market
Ceramics
Strontium Carbonate Market
Ceramics
White Fused Alumina Market
Ceramics
Calcium Oxide Market
Ceramics
Ceramic Substrate Market
Ceramics
Ceramic Pigments Market
Ceramics
Lithium Silicate Market
Ceramics
Calcined Bauxite Market
Ceramics
North America Activated Alumina Market