
 Glass Ceramics Market | 2026-2036
Glass Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Ceramics Market Analysis
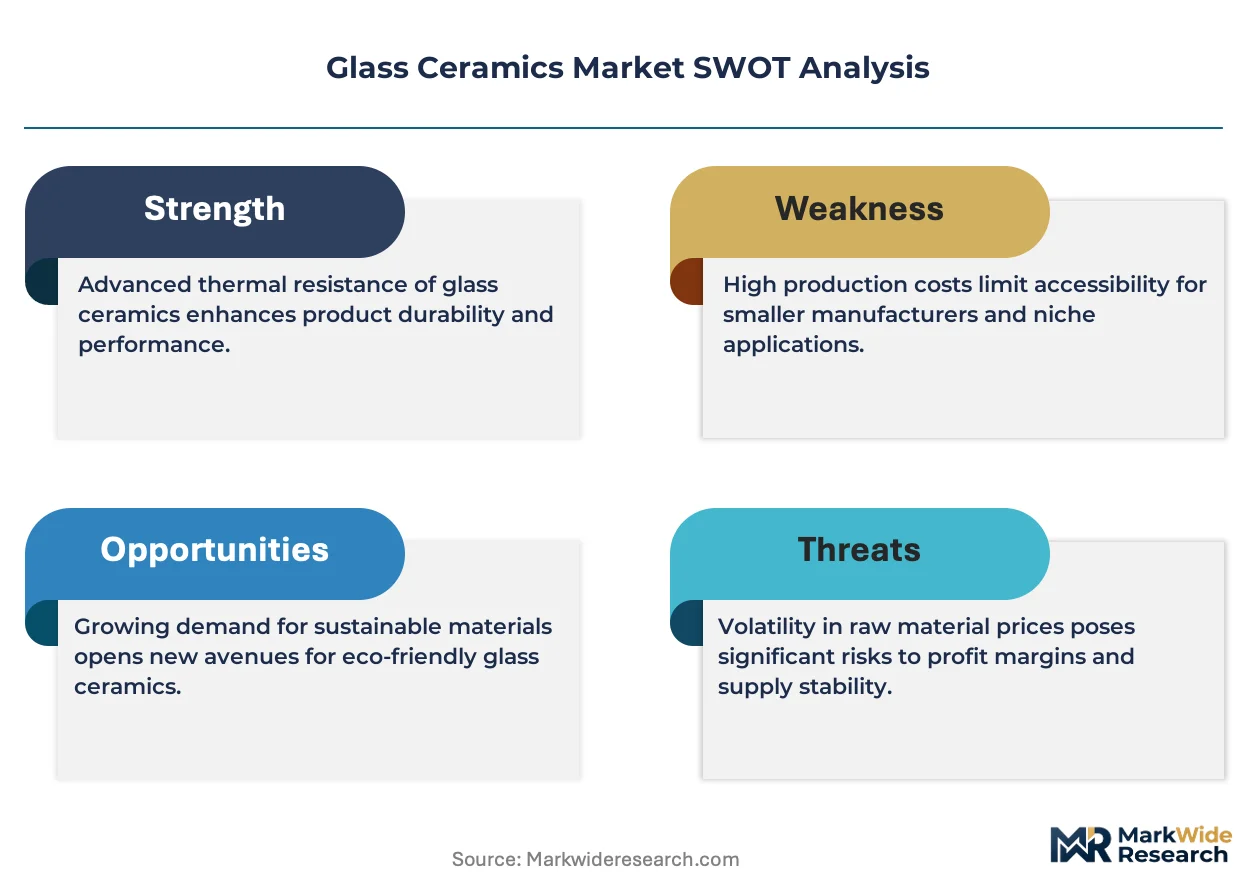
Controlled crystallization technology is tilting glass ceramics production toward near-net-shape manufacturing with minimal post-processing waste. Corning Incorporated leverages its fusion draw expertise to dominate high-performance substrate markets. Schott AG sustains leadership in thermal shock-resistant cookware and fire-rated glazing through proprietary Zerodur formulations. Kyocera Corporation anchors the electro-ceramics segment with multilayer ceramic capacitors for 5G infrastructure.
Glass ceramics are polycrystalline solids produced through controlled nucleation and crystallization of glass precursors, typically containing lithium aluminosilicate or magnesium aluminosilicate crystal phases that yield thermal expansion coefficients below 0.5 ppm/K. These materials serve precision applications where dimensional stability across temperature swings determines component reliability. Electro-ceramics generated the largest revenue pool in 2024, driven by insatiable capacitor demand from telecommunications and automotive electronics. Dental ceramics represent the fastest-expanding product category, as chairside CAD/CAM milling of lithium disilicate crowns displaces traditional metal-ceramic restorations in clinics across North America and Western Europe.
The EPA regulates silica emissions from glass ceramics furnaces under National Emission Standards for Hazardous Air Pollutants, while REACH restricts cadmium and lead content in decorative glazes sold into European consumer markets. Japan's METI enforces JIS R 1607 standards for fracture toughness testing that determine qualification for aerospace turbine components. Stakeholders must monitor evolving PFAS restrictions in fluorinated nucleating agents, as regulatory pressure on per- and polyfluoroalkyl substances threatens process chemistries that have defined glass ceramic fabrication for decades.
Market Dynamics
EU Green Deal emissions standards are forcing crystallization furnace operators to abandon gas-fired batch processing for electric melting systems, restructuring capital allocation across the entire supply base.
Growth Catalysts
- Chairside CAD/CAM milling:Dental clinics in North America and Western Europe are replacing metal-ceramic restorations with lithium disilicate crowns, pulling volume through precision machining centers.
- REACH cadmium restrictions:Decorative glaze manufacturers must reformulate lead-free and cadmium-free chemistries, creating qualification windows for compliant glass ceramic suppliers.
- 5G infrastructure buildouts:Telecommunications OEMs require multilayer ceramic capacitors with thermal expansion coefficients below 0.5 ppm/K for base station reliability.
Market Restraints
- Specialized nucleating agents:PFAS-based fluorinated chemistries face regulatory phase-out under evolving per- and polyfluoroalkyl substance restrictions, threatening decades-old process formulations.
- Precision ceramics cluster concentration:Bavaria and Baden-Württemberg host disproportionate crystallization expertise, creating geographic supply risk for automotive and electronics OEMs.
- Zirconia substitution:High-strength dental zirconia competes for posterior crown applications where fracture toughness requirements exceed glass ceramic limits.
Strategic Opportunities
- Aerospace turbine qualification:JIS R 1607 fracture toughness certification opens qualification pathways for glass ceramic hot-section components in Japan.
- Energy-efficient crystallization:Microwave-assisted nucleation reduces furnace cycle times and aligns with EU Green Deal decarbonization mandates.
- Fire-rated glazing retrofit:Commercial building codes in Germany and France mandate upgraded thermal barrier performance, expanding renovation demand.
Industry Challenges
- Crystallization process engineering talent:The specialized knowledge required for controlled nucleation of lithium aluminosilicate phases remains concentrated among retiring technical specialists.
- Dual certification timelines:Medical implant qualification under both FDA 510(k) and EU MDR pathways extends time-to-revenue for dental prosthetics manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Ceramics Market |
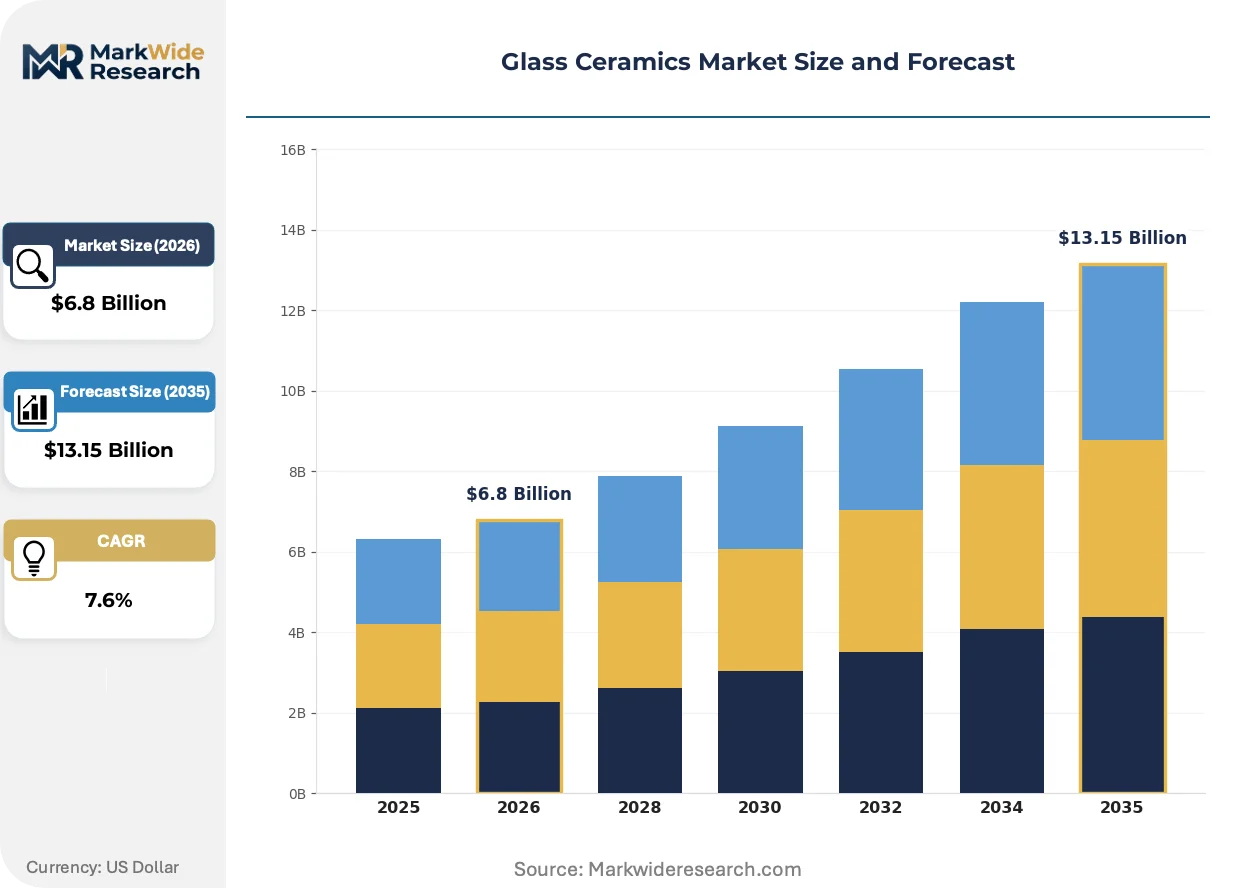
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Ceramics, Dental Ceramics, Cookware, Glass-Ceramic Tiles End Use Industry: Healthcare, Construction, Electronics, Automotive Form: Solid, Powder, Granules, Sheet Technology: Glass Transition, Sintering, Controlled Cooling, Crystallization |
| Companies Covered | Corning Incorporated, Schott AG, Nippon Electric Glass Co., Ltd., Saint-Gobain, Kyocera Corporation, CoorsTek Inc., Morgan Advanced Materials plc, AGC Inc., Kedi Glass-Ceramic Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Ceramics Market Emerging Trajectories
Digital process control and regulatory chemistry reformulation are converging to compress development cycles while elevating performance specifications across precision applications.
Machine vision-guided crystallization monitoring is digitizing quality assurance in nucleation furnace operations. Automotive electronics suppliers in Germany are adopting real-time thermal profile analytics to eliminate batch-to-batch variation. This sensor integration is digitizing the pathway to zero-defect electro-ceramic substrates for electric vehicle power modules.
EPA National Emission Standards for Hazardous Air Pollutants now mandate silica capture systems above threshold furnace capacities. Glass ceramics producers face retrofit capex or facility consolidation decisions. The dental prosthetics segment is responding by qualifying low-emission nucleating agent alternatives ahead of anticipated PFAS restrictions.
Consolidated procurement by dental service organizations is compressing supplier margins and favoring vertically integrated CAD/CAM material-library providers. Chairside milling equipment vendors now bundle lithium disilicate blanks with software subscriptions, displacing independent ceramic distributors. This concentration is most visible in United States group practice networks where single-source agreements cover multiple clinic locations.
Glass Ceramics Market Segmentation
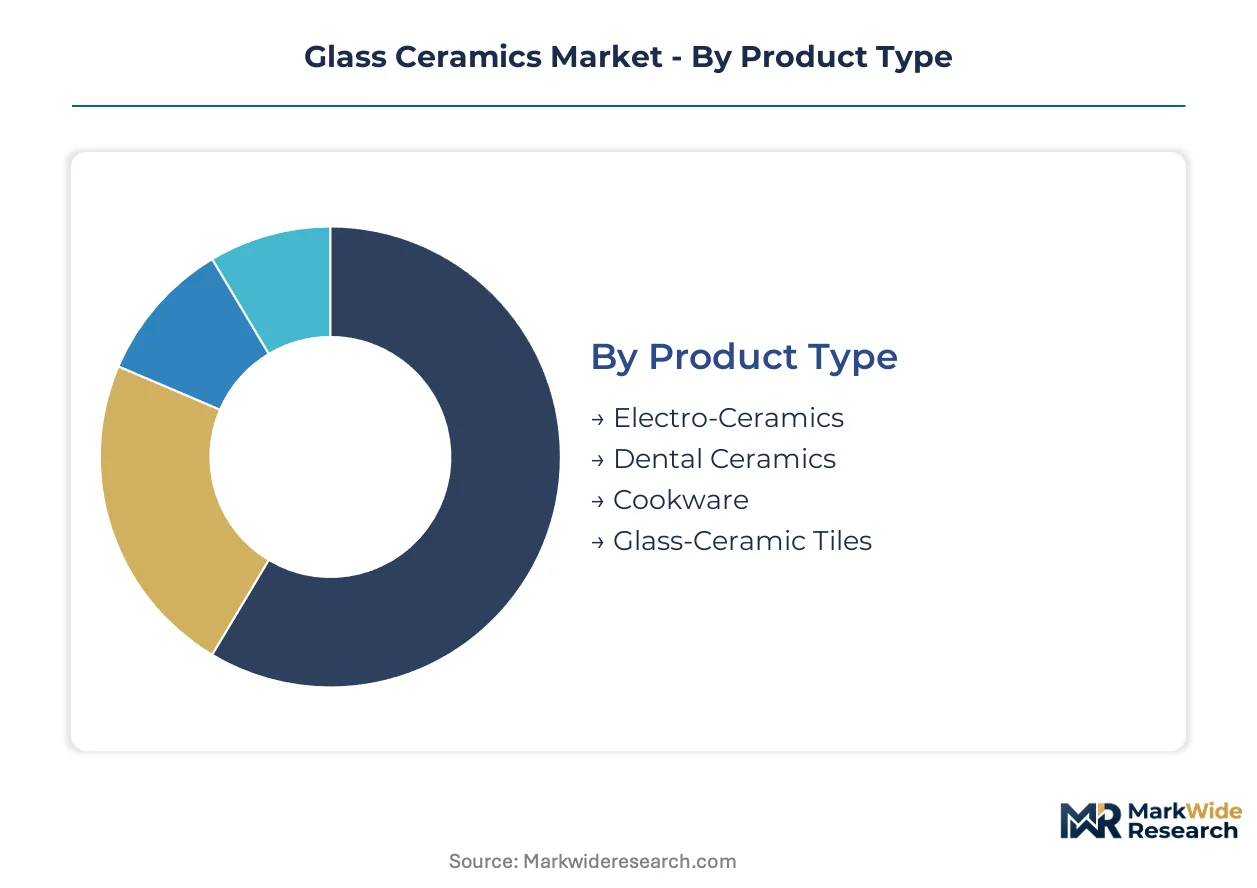
Glass ceramics manufacturers navigate distinct demand rhythms across product categories, with electro-ceramic substrates cycling monthly against decade-long building envelope specifications. Understanding these temporal patterns separates inventory-optimized suppliers from those carrying stranded working capital.
Product Type:
Cycle times compress from furnace batch production of cookware blanks to just-in-time dental block deliveries for chairside milling systems.
- Electro-Ceramics:Multilayer ceramic capacitors and substrate materials with thermal expansion coefficients below 0.5 ppm/K anchor telecommunications and automotive electronics supply chains. Base station OEMs in Germany and Japan qualify suppliers on JIS R 1607 fracture toughness protocols, locking in multi-year procurement agreements.
- Dental Ceramics:Lithium disilicate blanks for CAD/CAM chairside milling displace metal-ceramic restorations in North American and Western European clinics. Dental service organizations consolidate procurement through single-source agreements, compressing margins for independent ceramic distributors.
- Cookware:Thermal shock-resistant formulations from Schott AG's Zerodur line serve premium consumer markets.
- Glass-Ceramic Tiles:Fire-rated glazing products meet German and French commercial building code upgrades for thermal barrier retrofits.
Electro-ceramics anchors the volume base while dental ceramics gains share at the steepest rate.
End Use Industry:
Margin profiles diverge sharply between price-sensitive construction glazing and qualification-intensive medical implant pathways.
- Healthcare:Dental prosthetics and orthopedic implants demand dual FDA 510(k) and EU MDR certification timelines that extend time-to-revenue. Lithium disilicate crowns for posterior restorations compete against zirconia substitution where fracture toughness requirements exceed glass ceramic limits.
- Electronics:5G infrastructure buildouts pull multilayer ceramic capacitors with exacting thermal stability specifications. Telecommunications OEMs require zero-defect electro-ceramic substrates for base station reliability across temperature swings.
- Construction:Fire-rated glazing retrofits respond to German and French commercial building code mandates.
- Automotive:Electric vehicle power modules drive real-time thermal profile analytics adoption among German electronics suppliers.
Electronics commands the highest margin tier while healthcare shows the steepest expansion trajectory.
Form:
Processing economics favor near-net-shape solid forms over powder feedstocks that carry nucleating agent handling complexity.
- Solid:Near-net-shape blanks for dental CAD/CAM milling and precision electro-ceramic substrates minimize post-processing waste. Corning Incorporated leverages fusion draw expertise to dominate high-performance substrate markets with controlled dimensional stability.
- Powder:Spray-dried precursors for pressurized sintering operations in aerospace turbine component qualification.
- Granules:Feedstock for controlled crystallization furnace batch processing of cookware and architectural glazing.
- Sheet:Large-format fire-rated glazing for commercial building envelope retrofits in Germany.
Solid forms dominate value capture while powder feedstocks expand most quickly in aerospace qualification pathways.
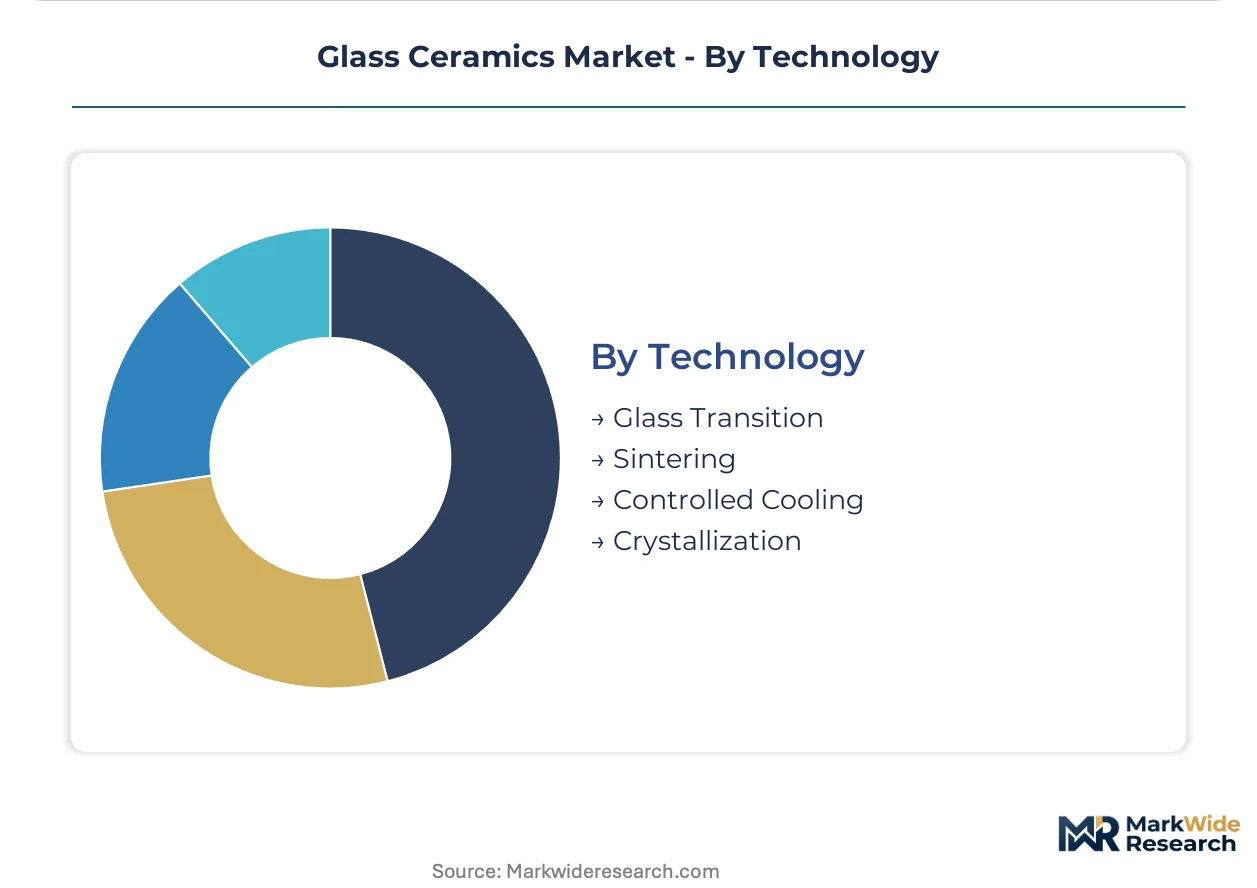
Technology:
Energy intensity separates electric melting adoption from gas-fired legacy systems facing EU Green Deal compliance deadlines.
- Crystallization:Controlled nucleation of lithium aluminosilicate or magnesium aluminosilicate phases yields polycrystalline solids with sub-0.5 ppm/K thermal expansion. Microwave-assisted nucleation reduces furnace cycle times and aligns with EU Green Deal decarbonization mandates.
- Sintering:Densification of glass-ceramic powders for structural components under JIS R 1607 fracture toughness standards.
- Glass Transition:Precursor formation for subsequent controlled nucleation sequences.
- Controlled Cooling:Thermal profile management to prevent residual stress accumulation in large-format glazing.
Crystallization anchors the installed base while microwave-assisted variants climb the fastest on energy efficiency advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision glass ceramics to automotive electronics suppliers across the European Union, while Japan supplies fracture-toughness-qualified substrates to aerospace turbine manufacturers in North America and Asia.
Germany
Automotive OEMs in Stuttgart and Munich demand thermal-shock-resistant substrates for electric vehicle power modules. The EU Green Deal forces crystallization furnace operators toward electric melting systems by 2030. Bavaria and Baden-Württemberg host precision ceramics clusters serving Bosch and Continental with zero-defect electro-ceramic supply chains.
Japan
Telecommunications infrastructure buildouts pull multilayer ceramic capacitors from domestic substrate manufacturers. METI enforces JIS R 1607 fracture toughness standards that determine aerospace component qualification. The Chubu region around Nagoya anchors crystallization expertise for turbine hot-section applications.
United States
Dental service organizations consolidate procurement of lithium disilicate blanks for chairside CAD/CAM milling. The EPA regulates silica emissions from glass ceramics furnaces under National Emission Standards for Hazardous Air Pollutants. Greater Boston hosts medical device qualification specialists navigating dual FDA 510(k) and EU MDR pathways.
China
Domestic 5G base station deployment accelerates demand for low-thermal-expansion electro-ceramic substrates. MIIT promotes indigenous crystallization technology development through state-backed industrial funds. The Yangtze River Delta concentrates glass-ceramic tile production for fire-rated commercial glazing retrofits.
France
Commercial building codes mandate upgraded thermal barrier performance in Paris and Lyon office stock. ECHA REACH restrictions on cadmium and lead content in decorative glazes force chemistry reformulation. The Auvergne-Rhône-Alpes region supplies fire-rated glazing for German and Benelux renovation markets.
Glass Ceramics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct margin tiers. Consolidation concentrates among furnace operators with proprietary nucleation chemistries, while fragmentation persists in dental blank distribution. Three archetypes dominate: integrated materials-software bundlers, precision substrate specialists, and regional glaze formulators. M&A activity targets CAD/CAM library providers, and capacity expansion focuses on microwave-assisted crystallization lines.
Among Japanese electro-ceramic specialists, Kyocera Corporation and Nippon Electric Glass Co., Ltd. exemplify the precision substrate archetype with multi-year telecommunications procurement locks. Corning Incorporated occupies a position among channel-controlling players leveraging fusion draw expertise. Schott AG represents the thermal-shock-resistant formulation tier through proprietary Zerodur chemistry control.
| Leading Market Players |
|---|
| Corning Incorporated |
| Schott AG |
| Nippon Electric Glass Co., Ltd. |
| Saint-Gobain |
| Kyocera Corporation |
| CoorsTek Inc. |
| Morgan Advanced Materials plc |
| AGC Inc. |
| Kedi Glass-Ceramic Industrial Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Rhine-Alpine Corridor freight rates from Rotterdam to Basel transmit crystallization furnace energy costs into lithium disilicate blank pricing across German dental supply chains. This logistics artery concentrates nucleating agent procurement leverage among Bavarian electro-ceramic producers while forcing French glaze formulators into cost-plus pass-through structures.
Pricing Analysis
Cost-plus contracts indexed to EU ETS carbon allowance prices dominate electro-ceramic substrate procurement between German automotive OEMs and precision ceramics clusters. Price differentiation separates JIS R 1607-certified aerospace grades from standard construction glazing tiers. Cost compression in dental blanks intensifies because dental service organizations consolidate procurement through single-source agreements. Chairside milling equipment vendors show the least price sensitivity; independent ceramic distributors face the most margin erosion.
Supply Chain Analysis
Upstream lithium carbonate feedstock draws from Chilean and Australian brine operations before conversion at Chinese refineries. High-purity silica sand rests on Bavarian and Baden-Württemberg deposits for nucleating agent production. Single-source vulnerability concentrates in fluorinated chemistry suppliers facing REACH phase-out timelines. Distribution runs through vertically integrated CAD/CAM library providers bundling material blanks with software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass ceramics markets reward service-attach models where software-enabled thermal profile analytics subscriptions outpace hardware revenue growth among automotive electronics suppliers.
For Market Incumbents: Harden crystallization process engineering capabilities against retiring specialist attrition through structured knowledge-capture programs and microwave-assisted furnace technology deployment. Secure captive supply of PFAS-free nucleating agent alternatives ahead of ECHA restrictions. Deepen backward integration into lithium carbonate refining to defend margin position against upstream volatility. For New Entrants and Emerging Players: Establish a beachhead in fire-rated glazing retrofit markets serving German and French commercial building code mandates. Target dental CAD/CAM material library gaps where independent distributors have been displaced by bundled equipment vendors. Lead with energy-efficient microwave crystallization technology as a differentiated sustainability narrative. For Investors and Strategic Acquirers: Proprietary nucleating agent chemistry specialists with microwave furnace integration capabilities present the most defensible acquisition profile across the analysis window. Monitor EU ETS carbon price trajectories as the inflection indicator for electric melting system retrofit capex cycles and consequent supply base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Carbonate | Captive supply secures margin insulation against Chilean-Australian brine price volatility. |
| Microwave-Assisted Crystallization Deployment | EU Green Deal alignment accelerates qualification timelines with Stuttgart automotive OEMs. |
| CAD/CAM Software Companion Development | Recurring revenue layers attach to chairside milling hardware in United States dental networks. |
| JIS R 1607 Certification Investment | Aerospace turbine component qualification opens procurement locks with Nagoya manufacturers. |
| PFAS-Free Nucleating Agent Reformulation | REACH compliance ahead of phase-out deadlines captures decorative glaze market share. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings from electro-ceramic substrate manufacturers, and METI industrial statistics preceded structured interviews with crystallization furnace operators, dental prosthetics procurement managers at group practice networks, and automotive Tier 1 supplier quality engineers. Bottom-up volume modeling across product type, end-use industry, and technology segments was cross-validated against top-down GDP elasticity approaches for industrial ceramics.
Assumptions held fixed include EU Green Deal emissions compliance deadlines and JIS R 1607 fracture toughness standards; variables included carbon allowance price trajectories and PFAS regulatory phase-out velocity. Modeled segmentation dimensions span product category, application vertical, thermal expansion coefficient tier, and regional production cluster. CAGRs were derived from installed base replacement cycles and emerging application penetration curves, with explicit inputs from 5G base station deployment schedules and dental clinic CAD/CAM adoption rates.
Sensitivities concentrate around ECHA PFAS restriction timing and EU ETS price volatility affecting electric melting system economics. Forecasts reflect documented assumptions regarding crystallization furnace energy intensity improvements and nucleating agent chemistry transitions. Cross-checking against Japanese industrial ceramics production surveys and German electrical engineering association order intake data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Diatomite Market
Ceramics
Global Ceramic Tube Market
Ceramics
Wollastonite Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Calcium Oxide Market
Ceramics
Calcined Kaolin Market
Ceramics
Cerium Nitride Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
White Fused Alumina Market
Ceramics
Ceramic Kilns Market
Ceramics
US Kaolin Market
Ceramics
Titanates Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
South Korea Ceramic Sanitaryware Market