
 Global Pseudo Boehmite Market | 2026-2036
Global Pseudo Boehmite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pseudo Boehmite Market Foresight
Buyer concentration among catalyst manufacturers is repositioning procurement leverage toward integrated chemical conglomerates seeking long-term supply security. Sasol leverages its Fischer-Tropsch catalyst heritage to sustain premium positioning in high-purity grades. Nabaltec anchors European supply through its flame retardant specialization, while UOP (Honeywell) competes via technology leadership in refinery catalyst formulations.
Pseudo boehmite is an aluminum oxyhydroxide with a poorly crystalline structure, typically synthesized via controlled precipitation of aluminum salts to achieve specific surface areas between 250-450 m²/g and pore volumes tailored for catalytic applications. Its primary industrial purpose centers on serving as a precursor for gamma-alumina catalyst supports and as a functional additive in flame retardant polymer systems. High Purity grades command the dominant value share due to stringent refinery catalyst specifications, while Modified Surface variants represent the fastest-expanding segment as electronics manufacturers seek tailored particle interfaces for advanced ceramic substrates. Catalyst Carrier applications retain the largest volume position, though Polymer Filler demand is accelerating from automotive lightweighting mandates.
China's SAMR enforces GB standards governing chemical purity thresholds that directly shape export eligibility for domestic producers like CHALCO Shandong Advanced Material. The EU REACH regulation and ECHA substance evaluations restrict residual impurity profiles, compelling reformulation investments among Asian suppliers targeting European coatings and adhesives markets. Stakeholders must monitor evolving dual carbon goals from China's MEE, as carbon intensity benchmarks for alumina-derived chemicals threaten to reshape production economics and regional sourcing patterns.
Market Dynamics
Refinery catalyst manufacturers are consolidating procurement around integrated alumina suppliers capable of certifying to tightening GB standards and REACH purity thresholds, compressing margins for standalone precipitated alumina producers.
Growth Catalysts
- Hydroprocessing unit upgrades:Petrochemical refiners in the US Gulf Coast and Rotterdam-Antwerp corridor are retrofitting hydrotreating reactors, expanding demand for high-surface-area catalyst carriers.
- REACH compliance investments:European coatings formulators are reformulating adhesive systems to meet ECHA substance evaluations, creating certified supply slots for compliant pseudo boehmite grades.
- Flame retardant polymer mandates:Automotive lightweighting regulations in Germany and Japan are accelerating halogen-free filler adoption in underhood components and interior panels.
Market Restraints
- Alumina hydrate input volatility:Bauxite refining capacity concentration in Shandong Province and Guinea exposes producers to freight and energy cost swings.
- Gamma-alumina substitution:Spray-dried alumina gels from captive refinery operations are displacing merchant pseudo boehmite in some catalyst support applications.
- REACH authorization timelines:ECHA's substance evaluation backlog delays market entry for modified surface variants targeting European electronics substrates.
Strategic Opportunities
- India specialty chemicals expansion:BIS certification pathways for high-purity grades remain underpenetrated as domestic catalyst manufacturers scale hydrotreater investments.
- Solid-state battery ceramic substrates:Modified surface pseudo boehmite is integrating with lithium-ion separator coatings, opening volume positions outside traditional petrochemical demand.
- China dual carbon alignment:MEE carbon intensity benchmarks for alumina-derived chemicals favor producers with integrated renewable power and carbon capture retrofits.
Industry Challenges
- Precipitation process control expertise:Narrow pH and temperature windows for achieving target pore distributions require experienced chemical engineers, constraining capacity expansion.
- Multi-jurisdiction certification synchronization:Simultaneous GB standard, REACH, and FDA catalyst contact approvals stretch quality assurance timelines for export-focused producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pseudo Boehmite Market |
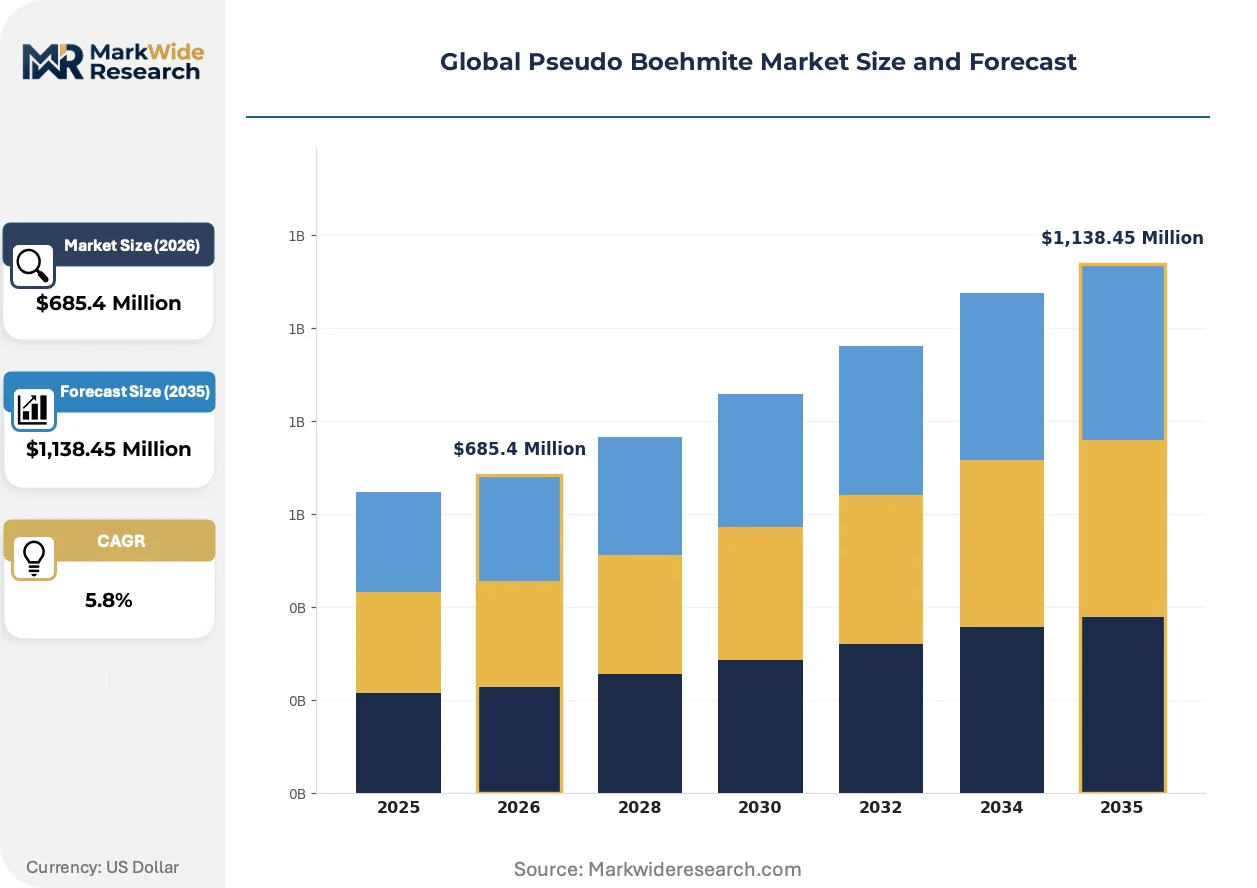
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Ultra Fine, Standard Grade, Modified Surface, Aluminous, Reactive Application: Catalyst Carrier, Adsorbent, Flame Retardant, Coating Agent, Ceramics, Polymer Filler End User Industry: Chemicals, Electronics Manufacturing, Construction Materials, Automotive Suppliers, Packaging Industry, Adhesives Packaging Type: Bag, Drum, Bulk Container, Box, Cartridge, Tote |
| Companies Covered | CHALCO Shandong Advanced Material, Taimei Chemicals, Nabaltec, Sasol, UOP (Honeywell), Zibo Yinghe Chemical, Zibo Honghe Chemical, KNT Group, ESTONE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pseudo Boehmite Market Shifts & Advancements
Continuous precipitation control systems and surface functionalization chemistry are compressing batch-to-batch variability while enabling particle architectures tailored to emerging solid-state battery and advanced ceramic applications.
Controlled hydrothermal synthesis is integrating real-time particle size monitoring with automated pH adjustment loops. German catalyst manufacturers are adopting these systems to reduce surface area deviation from 15% to under 5% across production lots. This precision is compressing qualification timelines for refinery catalyst supports from 18 months to under 12 months.
EU REACH substance evaluations are restricting residual sodium and silica thresholds in grades destined for cosmetics and food-contact applications. Formulators in the Netherlands and France are demanding certificates of analysis traceable to specific precipitation batches. Suppliers are responding by segregating production lines and implementing blockchain-based chain-of-custody documentation.
Long-term offtake agreements with fixed-price escalators are displacing spot market transactions for high-purity grades. Catalyst manufacturers in Texas and Louisiana are locking in five-year supply contracts with integrated alumina producers to secure volume against Shandong supply disruptions. This contractual shift is most visible in hydroprocessing catalyst supply chains serving US Gulf Coast refiners.
Global Pseudo Boehmite Market Segmentation
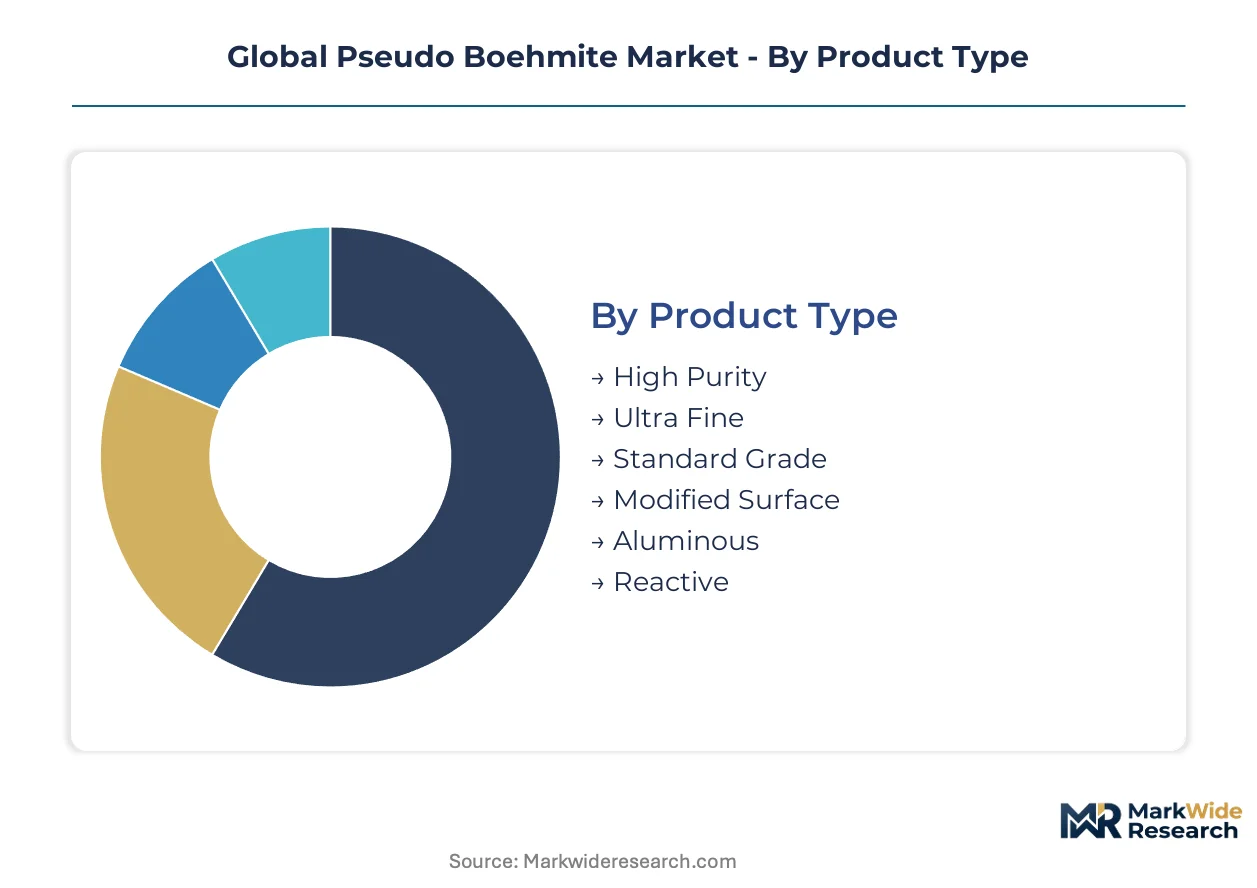
Segmentation in pseudo boehmite reveals how technical specifications align with divergent value pools across catalyst manufacturing, polymer compounding, and advanced ceramics. Product purity tiers and surface modification capabilities separate commodity alumina suppliers from specialty chemical producers commanding formulation partnerships.
Product Type:
Supply concentration among integrated alumina producers in Shandong Province and Rotterdam-Antwerp corridor dictates which purity grades achieve scale economics.
- High Purity:Aluminum oxyhydroxide with controlled residual sodium below 500 ppm and surface areas of 300-450 m²/g. Refinery catalyst manufacturers in Texas and Louisiana concentrate procurement here, driven by hydroprocessing unit upgrades requiring certified lot-to-lot consistency.
- Modified Surface:Functionalized particle interfaces via silane or phosphate treatments enabling tailored zeta potentials. Electronics manufacturers in South Korea and Japan are expanding offtake for solid-state battery ceramic substrates and lithium-ion separator coatings.
- Ultra Fine:Sub-micron particle distributions below 1 μm median diameter for precision coating applications.
- Standard Grade:General-purpose precipitated alumina for industrial adsorbent and bulk ceramic applications.
- Aluminous:Elevated Al₂O₃ content variants for high-temperature refractory binders.
- Reactive:Enhanced dissolution kinetics for rapid gelation in specialty catalyst preparations.
High Purity absorbs the bulk of installed capacity; Modified Surface is expanding most quickly.
Application:
Cost tier differentiation separates specification-grade formulations from commodity alumina hydrates in downstream value capture.
- Catalyst Carrier:Gamma-alumina precursor supports for hydrotreating, hydrocracking, and Fischer-Tropsch synthesis. US Gulf Coast refiners and Rotterdam-Antwerp petrochemical complexes anchor demand, constrained by REACH authorization timelines for new surface variants.
- Flame Retardant:Halogen-free filler synergies with phosphorus compounds in polyamide and polypropylene systems. Automotive suppliers in Germany and Japan are reformulating underhood components to meet lightweighting mandates and fire safety codes.
- Adsorbent:Desiccant and purification media for industrial gas and liquid streams.
- Coating Agent:Binder and rheology modifier for paper, textile, and architectural finishes.
- Ceramics:Structural and functional ceramic green body processing.
- Polymer Filler:Mechanical property enhancement in thermoset and thermoplastic compounds.
Catalyst Carrier commands the highest volume position; Flame Retardant is climbing the fastest as automotive electrification accelerates thermal management requirements.
End User Industry:
Customer type fragmentation across process industries, consumer goods, and advanced manufacturing shapes certification and packaging requirements.
- Chemicals:Catalyst manufacturers and specialty alumina derivative producers requiring REACH-compliant documentation and batch traceability.
- Automotive Suppliers:Tier-1 and tier-2 polymer compounders serving OEM thermal management and interior specifications.
- Electronics Manufacturing:Battery cell producers and ceramic substrate fabricators demanding ultra-low metallic impurity profiles.
- Construction Materials:Refractory and cementitious binder applications.
- Packaging Industry:Barrier coating and moisture control formulations.
- Adhesives:Rheology modification and adhesion promotion in industrial bonding systems.
Chemicals absorbs the bulk of procurement volume; Electronics Manufacturing is gaining share fastest on solid-state battery commercialization timelines.
Packaging Type:
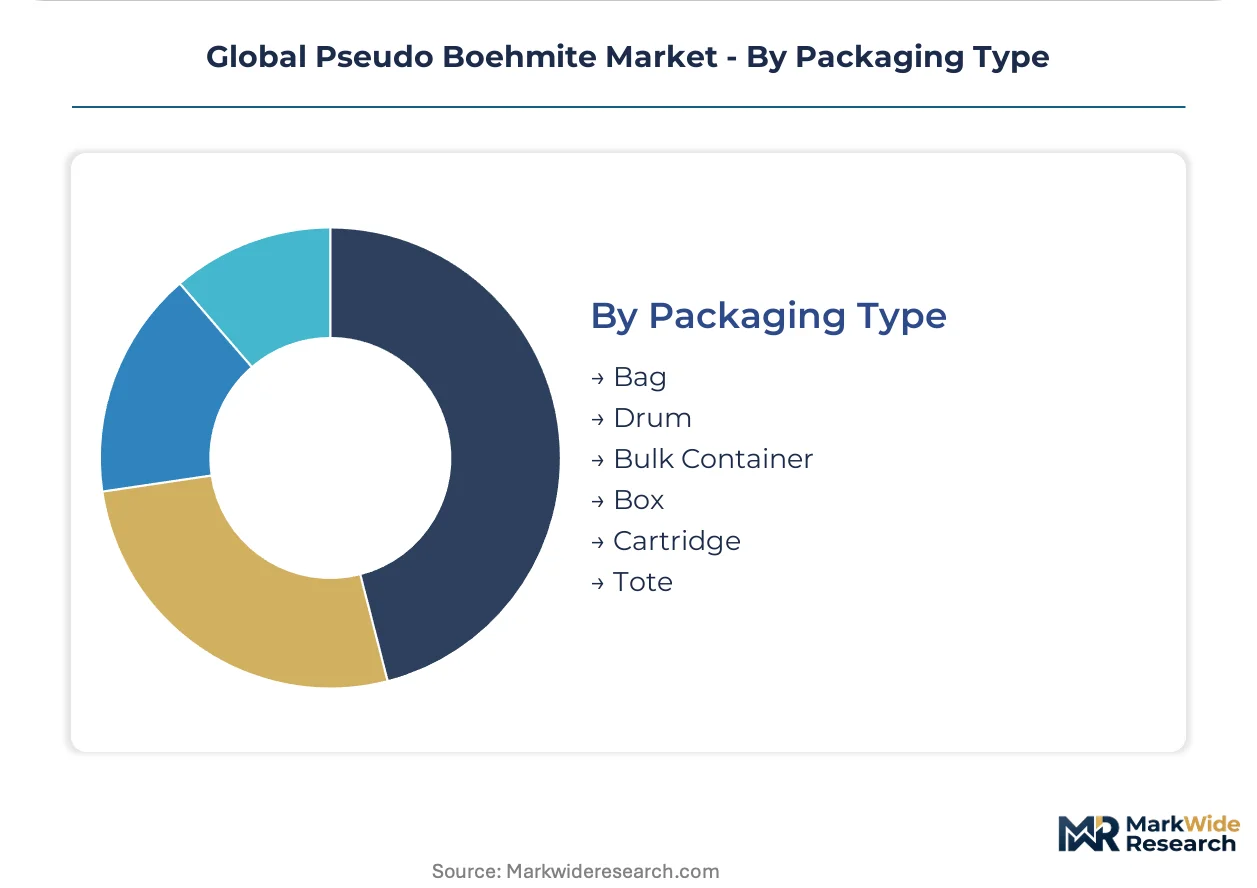
Volume and handling requirements diverge between bulk chemical distributors and precision formulation facilities.
- Bulk Container:Intermediate bulk containers and silo truck deliveries for integrated catalyst plants and polymer compounders.
- Drum:Steel and fiber drums for mid-volume specialty chemical distributors.
- Bag:Multi-wall paper and woven polypropylene for standard grade construction and adsorbent applications.
- Tote:Cubic intermediate bulk containers for liquid dispersion and slurry formulations.
- Box:Corrugated containment for laboratory and pilot-scale shipments.
- Cartridge:Precision-dispense packaging for automated coating and adhesive lines.
Bulk Container handles the majority of tonnage; Tote formats are expanding most quickly in electronics and coatings formulation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite refining clusters in Shandong Province and Guinea anchor feedstock availability for pseudo boehmite production. Refinery catalyst demand concentrates near petrochemical corridors in Texas, Louisiana, and Rotterdam-Antwerp. Regulatory divergence across GB standards, REACH, and emerging BIS pathways fragments certification requirements.
United States
Hydroprocessing unit upgrades along the US Gulf Coast drive procurement of high-purity catalyst carriers. EPA emissions standards for refinery operations tighten specifications for hydrotreating catalyst supports. Houston-area chemical plants are locking in long-term supply contracts with integrated alumina producers to secure volume against import volatility.
China
Shandong Province's integrated alumina-to-pseudo boehmite operations serve domestic catalyst manufacturers and export markets. SAMR enforces GB standards governing chemical purity thresholds that shape export eligibility for producers like CHALCO Shandong Advanced Material. The Yangtze River Delta electronics manufacturing cluster is expanding offtake for modified surface grades in lithium-ion separator coatings.
Germany
Automotive lightweighting mandates accelerate halogen-free flame retardant filler adoption in underhood components. ECHA REACH substance evaluations restrict residual sodium and silica thresholds in grades destined for cosmetics and food-contact applications. The Ruhr industrial corridor hosts reformulation investments by coatings formulators seeking compliant supply slots.
Japan
Solid-state battery ceramic substrate development creates demand for tailored particle interfaces in lithium-ion separator coatings. METI industrial standards govern purity specifications for electronics-grade alumina derivatives. The Kansai region's battery cell producers are qualifying modified surface pseudo boehmite for next-generation separator applications.
India
Domestic catalyst manufacturers scale hydrotreater investments to serve refinery expansion projects. BIS certification pathways for high-purity grades remain underpenetrated relative to procurement volumes. The Gujarat chemical manufacturing cluster is attracting specialty alumina producers seeking to localize supply for petrochemical catalyst operations.
Global Pseudo Boehmite Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics-grade surface modification capabilities. The vendor base stratifies across integrated alumina conglomerates, specialty chemical specialists, and catalyst technology licensors. Three archetypes dominate: backward-integrated bauxite refiners, formulation-technology licensors, and regional precipitated alumina specialists. Competitive intensity centers on long-term offtake contracting and multi-jurisdiction certification synchronization.
Within the integrated conglomerate tier, CHALCO Shandong Advanced Material and Sasol exemplify scale-driven positions anchored to captive feedstock security. Nabaltec occupies a European specialty niche, while UOP (Honeywell) represents the technology-licensor archetype competing via refinery catalyst formulation partnerships. Zibo Yinghe Chemical and Zibo Honghe Chemical sit within Shandong's dense supplier cluster, reflecting regional concentration dynamics. Taimei Chemicals, KNT Group, and ESTONE populate the mid-scale specialist segment where precipitation process control expertise constrains rapid expansion.
| Leading Market Players |
|---|
| CHALCO Shandong Advanced Material |
| Taimei Chemicals |
| Nabaltec |
| Sasol |
| UOP (Honeywell) |
| Zibo Yinghe Chemical |
| Zibo Honghe Chemical |
| KNT Group |
| ESTONE |
| Others |
Supply & Pricing Matrix
High Purity certification tiers create a bifurcation between REACH-compliant premium grades and standard industrial offerings, with this divergence manifesting in both contract structures and the geographic locus of production assets. Buyers qualifying for European coatings and refinery catalyst applications pay substantial premiums for batch-traceable documentation, while commodity grades compete on freight-adjusted delivered costs from Shandong Province's integrated operations.
Pricing Analysis
Long-term offtake agreements with fixed-price escalators bundle technical certification support and dedicated quality assurance teams, unbundling these services from spot-market transactions that carry no warranty coverage. Three-tier pricing structure across premium, standard, and economy levels separates REACH-authorized grades from GB-certified export variants and undifferentiated construction-grade material. Pricing pressure stems from gamma-alumina gel substitution in captive refinery operations, compressing merchant pseudo boehmite margins. Catalyst manufacturers demonstrate lowest price sensitivity due to qualification timeline investments, while construction materials buyers prioritize delivered cost above certification tier.
Supply Chain Analysis
Experienced chemical engineers with precipitation process control expertise concentrate in Shandong Province's alumina corridor and Germany's Ruhr industrial cluster, constraining rapid capacity scaling elsewhere. Bauxite refining capacity draws from Guinea and Shandong Province, with sodium aluminate and aluminum sulfate feedstocks sourced from integrated chlor-alkali operations. Single-source vulnerability runs through Shandong's dense supplier cluster, where energy cost swings and SAMR enforcement actions disrupt export availability. Distribution runs through intermediate bulk container deliveries to integrated catalyst plants and silo truck shipments for polymer compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precipitation process control expertise acts as the binding capacity constraint, propping pricing for qualified producers while excluding rapid entrant scaling. This supply-constrained structure favors incumbents with captive technical workforces and backward-integrated feedstock positions.
For Market Incumbents: Acquire precipitation process control expertise through targeted hiring from German catalyst manufacturers and Shandong's established operations. Defensive moves center on locking five-year supply contracts with US Gulf Coast refiners before hydrotreater upgrade cycles peak, and securing renewable power purchase agreements to meet MEE carbon intensity benchmarks. Gamma-alumina gel substitution from captive refinery operations threatens merchant volume; counter by deepening formulation partnerships with UOP and Sasol technology licensors. For New Entrants and Emerging Players: BIS certification pathways in India open a window for localized supply to domestic catalyst manufacturers scaling hydrotreater investments. White-space targets include solid-state battery ceramic substrates for South Korean electronics manufacturers and halogen-free flame retardant fillers for Japanese automotive suppliers. A go-to-market angle emphasizing REACH pre-certification and blockchain-based batch traceability bypasses the 18-month qualification timeline that protects established suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialists possessing precipitation process control expertise given solid-state battery commercialization timelines. Long-term viability favors producers with integrated renewable power and carbon capture retrofit capabilities aligned to China's dual carbon goals. The acquisition target archetype combines Shandong-based production assets with European REACH authorization. Watch ECHA substance evaluation backlog resolution as the inflection indicator for modified surface grade market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Captive alumina hydrate supply from Guinea operations insulates against Shandong energy cost volatility. |
| REACH Authorization Investment | Pre-certified production lines unlock European coatings and electronics substrate markets ahead of competitors. |
| Long-term Supply Agreement | Five-year contracts with Texas and Louisiana refiners secure volume against gamma-alumina substitution. |
| Green Manufacturing Transition | Renewable power and carbon capture retrofits align with MEE carbon intensity benchmarks for alumina-derived chemicals. |
| Joint Venture with Battery Cell Producer | Co-development of modified surface grades for lithium-ion separator coatings accelerates solid-state battery qualification. |
Research Methodology
Multi-period observation of hydroprocessing unit upgrade cycles, REACH authorization timelines, and SAMR enforcement patterns anchored the trend analysis, supplemented by interviews with plant managers at integrated alumina operations, procurement leads at catalyst manufacturers, technical R&D directors in flame retardant polymer systems, and distribution channel partners serving European coatings formulators. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical conglomerates, ECHA substance evaluation databases, and GB standards documentation from SAMR. Bottom-up capacity assessments across Shandong Province's supplier cluster triangulated against top-down demand modeling from refinery catalyst and automotive polymer compounding end-uses.
Segment-weighting applied grade tier differentiation between High Purity, Modified Surface, and Standard Grade variants, cross-referenced with end-use industry fragmentation across chemicals, automotive suppliers, and electronics manufacturing, plus regional production hub concentration in Shandong Province and the Rotterdam-Antwerp corridor. CAGRs were derived from installed capacity expansion announcements, qualification timeline compression effects, and substitution elasticity estimates for gamma-alumina gels. Industry-specific inputs included MEE carbon intensity benchmark trajectories and ECHA substance evaluation backlog resolution assumptions.
The model assumes a particular technology adoption path for solid-state battery ceramic substrates; alternative pathways for lithium-metal anode architectures would alter the outlook for modified surface grade demand. Forecasts reflect assumptions regarding REACH authorization timeline resolution, SAMR enforcement consistency, and hydroprocessing unit upgrade cycle pacing. Material deviation in bauxite supply disruptions, ECHA regulatory acceleration, or solid-state battery commercialization delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Mullite Market
Ceramics
Calcium Silicate Boards Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Europe Activated Alumina Market
Ceramics
Calcined Kaolin Market
Ceramics
Global Functional Ceramics Market
Ceramics
Automotive Ceramics Market
Ceramics
Wollastonite Market
Ceramics
Quartz Powder Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
Advanced Ceramic Additives Market