
 Saudi Arabia Ceramic Tiles Market | 2026-2036
Saudi Arabia Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Ceramic Tiles Market Analytics
Saudi Arabia is tilting toward domestic ceramic tile capacity expansion as Vision 2030 infrastructure spending accelerates. RAK Ceramics Saudi Arabia leverages integrated manufacturing from raw material processing through fired finished goods. Saudi Ceramic Company anchors its position through extensive distribution across the kingdom's construction corridors. Alfanar Ceramics specializes in high-volume porcelain production serving contractor-direct channels.
Ceramic tiles are thin, flat slabs formed from clay, silica, and fluxes, fired at temperatures between 1000°C and 1400°C to achieve hardness, water resistance, and dimensional stability; they serve primarily as protective and decorative surfacing for floors and walls in built environments. Porcelain tiles command premium positioning due to lower water absorption rates below 0.5 percent, making them dominant in commercial flooring applications where durability requirements intensify. Glazed tiles capture broad residential demand through aesthetic versatility and cost accessibility across Riyadh and Jeddah housing developments. Wholesale distributors remain the principal channel, though direct sales to construction companies are gaining share as project scale increases.
The Saudi Building Code and SFDA standards govern material emissions and surface safety, while SASO quality marks regulate import access and local manufacturing compliance. These frameworks elevate compliance costs for smaller producers while rewarding scaled manufacturers with certified laboratory testing and documented supply chain traceability. Stakeholders must monitor evolving green building mandates and local content requirements that will reshape supplier qualification criteria and procurement specifications across upcoming megaproject tenders.
Market Dynamics
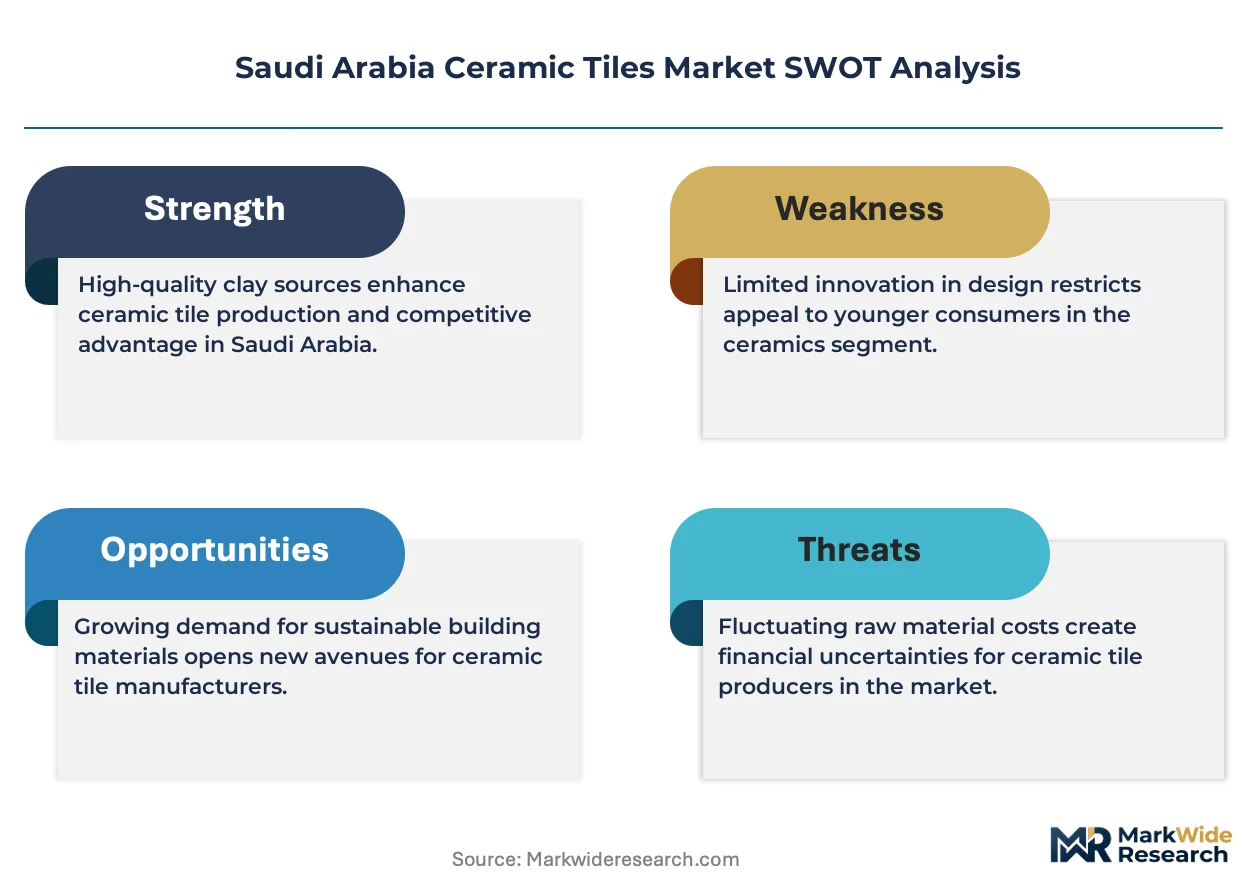
Vision 2030 infrastructure spending is compressing procurement cycles as megaproject developers consolidate supplier rosters around certified domestic manufacturers with integrated production capabilities and documented SASO compliance.
Growth Catalysts
- Central Province construction corridor:Riyadh's megaproject pipeline generates concentrated demand for porcelain and glazed tile volumes, pulling capacity expansion from Jeddah-based distributors.
- Saudi Building Code enforcement:Tightened material safety standards elevate certified manufacturers above import-dependent competitors in public tender qualifications.
- Dry-pressed porcelain technology:Lower water absorption specifications below 0.5 percent enable specification in high-traffic commercial flooring across airport and hospital developments.
Market Restraints
- Feldspar and kaolin import dependence:Raw material sourcing concentrates in limited supplier geographies, exposing margins to shipping cost volatility and currency fluctuation.
- Natural gas price sensitivity:Kiln firing operations consume substantial energy volumes, making production economics vulnerable to domestic utility tariff adjustments.
- SFDA certification timelines:Extended laboratory testing protocols for surface emissions and slip resistance delay product launch schedules for new formulations.
Strategic Opportunities
- Eastern Province industrial zone expansion:Jubail and Dammam construction activity remains underserved by current distribution networks anchored in Riyadh and Jeddah.
- NEOM giga-project specification:Sustainability mandates in this development create entry paths for low-carbon ceramic production with renewable energy integration.
- Direct contractor channels:Large-scale developers are consolidating procurement away from wholesale distributors toward manufacturer-direct relationships with volume commitments.
Industry Challenges
- Glaze chemistry specialization:Formulation expertise for high-durability commercial applications remains concentrated among a limited technical workforce, constraining product line expansion.
- SASO quality mark documentation:Supply chain traceability requirements demand upgraded ERP systems and batch-level tracking infrastructure that smaller producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Ceramic Tiles Market |
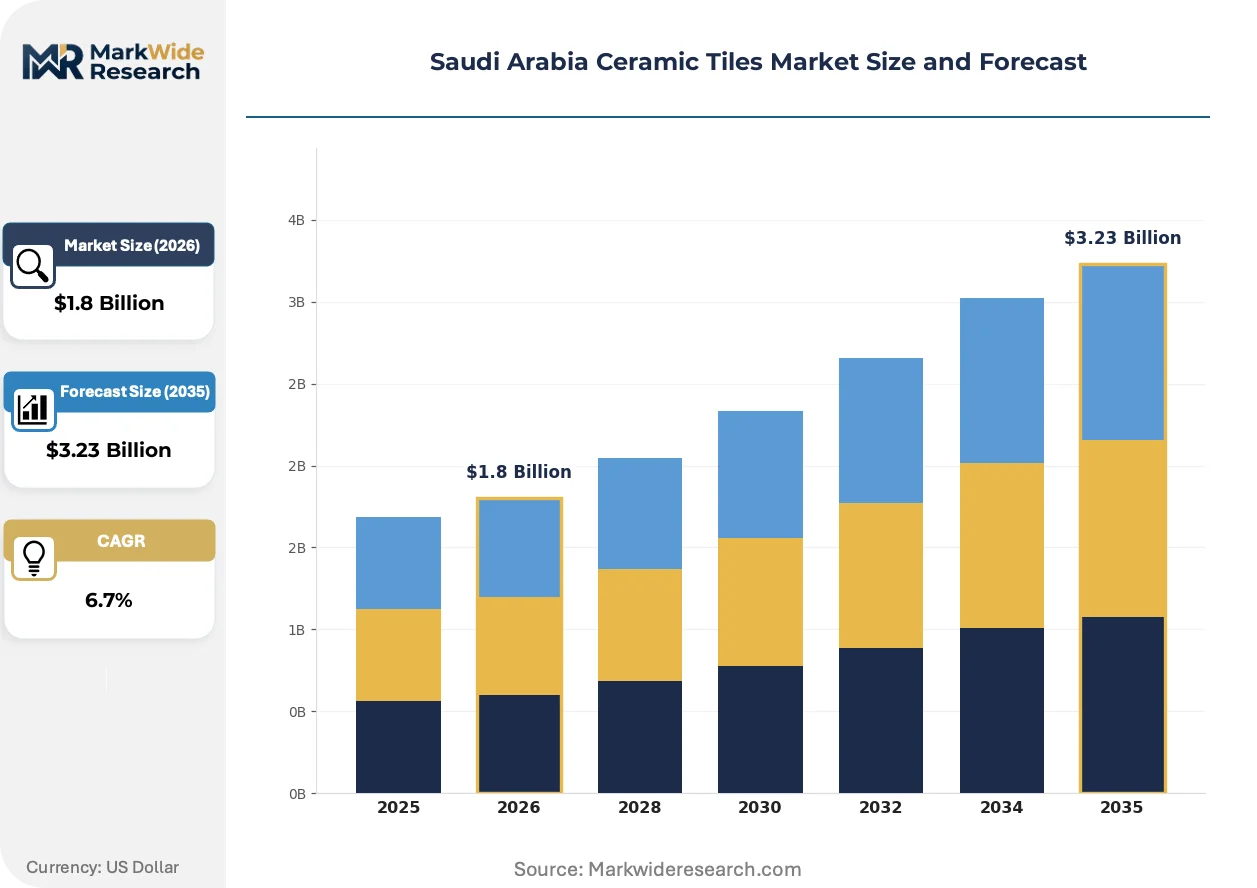
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Vitreous Tiles, Porcelain Tiles Application: Residential Flooring, Commercial Flooring, Wall Covering, Outdoor Paving Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores End User: Construction Companies, Contractors, Homeowners, Architects |
| Companies Covered | RAK Ceramics Saudi Arabia, Al Jawdah Ceramics, Exa, Riyadh Ceramics, Arabian Ceramics Manufacturing Company, Saudi Ceramic Company, Future Ceramics, Forsan Ceramics, Alfanar Ceramics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Ceramic Tiles Market Evolving Landscape
Digital inkjet decoration and large-format pressing technologies are redefining aesthetic possibilities and installation economics across Saudi residential and commercial specifications.
Digital inkjet printing is migrating from accent and decorative niche applications toward full-surface replication of natural stone and wood grain textures. High-end residential developers in Riyadh's northern districts specify these finishes for premium villa developments, compressing the price gap between ceramic and natural material alternatives. The technology is enabling shorter production runs and reduced inventory carrying costs for manufacturers serving fragmented design preferences.
SASO quality mark requirements now mandate third-party laboratory verification for all imported ceramic tile shipments, with random sampling protocols at Jeddah and Dammam port facilities. Local manufacturers with in-house testing capabilities accelerate market access while import-dependent distributors face extended customs clearance periods. Commercial project specifications increasingly exclude products lacking documented Saudi-origin certification.
Developer procurement teams now consolidate annual tile volumes through framework agreements with single-source manufacturers rather than project-by-project spot purchasing. This concentration displaces traditional wholesale distributor intermediaries in contracts above defined threshold values. The pattern is most visible in Riyadh's Diriyah Gate and Qiddiya entertainment district developments where master developers negotiate direct supply relationships.
Saudi Arabia Ceramic Tiles Market Segmentation
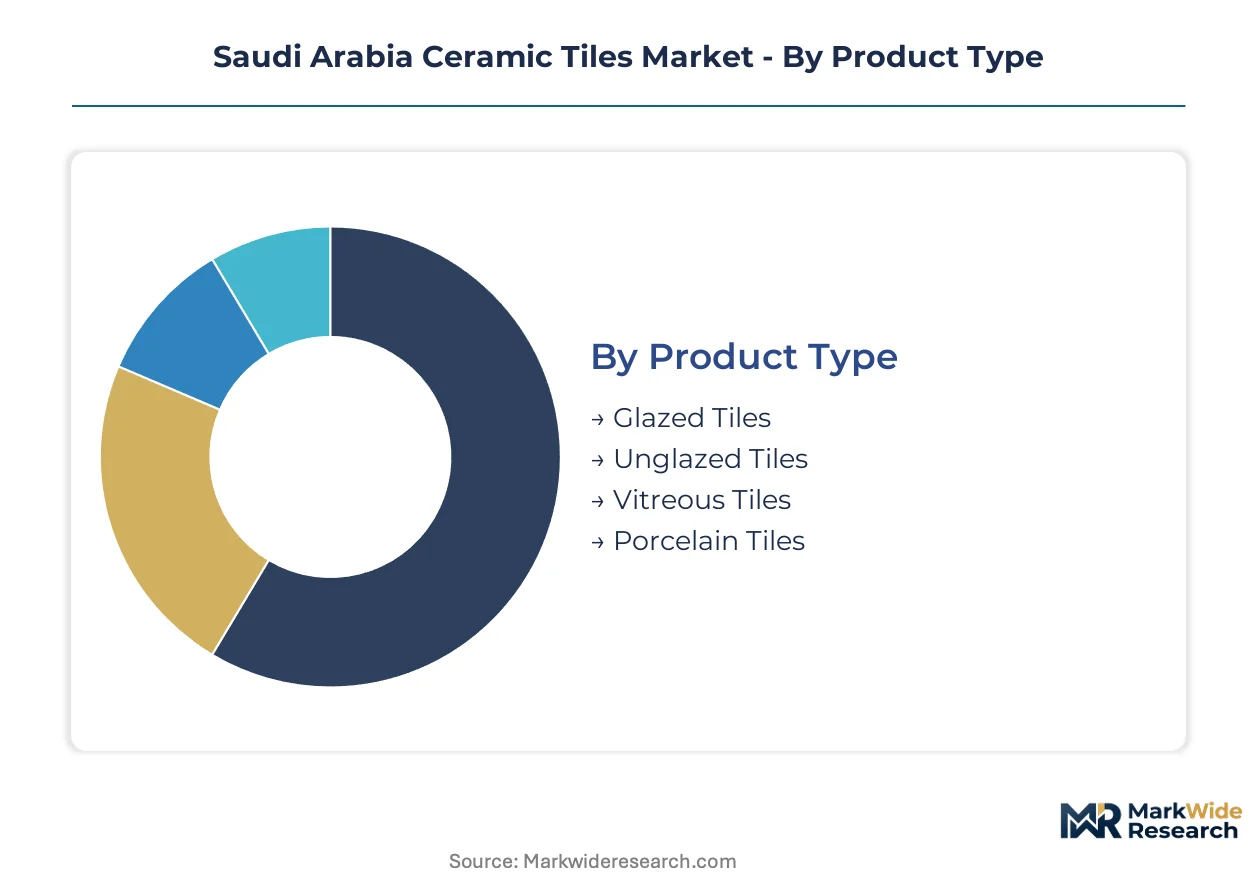
Product formulation, application environment, and procurement channel each dictate distinct margin structures and compliance requirements in Saudi Arabia's ceramic tiles market. Specification patterns across Vision 2030 megaprojects are compressing traditional segment boundaries as developers consolidate supplier relationships.
Product Type:
Cost tier stratification separates commodity-grade surfacing from premium specifications demanded by Riyadh's commercial developments.
- Porcelain Tiles:Fired at temperatures exceeding 1200°C, these achieve water absorption below 0.5 percent through vitrified clay body formation. Airport terminals and hospital complexes across Riyadh specify porcelain for high-traffic flooring where durability requirements intensify and maintenance cost minimization drives procurement decisions.
- Glazed Tiles:Surface glass coating applied post-firing creates aesthetic versatility across color and texture ranges. Residential villa developments in Jeddah's northern districts absorb substantial glazed volumes where cost accessibility and design flexibility outweigh performance specifications.
- Unglazed Tiles:Natural clay surface without protective coating serves outdoor paving and industrial applications where slip resistance prioritizes over visual refinement.
- Vitreous Tiles:Intermediate water absorption between 0.5 and 3 percent occupies the commercial wall covering segment where moisture resistance requirements are moderate.
Porcelain holds installed capacity. Glazed is rotating up the share rankings.
Application:
Volume concentration tracks construction phase sequencing across residential and commercial verticals.
- Commercial Flooring:Heavy-duty porcelain specifications dominate airport, hospital, and retail developments where traffic loads and cleaning chemical exposure demand superior abrasion resistance. Diriyah Gate and Qiddiya master developers mandate commercial-grade materials with documented SASO certification for warranty compliance.
- Residential Flooring:Glazed ceramic captures villa and apartment developments across Riyadh's northern districts and Jeddah's expanding suburbs. Developer procurement teams specify mid-range products balancing cost control with surface durability for owner-occupier resale value.
- Wall Covering:Lighter-weight ceramic and vitreous tiles serve vertical surfacing in bathrooms, kitchens, and commercial lobbies where structural load limits and moisture exposure dictate material selection.
- Outdoor Paving:Unglazed and textured surfaces address slip resistance requirements for pool decks, walkways, and plaza installations across NEOM and Red Sea Project coastal developments.
Commercial flooring commands specification authority. Residential flooring is climbing the fastest.
Distribution Channel:
Customer type and project scale determine channel selection with direct procurement displacing traditional intermediaries.
- Direct Sales:Manufacturer-to-developer relationships consolidate annual volumes through framework agreements. Riyadh-based megaproject master developers negotiate direct supply contracts above threshold values, eliminating wholesale distributor margins.
- Wholesale Distributors:Fragmented project volumes and regional construction companies continue sourcing through Jeddah and Riyadh-based distributors with established logistics networks and credit facilities.
- Specialty Stores:Retail showrooms serve homeowner renovation and architect specification sampling with curated product ranges and design consultation services.
- Online Retail:Digital platforms capture small-volume residential replacement demand with limited penetration in commercial specification channels.
Direct sales holds installed capacity. Wholesale distributors are rotating up the share rankings.
End User:
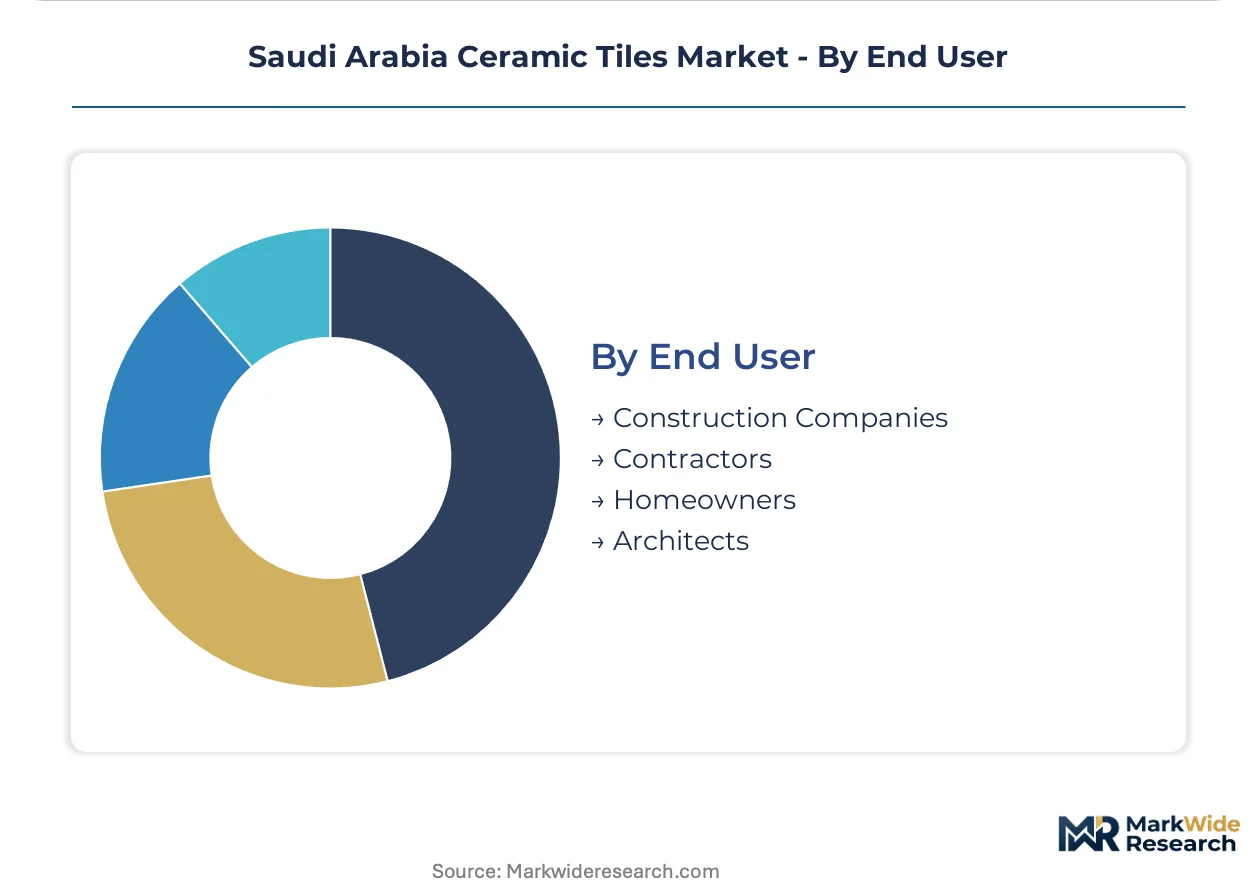
Procurement authority concentrates with construction companies consolidating material specifications across project portfolios.
- Construction Companies:Tier-one developers with multi-project pipelines negotiate manufacturer-direct relationships with volume commitments and certified supply chain documentation. Saudi Building Code compliance requirements elevate preferred supplier status for SASO-certified manufacturers.
- Contractors:Subcontractor procurement of specified materials maintains distributor channel dependence where project scale falls below direct negotiation thresholds.
- Architects:Specification influence precedes procurement execution, with design firms in Riyadh and Jeddah selecting products for developer approval based on aesthetic and performance criteria.
- Homeowners:Individual renovation demand fragments across retail and online channels with limited price leverage and specification authority.
Construction companies hold installed capacity. Architects are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA certification requirements and SASO quality marks anchor Saudi Arabia's regulatory framework for ceramic tile manufacturing and import compliance across the kingdom's construction corridors.
Riyadh
Riyadh's megaproject pipeline including Diriyah Gate and Qiddiya generates concentrated demand for porcelain and glazed tile volumes. The Saudi Building Code mandates SASO-certified materials for all public infrastructure tenders. Northern district villa developments specify premium digital inkjet finishes from Riyadh-based distribution networks.
Eastern Province
Jubail and Dammam industrial construction activity remains underserved by current distribution networks anchored in Riyadh and Jeddah. The Eastern Province municipality enforces local content requirements for government-backed developments. Dammam port facilities handle feldspar and kaolin raw material imports for regional manufacturers.
Western Region
Jeddah residential developments absorb substantial glazed ceramic volumes where cost accessibility outweighs performance specifications. Red Sea Project coastal developments specify unglazed textured surfaces for outdoor paving applications. Jeddah-based wholesale distributors maintain established logistics networks serving fragmented regional construction companies.
NEOM Northwest
NEOM giga-project sustainability mandates create entry paths for low-carbon ceramic production with renewable energy integration. The NEOM development authority specifies documented supply chain traceability for all building materials. Trojena and The Line construction phases consolidate procurement through framework agreements with certified manufacturers.
Saudi Arabia Ceramic Tiles Market Competitive Landscape
Capability concentration sits with integrated domestic manufacturers possessing in-house testing laboratories; scale advantage sits with distributors leveraging established logistics networks across the kingdom's construction corridors. The market structures around three tiers: vertically integrated producers with captive raw material processing, wholesale distributors with credit facilities and regional coverage, and project-direct specialists serving megaproject developers. Dominant competitive moves include capacity expansion in Riyadh and Jeddah production zones, and strategic partnerships between manufacturers and master developers for framework supply agreements.
Within the integrated manufacturing tier, RAK Ceramics Saudi Arabia and Saudi Ceramic Company represent archetypes of domestic capacity with documented SASO compliance and distribution reach across construction corridors. Alfanar Ceramics occupies a position among specialized porcelain producers serving contractor-direct channels with volume commitments.
| Leading Market Players |
|---|
| RAK Ceramics Saudi Arabia |
| Al Jawdah Ceramics |
| Exa |
| Riyadh Ceramics |
| Arabian Ceramics Manufacturing Company |
| Saudi Ceramic Company |
| Future Ceramics |
| Forsan Ceramics |
| Alfanar Ceramics |
| Others |
Value Network & Pricing Analysis
Feldspar import dependence from Turkey and India compresses margin structures across all three pricing tiers while simultaneously forcing inventory positioning decisions that elongate working capital cycles for distributors serving Riyadh's megaproject corridor.
Pricing Analysis
Riyadh commands premium positioning over Jeddah and Dammam by SAR 8-12 per square meter for equivalent SASO-certified porcelain specifications. Three-tier pricing structure across premium, standard, and economy levels separates Diriyah Gate framework suppliers from wholesale distributor spot purchases and import-dependent budget tier. Cost compression in the economy tier is intensifying because Eastern Province distributors are absorbing shipping cost volatility to defend market share. Small-scale contractors exhibit highest price sensitivity, while NEOM master developers prioritize documented supply chain traceability over unit cost.
Supply Chain Analysis
Tariff exposure between Saudi Arabia and Turkish ceramic exporters dominates raw material sourcing economics for feldspar and glaze chemistry inputs. Manufacturing draws from Turkey, India, and Spain for critical raw materials, with domestic kaolin deposits near Riyadh providing partial substitution. Single-source vulnerability concentrates in high-grade feldspar shipments through Jeddah Islamic Port. Distribution runs through Riyadh-based wholesale networks with established credit facilities, though direct manufacturer-to-developer channels are displacing intermediaries above volume thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO certification requirements create regulatory entrenchment that rewards incumbent manufacturers with in-house testing laboratories and documented batch-level traceability systems.
For Market Incumbents: Harden SASO quality mark documentation through ERP system upgrades that enable real-time batch tracking from raw material receipt through fired finished goods. Expand captive feldspar processing capacity to reduce Turkish import exposure. Defend against emerging UAE-based competitors by locking multi-year framework agreements with Diriyah Gate and Qiddiya master developers before NEOM procurement consolidation accelerates. For New Entrants and Emerging Players: Pursue Eastern Province industrial corridor penetration where Jubail and Dammam construction activity outruns current distribution network coverage. Target low-carbon ceramic production with renewable energy integration for NEOM sustainability-mandated tenders. Enter through specialty glaze chemistry partnerships with Riyadh-based technical workforce pools rather than head-to-head porcelain volume competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive raw material processing and established SASO laboratory infrastructure. Long-term viability hinges on regulatory compliance scalability rather than pure production volume. Acquisition targets should demonstrate framework agreement relationships with at least two megaproject master developers. Monitor NEOM procurement consolidation announcements as the critical inflection signal for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feldspar Processing | Captive raw material supply insulates margins from Turkish shipping cost volatility and currency fluctuation. |
| SASO Certification Laboratory Investment | In-house testing capabilities accelerate product launch timelines and customs clearance for import competitors. |
| NEOM Framework Agreement Negotiation | Direct supply relationships with NEOM development authority displace wholesale distributors in giga-project procurement. |
| Digital Inkjet Decoration Technology Deployment | High-resolution surface replication commands premium positioning in Riyadh northern district villa developments. |
| Eastern Province Distribution Network Expansion | Jubail and Dammam industrial construction corridors remain underserved by Riyadh-Jeddah anchored logistics. |
Research Methodology
Desk research of customs trade databases, SASO certification registries, and Saudi Building Code technical bulletins preceded structured interviews with ceramic plant operations directors, megaproject procurement managers, wholesale distributor principals, and glaze chemistry formulation specialists. Primary fieldwork combined facility visits to Riyadh and Jeddah production zones with telephone interviews covering Eastern Province market participants. Secondary validation drew from Saudi Ports Authority throughput statistics, Ministry of Industry mineral extraction reports, and developer tender documentation. Bottom-up volume estimates from manufacturer capacity utilization triangulated against top-down construction spending allocation models.
Assumptions held fixed across the modeling period include Vision 2030 megaproject execution timelines, SFDA surface safety standard enforcement intensity, and natural gas utility tariff structures. Segmentation dimensions modeled encompass product formulation tier, application environment, procurement channel type, and end-user authority concentration. CAGRs were derived from slope analysis of year-over-year volume progression adjusted for construction phase sequencing. Industry-specific forecast inputs incorporated kiln firing capacity expansion announcements and feldspar import shipment manifest patterns.
Sensitivities concentrate around Turkish lira volatility affecting feldspar landed costs, NEOM procurement consolidation velocity, and SFDA certification timeline extensions for new glaze formulations. Forecasts reflect documented assumptions regarding megaproject execution continuity and regulatory enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Ceramic Kilns Market
Ceramics
Global Alumina Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Ceramic Binders Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Lithium Silicate Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Ball Clay Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Porous Ceramic Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Nanoceramic Powder Market