
 Global Medical Imaging Reagents Market | 2026-2036
Global Medical Imaging Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Imaging Reagents Market Intelligence
Direct-to-hospital procurement channels for specialized reagents is narrowing the role of traditional third-party distributors. GE Healthcare leverages its installed base of imaging equipment to bundle reagent contracts. Bayer AG sustains market presence through its extensive portfolio of contrast agents for MRI and CT. Meanwhile, Siemens Healthineers differentiates with integrated diagnostic solutions combining hardware, software, and consumables.
Medical imaging reagents are chemical compounds administered to patients to enhance the visibility of internal body structures during diagnostic procedures. These substances, such as iodinated contrast media or gadolinium-based agents, alter the physical properties of tissues to improve image contrast. Contrast Agents represent the largest product type segment, driven by high-volume use in CT and MRI modalities. Radiopharmaceuticals for PET applications, particularly in tumor detection, are exhibiting the most significant expansion.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA dictates stringent clinical trial and manufacturing standards. These agencies' approval processes for new contrast agents and radiopharmaceuticals directly control market entry and product lifecycle. Future competitive positioning will depend on navigating evolving safety profiles for agents and developing tracers for personalized medicine applications.
Market Dynamics
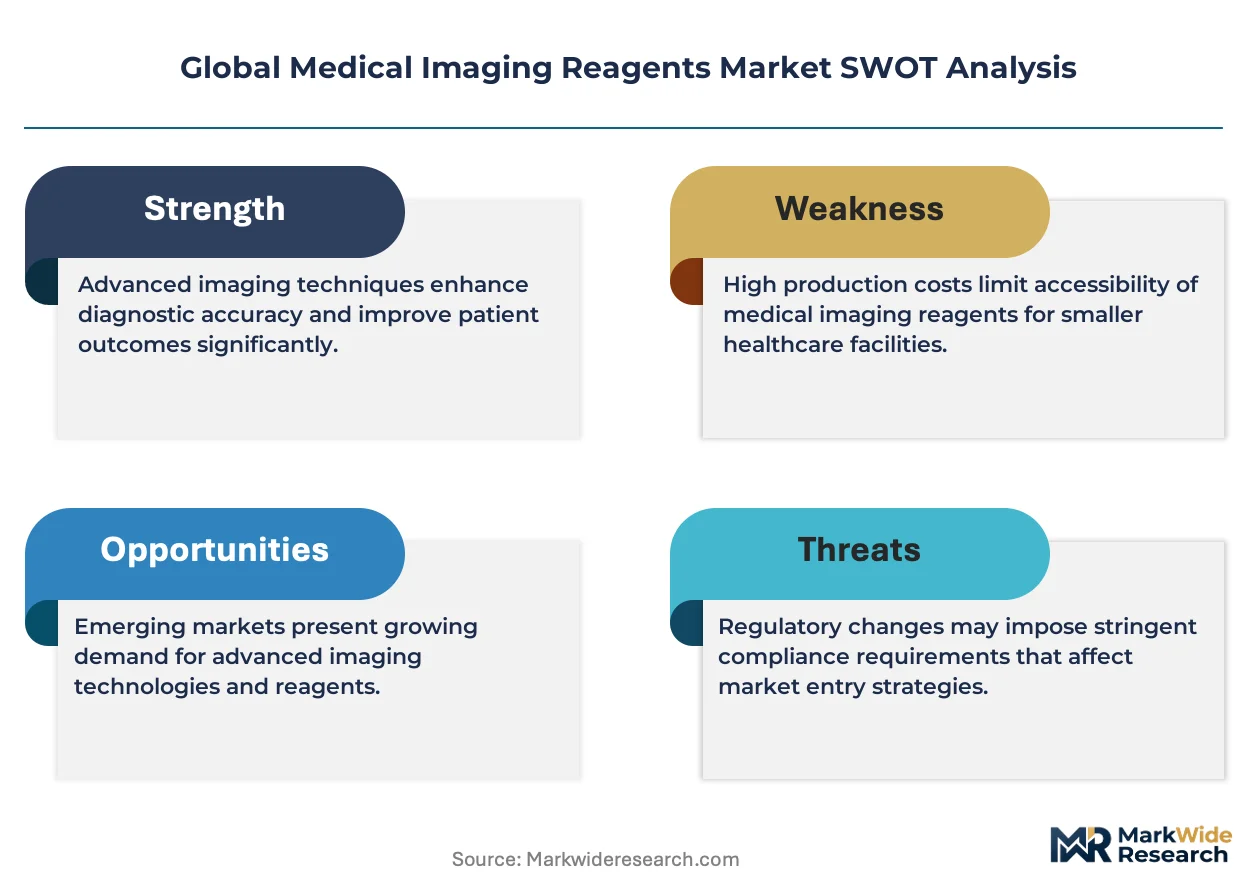
The central tension in the medical imaging reagents market is between the rapid innovation in targeted radiopharmaceuticals for personalized medicine and the increasingly stringent, multi-year regulatory pathways mandated by agencies like the FDA, EMA, and NMPA for new product approvals.
Growth Catalysts
- Targeted Radiopharmaceuticals:The development of novel PET tracers, particularly for oncology and neurology applications, provides highly specific diagnostic information, driving clinical adoption in advanced academic and research hospitals.
- Aging Demographics:Rising prevalence of chronic conditions such as cardiovascular disease and cancer in aging populations, especially in countries like Japan and Germany, increases the procedural volume of diagnostic imaging.
- Healthcare Infrastructure Modernization:Government-led initiatives in China and India to expand and upgrade diagnostic imaging capabilities are creating new demand for both contrast agents and radiopharmaceuticals.
Market Restraints
- Isotope Supply Volatility:The supply chain for key medical isotopes, such as Molybdenum-99 used for Technetium-99m generators, is concentrated and prone to disruptions, creating price and availability risks for radiopharmaceuticals.
- Regulatory Scrutiny:Heightened safety reviews of gadolinium-based contrast agents by both the FDA and EMA have led to restrictions on certain linear agents, prompting a shift toward macrocyclic agents and limiting their use.
- Alternative Imaging Techniques:Advancements in non-contrast MRI sequences and AI-powered image enhancement software can reduce or eliminate the need for contrast agents in certain diagnostic procedures, posing a substitution threat.
Strategic Opportunities
- Theranostic Agent Development:Combining diagnostic imaging with targeted radionuclide therapy creates a new class of theranostic agents, offering a pathway to personalized treatment in oncology and other disease areas.
- Emerging Market Expansion:Underpenetrated markets in Southeast Asia and Latin America represent significant growth areas as healthcare spending and access to advanced diagnostic modalities like CT and PET/CT increase.
- Molecular Imaging Applications:Developing novel tracers for non-oncology applications, such as assessing cardiac viability or neuroinflammation, opens new clinical segments beyond the traditional focus on tumor detection.
Industry Challenges
- Complex Manufacturing Compliance:Adhering to divergent and evolving Good Manufacturing Practice (GMP) standards for radiopharmaceuticals across the US, Europe, and China requires significant investment in quality control and regulatory affairs.
- Specialized Talent Scarcity:A shortage of trained radiochemists, nuclear medicine physicians, and technologists capable of handling and interpreting advanced imaging agents impedes the adoption of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Imaging Reagents Market |
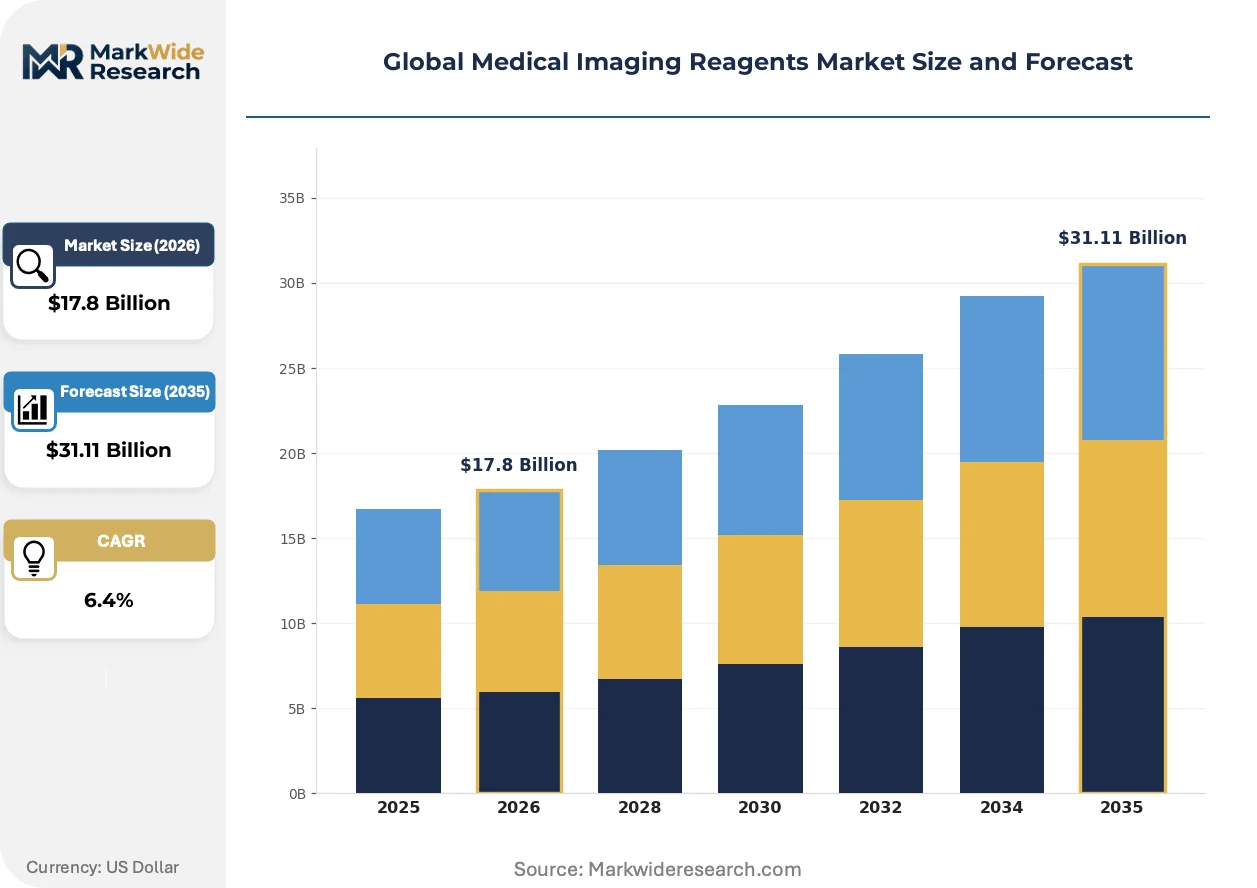
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contrast Agents, Radiopharmaceuticals, Fluorescent Dyes, Magnetic Nanoparticles Imaging Modality: MRI, CT, PET, Ultrasound, Optical Imaging End User: Diagnostic Laboratories, Research Institutes, Medical Clinics, Academic Hospitals Application: Cardiovascular Diagnosis, Tumor Detection, Neurological Assessment, Orthopedic Evaluation |
| Companies Covered | Bayer AG, Lantheus Medical Imaging, GE Healthcare, Mallinckrodt Pharmaceuticals, Guerbet Group, Siemens Healthineers, Bracco Imaging, Canon Medical Systems Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Imaging Reagents Market Strategic Shifts & Innovations
The convergence of biochemical innovation and data science is transforming imaging reagents from simple visibility enhancers into sophisticated tools for quantitative, personalized diagnostics. This shift is driven by advancements in tracer technology, stricter regulatory frameworks, and evolving hospital procurement models.
AI-powered image analysis software is a critical enabling technology for next-generation reagents. Radiology departments in large hospital systems are adopting these tools to interpret scans with greater precision. This technology is digitizing the diagnostic workflow, enabling the use of lower-dose reagent protocols and extracting more quantitative data, shifting the value of reagents from volume to informational yield.
Implementation of the European Union's Medical Device Regulation (MDR) is elevating requirements for clinical evidence and post-market surveillance. This regulation directly increases the cost and timeline for introducing new contrast agents and associated injection systems to the market. Manufacturers of established products must now invest in generating new data for recertification, impacting legacy portfolio strategies and R&D allocation.
A definitive shift toward bundled purchasing contracts is altering the supply chain. This model combines imaging capital equipment, multi-year service agreements, and reagent supply into a single contract with one vendor. Standalone third-party reagent distributors find their roles diminished, a trend most visible within large, integrated hospital networks across the United States and Western Europe.
Global Medical Imaging Reagents Market Segmentation
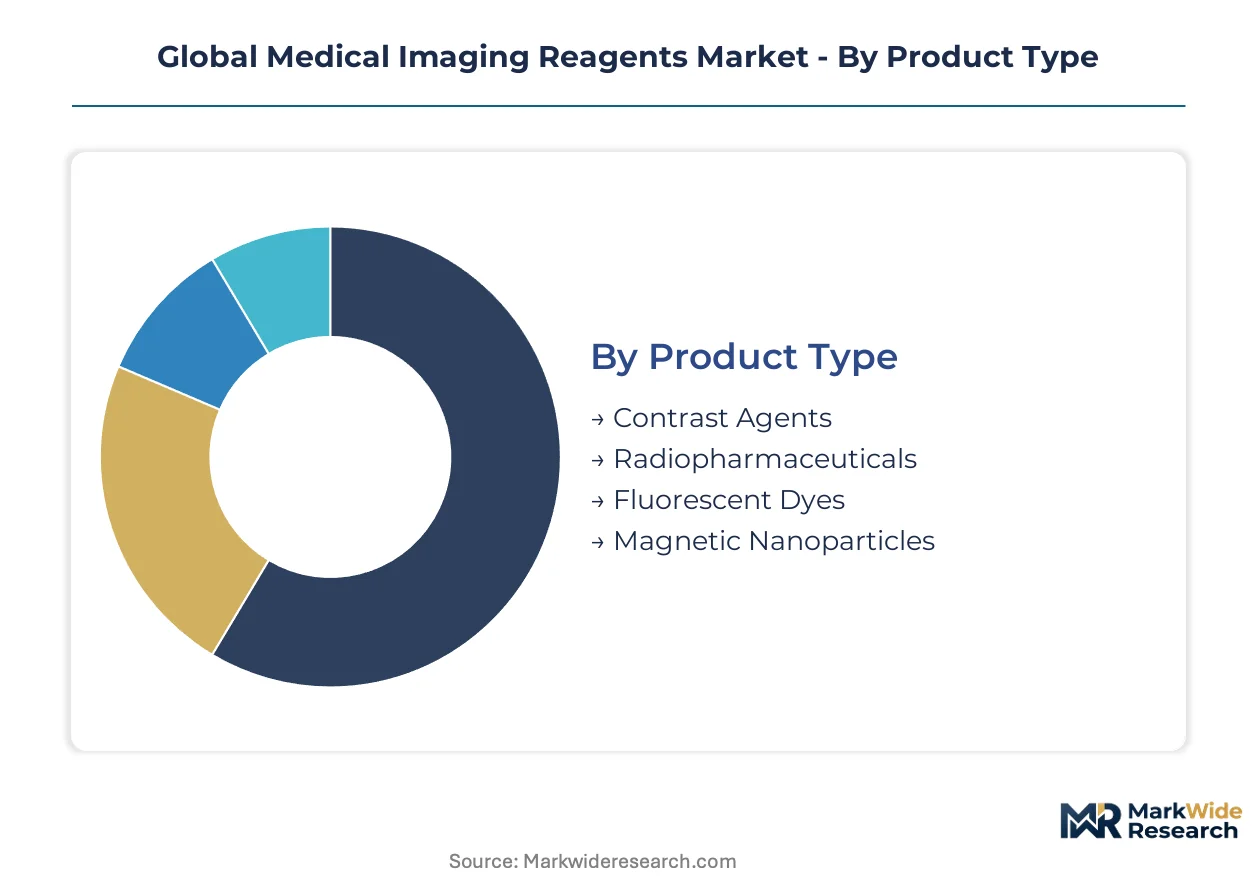
The medical imaging reagents market is delineated by key attributes that influence product development, adoption rates, and competitive strategies. Understanding these segmentations provides clarity on where demand concentrates and how technological advancements are shaping future growth trajectories.
Product Type:
The product type segmentation reveals a market balancing mature imaging reagents with emerging, highly specialized compounds.
- Contrast Agents:These chemical compounds, such as iodinated or gadolinium-based agents, enhance image contrast by altering tissue properties during CT and MRI scans. High-volume diagnostic procedures in cardiovascular and oncological imaging drive significant demand for these agents across global healthcare systems.
- Radiopharmaceuticals:Comprising radioactive isotopes linked to targeting molecules, these agents are primarily used in PET and SPECT imaging to visualize metabolic or molecular processes. Their utility in specific tumor detection and neurological assessment is driving substantial clinical adoption in advanced academic and research hospitals.
- Fluorescent Dyes:These agents emit light at specific wavelengths when excited, enabling real-time visualization in optical imaging techniques. Surgeons use fluorescent dyes for image-guided procedures and tissue demarcation.
- Magnetic Nanoparticles:Composed of iron oxide or other magnetic materials, these nanoparticles are being explored for enhanced MRI contrast and targeted drug delivery applications. Research institutes are actively investigating their potential for molecular imaging.
Contrast Agents handle the majority of diagnostic throughput; Radiopharmaceuticals are the fastest mover on share.
Imaging Modality:
Imaging modality segmentation highlights the procedural volume driven by established techniques and the specialized growth of advanced methods.
- CT:Computed Tomography imaging relies heavily on iodinated contrast agents to visualize blood vessels, soft tissues, and organs with high spatial resolution. Hospitals globally perform millions of CT scans annually, maintaining strong demand for these reagents.
- MRI:Magnetic Resonance Imaging frequently utilizes gadolinium-based contrast agents to improve the detection of tumors, inflammation, and vascular abnormalities. The versatility of MRI sequences contributes to its broad application across various clinical areas.
- PET:Positron Emission Tomography exclusively uses radiopharmaceuticals to detect metabolic activity and cellular function. Oncology and neurology departments frequently employ PET scans for disease staging and treatment monitoring.
- Ultrasound:While primarily a non-contrast modality, microbubble contrast agents enhance ultrasound imaging for cardiac, liver, and vascular assessments. Medical clinics use contrast-enhanced ultrasound for specific diagnostic challenges.
- Optical Imaging:This modality employs fluorescent dyes or probes to visualize biological processes at the cellular and molecular level. Research institutions and specialized surgical centers utilize optical imaging for preclinical studies and intraoperative guidance.
CT procedures currently dominate reagent consumption, while PET imaging is experiencing the steepest expansion trajectory.
End User:
The end-user classification delineates reagent consumption patterns across institutions with varying levels of specialization and patient volumes.
- Academic Hospitals:These institutions are major consumers of advanced imaging reagents, particularly targeted radiopharmaceuticals for complex tumor detection and neurological research. Their focus on clinical trials and specialized patient care drives high-value reagent procurement.
- Diagnostic Laboratories:Independent diagnostic laboratories perform a wide range of imaging procedures, consuming significant volumes of standard contrast agents for routine CT and MRI scans. Efficiency and cost-effectiveness are critical factors for these high-throughput facilities.
- Research Institutes:These entities primarily utilize novel imaging reagents and experimental tracers for preclinical studies and drug development. Their demand is driven by innovation in molecular imaging and theranostic agent research.
- Medical Clinics:Smaller medical clinics and outpatient centers use imaging reagents for routine diagnostic procedures, often focusing on common conditions. Their procurement prioritizes ease of use and broad applicability.
Academic Hospitals represent a significant portion of advanced reagent utilization, with Medical Clinics expanding their diagnostic capabilities.
Application:
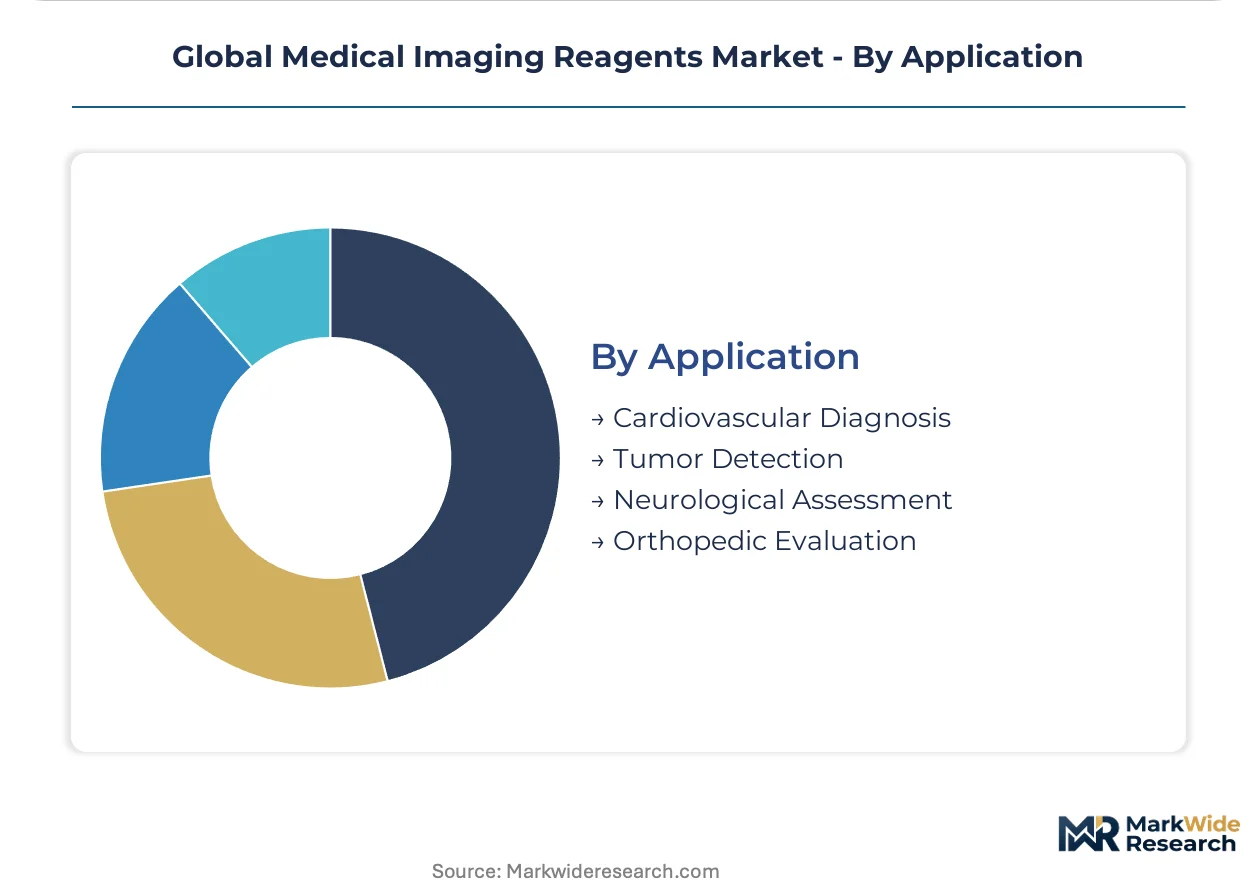
Application segmentation illustrates the clinical focus areas driving reagent development and diagnostic procedural growth.
- Tumor Detection:This application represents a primary driver for both contrast agents and radiopharmaceuticals, particularly for identifying, staging, and monitoring various cancers. Oncology departments in hospitals globally rely on these agents for precise diagnostic information.
- Neurological Assessment:Imaging reagents play a vital role in diagnosing conditions like Alzheimer's disease, Parkinson's disease, and brain tumors. Novel PET tracers are expanding capabilities for early detection and monitoring of neurodegenerative disorders.
- Cardiovascular Diagnosis:Contrast agents are essential for visualizing cardiac structures, blood flow, and assessing myocardial perfusion in conditions such as coronary artery disease. Cardiologists widely use these enhanced imaging techniques.
- Orthopedic Evaluation:Imaging reagents assist in the diagnosis of musculoskeletal injuries, inflammatory conditions, and bone tumors. MRI with contrast agents provides detailed insights into soft tissue and joint pathologies.
Tumor Detection applications drive substantial demand for targeted agents, while Neurological Assessment shows promising future growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for medical imaging reagents exhibits asymmetry, with established markets like the United States dictating premium pricing due to advanced healthcare systems. Conversely, emerging economies such as India prioritize cost-effectiveness and volume procurement. This dynamic influences market entry strategies and product portfolio development across global regions.
United States
The United States drives significant demand for novel PET tracers, particularly for oncology and neurology applications. The US FDA mandates rigorous clinical trial and manufacturing standards for new imaging agents. Research hubs like Boston's biotech corridor are central to developing advanced molecular imaging and theranostic agents.
Germany
Germany exhibits strong demand for contrast agents due to an aging population and high procedural volumes for chronic diseases. The European Medicines Agency (EMA) enforces strict regulatory pathways for new contrast agents and radiopharmaceuticals. Munich's advanced medical technology cluster drives innovation in integrated diagnostic solutions.
China
China's expanding diagnostic imaging capabilities create substantial demand for both contrast agents and radiopharmaceuticals. The NMPA implements stringent clinical trial and manufacturing standards for medical devices and reagents. Shanghai's burgeoning medical device industry cluster is a focal point for domestic imaging reagent development.
India
India's modernization of healthcare infrastructure fuels robust demand for medical imaging reagents. The CDSCO oversees the approval and quality control of medical devices and diagnostic agents in the country. Bengaluru's dynamic medical technology sector is attracting investments in advanced diagnostic imaging.
Japan
Japan's aging population and high prevalence of chronic diseases sustain significant demand for diagnostic imaging reagents. The PMDA rigorously assesses new medical imaging reagents for safety and effectiveness before market entry. Tokyo's prominent research institutions lead the development of novel PET tracers for neurology applications.
Global Medical Imaging Reagents Market Key Industry Players
Large diversified conglomerates and specialized imaging reagent manufacturers split the medical imaging reagents market, creating distinct competitive dynamics. Established players like GE Healthcare leverage extensive installed bases and broad portfolios to offer integrated diagnostic solutions, often through direct-to-hospital procurement channels. Smaller, focused entities differentiate through rapid innovation in targeted radiopharmaceuticals and theranostic agents for personalized medicine applications. Strategic partnerships, bundled purchasing contracts, and continuous R&D investment in advanced diagnostic capabilities are primary competitive moves.
Within the large diversified conglomerate tier, Bayer AG, a German AG, maintains significant market presence through its extensive portfolio of contrast agents for MRI and CT. GE Healthcare leverages its substantial installed base of imaging equipment to bundle reagent contracts, offering comprehensive diagnostic solutions to large hospital systems. Siemens Healthineers, another German AG, differentiates its offerings with integrated diagnostic solutions that combine hardware, software, and consumables for a seamless workflow. These companies exemplify the strategic importance of broad product portfolios and integrated service models in the global market, influencing procurement patterns.
| Leading Market Players |
|---|
| Bayer AG |
| Lantheus Medical Imaging |
| GE Healthcare |
| Mallinckrodt Pharmaceuticals |
| Guerbet Group |
| Siemens Healthineers |
| Bracco Imaging |
| Canon Medical Systems Corporation |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Shanghai's burgeoning medical device industry cluster, alongside other global production hubs, influences the pricing power for specialized imaging reagents by consolidating manufacturing capacity. This concentration creates distinct pricing dynamics, especially for advanced radiopharmaceuticals, where supply reliability directly impacts hospital procurement decisions.
Pricing Analysis
Configured-to-order pricing for specialized radiopharmaceuticals creates a premium spread over standard contrast agents, which are often sold on a per-unit transactional basis. Price differentiation in this market stems from the level of customization required for specific diagnostic applications and the volume scale of procurement. Pricing pressure stems from stringent regulatory compliance costs mandated by agencies like the FDA and EMA. Academic hospitals exhibit lower price sensitivity for high-value targeted agents, while medical clinics prioritize cost-effectiveness for routine procedures.
Supply Chain Analysis
Upstream feedstock for critical medical isotopes, such as Molybdenum-99 for Technetium-99m, is concentrated in a few global facilities, including those in Canada, Belgium, and South Africa. The supply chain relies heavily on inputs like iodine for contrast media and gadolinium for MRI agents. This concentration creates a single-source vulnerability, leading to availability and price risks for radiopharmaceuticals. Distribution runs through both direct-to-hospital channels for large diversified conglomerates and third-party distributors, though the latter's role is diminishing within integrated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical imaging reagents market represents an early-cycle expansion story, driven by the rapid innovation and increasing adoption of targeted radiopharmaceuticals for personalized medicine.
For Market Incumbents: Harden existing direct-to-hospital procurement channels by offering integrated diagnostic solutions that bundle imaging equipment with reagent contracts. Leverage installed bases of imaging equipment to counter threats from alternative imaging techniques and software-driven enhancements. R&D investment in theranostic agents and advanced molecular imaging will maintain a competitive edge against specialized entrants.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated markets like Southeast Asia and Latin America, where healthcare infrastructure modernization creates new demand for both contrast agents and radiopharmaceuticals. Focus on developing novel PET tracers for non-oncology applications, such as neurological assessment or cardiac viability, to target white-space opportunities. Strategic partnerships with local research institutes can accelerate market entry and product localization.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized firms innovating in targeted radiopharmaceuticals and theranostic agents. These entities offer pathways to personalized medicine applications and sustained growth. Investors should prioritize targets with strong intellectual property portfolios and robust regulatory approval pipelines. A key signal to watch is the increasing integration of AI-powered image analysis software, which enhances the value proposition of advanced reagents.
| Strategic Initiative | Industry Significance |
|---|---|
| Theranostic Agent Development | Combining diagnostic imaging with targeted therapy creates personalized treatment pathways in oncology. |
| Emerging Market Expansion | Accessing untapped demand in Southeast Asia and Latin America fuels long-term revenue growth. |
| AI-powered Image Analysis Integration | Enhances diagnostic precision and extracts more quantitative data from imaging reagent protocols. |
| Advanced Radiopharmaceutical R&D | Drives clinical adoption in oncology and neurology by providing highly specific diagnostic information. |
| Direct-to-Hospital Channel Optimization | Streamlines procurement processes and strengthens relationships with large healthcare systems. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market data anchors the qualitative findings of this analysis. The study incorporated insights from nuclear medicine physicians, hospital procurement managers, radiochemists, and regulatory affairs leads. Secondary data sources included FDA filings, EMA submissions, NMPA approvals, and extensive academic research papers, triangulated through both bottom-up and top-down approaches.
The calibration approach for market sizing and forecasting utilized a robust analytical framework across the analysis window. Segmentation dimensions modeled included product type, imaging modality, end user, application, and regional regulatory clusters. Compound annual growth rates were derived through a comprehensive analysis of historical trends, technological advancements, and expert projections. Key industry-specific forecast inputs included regulatory approval timelines for novel agents and chronic disease prevalence rates.
Stress conditions across isotope supply volatility, regulatory policy shifts, and alternative imaging technique advancements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through extensive research and stakeholder consultation. Cross-checking against industry association reports and national health statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Medical Holography Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Orthopedic Radiology Equipment Market