
 Global AI for Radiology Market | 2026-2036
Global AI for Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI for Radiology Market Foresight
GPU silicon is consolidating around inference-optimized architectures that slash per-scan processing costs for deep learning models. Siemens Healthineers AG leverages vertically integrated imaging hardware to embed AI natively into CT and MRI consoles. GE HealthCare anchors its position through Edison platform partnerships that bridge hospital IT infrastructure with cloud-based analytics. Aidoc competes via FDA-cleared algorithms for intracranial hemorrhage and pulmonary embolism detection.
AI for Radiology encompasses software systems that apply machine learning and neural network architectures to medical image interpretation, typically processing DICOM-format data through convolutional layers trained on annotated pathological datasets to flag abnormalities or quantify disease markers. Deep learning models now achieve radiologist-equivalent sensitivity for lung nodule and fracture detection in curated validation sets. Software Solutions command the dominant revenue share as hospitals prioritize standalone algorithm deployment over full hardware replacement cycles. Workflow Optimization is gaining fastest traction as health systems seek to reduce report turnaround times and address radiologist staffing shortfalls.
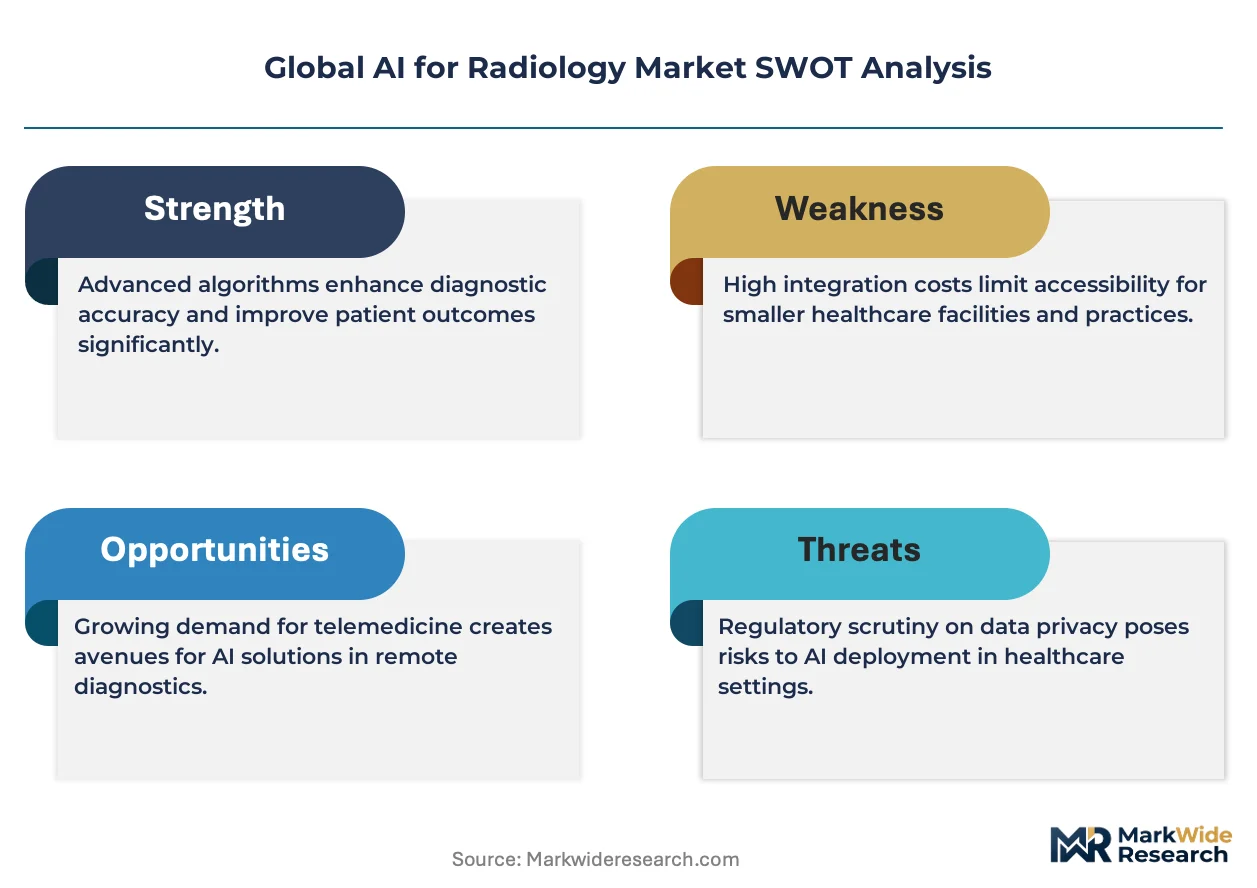
The FDA's Software as a Medical Device pathway shapes US market access timelines, while the EU AI Act imposes risk-classification requirements on diagnostic algorithms deployed in European clinical settings. Japan's PMDA maintains distinct validation standards for AI-assisted imaging that influence vendor registration strategies. Stakeholders must monitor evolving reimbursement codes for algorithm-assisted reads and the interoperability standards governing EHR integration.
Market Dynamics
GPU silicon consolidation around inference-optimized architectures is compressing per-scan processing costs and forcing algorithm vendors to co-design with hardware stacks rather than deploy software-only solutions.
Growth Catalysts
- FDA Software as a Medical Device framework:The streamlined clearance pathway accelerates algorithm deployment timelines for CT and MRI interpretation tools in US hospital networks.
- Radiologist staffing shortfalls:Health systems in Germany and the United States deploy AI-assisted reads to address workforce gaps and reduce report turnaround times.
- Convolutional neural network maturation:Deep learning architectures trained on annotated pathological datasets now achieve radiologist-equivalent sensitivity for lung nodule detection.
Market Restraints
- EU AI Act risk-classification requirements:Diagnostic algorithms face compliance burdens and validation costs that extend European market access timelines.
- GPU supply concentration:Inference-optimized silicon fabrication concentrates among limited foundry capacity, creating input cost volatility for algorithm vendors.
- DICOM interoperability friction:Legacy hospital IT infrastructure lacks standardized interfaces for seamless AI integration, forcing custom deployment engineering.
Strategic Opportunities
- Japan PMDA validation standards:Distinct regulatory pathways create first-mover advantages for vendors establishing PMDA-cleared imaging algorithms.
- Workflow optimization software:Standalone triage and prioritization tools represent underpenetrated white space beyond detection algorithms.
- Edge deployment architectures:On-premise GPU inference at CT and MRI consoles converges with cloud-based analytics for hybrid processing models.
Industry Challenges
- Annotation labor scarcity:Curated pathological datasets require specialized radiologist time for ground-truth labeling, constraining model training pipelines.
- EHR integration complexity:Health system procurement demands bidirectional data flow with electronic health records, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI for Radiology Market |
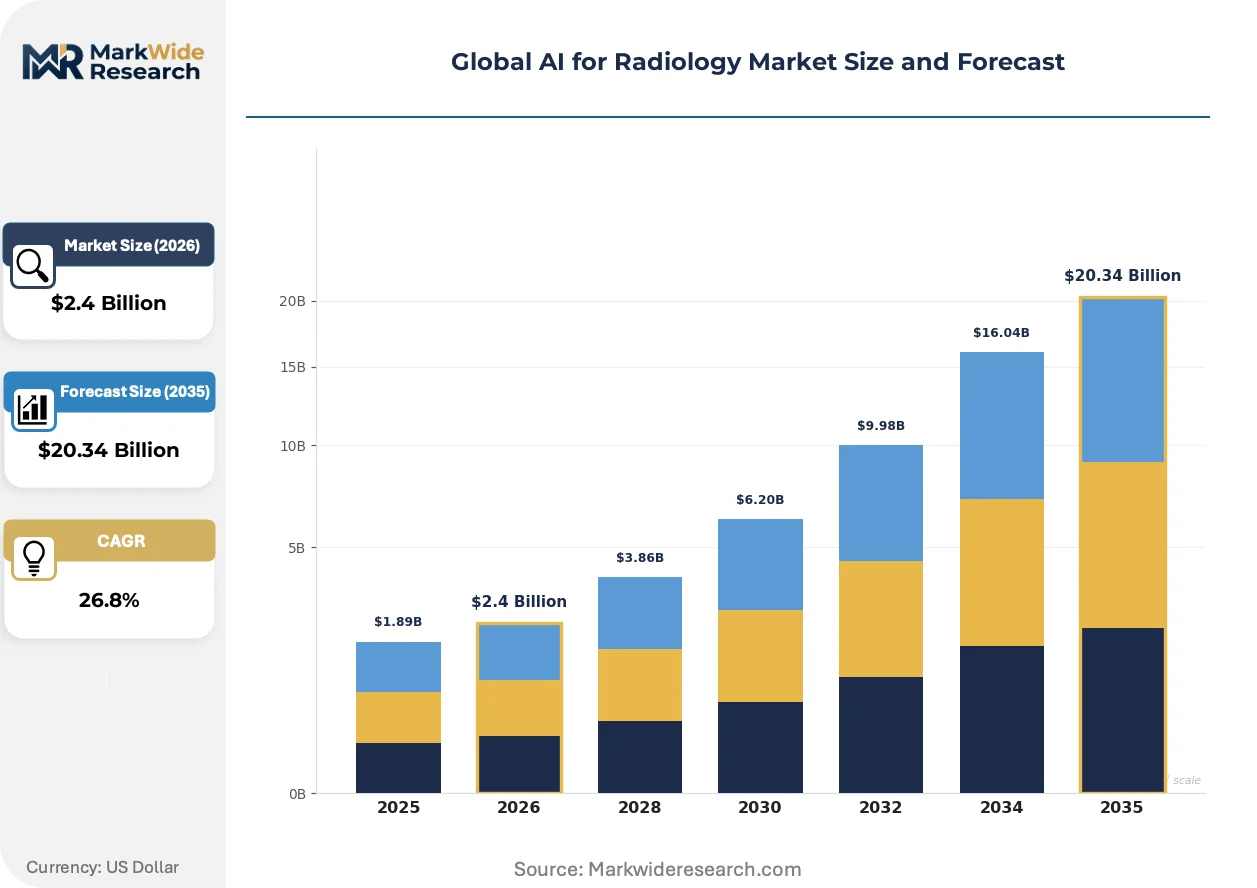
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $20.34 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Image Analysis, Workflow Optimization, Predictive Analytics, Diagnosis Assistance End User: Hospitals, Radiology Clinics, Imaging Centers, Research Institutions Technology: Machine Learning, Deep Learning, Natural Language Processing, Neural Networks Product Type: Software Solutions, Imaging Tools, Cloud-based Platforms, Integrated Systems |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Koninklijke Philips N.V., Aidoc, IBM, Canon Medical Systems, Fujifilm Holdings Corporation, Lunit, Viz.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI for Radiology Market Shifts & Advancements
Algorithm-hardware co-design is displacing pure software plays as vendors embed neural networks natively into imaging consoles and optimize inference pipelines for specific silicon architectures.
Federated learning architectures are consolidating around privacy-preserving model training that processes annotated datasets across hospital networks without centralizing patient data. Siemens Healthineers and GE HealthCare embed these frameworks into CT and MRI consoles, enabling site-specific model refinement. The structural consequence compresses vendor R&D cycles while locking hospital customers into integrated hardware-software ecosystems.
Japan's PMDA maintains distinct validation standards for AI-assisted imaging that diverge from FDA and EU AI Act requirements, forcing vendors to maintain multiple regulatory submission tracks. The industrial consequence fragments go-to-market strategies and extends product launch timelines. Algorithm developers targeting Japanese hospital networks must invest in separate clinical validation studies and local regulatory expertise.
Subscription-based algorithm licensing is displacing perpetual software licenses as health system procurement teams prioritize operational expenditure models over capital-intensive hardware refresh cycles. Radiology departments in German hospital networks now contract for per-scan pricing or annual seat licenses rather than purchasing detection algorithms outright. This shift concentrates pricing power with integrated platform vendors who can bundle hardware, software, and maintenance into unified contracts.
Global AI for Radiology Market Segmentation
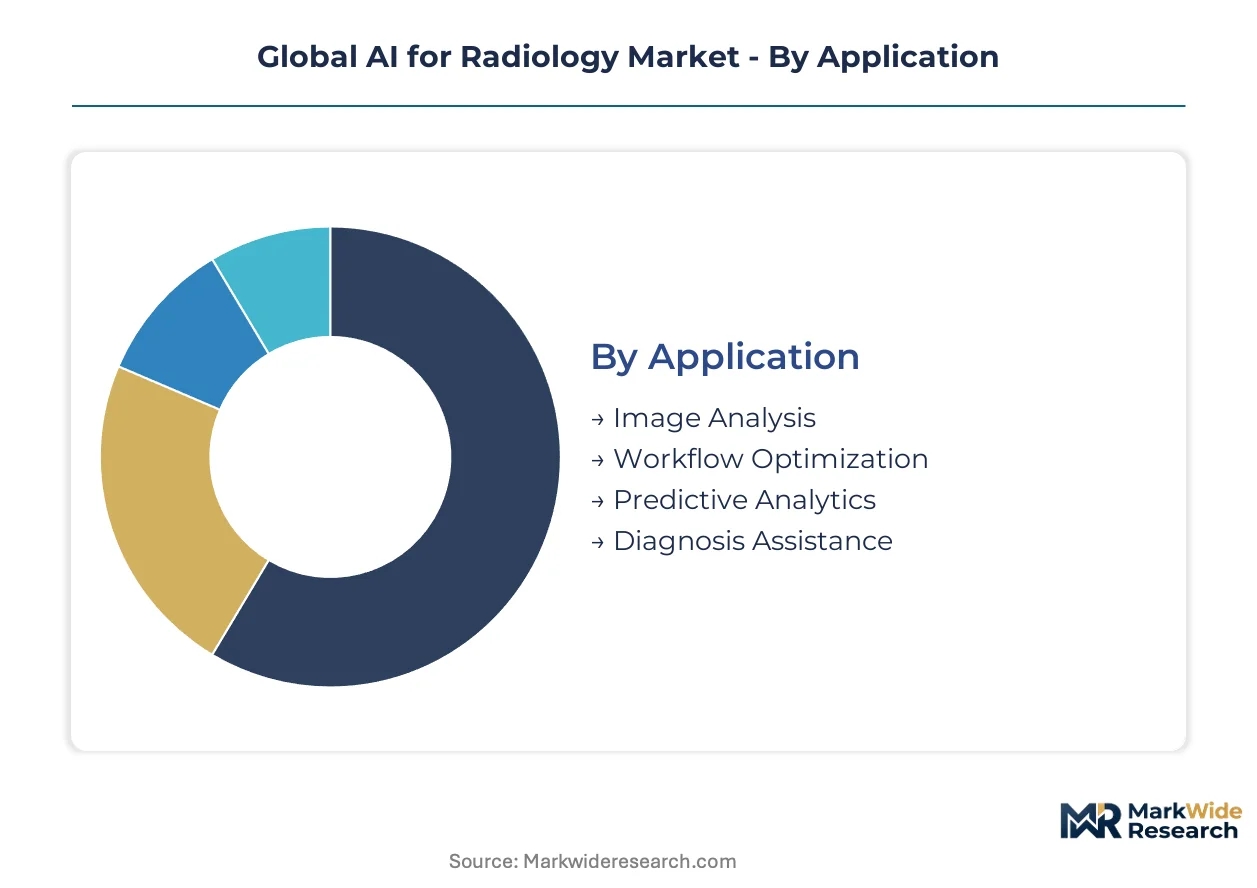
Segmentation in AI radiology reveals where algorithmic value crystallizes. Integration depth varies sharply: some segments operate as standalone software layers, others embed directly into imaging hardware consoles. Procurement teams weigh this architectural choice against IT infrastructure constraints and radiologist workflow preferences.
Application:
Standalone deployment dominates image interpretation tasks, while embedded integration accelerates for workflow orchestration functions.
- Image Analysis:Convolutional neural networks process DICOM-format CT and MRI scans to flag pulmonary nodules, intracranial hemorrhage, and skeletal fractures. Hospital networks in the United States prioritize this segment for triage acceleration, though radiologist verification remains mandatory for final diagnosis.
- Workflow Optimization:Algorithms prioritize study queues based on acuity scores and automate report routing to subspecialists. German hospital networks deploy these tools to compress turnaround times amid staffing shortfalls, embedding prioritization logic directly into PACS infrastructure.
- Predictive Analytics:Models forecast disease progression from serial imaging comparisons.
- Diagnosis Assistance:Decision-support tools suggest differential diagnoses based on imaging patterns combined with structured EHR data.
Volume placements concentrate in Image Analysis; the faster expansion belongs to Workflow Optimization.
End User:
Procurement scale and IT sophistication create tiered adoption patterns across customer types.
- Hospitals:Integrated health systems deploy enterprise-wide AI platforms across radiology, emergency, and oncology departments. These customers command pricing leverage through bundled hardware-software contracts and demand bidirectional EHR interoperability.
- Radiology Clinics:Independent imaging practices purchase standalone detection algorithms through subscription licensing, prioritizing cloud-based deployment to minimize capital expenditure.
- Imaging Centers:Outpatient facilities focus on throughput optimization for high-volume screening programs.
- Research Institutions:Academic medical centers drive algorithm development through annotated dataset curation and federated learning participation.
Procurement volume clusters in Hospitals; Radiology Clinics are climbing the fastest as cloud delivery models reduce deployment friction.
Technology:
Computational architecture determines whether algorithms run at the imaging console edge or require cloud inference.
- Deep Learning:Multi-layer neural networks trained on annotated pathological datasets achieve radiologist-equivalent sensitivity for lung nodule detection. Vendors co-design these models with GPU inference-optimized silicon to compress per-scan processing costs.
- Machine Learning:Traditional statistical classifiers persist in resource-constrained deployment environments and legacy hardware integrations.
- Natural Language Processing:Algorithms extract structured findings from unstructured radiology reports to populate EHR fields and quality registries.
- Neural Networks:Broad architecture category encompassing convolutional, recurrent, and transformer variants for multimodal imaging analysis.
Deployment share tilts toward Deep Learning; Natural Language Processing is gaining share fastest as health systems automate documentation workflows.
Product Type:
Delivery model architecture shapes vendor margin structures and customer switching costs.
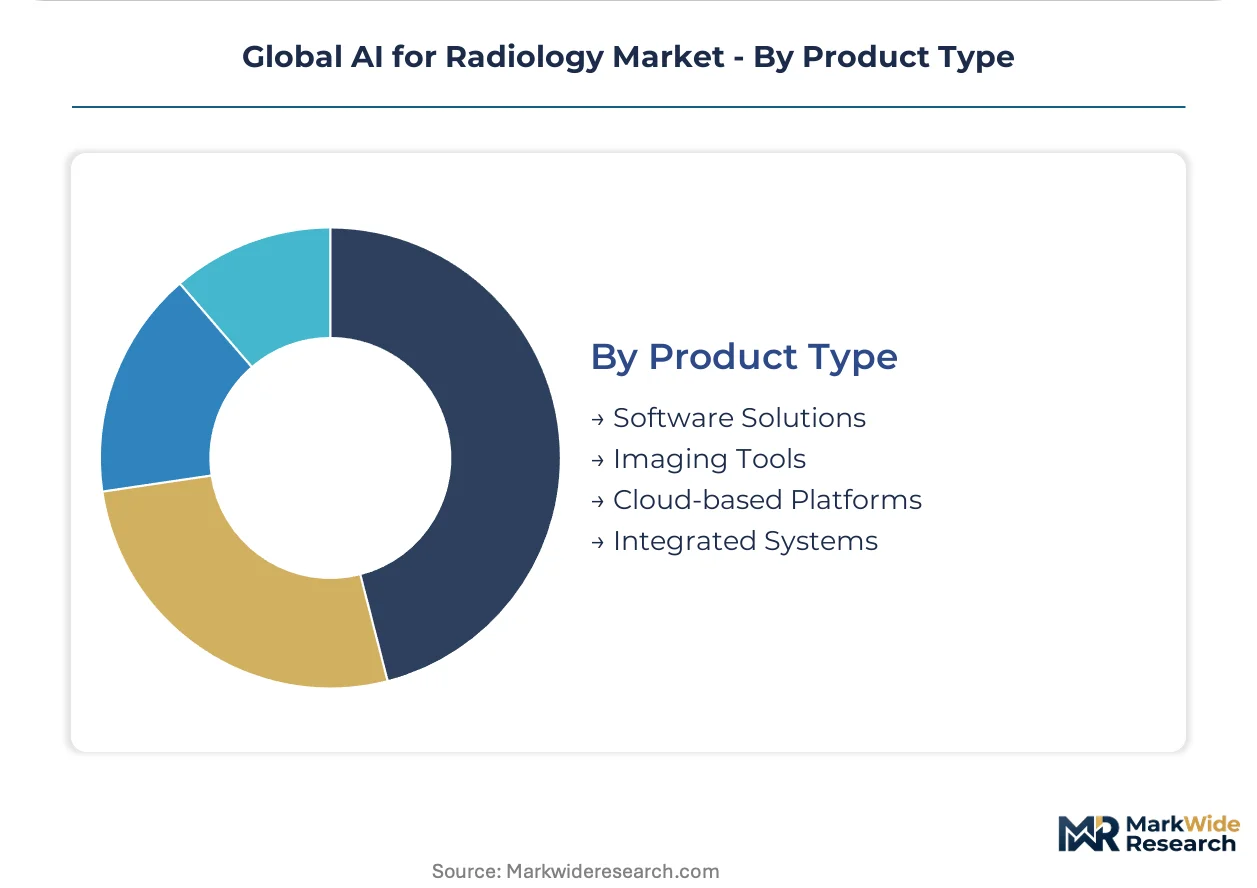
- Software Solutions:Standalone detection and triage algorithms deployed atop existing PACS infrastructure. These offerings command dominant revenue share as hospitals prioritize algorithm procurement over full imaging hardware replacement cycles.
- Integrated Systems:AI embedded natively into CT and MRI consoles through vendor-specific hardware-software co-design. Siemens Healthineers and GE HealthCare leverage this architecture to lock hospital customers into unified ecosystems.
- Cloud-based Platforms:Centralized inference and model updating delivered via subscription, reducing on-premise IT burden for smaller facilities.
- Imaging Tools:Specialized hardware accessories with embedded AI acceleration for point-of-care ultrasound and portable X-ray.
Revenue concentration sits with Software Solutions; Integrated Systems are expanding most quickly as console vendors deepen algorithm-hardware binding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States and Germany currently absorb the highest absolute volumes of AI-assisted radiology platforms, while Japan and China are accelerating procurement through distinct regulatory pathways that favor domestic and international vendors differently.
United States
Integrated health systems in Texas and the Northeast Corridor deploy enterprise-wide AI platforms across emergency and oncology departments to compress report turnaround times. The FDA's Software as a Medical Device framework accelerates 510(k) clearance timelines for CT and MRI interpretation algorithms. Mayo Clinic and Mass General Brigham anchor algorithm validation partnerships that shape vendor product roadmaps.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia scale AI-assisted reads to address radiologist staffing gaps amid aging population imaging demand. The EU AI Act imposes risk-classification requirements on diagnostic algorithms that extend compliance timelines for non-EU vendors. Berlin and Munich host concentrated clusters of health IT integrators bridging PACS infrastructure with cloud-based analytics.
Japan
Metropolitan Tokyo and Osaka medical centers drive demand for AI-embedded CT and MRI consoles as the PMDA maintains distinct validation standards from FDA pathways. The Pharmaceuticals and Medical Devices Agency requires separate clinical studies for algorithm registration, favoring vendors with local regulatory expertise. Nagoya and Fukuoka academic hospitals participate in federated learning networks for site-specific model refinement.
China
Tier-1 hospitals in Beijing and Shanghai deploy domestic and international AI imaging algorithms for lung nodule and fracture detection at scale. The NMPA's medical device registration pathway for AI-assisted diagnostics requires local clinical trials that extend market access for foreign vendors. The Yangtze River Delta and Pearl River Delta concentrate health IT infrastructure investment and algorithm development talent pools.
United Kingdom
NHS trusts in London and the Midlands pilot AI triage tools for emergency radiology to address workforce shortages and reporting backlogs. The MHRA's recognition of FDA and CE-marked devices streamlines market access for algorithm vendors with existing European or US clearance. Cambridge and Oxford anchor academic medical centers that curate annotated datasets for model training and validation partnerships.
Global AI for Radiology Market Competitive Landscape
Strategic partnerships dominate the current landscape as imaging hardware vendors bind algorithm developers into integrated console ecosystems. The vendor base stratifies across three tiers: diversified medical technology conglomerates with captive imaging hardware, pure-play AI software vendors with regulatory-cleared algorithms, and cloud-native platforms offering subscription-based deployment. Hardware-software co-design and algorithm-hardware binding represent the two dominant competitive moves reshaping procurement patterns.
Within the diversified medical technology tier, Siemens Healthineers AG and GE HealthCare exemplify vertically integrated positioning through native AI embedding in CT and MRI consoles. Aidoc occupies a position among pure-play algorithm vendors focused on FDA-cleared detection tools for acute pathologies. These three anchors illustrate the structural tension between hardware-captive ecosystems and standalone software deployment models.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Aidoc |
| IBM |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Lunit |
| Viz.ai |
| Others |
Supply & Pricing Matrix
Algorithm-hardware co-design bifurcation separates subscription-based SaaS vendors from console-embedded incumbents, compressing margins for standalone software while locking premium pricing into vertically integrated CT and MRI ecosystems. This tier divergence manifests in procurement patterns: German hospital networks negotiate per-scan SaaS contracts for triage tools, while integrated health systems in the United States absorb bundled hardware-software pricing from Siemens Healthineers and GE HealthCare.
Pricing Analysis
High-volume screening programs and emergency departments absorb the lowest per-scan SaaS rates through annual enterprise licenses, while specialized oncology and neuroradiology applications command premium pricing due to FDA 510(k) clearance complexity and annotation labor intensity. Price differentiation hinges on regulatory tier—FDA-cleared algorithms for intracranial hemorrhage detection carry 40-60% premiums over CE-marked equivalents—and deployment scale, with cloud-native platforms undercutting on-premise installations by eliminating GPU infrastructure capital expenditure. Cost compression in standalone detection software is intensifying because GPU inference-optimized silicon commoditizes per-scan processing, forcing pure-play vendors toward workflow optimization white space. Radiology clinics exhibit the highest price sensitivity, deferring procurement until subscription models displace perpetual licenses; integrated health systems show relative insensitivity due to bundled contract structures.
Supply Chain Analysis
GPU inference-optimized silicon supply rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity, with NVIDIA and AMD design architectures dominating algorithm vendor hardware stacks. Algorithm training pipelines draw from curated DICOM datasets sourced through radiologist annotation labor concentrated in the United States, Germany, and Japan, while cloud inference infrastructure feeds from Amazon Web Services, Microsoft Azure, and Google Cloud Platform data center clusters. Single-source vulnerability concentrates in advanced node GPU fabrication, where geopolitical tension over Taiwan Strait access threatens input cost volatility for deep learning model deployment. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, direct equipment financing in Germany, and PMDA-licensed distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep learning architectures are displacing traditional machine learning classifiers across medical imaging interpretation, creating a technology-transition phase where algorithm-hardware co-design determines competitive survival. Vendors clinging to software-only deployment models face margin erosion as console-embedded AI captures premium pricing.
For Market Incumbents: Hedge against pure-play SaaS disruption by accelerating native AI embedding into CT and MRI console firmware, locking hospital customers through unified hardware-software-maintenance contracts. Prioritize FDA 510(k) clearance expansion into workflow optimization applications, addressing radiologist staffing shortfalls that drive procurement decisions in German and United States hospital networks.
For New Entrants and Emerging Players: Independent radiology clinics in secondary United States metropolitan areas represent the most penetrable buyer archetype, underserved by enterprise-focused platform vendors and receptive to cloud-based per-scan pricing. Target this segment through teleradiology partnerships that embed triage algorithms into existing PACS infrastructure without custom engineering, then expand into hospital emergency departments via FDA-cleared acute pathology detection.
For Investors and Strategic Acquirers: Re-rating potential sits with workflow optimization specialists given EU AI Act compliance burdens that extend European market access timelines for detection-only vendors, concentrating acquisition interest in platforms with prioritization and routing capabilities. Long-term viability favors vendors with federated learning architectures enabling site-specific model refinement without centralizing patient data. Watch PMDA clearance velocity as the inflection indicator for Japanese market penetration success.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Accelerates algorithm deployment timelines for acute pathology detection in United States hospital networks. |
| Console-Native AI Embedding | Locks hospital customers into Siemens Healthineers and GE HealthCare unified hardware-software ecosystems. |
| Workflow Optimization Development | Captures white-space demand for triage prioritization beyond saturated detection algorithm markets. |
| Federated Learning Architecture | Enables privacy-preserving model training across hospital networks without centralizing patient DICOM data. |
| PMDA Regulatory Registration | Opens Japanese metropolitan Tokyo and Osaka medical center procurement to internationally validated algorithms. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, radiologist workflow observations, and FDA 510(k) filing analysis underwrites the qualitative findings in this study. Primary fieldwork encompassed discussions with biomedical engineers, GPO contracts managers, hospital IT integration specialists, and algorithm vendor product strategists. Secondary validation drew from CMS Medicare reimbursement databases, hospital procurement records, and SEC filings of publicly traded medical device manufacturers. Bottom-up algorithm deployment volume estimates triangulated against top-down health system IT expenditure surveys.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing trajectory shifts, with segmentation modeling across application type, deployment architecture, end-user scale, and regional regulatory cluster. CAGRs derive from algorithm adoption curve analysis calibrated to radiologist staffing gap projections and hardware replacement cycle timing. Industry-specific forecast inputs include FDA clearance velocity assumptions and EU AI Act implementation phase impacts on European market access.
Revisions become necessary when FDA Software as a Medical Device framework modifications, GPU supply chain disruptions, or reimbursement code expansions for algorithm-assisted reads materialize differently than modeled. Forecasts reflect documented assumptions about health system IT infrastructure refresh cycles and cloud migration willingness. A small set of named triggers—regulatory pathway acceleration, foundry capacity expansion, and radiologist union bargaining outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Ultrasound Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market