
 Mexico Mammography Market | 2026-2036
Mexico Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Mammography Market Foresight
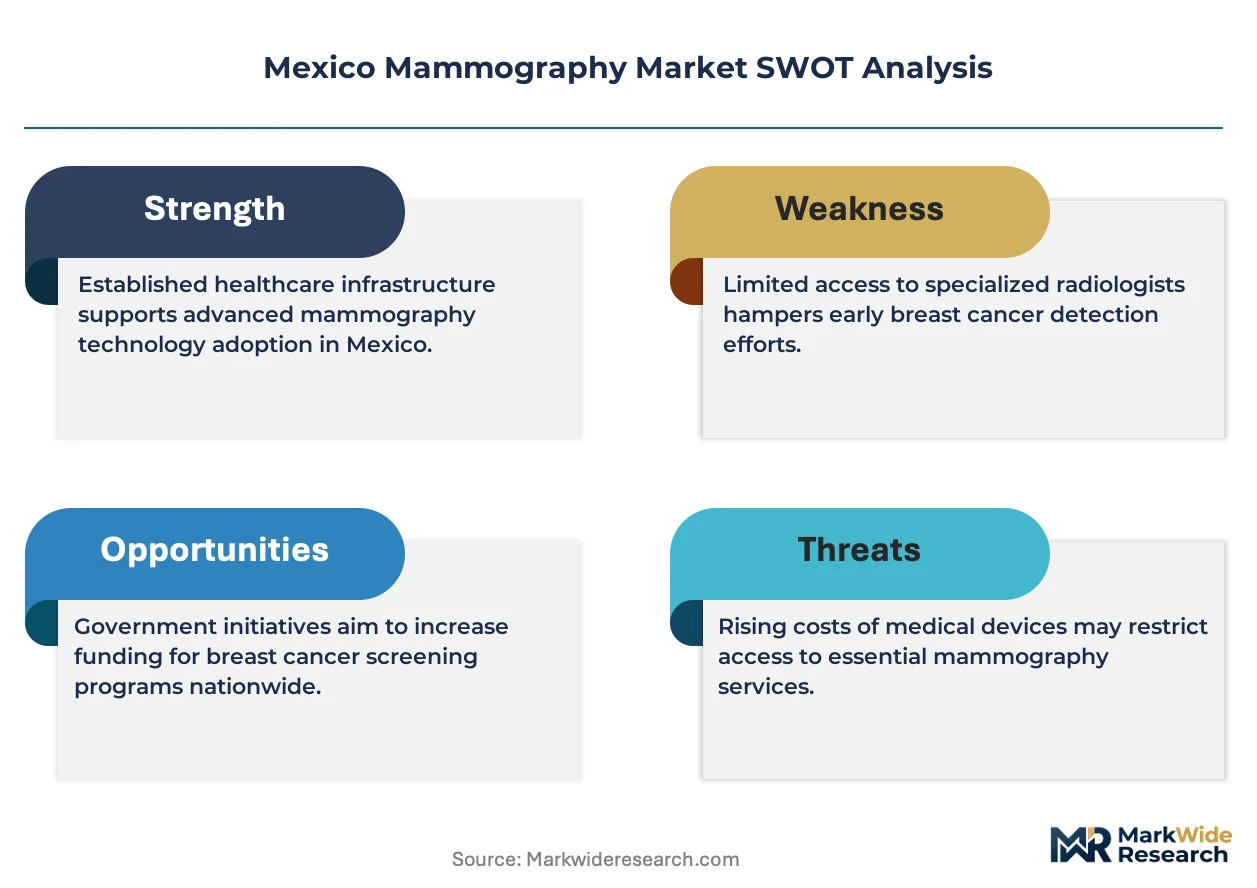
Private diagnostic chains is unwinding toward public sector procurement as government screening mandates expand. Siemens Healthineers leverages its installed base of analog-to-digital retrofit solutions across federal hospital networks. Hologic anchors the premium 3D tomosynthesis segment through direct technical service contracts with oncology institutes. Canon Medical Systems Corporation competes on portable system deployments for mobile breast cancer screening units in rural states.
Mammography denotes X-ray imaging of breast tissue using low-dose ionizing radiation, typically operating at 25-35 kVp with molybdenum or rhodium target tubes and dedicated compression paddles to optimize tissue separation and reduce motion artifact. Digital systems capture images via flat-panel detectors with pixel pitches of 50-100 micrometers, enabling computer-aided detection algorithms for microcalcification identification. 3D tomosynthesis segments command premium positioning as hospitals phase out analog fleets, while portable configurations address geographic access gaps in underserved states. Direct sales channels dominate capital equipment transactions, though distributor networks gain traction for aftermarket service and consumables in secondary cities.
COFEPRIS regulates medical device safety and efficacy through mandatory registration and post-market surveillance requirements for mammography systems. NOM-041-SSA2-2011 establishes technical specifications for breast cancer prevention, diagnosis, and treatment within national health programs. The Secretariat of Health's oncology strategy shapes procurement volumes and technology standards across IMSS, ISSSTE, and state health services. Stakeholders must monitor reimbursement rate adjustments under INSABI and Seguro Popular successor frameworks to anticipate public sector purchasing cycles and digital upgrade timelines.
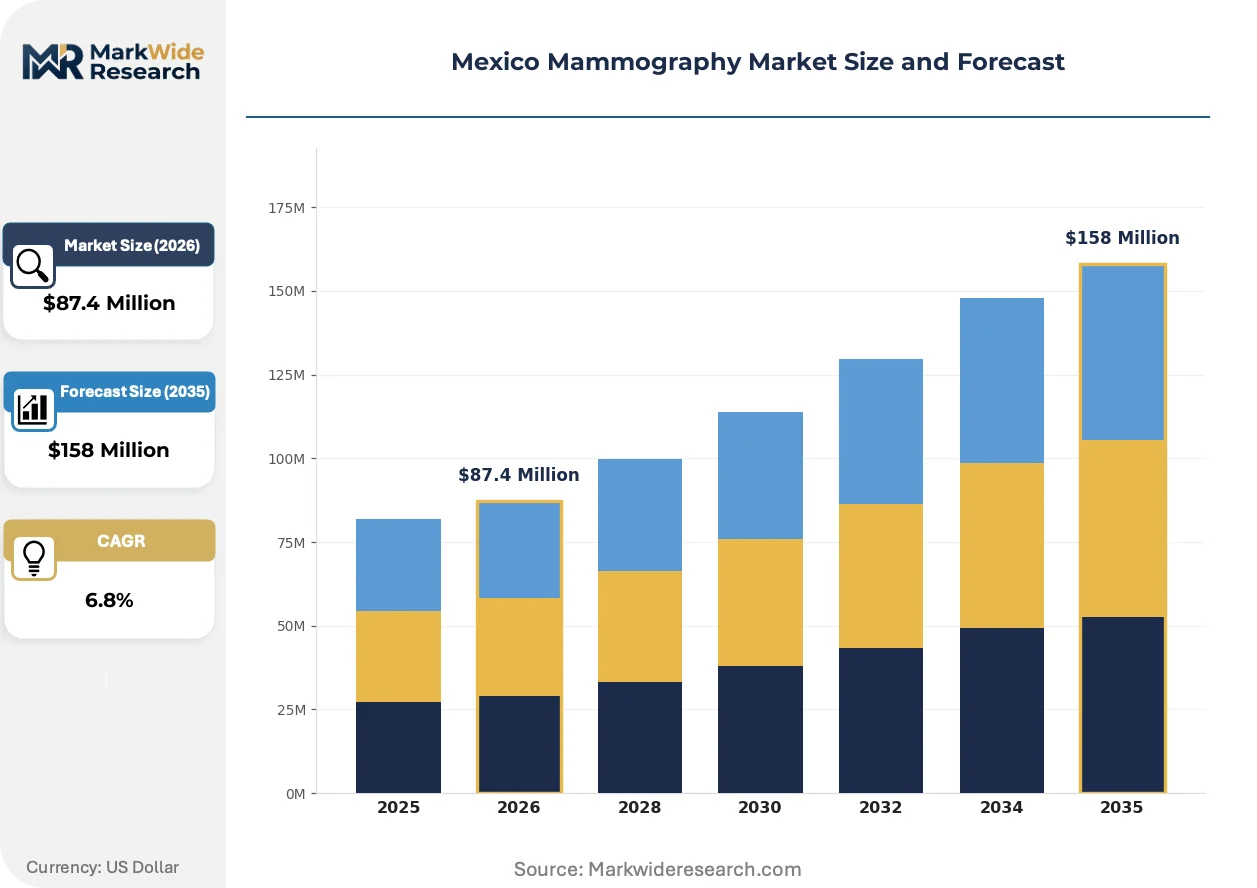
Market Dynamics
Federal screening mandates under NOM-041-SSA2-2011 are restructuring procurement flows from private diagnostic chains toward IMSS and ISSSTE hospital networks, compressing capital equipment replacement cycles and reshaping vendor contract structures.
Growth Catalysts
- NOM-041-SSA2-2011:This technical standard mandates breast cancer prevention protocols across national health programs, institutionalizing screening volumes that sustain equipment procurement.
- Flat-panel detector technology:Digital mammography systems with 50-100 micrometer pixel pitches enable computer-aided detection algorithms, improving diagnostic accuracy and justifying upgrade investments.
- Monterrey metropolitan corridor:Concentrated private healthcare infrastructure in Nuevo León generates sustained demand for premium 3D tomosynthesis installations.
Market Restraints
- Molybdenum and rhodium target tube supply:Specialized X-ray tube components face concentrated global manufacturing, exposing Mexican buyers to input cost volatility and extended lead times.
- COFEPRIS registration timelines:Medical device approval pathways for digital system upgrades create regulatory friction that delays fleet modernization in public hospital networks.
- Mobile screening unit deployment costs:Portable system logistics for rural state coverage require substantial operational expenditure that strains state health service budgets.
Strategic Opportunities
- Chiapas and Oaxaca rural coverage gaps:Underserved southern states present white space for mobile breast cancer screening units with portable mammography configurations.
- INSABI successor framework reimbursement adjustments:Evolving public insurance mechanisms may expand covered screening populations, creating procurement tailwinds for federal hospital networks.
- Artificial intelligence integration with tomosynthesis:Convergence of deep learning algorithms and 3D imaging workflows promises workflow efficiency gains for oncology institutes.
Industry Challenges
- Biomedical engineering specialization:Shortage of technicians trained in digital detector calibration and compression paddle maintenance limits service capacity expansion.
- Legacy analog-to-digital retrofit complexity:Integration of new flat-panel systems with existing generator infrastructure creates technical friction and extended downtime risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Mammography Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, 3D, Portable End User: Hospitals, Diagnostic Centers, Research Institutes, Clinics Technology: X-Ray, Ultrasound, MRI, Tomosynthesis Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | FUJIFILM, Koninklijke Philips, Siemens Healthineers, Planmed, Carestream Health, Hologic, Canon Medical Systems Corporation, Lunit, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Mammography Market Shifts & Advancements
Workflow automation and point-of-care imaging architectures are restructuring how breast screening services deploy across Mexico's heterogeneous healthcare infrastructure. Three developments warrant particular attention.
3D tomosynthesis is decomposing the traditional two-view mammography standard by enabling volumetric tissue analysis that reduces callback rates and compression-related patient discomfort. Oncology institutes in Mexico City are adopting these systems at accelerated pace, compressing the economic viability of analog and basic digital configurations in premium diagnostic settings.
COFEPRIS streamlined registration pathways for software-as-medical-device applications are accelerating algorithm-based diagnostic tool deployment. This regulatory evolution reduces time-to-market for computer-aided detection systems, prompting equipment vendors to bundle AI modules with new detector installations. Public sector procurement specifications increasingly reference automated microcalcification identification capabilities.
Service contract unbundling is fragmenting traditional capital equipment sales models. Federal hospital networks now separate hardware acquisition from technical service agreements, enabling multi-vendor maintenance arrangements and pressuring original equipment manufacturers to defend aftermarket revenue through specialized training certifications. This pattern is most visible in ISSSTE facilities undergoing fleet standardization.
Mexico Mammography Market Segmentation
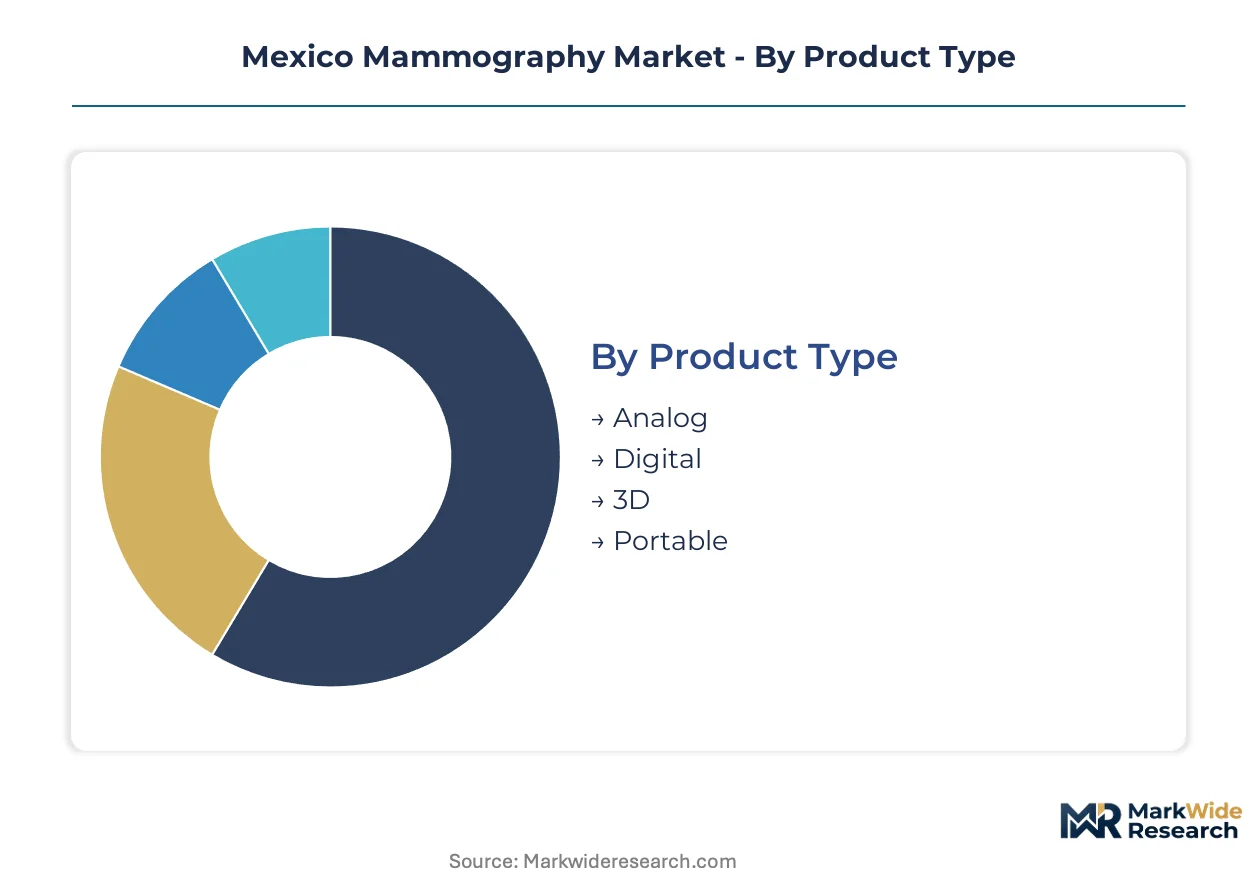
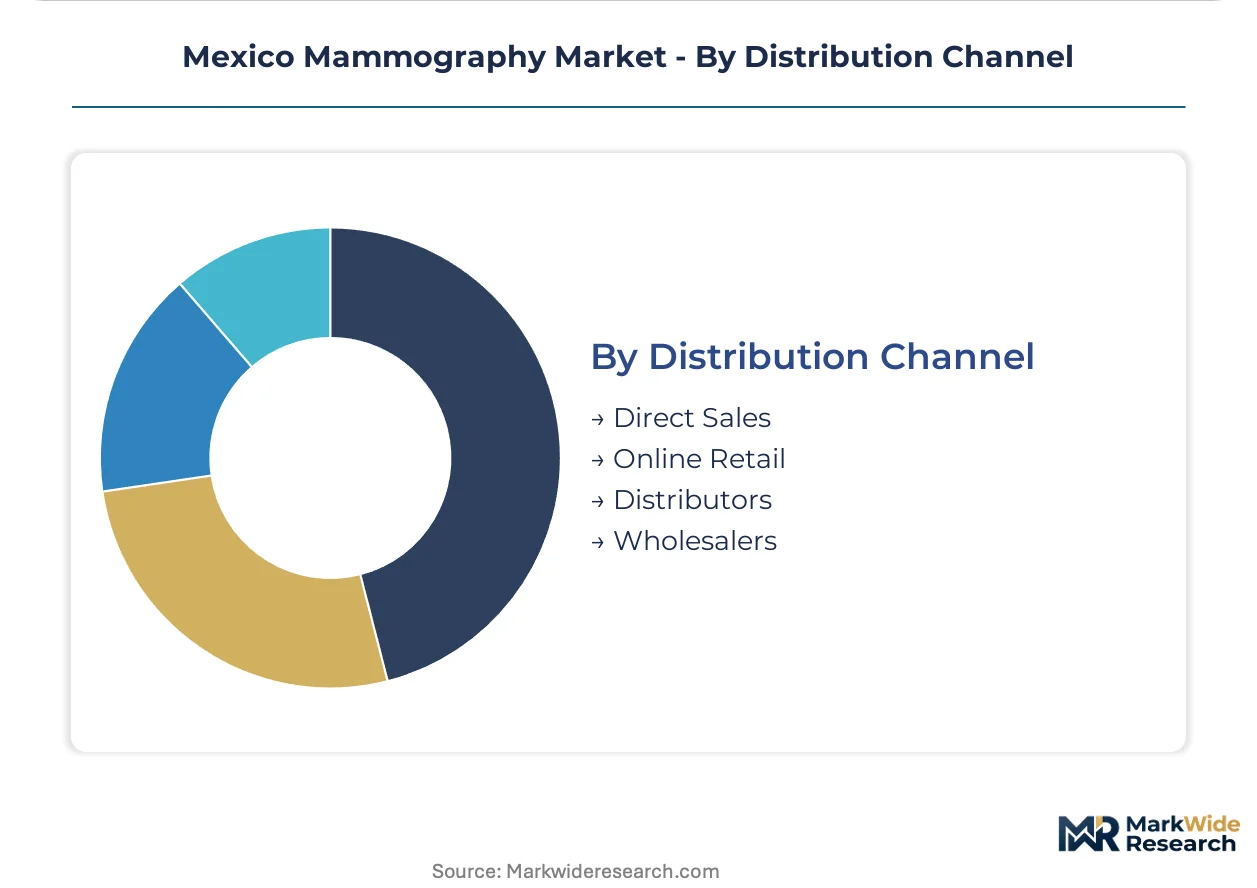
Segmentation in the Mexico mammography market reveals distinct procurement patterns across public and private healthcare infrastructure. Technology tiers and distribution channels determine vendor positioning and margin capture within federal hospital networks versus metropolitan diagnostic chains.
Product Type:
Margin pools concentrate in 3D tomosynthesis and portable configurations as public screening mandates expand and rural access gaps persist.
- 3D:Volumetric breast imaging systems reconstruct multiple thin-slice projections, enabling superior lesion characterization and reduced callback rates. Oncology institutes in Mexico City prioritize these installations as they phase out legacy analog fleets under NOM-041-SSA2-2011 compliance timelines.
- Portable:Mobile mammography units with battery-powered generators and lightweight detector arrays address geographic coverage gaps in Chiapas and Oaxaca. State health services fund these deployments through federal rural health allocations, though operational logistics compress per-procedure margins.
- Digital:Flat-panel detector systems with 50-100 micrometer pixel pitches serve as the workhorse configuration across IMSS and ISSSTE hospital networks, balancing diagnostic performance with capital expenditure constraints.
- Analog:Film-screen systems persist in underfunded state facilities awaiting digital upgrade cycles, though COFEPRIS registration pathways for retrofit components sustain limited aftermarket activity.
Digital holds installed capacity. 3D is rotating up the share rankings.
End User:
Procurement authority determines contract structures, with federal networks favoring centralized tenders and private chains negotiating direct technical service agreements.
- Hospitals:IMSS and ISSSTE facilities drive volume through standardized fleet purchases, with oncology institutes in Monterrey and Mexico City commanding premium 3D configurations.
- Diagnostic Centers:Private chains in Nuevo León and Jalisco concentrate demand for workflow-optimized systems with integrated computer-aided detection, though federal screening mandates are compressing their market share.
- Clinics:Smaller facilities in secondary cities favor refurbished digital systems or analog-to-digital retrofit solutions to manage capital constraints.
- Research Institutes:National Cancer Institute and university hospitals deploy specialized tomosynthesis platforms for clinical trial protocols and AI algorithm validation studies.
Hospitals anchor procurement volume. Diagnostic centers are ceding share to public networks.
Technology:
Imaging modality selection tracks reimbursement pathways and clinical workflow integration requirements across screening versus diagnostic applications.
- Tomosynthesis:Three-dimensional X-ray acquisition systems reduce tissue overlap artifacts and enable synthetic 2D reconstruction, justifying premium positioning in metropolitan oncology centers.
- X-Ray:Conventional digital mammography with molybdenum or rhodium target tubes remains the screening standard across federal programs, with flat-panel detector technology enabling computer-aided detection integration.
- Ultrasound:Handheld systems serve as adjunctive imaging for dense breast tissue evaluation and biopsy guidance in specialized breast centers.
- MRI:Magnetic resonance imaging for high-risk screening and staging applications operates at limited sites due to capital intensity and specialized radiologist requirements.
X-Ray dominates procedure volume. Tomosynthesis is gaining share fastest in premium installations.
Distribution Channel:
Channel selection reflects equipment complexity and service bundling requirements, with capital transactions separating from aftermarket maintenance.
- Direct Sales:Original equipment manufacturers engage federal hospital networks through centralized procurement tenders, bundling installation and initial training with detector systems.
- Distributors:Regional networks manage aftermarket service and consumables in Guadalajara, Puebla, and secondary cities, capturing recurring revenue streams.
- Wholesalers:Medical device aggregators supply replacement tubes, compression paddles, and calibration phantoms to facilities with unbundled service contracts.
- Online Retail:E-commerce platforms facilitate consumables procurement for small clinics, though capital equipment transactions remain relationship-driven.
Direct sales capture capital equipment value. Distributors are consolidating aftermarket position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical imaging equipment flows into Mexico primarily from manufacturing centers in Germany, Japan, and the United States, with distribution networks radiating from Mexico City toward secondary metropolitan corridors.
Mexico City Metro
The capital's oncology institutes drive premium 3D tomosynthesis installations under NOM-041-SSA2-2011 compliance mandates. COFEPRIS streamlined registration pathways accelerate digital system approvals for IMSS flagship hospitals. Hospital networks in Tlalpan and Cuauhtémoc concentrate specialized breast cancer screening capacity.
Nuevo León
Monterrey's private diagnostic chains sustain demand for workflow-optimized systems with integrated computer-aided detection. State health services coordinate with federal programs to expand public screening access beyond metropolitan boundaries. San Pedro Garza García anchors premium diagnostic infrastructure serving northern Mexico.
Jalisco
Guadalajara's hospital networks balance public procurement requirements with private clinic demand for refurbished digital configurations. The Secretariat of Health's oncology strategy channels federal resources toward state facility upgrades. Zapopan and Tlaquepaque cluster secondary diagnostic capacity.
Bajío Region
Aguascalientes and Guanajuato state health services deploy mobile screening units to address rural coverage gaps. Federal rural health allocations fund portable mammography configurations for underserved municipalities. León and Querétaro serve as logistics hubs for equipment distribution.
Chiapas and Oaxaca
Southern states present white space for mobile breast cancer screening programs with battery-powered portable systems. State health service budgets strain under operational expenditure requirements for geographic coverage extension. Tuxtla Gutiérrez and Oaxaca City anchor limited fixed-site diagnostic capacity.
Mexico Mammography Market Competitive Landscape
Listed leaders compete with private specialists across technology tiers and service contract structures. Siemens Healthineers and GE Healthcare anchor the premium capital equipment segment through direct federal procurement relationships, while specialized distributors capture aftermarket service revenue in secondary cities. Three archetypes dominate: multinational original equipment manufacturers with installed base leverage, regional distributors unbundling service from hardware sales, and software specialists integrating AI modules with detector systems. Competitive moves center on analog-to-digital retrofit bundling and multi-vendor maintenance certification programs.
Among Japan-based imaging conglomerates, FUJIFILM occupies a position exemplifying flat-panel detector manufacturing integration. Koninklijke Philips represents the European diversified health technology archetype with cross-modal imaging portfolios. Siemens Healthineers anchors the German precision engineering tier, its name signaling healthcare-specific focus within industrial conglomerate structures.
| Leading Market Players |
|---|
| FUJIFILM |
| Koninklijke Philips |
| Siemens Healthineers |
| Planmed |
| Carestream Health |
| Hologic |
| Canon Medical Systems Corporation |
| Lunit |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
COFEPRIS registration pathways gate both vendor qualification and price differentiation simultaneously, compressing margins for unregistered retrofit components while premium-tier digital systems command service-bundled premiums across federal procurement channels.
Pricing Analysis
Next-generation 3D tomosynthesis systems command substantial premiums over legacy digital configurations and obsolete analog fleets. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution tiers and AI integration depth. Cost compression in the analog retrofit segment intensifies because state health services prioritize lowest-capital pathways. Public hospital networks exhibit highest price sensitivity, while Monterrey private diagnostic chains absorb premium positioning for workflow-optimized installations.
Supply Chain Analysis
Molybdenum and rhodium target tube manufacturing concentrates in Germany, Japan, and the United States, creating procurement bottlenecks for Mexican buyers. Flat-panel detector arrays draw from Taiwanese semiconductor foundries and South Korean display fabrication. Single-source vulnerability runs through specialized X-ray tube suppliers, with extended lead times amplifying working capital requirements. Distribution runs through Mexico City-based medical device aggregators radiating toward Guadalajara and Monterrey secondary hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with COFEPRIS registration history and installed base service relationships creating switching costs that resist displacement.
For Market Incumbents: Secure multi-year technical service contracts with ISSSTE and IMSS facilities before federal fleet standardization completes. Anchor aftermarket revenue through biomedical engineer certification programs that lock out independent service organizations. Emerging AI diagnostic entrants threaten premium positioning, requiring accelerated software companion development for tomosynthesis platforms. For New Entrants and Emerging Players: COFEPRIS expedited review pathways for software-as-medical-device applications open regulatory fast-track opportunities. Chiapas and Oaxaca mobile screening deployments represent the most penetrable white space, with battery-powered portable configurations addressing geographic access gaps. Partner with state health services on operational expenditure-sharing models rather than capital-heavy direct sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable system manufacturing as component modularization reduces final assembly complexity. Acquisition targets should concentrate on regional distributors with unbundled service contract portfolios and COFEPRIS regulatory expertise. Monitor INSABI successor framework reimbursement rate announcements as the critical inflection signal for public procurement volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Pathway | Accelerated software-as-medical-device approvals compress time-to-revenue for AI diagnostic modules. |
| Hospital System Partnership | IMSS and ISSSTE fleet standardization creates multi-year procurement visibility for compliant vendors. |
| Software Companion Development | Computer-aided detection integration with tomosynthesis workflows differentiates premium system positioning. |
| Reimbursement Strategy | INSABI successor framework alignment determines covered screening populations and equipment upgrade timelines. |
| Geographic Expansion | Mobile unit deployment in Chiapas and Oaxaca addresses federal rural health allocation priorities. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and COFEPRIS regulatory consultants and refined through secondary validation. Sources included hospital procurement databases, GPO contract filings, Secretaría de Salud oncology program disclosures, and IMSS capital expenditure records. Bottom-up equipment installation tracking and top-down federal health budget allocation analysis were triangulated to establish market sizing boundaries.
Variance decomposition across the projection horizon isolates volume drivers by technology generation, end-user procurement authority, and regional infrastructure maturity. Segmentation dimensions modeled include product configuration tier, distribution channel structure, and state-level health service budget capacity. CAGRs were derived from installed base replacement cycle analysis and federal screening mandate compliance timelines. Forecast inputs incorporated NOM-041-SSA2-2011 protocol expansion assumptions and flat-panel detector technology diffusion curves.
Underlying assumptions cover federal rural health allocation continuity and COFEPRIS registration pathway stability, with deviation risk concentrated in molybdenum target tube supply disruptions and INSABI successor framework reimbursement adjustments. Practitioners should keep alternative scenarios live as public insurance mechanism reforms and AI diagnostic algorithm validation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Spain Digital X-Ray Market