
 MRI Ferromagnetic Detection Systems Market | 2026-2036
MRI Ferromagnetic Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Ferromagnetic Detection Systems Market Analytics
Direct distribution to hospital procurement departments is rewriting how MRI ferromagnetic detection systems reach end users. Kopp Development leverages its longstanding relationships with major academic medical centers to sustain repeat installations. Metrasens anchors the European channel through specialized MRI safety distributors. ETS-Lindgren competes on electromagnetic compatibility integration, extending its reach into hybrid imaging suites.
MRI ferromagnetic detection systems are active safety instruments that identify ferromagnetic materials through magneto-optical or induction sensing before they enter the MRI suite's fringe field, typically operating at detection thresholds measured in millitesla. These systems prevent projectile incidents, protect superconducting magnets from quench events, and preserve operational uptime in high-throughput imaging departments. Floor-mounted systems dominate installed base due to their fixed-position reliability at suite entry points, while handheld devices represent the fastest-expanding segment as point-of-care screening protocols proliferate in outpatient settings. Magneto-optical sensors capture the premium tier of the technology split, with induction sensors occupying cost-sensitive hospital budgets.
The U.S. FDA's MRI safety labeling requirements, the EU Medical Device Regulation's Class IIa designation for ferromagnetic detectors, and Joint Commission accreditation standards collectively mandate systematic screening in accredited imaging facilities. These frameworks elevate compliance from voluntary best practice to enforceable condition of operation, directly expanding replacement cycles and first-time purchases. Stakeholders must monitor how evolving IEC 60601 electromagnetic compatibility standards reshape sensor architecture and certification timelines.
Market Dynamics
The Joint Commission's accreditation standards for MRI safety screening have transformed voluntary protocols into operational mandates, forcing imaging departments to upgrade detection infrastructure or risk credential suspension.
Growth Catalysts
- EU Medical Device Regulation Class IIa:The MDR designation elevates ferromagnetic detectors to regulated medical devices, accelerating replacement cycles as hospitals seek certified systems for compliance audits.
- Magneto-optical sensing:This detection modality delivers millitesla-level precision at suite entry points, driving premium adoption in academic medical centers with high-field 3T and 7T installations.
- Outpatient imaging proliferation:Freestanding diagnostic centers in the United States are deploying handheld screening devices to maintain throughput without dedicated MRI technologists at every entry.
Market Restraints
- Superconducting magnet quench costs:The catastrophic financial exposure from helium loss creates risk-averse procurement committees that delay detector investments until capital cycles align.
- Induction sensor commoditization:Cost-sensitive hospital budgets gravitate toward lower-threshold induction systems, compressing margins for advanced magneto-optical manufacturers.
- Installation footprint constraints:Retrofitting floor-mounted systems into existing MRI suite architecture requires structural modifications that extend project timelines and inflate total cost of ownership.
Strategic Opportunities
- Hybrid imaging suites:PET-MRI and intraoperative MRI installations create demand for multi-zone detection networks that coordinate screening across adjacent procedure rooms.
- Japan's aging infrastructure base:The country's extensive installed MRI fleet predates modern safety protocols, presenting upgrade potential as METI guidelines tighten enforcement.
- Remote monitoring integration:Cloud-connected detectors that stream screening logs directly to hospital safety officers are displacing manual documentation workflows in large health systems.
Industry Challenges
- IEC 60601-1-2 electromagnetic compatibility:Evolving immunity test levels for radiated disturbances force sensor architecture redesigns that extend certification timelines by 12-18 months.
- Biomedical engineering talent scarcity:Hospitals lack personnel trained to calibrate detection thresholds against fringe field mapping, creating service dependency on original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Ferromagnetic Detection Systems Market |
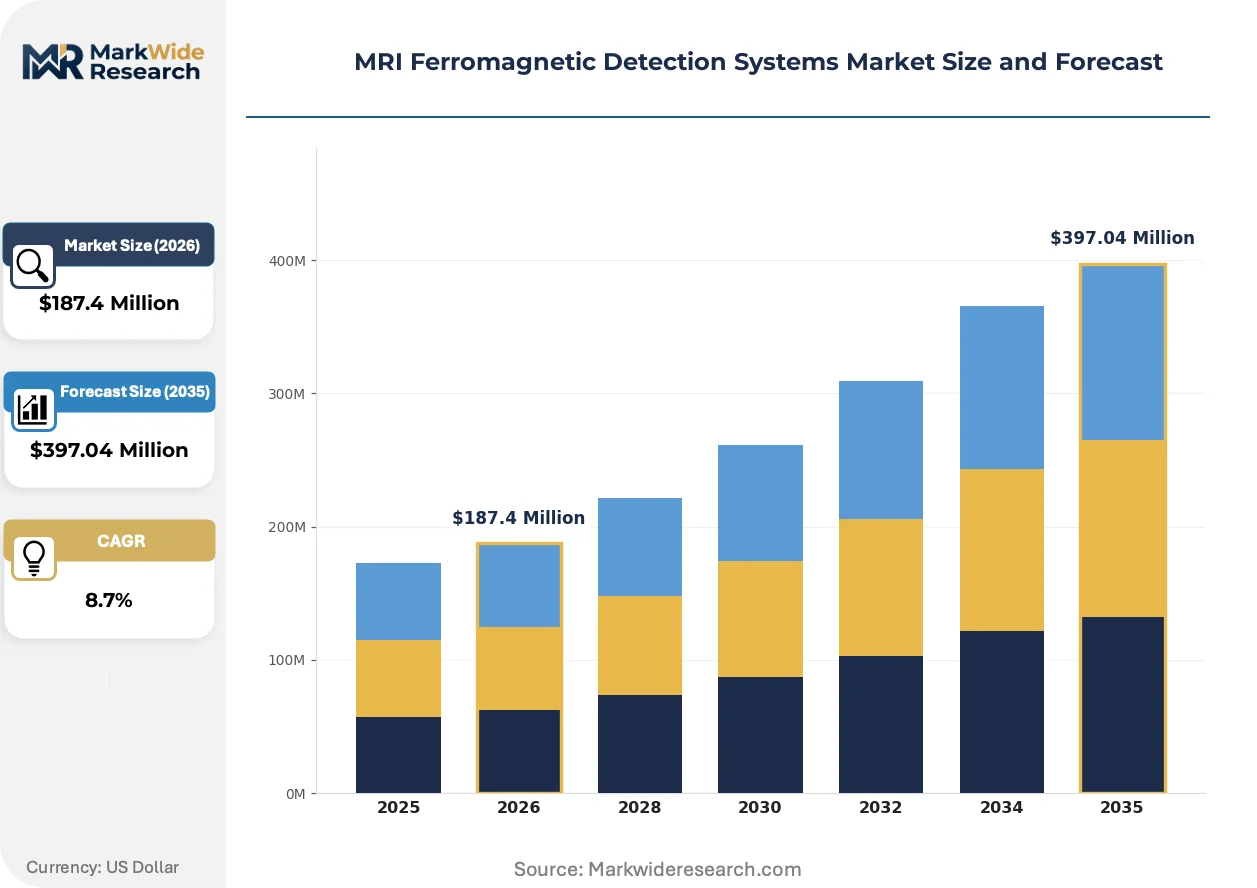
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor-mounted Systems, Handheld Devices, Wall-mounted Units, Portable Scanners End User: Hospitals, Research Institutions, Diagnostic Centers, Outpatient Clinics Technology: Magneto-optical Sensors, Induction Sensors, RFID Systems, Infrared Readers Application: Patient Safety, Equipment Screening, Research Applications, Incident Management |
| Companies Covered | Kopp Development, Metrasens, ETS-Lindgren, C.E.I.A., ITEL Telecomunicazioni, Magmedix, Bio-x, Fujidenolo, Nanjing Cloud Magnet Electronics Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Ferromagnetic Detection Systems Market Evolving Landscape
Detection technology is converging with hospital information systems, creating screening workflows that generate auditable safety records rather than standalone alerts.
Artificial intelligence-enhanced false-positive filtering is collapsing the operational burden on MRI technologists who previously manually verified every detector alarm. Outpatient imaging chains in Germany are deploying these systems to maintain patient flow without additional staffing. The compression of alarm fatigue is enabling same-day scheduling volumes that unfiltered systems cannot support.
The FDA's updated MRI safety guidance now explicitly references ferromagnetic detection as a component of facility risk management, triggering documentation overhauls at US imaging centers. Joint Commission surveyors are citing facilities that lack systematic screening protocols during accreditation visits. Academic medical centers are responding by consolidating vendor relationships to ensure end-to-end compliance documentation.
Point-of-care screening protocols are fragmenting procurement authority away from centralized biomedical engineering departments. Individual MRI suite managers in US hospital systems now specify handheld devices for satellite clinics without corporate approval. This decentralization is most visible in multi-site radiology groups operating across state lines where standardization previously dominated capital planning.
MRI Ferromagnetic Detection Systems Market Segmentation
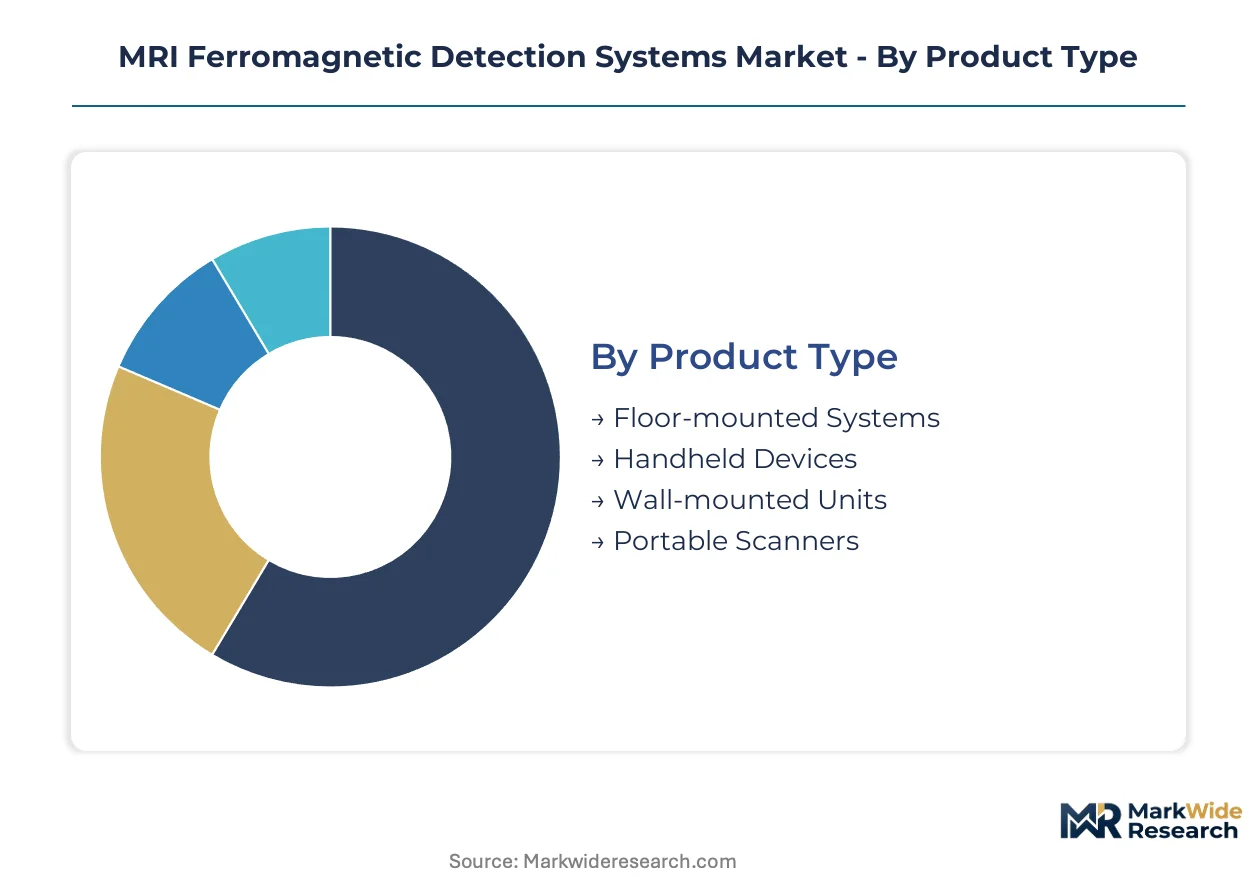
MRI ferromagnetic detection systems fragment across four critical dimensions that determine procurement authority, installation complexity, and compliance documentation requirements. Hospital capital committees evaluate these segments against Joint Commission audit criteria, imaging suite throughput targets, and total cost of ownership calculations.
Product Type:
Fixed-position systems anchor high-throughput hospital workflows, while mobile alternatives address satellite clinic constraints and retrofit scenarios.
- Floor-mounted Systems:Permanent installations at MRI suite entry points deliver millitesla-level detection thresholds with minimal calibration drift. Academic medical centers in the United States specify these for 3T and 7T installations where projectile prevention is non-negotiable.
- Handheld Devices:Battery-powered units enable point-of-care screening in outpatient settings without dedicated MRI technologists. Diagnostic centers across Germany deploy these to maintain patient flow across multiple imaging rooms.
- Wall-mounted Units:Space-constrained retrofit installations favor these units where floor penetration or structural reinforcement is prohibitive.
- Portable Scanners:Temporary deployments for mobile MRI trailers and construction-phase screening.
The dominant share belongs to Floor-mounted Systems, while Handheld Devices are closing the gap fastest.
End User:
Procurement sophistication varies sharply across customer types, with research institutions demanding custom integration and outpatient clinics prioritizing operational simplicity.
- Hospitals:Integrated health systems in Japan consolidate vendor relationships to streamline Joint Commission documentation and METI compliance audits across multiple MRI suites.
- Research Institutions:University imaging centers require detection networks that interface with experimental protocols and multi-zone safety systems for 7T research magnets.
- Diagnostic Centers:Freestanding imaging chains in the United States prioritize throughput-optimized handheld screening to maximize same-day appointment volumes.
- Outpatient Clinics:Satellite facilities delegate procurement authority to individual suite managers, fragmenting standardization.
Hospitals command the largest installed base, though Diagnostic Centers are expanding most quickly as outpatient imaging proliferates.
Technology:
Sensor architecture determines detection precision, calibration frequency, and electromagnetic compatibility certification complexity under evolving IEC standards.
- Magneto-optical Sensors:Polarization-based detection achieves sub-millitesla resolution for high-field MRI environments. Premium-tier academic centers absorb the cost premium to eliminate false negatives.
- Induction Sensors:Coil-based detection occupies cost-sensitive hospital budgets with acceptable thresholds for standard 1.5T installations.
- RFID Systems:Tagged inventory tracking extends screening to implanted devices and surgical equipment.
- Infrared Readers:Thermal signature verification supplements primary detection in hybrid imaging suites.
Magneto-optical Sensors retain the premium tier, while Induction Sensors capture volume share through budget-conscious procurement.
Application:
Functional use cases determine sensor placement, alert protocols, and integration depth with hospital information systems.
- Patient Safety:Pre-screening workflows prevent projectile incidents from concealed ferromagnetic objects. FDA guidance now explicitly references systematic detection as a risk management component.
- Equipment Screening:Incoming surgical tools, wheelchairs, and maintenance equipment require verification before fringe field entry.
- Research Applications:Experimental protocols in 7T environments demand detection networks with customizable threshold mapping.
- Incident Management:Post-event documentation and root-cause analysis leverage screening logs for liability protection.
Patient Safety drives the majority of installations, with Equipment Screening gaining priority as hybrid imaging suites proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical technology logistics corridor underwrites Germany's central role in European MRI safety equipment distribution, channeling precision instrumentation to imaging centers across the continent.
United States
The FDA's updated MRI safety guidance explicitly references ferromagnetic detection as a risk management component, triggering documentation overhauls at imaging centers nationwide. Johns Hopkins Medicine in Baltimore and the Mayo Clinic in Rochester anchor procurement demand for high-field 3T and 7T installations. The Joint Commission's accreditation standards have transformed voluntary screening protocols into operational mandates, forcing upgrade cycles across integrated health systems.
Germany
The EU Medical Device Regulation's Class IIa designation elevates ferromagnetic detectors to regulated medical devices, accelerating replacement cycles as hospitals seek certified systems for compliance audits. Heidelberg University Hospital and Charité Berlin drive specification demand for magneto-optical precision in research-intensive environments. The country's national pharmaceutical regulator enforces systematic documentation requirements that favor integrated vendor relationships.
Japan
METI guidelines tightening enforcement across Japan's aging MRI infrastructure base present substantial upgrade potential as safety protocols modernize. The University of Tokyo Hospital and Osaka University Hospital anchor demand for detection networks compatible with 7T research magnets. Japan's extensive installed fleet predates contemporary screening standards, creating replacement urgency as regulatory inspections intensify.
United Kingdom
The Medicines and Healthcare products Regulatory Agency enforces EU-legacy device standards through post-Brexit transitional frameworks, maintaining certification rigor for hospital procurement committees. Imperial College Healthcare NHS Trust and Guy's and St Thomas' NHS Foundation Trust specify multi-zone detection networks for hybrid imaging suites. London's concentration of academic medical centers drives premium-tier adoption of polarization-based sensing technology.
China
The National Medical Products Administration's strengthening device classification standards reshape import requirements for foreign detection system manufacturers. Peking Union Medical College Hospital and Fudan University Shanghai Cancer Center anchor demand in high-field imaging corridors. Shanghai's Yangtze River Delta medical device cluster concentrates distribution logistics for domestic and international suppliers.
MRI Ferromagnetic Detection Systems Market Competitive Landscape
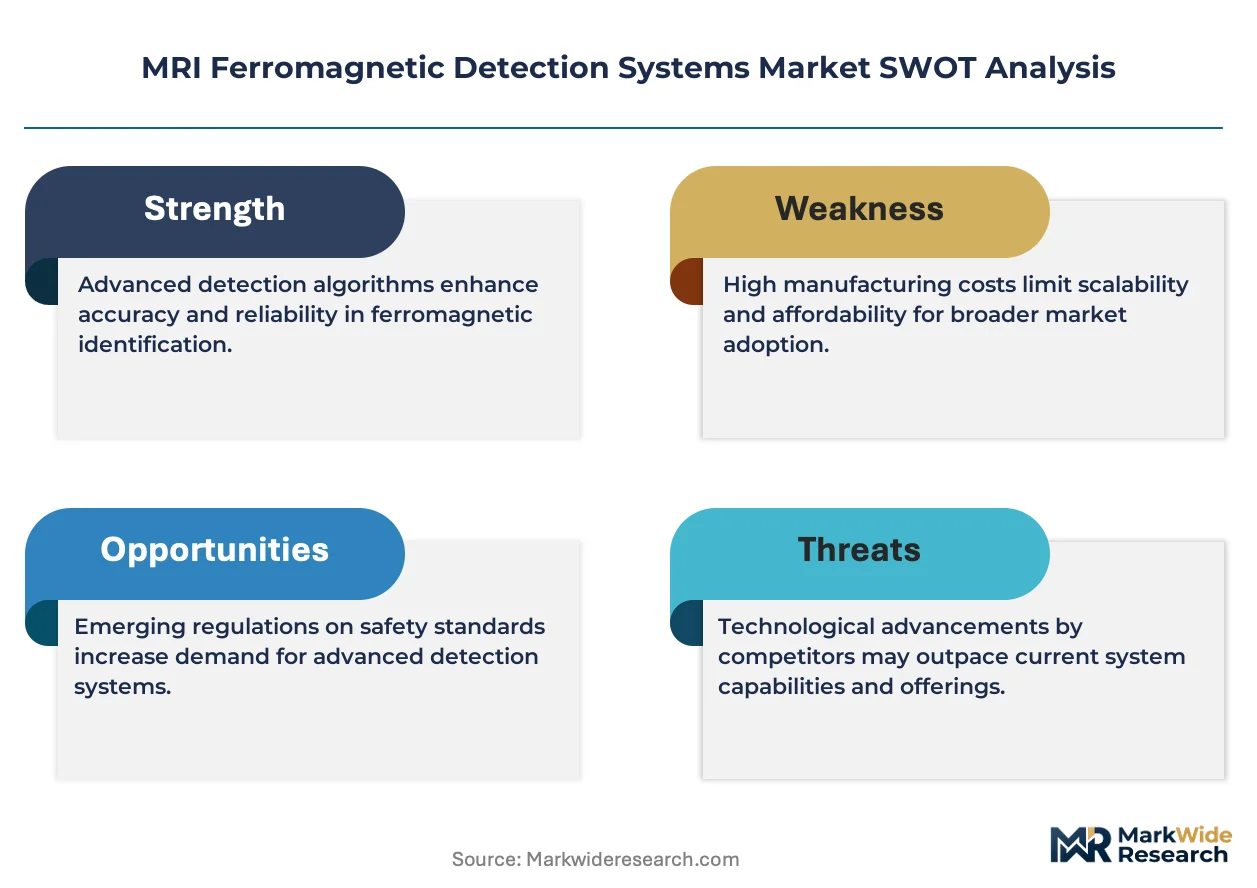
On the supply side, the industry is moderately concentrated with tiered specialization across technology modalities and geographic reach. Three strategic archetypes dominate: magneto-optical precision specialists serving academic medical centers, induction sensor manufacturers occupying cost-sensitive hospital budgets, and electromagnetic compatibility integrators targeting hybrid imaging environments. Competitive dynamics center on certification timeline acceleration and strategic partnerships with MRI original equipment manufacturers for co-development of suite-integrated detection networks.
Within the established specialist tier, Kopp Development exemplifies longstanding academic medical center relationships that sustain repeat installations, while Metrasens anchors European market access through specialized MRI safety distribution channels. ETS-Lindgren occupies a position emphasizing electromagnetic compatibility integration that extends naturally into hybrid PET-MRI and intraoperative MRI installations. These three entities represent distinct competitive vectors—direct institutional relationships, regional channel control, and technical integration capability—that shape procurement committee evaluations across hospital systems.
| Leading Market Players |
|---|
| Kopp Development |
| Metrasens |
| ETS-Lindgren |
| C.E.I.A. |
| ITEL Telecomunicazioni |
| Magmedix |
| Bio-x |
| Fujidenolo |
| Nanjing Cloud Magnet Electronics Technology |
| Others |
Value Network & Pricing Analysis
The Port of Hamburg's medical technology logistics corridor channels precision instrumentation from German manufacturers to imaging centers across Europe, with freight cost volatility feeding directly into magneto-optical sensor pricing premiums and compressing margins for induction-based alternatives in budget-sensitive hospital procurement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with magneto-optical systems commanding premium positioning through FDA 510(k) certification tiers and IEC 60601-1-2 electromagnetic compatibility validation. Price differentiation hinges on detection threshold precision and after-sales calibration service bundling. Cost compression in the induction sensor tier is intensifying because Chinese manufacturers are expanding export capacity. Diagnostic centers in outpatient settings exhibit the highest price sensitivity, while academic medical centers with 7T installations absorb premium tier costs to eliminate false-negative liability exposure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for ferrite core suppliers and magneto-optical polarization components. Manufacturing concentrates in Germany, Japan, and the United States for precision sensor assemblies, with China expanding capacity in induction coil production. Raw material dependencies draw from rare-earth magnet suppliers, specialized optical glass foundries, and semiconductor-grade Hall effect sensors. Single-source vulnerability persists for sub-millitesla calibration reference standards. Distribution runs through specialized MRI safety distributors in Europe and direct hospital procurement relationships in North American integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from remote monitoring subscriptions and annual calibration contracts is expanding faster than hardware unit sales, transforming capital equipment vendors into recurring-revenue platforms.
For Market Incumbents: Build switching-cost moats through cloud-connected detection networks that embed patient screening logs directly into hospital information systems. Consolidate certification investment across IEC 60601-1-2 and EU MDR Class IIa pathways to accelerate audit readiness. Defensive capacity expansion in Japan addresses METI enforcement tightening across aging MRI infrastructure. For New Entrants and Emerging Players: Handheld device procurement authority fragmenting to individual MRI suite managers in US multi-site radiology groups represents the most penetrable entry point. Outpatient imaging chains in Germany seeking throughput-optimized screening without dedicated technologist staffing offer secondary white-space. Channel partnership with specialized MRI safety distributors accelerates European market access without direct hospital selling infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electromagnetic compatibility testing conglomerates seeking to monetize non-core medical device detection divisions. Long-term viability centers on software companion revenue multiples exceeding hardware trading valuations. Watch Joint Commission citation frequency for facilities lacking systematic screening protocols as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa compliance accelerates hospital audit readiness across German imaging centers. |
| Hospital System Partnership | Johns Hopkins Medicine and Mayo Clinic anchor demand for integrated detection networks in 7T suites. |
| Software Companion Development | AI-enhanced false-positive filtering collapses operational burden on MRI technologists in outpatient chains. |
| Reimbursement Strategy | Joint Commission accreditation standards elevate detection infrastructure to operational mandate status. |
| Backward Integration | In-house production of magneto-optical polarization components secures supply against ferrite core tariff exposure. |
Research Methodology
The analysis maps magneto-optical sensor architectures, induction detection systems, handheld portable units, and floor-mounted permanent installations, each validated through biomedical engineering directors, hospital procurement committee chairs, MRI safety officers, and GPO contracts managers. Primary interview intelligence triangulates against FDA 510(k) device listings, EU MDR notified body certification databases, Joint Commission accreditation survey reports, and hospital capital expenditure disclosures. Secondary validation draws from customs trade data for electromagnetic sensor components and SEC filings of publicly traded medical device distributors. Bottom-up unit economics and top-down imaging suite installation rates converge through iterative reconciliation.
Fixed assumptions across the projection horizon include sustained Joint Commission enforcement of MRI safety screening mandates, continued EU MDR Class IIa classification for ferromagnetic detectors, and stable helium pricing for superconducting magnet operations. Segmentation dimensions modeled span product type, sensor technology, end-user facility category, and field strength compatibility tier. CAGR derivation rests on replacement cycle analysis for aging installed base and first-purchase penetration in outpatient imaging expansion. Forecast inputs incorporate METI guideline enforcement intensity in Japan and FDA guidance documentation revision frequency.
Macroeconomic conditions sit as an overlay; deviation in hospital capital budget cycles, medical device tariff schedules, or rare-earth magnet pricing would shift the trajectory. Forecasts reflect documented assumptions without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
US Imaging Services Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Global Super Resolution Microscopes Market