
 Myocardial Ischemia Market | 2026-2036
Myocardial Ischemia Market Size, Share, and Industry Trends Forecast 2026-2036
Myocardial Ischemia Market Outlook
Software-enabled remote patient monitoring for post-acute ischemia management is restructuring how cardiac care contracts are priced and renewed. Merck leverages its antiplatelet R&D pipeline to sustain differentiation in oral therapy segments. Boston Scientific anchors North American device markets through specialized stent and balloon catheter portfolios. Novartis competes on geographic breadth, operating cardiovascular franchises across multiple continental markets.
Myocardial ischemia denotes inadequate oxygen supply to cardiac muscle tissue, typically arising from coronary artery stenosis or occlusion, with functional parameters measured by ST-segment deviation, troponin elevation, and fractional flow reserve thresholds below 0.80. Its primary purpose is clinical: restoring perfusion limits myocardial necrosis, preserves ejection fraction, and reduces subsequent heart failure incidence. Antiplatelet drugs command the largest revenue pool among product types due to chronic administration protocols and broad post-intervention indications. Hospitals dominate end-user value capture, though cardiac rehabilitation centers represent the fastest-growing site of care as payors shift toward bundled recovery episodes.
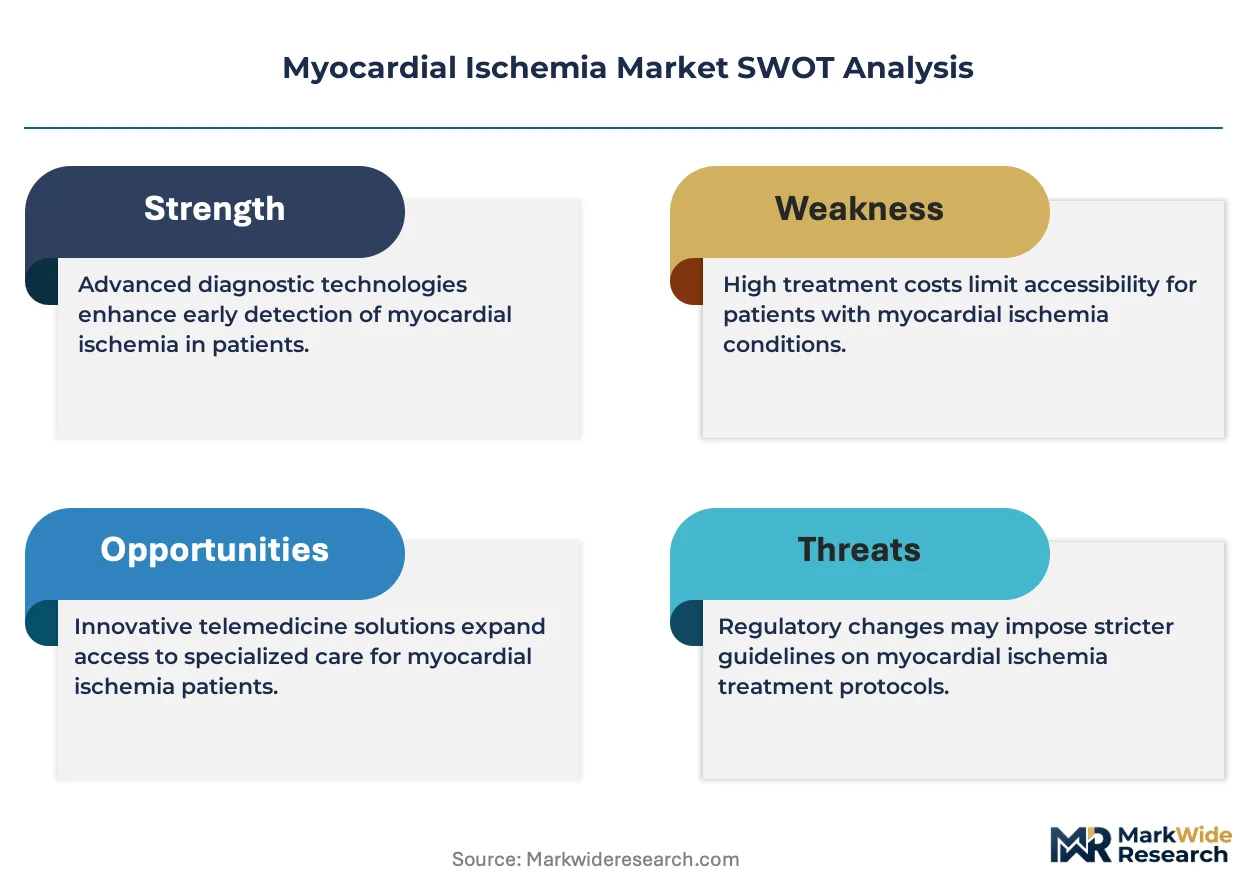
FDA, EMA, and Japan's PMDA collectively govern market access through divergent evidentiary standards for stent biocompatibility and antiplatelet bleeding-risk profiles, creating fragmented registration timelines that shape regional launch sequencing. The EU MDR and FDA's updated 510(k) predicate rules are forcing device manufacturers toward larger prospective registries. Stakeholders must monitor how decentralized clinical trial frameworks and real-world evidence mandates reshape competitive moats between pharmaceutical and interventional device paradigms.
Market Dynamics
Software-enabled remote patient monitoring is restructuring cardiac care contracting by enabling continuous post-intervention surveillance outside traditional hospital settings. This shift compresses episode-based reimbursement timelines and forces device and pharmaceutical suppliers to integrate digital endpoints into value demonstrations.
Growth Catalysts
- Breakthrough Device Designation:FDA's expedited pathway accelerates market access for novel antiplatelet and revascularization technologies, compressing traditional 18-month review cycles.
- Aging Cath Lab Infrastructure:Established networks in Germany, Japan, and the United States sustain high procedural volumes for minimally invasive coronary interventions.
- EMA Adaptive Pathway:Conditional approval frameworks enable earlier patient access to ischemia therapies while generating real-world evidence post-launch.
Market Restraints
- Biocompatibility Testing Burden:EU MDR mandates expanded prospective registries for stent coatings, extending device certification timelines by 12-24 months.
- Antiplatelet Bleeding Risk:EMA and FDA diverge on acceptable bleeding profiles for chronic therapy, forcing parallel clinical programs and duplicated development costs.
- Specialized Interventionalist Scarcity:Concentration of trained operators in tertiary centers limits procedure expansion into community hospital settings.
Strategic Opportunities
- Cardiac Rehabilitation Centers:Bundled recovery episodes create new site-of-care demand for remote monitoring integration and medication adherence programs.
- Fractional Flow Reserve Guidance:Physiology-guided PCI using pressure wire technology enables more precise lesion selection and reduces unnecessary stent deployment.
- Japan PMDA Sakigake:Priority review designation for innovative ischemia diagnostics accelerates commercialization timelines in the world's second-largest device market.
Industry Challenges
- Real-World Evidence Infrastructure:Decentralized trial frameworks require sponsors to build direct-to-patient data collection capabilities outside traditional site networks.
- Legacy EHR Integration:Remote monitoring platforms face interoperability barriers with hospital information systems, delaying deployment and complicating workflow adoption.
- Dual Certification Complexity:Manufacturers must maintain parallel quality systems for FDA 510(k) predicate rules and EU MDR technical documentation, inflating regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myocardial Ischemia Market |
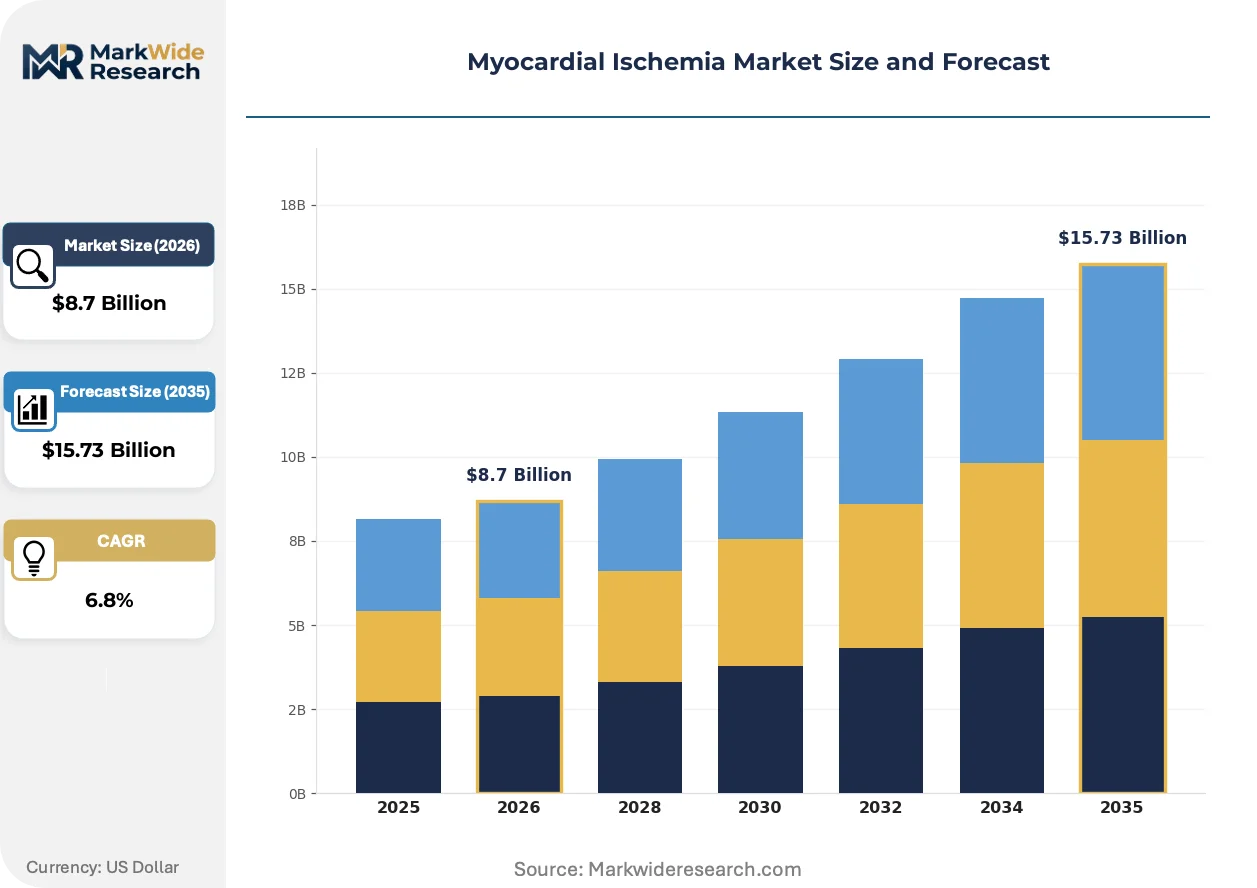
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angioplasty Balloons, Stents, Antiplatelet Drugs, Beta Blockers End User: Hospitals, Clinics, Cardiac Rehabilitation Centers, Homecare Settings Therapy Area: Coronary Artery Disease, Heart Failure, Hypertension, arrhythmias Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal |
| Companies Covered | Merck, Boehringer Ingelheim, Pfizer, Daiichi Sankyo, Bayer, AstraZeneca, Johnson & Johnson, Boston Scientific, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myocardial Ischemia Market Strategic Shifts
Artificial intelligence interpretation of electrocardiographic signals is compressing ischemia detection timelines from hours to minutes. This capability is redrawing competitive boundaries between diagnostic device manufacturers and digital health platforms.
Machine learning algorithms applied to continuous ECG streams are automating ST-segment deviation detection in ambulatory and emergency settings. Hospital systems and emergency medical services in the United States are piloting these tools to accelerate triage decisions. The technology is automating the initial diagnostic layer, reducing reliance on specialist over-read and enabling earlier catheterization lab activation.
EU MDR's updated clinical evidence requirements for implantable devices are forcing manufacturers toward larger post-market surveillance cohorts. Stent manufacturers must now demonstrate sustained safety profiles across diverse patient populations to maintain CE marking. High-risk device categories face the steepest compliance burden, with notified bodies demanding extended follow-up data before renewal.
Buyers are consolidating cardiovascular service line procurement under centralized value analysis committees. Individual catheterization laboratories lose autonomous purchasing authority as health systems standardize across stent, balloon, and pressure wire portfolios. This concentration is most pronounced in United States integrated delivery networks, where annual vendor negotiations now cover entire device categories rather than individual SKUs.
Myocardial Ischemia Market Segmentation
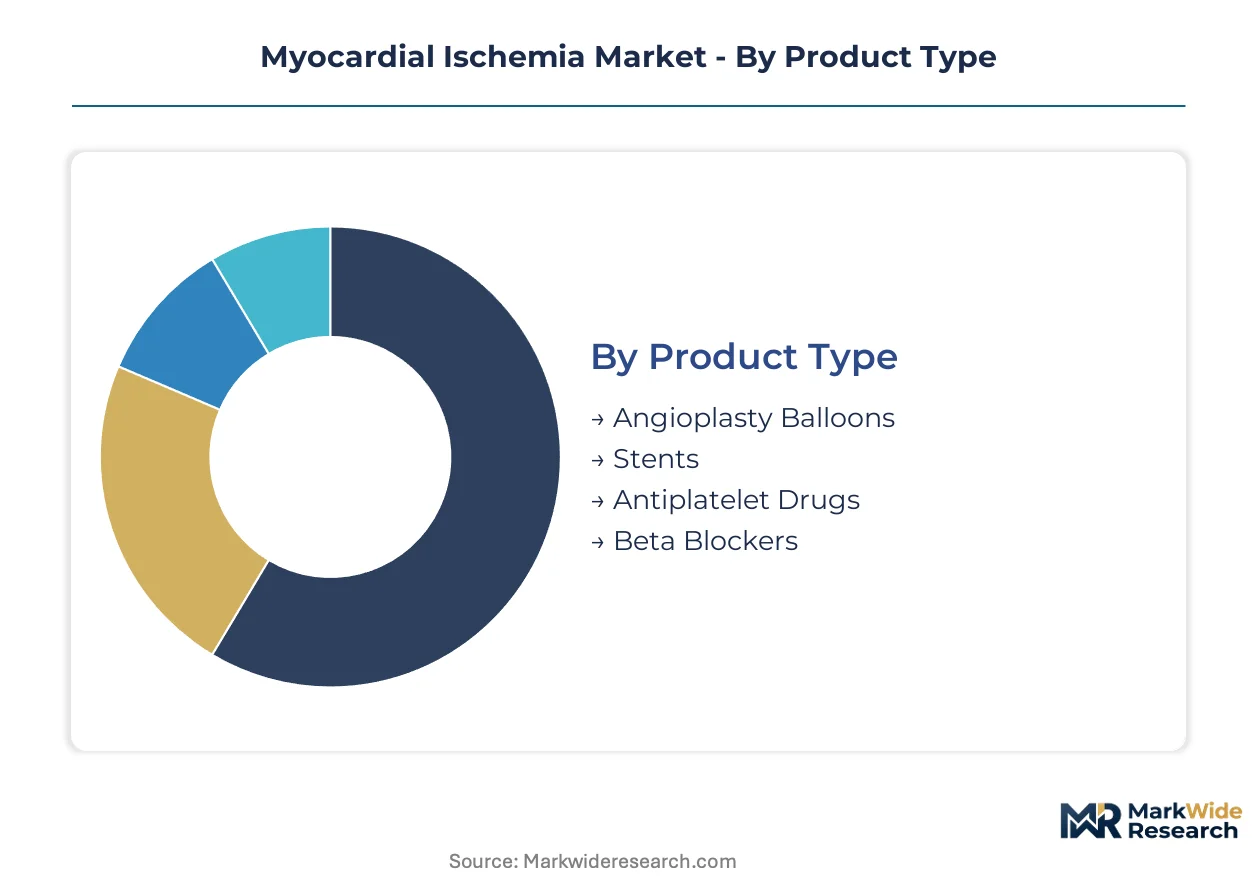
Segmentation in myocardial ischemia reveals divergent regulatory pathways and site-of-care economics that reshape vendor go-to-market strategies. Each dimension carries distinct certification burdens, reimbursement codes, and clinical workflow requirements.
Product Type:
FDA 510(k) predicates govern device segments, while antiplatelet therapies face NDA/BLA review cycles and REMS requirements for bleeding-risk mitigation.
- Antiplatelet Drugs:Chronic oral administration protocols generate recurring revenue streams across post-PCI and medical management populations. Demand concentrates in United States hospital formularies and Japanese outpatient cardiology practices, where payor contracts favor generic substitutions that compress originator margins.
- Stents:Drug-eluting and bare-metal platforms require biocompatibility dossiers under EU MDR and Japan PMDA Sakigake pathways. German cath labs and United States integrated delivery networks drive volume through bundled PCI reimbursement structures.
- Angioplasty Balloons:Semi-compliant and non-compliant balloon catheters face predicate-device comparisons for FDA clearance.
- Beta Blockers:Post-infarction secondary prevention protocols sustain demand in generic-dominated markets.
Leading the category by volume: Antiplatelet Drugs. Growing fastest: Stents.
End User:
Site-of-care migration from inpatient to ambulatory settings restructures procurement authority and technology requirements across customer types.
- Hospitals:Tertiary centers with 24/7 cath lab activation capability capture high-acuity STEMI cases and complex multivessel interventions. United States academic medical centers and Japanese university hospitals anchor procedural volume through specialized interventionalist staffing.
- Cardiac Rehabilitation Centers:Bundled recovery episodes create new demand for remote monitoring integration and medication adherence programs. German post-acute networks and United States outpatient cardiac rehab facilities expand fastest under episode-based payment models.
- Clinics:Community-based cardiology practices focus on stable ischemia diagnosis and medical management referrals.
- Homecare Settings:Remote patient monitoring platforms enable post-discharge surveillance outside traditional facilities.
Revenue concentrates in Hospitals. Steepest expansion trajectory: Cardiac Rehabilitation Centers.
Therapy Area:
Clinical indication determines trial design complexity and label expansion potential across cardiovascular disease states.
- Coronary Artery Disease:Stable angina and acute coronary syndrome indications drive the majority of revascularization procedures and chronic pharmaceutical prescribing. United States and German patient populations sustain trial enrollment for novel antiplatelet and device studies.
- Heart Failure:Ischemic cardiomyopathy sequelae create crossover demand for device and pharmaceutical interventions. Japanese geriatric populations and United States Medicare beneficiaries expand addressable populations for combined ischemia-heart failure protocols.
- Hypertension:Comorbid management influences antihypertensive co-prescribing patterns with ischemia therapies.
- Arrhythmias:Ischemia-triggered electrical instability requires coordinated electrophysiology and interventional cardiology workflows.
Coronary Artery Disease dominates procedure and prescription volume. Heart Failure exhibits the fastest clinical trial expansion.
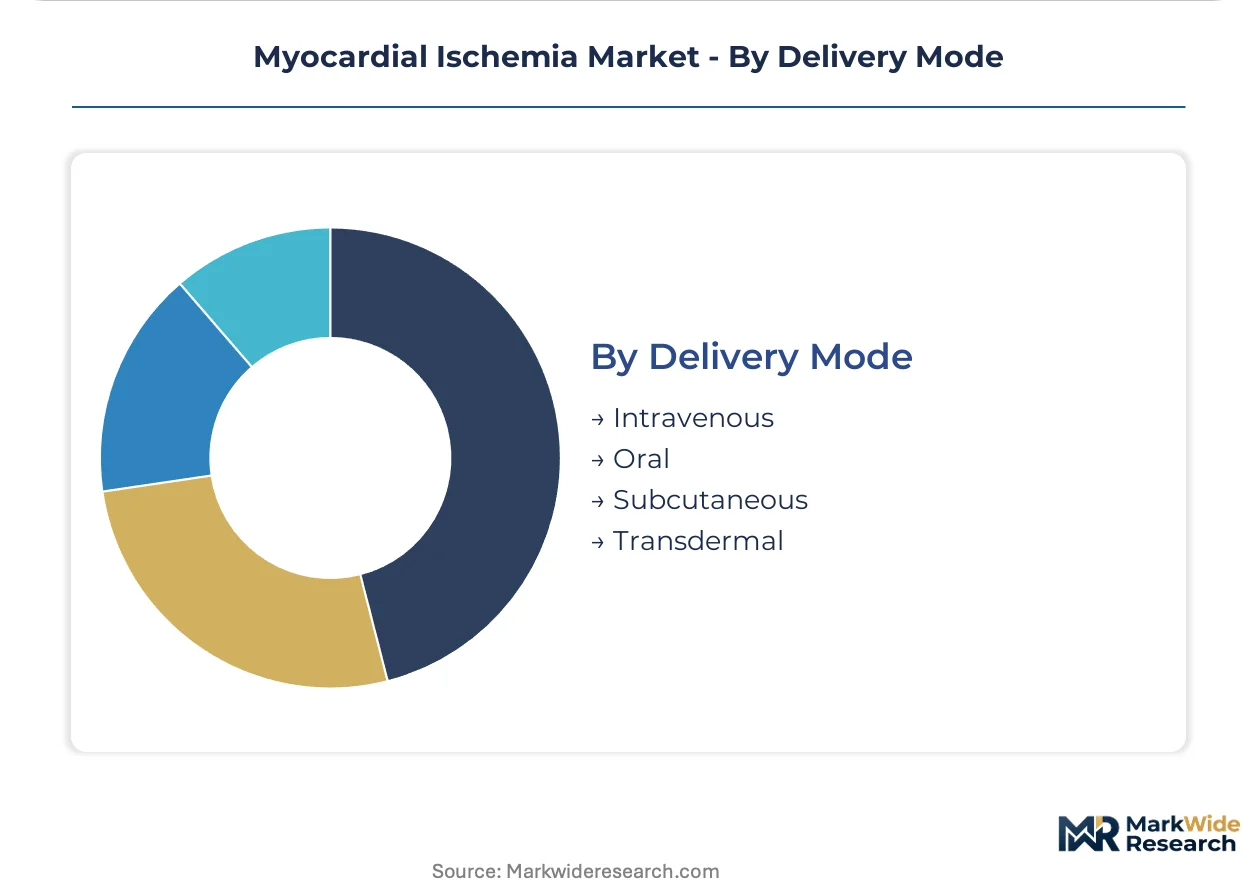
Delivery Mode:
Route of administration shapes manufacturing complexity, cold chain requirements, and patient compliance monitoring infrastructure.
- Oral:Antiplatelet and beta-blocker tablets enable outpatient chronic administration with established generic substitution dynamics. United States pharmacy benefit managers and Japanese National Health Insurance reimbursement tiers determine formulary placement and patient out-of-pocket exposure.
- Intravenous:Cath lab-administered anticoagulants and glycoprotein inhibitors require hospital-based infusion capability. German and United States tertiary centers sustain demand through PCI procedural bundles.
- Subcutaneous:Self-injection formulations for anticoagulation bridge therapy face patient training and adherence challenges.
- Transdermal:Nitrate patches for angina prophylaxis compete with oral formulations on convenience and efficacy endpoints.
Oral delivery commands the largest patient-day volume. Intravenous routes capture the highest per-procedure revenue intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors North American myocardial ischemia innovation through dense concentrations of interventional cardiology research centers and FDA premarket review proximity.
United States
Cleveland Clinic and Mayo Clinic cath labs drive adoption of fractional flow reserve-guided PCI protocols. FDA breakthrough device designations compress review timelines for novel stent platforms. The Texas Medical Center in Houston sustains among the highest annual PCI volumes globally, anchoring device trial enrollment.
Germany
Heidelberg and Munich university hospitals maintain Europe's densest networks of 24/7 STEMI activation centers. EMA adaptive pathway frameworks enable conditional approvals for antiplatelet therapies with real-world evidence generation mandates. The Rhine-Main metropolitan region concentrates medical device engineering talent for catheter and pressure wire manufacturing.
Japan
Tokyo and Osaka academic medical centers generate substantial procedure volume for complex multivessel interventions. PMDA Sakigake priority review accelerates commercialization timelines for innovative ischemia diagnostics. The Kobe biomedical cluster hosts concentrated stent coating research facilities serving domestic and export markets.
Switzerland
Basel anchors European pharmaceutical cardiology R&D through integrated discovery-to-commercialization infrastructure. Swissmedic maintains alignment with EMA standards while offering streamlined review for devices with prior CE marking. The Lake Geneva region concentrates contract research organizations supporting decentralized clinical trial execution.
United Kingdom
London teaching hospitals pilot AI-enabled ECG interpretation for emergency department triage acceleration. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for software-as-medical-device platforms. The Oxford-Cambridge arc sustains cardiovascular imaging research clusters advancing perfusion assessment technologies.
Myocardial Ischemia Market Competitive Environment
Capital-heavy device manufacturers compete with asset-light pharmaceutical developers across divergent regulatory and reimbursement pathways. The market structures around three tiers: integrated conglomerates with dual pharmaceutical-device portfolios, specialized interventional device pure-plays, and generic-focused oral therapy suppliers. Consolidation concentrates procurement leverage among United States integrated delivery networks and German hospital alliances. Strategic moves center on digital health integration partnerships and real-world evidence generation infrastructure.
Among pharmaceutical-centric developers, Merck and Novartis occupy positions emphasizing chronic oral therapy portfolios and geographic breadth across continental markets. Boston Scientific anchors the device-specialist archetype within North American markets. These three exemplify divergent competitive positioning: Merck represents antiplatelet R&D concentration, Novartis illustrates multi-market cardiovascular franchise operations, and Boston Scientific demonstrates interventional technology portfolio depth.
| Leading Market Players |
|---|
| Merck |
| Boehringer Ingelheim |
| Pfizer |
| Daiichi Sankyo |
| Bayer |
| AstraZeneca |
| Johnson & Johnson |
| Boston Scientific |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
EU MDR biocompatibility dossiers and FDA 510(k) predicate rules gate qualified supply for drug-eluting stents and antiplatelet therapies, with premium-tier pricing access reserved for manufacturers maintaining dual certification infrastructure across both jurisdictions. This regulatory moat compresses margins for mid-tier suppliers while originators command sustained price premiums through demonstrated safety profiles.
Pricing Analysis
Episode-based reimbursement anchors value-based pricing for PCI procedures and post-intervention pharmaceutical protocols. Three-tier pricing structure across premium, standard, and economy levels separates originator antiplatelet therapies from authorized generics and commodity beta-blockers. Cost compression in generic oral therapy tiers intensifies because pharmacy benefit manager formulary exclusions squeeze originator volumes. United States integrated delivery networks exhibit highest price sensitivity through centralized value analysis committees, while Japanese National Health Insurance reimbursement tiers favor originator retention for bleeding-risk-sensitive populations.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States maintain hub-and-spoke patterns for stent and catheter inventory positioning near tertiary cath lab clusters. Manufacturing concentration rests on Ireland and Puerto Rico for sterile device finishing, with active pharmaceutical ingredient synthesis anchored in India and Italy. Single-source vulnerability runs through specialized nitinol wire suppliers serving balloon catheter and pressure wire platforms. Distribution runs through hospital system GPO contracts and cardiac rehabilitation center direct agreements for remote monitoring hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized interventionalist scarcity props pricing power for procedure-capable centers, creating supply-constrained access to complex multivessel interventions that sustains premium reimbursement rates.
For Market Incumbents: Acquire remote patient monitoring platforms to bundle digital endpoints into cardiac rehabilitation contracts. Boston Scientific and Abbott must defend against software-enabled diagnostic displacement by integrating AI-ECG interpretation into existing cath lab workflows. Capacity addition in German and Japanese STEMI activation centers reinforces procedural volume capture against emerging Asian manufacturers. For New Entrants and Emerging Players: Capture cardiac rehabilitation center site-of-care migration through medication adherence program partnerships. United States outpatient bundled payment models offer the most penetrable entry point for digital health platforms lacking 510(k) predicate device heritage. Go-to-market execution hinges on EHR interoperability demonstrations with Epic and Cerner hospital networks. For Investors and Strategic Acquirers: FDA breakthrough device designation awards are the leading indicator that novel antiplatelet or revascularization technologies will achieve compressed commercialization timelines and sustained pricing power. Long-term viability favors platforms spanning pharmaceutical-device boundaries with real-world evidence generation infrastructure. Target acquisition profile centers on mid-cap stent coating specialists with EU MDR technical documentation already filed.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses 18-month cycles for novel stent platforms entering United States cath labs. |
| EU MDR Technical Documentation | Post-market surveillance cohorts satisfy notified body demands for sustained biocompatibility evidence. |
| Hospital System Partnership | GPO contract consolidation in United States IDNs standardizes procurement across entire device categories. |
| Software Companion Development | AI-enabled ECG interpretation automates ST-segment detection for emergency department triage acceleration. |
| Reimbursement Strategy | Episode-based payment models align device and pharmaceutical pricing with bundled recovery outcomes. |
Study Parameters
FDA 510(k) clearance databases, EMA adaptive pathway submissions, and ClinicalTrials.gov enrollment records formed the secondary backbone for device and pharmaceutical pipeline tracking. Primary interviews with interventional cardiologists, cath lab purchasing committee chairs, and pharmacy benefit manager formulary directors combined with secondary validation across hospital procurement databases and GPO contract repositories. Bottom-up procedure volume estimates and top-down pharmaceutical prescription analytics underwent triangulation for segmentation-level consistency.
Historical trendline analysis of PCI procedure volumes and antiplatelet prescription patterns informed baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, end-user site-of-care, therapy area indication, and delivery mode dimensions. CAGRs derived from regression-adjusted growth rates applied to baseline 2026 market valuation. Forecast inputs included aging demographic projections, cath lab infrastructure expansion plans, and regulatory pathway timeline assumptions.
The model holds under stable reimbursement and regulatory pathway conditions; deviation in FDA predicate rule stringency or EMA biocompatibility evidence requirements would shift commercialization timelines and market access sequencing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Stroke Management Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Ischemia Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market