
 Radiology Positioning Aids Market | 2026-2036
Radiology Positioning Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Radiology Positioning Aids Market Insights
European foam molding specialists is realigning capacity toward medical-grade polyurethane cores for radiology tables. Bionix LLC leverages its vertically integrated manufacturing base in Ohio to control domestic supply of CT positioning cradles. Klarity Medical Products anchors its position through dedicated cleanroom production of MRI-safe positioning kits. Elekta AB competes by bundling positioning aids with linear accelerator systems for radiation therapy workflows.
Radiology positioning aids encompass foam, gel, and vacuum-locked devices engineered to immobilize anatomical regions during diagnostic imaging, typically fabricated from viscoelastic memory foam or silicone gel composites with attenuation properties below 0.5 mm aluminum equivalence to preserve image clarity. Spine cushions and head supports command the largest revenue share among product types due to their universal deployment across imaging modalities, while MRI-compatible arm positioners represent the fastest-expanding category as scanner throughput rises and patient safety protocols tighten around ferromagnetic exclusion. X-ray procedures still consume the highest unit volumes of leg positioners, though CT scan applications are pulling premium pricing for multi-axis adjustable systems that reduce retake rates.
FDA 510(k) clearance pathways shape product development timelines for US manufacturers, while the EU MDR transition forces European suppliers to renew technical documentation for CE-marked positioning devices. ISO 13485 certification has become a baseline qualifier for distributor access to hospital procurement frameworks across both jurisdictions. Stakeholders must weigh magnetic compatibility testing investments against the expanding installed base of high-field MRI systems before committing to new material platforms.
Market Dynamics
High-field MRI installations are compressing material specifications for positioning aids, forcing manufacturers to recertify foam cores and gel composites against stricter ferromagnetic thresholds while diagnostic networks consolidate vendor lists.
Growth Catalysts
- EU MDR compliance deadlines:European hospitals are accelerating replacement cycles for legacy positioning devices to meet renewed CE-marking requirements, creating pull-through demand for certified suppliers.
- CT throughput optimization:Radiology departments are prioritizing multi-axis adjustable head supports that reduce retake rates and scanner idle time.
- Silicone gel composites:Advances in low-attenuation gel formulations are expanding deployment across pediatric and bariatric patient segments previously underserved by rigid foam alternatives.
Market Restraints
- Medical-grade polyurethane supply concentration:Foam core production clusters in Germany and Ohio, exposing buyers to regional logistics disruptions and input cost volatility.
- FDA 510(k) timeline friction:Magnetic compatibility testing requirements extend product development cycles by 8-14 months for novel material platforms.
- Vacuum-locked positioning systems:These devices compete directly with traditional foam and gel products in radiation therapy workflows, pressuring pricing for conventional cradles.
Strategic Opportunities
- Japan's aging imaging infrastructure:Hospital networks are modernizing CT suites, creating demand for protocol-standardized positioning kits.
- ISO 13485-certified cleanroom production:Suppliers with dedicated medical manufacturing facilities are capturing preferred vendor status in hospital procurement frameworks.
- MRI-linear accelerator convergence:Positioning aid bundling with radiation therapy systems opens recurring revenue streams through integrated service contracts.
Industry Challenges
- Magnetic compatibility engineering talent:Shortage of specialists capable of validating materials against 3T and 7T field strengths constrains R&D velocity.
- Cleanroom capex requirements:Dedicated production environments for MRI-safe kits demand facility investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiology Positioning Aids Market |
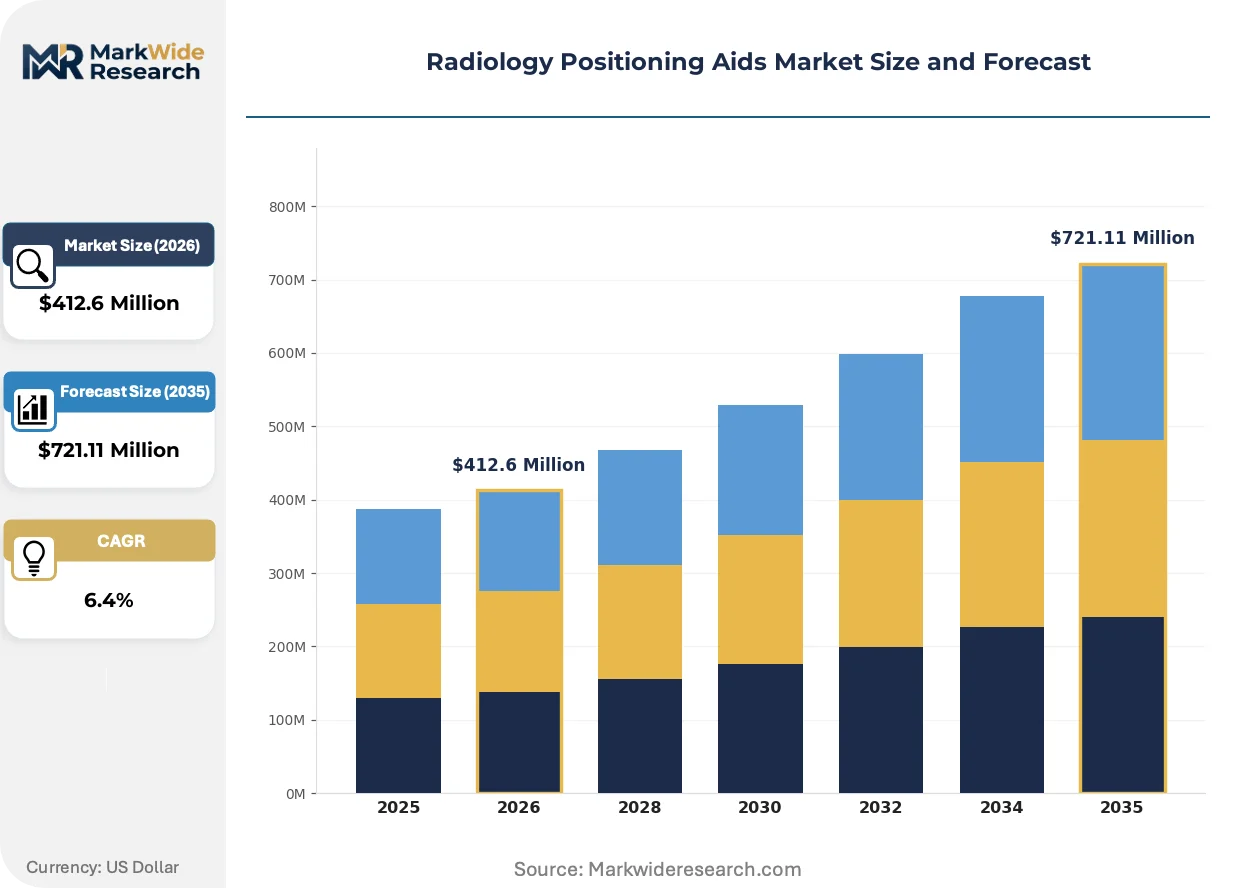
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spine Cushions, Head Supports, Arm Positioners, Leg Positioners Application: X-ray Procedures, CT Scans, MRI Scans, Ultrasound Imaging End User: Hospitals, Diagnostic Centers, Imaging Centers, Research Institutions Delivery Mode: Online Sales, Direct Sales, Distributors, Wholesale |
| Companies Covered | Bionix LLC, Clear Image Devices LLC, Civco Radiotherapy, Elekta AB, Vertec, AADCO Medical, Inc., IZI Medical Products, Klarity Medical Products, CQ Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiology Positioning Aids Market Trends and Innovations
Material science breakthroughs and regulatory recertification waves are restructuring how positioning aids are specified, manufactured, and procured across radiology networks.
Carbon-embedded foam cores with real-time pressure sensing is electrifying the market for intelligent positioning systems. Academic medical centers in the US and Germany are piloting these materials to monitor patient motion during lengthy MRI sequences. The technology is compressing the gap between diagnostic imaging and radiation therapy positioning requirements, enabling single-device deployment across hybrid scanner-linac suites.
EU MDR technical documentation renewal is forcing European suppliers to rebuild quality management systems for legacy positioning devices. Manufacturers must resubmit clinical evidence and risk management files for CE-marked products previously cleared under the Medical Devices Directive. CT-specific head supports face the steepest compliance burden, as notified bodies scrutinize biocompatibility testing for prolonged skin contact applications.
Hospital procurement teams are consolidating vendor relationships around full-modality positioning portfolios rather than single-product contracts. Group purchasing organizations are penalizing suppliers who cannot deliver MRI-compatible, CT-specific, and X-ray positioning aids through unified frameworks. This concentration is most visible in US diagnostic center networks, where procurement officers prioritize ISO 13485-certified manufacturers with domestic cleanroom capacity over fragmented specialty suppliers.
Radiology Positioning Aids Market Segmentation
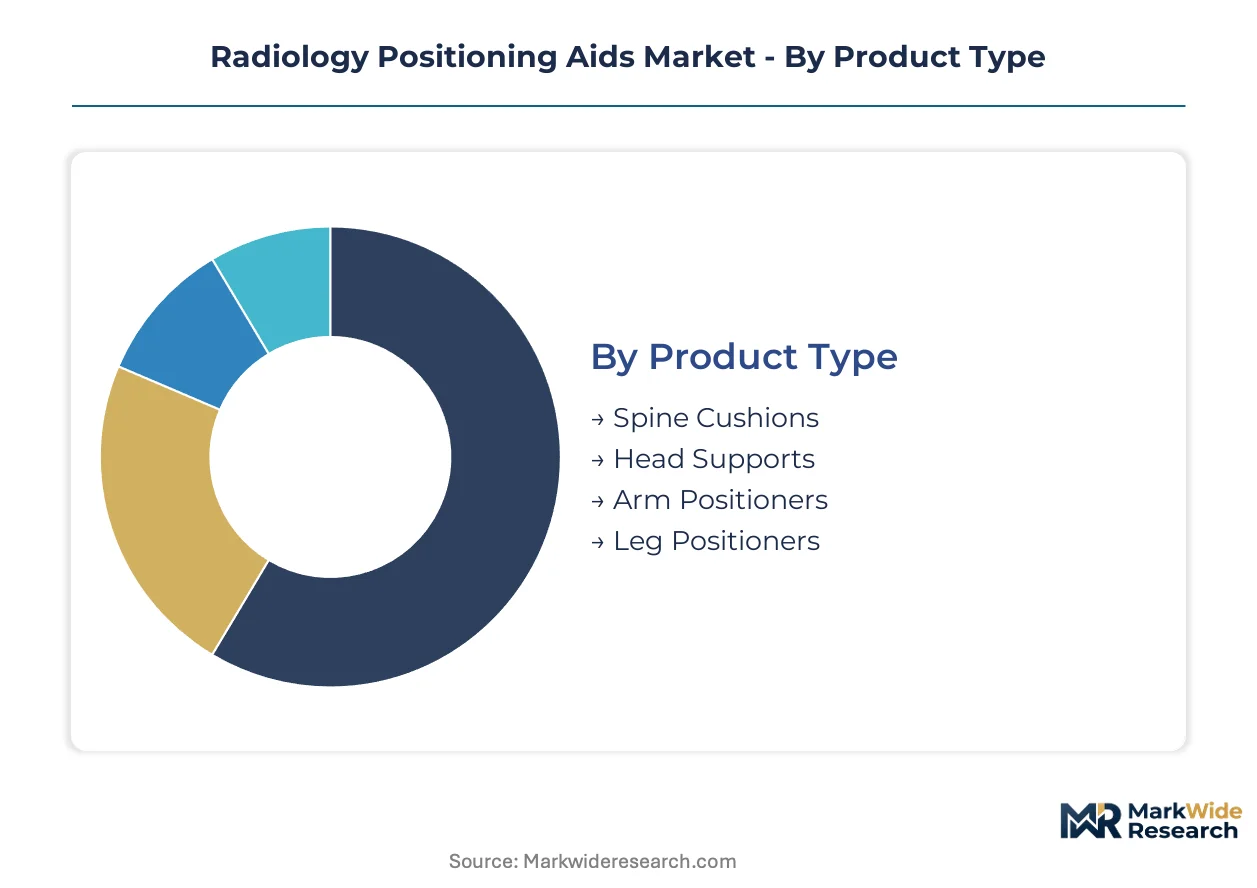
Segmentation in radiology positioning aids reveals how material specifications, imaging modality requirements, and procurement channel economics fragment demand across patient positioning applications. Understanding these divisions clarifies where manufacturers must engineer for magnetic compatibility versus radiation attenuation versus cost efficiency.
Product Type:
Material composition and anatomical immobilization requirements define competitive positioning across the four product categories.
- Spine Cushions:Viscoelastic memory foam cores with contoured lumbar support dominate hospital procurement for multi-modality suites. Demand concentrates in German hospital networks standardizing CT protocols, where pressure distribution specifications reduce patient motion artifacts during lengthy sequences.
- Head Supports:Silicone gel composites and vacuum-locked systems compete for premium positioning in neuroimaging workflows. CT-specific adjustable cradles command strongest pricing in Japan as aging infrastructure modernizes, with multi-axis designs cutting retake rates in high-throughput departments.
- Arm Positioners:MRI-compatible variants with ferromagnetic testing below 3T thresholds are expanding most quickly as scanner throughput rises.
- Leg Positioners:Basic foam wedges retain volume leadership in X-ray suites where aluminum equivalence below 0.5 mm preserves image clarity.
Mature deployment sits with spine cushions. Newer deployment is concentrated in arm positioners.
Application:
Imaging modality physics dictate material selection, with magnetic field strength and radiation energy creating incompatible specification clusters.
- CT Scans:Multi-axis adjustable head supports and torso cradles reduce retake rates through precise anatomical alignment. Premium pricing concentrates in North American diagnostic centers optimizing scanner utilization, where idle time costs exceed material premiums.
- MRI Scans:Ferromagnetic exclusion requirements below strict thresholds force dedicated foam core formulations and gel composites. Demand clusters in academic medical centers piloting 7T systems, where material validation against higher field strengths constrains supplier pools.
- X-ray Procedures:Basic foam wedges and leg positioners consume highest unit volumes through cost-driven hospital procurement.
- Ultrasound Imaging:Gel pads with acoustic transparency properties serve echocardiography and obstetric workflows.
Volume concentration rests with X-ray applications. Value concentration is shifting toward MRI scans.
End User:
Procurement sophistication and compliance burden separate institutional buyers across the care continuum.
- Hospitals:Integrated radiology departments demand full-modality positioning portfolios through unified vendor contracts. ISO 13485 certification and domestic cleanroom capacity filter supplier access in US health systems consolidating procurement around group purchasing organization frameworks.
- Diagnostic Centers:Independent imaging facilities prioritize CT throughput optimization and rapid patient turnover. Multi-axis adjustable systems that cut retake rates command premium positioning in high-volume outpatient settings.
- Imaging Centers:Specialized facilities balance equipment specialization against capital constraints.
- Research Institutions:Academic medical centers pilot carbon-embedded foam cores with pressure sensing for motion monitoring during lengthy MRI sequences.
Standardized procurement dominates hospital purchasing. Experimental adoption clusters in research institutions.
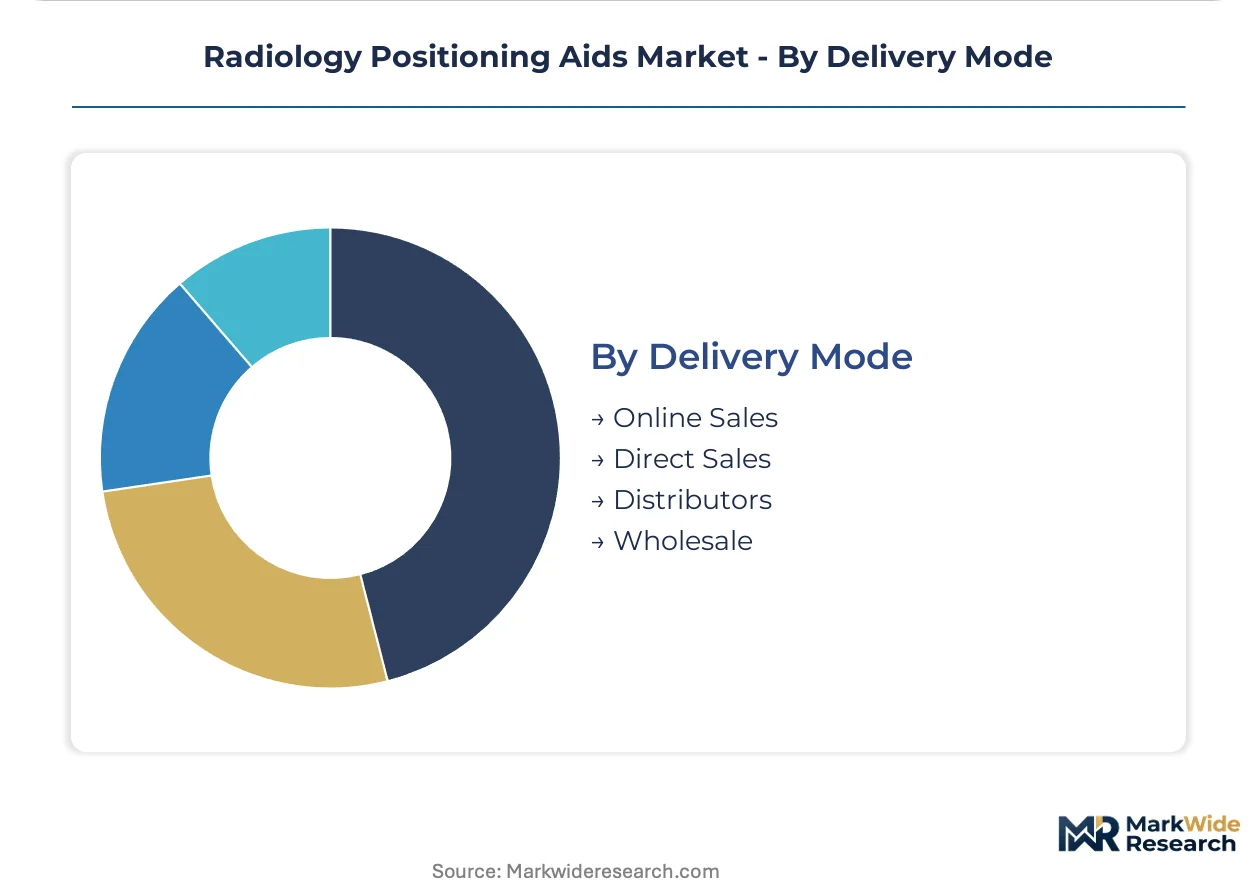
Delivery Mode:
Channel economics and customer scale determine margin structure and inventory risk allocation.
- Direct Sales:Manufacturer field teams serve large hospital networks with custom positioning kit configurations. Klarity Medical Products and Elekta AB deploy dedicated clinical specialists to radiation therapy departments for bundled system sales.
- Distributors:Medical device distributors aggregate fragmented demand from independent imaging centers, carrying inventory risk for standard foam and gel products.
- Online Sales:E-commerce penetration remains limited to replacement cushions and accessories.
- Wholesale:Bulk procurement of basic foam wedges supplies developing market health systems.
Relationship-based contracting anchors direct sales. Transactional efficiency drives distributor volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polyurethane production clusters in Germany and Ohio anchor radiology positioning aid supply chains, with foam core fabrication driving regional specialization across three continents.
United States
Diagnostic center networks in the United States are expanding procurement of MRI-compatible positioning systems following FDA guidance on magnetic resonance safety. The FDA 510(k) clearance pathway shapes product development timelines for domestic manufacturers. Ohio hosts vertically integrated manufacturing operations controlling domestic supply of CT positioning cradles.
Germany
German hospital networks are standardizing imaging protocols across radiology departments, creating concentrated demand for CT-specific head supports. EU MDR compliance deadlines force European suppliers to renew technical documentation for CE-marked positioning devices. Bavaria and North Rhine-Westphalia host foam molding specialists realigning capacity toward medical-grade polyurethane cores for radiology tables.
Japan
Japan's aging imaging infrastructure is driving hospital network modernization of CT suites, creating demand for protocol-standardized positioning kits. The country's national pharmaceutical regulator maintains stringent biocompatibility testing requirements for prolonged skin contact applications. Tokyo and Osaka metropolitan areas concentrate procurement decisions for multi-axis adjustable systems that reduce retake rates.
China
China's diagnostic imaging expansion is pulling premium pricing for multi-axis adjustable positioning systems as hospital procurement frameworks consolidate vendor relationships. NMPA regulatory pathways for medical device registration influence material validation timelines. Yangtze River Delta manufacturing clusters are developing domestic capacity for low-attenuation gel formulations serving pediatric and bariatric segments.
Radiology Positioning Aids Market Competitive Landscape
Global majors compete with regional champions across certification standards and cleanroom production capabilities, creating a tiered structure where ISO 13485 certification filters supplier access to hospital procurement frameworks. The vendor base separates into three strategic archetypes: vertically integrated domestic manufacturers, cleanroom-specialized medical device producers, and radiation therapy system bundlers. Dominant competitive moves include capacity expansion into dedicated medical-grade polyurethane production and strategic partnerships with group purchasing organizations.
Among North American fabricators, Bionix LLC and Klarity Medical Products exemplify divergent positioning strategies within the certification-driven tier. Bionix LLC represents the vertically integrated archetype with in-house control over foam core supply chains. Klarity Medical Products occupies a position emphasizing dedicated cleanroom production environments for MRI-safe positioning kits. Elekta AB anchors the radiation therapy bundling segment, competing through integrated system offerings that combine positioning aids with linear accelerator workflows.
| Leading Market Players |
|---|
| Bionix LLC |
| Clear Image Devices LLC |
| Civco Radiotherapy |
| Elekta AB |
| Vertec |
| AADCO Medical, Inc. |
| IZI Medical Products |
| Klarity Medical Products |
| CQ Medical |
| Others |
Pricing and Supply Chain Analysis
Medical-grade polyurethane feedstock indices cascade through radiology positioning aid supply chains, compressing margins for foam core fabricators while amplifying pricing power for suppliers with captive polymer production. Contract structures stratify across three tiers: premium MRI-compatible kits with ISO 13485 certification and bundled validation services, standard CT-specific cradles with limited warranty coverage, and economy foam wedges sold through distributor channels without technical support.
Pricing Analysis
Service bundling separates premium positioning aid contracts from transactional commodity sales. Pricing stratifies across premium, standard, and economy tiers based on magnetic compatibility certification grade and after-sales validation support. Cost compression in the economy tier intensifies as distributor consolidation squeezes foam wedge margins. Independent diagnostic centers exhibit highest price sensitivity, while academic medical centers purchasing for 7T MRI suites prioritize certification depth over unit cost.
Supply Chain Analysis
Refurbishment flows for vacuum-locked positioning systems create secondary supply channels that compete with new product sales. Production gravity centers on Germany, Ohio, and Japan for medical-grade polyurethane cores and silicone gel composites. Raw material sourcing draws from petrochemical feedstocks, specialty silicone precursors, and carbon fiber additives. Single-source vulnerability concentrates in German foam molding capacity serving EU hospital networks. Distribution runs through manufacturer direct sales for large health systems and medical device distributors for fragmented imaging center demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiology positioning aid procurement consolidation favors suppliers with integrated certification capabilities, squeezing mid-tier manufacturers lacking dedicated cleanroom capacity or multi-modality product portfolios.
For Market Incumbents: Deepen backward integration into medical-grade polyurethane production to insulate margin structures from feedstock volatility. Expand ISO 13485-certified cleanroom footprint in Ohio and Bavaria to capture preferred vendor status in consolidating hospital procurement frameworks. Vacuum-locked system entrants threaten traditional foam and gel positioning aid pricing; differentiation through carbon-embedded pressure sensing technology anchors premium positioning. For New Entrants and Emerging Players: EU MDR compliance deadlines in Germany and France open a window for certified suppliers to capture replacement demand from legacy device manufacturers unable to renew technical documentation. Target Japan's aging CT infrastructure modernization for protocol-standardized positioning kit contracts. Partner with group purchasing organizations in US diagnostic center networks to bypass entrenched direct sales relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier foam fabricators in Germany facing EU MDR recertification cost burdens but possessing established hospital relationships. Five-to-ten year viability hinges on magnetic compatibility engineering talent acquisition and 7T field strength validation capabilities. Monitor FDA 510(k) clearance timeline extensions for novel gel composite platforms as inflection indicator for R&D productivity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation renewal forces quality system rebuilds for legacy positioning devices. |
| Hospital System Partnership | GPO frameworks in US diagnostic networks consolidate vendor relationships around full-modality portfolios. |
| Magnetic Compatibility Validation | 3T and 7T field strength testing investments filter supplier access to academic medical center procurement. |
| Cleanroom Capacity Expansion | Dedicated medical manufacturing environments capture preferred status in ISO 13485-driven hospital tenders. |
| Silicone Gel Formulation R&D | Low-attenuation gel advances expand addressable market into pediatric and bariatric patient segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and foam molding specialists. FDA 510(k) clearance databases, EU MDR notified body submissions, and Japanese PMDA medical device registrations supplied regulatory trajectory inputs. Bottom-up demand modeling across imaging modality installations triangulated against top-down healthcare capital expenditure forecasts.
Segment-level granularity modeled product type splits across spine cushions, head supports, arm positioners, and leg positioners; application dimensions across CT, MRI, X-ray, and ultrasound; and end-user categories spanning hospitals, diagnostic centers, imaging centers, and research institutions. CAGRs derived from installed base expansion curves for high-field MRI and CT scanner deployments, overlaid with replacement cycle acceleration from EU MDR compliance deadlines. Pricing trajectories incorporated raw material index movements and certification cost pass-through elasticity.
The model assumes a particular technology adoption path; alternative pathways for carbon-embedded pressure sensing foam cores would alter the outlook if clinical validation timelines accelerate or stall. Forecasts embed assumptions regarding magnetic compatibility testing standardization and hospital procurement consolidation velocity. Practitioners should monitor FDA guidance updates on ferromagnetic thresholds and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Specialty PACS Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Ultrasound Elastography Systems Market