
 United Kingdom Computed Tomography Market | 2026-2036
United Kingdom Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Computed Tomography Market Analytics
Hospital procurement frameworks is reconfiguring how CT systems reach National Health Service buyers. GE Healthcare leverages its installed base across England's teaching hospitals to sustain long-term service contracts. Siemens Healthineers anchors its position through R&D intensity in photon-counting detector technology. Koninklijke Philips competes on workflow-integrated imaging platforms that reduce radiologist reading times.
Computed tomography denotes a medical imaging modality that reconstructs cross-sectional anatomical slices from multiple X-ray projections, typically employing tube voltages between 80 and 140 kVp and detector arrays with thousands of elements. Its primary commercial purpose lies in non-invasive diagnostic visualization for disease detection, treatment planning, and interventional guidance. Multi-slice CT dominates hospital capital budgets due to throughput requirements in emergency and cardiac departments, while dual-energy CT captures growing interest in oncology and orthopedics for material decomposition and bone marrow imaging. Portable CT systems occupy a narrower but expanding niche in intensive care and intraoperative settings where patient transport risks outweigh resolution trade-offs.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking and post-market surveillance for CT devices, while NICE technology appraisals determine reimbursement eligibility for novel clinical applications. Ionising Radiation (Medical Exposure) Regulations mandate dose optimization protocols that directly influence detector efficiency requirements and software-based iterative reconstruction adoption. Stakeholders must monitor how NHS England capital allocation shifts between centralized imaging hubs and distributed diagnostic networks.
Market Dynamics
NHS England's capital allocation shift toward centralized imaging hubs is compressing procurement cycles and favoring vendors with service-network density across England's acute hospital trusts. This structural force is redistributing CT system deployment from distributed district general hospitals toward regional diagnostic centers.
Growth Catalysts
- Oncology screening mandates:NHS Long Term Plan targets for earlier cancer detection are expanding CT capacity in lung and colorectal screening programs across England's major acute networks.
- Photon-counting detector technology:Next-generation CT platforms reduce radiation dose while improving tissue characterization, accelerating replacement cycles in cardiac and pediatric imaging departments.
- Ionising Radiation (Medical Exposure) Regulations:IR(ME)R compliance requirements for dose optimization are driving software upgrades and detector efficiency investments in existing installed bases.
Market Restraints
- Capital budget fragmentation:NHS England's devolved capital allocation to integrated care boards creates inconsistent procurement timelines and delays multi-system purchases.
- Detector material supply concentration:Rare-earth scintillator and semiconductor substrate supply chains concentrate in East Asian manufacturing hubs, exposing UK buyers to logistics volatility.
- Workforce pipeline constraints:Society of Radiographers data shows persistent vacancy rates in diagnostic radiography limiting CT utilization rates even where hardware capacity exists.
Strategic Opportunities
- Scotland and Wales capacity gaps:NHS Scotland and NHS Wales operate lower CT scanner density per capita than England, creating procurement whitespace for mobile and fixed-site systems.
- Dual-energy clinical expansion:Material decomposition applications in gout, bone marrow imaging, and renal stone characterization are opening reimbursement pathways outside traditional oncology.
- Artificial intelligence workflow integration:MHRA-approved AI triage tools for stroke and trauma are creating attach-rate opportunities for software subscriptions alongside hardware contracts.
Industry Challenges
- UKCA marking transition complexity:Manufacturers face dual compliance burdens maintaining CE marking for EU access while completing UKCA conformity assessments for England, Scotland, Wales, and Northern Ireland markets.
- Legacy PACS integration friction:Hospital trusts with decade-old picture archiving systems require costly middleware investments to support photon-counting CT data volumes and advanced visualization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Computed Tomography Market |
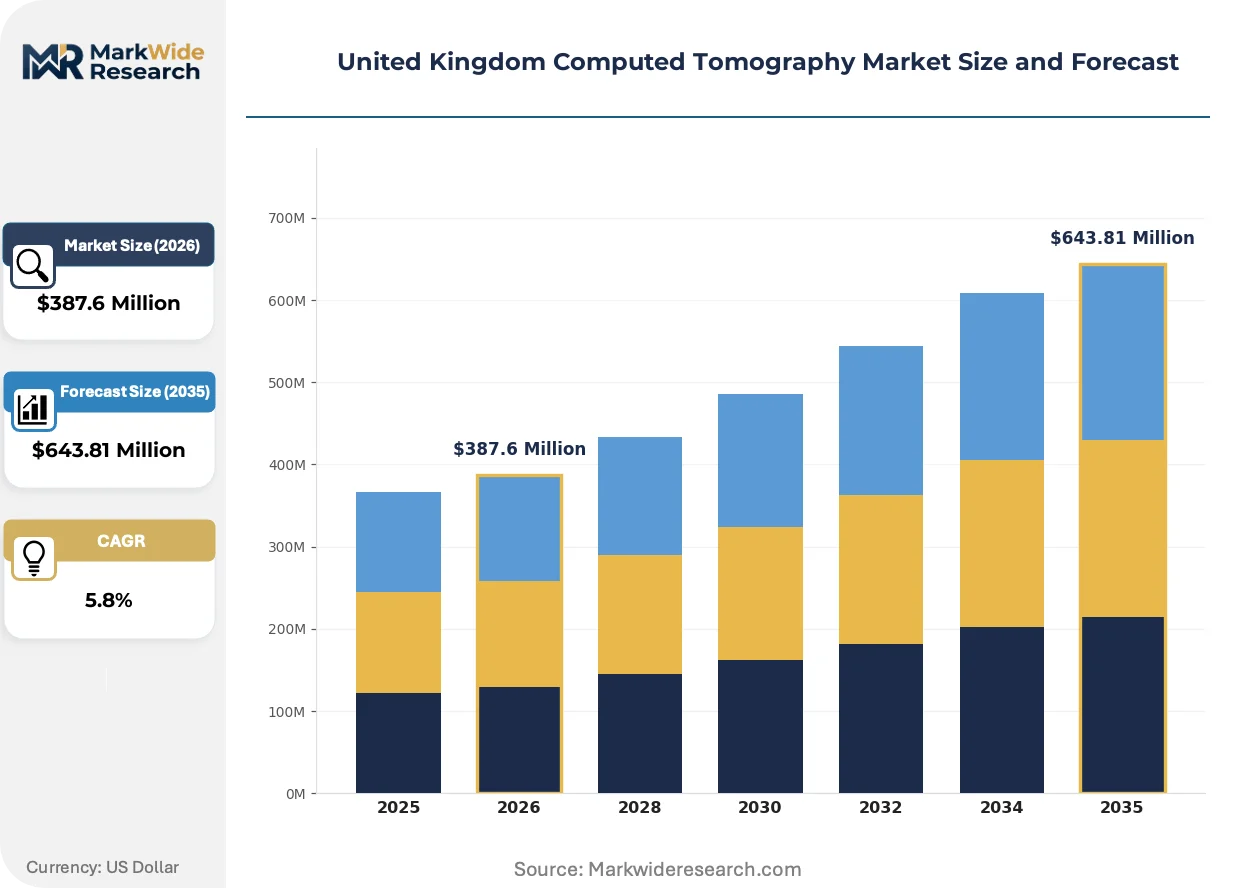
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable CT, Cone Beam CT, Multi-slice CT, Dual-energy CT Application: Oncology, Neurology, Orthopedics, Cardiology End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: 3D Imaging, Image Reconstruction, Digital Tomosynthesis, Hybrid Systems |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings, Carestream Health, Neusoft Medical Systems, Planmeca Group, United Imaging Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Computed Tomography Market Evolving Landscape
Computed tomography in the United Kingdom is undergoing platform-level transformation as detector physics, regulatory frameworks, and procurement mechanics simultaneously evolve. Three distinct movements are reshaping how systems are specified, purchased, and deployed across NHS and private provider networks.
Photon-counting CT is virtualizing the traditional energy-integrating detector paradigm. This semiconductor-based detection method directly converts X-ray photons to electronic signals, eliminating scintillator light conversion losses. NHS England's specialized commissioning teams are prioritizing these systems for high-volume cancer centers in Manchester, Leeds, and London. The technology is virtualizing conventional contrast protocols by enabling multi-material decomposition at lower radiation doses.
NICE technology appraisals are tightening evidentiary standards for novel CT applications. New diagnostic pathways must demonstrate cost-effectiveness against existing modalities before securing NHS reimbursement codes. Cardiac CT for stable chest pain evaluation secured positive guidance in 2023, accelerating coronary CT angiography adoption in rapid-access chest pain clinics across England's cardiovascular networks. Private providers in London and Manchester are responding by marketing direct-access cardiac CT outside NHS referral pathways.
Consolidated procurement through NHS Supply Chain frameworks is displacing trust-level capital purchasing. Multi-year, multi-system agreements with national pricing are concentrating vendor relationships and reducing site-by-site negotiation leverage. England's integrated care systems in the West Midlands and Greater Manchester are piloting pooled imaging budgets that span acute, community, and mental health trusts. This shift is most visible in urban conurbations where population density supports shared diagnostic infrastructure across organizational boundaries.
United Kingdom Computed Tomography Market Segmentation
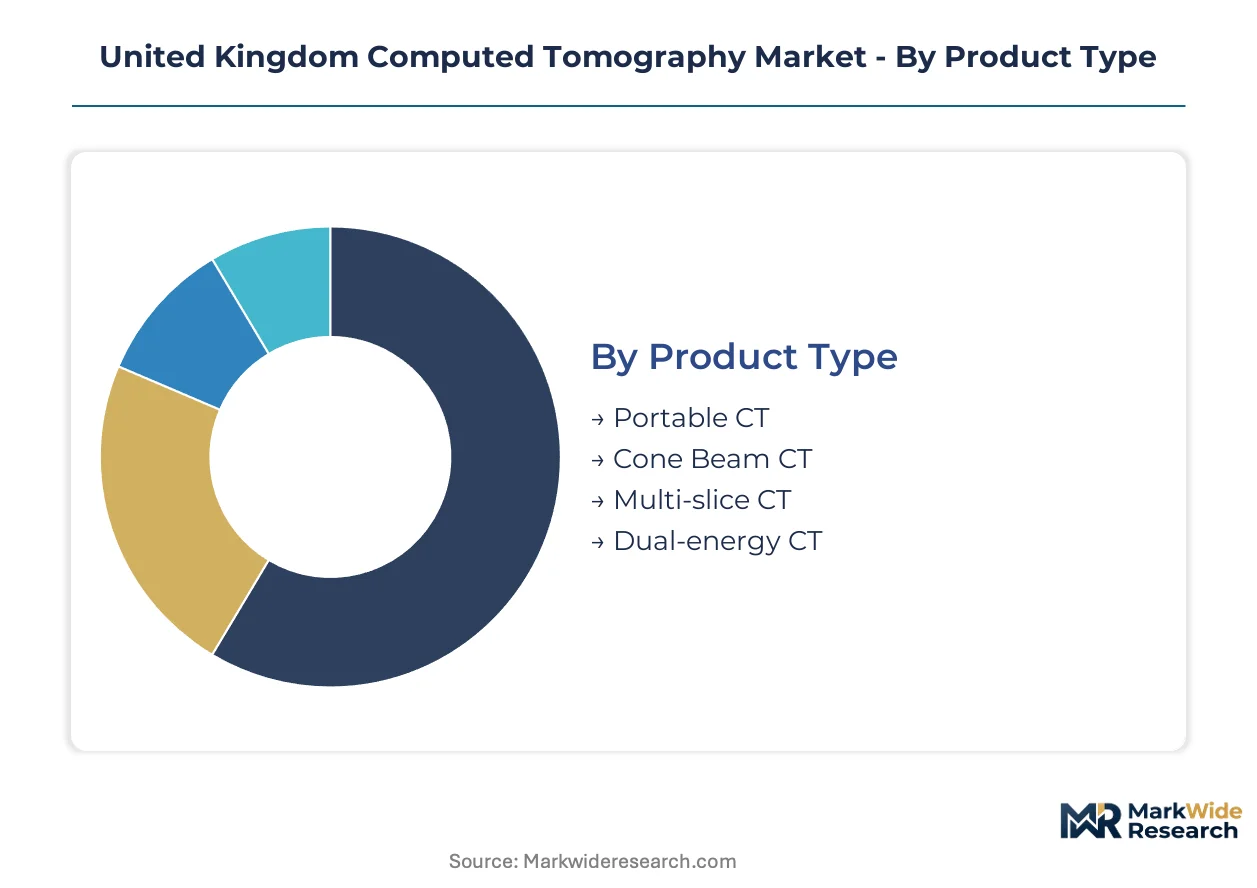
CT market segmentation in the United Kingdom reveals distinct procurement rhythms across product architectures, clinical applications, and institutional settings. NHS capital planning cycles and MHRA regulatory pathways create divergent replacement timelines that vendors must navigate.
Product Type:
Replacement cycles vary dramatically across CT architectures, with portable systems turning over fastest due to mechanical wear from transport, while fixed-site platforms operate on decade-long depreciation schedules.
- Multi-slice CT:Systems with 64 to 320 detector rows dominate emergency and cardiac departments across England's acute hospital trusts. NHS England's specialized commissioning prioritizes these platforms for high-throughput regional diagnostic hubs in Manchester, Leeds, and London.
- Dual-energy CT:Material decomposition capabilities enable gout characterization, bone marrow imaging, and renal stone analysis beyond traditional oncology applications. NICE technology appraisals are expanding reimbursement eligibility for these clinical pathways.
- Portable CT:Mobile units serve intensive care units and intraoperative settings where patient transport risks outweigh resolution trade-offs. NHS Scotland and NHS Wales procurement represents whitespace for mobile deployment.
- Cone Beam CT:Dental and maxillofacial imaging systems concentrate in private dental networks and oral surgery centers. Lower radiation dose profiles suit outpatient settings with limited shielding infrastructure.
Multi-slice CT dominates installed base. Dual-energy CT is where expansion concentrates.
Application:
Clinical demand intensity varies by specialty, with oncology driving capital allocation through screening mandates while cardiology accelerates through rapid-access chest pain clinic expansion.
- Oncology:Lung and colorectal screening programs under the NHS Long Term Plan are expanding CT capacity across England's major acute networks. Early cancer detection targets prioritize throughput and dose optimization.
- Cardiology:Coronary CT angiography adoption is climbing fastest following NICE's positive guidance for stable chest pain evaluation. Rapid-access chest pain clinics in England's cardiovascular networks are primary deployment sites.
- Neurology:Stroke triage and trauma imaging concentrate in hyperacute stroke units and major trauma centers. MHRA-approved AI triage tools are creating software attach-rate opportunities.
- Orthopedics:Pre-operative planning and post-operative assessment applications concentrate in elective surgical hubs. Dual-energy CT's bone marrow imaging capabilities are opening reimbursement pathways.
Oncology commands capital allocation. Cardiology is gaining share fastest.
End User:
Procurement authority and budget scale create tiered access patterns, with national frameworks consolidating hospital purchasing while imaging clinics operate on shorter decision cycles.
- Hospitals:NHS acute trusts and teaching hospitals execute multi-year, multi-system agreements through NHS Supply Chain frameworks. England's integrated care systems are piloting pooled imaging budgets across organizational boundaries.
- Diagnostic Centers:Regional diagnostic hubs concentrate high-volume screening and complex imaging outside traditional hospital settings. NHS England's capital shift toward centralized imaging favors this segment.
- Imaging Clinics:Private providers in London and Manchester market direct-access cardiac CT outside NHS referral pathways. Shorter procurement cycles and competitive positioning drive technology refresh rates.
- Research Institutions:Academic medical centers and clinical trial units prioritize photon-counting detector platforms for tissue characterization studies. Funding cycles align with research grant timelines rather than clinical depreciation schedules.
Hospitals dominate installed base. Diagnostic centers are where expansion concentrates.
Technology:
Software and hardware integration depth determines competitive differentiation, with reconstruction algorithms and AI workflow tools displacing raw hardware specifications in procurement evaluations.
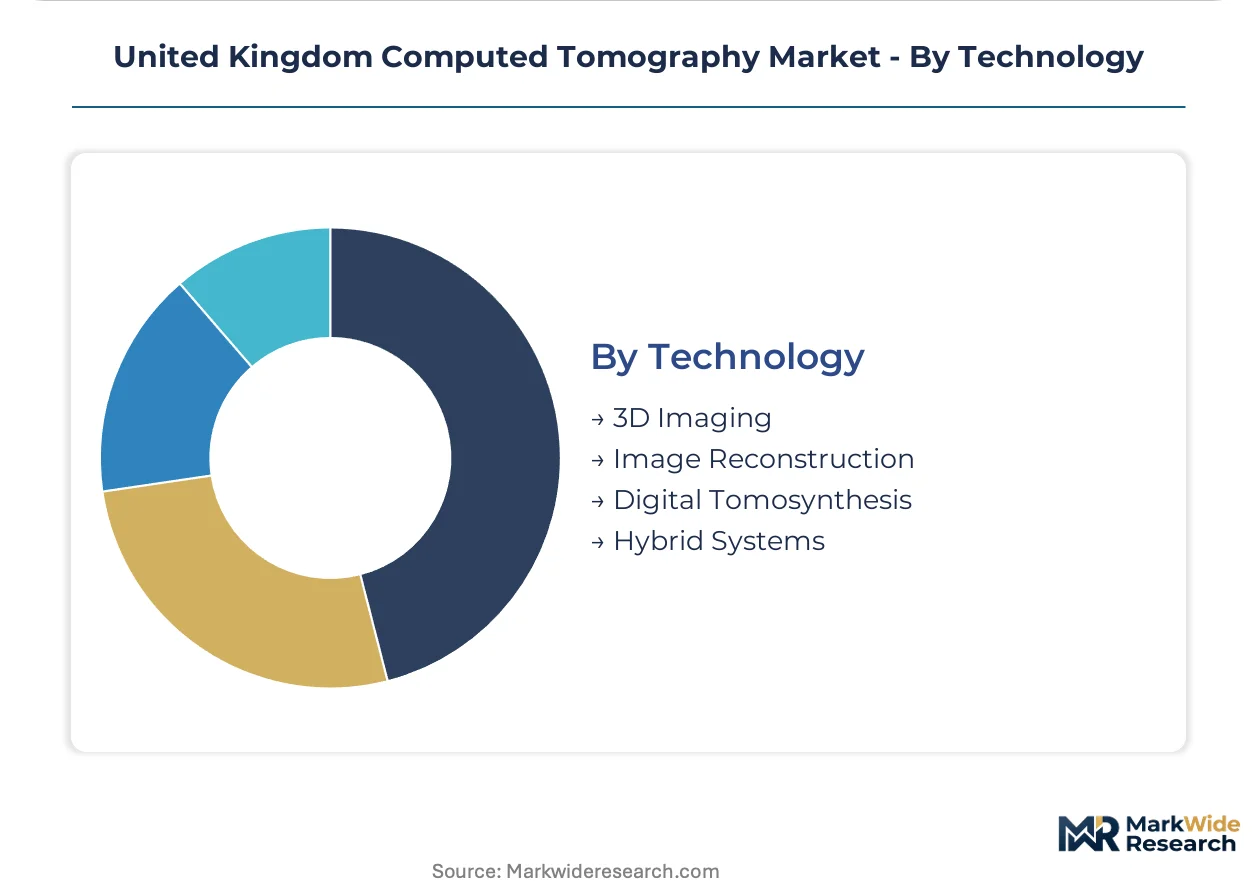
- Image Reconstruction:Iterative reconstruction algorithms reduce radiation dose while maintaining diagnostic image quality. IR(ME)R compliance requirements are accelerating adoption across existing installed bases.
- 3D Imaging:Advanced visualization protocols support surgical planning and interventional guidance. Legacy PACS integration friction requires costly middleware investments in hospital trusts with decade-old archiving systems.
- Hybrid Systems:PET-CT and SPECT-CT platforms concentrate in oncology and nuclear medicine departments. Specialized commissioning teams manage procurement for these high-capital modalities.
- Digital Tomosynthesis:Limited-angle reconstruction applications concentrate in breast imaging and musculoskeletal assessment. Narrower clinical niche constrains deployment scale relative to full CT platforms.
Image reconstruction dominates installed base. 3D imaging is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England commands premium pricing power through NHS England's consolidated procurement frameworks, while Wales and Scotland operate at lower scanner density with fragmented capital allocation. This asymmetry concentrates vendor service networks in England's acute trusts while leaving procurement whitespace in peripheral nations.
England
Oncology screening mandates and cardiac CT expansion drive demand across Manchester, Leeds, and London cancer centers. NHS England's specialized commissioning teams enforce IR(ME)R compliance through dose optimization protocols. The Greater Manchester and West Midlands integrated care systems pilot pooled imaging budgets across organizational boundaries.
Scotland
Lower CT scanner density per capita creates capacity gaps in regional diagnostic networks. NHS Scotland procurement operates outside England's centralized frameworks with devolved capital planning cycles. Edinburgh and Glasgow teaching hospitals concentrate high-complexity imaging while rural health boards depend on mobile unit deployment.
Wales
NHS Wales maintains fewer fixed-site systems relative to population, generating whitespace for portable CT procurement. Welsh Government health technology assessments parallel NICE guidance but operate independent reimbursement timelines. Cardiff and Swansea health boards anchor regional capacity while North Wales relies on cross-border referral agreements.
Northern Ireland
Department of Health capital allocations prioritize emergency department throughput and trauma imaging. The Western Health and Social Care Trust manages scanner deployment across dispersed populations. Belfast's Royal Victoria Hospital concentrates subspecialty CT services for the province.
United Kingdom Computed Tomography Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector materials and reconstruction software. The vendor base consolidates around three multinational imaging conglomerates with England-wide service networks. Archetypes include full-platform manufacturers, workflow-software developers, and mobile-unit leasing specialists. Competitive moves center on multi-year NHS Supply Chain framework agreements and photon-counting detector R&D partnerships.
Among the platform integrators named in raw data, GE Healthcare, Siemens Healthineers, and Koninklijke Philips occupy positions as archetypal full-system providers. These manufacturers represent the consolidated tier where NHS England procurement concentrates, each anchoring distinct competitive vectors through installed base relationships and service contract density across England's teaching hospital networks.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings |
| Carestream Health |
| Neusoft Medical Systems |
| Planmeca Group |
| United Imaging Healthcare |
| Others |
Value Network & Pricing Analysis
East Asian semiconductor foundries in Taiwan and South Korea anchor detector substrate production, concentrating upstream bargaining power in photon-counting CT component sourcing and compressing margin flexibility for UK hospital procurement teams negotiating multi-year NHS Supply Chain frameworks.
Pricing Analysis
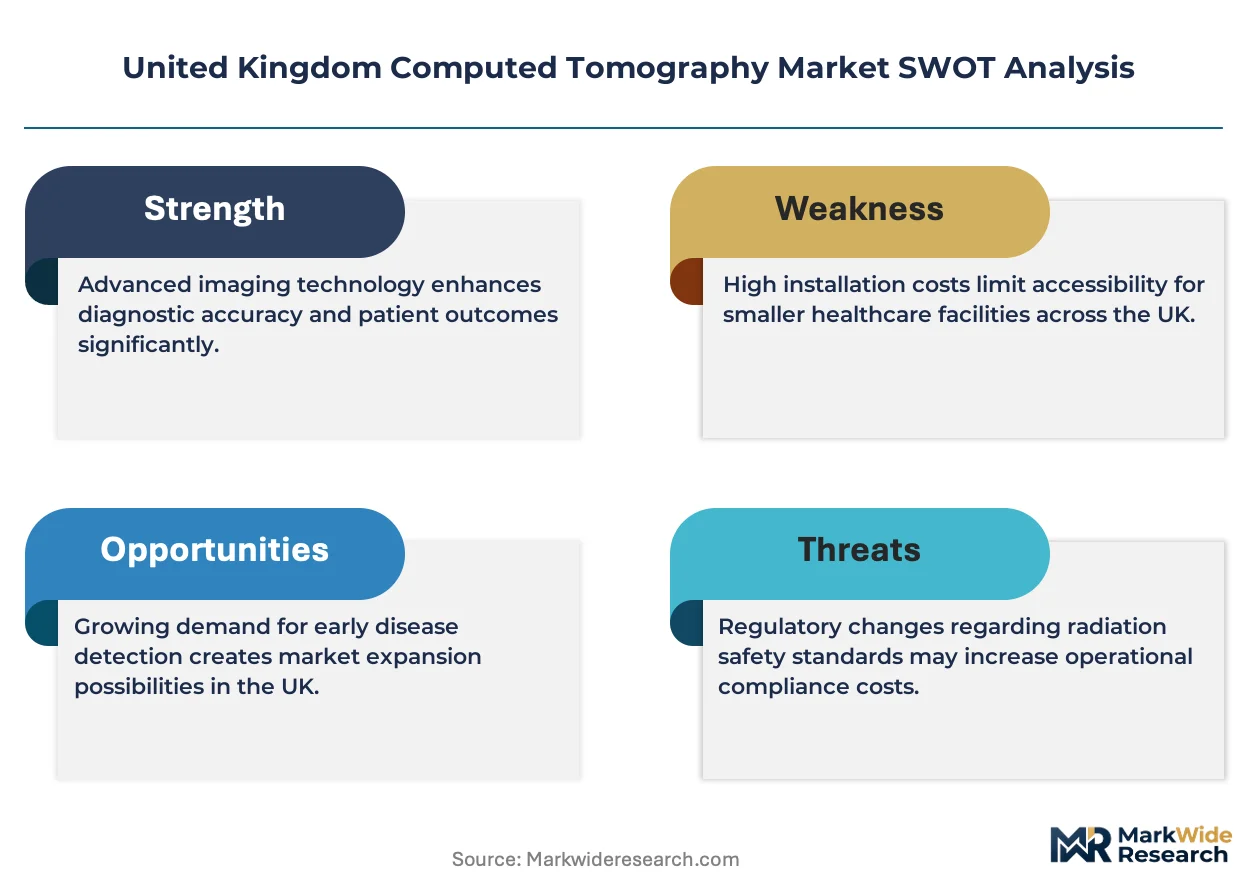
Configured-to-order pricing for photon-counting CT platforms commands substantial premiums over standard multi-slice configurations. Three-tier pricing structure across premium, standard, and economy levels segments buyers by throughput requirements and service contract bundling. Cost compression in standard-tier systems is intensifying because NHS England's consolidated procurement frameworks aggregate volume across integrated care systems. District general hospitals exhibit highest price sensitivity, while specialized cancer centers prioritize dose optimization capabilities over capital expenditure constraints.
Supply Chain Analysis
Rare-earth scintillator feedstock draws from Chinese and Malaysian processing facilities, while semiconductor substrates hinge on Taiwanese and South Korean wafer fabrication. Detector material dependencies include cadmium zinc telluride crystals, silicon photomultipliers, and ceramic substrate assemblies. Single-source vulnerability concentrates in advanced semiconductor packaging nodes. Distribution runs through manufacturer-direct service networks anchored in England's teaching hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock NHS trusts into incumbent service relationships and regulatory entrenchment through MHRA approval pathways creates multi-year barriers to displacement.
For Market Incumbents: Insulate installed base positions by extending photon-counting detector R&D partnerships and deepening software subscription attach rates. Emerging Chinese manufacturers with CE-marked platforms threaten mid-tier pricing. Vertical integration into detector material sourcing reduces East Asian supply exposure. For New Entrants and Emerging Players: Establish a beachhead in NHS Scotland and NHS Wales mobile CT procurement, where lower scanner density and devolved capital cycles favor flexible deployment models. Portable systems for intensive care units represent the most penetrable segment. Direct-to-trust leasing arrangements bypass NHS Supply Chain framework complexity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-contract-intensive platform providers with dense England-wide engineer networks. Long-term viability centers on AI workflow software attach rates and photon-counting technology transition timing. Watch NHS England capital allocation shifts between centralized hubs and distributed networks as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Platform Launch | MHRA approval for photon-counting CT secures specialized commissioning eligibility in Manchester and London cancer centers. |
| AI Triage Software Development | MHRA-cleared stroke and trauma algorithms create subscription revenue streams alongside hardware contracts. |
| NHS Supply Chain Framework Bid | Multi-year agreements with national pricing concentrate vendor relationships and reduce site-level negotiation leverage. |
| Scotland-Wales Mobile Deployment | Lower fixed-site density in NHS Scotland and NHS Wales generates whitespace for portable CT leasing models. |
| Detector Material Backward Integration | Captive supply of cadmium zinc telluride crystals mitigates East Asian logistics volatility and tariff exposure. |
Research Methodology
Initial hypotheses were tested against primary input from NHS procurement directors, biomedical engineering leads, radiology department heads, and MHRA regulatory specialists and refined through secondary validation against hospital procurement databases, NICE technology appraisal records, NHS Supply Chain framework documentation, and integrated care system capital planning disclosures. Bottom-up demand modeling triangulated against top-down NHS England equipment census data.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product architecture, clinical application, end-user institution type, and technology integration depth. CAGRs derived from equipment replacement cycle analysis and screening program capacity expansion trajectories. Forecast inputs incorporated IR(ME)R compliance upgrade timelines and photon-counting detector adoption curves.
Sensitivities concentrate around NHS capital allocation shifts, MHRA approval timeline delays, and East Asian semiconductor supply disruptions. Cross-checking against NHS England equipment census benchmarks and Society of Radiographers workforce vacancy data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
China Medical Imaging Market