
 PSMA-PET Imaging Market | 2026-2036
PSMA-PET Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
PSMA-PET Imaging Market Analytics
Project finance for cyclotron facilities and isotope production infrastructure is rewriting capital requirements for market entry. Blue Earth Diagnostics leverages its specialized focus on urologic oncology imaging to sustain clinical credibility. Telix Pharmaceuticals anchors its position through vertically integrated radiopharmaceutical manufacturing. Novartis dominates commercial scale with its established nuclear medicine distribution network.
PSMA-PET imaging employs prostate-specific membrane antigen-targeted radiotracers, typically labeled with Gallium-68 or Fluorine-18, to detect metastatic and recurrent prostate cancer lesions with sub-centimeter resolution through positron emission tomography detection of gamma ray emissions. Gallium-68 labeled agents lead procedural volume due to generator-based production eliminating cyclotron dependency, while Fluorine-18 tracers compete on longer half-life enabling centralized manufacturing and broader distribution. Among end users, diagnostic centers capture margin pools through bundled reading and reporting services, whereas hospitals anchor referral volume for initial staging and biochemical recurrence evaluation.
The FDA regulates radiopharmaceutical chemistry, manufacturing, and controls under 21 CFR Part 315, while the Nuclear Regulatory Commission governs patient dosing and handling protocols; EMA's centralized marketing authorization process shapes European commercial timelines through the Committee for Medicinal Products for Human Use. Reimbursement determinations by the Centers for Medicare and Medicaid Services in the United States and parallel health technology assessment bodies in Germany and Japan directly determine addressable procedure volume. Stakeholders must monitor isotope supply chain resilience and payer evidence requirements as the technology diffuses from academic centers to community practice settings.
Market Dynamics
Cyclotron infrastructure scarcity and generator-based Gallium-68 production economics are redrawing capital allocation across radiopharmaceutical supply chains, compressing time-to-market for new molecular imaging agents while fragmenting manufacturing ownership between hospital-based and centralized production models.
Growth Catalysts
- FDA 21 CFR Part 315 Pathways:Streamlined chemistry, manufacturing, and controls review timelines accelerate radiotracer commercialization for diagnostic developers targeting prostate cancer staging protocols.
- Biochemical Recurrence Evaluation:Rising procedural volume for post-treatment prostate cancer monitoring in tertiary care centers drives sustained demand for PSMA-targeted imaging sensitivity.
- Japan's PMDA Accelerated Assessment:Priority review designation for oncology diagnostics compresses regulatory timelines and enables earlier reimbursement negotiations for Gallium-68 labeled agents.
Market Restraints
- Molybdenum-99 Decay Chain Volatility:Concentrated fission-based isotope production in aging research reactors creates supply fragility for technetium-99m alternatives and generator feedstocks.
- Fluorine-18 Cyclotron Dependency:Capital intensity of particle accelerator infrastructure limits centralized manufacturing scale and geographic reach of longer-half-life tracers.
- CMS National Coverage Determination Lag:Reimbursement coding delays for novel PET radiopharmaceuticals compress margin realization for hospital-based nuclear medicine departments.
Strategic Opportunities
- Community Oncology Integration:Untapped procedural volume in United States outpatient imaging centers offers expansion beyond academic medical center reference laboratories.
- Artificial Intelligence-Assisted Reading:Machine learning algorithms for lesion detection and quantification are converging with molecular imaging workflows to standardize inter-reader variability.
- Germany's Diagnosis-Related Group Reform:Bundled payment recalibration for prostate cancer pathways creates reimbursement tailwinds for PSMA-PET inclusion in staging protocols.
Industry Challenges
- Radiochemist Talent Scarcity:Specialized synthesis expertise for short-half-life isotope handling remains concentrated in academic training programs, constraining production scale-out.
- Good Manufacturing Practice Facility Certification:EMA centralized marketing authorization requires extensive chemistry, manufacturing, and controls documentation that extends commercial timelines.
- Cross-Modality Integration Complexity:PSMA-PET data harmonization with MRI and CT anatomical mapping demands specialized informatics infrastructure that fragments vendor compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PSMA-PET Imaging Market |
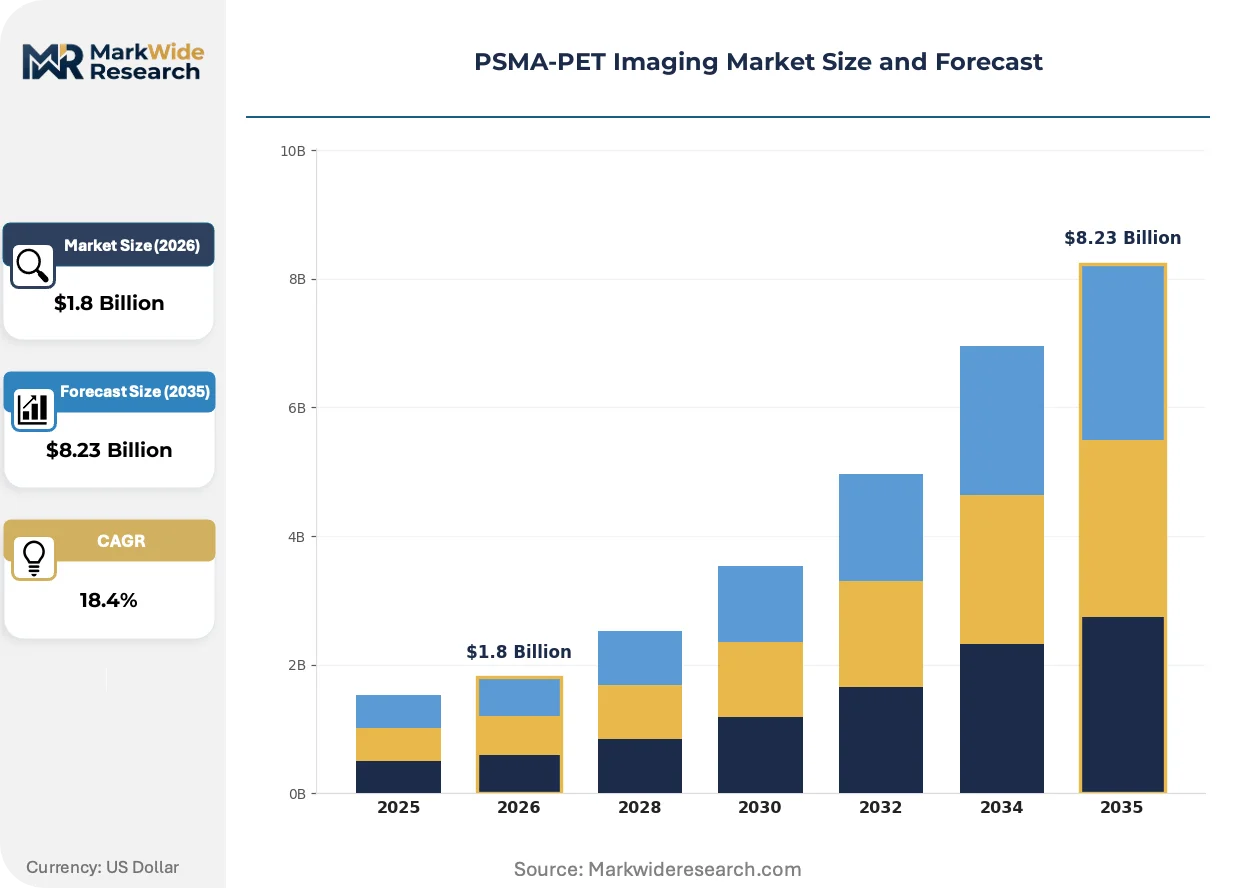
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Imaging Agents, Scanners, Software Solutions End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Facilities Technology: Fluorine-18, Gallium-68, PET Systems, Hybrid Imaging Application: Oncology, Cardiology, Neurology, Infectious Diseases |
| Companies Covered | Fisher Scientific, Bio-Rad Laboratories, Blue Earth Diagnostics, Bayer Health, SOFIE Biosciences, Telix Pharmaceuticals, Agilent Technologies, Endocyte, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PSMA-PET Imaging Market Evolving Landscape
Digital reconstruction algorithms and theranostic platform development are compressing the boundary between diagnostic imaging and radioligand therapy, enabling unified prostate cancer management protocols that pair lesion detection with targeted treatment delivery.
Artificial intelligence-based lesion segmentation software is virtualizing the radiologist's interpretive workflow by automating standardized uptake value quantification and volumetric tumor burden assessment. Academic medical centers in the United States and Germany are piloting these tools for multi-reader consistency in clinical trials. The technology is virtualizing quality assurance processes that previously required specialized nuclear medicine physician oversight.
REACH authorization requirements for radiometal chelator chemistry are tightening environmental release monitoring for Gallium-68 and Lutetium-177 manufacturing facilities across European production sites. EMA's Committee for Medicinal Products for Human Use has intensified scrutiny of impurity profiling for generator-eluted isotopes. German and Swiss radiopharmaceutical manufacturers are responding by investing in closed-loop synthesis automation that reduces operator exposure and batch variability.
Hospital procurement committees are consolidating molecular imaging contracts under centralized radiopharmacy agreements that bundle tracer supply with reading and reporting services. Diagnostic centers in Japan and the United States are displacing transactional per-dose purchasing with multi-year supply commitments that lock volume and pricing. This concentration is most visible in integrated delivery networks where nuclear medicine departments negotiate directly with vertically integrated radiopharmaceutical manufacturers.
PSMA-PET Imaging Market Segmentation
PSMA-PET imaging segments fragment across isotope half-life economics, capital intensity tiers, and clinical workflow integration depth. Each dimension carries distinct margin profiles and regulatory touchpoints that shape vendor positioning and procurement decisions.
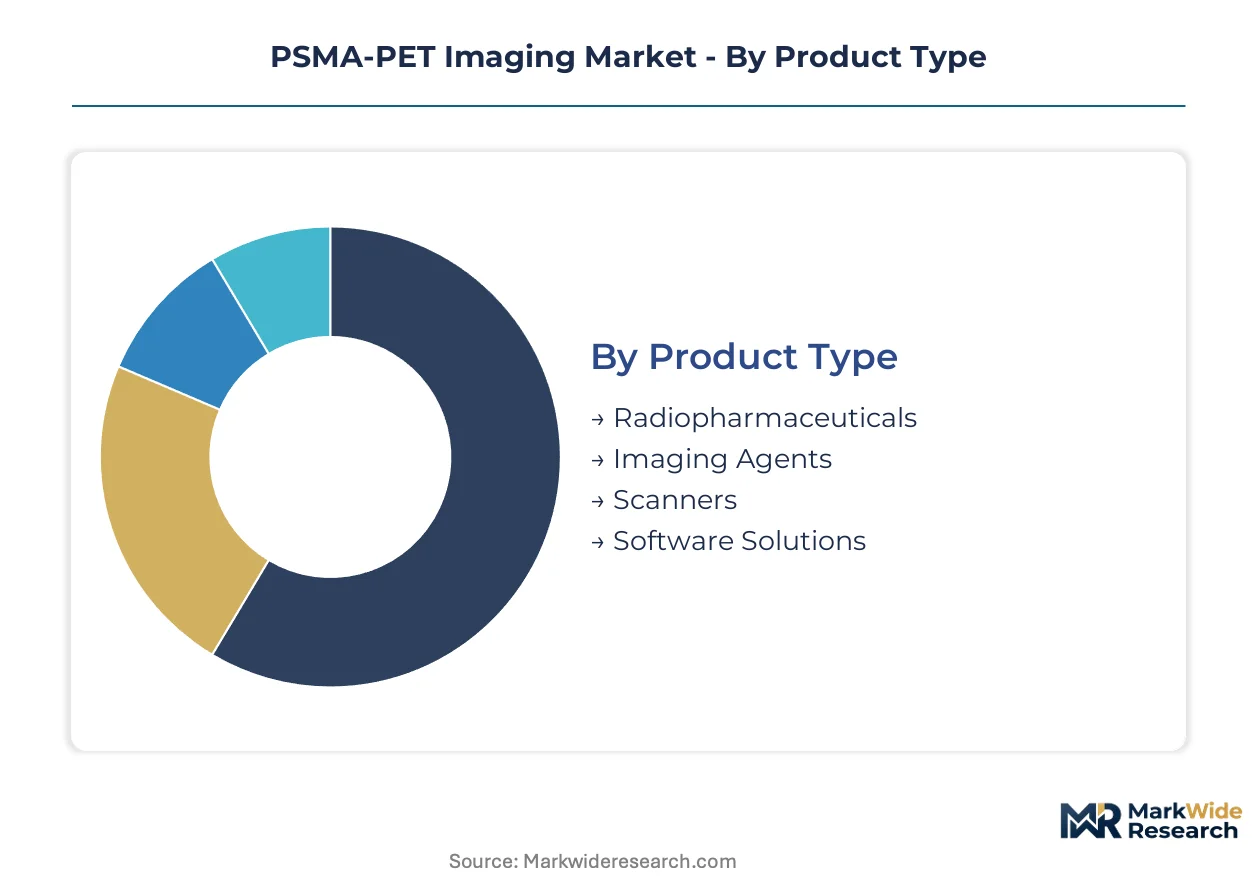
Product Type:
Radiopharmaceuticals turn inventory fastest due to isotope decay windows measured in hours, while hardware systems cycle on decade-long replacement timelines.
- Radiopharmaceuticals:Short-half-life isotopes require just-in-time synthesis and immediate patient dosing. Hospital-based nuclear medicine departments in the United States and Germany anchor procurement volume as they integrate generator-based Gallium-68 production into daily workflows. Supply security concerns intensify procurement committee scrutiny of manufacturing source diversity.
- Imaging Agents:PSMA-targeted molecular probes concentrate development investment from specialized radiochemistry operations. Japanese diagnostic centers drive adoption through PMDA accelerated assessment pathways that compress regulatory timelines. Formulation stability improvements are extending cold-chain distribution reach.
- Scanners:PET detector hardware represents capital-intensive infrastructure with extended depreciation schedules.
- Software Solutions:AI-assisted lesion quantification tools virtualize interpretation workflows and standardize uptake value reporting.
Radiopharmaceuticals anchor the volume base while software solutions gain share at the steepest rate.
End User:
Cost tiers separate high-acuity tertiary centers from outpatient imaging networks, with reimbursement complexity driving divergence in procurement sophistication.
- Hospitals:Academic medical centers and integrated delivery networks command referral volume for initial prostate cancer staging and biochemical recurrence evaluation. CMS reimbursement determinations directly shape addressable procedure economics, with national coverage determination lags compressing margin realization for nuclear medicine departments.
- Diagnostic Centers:Outpatient imaging facilities capture margin pools through bundled reading and reporting services. Community oncology integration in the United States offers expansion beyond academic reference laboratories, though radiochemist talent scarcity constrains production scale-out.
- Research Institutions:Clinical trial sponsors drive protocol standardization and multi-reader consistency studies.
- Imaging Facilities:Independent operators compete on throughput and geographic accessibility.
Hospitals anchor the volume base while diagnostic centers gain share at the steepest rate.
Technology:
Supply concentration distinguishes cyclotron-dependent isotopes from generator-based alternatives, fragmenting manufacturing ownership between centralized and hospital-based production models.
- Fluorine-18:Longer half-life enables centralized manufacturing and broader geographic distribution. Capital intensity of particle accelerator infrastructure limits manufacturing scale and creates supply-side concentration in major metropolitan clusters. EMA centralized marketing authorization requirements extend commercial timelines for European market entry.
- Gallium-68:Generator-based production eliminates cyclotron dependency and accelerates time-to-market for new molecular imaging agents. Hospital-based nuclear medicine departments scale adoption as production economics favor distributed manufacturing models.
- PET Systems:Detector technology platforms compete on sensitivity and spatial resolution specifications.
- Hybrid Imaging:PET-MRI and PET-CT convergence demands specialized informatics infrastructure for cross-modality data harmonization.
Gallium-68 anchors the volume base while hybrid imaging gains share at the steepest rate.
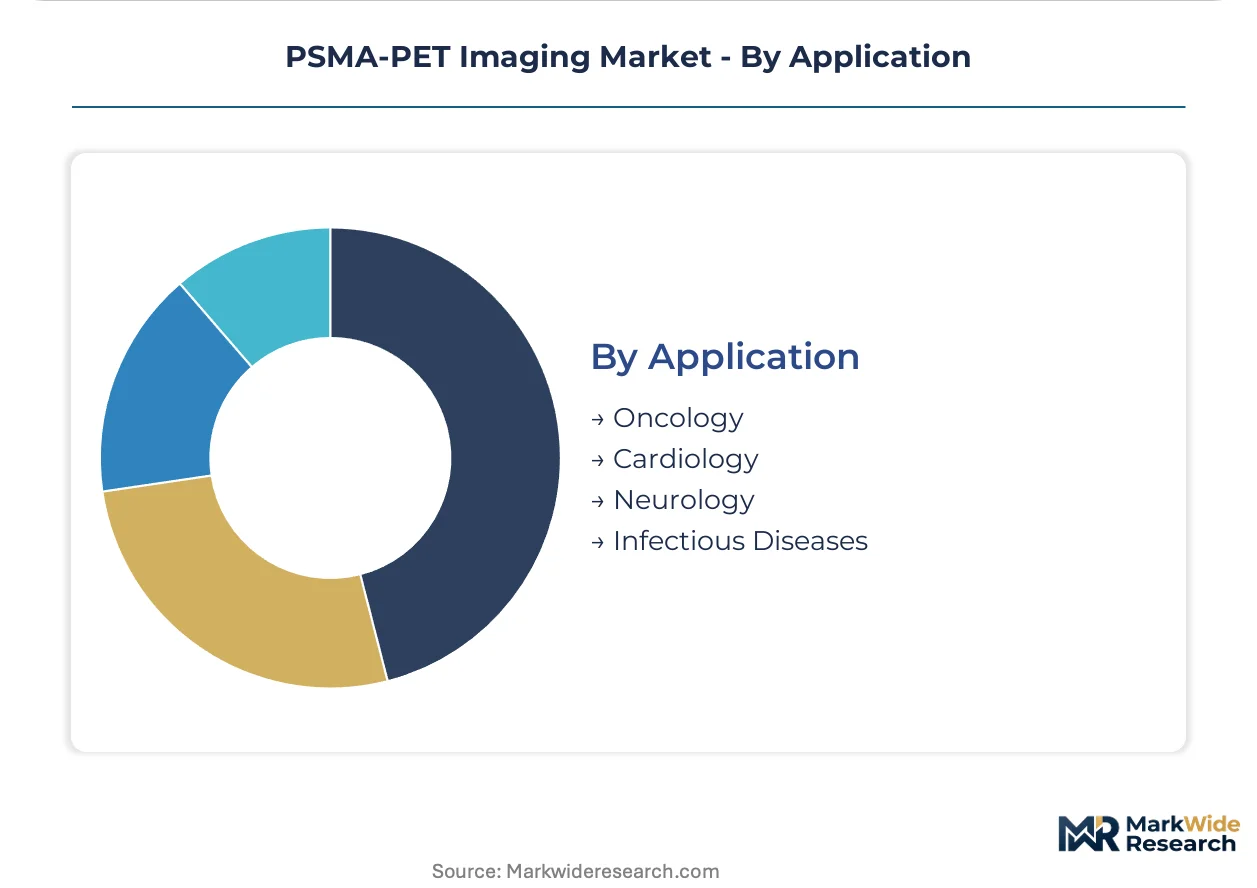
Application:
Clinical maturity separates oncology's established reimbursement pathways from emerging indications still building evidence bases for payer acceptance.
- Oncology:Prostate cancer staging and biochemical recurrence evaluation concentrate procedural volume and reimbursement clarity. FDA 21 CFR Part 315 pathways streamline radiopharmaceutical commercialization, while Germany's diagnosis-related group reform creates bundled payment tailwinds for PSMA-PET inclusion.
- Cardiology:Myocardial perfusion imaging represents adjacent demand with established technetium-99m infrastructure.
- Neurology:Amyloid and tau imaging applications compete for cyclotron capacity and radiochemist expertise.
- Infectious Diseases:White blood cell labeling and specific pathogen targeting remain investigational with limited commercial scale.
Oncology anchors the volume base while neurology gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for Gallium-68 generators and Fluorine-18 cyclotron output shapes cross-border supply flows. The United States absorbs the largest share of imported radiopharmaceutical capacity, while Germany and Japan balance domestic production with selective sourcing from Swiss and Belgian manufacturing hubs.
United States
Academic medical centers in Houston and Boston drive procedural volume for biochemical recurrence evaluation. FDA 21 CFR Part 315 pathways compress approval timelines for new radiotracers entering prostate cancer staging protocols. CMS reimbursement determinations for hospital-based nuclear medicine departments lag technology diffusion, compressing margin realization in community oncology settings.
Germany
Diagnosis-related group reform for prostate cancer pathways creates bundled payment tailwinds for PSMA-PET inclusion. EMA centralized marketing authorization through the Committee for Medicinal Products for Human Use shapes commercial timelines for European market entry. The Munich and Heidelberg clusters concentrate radiochemistry expertise and generator-based production infrastructure.
Japan
PMDA accelerated assessment designation for oncology diagnostics compresses regulatory timelines for Gallium-68 labeled agents. Aging demographics and rising prostate cancer incidence expand addressable patient populations. Tokyo and Osaka academic centers anchor adoption, with procurement committees negotiating multi-year supply commitments with vertically integrated manufacturers.
Switzerland
Swissmedic oversight of radiopharmaceutical manufacturing aligns with EMA standards while permitting faster national market access. Basel and Zurich host concentrated production infrastructure serving export markets across Western Europe. REACH authorization requirements for radiometal chelator chemistry tighten environmental release monitoring for manufacturing facilities.
Australia
TGA regulatory pathways for PET radiopharmaceuticals parallel FDA timelines, enabling earlier adoption of approved agents. Sydney and Melbourne nuclear medicine departments scale generator-based Gallium-68 production into daily workflows. Telix Pharmaceuticals anchors domestic manufacturing capacity with vertically integrated radiopharmaceutical operations.
PSMA-PET Imaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in radiochemistry and isotope production. The vendor base concentrates around three strategic archetypes: vertically integrated radiopharmaceutical manufacturers, specialized urologic oncology imaging developers, and diversified health science conglomerates. Competitive positioning hinges on cyclotron infrastructure ownership, generator supply security, and reimbursement pathway navigation. M&A activity targets radiochemistry talent and GMP facility certification; strategic partnerships bridge isotope supply gaps.
Among specialized urologic oncology developers, Blue Earth Diagnostics and Telix Pharmaceuticals exemplify focused clinical credibility strategies. Novartis anchors the diversified conglomerate tier through established nuclear medicine distribution networks. Bayer Health and Agilent Technologies occupy positions spanning diagnostic hardware and reagent supply. Fisher Scientific and Bio-Rad Laboratories represent the laboratory infrastructure and analytical instrumentation archetype serving downstream production workflows.
| Leading Market Players |
|---|
| Fisher Scientific |
| Bio-Rad Laboratories |
| Blue Earth Diagnostics |
| Bayer Health |
| SOFIE Biosciences |
| Telix Pharmaceuticals |
| Agilent Technologies |
| Endocyte |
| Novartis |
| Others |
Value Network & Pricing Analysis
Overcapacity in Gallium-68 generator production across Swiss and Belgian manufacturing hubs is compressing per-dose pricing while forcing hospital-based nuclear medicine departments toward multi-year supply commitments that lock volume and pricing. This utilization dynamic feeds directly into supplier consolidation behavior and procurement committee leverage.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term offtake structures that bundle tracer supply with reading and reporting services. Price differentiation separates FDA-approved agents from pre-commercial investigational compounds, with volume scale and GMP certification status as secondary tiering factors. Cost compression in the standard-tier segment is intensifying because generator supply security concerns are prompting dual-source requirements. Community oncology imaging centers exhibit the highest price sensitivity, while academic medical centers prioritize clinical evidence and supply reliability over per-dose economics.
Supply Chain Analysis
Export-control regimes governing radiometal chelator chemistry and isotope handling protocols limit cross-border flows of Gallium-68 generators and Fluorine-18 cyclotron output. Supply concentrates in the United States, Germany, and Switzerland, with raw material dependencies on Molybdenum-99 decay chain feedstocks, radiometal chelators, and specialized synthesis hardware. Single-source vulnerability in aging research reactor infrastructure for fission-based isotope production creates systemic fragility. Distribution runs through vertically integrated radiopharmaceutical manufacturers and hospital-based nuclear pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as biochemical recurrence evaluation demand diffuses from academic centers to community oncology settings, creating service-level niches for specialized operators.
For Market Incumbents: Insulate generator supply relationships through backward integration into isotope production infrastructure and captive manufacturing capacity in Basel or Zurich clusters. Secure GMP facility certification ahead of EMA centralized marketing authorization timelines to compress commercial launch windows. Defensive priority rests on radiochemist talent retention as synthesis expertise scarcity constrains competitor scale-out. For New Entrants and Emerging Players: Pursue community oncology integration in United States outpatient imaging centers as the most penetrable white-space target, where CMS reimbursement determination lags have suppressed incumbent margin realization. Target AI-assisted lesion quantification software development as a capital-light entry angle. Go-to-market execution should emphasize standardized uptake value reporting automation that reduces nuclear medicine physician oversight requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cyclotron-dependent Fluorine-18 manufacturing as particle accelerator infrastructure scarcity drives facility valuation premiums. Long-term viability favors vertically integrated radiopharmaceutical manufacturers with generator-based production economics and established nuclear medicine distribution networks. Acquisition target archetype: specialized urologic oncology imaging developers with PMDA accelerated assessment pathway progress. Signal to watch: CMS national coverage determination timing for novel PET radiopharmaceuticals as inflection indicator for addressable procedure volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Generator Supply Security Investment | Dual-source Gallium-68 generator commitments reduce hospital procurement committee supply risk exposure. |
| GMP Facility Certification | EMA chemistry manufacturing and controls documentation accelerates European commercial timeline compression. |
| AI-Assisted Reading Software Development | FDA 21 CFR Part 315 pathway alignment enables diagnostic workflow virtualization for lesion quantification. |
| Community Oncology Network Partnership | United States outpatient imaging center integration expands procedural volume beyond academic reference laboratories. |
| Theranostic Platform Expansion | PSMA-targeted radioligand therapy pairing with diagnostic imaging creates unified prostate cancer management protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 315 filings, EMA centralized marketing authorization submissions, CMS national coverage determinations, and hospital procurement database records. Primary interviews engaged nuclear medicine department directors, radiopharmaceutical manufacturing executives, GPO contracts managers, and payer access specialists across the United States, Germany, and Japan. Bottom-up procedure volume modeling triangulates against top-down radiopharmaceutical production capacity estimates.
Forecast inputs span isotope half-life economics, capital intensity tiers, and clinical workflow integration depth across the projection horizon. Segmentation dimensions include product type, end user archetype, technology platform, and application area with regional regulatory cluster overlays. CAGRs derive from procedure volume trajectories and reimbursement pathway maturation curves. Industry-specific inputs incorporate cyclotron infrastructure deployment timelines and radiochemist training pipeline throughput.
Sensitivities concentrate around CMS reimbursement determination timing, Molybdenum-99 research reactor operational status, and PMDA accelerated assessment pathway success rates. Forecasts reflect assumptions regarding regulatory approval continuity and isotope supply chain resilience. Cross-checking against hospital capital expenditure survey data and nuclear medicine department budget allocation trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Global Medical Image Management Market