
 United Kingdom Digital X-Ray Devices Market | 2026-2036
United Kingdom Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Digital X-Ray Devices Market Analytics
Buyer consolidation among NHS England hospital trusts is repositioning procurement leverage toward larger integrated care systems. Siemens Healthineers leverages its installed base of radiography rooms to sustain service contract renewals across acute trusts. Philips Healthcare anchors its position through diagnostic informatics that connect imaging workflows to electronic patient records. GE Healthcare competes by extending AI-powered image reconstruction into emergency department throughput optimization.
Digital X-ray devices employ solid-state detectors—flat panel or charge-coupled—to convert X-ray photons directly into electronic signals, eliminating chemical film processing while enabling immediate image review and PACS integration. Portable systems lead volume uptake as NHS trusts prioritize point-of-care imaging in emergency departments and ward settings, while fixed systems retain margin concentration in specialized orthopedics and cardiovascular suites where high-resolution fluoroscopy commands premium positioning. Image processing software represents the fastest-expanding technology layer as vendors embed machine learning algorithms for automated dose optimization and pathology flagging.
MHRA medical device regulations enforce post-market surveillance and software validation standards that lengthen product development cycles but raise barriers against non-compliant imports. NHS England's MedTech Funding Mandate accelerates adoption of technologies demonstrating cost-per-scan reductions, while BSI certification requirements for electromagnetic compatibility shape hardware design specifications. Stakeholders must monitor how integrated care system procurement frameworks redistribute purchasing authority between individual trusts and regional collaboratives.
Market Dynamics
NHS England's consolidation of procurement authority into integrated care systems is compressing vendor margins while accelerating replacement cycles for aging analog-to-digital conversions.
Growth Catalysts
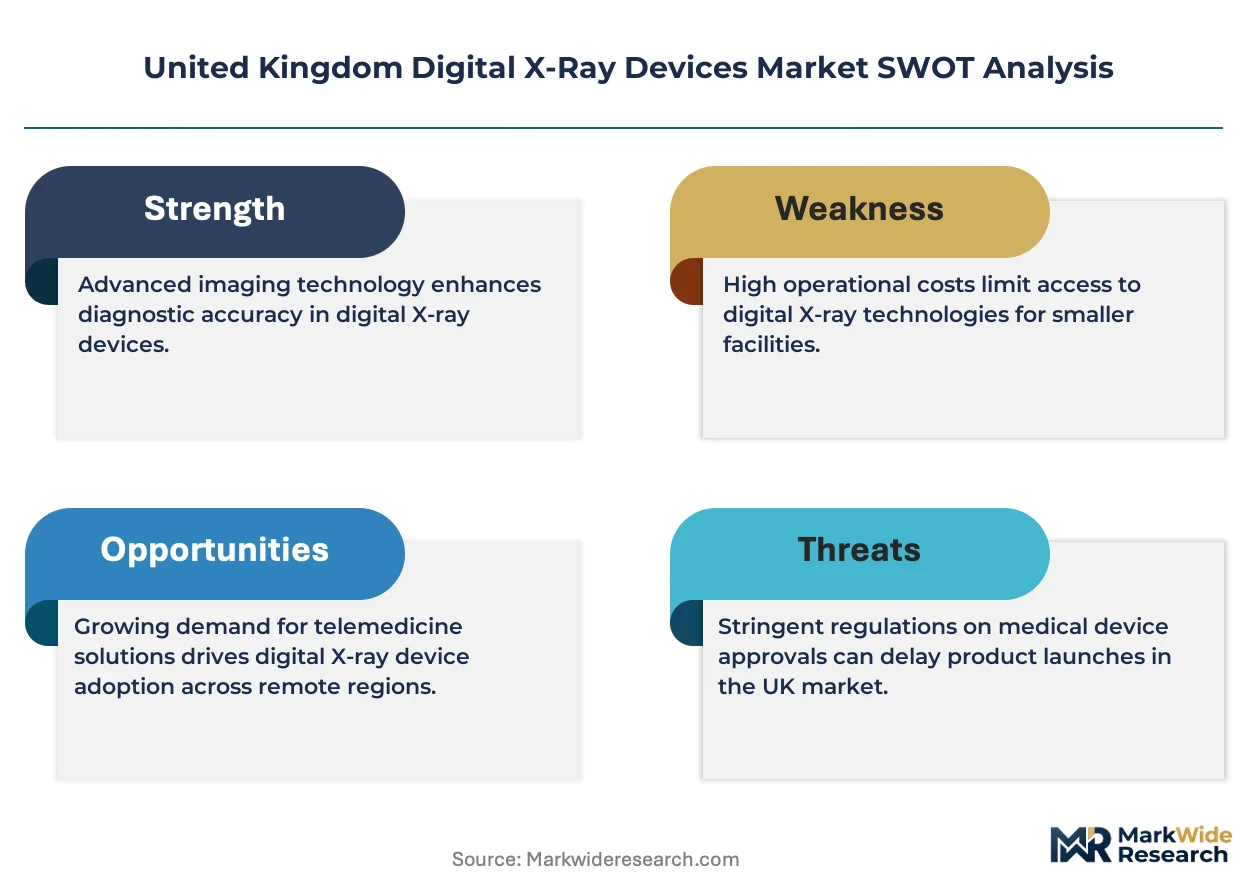
- MedTech Funding Mandate:NHS England's cost-per-scan reduction requirements accelerate hospital trust adoption of AI-enabled diagnostic suites that demonstrate measurable workflow efficiency gains.
- Point-of-care imaging:Emergency departments across Greater Manchester and West Yorkshire hospital networks prioritize portable digital X-ray systems for bedside trauma assessment.
- AI software integration:Machine learning algorithms embedded in image reconstruction are automating pathology flagging and dose optimization protocols.
Market Restraints
- Detector component concentration:Flat-panel detector manufacturing concentrates among East Asian suppliers, exposing UK distributors to semiconductor supply volatility.
- MHRA software validation:Post-market surveillance requirements for AI-enabled diagnostic tools extend product development timelines by 12-18 months.
- Capital intensity:Fixed fluoroscopy suite installations require specialized shielding infrastructure that constrains rapid deployment in older hospital estates.
Strategic Opportunities
- Scotland and Northern England trusts:Underpenetrated regional health boards outside London-Manchester corridor present first-mover advantages for mobile digital radiography vendors.
- Veterinary diagnostic crossover:Companion animal imaging demand from UK veterinary chains creates adjacent revenue streams for portable system manufacturers.
- BSI certification alignment:Electromagnetic compatibility standards harmonization with EU MDR opens streamlined export pathways to continental European markets.
Industry Challenges
- Clinical engineering staffing:NHS trusts face persistent shortages of biomedical equipment technicians qualified for solid-state detector calibration and PACS integration.
- Legacy system interoperability:Hospital networks running heterogeneous imaging archives encounter data migration friction when consolidating onto unified diagnostic informatics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Digital X-Ray Devices Market |
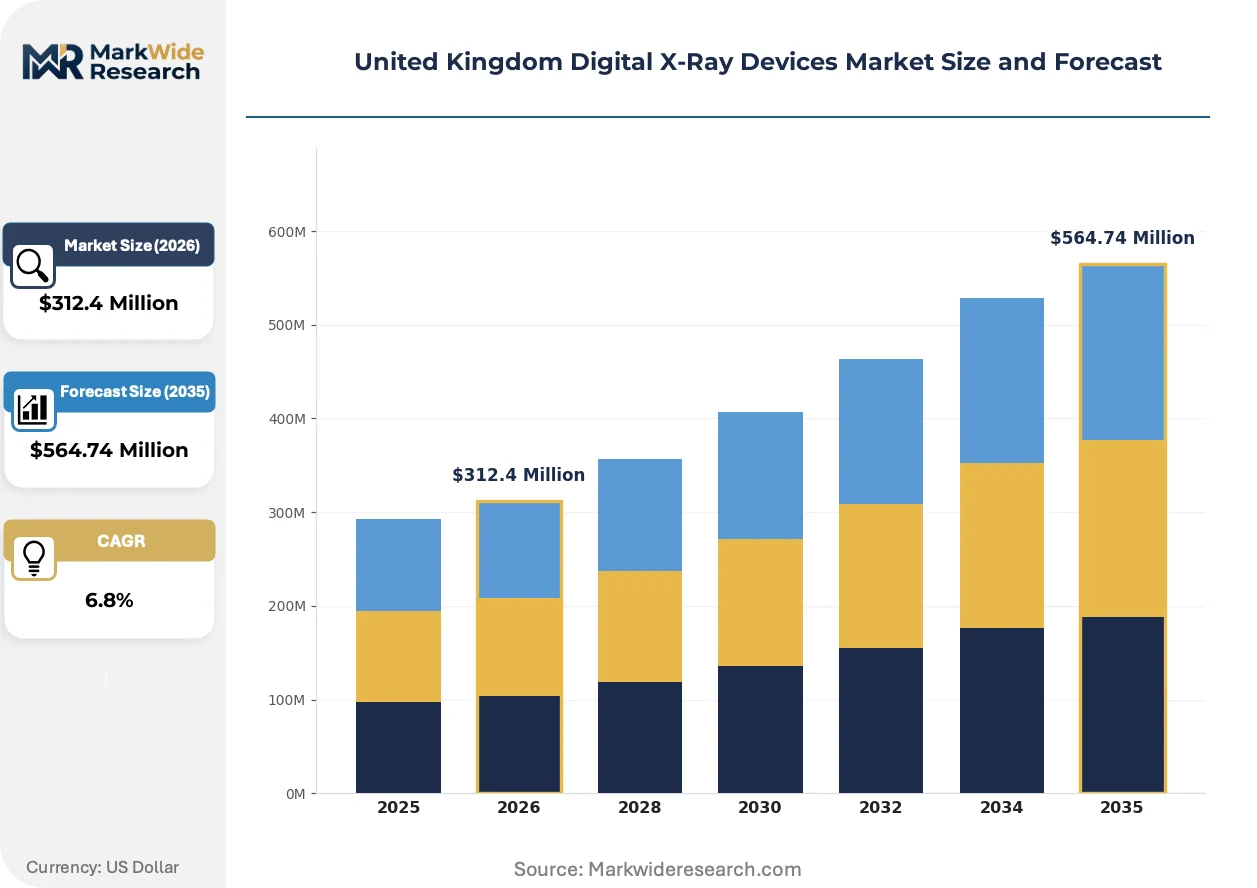
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Computed Radiography, Digital Radiography End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes Application: Oncology, Orthopedics, Cardiovascular, Dental Technology: Flat Panel Detectors, Charge-Coupled Devices, Image Processing Software, Analog Detectors |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Fujifilm Holdings Corporation, Carestream Health, Canon Medical Systems Corporation, Shimadzu Corporation, Samsung Electronics Co Ltd, Agfa-Gevaert Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Digital X-Ray Devices Market Evolving Landscape
Computational imaging and regulatory software mandates are reconfiguring how NHS trusts evaluate total cost of ownership across hardware-service-software bundles.
Deep learning reconstruction algorithms are automating low-dose image enhancement without radiologist intervention. Acute trusts in the West Midlands are deploying these tools in emergency departments to reduce repeat scan rates. The compression of diagnostic confidence thresholds is automating triage protocols and shortening inpatient length-of-stay metrics.
MHRA's software-as-a-medical-device framework imposes validation documentation burdens on AI-enabled pathology detection modules. Vendors must submit algorithm training datasets and performance benchmarks for registration renewal. Orthopedic and cardiovascular imaging suites face the steepest compliance costs given higher-risk classification of automated fracture and stent assessment tools.
Integrated care system procurement frameworks concentrate purchasing decisions at regional collaborative levels rather than individual hospital trusts. Framework agreements now bundle hardware, maintenance, and software subscriptions into single tender awards. The East of England and South West regions exhibit the most advanced consolidated contracting models, with three-year rolling commitments replacing transactional equipment purchases.
United Kingdom Digital X-Ray Devices Market Segmentation
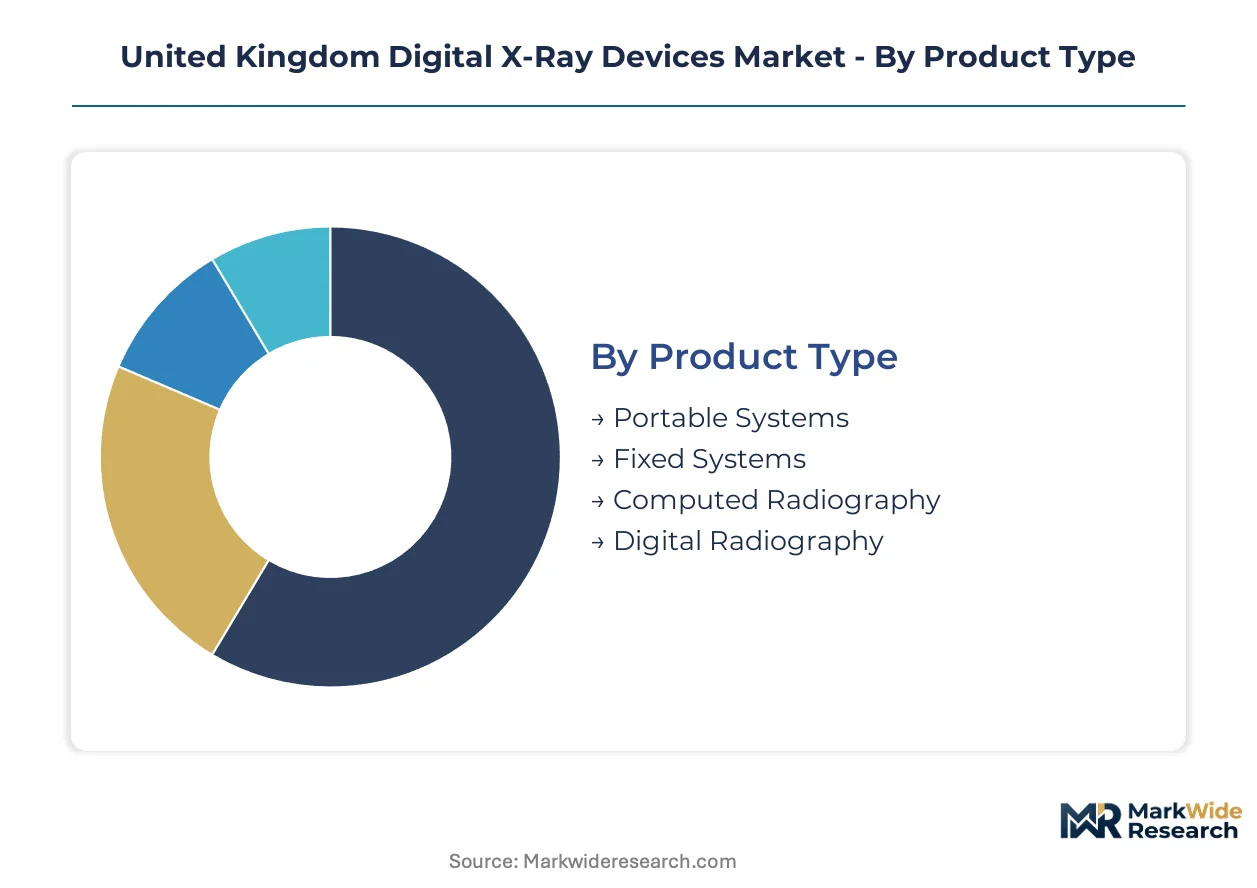
Segmentation reveals how NHS procurement frameworks allocate capital across hardware, software, and service bundles. Trust-level purchasing authority shapes which product configurations dominate metropolitan versus regional deployments.
Product Type:
Capital intensity varies sharply: fixed systems demand specialized shielding infrastructure and civil works, while portable units minimize installation overhead.
- Portable Systems:Battery-powered mobile units with wireless detector panels enable bedside imaging in emergency departments and ward settings. NHS trusts across Greater Manchester and West Yorkshire prioritize these for trauma throughput optimization.
- Fixed Systems:Ceiling-suspended or floor-mounted installations integrate fluoroscopy capabilities for interventional procedures. High-resolution cardiovascular suites in London teaching hospitals command premium positioning for these configurations.
- Computed Radiography:Cassette-based phosphor plate systems bridge analog-to-digital transitions in budget-constrained trusts.
- Digital Radiography:Direct-capture flat panel systems eliminate chemical processing entirely.
Most installed capacity flows through Portable Systems. Expansion is steepest in Fixed Systems where AI-enabled fluoroscopy commands replacement premiums.
End User:
Procurement concentration determines contract scale: integrated care systems aggregate demand across multiple hospital sites.
- Hospitals:Acute NHS trusts operate the majority of installed base, with emergency departments driving portable system deployment and specialized suites anchoring fixed system revenue.
- Diagnostic Centers:Independent imaging providers compete on throughput metrics, prioritizing high-volume digital radiography rooms with rapid patient turnaround.
- Ambulatory Surgical Centers:Same-day procedure facilities require compact C-arm systems for intraoperative imaging.
- Research Institutes:Academic medical centers in Oxford and Cambridge deploy preclinical imaging systems for translational studies.
Procurement volume concentrates in Hospitals. Research Institutes show the steepest technology refresh cycles.
Application:
Clinical workflow requirements dictate detector specifications and software integration depth.
- Oncology:Staging and treatment monitoring demand low-dose protocols with automated lesion tracking algorithms. Integrated care systems in the East of England prioritize these capabilities for lung and breast screening programs.
- Orthopedics:Weight-bearing extremity imaging and automated fracture detection drive flat panel resolution requirements. Major trauma centers across the West Midlands deploy specialized suites for polytrauma assessment.
- Cardiovascular:Interventional suites require high-frame-rate fluoroscopy with dose tracking.
- Dental:Panoramic and cephalometric systems serve primary care contracts.
Orthopedics commands the largest installed base. Oncology applications are expanding most quickly as screening mandates widen.
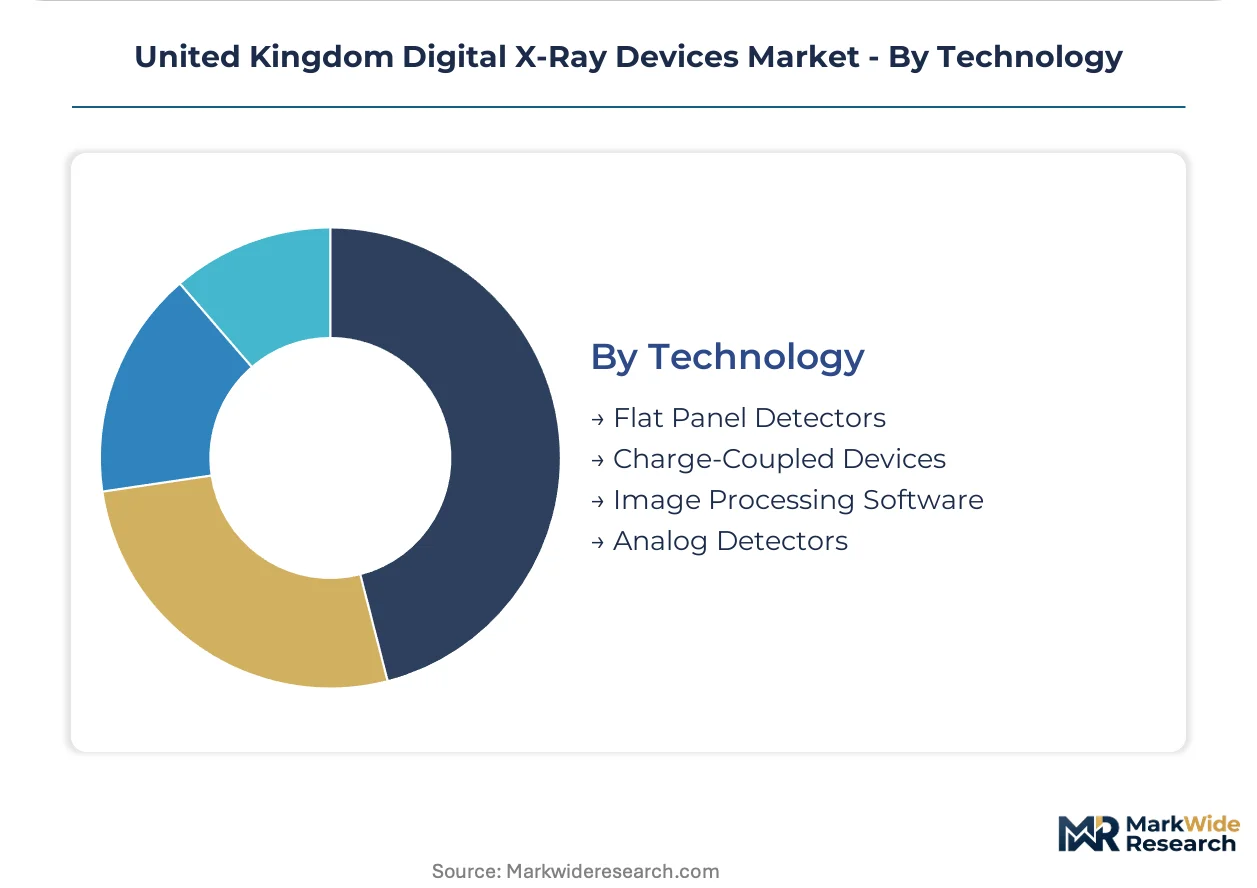
Technology:
Supply chain configuration determines availability: flat panel detector manufacturing concentrates among East Asian suppliers.
- Flat Panel Detectors:Amorphous silicon or CMOS active matrix arrays convert X-ray photons to digital signals with micron-level resolution. These dominate new installations across England's metropolitan hospital networks.
- Charge-Coupled Devices:Scintillator-coupled CCD sensors persist in retrofit applications and veterinary crossover markets.
- Image Processing Software:Machine learning reconstruction algorithms represent the fastest-expanding value layer.
- Analog Detectors:Film-screen systems survive only in legacy maintenance contracts.
Detector hardware generates the largest revenue share. Software layers are climbing the fastest as MHRA validation frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial imaging base contrasts with the United Kingdom's NHS-centric procurement model, while France and Italy demonstrate intermediate healthcare system structures. Each national market exhibits distinct regulatory pathways and hospital network configurations.
Germany
University hospital networks in Bavaria and Baden-Württemberg drive demand for high-resolution fluoroscopy suites. The BfArM medical device database enforces strict post-market surveillance for AI-enabled diagnostic modules. Siemens Healthineers anchors manufacturing and R&D concentration in Erlangen and Forchheim.
France
Public hospital groups in Île-de-France prioritize portable digital radiography for emergency department throughput. ANSM software validation requirements extend timelines for algorithm-based pathology detection. Lyon and Marseille academic medical centers lead adoption of deep learning reconstruction protocols.
Italy
Lombardy's regional health system consolidates procurement across Milan's metropolitan hospital network. CE marking under EU MDR shapes device registration pathways for domestic and imported equipment. Bologna's medical technology corridor hosts specialized service providers for detector calibration.
Spain
Andalusia's regional health service accelerates analog-to-digital conversion in provincial hospitals. AEMPS medical device regulations align with EU harmonized standards while maintaining national vigilance procedures. Barcelona's hospital clusters command premium positioning for interventional cardiovascular suites.
Netherlands
Academic medical centers in the Randstad region deploy AI-enabled screening programs for oncology applications. Health and Youth Care Inspectorate oversight integrates with CE marking conformity assessment. Eindhoven's high-tech ecosystem supports detector component supply relationships.
United Kingdom Digital X-Ray Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service bundles. The vendor base stratifies into three tiers: integrated imaging conglomerates with diagnostic informatics platforms, mid-scale equipment manufacturers with regional service networks, and niche software developers with algorithm-specific regulatory clearances. Dominant competitive moves include framework contract aggregation through integrated care system procurement and AI software licensing partnerships that embed pathology detection into hardware-service bundles.
Within the integrated conglomerate tier, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify positioning through diagnostic informatics depth and installed base service relationships. These corporations anchor competitive dynamics through multi-year managed equipment service contracts that consolidate hardware, maintenance, and software subscriptions into single procurement frameworks.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Samsung Electronics Co Ltd |
| Agfa-Gevaert Group |
| Others |
Value Network & Pricing Analysis
Flat-panel detector manufacturing costs in South Korea and Japan flow through three pricing tiers downstream, with NHS integrated care systems capturing scale discounts that independent diagnostic centers cannot match.
Pricing Analysis
Capacity additions in East Asian detector fabrication are reshaping price floors for UK distributors. Three-tier pricing structure across premium AI-enabled suites, standard digital radiography rooms, and economy cassette-based systems separates university hospital trusts from community providers. Price differentiation hinges on MHRA software validation tier and bundled service contract duration. Margins are tightening in standard-tier hardware as procurement frameworks consolidate multi-hospital awards.
Supply Chain Analysis
Dual-sourcing requirements embedded in NHS procurement frameworks mandate qualified suppliers for both amorphous silicon detector arrays and CMOS active matrix components. Manufacturing concentrates in South Korea, Japan, and Taiwan, with scintillator materials drawing from specialized chemical processors in Germany. Single-source vulnerability persists for high-resolution fluoroscopy detectors. Distribution runs through authorized UK service partners holding BSI electromagnetic compatibility certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom market functions as a geographic-arbitrage opportunity where MHRA software validation requirements create compliance moats deeper than continental EU markets, rewarding early investment in algorithm documentation.
For Market Incumbents: Acquire AI pathology detection algorithm portfolios to defend against pure-play software entrants penetrating through diagnostic informatics partnerships. Anchor service contract renewals through PACS integration depth. Prioritize calibration technician training programs to address NHS clinical engineering staffing gaps. For New Entrants and Emerging Players: Capture Scotland and Northern England regional health boards where procurement consolidation remains less advanced than the Manchester-Leeds corridor. Veterinary diagnostic crossover applications present white-space expansion with lower regulatory barriers. Position through portable system mobility specifications optimized for ward-based imaging workflows. For Investors and Strategic Acquirers: Consolidation pressure builds where AI software validation costs exceed standalone hardware margins, favoring integrated platform vendors over component specialists. Long-term viability centers on recurring software subscription revenue streams embedded in multi-year managed equipment service frameworks. Monitor MHRA software-as-a-medical-device registration renewal timelines as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | BSI certification alignment with EU MDR opens streamlined export pathways to Germany and France. |
| Hospital System Partnership | Integrated care system framework agreements bundle hardware, maintenance, and AI software subscriptions. |
| Software Companion Development | Machine learning reconstruction algorithms automate low-dose image enhancement for emergency department throughput. |
| Reimbursement Strategy | NHS MedTech Funding Mandate cost-per-scan metrics determine technology adoption velocity. |
| Backward Integration | In-house detector calibration capabilities reduce dependency on East Asian service networks. |
Research Methodology
Direct dialogue with NHS procurement directors, biomedical equipment technicians, GPO contracts managers, and diagnostic informatics specialists grounded qualitative findings in operational constraints. Secondary validation drew from MHRA device registration databases, NHS England procurement frameworks, BSI certification records, and hospital trust capital expenditure disclosures. Bottom-up trust-level demand aggregation triangulated against top-down integrated care system budget allocations.
Segment-level revenue outputs across the projection horizon reflect modeled interactions between product type, end user concentration, and technology layer adoption velocity. Segmentation dimensions encompassed portable versus fixed system configuration, acute trust versus independent diagnostic center procurement authority, and flat panel detector versus image processing software value capture. CAGRs derived from replacement cycle analysis of analog-to-digital conversion waves and AI software refresh mandates. Forecast inputs incorporated MHRA software validation timeline assumptions and integrated care system consolidation trajectories.
Underlying measurement precision varies by segment; portable system volume estimates carry tighter precision than emerging AI software revenue layers given nascent pricing transparency. Forecasts reflect documented assumptions regarding NHS capital allocation priorities and semiconductor supply availability. Deviation in MHRA software-as-a-medical-device enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Italy Magnetic Resonance Imaging Market
Medical Imaging
Argentina Mammography Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Australia Mammography Market