
 Donohue Syndrome Treatment Market | 2026-2036
Donohue Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Donohue Syndrome Treatment Market Outlook
Aftermarket service revenue for insulin pump maintenance and calibration is narrowing as device manufacturers shift toward subscription-based continuous glucose monitoring bundles. Hoffmann-La Roche Ltd leverages its diagnostics-to-therapeutics integration to sustain captive demand for companion testing. Tandem Diabetic Care, Inc. anchors its position through automated insulin delivery algorithms that dominate the Type A insulin resistance segment. Insulet Corporation differentiates via tubeless patch pump architectures that occupy the home care channel.
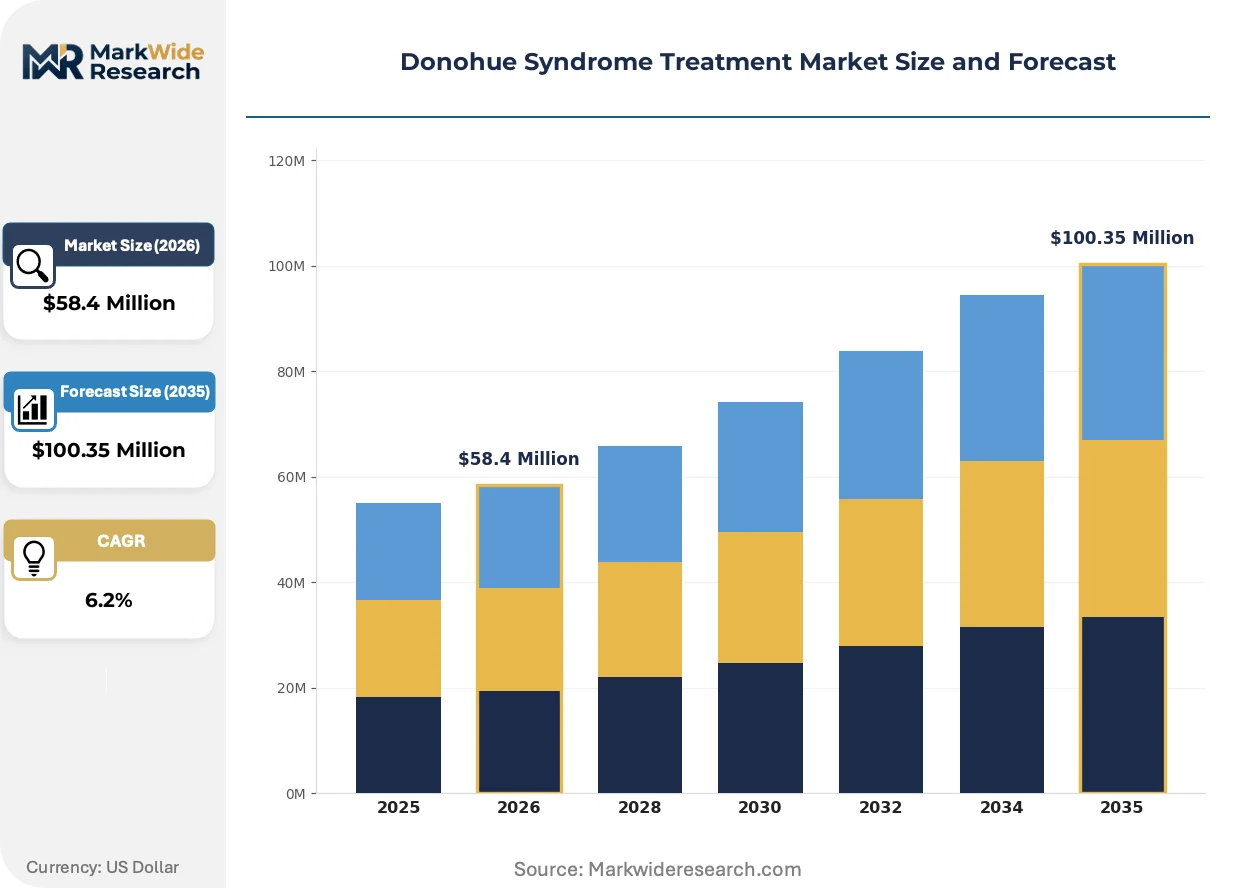
Donohue syndrome treatment encompasses therapeutic interventions for the autosomal recessive disorder caused by homozygous or compound heterozygous mutations in the INSR gene, characterized by extreme insulin resistance, fasting hypoglycemia, and postprandial hyperglycemia requiring supraphysiologic insulin dosing often exceeding 10,000 units daily. The primary purpose is metabolic stabilization and growth preservation in neonates and infants who otherwise face severe failure to thrive and early mortality. Subcutaneous injection delivery mode leads volume due to the necessity of high-dose insulin absorption, though intravenous routes retain margin concentration in acute critical care settings. Pediatric hospitals represent the dominant end user segment where multidisciplinary teams coordinate endocrinology, genetics, and intensive care, while home care providers are gaining traction as pump technology enables outpatient management of this historically inpatient-bound population.
FDA orphan drug designation and EMA's regulation on pediatric medicines shape clinical development incentives, accelerating trial design for ultra-rare indications where natural history data scarcity previously stalled enrollment. ISO 14155 governs Good Clinical Practice standards for device and drug trials, while national competent authorities in France and Germany enforce additional pharmacovigilance layering for high-dose insulin products. Stakeholders must monitor how real-world evidence frameworks evolve to support accelerated approval pathways for therapies addressing fewer than one hundred documented patients worldwide.
Market Dynamics
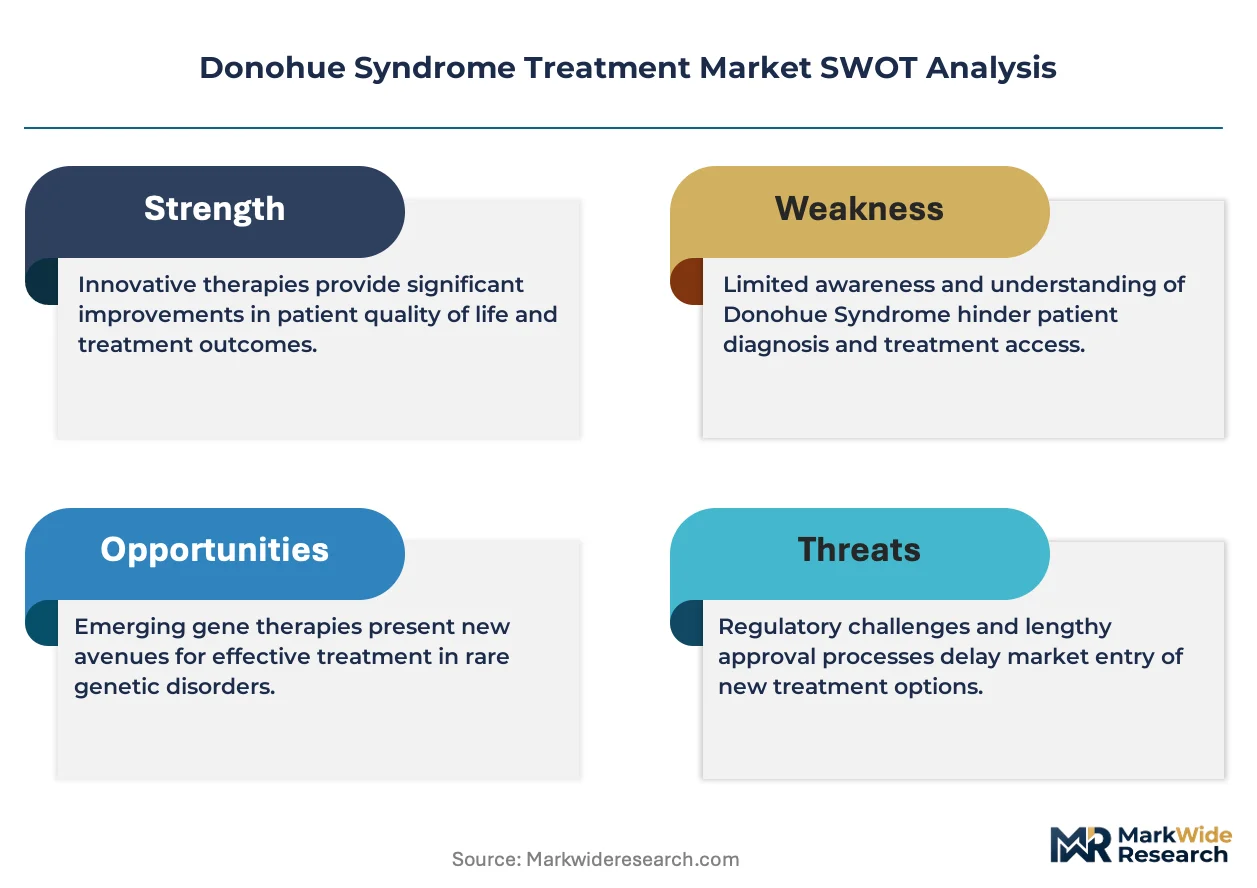
The transition from inpatient-intensive care to home-based management is compressing service delivery economics for Donohue syndrome treatment, as pump technology and remote monitoring collapse the traditional hospital-centric model.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate clinical trial enrollment for ultra-rare INSR mutations, reducing sponsor risk in patient populations below one hundred cases.
- Pediatric Hospital Expansion:Specialized metabolic disorder units in tertiary referral centers concentrate multidisciplinary expertise, shortening diagnostic timelines from months to weeks.
- Continuous Glucose Monitoring Integration:Algorithm-driven insulin delivery systems enable outpatient stabilization, extending survival windows and creating addressable patient cohorts previously lost to early mortality.
Market Restraints
- Recombinant Insulin Supply Concentration:Production of ultra-high-dose formulations depends on three dominant biologics manufacturers, creating vulnerability to batch contamination or capacity constraints.
- EMA Pediatric Investigation Plan Burden:Mandatory pediatric study requirements impose fixed costs that exceed revenue potential for therapies addressing single-digit patient counts annually.
- Genetic Diagnostic Access Gaps:INSR sequencing availability clusters in metropolitan academic centers, leaving rural and middle-income populations undiagnosed or misdiagnosed.
Strategic Opportunities
- Japan's Rare Disease Framework:PMDA's Sakigake designation pathway offers conditional approval based on single-arm trials, compressing time-to-market for Japanese neonatal intensive care units.
- Subscription-Based Monitoring Bundles:Device manufacturers are pivoting from pump hardware sales to recurring revenue models integrating sensors, algorithms, and clinical decision support.
- Real-World Evidence Pathways:FDA's Project Orbis enables simultaneous regulatory submissions across the United States, United Kingdom, and Canada, pooling sparse natural history data.
Industry Challenges
- Metabolic Geneticist Workforce Scarcity:Fellowship-trained specialists capable of interpreting INSR variant significance number fewer than two hundred across all OECD markets.
- Pump Calibration Complexity:Supraphysiologic insulin dosing requirements exceed standard device specifications, necessitating custom firmware and specialized training protocols.
- Cross-Border Reimbursement Friction:Orphan drug status in one jurisdiction rarely transfers, forcing sponsors to duplicate health technology assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Donohue Syndrome Treatment Market |
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $100.35 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Growth Hormone, Medication, Nutritional Supplements Therapy Area: Endocrinology, Metabolism Disorders, Pediatric Care, Genetic Disorders Delivery Mode: Oral, Subcutaneous Injection, Intravenous, Transdermal End User: Pediatric Hospitals, Specialty Clinics, Home Care Providers, Research Institutions |
| Companies Covered | Medtronic plc, Hoffmann-La Roche Ltd, Tandem Diabetic Care, Inc., Insulet Corporation, Ypsomed, Sooil Development, Jiangsu Delfu Co., Ltd., Becton Dickinson and Company, Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Donohue Syndrome Treatment Market Strategic Shifts
Algorithmic insulin delivery and regulatory convergence are dismantling the historical isolation between critical care and chronic disease management for extreme insulin resistance disorders.
Tubeless patch pump architectures are collapsing the infrastructure requirements for high-dose insulin administration. Pediatric endocrinology units in Germany and Japan are deploying these systems within weeks of diagnosis rather than months. The technology is collapsing the distinction between acute stabilization and long-term metabolic control, enabling discharge from neonatal intensive care at earlier gestational ages.
EMA's regulation on pediatric medicines mandates integrated development plans for all novel therapies with potential pediatric applicability. Sponsors must submit PIP applications within six months of adult investigational new drug filings, forcing parallel rather than sequential trial design. Ultra-rare disease developers are responding by embedding neonatal cohorts into Phase I protocols, accepting higher initial risk for accelerated label expansion.
Caregivers of Donohue syndrome patients are organizing digital communities that aggregate treatment experience data outside traditional clinical channels. These networks are compressing information asymmetry between families and specialists, particularly in the United States where patient advocacy groups directly fund INSR variant research. Hospital-based endocrinologists now face pressure to incorporate caregiver-reported outcomes into formal treatment protocols.
Donohue Syndrome Treatment Market Segmentation
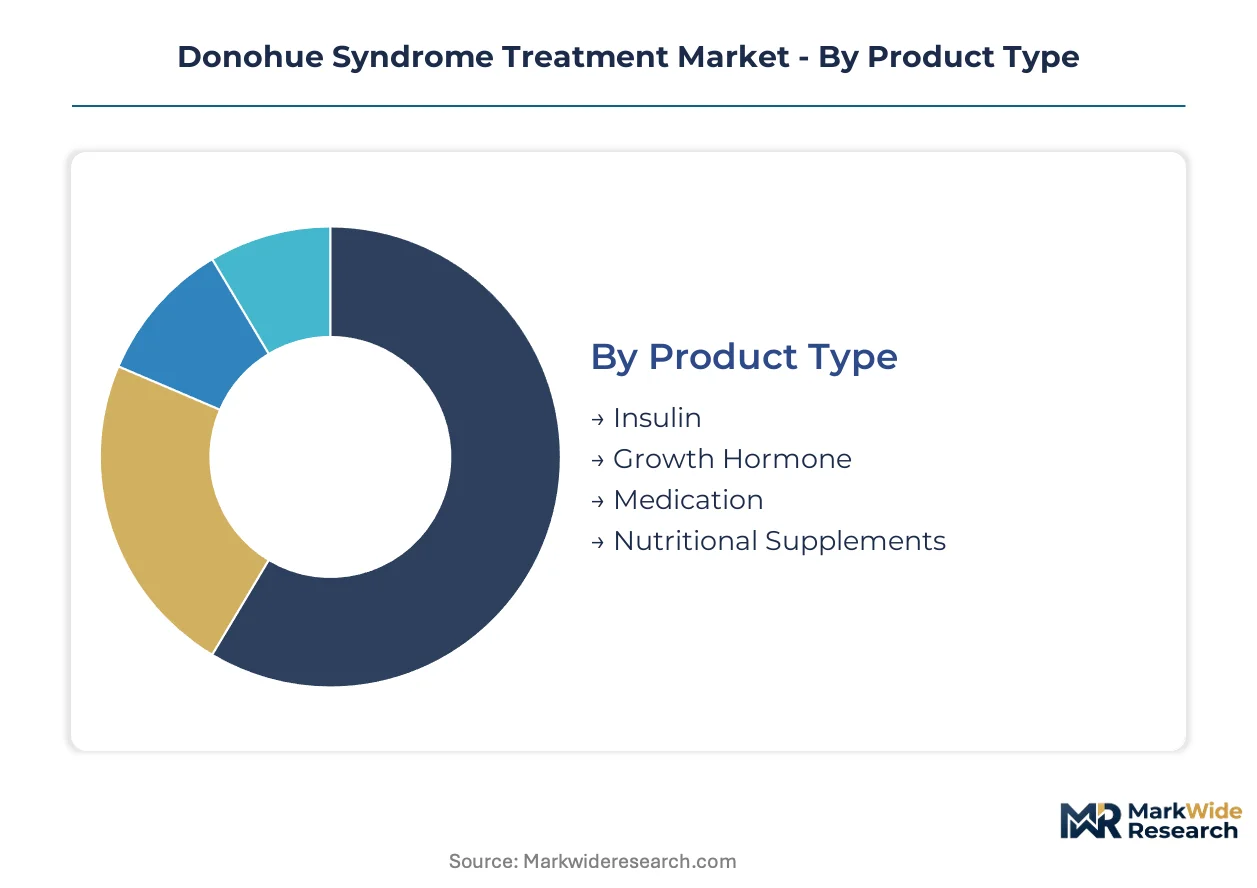
Donohue syndrome treatment demands precise segmentation because therapeutic requirements vary dramatically by disease severity, patient age, and care setting. The extreme insulin resistance phenotype necessitates product-specific dosing protocols that reshape procurement patterns across delivery channels.
Product Type:
Use-case spectrum spans acute metabolic rescue through chronic growth support, with each product category serving distinct physiological targets in INSR-mutant patients.
- Insulin:U-500 and U-1000 concentrated formulations enable subcutaneous absorption of doses exceeding 10,000 units daily. Pediatric hospitals in the United States and Germany concentrate procurement of these ultra-high-concentration products for neonatal intensive care stabilization.
- Growth Hormone:Recombinant human growth hormone adjunct therapy addresses the severe failure-to-thrive component characteristic of Donohue syndrome. Demand clusters in academic medical centers with dedicated pediatric endocrinology units capable of coordinating dual metabolic and growth protocols.
- Medication:Metformin and IGF-1 analogs provide adjunctive insulin-sensitizing and growth-promoting effects.
- Nutritional Supplements:High-calorie enteral formulations support caloric intake in infants with feeding difficulties.
Established volume favors insulin; emerging adoption favors growth hormone combination protocols.
Therapy Area:
Cost tier stratification reflects specialist availability, with metabolic genetics commanding premium reimbursement versus general pediatric endocrinology.
- Endocrinology:Core discipline managing insulin dosing algorithms and glucose monitoring integration. Tertiary referral networks in Japan and the United States anchor demand for fellowship-trained specialists capable of interpreting extreme insulin resistance patterns.
- Metabolism Disorders:Inborn errors of metabolism units provide diagnostic sequencing and multidisciplinary care coordination. Access concentrates in metropolitan academic centers with biochemical genetics laboratories, leaving rural populations dependent on telemedicine bridges.
- Pediatric Care:General pediatric services provide initial screening and referral pathways.
- Genetic Disorders:Clinical genetics services deliver INSR variant interpretation and family counseling.
Volume concentrates in endocrinology; steepest expansion trajectory belongs to metabolism disorders as diagnostic sequencing penetrates community hospitals.
Delivery Mode:
Application requirements dictate route selection, with acute stabilization demanding vascular access and chronic management favoring patient-administered alternatives.
- Subcutaneous Injection:High-volume insulin absorption via concentrated formulations enables outpatient management. Home care providers in Germany and Japan are deploying pump-based subcutaneous protocols that collapse historical inpatient dependency.
- Intravenous:Critical care settings require intravenous insulin for acute metabolic decompensation. Neonatal intensive care units retain this route for initial stabilization of hypoglycemic crises, with dosing titrated against continuous glucose monitoring outputs.
- Oral:Limited bioavailability restricts oral routes to adjunctive medications.
- Transdermal:Patch-based delivery remains experimental for insulin in this population.
Subcutaneous injection dominates chronic volume; intravenous retains acute-care margin concentration.
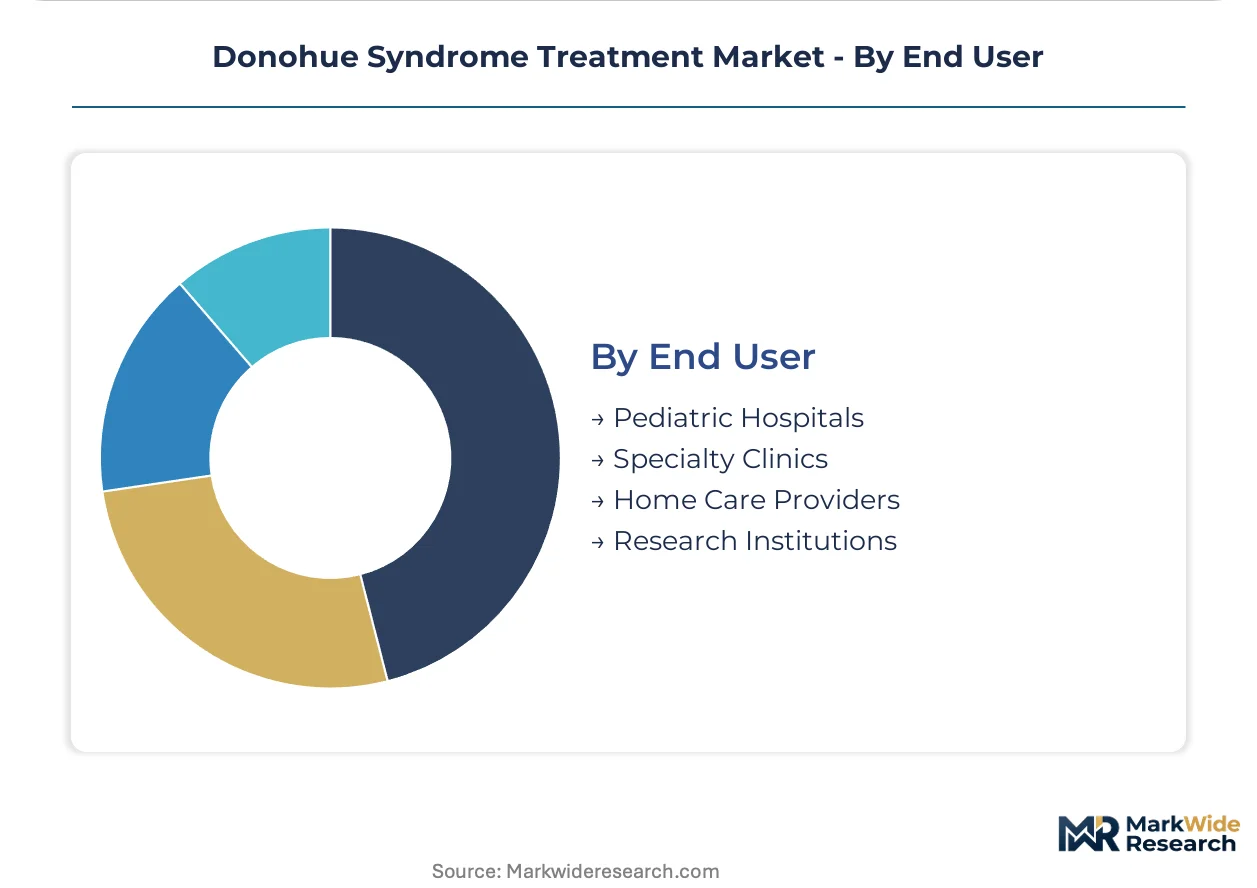
End User:
Customer type determines service intensity, with hospital-based care requiring 24-hour specialist coverage versus home-based models dependent on caregiver training.
- Pediatric Hospitals:Tertiary centers with dedicated metabolic disorder units coordinate multidisciplinary care. The United States, Germany, and Japan concentrate the highest-density referral networks for ultra-rare endocrine conditions.
- Home Care Providers:Pump technology and remote monitoring enable discharge to outpatient management. Japanese home nursing services are expanding specialized training programs for high-dose insulin administration in neonatal patients.
- Specialty Clinics:Outpatient endocrinology practices provide follow-up care for stabilized patients.
- Research Institutions:Academic centers conduct natural history studies and clinical trials under FDA and EMA orphan drug frameworks.
Pediatric hospitals anchor current volume; home care providers are gaining share fastest as device technology enables earlier discharge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement elasticity varies sharply across geographies, with United States payers absorbing premium pricing for ultra-rare therapies while German statutory insurers negotiate outcome-based discounts and Japanese municipal governments face budget constraints for neonatal intensive care.
United States
Academic medical centers in Boston and New York anchor referral networks for INSR mutation diagnostics. FDA orphan drug tax credits reduce clinical trial costs for sponsors developing high-dose insulin formulations. Texas Children's Hospital and Children's Hospital of Philadelphia coordinate multidisciplinary metabolic disorder units that shorten diagnostic timelines.
Germany
Bavarian university hospitals concentrate pediatric endocrinology expertise with dedicated metabolic genetics laboratories. EMA pediatric investigation plans mandate parallel neonatal cohort enrollment, accelerating label expansion for ultra-rare indications. Heidelberg and Munich clusters deploy tubeless patch pump systems for earlier neonatal intensive care discharge.
Japan
PMDA's Sakigake designation enables conditional approval based on single-arm trials, compressing regulatory timelines for Tokyo and Osaka neonatal units. METI rare disease funding supports domestic production of concentrated insulin formulations. Yokohama-based home nursing services expand specialized training for high-dose outpatient administration.
United Kingdom
NHS England's specialized commissioning framework pools funding for ultra-rare endocrine conditions across London and Manchester referral networks. MHRA alignment with FDA Project Orbis facilitates simultaneous regulatory submissions. Cambridge and Oxford academic centers lead natural history data collection for INSR variant registries.
Switzerland
Swissmedic expedited pathways for orphan medicines attract sponsor headquarters to Basel and Zurich. Cantonal hospital networks in Geneva and Lausanne coordinate cross-border care for French and Italian patients. Private insurance dominance enables premium pricing for concentrated insulin products unavailable through neighboring statutory systems.
Donohue Syndrome Treatment Market Competitive Environment
Integrated diagnostics-to-therapeutics conglomerates and specialized pump technology developers split the market along capability lines. The structure concentrates around firms with captive supply of companion testing or proprietary algorithmic delivery systems. Three archetypes dominate: diversified medtech holding companies, insulin delivery device specialists, and biologics manufacturers with metabolic disorder portfolios. Competitive moves center on algorithm licensing partnerships and backward integration into continuous glucose monitoring sensor production.
Within the diversified medtech tier, Hoffmann-La Roche Ltd and Medtronic plc exemplify integrated diagnostics-to-therapeutics positioning. Among pump technology specialists, Tandem Diabetic Care, Inc. and Insulet Corporation occupy positions defined by automated delivery algorithms and tubeless architectures respectively. These named entities anchor archetype categories rather than representing discrete strategic actions, with geographic origins reflecting Basel-based pharmaceutical heritage and California-incorporated device development clusters.
| Leading Market Players |
|---|
| Medtronic plc |
| Hoffmann-La Roche Ltd |
| Tandem Diabetic Care, Inc. |
| Insulet Corporation |
| Ypsomed |
| Sooil Development |
| Jiangsu Delfu Co., Ltd. |
| Becton Dickinson and Company |
| Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in recombinant insulin production for ultra-high-concentration formulations is tightening supplier leverage and compressing procurement flexibility for pediatric hospitals managing Donohue syndrome patients. This utilization squeeze is amplifying price premiums for U-500 and U-1000 products while forcing device manufacturers to absorb calibration complexity costs within bundled subscription offerings.
Pricing Analysis
Aftermarket service contracts for pump maintenance and firmware customization now drive lifetime value capture exceeding hardware margins. Subscription-based continuous glucose monitoring bundles with embedded insulin delivery algorithms command premium positioning against transactional pump sales. Cost compression in standard insulin formulations is intensifying because concentrated biologics production rests on three dominant manufacturers. Academic medical centers with dedicated metabolic disorder units exhibit lowest price sensitivity due to captive patient volumes and orphan drug reimbursement guarantees, while community hospitals face acute budget constraints for ultra-rare disease protocols.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for concentrated insulin procurement as biologics manufacturers manage working capital through supply-chain finance facilities. Production of U-500 and U-1000 formulations concentrates in the United States, Denmark, and Germany where fermentation capacity and cold-chain infrastructure anchor supply. Raw material dependencies include recombinant DNA cell lines, pharmaceutical-grade excipients, and specialized pump polymers. Single-source vulnerability in INSR genetic testing kits creates diagnostic bottlenecks that delay treatment initiation. Distribution runs through hospital purchasing committees and specialized metabolic disorder unit procurement channels rather than wholesale pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Donohue syndrome treatment market is entering a cyclical recovery phase as algorithmic insulin delivery systems collapse historical inpatient dependency and extend patient survival windows. FDA orphan drug incentive renewal and EMA pediatric investigation plan streamlining are restoring sponsor confidence in ultra-rare disease development.
For Market Incumbents: Harden algorithmic delivery capabilities through backward integration into continuous glucose monitoring sensor production, neutralizing substitute threats from standalone CGM developers. Secure exclusive firmware customization partnerships with pediatric hospital networks in Boston and Heidelberg to lock in referral channel control. Deepen captive supply of companion INSR diagnostic testing to sustain diagnostics-to-therapeutics integration against emerging molecular diagnostic entrants. For New Entrants and Emerging Players: Establish a beachhead in Japanese home nursing services where PMDA Sakigake designation compresses regulatory timelines and municipal rare disease funding supports premium reimbursement. Target white-space in tubeless patch pump training protocols for neonatal patients, a segment where incumbent device manufacturers lack specialized pediatric expertise. Deploy direct-to-clinic go-to-market models bypassing traditional hospital purchasing committee friction through metabolic geneticist specialist relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device manufacturers with algorithmic insulin delivery platforms and subscription-based monitoring bundles, offering superior cash flow quality against transactional biologics suppliers. Long-term viability favors firms with integrated diagnostics capabilities and regulatory approval across FDA, EMA, and PMDA jurisdictions. Acquisition targets should display proprietary firmware for supraphysiologic dosing and established pediatric hospital relationships. The signal to watch is FDA Project Orbis expansion to additional regulatory authorities, which would compress approval timelines and accelerate addressable patient pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA tax credits reduce clinical trial costs for INSR mutation therapies below hundred-patient populations. |
| Algorithmic Delivery Platform Integration | Tandem Diabetic Care anchors market position through automated insulin delivery dominating Type A insulin resistance. |
| Pediatric Investigation Plan Alignment | EMA mandates force parallel neonatal cohort enrollment, accelerating label expansion for ultra-rare indications. |
| Tubeless Patch Pump Architecture Deployment | Insulet Corporation collapses infrastructure requirements for high-dose home administration in German and Japanese markets. |
| Real-World Evidence Registry Development | Cambridge and Oxford academic centers pool natural history data to support FDA Project Orbis simultaneous submissions. |
Study Parameters
Initial hypotheses were tested against primary input from pediatric endocrinologists, metabolic geneticists, hospital procurement managers, and regulatory affairs specialists at orphan drug sponsors, then refined against secondary validation. Sources included FDA orphan drug designation filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov ultra-rare disease protocols, and hospital GPO contract databases. Bottom-up patient volume estimates across United States, German, and Japanese referral networks were triangulated with top-down market sizing from concentrated insulin procurement data.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation by product type, therapy area, delivery mode, and end user informing volume allocation. CAGRs were derived from patient survival extension curves and pump technology penetration rates in neonatal intensive care discharge protocols. Forecast inputs incorporated PMDA Sakigake approval timelines and METI rare disease funding trajectories.
Sensitivities concentrate around regulatory pathway modifications, recombinant insulin manufacturing capacity constraints, and metabolic geneticist workforce availability. Forecasts reflect documented assumptions regarding patient identification rates and reimbursement stability for ultra-high-dose therapies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market