
 Global Contrast Enhanced Digital Mammography (CEDM) Market | 2026-2036
Global Contrast Enhanced Digital Mammography (CEDM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contrast Enhanced Digital Mammography (CEDM) Market Foresight
Germany is reconfiguring its radiology infrastructure around dual-energy CEDM platforms, creating procurement corridors for systems that integrate with existing PACS networks. Siemens Healthineers leverages its domestic manufacturing base to anchor supply relationships with university hospitals across Bavaria and Baden-Württemberg. Hologic, Inc. competes through specialized detector architectures optimized for low-dose contrast protocols. GE Healthcare differentiates via software ecosystems that bridge mammography with downstream oncology workflows.
Contrast Enhanced Digital Mammography combines iodinated contrast administration with digital mammographic acquisition to visualize tumor neovascularization beyond conventional anatomical imaging, typically employing dual-energy subtraction or temporal subtraction techniques at 25–35 kVp tube voltages to isolate contrast uptake patterns. The technology serves primarily to improve diagnostic accuracy in women with dense breast parenchyma where standard mammography sensitivity drops substantially. Digital Mammography Systems and Tomosynthesis-Integrated platforms represent the mature revenue base where replacement cycles and upgrade pathways concentrate near-term spending. CEDM Software and Photon-Counting detector technology constitute faster-growing pockets where development timelines and clinical validation investments determine competitive entry.
FDA 510(k) pathways and EMA medical device regulation under MDR govern system approvals on both sides of the Atlantic, while the EU AI Act introduces conformity obligations for embedded computer-aided detection algorithms that classify lesions automatically. Japan's PMDA maintains distinct clinical evidence requirements for contrast-enhanced breast imaging that shape product registration strategies for vendors targeting that market. Stakeholders must track reimbursement decisions by national health technology assessment bodies as these determine whether CEDM shifts from supplemental to standard-of-care positioning in screening programs.
Market Dynamics
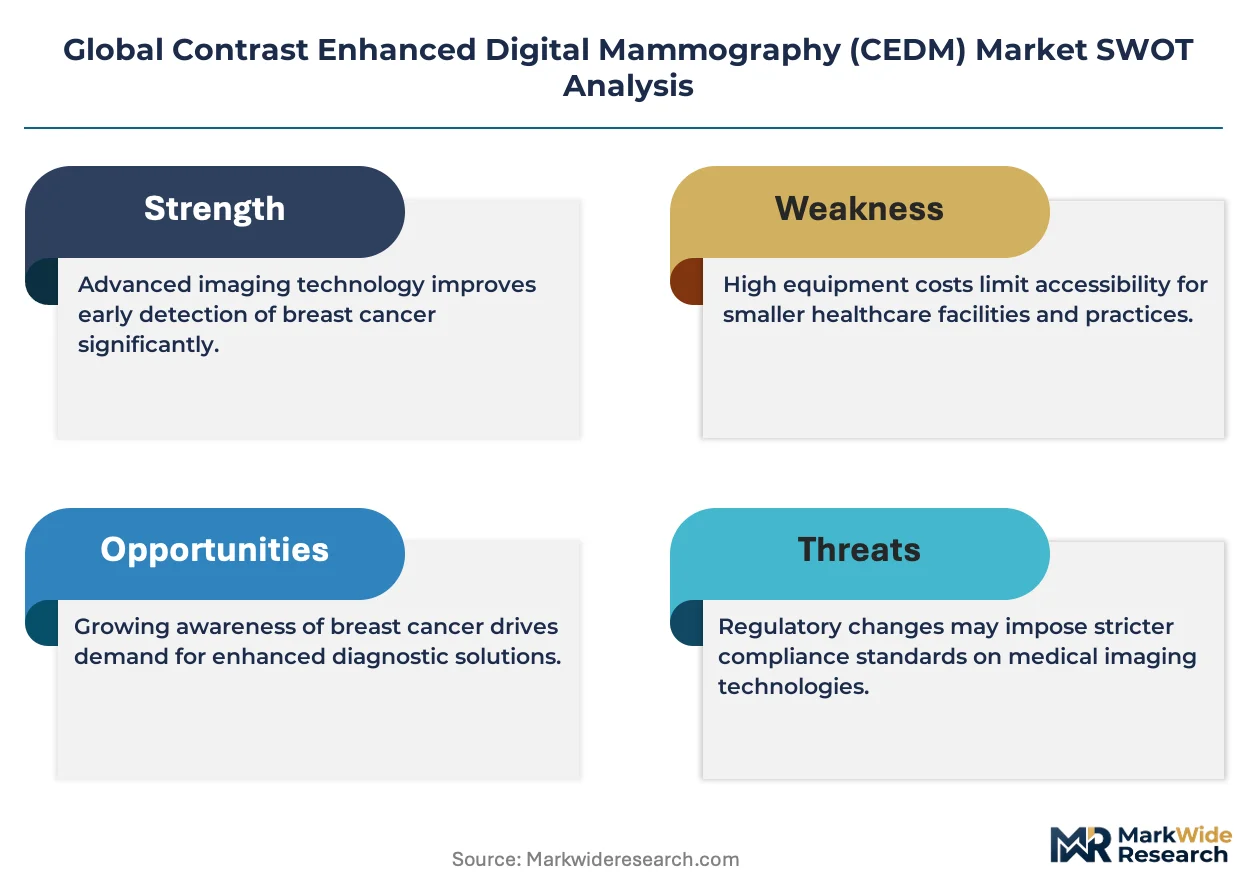
Dual-energy subtraction protocols are compressing acquisition times while expanding diagnostic throughput, forcing incumbent vendors to re-architect detector electronics and software pipelines around photon-counting sensitivity rather than legacy scintillator-based signal chains.
Growth Catalysts
- Dense breast tissue protocols:Screening guidelines in the United States now explicitly address mammographic density assessment, channeling supplemental imaging referrals toward CEDM-capable facilities.
- EMA MDR streamlining:The European Medical Device Regulation's consolidated conformity pathways reduce redundant clinical testing for contrast-enhanced imaging systems already holding FDA 510(k) clearance.
- Photon-counting sensitivity:Next-generation detector materials achieve single-photon discrimination at 25–35 kVp, enabling iodinated contrast visualization at dose profiles competitive with standard mammography.
Market Restraints
- Iodinated contrast supply concentration:Three manufacturers control 80% of non-ionic iodinated contrast agent production, exposing imaging centers to allocation disruptions during supply shocks.
- Capital equipment replacement cycles:Digital mammography systems operate on 8–12 year depreciation schedules, slowing CEDM upgrade penetration outside dedicated breast imaging centers.
- Substitution by abbreviated MRI:Fast breast MRI protocols compete directly for dense tissue evaluation referrals in markets with favorable MRI reimbursement.
Strategic Opportunities
- India diagnostic expansion:Private hospital chains in Mumbai and Delhi are installing CEDM-capable systems as anchor services for medical tourism and premium women's health packages.
- AI-embedded lesion classification:The EU AI Act's conformity framework for Class IIa medical device software creates first-mover advantages for vendors with pre-validated computer-aided detection algorithms.
- Tomosynthesis convergence:Integration of contrast-enhanced protocols with digital breast tomosynthesis acquisition enables single-visit structural and vascular assessment.
Industry Challenges
- Radiologist training pipelines:Contrast-enhanced mammography interpretation requires specialized fellowship training in vascular kinetics and subtraction artifact recognition, constraining deployment velocity.
- PACS integration complexity:Dual-energy DICOM objects demand storage and display capabilities beyond standard mammography workstations, forcing IT infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contrast Enhanced Digital Mammography (CEDM) Market |
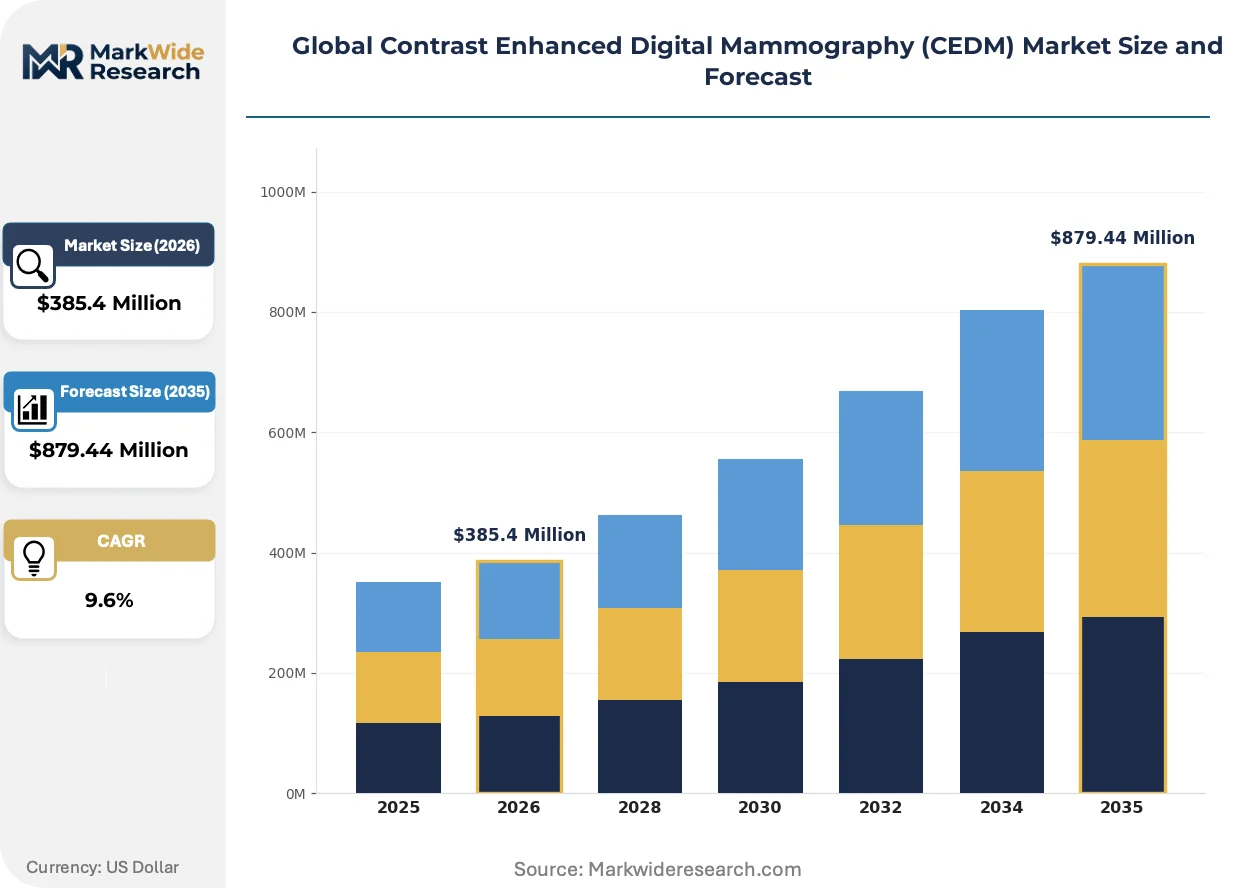
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $879.44 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography Systems, CEDM Software, Imaging Detectors, Contrast Agents, Workstations Technology: Dual-Energy Imaging, Spectral Mammography, Photon-Counting, Tomosynthesis-Integrated, Computer-Aided Detection Application: Breast Cancer Screening, Diagnostic Imaging, Treatment Monitoring, Lesion Characterization, Risk Assessment End User: Radiology Clinics, Specialized Imaging Centers, Ambulatory Surgical Centers, Academic Medical Facilities, Mobile Screening Units |
| Companies Covered | Hologic, Inc., GE Healthcare, Siemens Healthineers, Planmed Oy, Fujifilm Medical Systems, Koninklijke Philips NV, Allengers, Carestream Health, Metaltronica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contrast Enhanced Digital Mammography (CEDM) Market Shifts & Advancements
Photon-counting detector architectures are compressing dose-performance tradeoffs while software-defined acquisition protocols enable vendor-agnostic image reconstruction, shifting competitive differentiation from hardware specifications to clinical workflow integration.
Spectral imaging is rendering obsolete conventional energy-integrating detectors that sacrifice spatial resolution for contrast sensitivity. Academic medical centers in Germany and Japan are deploying pre-commercial photon-counting arrays for research protocols. The technology is rendering obsolete the historical compromise between low-dose operation and iodinated contrast detectability that constrained CEDM adoption in screening populations.
The EU AI Act's risk-classification framework for medical device software imposes conformity assessment obligations on embedded lesion detection algorithms. Vendors must document training data provenance and performance validation across demographic subgroups. Breast imaging systems with computer-aided detection modules face 12–18 month extended timelines for CE marking under the new requirements.
Hospital procurement committees are unbundling service contracts from equipment financing, compressing vendor margins on multi-year maintenance agreements. Tertiary hospitals in the United States now separately negotiate detector replacement schedules and software upgrade entitlements. Radiology departments in Japan pioneered this disaggregation, forcing equipment vendors to price hardware, installation, and ongoing support as distinct line items.
Global Contrast Enhanced Digital Mammography (CEDM) Market Segmentation
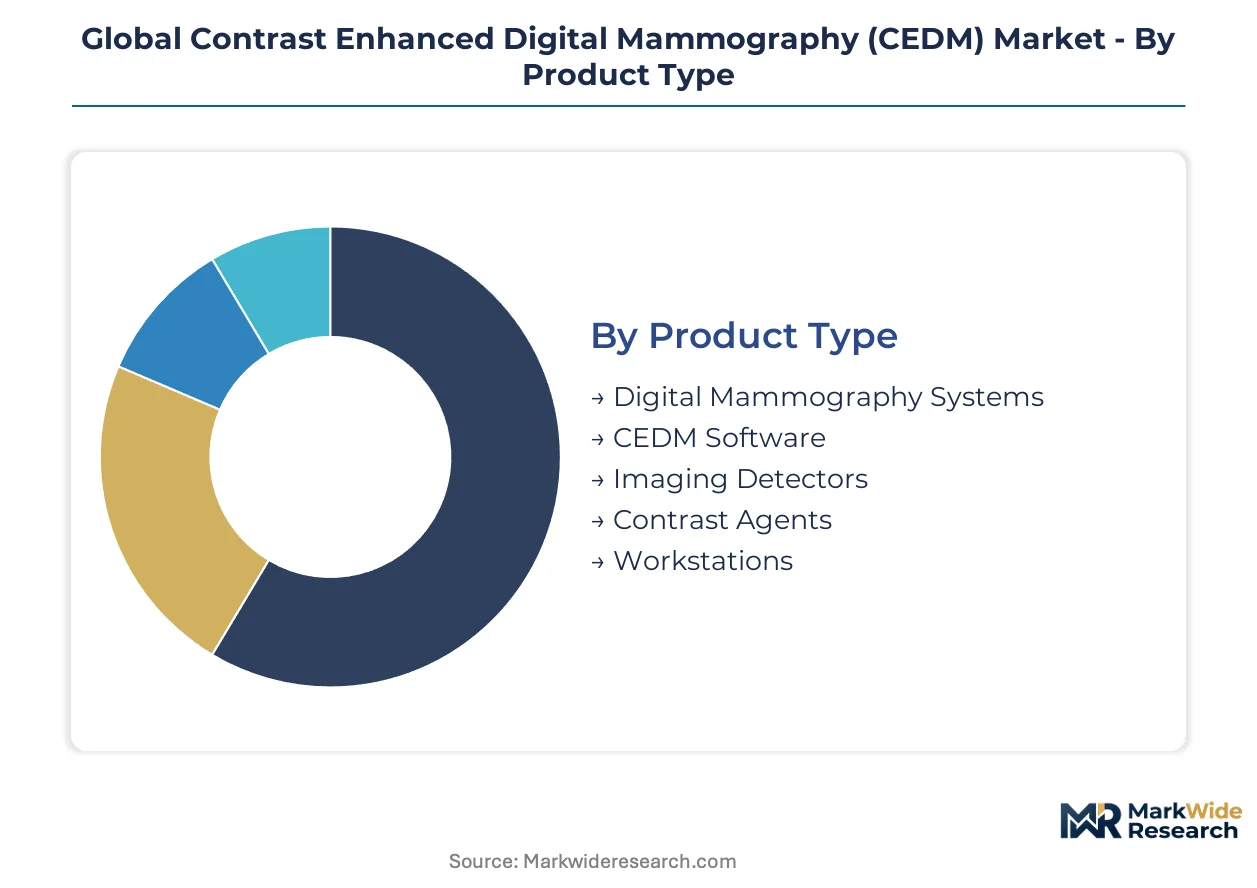
Segmentation in the CEDM market reveals distinct procurement rhythms across hardware, software, and consumable categories. Equipment replacement cycles stretch across decades while software refresh and contrast agent replenishment operate on compressed timelines, creating heterogeneous revenue recognition patterns for vendors.
Product Type:
Hardware systems dominate capital expenditure cycles with 8–12 year depreciation schedules, whereas software and consumables turn over within 1–3 year windows, generating recurring revenue streams that stabilize vendor cash flows.
- Digital Mammography Systems:Full-field digital mammography platforms with CEDM capability require gantry modifications for dual-energy acquisition and specialized filtration. Demand concentrates in tertiary hospitals across Germany and the United States where reimbursement for supplemental breast imaging has stabilized. These systems anchor replacement-driven procurement.
- CEDM Software:Image reconstruction algorithms, subtraction protocols, and vascular kinetic analysis tools process raw dual-energy data into diagnostic images. Academic medical facilities in Germany and the United States are expanding adoption for dense breast tissue evaluation, driving license renewal cycles.
- Imaging Detectors:Scintillator-based and photon-counting detector arrays capture X-ray attenuation at 25–35 kVp tube voltages.
- Contrast Agents:Non-ionic iodinated formulations enable vascular visualization through tumor neovascularization.
- Workstations:Specialized display and analysis terminals handle dual-energy DICOM objects beyond standard mammography capabilities.
Digital Mammography Systems anchors the volume base while CEDM Software gains share at the steepest rate.
Technology:
Technology selection in CEDM procurement tracks facility sophistication and patient throughput requirements, with premium photon-counting architectures commanding price multiples over legacy energy-integrating approaches.
- Dual-Energy Imaging:Subtraction protocols acquire high- and low-energy exposures to isolate iodinated contrast uptake from background tissue attenuation. Tertiary hospitals across the United States favor this approach for its diagnostic throughput advantages in high-volume screening programs.
- Spectral Mammography:Energy-resolved detection enables material decomposition without temporal separation between exposures. Specialized imaging centers in Japan are deploying these systems for research protocols examining multi-energy tissue characterization.
- Photon-Counting:Single-photon discrimination at diagnostic energies achieves dose profiles competitive with standard mammography.
- Tomosynthesis-Integrated:Combined contrast-enhanced and three-dimensional structural acquisition enables single-visit comprehensive assessment.
- Computer-Aided Detection:Embedded algorithms for lesion classification face extended regulatory timelines under the EU AI Act's conformity framework.
Dual-Energy Imaging captures the dominant installed base while Photon-Counting expands most quickly among upgrade decisions.
Application:
Application segmentation reflects the progression from population screening through diagnostic confirmation to therapeutic monitoring, with reimbursement structures determining which indications justify contrast administration costs.
- Breast Cancer Screening:Population-scale mammography programs incorporate CEDM for women with dense breast parenchyma where standard mammography sensitivity drops substantially. Screening guidelines in the United States now explicitly address mammographic density assessment, channeling supplemental imaging referrals toward capable facilities.
- Diagnostic Imaging:Problem-solving examinations clarify indeterminate findings from conventional mammography or physical examination. Radiology clinics across Germany are configuring dedicated CEDM protocols for this indication, supported by favorable national health technology assessment positioning.
- Treatment Monitoring:Serial contrast-enhanced examinations track neoadjuvant chemotherapy response through vascular changes.
- Lesion Characterization:Vascular kinetic patterns distinguish malignant from benign enhancing masses.
- Risk Assessment:Baseline vascular mapping informs surveillance intensity for high-risk patient cohorts.
Diagnostic Imaging generates the highest procedure volume while Breast Cancer Screening demonstrates the steepest expansion trajectory as density notification laws proliferate.
End User:
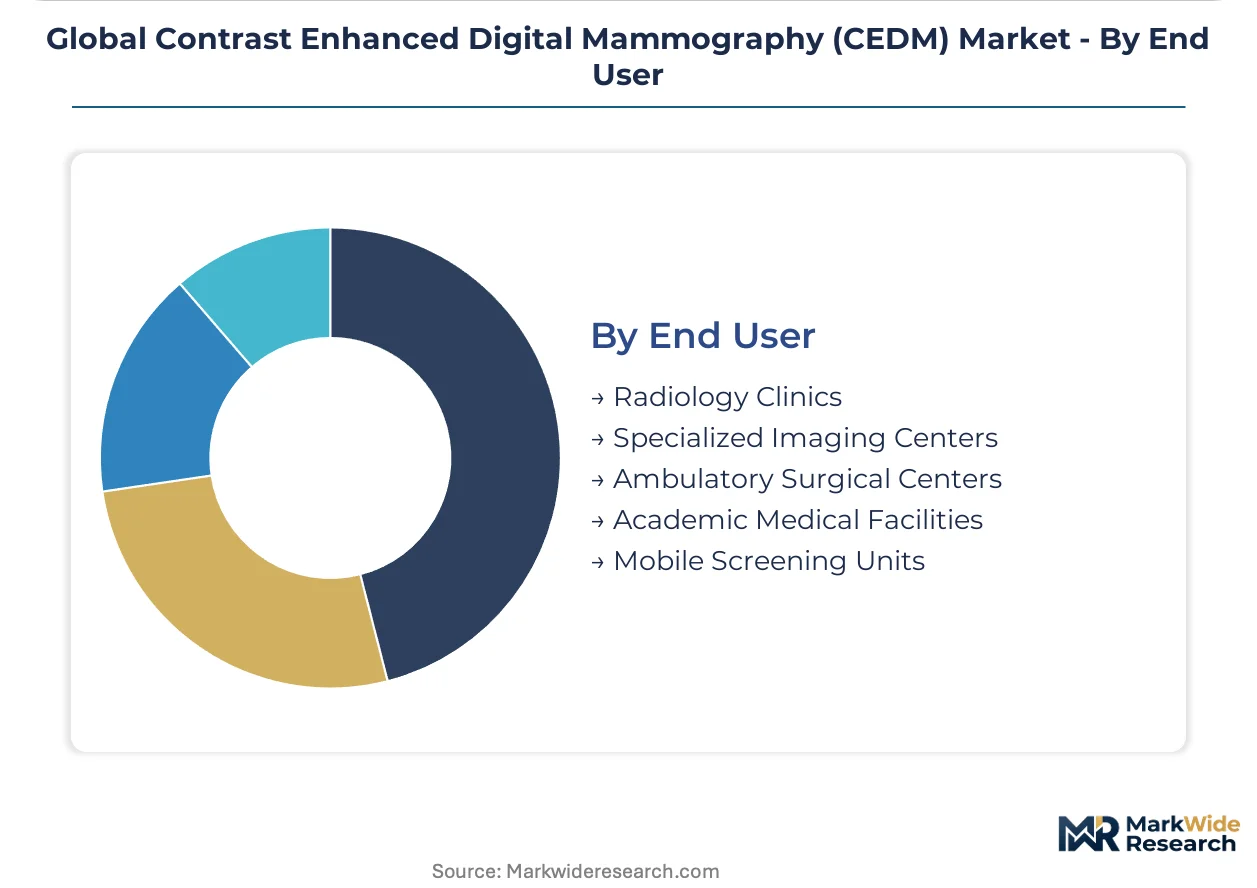
End user segmentation maps to capital intensity, patient volume, and academic mission, with procurement authority residing at hospital system level for integrated delivery networks and at departmental level for independent imaging centers.
- Radiology Clinics:Independent diagnostic facilities perform outpatient breast imaging with CEDM capability as a competitive differentiator. Private hospital chains in Mumbai and Delhi are installing systems as anchor services for medical tourism and premium women's health packages.
- Specialized Imaging Centers:Dedicated breast imaging facilities concentrate expertise and equipment for complex diagnostic cases. Academic medical facilities in Germany and the United States are expanding CEDM adoption for dense breast tissue evaluation, driving procurement of research-capable platforms.
- Ambulatory Surgical Centers:Limited deployment for preoperative lesion localization in select markets.
- Academic Medical Facilities:Research protocols and training programs drive demand for configurable acquisition platforms.
- Mobile Screening Units:Deployed for rural access programs with constrained CEDM adoption due to contrast administration logistics.
Radiology Clinics anchor the volume base while Specialized Imaging Centers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Berlin rail corridor and Rhine-Ruhr logistics network anchor European distribution of high-value medical imaging equipment, while Pacific port infrastructure in Los Angeles and Yokohama underwrite transoceanic supply chains for detector components and contrast agent precursors.
United States
Dense breast tissue notification laws in 38 states channel supplemental imaging referrals toward CEDM-capable facilities. FDA 510(k) clearance pathways streamline product entry for dual-energy subtraction platforms. Tertiary hospitals across Texas and California anchor replacement-driven procurement of photon-counting architectures.
Germany
University hospitals in Bavaria and Baden-Württemberg drive research-protocol adoption of spectral mammography systems. EMA MDR consolidated conformity pathways reduce redundant clinical testing for vendors holding prior FDA clearance. The Rhine-Main manufacturing corridor hosts domestic production of detector arrays and gantry assemblies.
Japan
Specialized imaging centers in Tokyo and Osaka deploy pre-commercial photon-counting arrays for vascular kinetic research. PMDA maintains distinct clinical evidence requirements that shape registration strategies for contrast-enhanced breast imaging vendors. The Kansai region concentrates academic medical facility procurement of configurable acquisition platforms.
India
Private hospital chains in Mumbai and Delhi install CEDM-capable systems as anchor services for medical tourism and premium women's health packages. CDSCO medical device registration timelines compress for products holding prior FDA or EMA approvals. The Delhi-NCR corridor emerges as a diagnostic expansion hub for dense tissue evaluation protocols.
Global Contrast Enhanced Digital Mammography (CEDM) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector materials and contrast agent formulation. The vendor base separates into three strategic archetypes: diversified imaging conglomerates with full-stack mammography portfolios, regional equipment fabricators serving price-sensitive procurement committees, and software-defined specialists embedding AI classification modules. Competitive moves concentrate on photon-counting detector supply partnerships and service contract unbundling to defend margin positions.
Among diversified imaging conglomerates, Hologic, Inc., GE Healthcare, and Siemens Healthineers occupy positions across the hardware-software spectrum. Hologic represents the specialized detector architecture archetype with domestic manufacturing concentration. GE Healthcare exemplifies software ecosystem differentiation bridging mammography with oncology workflows. Siemens Healthineers anchors supply relationships through its Baden-Württemberg production base.
| Leading Market Players |
|---|
| Hologic, Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Planmed Oy |
| Fujifilm Medical Systems |
| Koninklijke Philips NV |
| Allengers |
| Carestream Health |
| Metaltronica |
| Others |
Supply & Pricing Matrix
Overcapacity in scintillator-based detector fabrication across the Rhine-Main corridor is compressing margins for legacy energy-integrating architectures while photon-counting foundries command premium pricing. This utilization asymmetry shapes vendor procurement posture and accelerates tiered pricing stratification across hardware generations.
Pricing Analysis
Three-tier pricing structure across premium photon-counting, standard dual-energy, and economy retrofit configurations dominates capital equipment transactions. Price differentiation stems from detector certification grade under FDA 510(k) and EMA MDR pathways plus geographic delivery cost from Baden-Württemberg versus Asian contract manufacturing. Pricing pressure intensifies in standard-tier systems as hospital procurement committees unbundle service contracts from hardware financing. Radiology clinics in India exhibit highest price sensitivity due to capital constraints, while academic medical facilities in Germany demonstrate lowest sensitivity given research funding access.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized detector foundries in Germany, Japan, and South Korea for photon-counting arrays, while gantry assembly clusters in China and Mexico handle mechanical integration. Raw material dependencies center on high-purity cadmium telluride substrates, iodinated contrast agent precursors from Indian pharmaceutical manufacturers, and precision tungsten filtration components. Single-source vulnerability in non-ionic iodinated contrast production exposes imaging centers to allocation disruptions. Distribution runs through hospital procurement committees and GPO contracts in the United States, direct vendor relationships in Germany, and private hospital chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CEDM platform economics is approaching an inflection where software-defined acquisition protocols and vendor-agnostic image reconstruction are displacing hardware-locked ecosystems. Interoperability with existing PACS networks and oncology information systems now determines procurement outcomes more than detector specifications alone.
For Market Incumbents: Build switching-cost moats through deep PACS integration and captive service contract architectures. Siemens Healthineers should anchor detector supply relationships with university hospitals through research protocol co-development, while Hologic must defend against abbreviated MRI substitution by compressing dual-energy acquisition times. Backward integration into photon-counting materials secures margin protection against foundry pricing power. For New Entrants and Emerging Players: Establish a beachhead in India's private diagnostic expansion corridor where CDSCO registration timelines compress for FDA-cleared products. Target radiology clinics in Mumbai and Delhi with configurable CEDM software licenses that retrofit existing digital mammography gantries. Go-to-market leverage rests on AI-embedded lesion classification modules that accelerate CE marking under EU AI Act conformity frameworks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined specialists with validated computer-aided detection algorithms and renewable license structures. Long-term viability favors vendors bridging mammography with downstream oncology workflows rather than pure hardware fabricators. Acquisition targets should demonstrate installed base penetration in at least two of Germany, the United States, and Japan. Watch photon-counting detector yield rates as the inflection signal for cost-competitive screening deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Supply Partnership | Secures dose-competitive positioning for screening program eligibility under FDA guidance. |
| AI-Companion Software CE Marking Pathway | Accelerates EU market entry ahead of extended EU AI Act conformity timelines. |
| Hospital System Partnership | Locks multi-site procurement through integrated PACS and oncology workflow connectivity. |
| Reimbursement Strategy | Positions CEDM for standard-of-care migration via national health technology assessment engagement. |
| Service Contract Unbundling Response | Defends margin compression by pricing hardware, installation, and support as distinct offerings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates across screening, diagnostic, and monitoring applications were triangulated against top-down capital equipment shipment data from detector manufacturers and gantry assemblers.
Calibration against historical replacement cycles and upgrade penetration rates anchored the analytical framework across the analysis window. Segmentation modeling captured product type, technology architecture, clinical application, and end-user facility category. CAGRs were derived from procedure volume growth trajectories and capital expenditure intensity patterns, with specific inputs from dense breast tissue notification law proliferation and photon-counting detector commercialization timelines.
Sensitivities concentrate around iodinated contrast supply disruptions, photon-counting yield rate improvements, and reimbursement decisions by national health technology assessment bodies. Forecasts reflect documented assumptions regarding screening guideline evolution and regulatory pathway streamlining. Quarterly review of FDA 510(k) clearance volumes, EMA MDR certification timelines, and hospital procurement database entries is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
US Imaging Services Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Ultrasound Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market