
 Carotid Ultrasound Imaging Market | 2026-2036
Carotid Ultrasound Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Carotid Ultrasound Imaging Market Outlook
High-frequency transducer specifications above 7 MHz is reorganizing procurement criteria across vascular imaging departments. Siemens Healthineers leverages its transducer manufacturing scale to dominate premium platform configurations. GE Healthcare anchors its position through deep integration of Doppler algorithms with hospital IT networks. Koninklijke Philips N.V. competes by specializing in portable-to-tablet workflow continuity for emergency stroke protocols.
Carotid ultrasound imaging employs high-frequency sound waves, typically 5–15 MHz, to generate real-time images of the common carotid, internal carotid, and external carotid arteries for detecting stenosis, plaque morphology, and intima-media thickness. Its primary purpose is non-invasive assessment of cerebrovascular risk prior to ischemic events. Portable ultrasound systems now lead volume shipments as diagnostic centers prioritize mobility for bedside and outpatient deployment. Doppler ultrasound commands the technology margin pool due to its indispensability in hemodynamic quantification, while contrast-enhanced ultrasound represents the fastest-expanding segment as microbubble agents gain procedural reimbursement. Software solutions remain a mature, high-recurring-revenue category tethered to hardware replacement cycles.
FDA 510(k) pathways and the EU Medical Device Regulation govern device approval, software validation, and post-market surveillance, directly shaping R&D allocation and commercialization timelines for manufacturers. In the United States, CMS reimbursement codes for carotid duplex scanning determine hospital capital budgeting rhythms and equipment refresh priorities. Stakeholders must monitor evolving AI-enabled diagnostic criteria and their interaction with existing regulatory frameworks for autonomous clinical decision support.
Market Dynamics
Portable system miniaturization is compressing capital deployment timelines and redistributing purchasing authority from centralized radiology departments toward emergency medicine and outpatient vascular clinics.
Growth Catalysts
- CMS reimbursement codes for carotid duplex scanning:Hospital capital budgeting cycles now prioritize equipment refresh in the United States as these codes stabilize revenue predictability for cerebrovascular screening programs.
- Outpatient vascular clinics in Germany:These facilities are upgrading from 2D to Doppler-capable platforms, creating concentrated demand for mid-range systems with hemodynamic quantification features.
- Contrast-enhanced ultrasound microbubble agents:Procedural reimbursement expansion for this technology is accelerating clinical validation and adoption across stroke risk stratification protocols.
Market Restraints
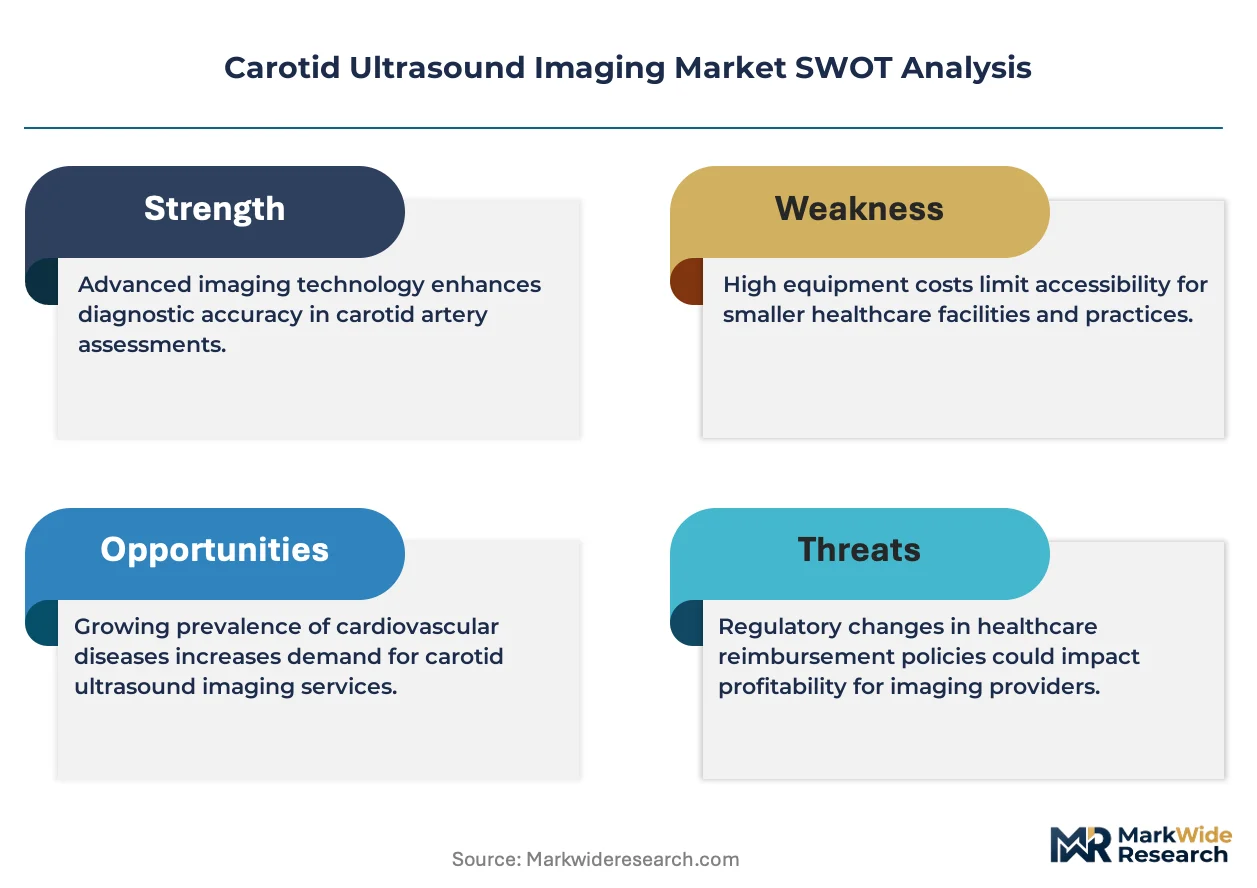
- High-frequency transducer manufacturing concentration:Production of transducers above 7 MHz relies on specialized piezoelectric material suppliers concentrated in East Asia, creating input vulnerability.
- EU Medical Device Regulation compliance costs:Software validation and post-market surveillance requirements for AI-enabled diagnostic features are extending commercialization timelines by 12-18 months for smaller manufacturers.
- CT angiography substitution threat:Hospitals with existing CT capacity increasingly default to this alternative for complex plaque characterization, limiting ultrasound penetration in tertiary care.
Strategic Opportunities
- Point-of-care stroke screening in India:Neurology departments in tier-2 cities lack dedicated vascular imaging infrastructure, creating whitespace for portable system deployment with training partnerships.
- AI-enabled autonomous intima-media thickness measurement:Integration of machine learning algorithms with tablet-based workflows is reducing operator dependency and enabling technician-led screening.
- Telemedicine-linked ultrasound interpretation:Cloud-based image transmission to centralized reading centers is opening subscription revenue models for device manufacturers.
Industry Challenges
- Sonographer training pipeline constraints:Vascular ultrasound certification programs produce insufficient graduates to match deployment of portable systems into non-traditional settings.
- Legacy PACS integration complexity:Hospital IT networks require custom middleware to incorporate DICOM outputs from newer portable platforms, delaying bedside implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotid Ultrasound Imaging Market |
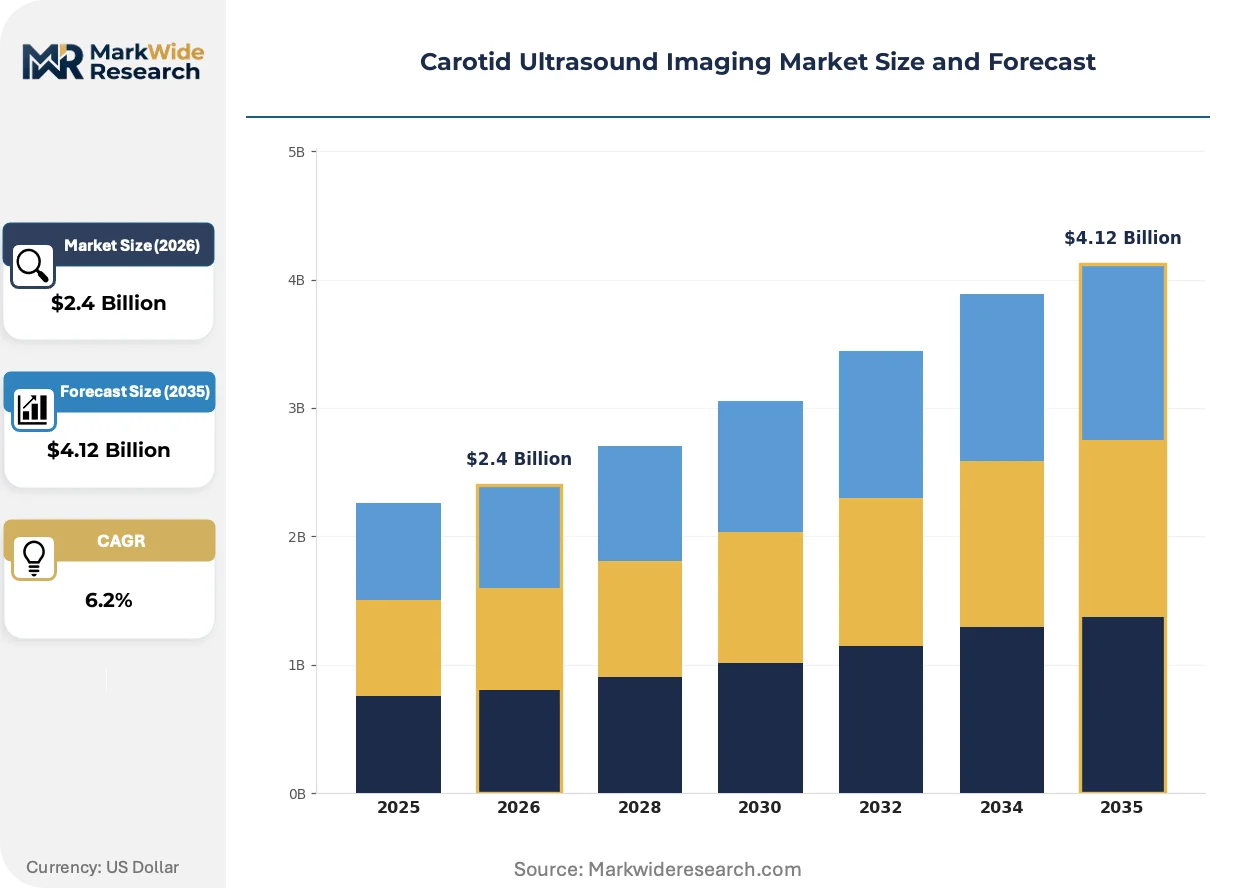
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Tabletop Ultrasound, Software Solutions, Imaging Accessories End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Facilities Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, Contrast-Enhanced Ultrasound Application: Stroke Detection, Vascular Assessment, Preoperative Evaluation, Follow-Up Monitoring |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Corporation, Samsung Medison Co., Ltd, Hitachi Medical Corporation, Mindray Medical International Limited, Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotid Ultrasound Imaging Market Strategic Shifts
Workflow automation and algorithmic diagnostic support are redrawing skill boundaries between specialists and generalists, while regulatory frameworks race to catch up with software-as-medical-device classifications.
Shear wave elastography is displacing conventional B-mode assessment for plaque vulnerability characterization. Vascular surgery departments in academic medical centers are adopting this modality for pre-intervention risk stratification. The technology is displacing subjective grayscale interpretation with quantitative stiffness measurements that standardize surgical decision thresholds.
FDA 510(k) pathways for contrast-enhanced ultrasound agents are streamlining clinical validation timelines. Manufacturers now submit abbreviated premarket notifications leveraging predicate device comparisons for microbubble formulations. Emergency medicine departments are responding by incorporating contrast protocols into acute stroke workup algorithms ahead of full guideline adoption.
Equipment-as-a-service contracting is displacing traditional capital purchase models for high-end platforms. Diagnostic center chains in the United States are negotiating multi-year agreements bundling hardware, software updates, and remote technical support. This shift concentrates vendor relationships among national account teams and reduces procurement autonomy at individual facility level.
Carotid Ultrasound Imaging Market Segmentation
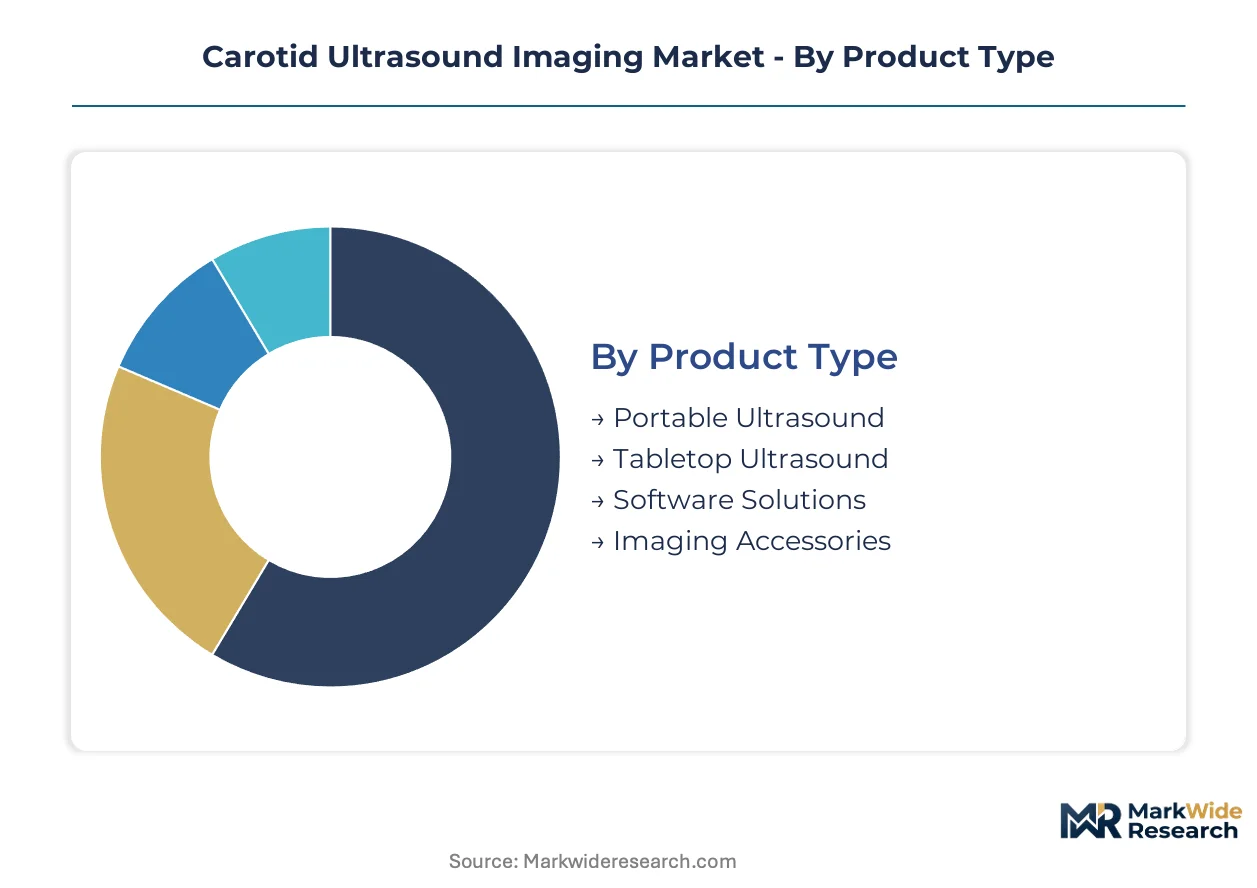
Carotid ultrasound imaging segments diverge sharply in their exposure to CT angiography substitution, with hardware categories facing the strongest pressure while software and service layers build defensive moats through workflow integration.
Product Type:
Portable systems face intensifying substitution pressure from point-of-care CT scanners, while tabletop platforms defend position through procedural reimbursement anchoring.
- Portable Ultrasound:Battery-powered units with sub-5 kg chassis configurations enable bedside deployment across emergency departments. Demand concentrates in North American hospitals expanding point-of-care stroke screening protocols, though sonographer training gaps constrain deployment velocity.
- Tabletop Ultrasound:Cart-based systems with integrated Doppler processors and multi-frequency transducer arrays support comprehensive vascular labs. Outpatient vascular clinics in Germany prioritize these platforms for 2D-to-Doppler upgrades, capitalizing on procedural fee structures that reward hemodynamic quantification.
- Software Solutions:Image analysis suites with AI-enabled plaque characterization and automated IMT measurement command recurring revenue streams tied to hardware refresh cycles.
- Imaging Accessories:Specialized transducers, gel warmers, and probe covers represent attach-rate-dependent revenue with lower margin profiles than system sales.
Portable systems retain volume leadership; contrast-enhanced ultrasound agents hold the steepest expansion curve.
End User:
Capital deployment authority is fragmenting across customer types, with purchasing decisions migrating from centralized radiology departments toward emergency medicine and outpatient operators.
- Hospitals:Tertiary care centers with existing CT capacity increasingly default to angiography for complex plaque characterization, compressing ultrasound to screening and surveillance roles. CMS reimbursement codes for carotid duplex scanning nonetheless stabilize capital budgeting for equipment refresh.
- Diagnostic Centers:High-throughput facilities prioritize throughput optimization through automated measurement protocols and technician-operator workflows. Equipment-as-a-service contracting is displacing traditional capital purchases among US diagnostic chains.
- Outpatient Clinics:Vascular specialty clinics in Germany drive concentrated demand for mid-range Doppler-capable platforms.
- Research Facilities:Academic medical centers adopt shear wave elastography for pre-intervention plaque vulnerability studies.
Diagnostic centers command the highest system utilization rates; outpatient clinics are expanding most quickly as care decentralization accelerates.
Technology:
Technology tiers stratify by margin capture potential, with advanced modalities defending premium pricing against commodity 2D alternatives.
- 2D Imaging:Grayscale B-mode visualization of carotid anatomy and plaque morphology represents the baseline capability layer. German outpatient clinics are upgrading away from standalone 2D systems toward Doppler-integrated platforms.
- Doppler Ultrasound:Spectral and color Doppler modalities quantify hemodynamic parameters including peak systolic velocity and end-diastolic velocity. This technology commands the technology margin pool due to indispensability in stenosis grading.
- 3D Imaging:Volume-rendered reconstruction of carotid bifurcation anatomy supports surgical planning in academic vascular surgery departments.
- Contrast-Enhanced Ultrasound:Microbubble agent administration enables perfusion imaging and plaque neovascularization detection. FDA 510(k) pathway streamlining is accelerating clinical validation timelines for this fastest-expanding segment.
Doppler ultrasound retains revenue concentration; contrast-enhanced protocols are gaining share fastest as procedural reimbursement expands.
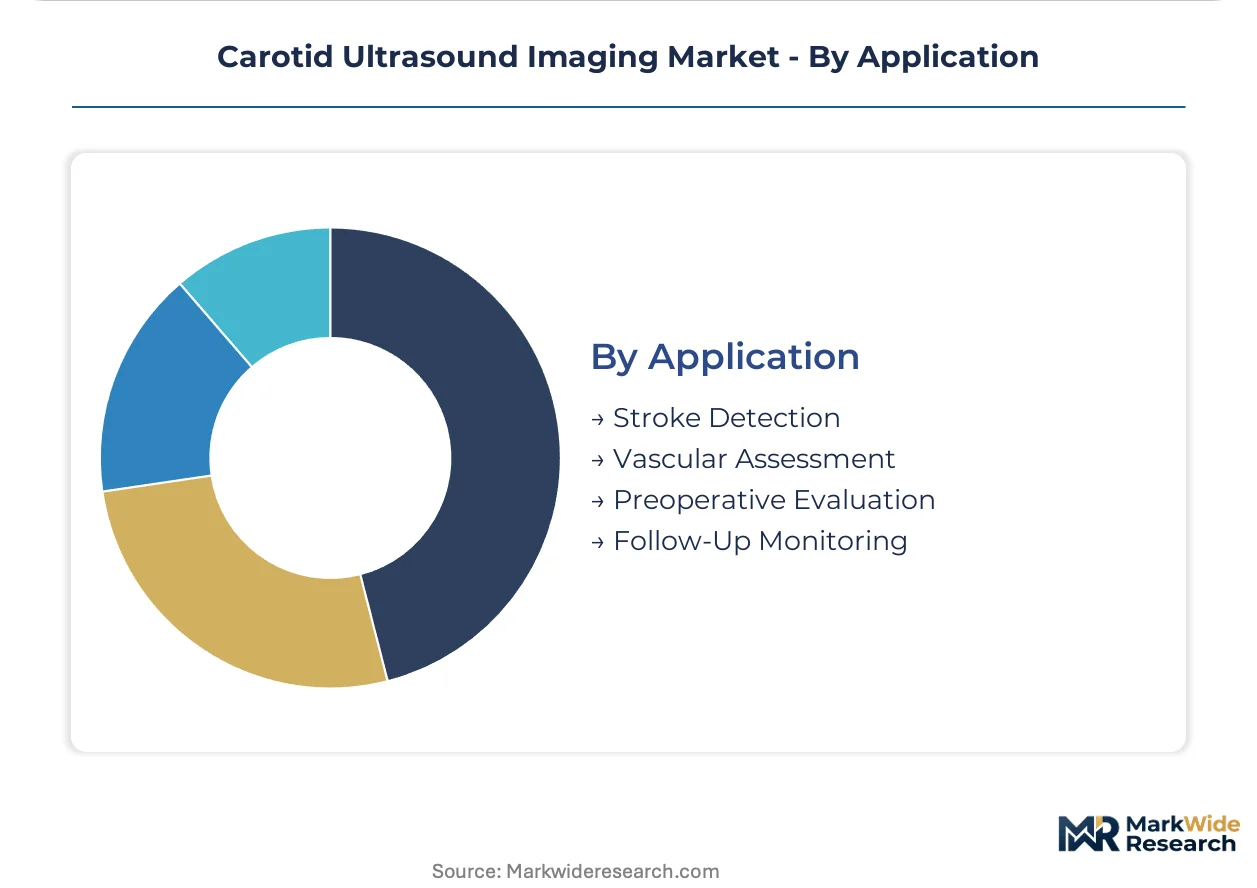
Application:
Application segments align with distinct clinical workflows and reimbursement codes, with acute indications commanding premium pricing against routine surveillance.
- Stroke Detection:Emergency department protocols for acute ischemic event workup demand rapid carotid assessment. North American hospitals are expanding portable system deployment specifically for this application.
- Vascular Assessment:Asymptomatic screening and risk stratification for cerebrovascular disease represents the volume base. Tier-2 cities in India present whitespace for technician-led screening programs.
- Preoperative Evaluation:Surgical planning for carotid endarterectomy or stenting requires detailed plaque characterization. Shear wave elastography is displacing conventional B-mode assessment in academic centers.
- Follow-Up Monitoring:Post-intervention surveillance protocols generate recurring imaging demand with standardized measurement requirements.
Vascular assessment retains procedure volume leadership; stroke detection applications are climbing the fastest as emergency protocol adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized piezoelectric material suppliers cluster in East Asia, creating input vulnerability for high-frequency transducer production above 7 MHz. German outpatient vascular clinics and North American emergency departments drive contrasting demand profiles for Doppler-capable versus portable platforms.
United States
CMS reimbursement codes for carotid duplex scanning stabilize hospital capital budgeting rhythms for equipment refresh cycles. FDA 510(k) pathways streamline clinical validation timelines for contrast-enhanced ultrasound agents. Emergency medicine departments in academic medical centers across the Northeast Corridor are expanding portable system deployment for point-of-care stroke screening protocols.
Germany
Outpatient vascular clinics concentrate demand for mid-range Doppler-capable platforms upgrading from 2D systems. EU Medical Device Regulation compliance requirements extend commercialization timelines for AI-enabled diagnostic features. The Baden-Württemberg industrial corridor hosts precision transducer manufacturing operations supplying premium platform configurations.
China
Tier-2 city neurology departments present whitespace for portable system deployment with training partnerships. NMPA regulatory frameworks govern device approval and software validation for domestic manufacturers. The Yangtze River Delta region concentrates assembly operations for battery-powered ultrasound chassis configurations.
India
Technician-led screening programs in Maharashtra and Karnataka create demand for tablet-based workflow continuity. CDSCO oversight shapes import licensing for diagnostic imaging equipment. Hyderabad's medical technology corridor is emerging as a hub for cloud-based ultrasound interpretation services.
Japan
Academic vascular surgery departments adopt shear wave elastography for pre-intervention plaque vulnerability studies. PMDA regulatory pathways influence R&D allocation for autonomous diagnostic algorithms. The Kansai region around Osaka maintains concentration in high-precision piezoelectric material processing for transducer arrays.
Carotid Ultrasound Imaging Market Competitive Environment
Concentration sits with diversified medical technology conglomerates possessing captive transducer manufacturing capabilities. Siemens Healthineers leverages its manufacturing scale to dominate premium platform configurations, while GE Healthcare anchors position through hospital IT network integration. Three archetypes define competitive positioning: diversified imaging conglomerates with full-stack capabilities, portable specialists emphasizing workflow continuity, and mid-tier Asian manufacturers competing on capital efficiency. Dominant competitive moves include equipment-as-a-service contracting displacing traditional capital purchases, and AI algorithm licensing partnerships reducing operator dependency.
Within the diversified conglomerate tier, Siemens Healthineers and GE Healthcare exemplify scale-driven positioning through integrated hardware-software ecosystems. Koninklijke Philips N.V. occupies a distinct position emphasizing portable-to-tablet workflow continuity for emergency stroke protocols. Among Asia-based manufacturers, Canon Medical Systems Corporation and Samsung Medison Co., Ltd represent capital-efficient production anchored to regional supply chains for transducer components.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Corporation |
| Samsung Medison Co., Ltd |
| Hitachi Medical Corporation |
| Mindray Medical International Limited |
| Hologic Inc. |
| Others |
Value Chain & Pricing Dynamics
Transducer manufacturing scale economies in the Yangtze River Delta and Kansai region concentrate production capacity above 7 MHz specifications, compressing unit economics for premium platform configurations while elevating price floors for mid-range Doppler-capable systems. This geographic clustering of piezoelectric material processing capabilities ties procurement costs directly to regional capacity utilization and input material access.
Pricing Analysis
FDA 510(k) clearance tiers and EU MDR conformity assessment levels dictate the pricing tier structure across hardware categories. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled autonomous measurement platforms from technician-operated Doppler systems and basic 2D imaging units. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because outpatient vascular clinics in Germany prioritize mid-range Doppler upgrades over premium configurations. Diagnostic center chains exhibit the highest price sensitivity due to equipment-as-a-service contracting concentration, while academic medical centers demonstrate the lowest sensitivity given procedural reimbursement anchoring.
Supply Chain Analysis
Inventory cycles for specialized piezoelectric ceramics extend 16-20 weeks, constraining OEM responsiveness to demand surges in portable system categories. Manufacturing draws from Japan, China, and South Korea for high-frequency transducer arrays, with additional component sourcing from Germany for precision Doppler processors. Raw material dependencies include lead zirconate titanate ceramics, lithium niobate crystals, and medical-grade ultrasound gel formulations. Single-source vulnerability sits with East Asian suppliers of sub-7 MHz transducer substrates. Distribution runs through hospital GPO contracts in the United States, direct procurement by outpatient clinic chains in Germany, and regional distributor networks across tier-2 Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CT angiography substitution in tertiary care hospitals threatens ultrasound volume retention, forcing incumbents to defend procedural anchoring in screening and surveillance workflows.
For Market Incumbents: Secure captive transducer manufacturing capacity through backward integration into piezoelectric material processing or long-term offtake agreements with Yangtze River Delta suppliers. Anchor hospital IT network integration to defend against portable specialist encroachment in emergency medicine departments. The CT angiography default in complex plaque characterization demands reinforcement of Doppler algorithm superiority for hemodynamic quantification. For New Entrants and Emerging Players: Differentiate on tablet-based workflow continuity for technician-led screening programs in Maharashtra and Karnataka, where vascular imaging infrastructure gaps create whitespace deployment opportunities. Target point-of-care stroke screening in tier-2 Indian cities through training partnership bundled offerings. The most penetrable segment remains portable system deployment in neurology departments lacking dedicated vascular labs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enabled software layer specialists with FDA-cleared autonomous measurement algorithms over hardware-commoditized chassis manufacturers. Long-term viability hinges on recurring revenue attachment rates from software subscriptions tethered to hardware refresh cycles. Acquisition target archetype: portable system specialists with established CDSCO import licensing and cloud-based interpretation service infrastructure. The signal to watch is CMS reimbursement code expansion for contrast-enhanced ultrasound microbubble protocols.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Contrast-Enhanced Agents | Abbreviated premarket pathways accelerate clinical validation timelines for microbubble formulations. |
| Hospital System Partnership for IT Integration | Deep DICOM integration with legacy PACS networks delays bedside implementation of competitor platforms. |
| Equipment-as-a-Service Contracting Model | Multi-year agreements concentrate vendor relationships among national diagnostic center chains. |
| Software Companion Development for AI-Enabled IMT | Autonomous measurement algorithms reduce operator dependency and enable technician-led screening. |
| Reimbursement Strategy for Procedural Fee Expansion | CMS code stabilization determines capital budgeting rhythms for cerebrovascular screening programs. |
Study Parameters
Cross-validation between primary interviews with vascular surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR conformity assessment records, and hospital procurement registries anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Sensitivity analysis on transducer manufacturing capacity utilization and CMS reimbursement code stability frames the projection framework. Segmentation dimensions modeled include product type, end user category, technology tier, and application indication across the projection horizon. CAGRs derive from equipment shipment trajectories, software attachment rate evolution, and procedural volume growth assumptions. Forecast inputs incorporate contrast-enhanced ultrasound adoption curves and AI algorithm regulatory clearance timelines.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR enforcement regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Medical Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
US Interventional Radiology Market