
 Ultrasound Consoles and Transducers Market | 2026-2036
Ultrasound Consoles and Transducers Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Consoles and Transducers Market Analytics
Emergency medicine and point-of-care settings is broadening as the fastest-expanding end-use vertical for ultrasound systems. GE Healthcare leverages its installed base of console platforms to sustain recurring transducer revenue. Philips Healthcare anchors its competitive stance through advanced 3D imaging modules for cardiology workflows. Siemens Healthineers differentiates via AI-integrated acquisition software that reduces operator dependency.
Ultrasound consoles and transducers comprise electronic imaging systems that emit high-frequency sound waves, typically operating between 2 and 18 MHz, to generate real-time anatomical visualizations for diagnostic and interventional procedures. The transducer assembly incorporates piezoelectric crystals that convert electrical pulses into acoustic energy and vice versa, with probe design determining beam shape, penetration depth, and resolution characteristics. Portable and handheld systems represent the fastest-growing product type segment as decentralized care models shift capital allocation toward bedside and field-deployable equipment. Cart-based trolley systems retain the dominant share of hospital radiology department procurement budgets where throughput and image fidelity requirements remain stringent. Doppler ultrasound technology commands premium positioning within vascular and cardiac application areas where hemodynamic assessment drives clinical decision-making.
The FDA's 510(k) premarket notification pathway governs US commercialization timelines for new ultrasound devices, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for transducer materials and biocompatibility. China's NMPA implements GB standards for electromagnetic compatibility that foreign manufacturers must satisfy for market access. Stakeholders must monitor evolving AI diagnostic algorithm classification rules across FDA, EMA, and NMPA jurisdictions to anticipate software-enabled feature roadmaps.
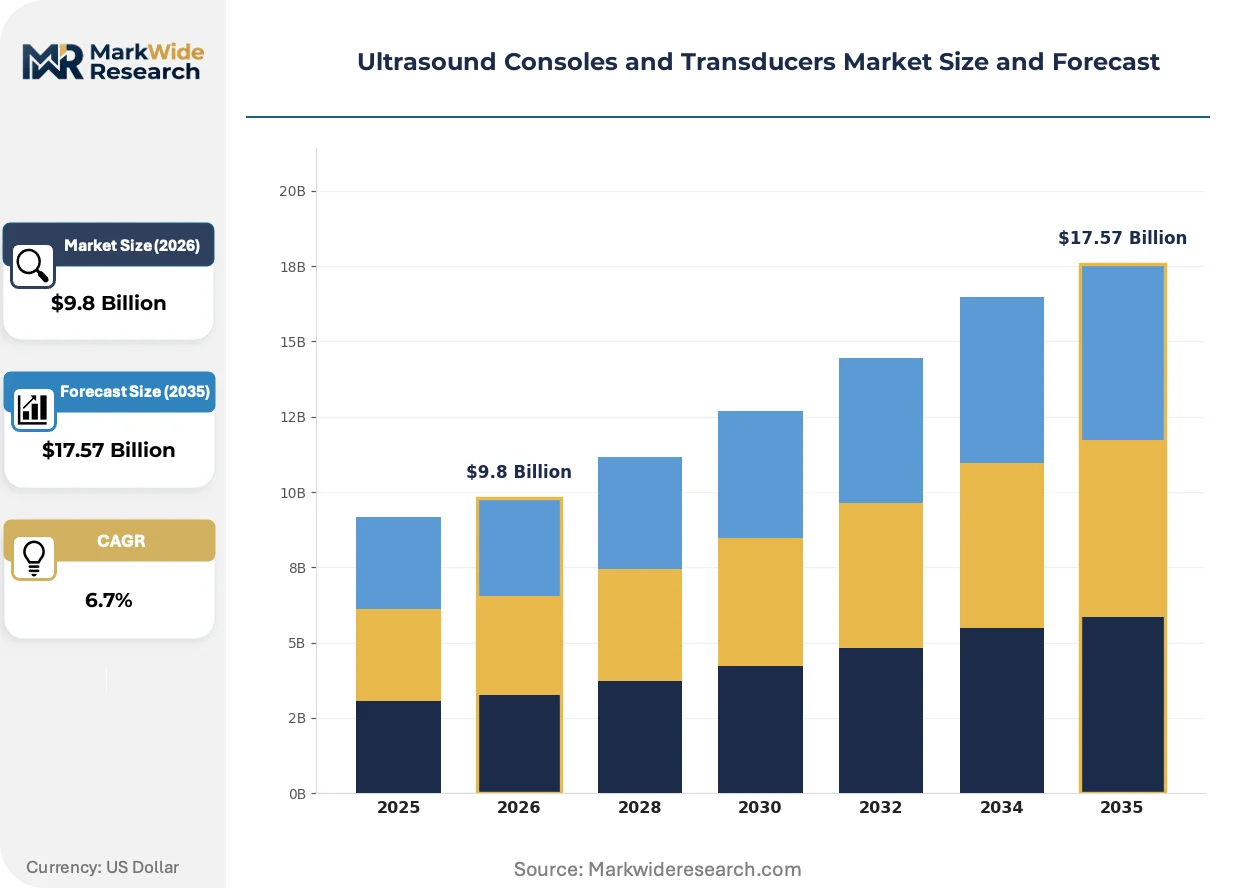
Market Dynamics
Point-of-care ultrasound deployment is restructuring capital allocation across healthcare systems, compressing procurement cycles from radiology departments into emergency medicine and ambulatory settings where bedside imaging replaces centralized diagnostics.
Growth Catalysts
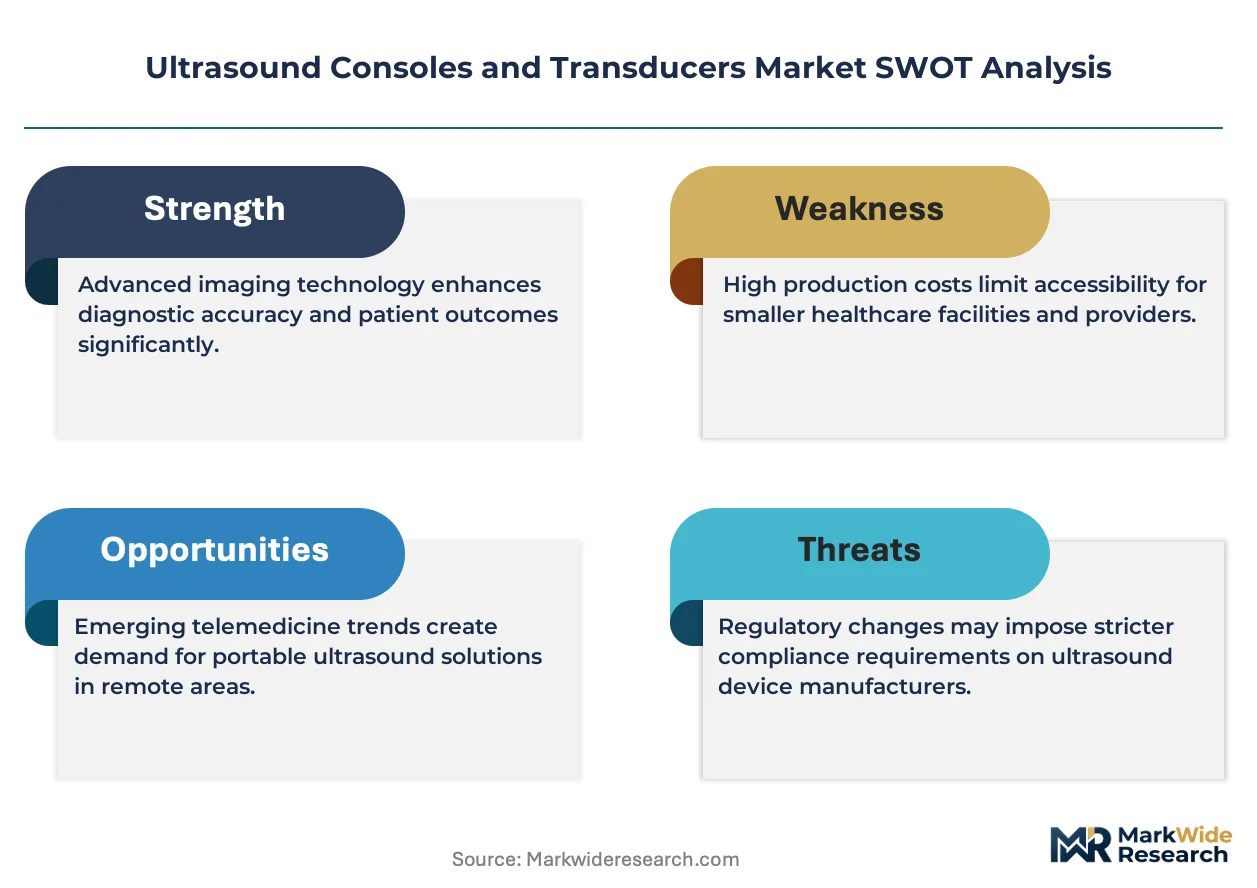
- FDA 510(k) Pathway:The streamlined premarket notification framework accelerates commercialization timelines for AI-enabled diagnostic features, reducing regulatory friction for algorithm-integrated systems.
- Emergency Medicine Vertical:Hospital emergency departments are expanding dedicated ultrasound programs for trauma assessment and procedural guidance, creating dedicated capital budgets distinct from radiology.
- Handheld Form Factor:Miniaturized probe technology paired with tablet-based acquisition software enables field deployment in rural clinics and disaster response scenarios.
Market Restraints
- Piezoelectric Material Concentration:Specialty crystal manufacturing concentrates among Japanese and German suppliers, exposing transducer producers to input volatility and single-source risk.
- EU MDR Compliance Burden:The Medical Device Regulation imposes expanded clinical evidence requirements for transducer biocompatibility, extending certification timelines and elevating documentation costs.
- CT and MRI Substitution:Advanced cross-sectional imaging modalities retain diagnostic preference for complex abdominal and neurological indications, limiting ultrasound penetration in high-acuity cases.
Strategic Opportunities
- China NMPA Market Access:GB standards for electromagnetic compatibility create compliance barriers that, once satisfied, unlock procurement from tier-two and tier-three hospital networks.
- AI-Assisted Image Interpretation:Machine learning algorithms for automated anatomical recognition and measurement are converging with cloud-based delivery models, enabling subscription revenue streams.
- Home-Based Monitoring:Cardiology and obstetrics applications are testing direct-to-consumer channels for remote fetal and cardiac monitoring, bypassing traditional hospital procurement.
Industry Challenges
- Sonographer Training Pipeline:Specialized expertise in point-of-care image acquisition remains scarce, constraining deployment velocity even where hardware is available.
- Legacy PACS Integration:New ultrasound systems must interface with entrenched picture archiving infrastructure, complicating interoperability and extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Consoles and Transducers Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Trolley Mounted, Cart Based, Handheld End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutions Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, Elastography Application: Obstetrics, Cardiology, Urology, Vascular |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Canon Medical Systems, Mindray Medical International, FUJIFILM Holdings, Hitachi Ltd., Esaote SpA, Samsung Medison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Consoles and Transducers Market Evolving Landscape
Software-defined acquisition and artificial intelligence are displacing hardware-centric differentiation, compressing development cycles and enabling feature delivery through over-the-air updates rather than platform replacement.
Shear wave elastography is converging with conventional B-mode imaging to deliver quantitative tissue stiffness measurements during routine scans. Hepatology and breast imaging departments are adopting combined systems to reduce biopsy referrals. This convergence is compressing the diagnostic pathway by enabling characterization and surveillance in a single encounter.
The EU AI Act classification framework is establishing conformity assessment requirements for diagnostic algorithms that influence clinical decisions. Manufacturers must now document algorithm validation across diverse patient populations. Cardiology applications face the steepest compliance burden given the directive's risk-tiering methodology.
Hospital procurement committees are unbundling service contracts from hardware acquisition, negotiating separate agreements for preventive maintenance and probe replacement. Integrated delivery networks in the United States are driving this disintermediation, using scale to command aftermarket pricing concessions. Emergency medicine departments show the strongest preference for usage-based service models.
Ultrasound Consoles and Transducers Market Segmentation
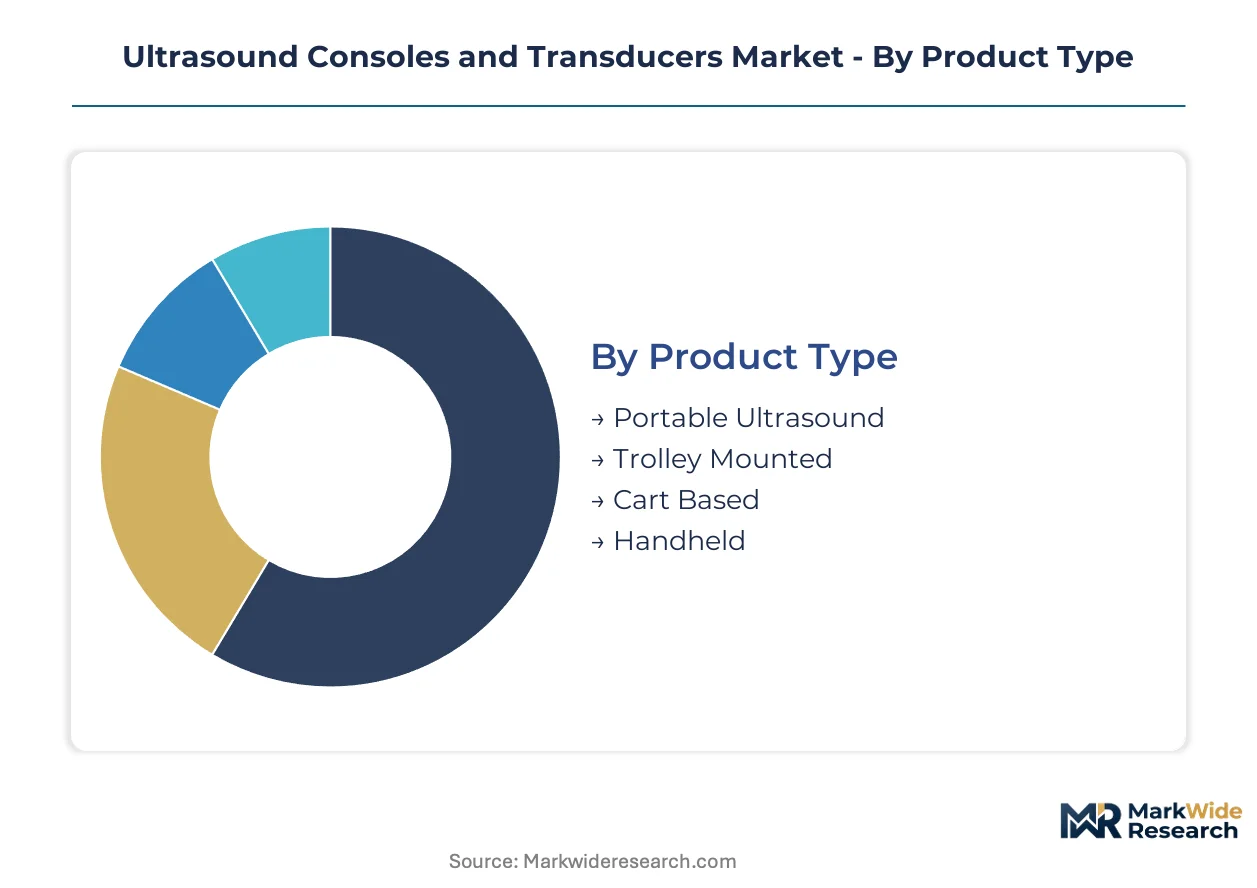
Ultrasound equipment purchasing decisions split sharply between centralized radiology departments demanding premium image fidelity and decentralized point-of-care settings prioritizing mobility and rapid deployment. The report maps four intersecting segmentation planes that determine pricing architecture, regulatory pathways, and vendor competitive positioning across clinical workflows.
Product Type:
Capital allocation intensity separates buyers in this category, with hospital procurement committees weighing acquisition cost against throughput requirements and field deployment teams emphasizing battery life and durability.
- Trolley Mounted:These systems integrate high-channel-count beamformers and large-format displays on motorized bases, delivering the spatial resolution and frame rates required for cardiac stress echo and interventional guidance. Radiology departments in the United States and Germany concentrate demand here, though extended replacement cycles and PACS integration complexity constrain refresh velocity.
- Handheld:Single-element or phased-array probes connect via USB-C or wireless protocols to smartphones and tablets, stripping hardware to essential acoustic components. Emergency medicine departments and rural clinics in China are expanding procurement fastest, driven by disaster response mandates and tier-three hospital network saturation targets.
- Portable Ultrasound:Laptop-class systems with integrated displays and cart-optional configurations occupy the mid-market, balancing image quality against transportability for bedside and ambulatory use.
- Cart Based:Fixed-installation platforms with dedicated power infrastructure and specialized transducer docks serve hybrid operating rooms and catheterization labs where procedural integration outweighs mobility needs.
Trolley mounted systems lead volumes today; handheld configurations are gaining share fastest.
End User:
Reimbursement structure and capital budget autonomy create distinct buying behaviors across institutional settings.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts spanning multiple campuses, leveraging installed base scale for service bundling concessions. Inpatient throughput requirements and 24/7 coverage mandates drive preference for redundant system availability and rapid manufacturer response times.
- Diagnostic Centers:Freestanding imaging facilities operate on per-scan economics, prioritizing patient turnaround speed and multi-modality referral capture. These buyers concentrate in urban China and Germany where outpatient imaging volume has decoupled from hospital ownership.
- Ambulatory Surgical Centers:Procedure-specific ultrasound for regional anesthesia and vascular access guidance is expanding as same-day surgery volume shifts from hospital campuses.
- Research Institutions:Preclinical and translational imaging groups acquire specialized high-frequency systems for small-animal and phantom studies, representing low volume but premium pricing tolerance.
Hospitals dominate absolute procurement value; diagnostic centers are expanding most quickly.
Technology:
Software-enabled feature differentiation is displacing hardware specifications as the primary vendor comparison axis.
- Doppler Ultrasound:Spectral, color, and power Doppler modes measure blood velocity and directionality, essential for stenosis grading and shunt assessment. Cardiology and vascular surgery departments in the United States command premium positioning here, with AI-assisted flow quantification emerging as the next competitive battleground.
- Elastography:Shear wave and strain imaging techniques quantify tissue stiffness, enabling non-invasive liver fibrosis staging and breast lesion characterization. Hepatology units in Germany and China are adopting combined B-mode/elastography systems to reduce biopsy referral volume.
- 2D Imaging:Conventional grayscale B-mode remains the foundational modality across all clinical applications, with resolution and penetration depth determined by transducer frequency selection.
- 3D Imaging:Volume acquisition and multiplanar reconstruction enable fetal face rendering and cardiac chamber quantification, though extended acquisition times limit adoption in time-critical settings.
2D imaging anchors installed base volumes; elastography is climbing the fastest.
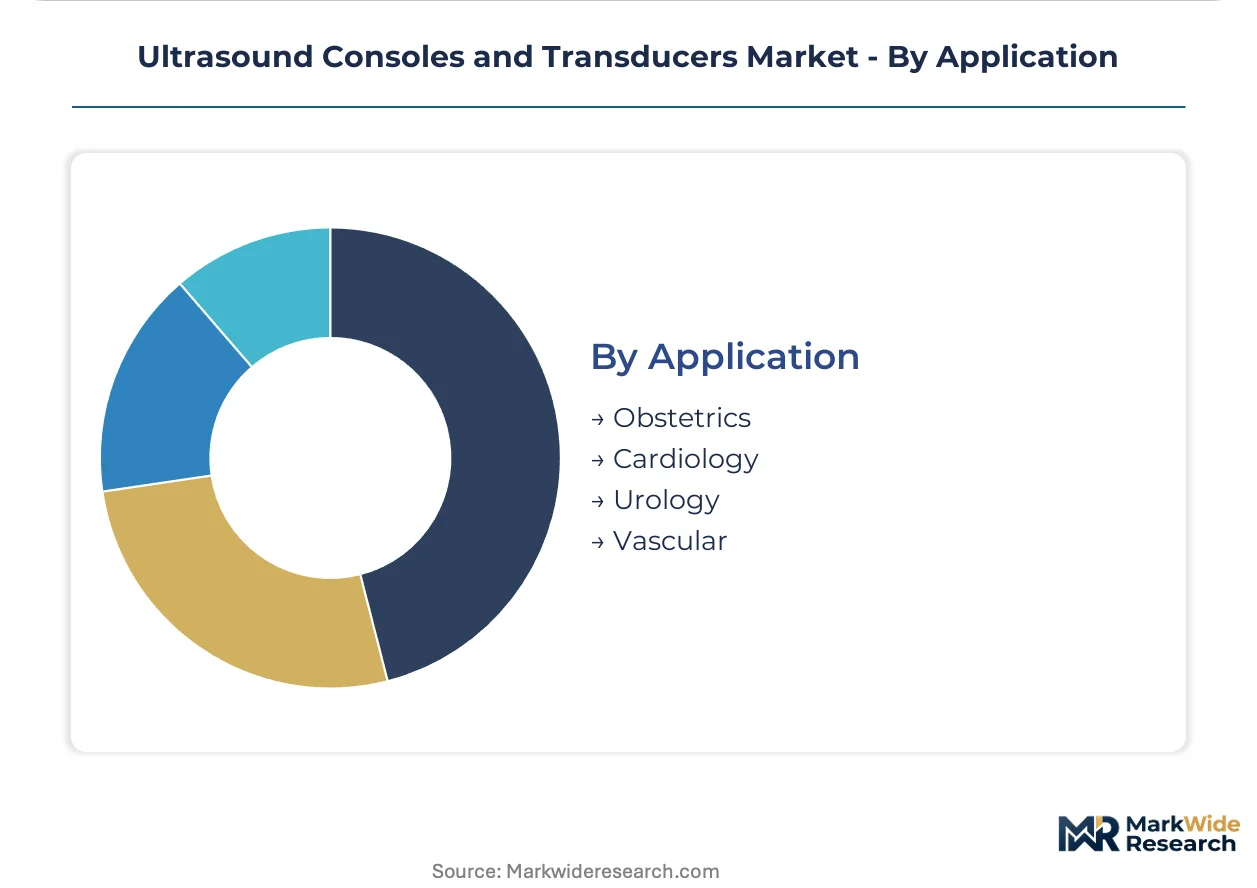
Application:
Clinical workflow integration requirements and reimbursement coding specificity shape segment profitability profiles.
- Cardiology:Transthoracic and transesophageal echocardiography demand specialized phased-array transducers and ECG-gated acquisition protocols. The EU AI Act's risk-tiering methodology imposes the steepest algorithm validation burden on cardiology applications given clinical decision influence.
- Obstetrics:Fetal biometry and anatomical survey protocols drive high examination volume with standardized reporting requirements, making this the most price-sensitive application segment.
- Vascular:Carotid, venous, and peripheral arterial imaging supports surgical planning and surveillance programs, with point-of-care deployment expanding in emergency department deep vein thrombosis protocols.
- Urology:Transrectal prostate imaging and renal transplant surveillance utilize specialized endocavity probes with higher frequency ranges for superficial organ assessment.
Obstetrics generates the highest examination volume; cardiology commands premium system pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers relocate assembly to jurisdictions with streamlined medical device approval pathways, compressing time-to-market for new transducer platforms while maintaining quality certifications.
United States
Emergency medicine departments in Texas and Florida are expanding point-of-care ultrasound programs with dedicated capital budgets. The FDA's 510(k) premarket notification framework accelerates commercialization timelines for AI-enabled diagnostic features. Boston's medical technology cluster anchors development of algorithm-integrated acquisition software.
Germany
Diagnostic centers in Bavaria and North Rhine-Westphalia drive demand for combined B-mode and elastography systems to reduce biopsy referrals. The EU Medical Device Regulation imposes expanded clinical evidence requirements for transducer biocompatibility. Berlin's healthcare procurement networks are unbundling service contracts from hardware acquisition.
China
Tier-two and tier-three hospital networks in Sichuan and Shandong provinces are saturating with portable and handheld systems. The NMPA implements GB standards for electromagnetic compatibility that foreign manufacturers must satisfy. Shenzhen's electronics manufacturing base concentrates piezoelectric crystal assembly operations.
Japan
Specialty crystal manufacturing concentrates in Osaka and Nagoya industrial corridors, exposing transducer producers to input volatility. METI oversees domestic medical device quality frameworks aligned with international standards. Tokyo's academic medical centers drive adoption of high-frequency systems for preclinical imaging.
India
Ambulatory surgical centers in Maharashtra and Karnataka are expanding ultrasound-guided regional anesthesia programs. The CDSCO regulates medical device imports under the Drugs and Cosmetics Act. Hyderabad's diagnostic imaging distribution networks are penetrating tier-three cities with refurbished console platforms.
Ultrasound Consoles and Transducers Market Competitive Landscape
Portfolio diversification dominates the current landscape as established imaging conglomerates extend software-defined feature sets to defend installed base positions. The vendor base stratifies across three tiers: diversified healthcare conglomerates with full-modality portfolios, mid-scale specialists concentrating on portable form factors, and regional assemblers serving price-sensitive procurement channels. Two strategic archetypes prevail: platform vendors leveraging recurring transducer revenue from captive console bases, and disruptors attacking point-of-care segments with miniaturized probe-tablet bundles. M&A activity and technology licensing partnerships represent the dominant competitive vectors.
Within the diversified conglomerate tier, GE Healthcare and Philips Healthcare exemplify platform-centric positioning, while Siemens Healthineers anchors the AI-integrated software differentiation vector. These three entities collectively represent the archetype of vendors sustaining market presence through installed base scale and recurring aftermarket revenue streams rather than hardware substitution cycles alone.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Canon Medical Systems |
| Mindray Medical International |
| FUJIFILM Holdings |
| Hitachi Ltd. |
| Esaote SpA |
| Samsung Medison |
| Others |
Value Network & Pricing Analysis
Performance-tier bifurcation between AI-integrated console platforms and commodity handheld probes manifests in divergent margin structures and sourcing strategies across the ultrasound equipment value chain. Premium systems command pricing power through proprietary transducer lock-in and software subscription bundles, while handheld manufacturers compete on unit economics shaped by Shenzhen-based electronics assembly and standardized piezoelectric crystal sourcing.
Pricing Analysis
Distributor margins compress most acutely in the handheld segment where direct-to-hospital tablet bundles bypass traditional medical device distribution. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled cart-based systems from laptop-class portables and smartphone-connected probes. Pricing pressure stems from Chinese domestic manufacturers saturating tier-two hospital procurement with sub-premium alternatives. Emergency medicine departments exhibit highest price sensitivity due to capital budget fragmentation, while cardiology departments retain lowest sensitivity given reimbursement capture from high-value diagnostic codes.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty crystal manufacturers supplying lead zirconate titanate and single-cine piezoelectric materials. Transducer assembly draws from Japan, Germany, and China for acoustic components, with Shenzhen and Osaka anchoring final probe manufacturing. Supply chain risk centers on tariff exposure for US-bound shipments from Chinese electronics subcontractors. Distribution runs through regional medical device distributors in developed markets and direct government procurement channels in China's hospital tier system.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasound market compounds steadily as point-of-care imaging displaces centralized radiology workflows across emergency and ambulatory settings. This structural shift in clinical site-of-care generates durable replacement demand for portable form factors.
For Market Incumbents: Anticipate margin compression from AI-native entrants by accelerating software-defined feature roadmaps and deepening backward integration into piezoelectric crystal supply. Prioritize certification investment for EU AI Act conformity assessment in cardiology algorithms. Lock hospital IDN procurement through bundled transducer replacement contracts that raise switching costs for challenger hardware.
For New Entrants and Emerging Players: Enter via handheld-tablet bundles targeting China's tier-three hospital saturation mandates and rural clinic disaster response programs. White-space concentrates in AI-assisted image interpretation delivered through cloud subscription models bypassing capital-intensive console manufacturing. Go-to-market leverage rests on direct digital sales channels disintermediating entrenched distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where AI software capabilities outpace legacy hardware differentiation and standalone algorithm developers face reimbursement strategy gaps. Long-term viability favors platform vendors with installed base scale and recurring transducer revenue streams. Acquisition target archetype: mid-scale portable specialists with NMPA clearance and thin but expanding China distribution. Signal to watch: hospital procurement committee unbundling of service contracts from hardware acquisition accelerating aftermarket pricing transparency.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates AI-enabled diagnostic feature commercialization through streamlined premarket notification pathways. |
| CE Marking Pathway | Unlocks EU market access for elastography-integrated systems amid MDR biocompatibility evidence requirements. |
| Hospital System Partnership | Secures enterprise-wide installed base expansion through integrated delivery network procurement leverage. |
| Software Companion Development | Enables subscription revenue streams via cloud-based image interpretation algorithms decoupled from hardware refresh cycles. |
| Reimbursement Strategy | Captures cardiology premium pricing through CPT code alignment for AI-assisted echocardiography quantification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ultrasound equipment procurement managers, biomedical engineering directors, GPO contracts administrators, and point-of-care clinicians with secondary validation against FDA 510(k) filings, NMPA registration databases, hospital procurement records, and EU MDR technical documentation. Bottom-up modeling of transducer replacement cycles and console refresh rates triangulated against top-down healthcare capital expenditure surveys.
Segment-weighting approaches distributed value and volume across trolley-mounted, handheld, portable, and cart-based product configurations intersecting with cardiology, obstetrics, vascular, and urology applications. CAGRs were derived from regression analysis of historical shipment data and elasticity-adjusted demand projections across the analysis window. Industry-specific inputs included sonographer training pipeline constraints and PACS interoperability implementation timelines.
Inputs from hospital procurement databases and regulatory filing repositories were available through the study window; gaps in real-time tier-three China hospital inventory data introduce uncertainty bands around handheld penetration assumptions. Forecasts reflect documented assumptions regarding AI algorithm classification timelines and reimbursement code expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Argentina Digital X-Ray Market