
 South America Portable X Ray Devices Market | 2026-2036
South America Portable X Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South America Portable X Ray Devices Market Analytics
Radiology technician shortages across South America are rotating investment toward portable systems that require less specialized operation than fixed-room equipment. GE Healthcare leverages its established service infrastructure across Brazilian teaching hospitals to sustain recurring revenue streams. Siemens Healthineers anchors its regional position through direct radiography platforms optimized for high-throughput trauma settings. Philips competes on wireless connectivity architectures that reduce exam turnaround times in understaffed emergency departments.
Portable X ray devices are self-contained imaging systems incorporating X ray tubes, digital detectors or film cassettes, and battery power assemblies within wheeled or handheld form factors, typically operating at kilovoltage ranges from 40 to 120 kVp for musculoskeletal and chest applications. Their primary purpose is delivering diagnostic radiography at point-of-care locations lacking fixed radiology infrastructure. Handheld devices represent the fastest-expanding product category as miniaturized tube technology and solid-state detectors enable ward-based imaging without patient transport. Emergency services command disproportionate margin attention due to premium pricing for ruggedized systems with rapid boot cycles and extended battery autonomy. Computed radiography retains installed-base dominance across public hospital networks where capital constraints delay full digital transitions.
ANVISA governs medical device registration and post-market surveillance in Brazil, while Argentina's national pharmaceutical regulator oversees import licensing and clinical evidence requirements for imaging equipment. These frameworks shape demand by mandating electromagnetic compatibility testing and radiation safety certifications that filter lower-cost Asian manufacturers from formal procurement channels. Stakeholders must monitor how Mercosur harmonization efforts alter mutual recognition of device approvals across member states.
Market Dynamics
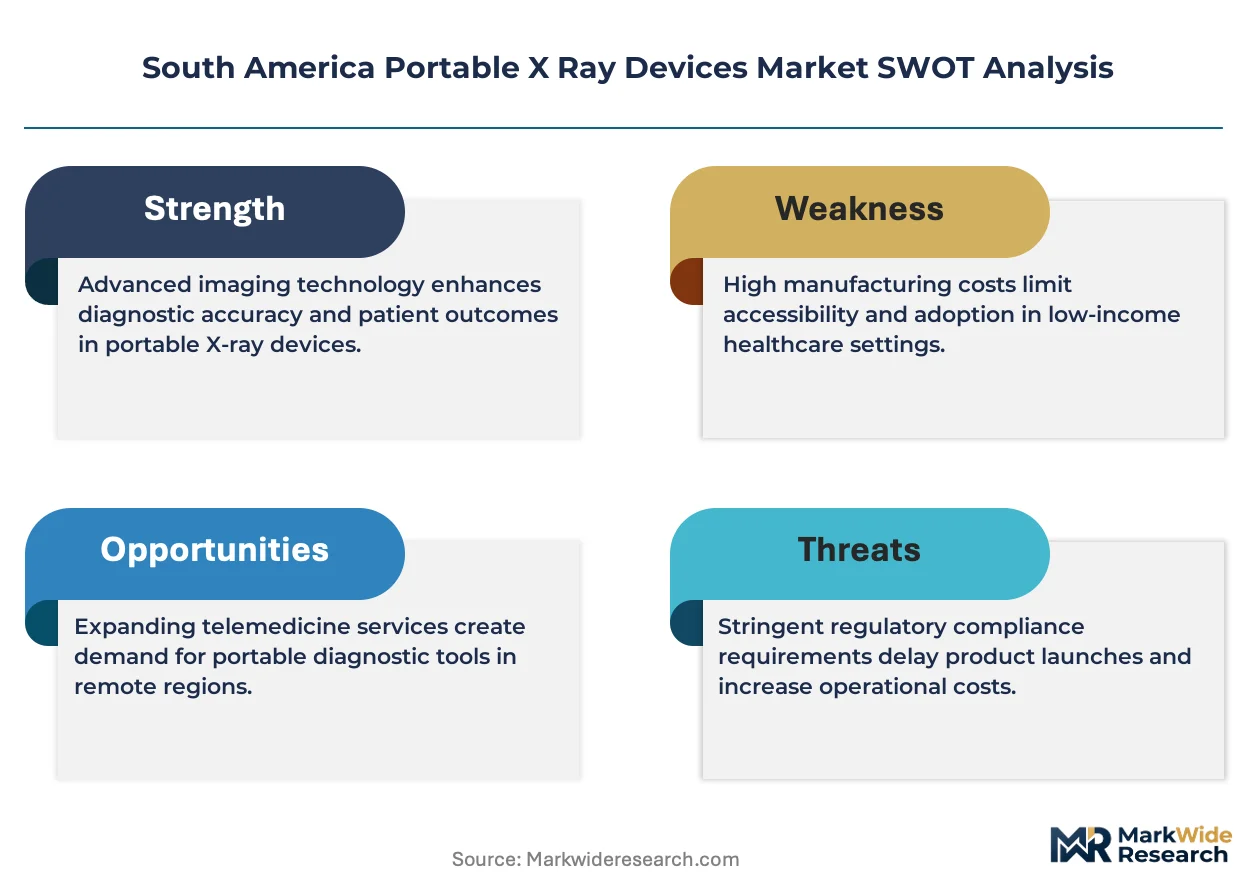
ANVISA's compressed registration timelines for digital imaging equipment are accelerating replacement cycles across Brazilian hospital networks, while radiology technician shortages rotate capital toward systems requiring less specialized operation.
Growth Catalysts
- Emergency Medical Services Procurement:Mobile radiography unit orders from ambulance services and trauma centers in São Paulo and Rio de Janeiro are expanding fleet deployments. These systems address transport risks for critically ill patients.
- Mercosur Harmonization:Mutual recognition pathways for device approvals across member states are reducing redundant certification burdens for manufacturers. This streamlines cross-border supply chains.
- Handheld Miniaturization:Solid-state detector advances and compact X-ray tube designs enable ward-based imaging without fixed infrastructure. Rural clinics adopt these for bedside diagnostics.
Market Restraints
- Electromagnetic Compatibility Testing:ANVISA mandates EMC and radiation safety certifications that filter lower-cost Asian manufacturers from formal procurement channels. Compliance costs disadvantage budget-tier suppliers.
- Public Hospital Capital Constraints:Computed radiography retains dominance across Brazilian public networks where full digital transitions face budget freezes. Legacy film infrastructure delays detector upgrades.
- Import Licensing Friction:Argentina's national pharmaceutical regulator imposes extended clinical evidence requirements for imaging equipment. Approval timelines stretch 18-24 months for non-established vendors.
Strategic Opportunities
- Colombian Underserved Corridors:Mountainous regions and Amazon-adjacent municipalities lack fixed radiology infrastructure. Portable units address geographic access gaps for indigenous health programs.
- Wireless Connectivity Integration:DICOM-over-WiFi architectures reduce exam turnaround times in understaffed emergency departments. Cloud-native image routing enables teleradiology partnerships.
- Rural Primary Care Expansion:Argentina's provincial health initiatives are funding mobile diagnostic units for remote municipalities. Federal matching programs lower acquisition barriers for small clinics.
Industry Challenges
- Radiology Technician Scarcity:Training program bottlenecks across Brazil, Argentina, and Colombia limit operational scaling. Facilities compete for certified staff to run portable systems.
- Battery Autonomy Engineering:Ruggedized emergency systems require extended power cycles for field deployment. Thermal management in tropical climates degrades lithium-ion performance.
- Legacy System Integration:PACS connectivity with aging hospital information systems demands custom middleware development. Interoperability gaps delay go-live schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Portable X Ray Devices Market |
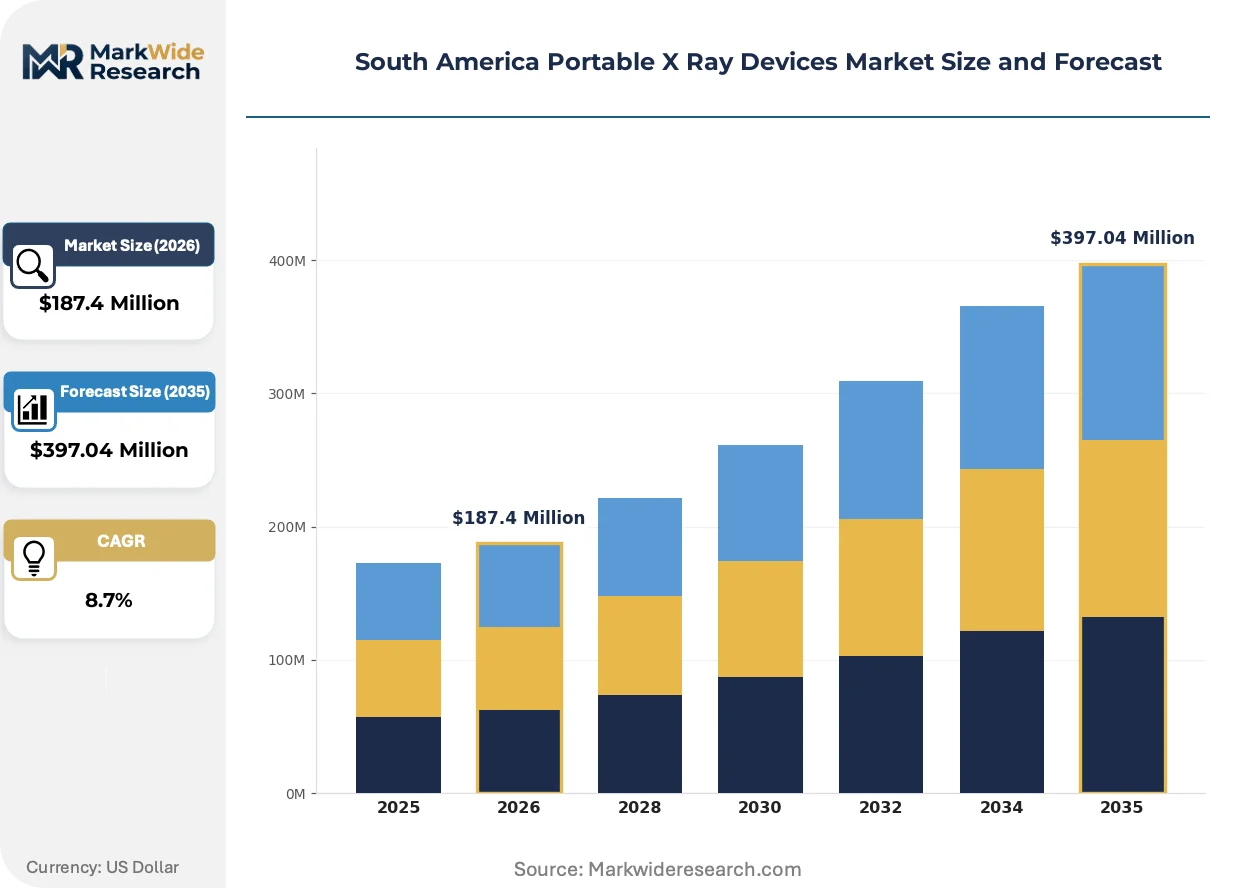
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Mobile Systems, Digital Radiography, Analog Radiography End User: Hospitals, Clinics, Diagnostic Centers, Emergency Services Technology: Computed Radiography, Direct Radiography, Wireless, Portable Film Application: Trauma Imaging, Dental Imaging, Orthopedic Imaging, Veterinary Imaging |
| Companies Covered | GE Healthcare, Koninklijke Philips NV, Siemens Healthineers, Canon Medical Systems, FUJIFILM Holdings Corporation, Shimadzu Corporation, Carestream Health, Danaher Corporation, Hitachi Medical Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Portable X Ray Devices Market Evolving Landscape
Digital radiography platforms are compressing exam workflows while regulatory harmonization and procurement centralization reshape competitive access across South American healthcare systems.
Direct radiography detectors with cesium iodide scintillators are displacing computed radiography plates in high-throughput trauma settings. São Paulo's municipal hospital network is phasing out cassette-based systems for seamless image acquisition. This transition eliminates processing delays and reduces technician handling steps.
ANVISA's updated medical device registration pathways are compressing approval timelines for digital imaging equipment. Manufacturers now navigate consolidated technical documentation requirements rather than sequential review stages. Emergency services procurement channels benefit most from accelerated market entry.
Hospital buying consortia across southeastern Brazil are consolidating radiography purchases through framework agreements. Single-source contracting replaces fragmented departmental procurement. Rio de Janeiro's state health secretariat exemplifies this concentration, negotiating fleet pricing for multiple facilities simultaneously.
South America Portable X Ray Devices Market Segmentation
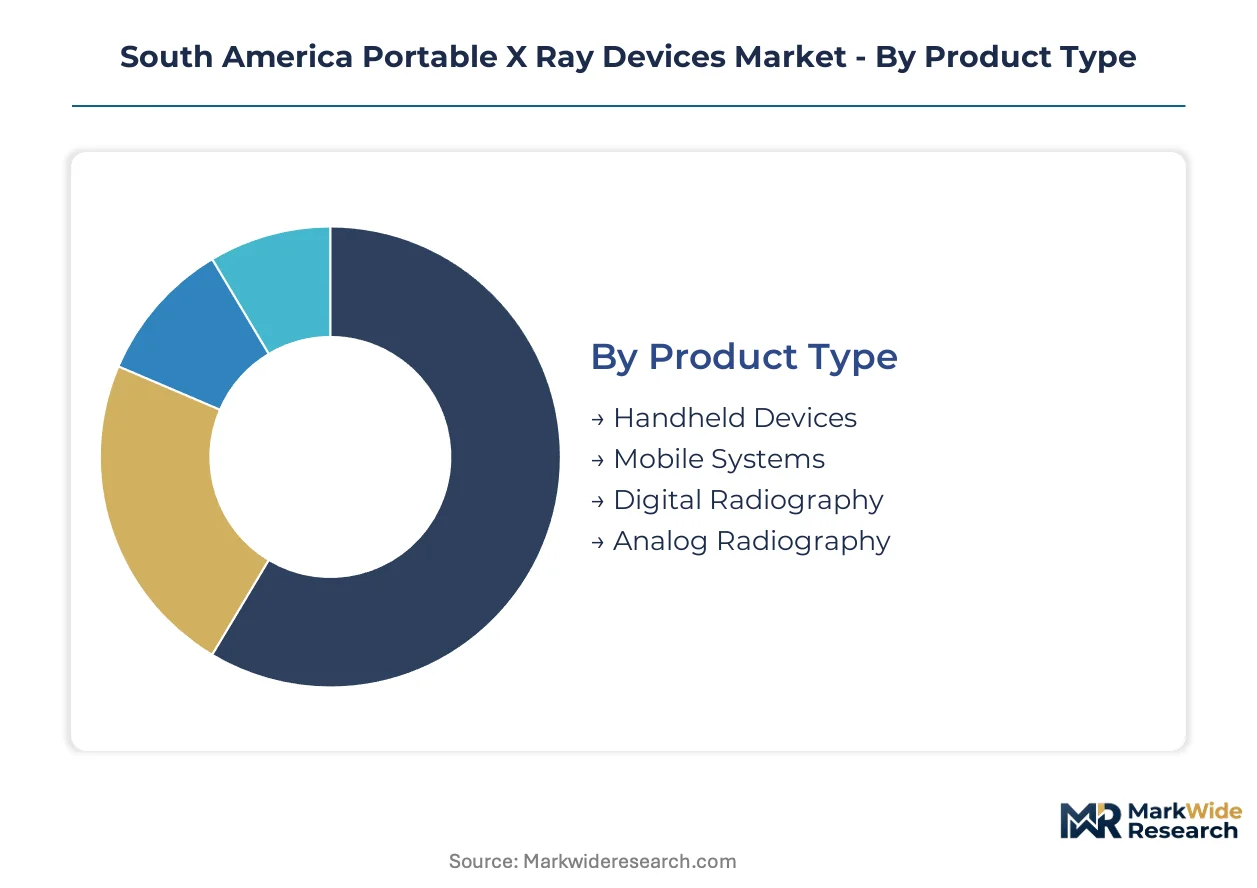
Portable X-ray device segmentation in South America reflects divergent regulatory pathways, capital constraints, and clinical workflows across Brazilian, Argentine, and Colombian healthcare networks. Each dimension—product form, care setting, imaging technology, and clinical application—carries distinct compliance burdens and procurement dynamics that shape vendor access and pricing power.
Product Type:
ANVISA's electromagnetic compatibility and radiation safety certifications create tiered barriers that filter lower-cost handheld imports while permitting established mobile system vendors through accelerated registration pathways.
- Handheld Devices:Miniaturized X-ray tubes paired with solid-state detectors enable single-operator ward-based imaging without patient transport. São Paulo's municipal hospital network and Rio de Janeiro's emergency services are replacing aging analog fleets with these units to address radiology technician shortages and reduce ICU patient movement risks.
- Mobile Systems:Wheeled configurations integrating battery assemblies, tube heads, and digital detectors serve high-throughput trauma bays and ambulance services. Colombian mountain municipalities and Amazon-adjacent health posts deploy these for geographic access where fixed radiology infrastructure is absent.
- Digital Radiography:Direct detector platforms with cesium iodide scintillators deliver seamless image acquisition versus cassette-based workflows. Brazilian teaching hospitals favor these for throughput advantages in understaffed emergency departments.
- Analog Radiography:Film-cassette systems retain installed-base dominance across Argentine and Brazilian public networks where capital freezes delay full digital transitions. Legacy infrastructure persists where procurement budgets prioritize volume over technology refresh.
Established volume favors mobile systems; emerging adoption favors handheld devices.
End User:
Procurement centralization across southeastern Brazil concentrates purchasing power while fragmented provincial health initiatives in Argentina and Colombia sustain diverse supplier access tiers.
- Hospitals:São Paulo's state hospital consortium and Rio de Janeiro's municipal networks negotiate framework agreements for fleet standardization. These facilities demand PACS interoperability and extended service contracts that favor vendors with established Brazilian technical infrastructure.
- Emergency Services:Ambulance-based trauma units in Brazil's southeastern corridor and Colombia's Medellín-Bogotá highway network require ruggedized systems with rapid boot cycles and tropical-climate battery management. Premium pricing applies for field-proven autonomy specifications.
- Clinics:Small-format facilities across Argentina's provincial health programs acquire mobile units through federal matching initiatives. Capital constraints here sustain computed radiography plate systems alongside gradual digital migration.
- Diagnostic Centers:Independent imaging chains in Brazilian urban centers prioritize throughput-optimized direct radiography for high-volume musculoskeletal and chest screening. Wireless DICOM architectures reduce exam turnaround times to compete with hospital-affiliated networks.
Procurement concentration favors hospitals; volume expansion favors emergency services.
Technology:
Detector chemistry and connectivity architecture determine workflow compression potential and regulatory classification complexity across ANVISA's consolidated technical documentation framework.
- Direct Radiography:Flat-panel detectors with immediate image readout eliminate processing delays and technician handling steps. São Paulo's trauma centers are phasing out cassette-based systems for these platforms to address staff scarcity.
- Wireless:DICOM-over-WiFi and cloud-native routing architectures enable teleradiology partnerships for rural Colombian clinics and Argentine provincial networks. These systems reduce infrastructure dependency but require cybersecurity validation under national data protection frameworks.
- Computed Radiography:Photostimulable phosphor plate systems retain dominance where capital constraints delay detector replacement. Brazilian public hospital networks sustain these through legacy service contracts and lower per-exam operating assumptions.
- Portable Film:Analog cassette systems persist in remote Amazon-adjacent municipalities and Andean corridor clinics where power reliability and technical support access limit digital adoption. These configurations avoid battery autonomy engineering challenges.
Technology transition favors direct radiography; installed-base persistence favors computed radiography.
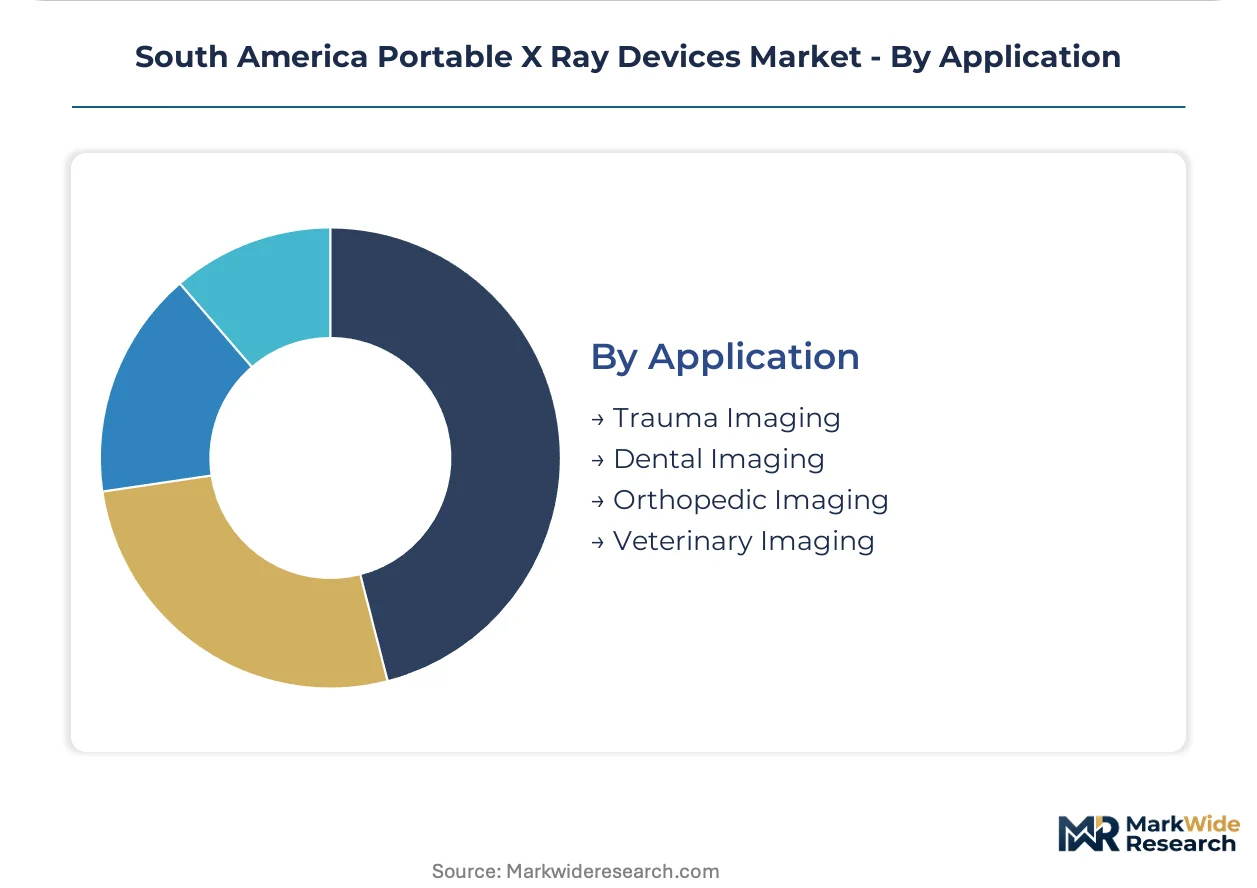
Application:
Clinical use case determines kilovoltage range requirements, positioning accessory needs, and reimbursement pathway stability across Brazilian, Argentine, and Colombian health financing systems.
- Trauma Imaging:High-throughput chest and extremity radiography at 60-120 kVp dominates emergency department and ambulance service procurement. Brazilian trauma centers prioritize rapid boot cycles and wireless image transmission to reduce critically ill patient transport.
- Orthopedic Imaging:Musculoskeletal applications at 50-80 kVp require specialized positioning aids and weight-bearing capabilities. Colombian orthopedic clinics and Argentine sports medicine centers demand portable units for bedside post-operative verification.
- Dental Imaging:Intraoral and panoramic configurations at 40-70 kVp serve clinic-based dental chains across Brazil's southeastern urban corridor. Lower regulatory classification simplifies import licensing versus full-body systems.
- Veterinary Imaging:Equine and small-animal applications in Argentina's agricultural provinces and Brazilian veterinary teaching hospitals adapt human-portable systems with species-specific positioning tables. Niche volume limits dedicated vendor investment.
Procurement scale favors trauma imaging; margin premium favors orthopedic imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's consolidated technical documentation framework anchors Brazil's dominant position, compressing approval timelines for digital imaging equipment while radiology technician shortages rotate capital toward portable systems across the continent.
Brazil
Emergency medical services in São Paulo and Rio de Janeiro drive mobile radiography procurement, addressing transport risks for critically ill patients. ANVISA's electromagnetic compatibility mandates filter lower-cost Asian imports from formal channels. The southeastern hospital corridor anchors replacement cycles for aging analog fleets through consolidated framework agreements.
Argentina
Provincial health initiatives fund mobile diagnostic units for remote municipalities, with federal matching programs lowering acquisition barriers. The national pharmaceutical regulator imposes extended clinical evidence requirements stretching 18-24 months for non-established vendors. Buenos Aires and Córdoba concentrate orthopedic and trauma imaging demand.
Colombia
Mountainous regions and Amazon-adjacent municipalities lack fixed radiology infrastructure, creating geographic access gaps for indigenous health programs. Wireless DICOM architectures enable teleradiology partnerships for rural clinics. Medellín-Bogotá highway networks deploy ruggedized ambulance-based trauma units.
Chile
Santiago's metropolitan health network prioritizes throughput-optimized direct radiography for high-volume emergency departments. The country's national pharmaceutical regulator maintains alignment with Mercosur harmonization efforts for mutual device approval recognition. Northern mining corridors adapt portable systems for occupational health screening.
South America Portable X Ray Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated purchasing power across Brazilian hospital consortia favoring vendors with established service infrastructure. Three archetypes dominate: diversified health technology conglomerates with full imaging portfolios, dedicated radiography specialists with detector manufacturing capabilities, and regional distributors with customization expertise. Competitive moves concentrate on strategic partnerships for wireless connectivity integration and geographic expansion into Colombian underserved corridors.
Within the diversified conglomerate tier, GE Healthcare leverages its Brazilian teaching hospital presence, while Koninklijke Philips NV and Siemens Healthineers occupy positions defined by wireless architecture and direct radiography optimization respectively. These three entities exemplify how established technical infrastructure and accelerated ANVISA registration pathways create defensive moats against lower-cost entrants lacking electromagnetic compliance certification.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips NV |
| Siemens Healthineers |
| Canon Medical Systems |
| FUJIFILM Holdings Corporation |
| Shimadzu Corporation |
| Carestream Health |
| Danaher Corporation |
| Hitachi Medical Corporation |
| Others |
Value Network & Pricing Analysis
Solid-state detector substitution for legacy computed radiography plates simultaneously redraws procurement geography toward Brazilian and Colombian hospital networks while compressing per-exam economics across the value chain. This input transition concentrates pricing power with vendors holding ANVISA electromagnetic compliance certification, filtering uncertified Asian suppliers from formal channels.
Pricing Analysis
Brazilian southeastern corridor hospitals pay premium positioning fees versus Argentine provincial clinics, where federal matching programs compress acquisition budgets. Three-tier pricing structure across premium, standard, and economy levels separates emergency-grade ruggedized systems with tropical battery management from clinic-grade mobile units and analog film configurations. Cost compression in economy tiers intensifies because public hospital capital freezes sustain legacy cassette-based workflows. Emergency services demonstrate least price sensitivity due to patient transport risk mitigation value, while rural Colombian municipalities exhibit highest sensitivity amid indigenous health program budget constraints.
Supply Chain Analysis
Strategic stockpiling of cesium iodide scintillators and lithium-ion battery assemblies prevails over just-in-time approaches due to ANVISA registration timeline unpredictability and tropical climate logistics disruptions. Manufacturing concentration rests on China, South Korea, and Japan for flat-panel detectors, compact X-ray tubes, and solid-state imaging sensors. Single-source vulnerability runs through Taiwanese semiconductor foundries supplying detector readout circuitry. Distribution runs through Brazilian medical device distributors with ANVISA-established import licensing, Argentine provincial health procurement cooperatives, and Colombian ministry of health centralized tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ANVISA regulatory entrenchment creates sustainable barriers against low-cost import competition, with electromagnetic compliance certification acting as the primary switching cost mechanism.
For Market Incumbents: Consolidate service infrastructure dominance across Brazilian teaching hospital networks through extended technical support contracts that embed switching costs. Deepen backward integration into detector calibration and battery thermal management engineering to capture margin from tropical climate performance requirements. Counter emerging wireless connectivity specialists by anchoring PACS interoperability standards within hospital information system upgrade cycles. For New Entrants and Emerging Players: ANVISA's consolidated technical documentation fast-track offers accelerated market entry for digital imaging equipment vendors with pre-cleared electromagnetic compatibility testing. Colombian Amazon-adjacent municipalities and Argentine Andean corridor clinics represent the most penetrable white-space, lacking fixed radiology infrastructure and served by fragmented procurement. Pursue provincial health ministry direct contracting bypassing distributor markups, paired with teleradiology partnership packaging to demonstrate workflow value. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding ANVISA import licensing and Brazilian hospital GPO relationships but lacking detector manufacturing capabilities. Five-to-ten year viability hinges on digital radiography transition completion across public hospital networks. Watch for ANVISA Mercosur harmonization implementation as inflection signal, with mutual recognition pathways potentially unlocking Argentine and Colombian volume for Brazilian-registered platforms.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pathway Optimization | Accelerated approval timelines compress go-to-market cycles for digital imaging vendors. |
| Wireless DICOM Architecture Development | Cloud-native image routing enables teleradiology partnerships for underserved Colombian corridors. |
| Hospital System Fleet Standardization | São Paulo state consortium negotiations concentrate purchasing power behind single-source contracts. |
| Battery Thermal Management Engineering | Tropical climate lithium-ion performance optimization differentiates emergency-grade ruggedized systems. |
| Provincial Health Ministry Direct Contracting | Argentine federal matching programs lower acquisition barriers for remote municipality mobile units. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across radiology department heads, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers at Brazilian teaching hospitals and Argentine provincial health networks. Secondary validation drew from ANVISA medical device registration databases, hospital procurement records, Mercosur trade harmonization documentation, and electromagnetic compatibility certification filings. Bottom-up volume estimates from individual facility replacement cycles were triangulated against top-down healthcare expenditure projections.
Across the analysis window, the forecasting framework modeled portable X-ray device adoption by product form factor, detector technology tier, care setting intensity, and clinical application kilovoltage requirements. CAGRs were derived from weighted regression across historical procurement trajectories and projected technician shortage impacts. Industry-specific inputs included ANVISA approval velocity indices, radiology training program graduation rates, and provincial health initiative budget allocation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained ANVISA regulatory stability and continued Mercosur harmonization progress; material deviation would warrant model refresh. Revision becomes warranted when electromagnetic compliance certification backlogs or public hospital capital freeze durations cross thresholds altering replacement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Open System MRI Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Echocardiography Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Global Picture Archiving Communications System Market