
 Functional Brain Imaging Systems Market | 2026-2036
Functional Brain Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Brain Imaging Systems Market Foresight
Leasing and managed equipment service contracts is narrowing the capital barrier for mid-sized hospitals seeking PET and functional MRI capacity. Siemens Healthineers leverages its hybrid imaging portfolio to sustain installed-base loyalty across European university hospitals. GE Healthcare anchors its position through captive supply of helium-3 and gadolinium-based contrast agents. Philips Healthcare differentiates via ambulatory-compatible optical imaging systems for psychiatric outpatient settings.
Functional brain imaging systems comprise non-invasive neurophysiological measurement instruments that detect hemodynamic, metabolic, or electromagnetic signals to map cerebral activity in real time, typically achieving spatial resolution below three millimeters for BOLD-fMRI and temporal resolution near one millisecond for MEG. Their primary commercial purpose is to enable diagnosis of neurodegenerative disease, guide neurosurgical planning, and support pharmaceutical efficacy trials. Functional MRI and PET together occupy the dominant margin pool due to established reimbursement codes and high per-scan revenue, while near infrared spectroscopy represents the fastest-expanding segment for neonatal and intraoperative monitoring applications where portability outweighs absolute precision. Blood oxygen level dependent imaging leads technology adoption volumes, though diffusion tensor imaging commands premium pricing in presurgical epilepsy mapping.
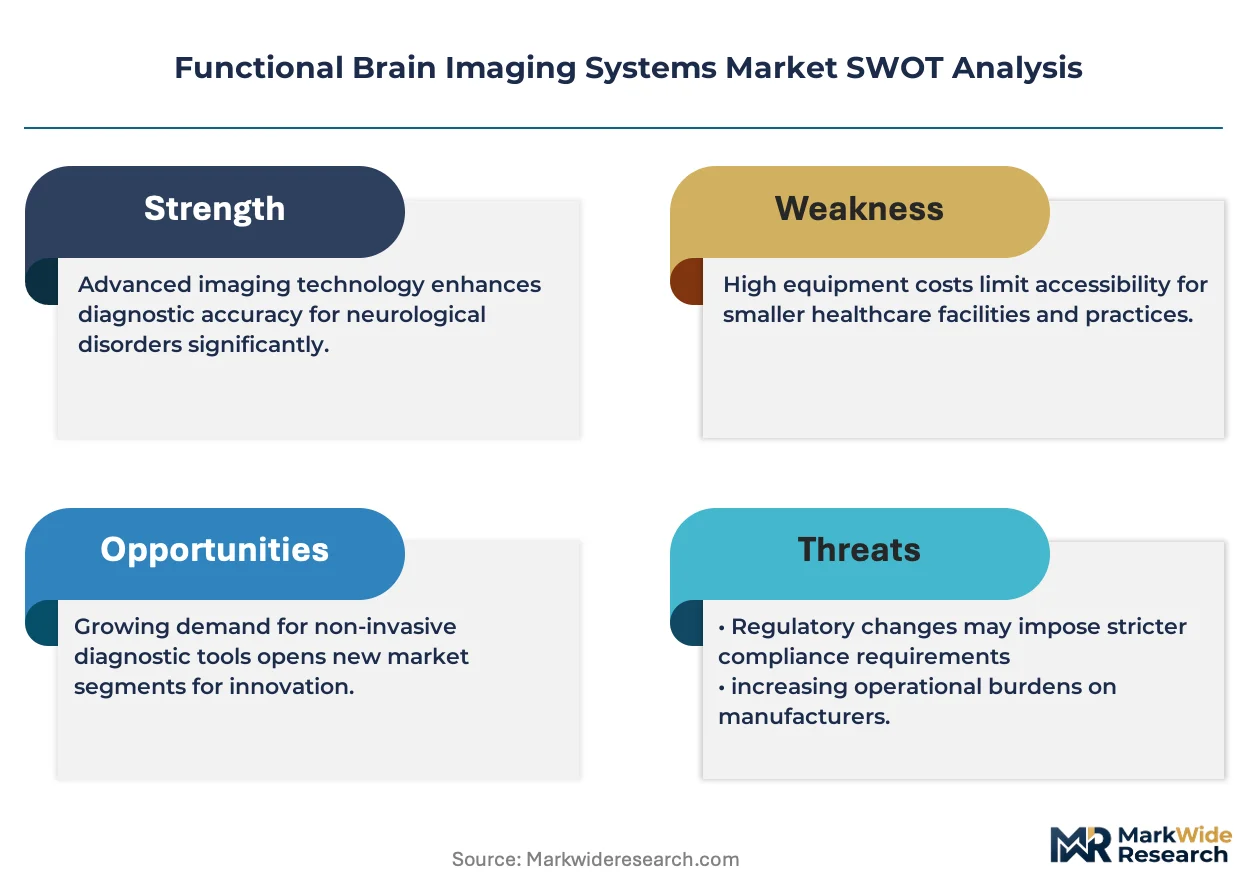
FDA premarket notification requirements for Class II neuroimaging devices govern hardware safety and software algorithm validation, while EMA's Medical Device Regulation imposes clinical evidence standards for PET radiotracer approval across EU member states. The EU AI Act introduces conformity obligations for machine-learning diagnostic adjuncts embedded in functional MRI post-processing suites. Stakeholders must monitor how FDA's evolving software-as-medical-device guidance and EMA's parallel radiopharmaceutical inspection frameworks reshape product development timelines and market access pathways.
Market Dynamics
Hybrid PET-MRI system deployment is accelerating as CMS reimbursement determinations in the United States expand coverage for amyloid-beta and tau imaging, directly altering capital allocation patterns across hospital networks and academic medical centers.
Growth Catalysts
- CMS National Coverage Determinations:Expanded Medicare reimbursement for amyloid PET imaging in Alzheimer's diagnosis drives hospital procurement cycles for PET-MRI hybrids in the United States.
- Max Planck Institute clinical research:German university hospitals and affiliated research institutes sustain demand for ultra-high-field functional MRI systems in neurodegenerative disease studies.
- Helium-3 hyperpolarized gas imaging:Advances in pulmonary neuroscience applications create crossover demand for functional lung-brain axis research platforms.
Market Restraints
- Gadolinium supply concentration:GE Healthcare's captive production of gadolinium-based contrast agents creates dependency risk for competing OEM service networks.
- Helium-3 isotope scarcity:US Department of Defense allocation priorities restrict commercial availability of hyperpolarized helium-3 for advanced diffusion imaging protocols.
- EU MDR clinical evidence thresholds:EMA's Medical Device Regulation imposes extended trial timelines for novel PET radiotracer approvals across member states.
Strategic Opportunities
- Neonatal intensive care units:Near-infrared spectroscopy penetration remains below 15% in US level-III NICUs, creating whitespace for portable cerebral oxygenation monitors.
- Psychiatric outpatient networks:Ambulatory-compatible optical imaging systems address unmet need for functional biomarkers in depression and anxiety treatment monitoring.
- EU AI Act conformity pathways:Machine-learning diagnostic adjuncts embedded in fMRI post-processing suites gain competitive differentiation through early regulatory alignment.
Industry Challenges
- MEG physicist shortage:Magnetoencephalography system operation requires specialized doctoral-level expertise that academic medical centers struggle to retain against technology sector compensation.
- Legacy PACS integration:Functional MRI data formats often conflict with hospital picture archiving systems, requiring costly middleware development for seamless workflow incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Brain Imaging Systems Market |
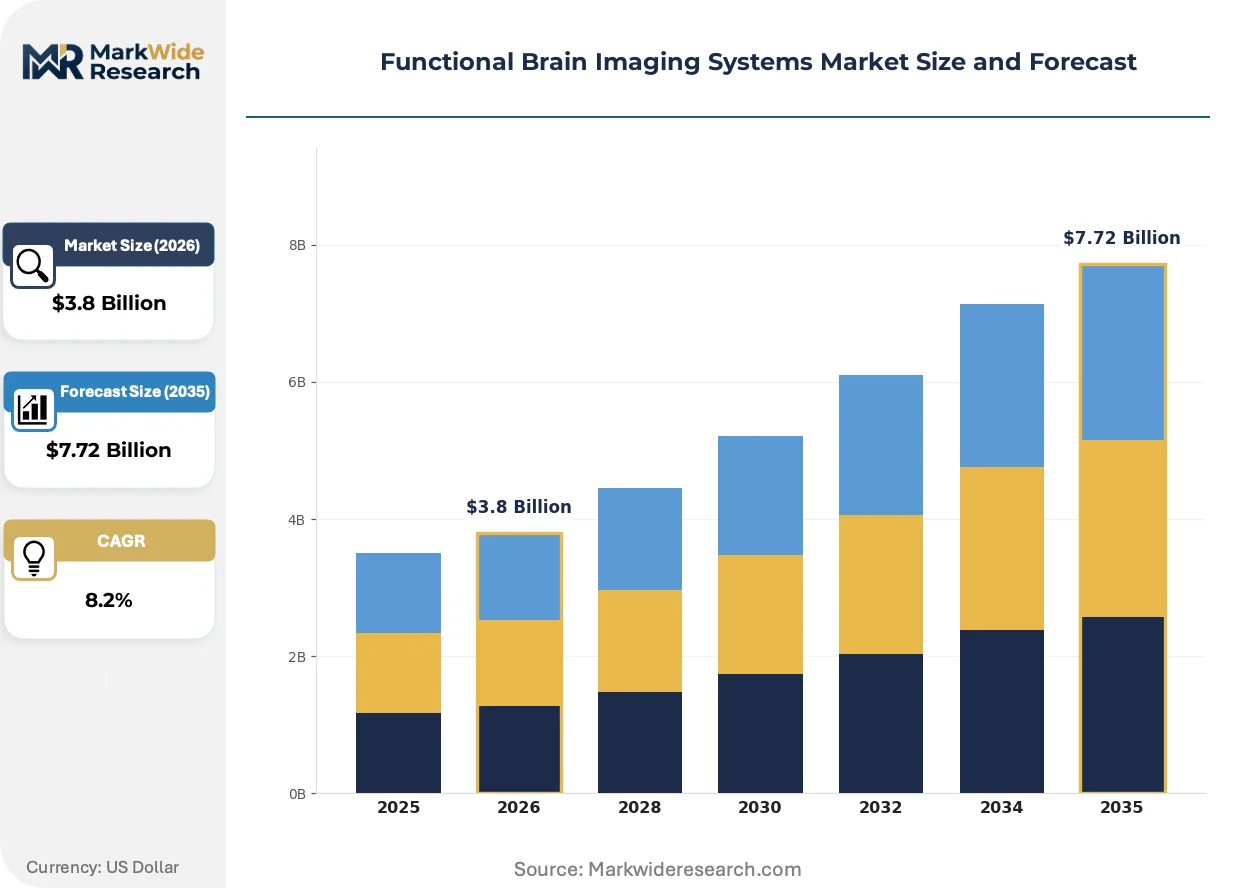
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.72 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional MRI, Positron Emission Tomography, Magnetoencephalography, Near Infrared Spectroscopy Technology: Diffusion Tensor Imaging, Blood Oxygen Level Dependent Imaging, Optical Imaging, Cerebral Blood Flow Measurement Application: Neurological Disorder Diagnosis, Cognitive Neuroscience, Psychiatric Evaluation, Brain Mapping Research End User: Research Institutes, Diagnostic Clinics, Academic Laboratories, Pharmaceutical Development |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems, Hitachi Medical Systems, Medtronic, EB Neuro, MinFound Medical Systems, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Brain Imaging Systems Market Shifts & Advancements
Computational neuroimaging is compressing the gap between research-grade spatial resolution and clinically viable scan durations, forcing equipment vendors to reconfigure hardware-software bundling strategies.
Diffusion tensor imaging is migrating from research-exclusive 7 Tesla platforms to clinically deployable 3 Tesla systems with advanced gradient coil architectures. Epilepsy surgery centers in Germany and the Netherlands are adopting these platforms for presurgical white matter tractography. The technology is migrating from academic proof-of-concept to reimbursable standard-of-care, compressing the premium pricing window for specialized neurosurgical planning services.
FDA's evolving software-as-medical-device guidance now explicitly governs machine-learning algorithms embedded in functional MRI post-processing suites. Manufacturers must submit premarket notifications for AI-driven lesion detection and volumetric analysis tools previously treated as research accessories. European vendors are responding by segregating US and EU software builds to isolate regulatory compliance costs.
Hospital procurement teams are unbundling service contracts from equipment financing, negotiating separate agreements for preventive maintenance, application training, and radiotracer logistics. Academic medical centers in the United States lead this behavior, using competitive bidding for multi-vendor service portfolios. The shift pressures OEM margins on captive service revenue while opening third-party clinical engineering markets.
Functional Brain Imaging Systems Market Segmentation
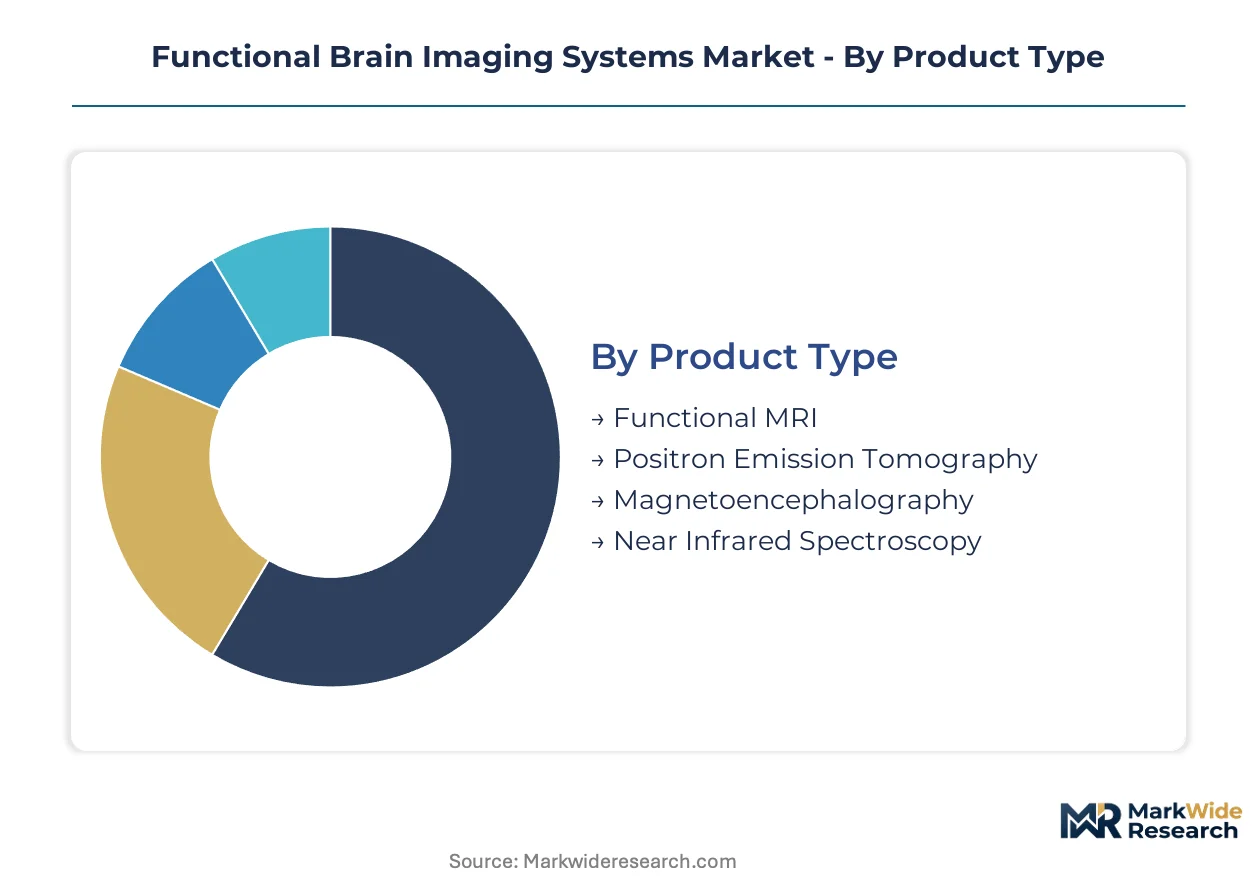
Segmentation in functional brain imaging reveals how reimbursement patterns and technical specifications fragment procurement decisions across hospital networks and research consortia. Equipment vendors must align service contract structures with the operational intensity each segment demands.
Product Type:
After-sales-service intensity varies sharply across modalities, with hybrid systems requiring multi-vendor coordination and single-technology platforms enabling standardized maintenance protocols.
- Functional MRI:Blood oxygen level dependent signal detection achieves sub-three-millimeter spatial resolution using superconducting magnet arrays. Demand concentrates in German university hospitals and Max Planck Institute affiliates where ultra-high-field research installations drive replacement cycles. Siemens Healthineers sustains installed-base loyalty through integrated coil and software upgrade pathways.
- Positron Emission Tomography:Radiotracer-dependent metabolic imaging requires cyclotron proximity or centralized isotope logistics networks. Hospital networks in the United States expand procurement as CMS national coverage determinations broaden amyloid-beta and tau imaging reimbursement.
- Magnetoencephalography:Superconducting quantum interference device arrays detect femtotesla-scale magnetic fields with millisecond temporal precision.
- Near Infrared Spectroscopy:Portable cerebral oxygenation monitoring penetrates neonatal intensive care units where bedside deployment outweighs absolute spatial precision.
By volume, functional MRI leads. By growth pace, near infrared spectroscopy is expanding most quickly.
Technology:
Cost tier stratification separates premium research-grade protocols from clinically deployable alternatives, with gradient coil architecture and field strength driving capital expenditure differentiation.
- Diffusion Tensor Imaging:White matter tractography via magnetic resonance diffusion weighting enables presurgical epilepsy mapping with advanced gradient performance. Epilepsy surgery centers in Germany and the Netherlands adopt 3 Tesla platforms with enhanced gradient coils, compressing the premium pricing window previously exclusive to 7 Tesla research systems.
- Blood Oxygen Level Dependent Imaging:Hemodynamic response detection remains the dominant clinical protocol for neurodegenerative disease assessment. Academic medical centers in the United States drive volume through standardized Alzheimer's and Parkinson's diagnostic workflows.
- Optical Imaging:Ambulatory-compatible systems address psychiatric outpatient monitoring needs with reduced capital barriers.
- Cerebral Blood Flow Measurement:Perfusion-weighted protocols guide acute stroke triage and neurovascular surgical planning.
By installed base, blood oxygen level dependent imaging dominates. By margin expansion, diffusion tensor imaging is gaining share fastest.
Application:
Customer type fragmentation splits procurement between reimbursement-driven clinical workflows and grant-funded research programs with diverging equipment specification priorities.
- Neurological Disorder Diagnosis:Alzheimer's, Parkinson's, and multiple sclerosis assessment protocols command established CPT codes in the United States. CMS coverage determinations for amyloid PET imaging directly alter capital allocation across hospital network imaging departments.
- Cognitive Neuroscience:Experimental paradigms require flexible pulse sequence programming and research collaboration tools. Max Planck Institute and German university hospital consortia sustain demand for highest-field systems with open software architectures.
- Psychiatric Evaluation:Depression and anxiety biomarker development drives ambulatory optical imaging adoption.
- Brain Mapping Research:Large-scale connectomics initiatives require harmonized data formats across multi-site consortia.
By procedure volume, neurological disorder diagnosis leads. By protocol innovation velocity, cognitive neuroscience shows the steepest expansion trajectory.
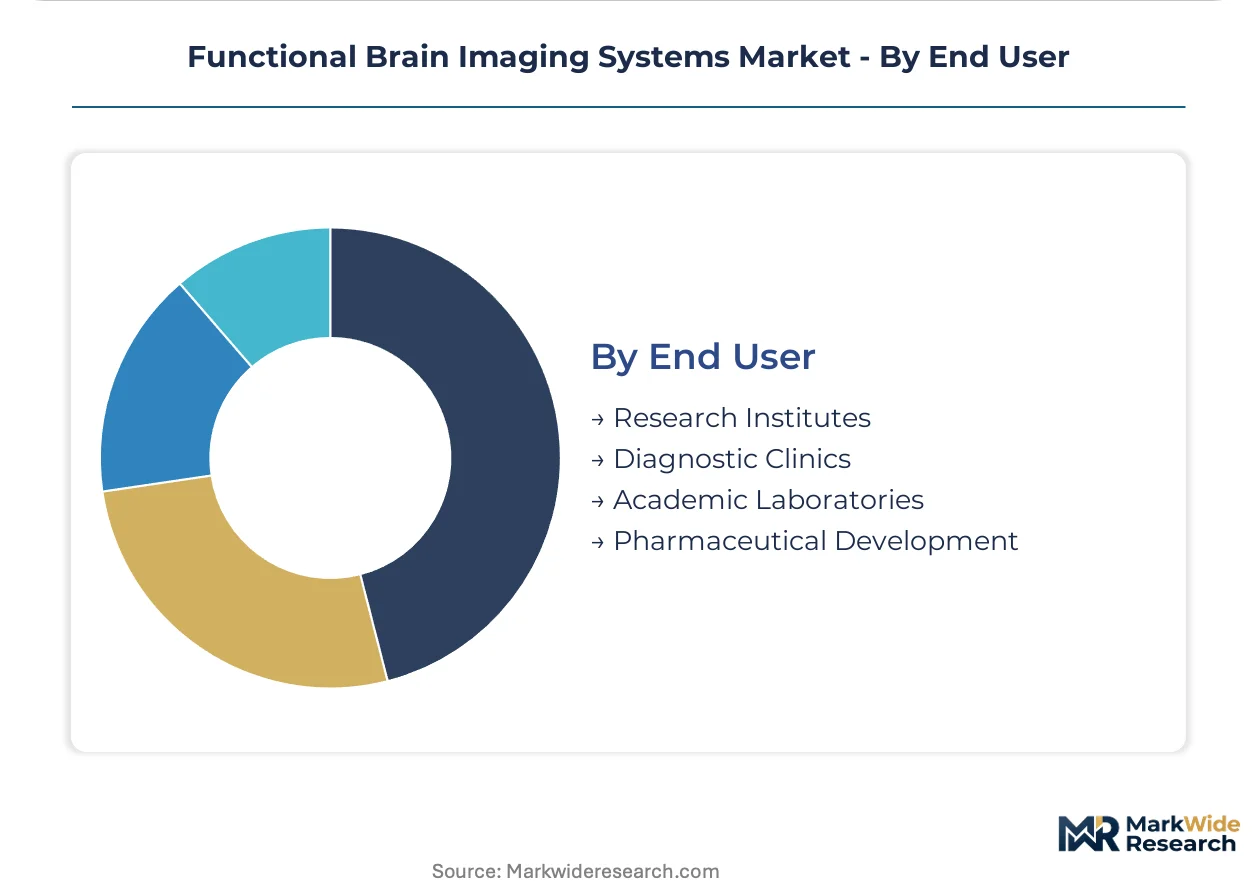
End User:
Supply concentration in contrast agent production and radiotracer logistics shapes vendor selection criteria differently across institutional categories with varying in-house chemistry capabilities.
- Research Institutes:Max Planck Institute affiliates and national laboratory networks prioritize magnetic field strength and pulse sequence flexibility over scan throughput. Helium-3 hyperpolarized gas imaging for pulmonary neuroscience applications creates crossover platform demand.
- Diagnostic Clinics:Outpatient imaging centers concentrate on reimbursable procedure volumes and rapid patient turnaround. Leasing and managed equipment service contracts narrow capital barriers for mid-sized facilities seeking PET and functional MRI capacity.
- Academic Laboratories:University-based investigators balance clinical revenue generation with grant-funded experimental programs.
- Pharmaceutical Development:Central nervous system drug trials require standardized biomarker acquisition across multi-site phase II and III studies.
By equipment value, research institutes lead. By procurement cycle frequency, diagnostic clinics are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement expansions for amyloid-beta and tau imaging reshape procurement patterns across hospital networks. German university hospitals and Max Planck Institute affiliates sustain demand for ultra-high-field research installations. Helium-3 isotope scarcity and EU MDR compliance costs create divergent regulatory pressures across major markets.
United States
Hospital networks expand PET-MRI hybrid procurement as CMS national coverage determinations broaden Medicare reimbursement for Alzheimer's diagnostic imaging. FDA software-as-medical-device guidance governs machine-learning algorithm validation in fMRI post-processing suites. Academic medical centers in Boston and Baltimore lead unbundled service contract negotiations, separating equipment financing from preventive maintenance agreements.
Germany
Max Planck Institute affiliates and university hospitals in Munich and Tübingen drive replacement cycles for 7 Tesla ultra-high-field functional MRI systems. EMA Medical Device Regulation imposes extended clinical evidence timelines for novel PET radiotracer approvals. The Helmholtz Association's neuroscience centers in Leipzig and Jülich concentrate demand for open-software-architecture research platforms.
Japan
PMDA regulatory frameworks align with FDA premarket notification pathways for Class II neuroimaging hardware. METI funding for cognitive neuroscience infrastructure sustains demand at RIKEN Brain Science Institute and University of Tokyo Hospital. Osaka-based epilepsy surgery centers adopt 3 Tesla diffusion tensor imaging platforms for presurgical white matter tractography.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement eligibility for functional brain imaging in neurodegenerative disease pathways. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements for PET radiotracer market access. London's UCL Queen Square Institute of Neurology and Oxford's Wellcome Centre for Integrative Neuroimaging anchor research-grade system deployment.
China
NMPA Class II medical device registration governs functional MRI and PET system market entry for domestic and imported equipment. National neuroscience infrastructure investments under the 14th Five-Year Plan expand capacity at Huashan Hospital in Shanghai and Beijing Tiantan Hospital. Shenzhen and Suzhou industrial zones host emerging domestic OEM assembly operations for mid-field MRI platforms.
Functional Brain Imaging Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement contexts in the functional brain imaging systems market. Siemens Healthineers, GE Healthcare, and Philips Healthcare anchor the consolidated premium tier through hybrid imaging portfolios and captive contrast agent supply chains. Mid-sized specialists occupy niches in neonatal near-infrared spectroscopy and ambulatory optical imaging. Dominant competitive moves include strategic partnerships for radiotracer logistics networks and technology licensing agreements for gradient coil architectures.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the integrated-systems archetype through hybrid PET-MRI platforms and vertical control over helium-3 or gadolinium supply. Philips Healthcare occupies a differentiated position in ambulatory-compatible optical systems for psychiatric outpatient settings. Canon Medical Systems and Hitachi Medical Systems represent the precision-engineering tier, with Japanese industrial heritage informing magnet and detector fabrication capabilities. Medtronic anchors the neurophysiological monitoring specialist segment, while EB Neuro exemplifies the European mid-cap specialist model focused on electrophysiological measurement systems.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Medical Systems |
| Hitachi Medical Systems |
| Medtronic |
| EB Neuro |
| MinFound Medical Systems |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Suzhou and Shenzhen industrial clusters anchor superconducting magnet and gradient coil fabrication for mid-field MRI platforms, concentrating component sourcing power among a handful of domestic Chinese suppliers whose capacity expansion directly compresses capital equipment pricing in downstream markets.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared systems commanding substantial premiums over CE-marked equivalents in United States hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects field strength, gradient performance, and software architecture bundling. Cost compression in the economy tier is intensifying because domestic Chinese OEMs are scaling assembly operations for 1.5 Tesla platforms. Diagnostic clinics exhibit highest price sensitivity, while Max Planck Institute affiliates prioritize pulse sequence flexibility over capital expenditure.
Supply Chain Analysis
Foundry capacity for superconducting wire and cryogenic cooling systems concentrates in Japan, Germany, and the United States, with Mitsubishi Electric and Bruker Energy & Supercon Technologies holding dominant positions in niobium-titanium filament production. The functional brain imaging supply chain draws from helium-3 isotope stockpiles managed by the US Department of Energy, gadolinium rare earth processing concentrated in Chinese Inner Mongolia operations, and specialized gradient amplifier electronics sourced from German and Japanese precision engineering clusters. Single-source vulnerability in helium-3 allocation creates procurement risk for advanced diffusion imaging protocols. Distribution runs through OEM direct sales forces for premium systems and third-party clinical engineering networks for refurbished mid-field platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are accelerating as CMS reimbursement expansions for amyloid PET imaging trigger capital release across United States hospital networks, positioning the market in early-cycle recovery.
For Market Incumbents: Insulate service revenue streams from competitive bidding pressure by unbundling preventive maintenance contracts from equipment financing and establishing captive radiotracer logistics networks. Siemens Healthineers and GE Healthcare must defend against emerging domestic Chinese OEMs in mid-field MRI by deepening backward integration into superconducting wire production and securing exclusive helium-3 allocation agreements with Department of Energy distributors. For New Entrants and Emerging Players: United States level-III neonatal intensive care units present underpenetrated whitespace for portable near-infrared spectroscopy systems where bedside deployment outweighs absolute spatial precision. Psychiatric outpatient networks in Germany and the Netherlands offer secondary entry points for ambulatory-compatible optical imaging platforms. A software-first go-to-market approach emphasizing FDA-cleared machine-learning diagnostic adjuncts enables faster regulatory alignment than hardware-heavy capital equipment strategies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized component suppliers with defensible intellectual property in gradient coil architectures and cryogenic cooling systems. Five-to-ten year viability rests on exposure to hybrid imaging platform refresh cycles rather than single-modality replacement demand. Watch CMS national coverage determination timelines for novel tau radiotracers as the inflection signal indicating accelerated PET-MRI hybrid procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS national coverage determinations for amyloid PET imaging directly alter hospital capital allocation patterns. |
| Hospital System Partnership | Academic medical centers in Boston and Baltimore lead unbundled service contract negotiations across multi-vendor portfolios. |
| CE Marking Pathway | EMA Medical Device Regulation imposes extended clinical evidence timelines for novel PET radiotracer approvals. |
| Software Companion Development | FDA software-as-medical-device guidance governs machine-learning algorithm validation in fMRI post-processing suites. |
| Strategic Partnership | Helmholtz Association neuroscience centers concentrate demand for open-software-architecture research platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and neuroradiology department heads; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA medical device registration data. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis were triangulated to establish market sizing.
Forecast inputs include modality-specific replacement cycles, field strength migration patterns, and reimbursement expansion trajectories across the projection horizon. Segmentation modeling incorporated product type, technology protocol, clinical application, and end-user institutional category. CAGRs were derived from equipment installation base growth, procedure volume elasticity to reimbursement changes, and capital expenditure survey responses from academic medical center imaging directors.
Practitioners should monitor CMS national coverage determination schedules, helium-3 allocation policy shifts from the Department of Energy, and EU AI Act conformity assessment timelines for early signals requiring forecast revision. Quarterly review of hospital network capital expenditure announcements and radiotracer manufacturing facility licensing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
South America MRI Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
South Korea Mammography Market