
 Asia Pacific Computed Tomography (CT) Market | 2026-2036
Asia Pacific Computed Tomography (CT) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Computed Tomography (CT) Market Insights
Service-based revenue from AI-enhanced image reconstruction subscriptions is shifting how CT vendors capture lifetime value from installed base contracts. Siemens Healthineers leverages embedded software analytics to sustain recurring revenue per scanner across Japanese university hospitals. Canon Medical Systems anchors its Asia Pacific position through dense field service networks in Thailand and Vietnam. Neusoft Medical Systems competes on localized imaging protocols designed for high patient throughput in Chinese provincial facilities.
Computed tomography in the Asia Pacific region generates cross-sectional anatomical images using rotating X-ray tubes and detector arrays, with modern systems achieving sub-millimeter spatial resolution through helical acquisition geometries and iterative reconstruction algorithms. Multi-slice CT dominates installed capacity across the region's hospital networks, while photon-counting technology captures premium replacement cycles as early adopters in South Korea and Australia validate dose reduction claims. Portable CT segments address emergency and intraoperative demand, though margins concentrate in fixed-site oncology and neurology applications where contrast-enhanced protocols require higher tube power and advanced detector coverage.
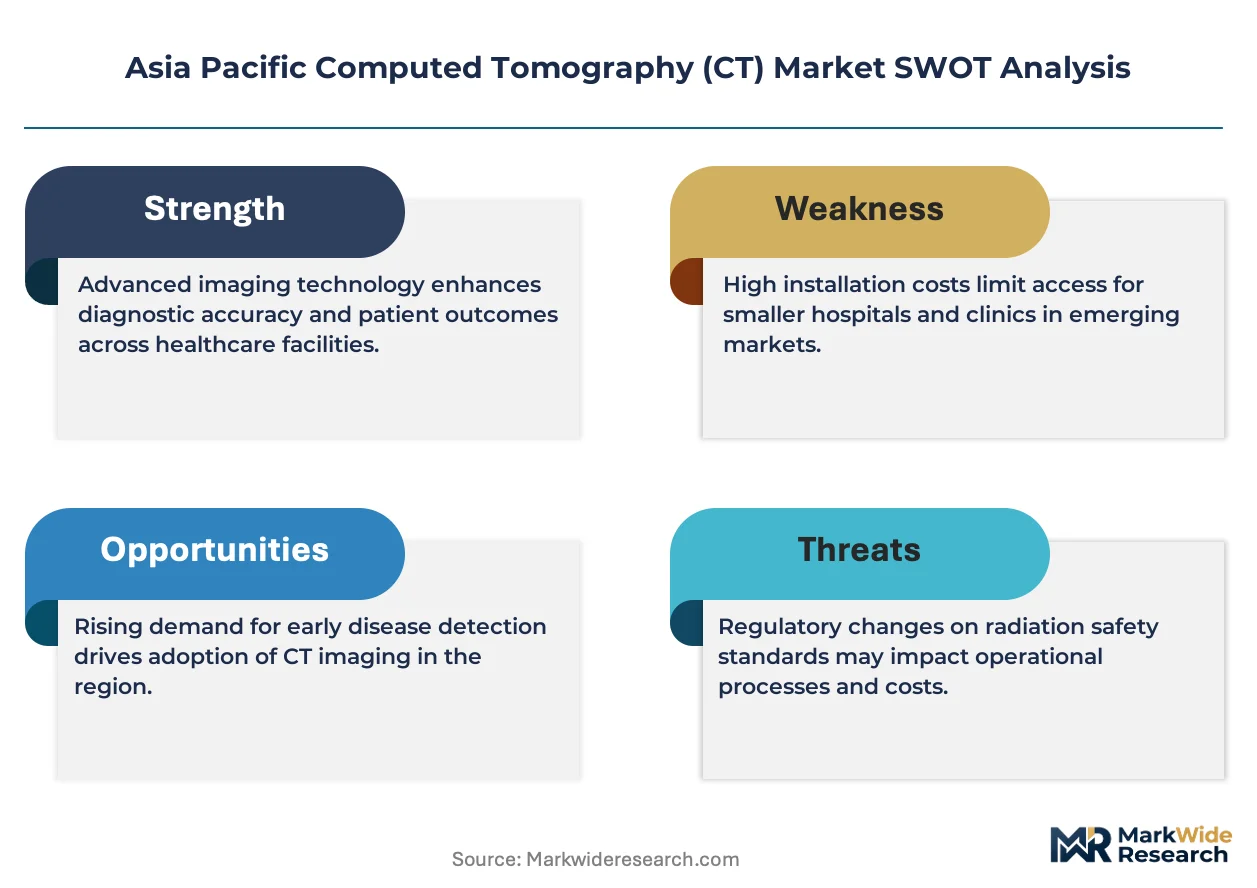
Japan's PMDA and China's NMPA enforce divergent clinical evidence requirements for novel CT technologies, creating dual-track regulatory burdens for manufacturers seeking broad Asia Pacific access. India's CDSCO has aligned import licensing with BIS electrical safety standards, extending product registration timelines for non-domestic suppliers. Procurement officers must monitor how China's volume-based purchasing reforms redistribute scanner allocations across provincial health alliances without eroding service contract profitability.
Market Dynamics
Photon-counting detector technology is compressing replacement cycles across Asia Pacific hospital networks as dose reduction protocols become non-negotiable in tender specifications. China's volume-based procurement reforms are redistributing scanner allocations across provincial health alliances, forcing vendors to restructure service contract economics without eroding margin pools.
Growth Catalysts
- Centralized procurement mandates:China's tier-one city hospital networks are modernizing radiology infrastructure under unified equipment standards, creating predictable demand pipelines for multi-slice CT systems.
- Cancer screening volumes:Southeast Asian hospitals are expanding diagnostic imaging fleets to manage rising oncology case loads, particularly in Thailand and Vietnam where public health programs prioritize early detection.
- PMDA streamlined pathways:Japan's pharmaceutical and medical device agency has accelerated approval timelines for photon-counting systems, reducing regulatory friction for next-generation scanner introductions.
Market Restraints
- Dual-track regulatory burdens:Divergent clinical evidence requirements between Japan's PMDA and China's NMPA force manufacturers to maintain parallel approval processes, inflating compliance costs.
- Import licensing friction:India's CDSCO alignment with BIS electrical safety standards extends product registration timelines for non-domestic suppliers, constraining supply responsiveness.
- Helium supply concentration:Superconducting magnet cooling depends on constrained helium sourcing, with price volatility threatening superconductive CT system production economics.
Strategic Opportunities
- AI-enhanced reconstruction subscriptions:Embedded software analytics are shifting vendor revenue models toward recurring service streams from installed base contracts.
- Portable CT segments:Emergency and intraoperative applications remain underpenetrated across Indonesian and Philippine hospital networks, offering expansion vectors beyond fixed-site oncology.
- Photon-counting replacement waves:South Korean and Australian early adopter validation of dose reduction claims is creating premium upgrade demand across academic medical centers.
Industry Challenges
- Iterative reconstruction expertise gaps:Advanced algorithm deployment requires specialized radiology informatics skills that remain scarce across provincial Chinese and Indian imaging departments.
- Legacy system integration complexity:PACS connectivity and workflow interoperability with existing hospital information systems creates implementation friction during scanner fleet upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Computed Tomography (CT) Market |
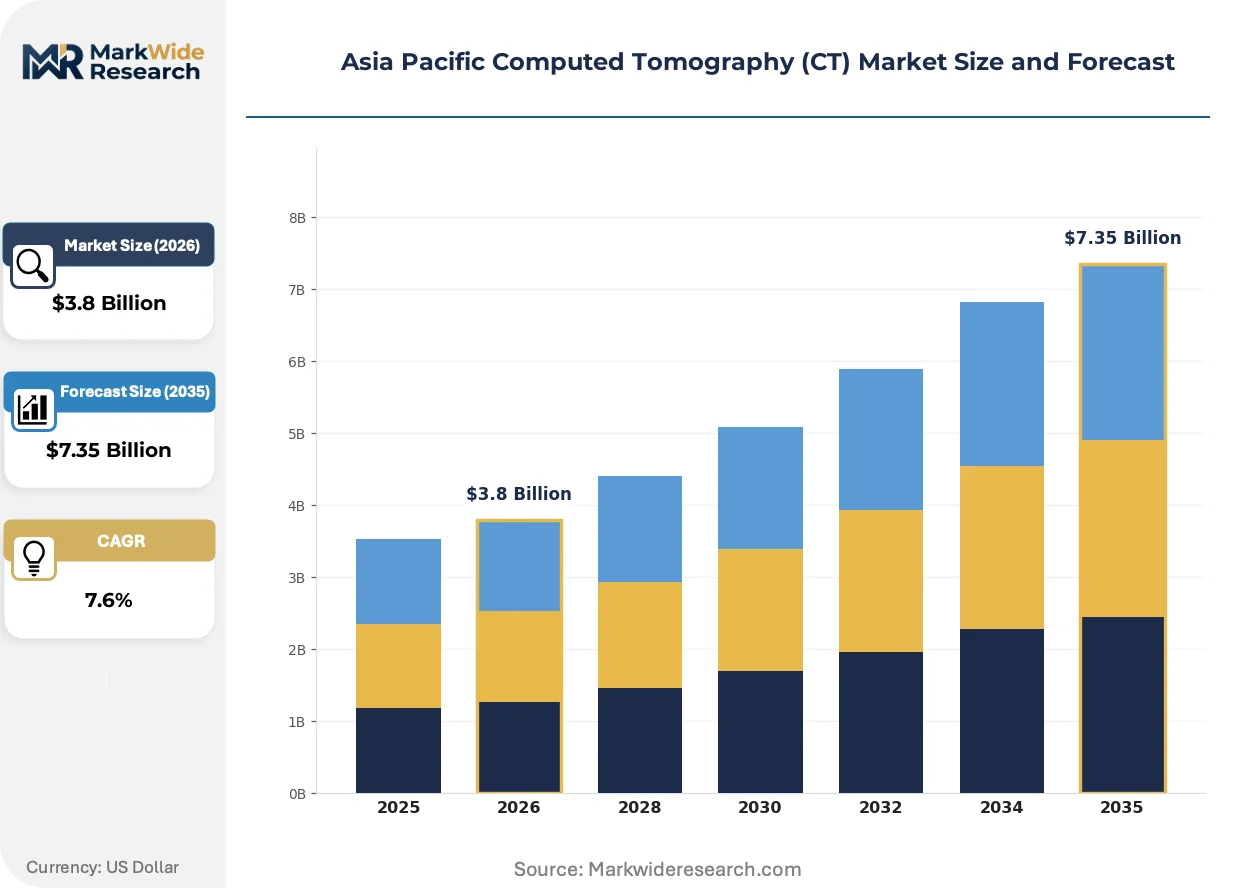
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical CT, Cone Beam CT, Multi-Slice CT, Portable CT Technology: Analog, Digital, Photon Counting, Dual-Energy End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Application: Oncology, Neurology, Cardiology, Musculoskeletal |
| Companies Covered | Canon Medical Systems Corporation, GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Hitachi Healthcare Systems, Fujifilm Holdings Corporation, Neusoft Medical Systems Co. Ltd, Shenzhen Anke High-Tech Co. Ltd, Shimadzu Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Computed Tomography (CT) Market Trends and Innovations
Software-defined imaging architectures are displacing hardware-centric product roadmaps across Asia Pacific CT vendor strategies. Three developments are compressing innovation cycles and redistributing competitive advantage.
Photon-counting detector technology is converging with deep learning-based noise reduction algorithms to enable sub-mSv dose protocols without sacrificing diagnostic confidence. Japanese university hospitals are validating these systems for cardiac and pediatric applications where cumulative radiation exposure carries heightened liability. The convergence is compressing the premium scanner segment, forcing vendors to differentiate through analytics integration rather than raw detector specifications alone.
China's NMPA has tightened clinical evidence requirements for AI-enabled diagnostic software, mandating prospective validation studies for algorithms supporting triage or quantification. This regulatory shift is filtering software vendors without hospital partnership networks, concentrating AI module approvals among established scanner OEMs with captive clinical sites. Korean and Australian regulators are monitoring these evidentiary standards for potential harmonization, creating anticipatory compliance investments across regional R&D budgets.
After-sales service unbundling is fragmenting traditional full-service contracts into componentized offerings across Southeast Asian private hospital chains. Procurement officers in Bangkok and Ho Chi Minh City are negotiating remote monitoring subscriptions separately from on-site engineer dispatch, pressuring vendor field service density economics. This behavioral shift is most visible in Thailand, where hospital groups with captive biomedical engineering teams prefer software-only support tiers for established scanner fleets.
Asia Pacific Computed Tomography (CT) Market Segmentation
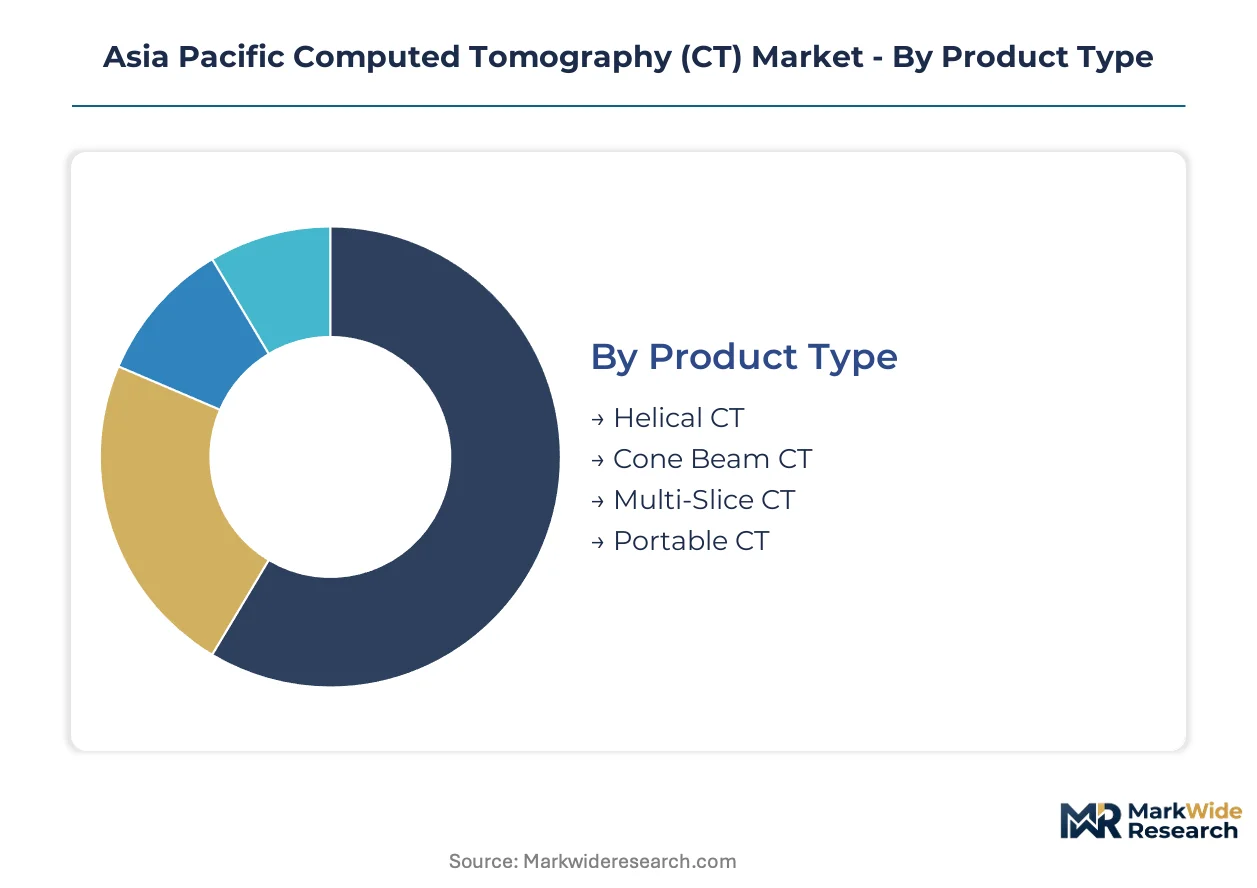
CT market segmentation reveals how hardware specifications, detector physics, and clinical workflows fragment procurement priorities across Asia Pacific hospital networks. Vendor positioning depends on matching product architecture to specific end-use throughput requirements and regulatory compliance burdens.
Product Type:
Scanner geometry and gantry mobility define capital allocation patterns across fixed-site and point-of-care deployments.
- Multi-Slice CT:Systems with 64+ detector rows dominate installed capacity across Asia Pacific hospital networks, delivering sub-millimeter isotropic resolution for contrast-enhanced oncology protocols. China's tier-one public hospitals prioritize 128-slice and 256-slice configurations under centralized procurement mandates to handle high patient throughput.
- Helical CT:Continuous patient translation during tube rotation enables volumetric acquisition without inter-scan delays, supporting cardiac and vascular imaging where motion artifacts compromise diagnostic confidence. Southeast Asian diagnostic centers favor these systems for their balance of acquisition speed and capital efficiency.
- Cone Beam CT:Flat-panel detector geometry delivers high spatial resolution at reduced radiation dose for maxillofacial and extremity applications.
- Portable CT:Self-contained gantry systems on motorized bases address intraoperative neurosurgery and emergency department demand where patient transport risks outweigh fixed-scanner throughput advantages.
Mature deployment sits with Multi-Slice CT across Japan's university hospitals and China's provincial medical centers. Newer deployment is concentrated in Portable CT segments across Indonesian and Philippine emergency networks.
Technology:
Detector signal processing architecture determines dose efficiency, spectral discrimination capability, and replacement cycle timing.
- Photon Counting:Direct X-ray photon registration eliminates electronic noise inherent in energy-integrating detectors, enabling sub-mSv dose protocols for pediatric and repeat screening applications. Japan's PMDA has streamlined approval pathways for these systems, accelerating turnover in academic medical centers where cumulative radiation liability drives procurement specifications.
- Digital:Solid-state scintillator-photodiode arrays with analog-to-digital conversion dominate current installed base across Asia Pacific, balancing diagnostic performance against service infrastructure maturity. Korean and Australian hospitals are validating these platforms as bridge technology during photon-counting transition periods.
- Analog:Legacy detector electronics persist in secondary imaging departments with constrained capital renewal cycles.
- Dual-Energy:Rapid kVp switching or dual-layer detectors enable material decomposition for gout, kidney stone, and perfusion imaging.
Digital platforms anchor current procurement volumes across Thailand and Vietnam. Photon Counting is expanding most quickly in South Korea's national cancer screening programs and Australia's tertiary referral networks.
End User:
Facility scale and patient acuity shape scanner specification requirements and service contract structures.
- Hospitals:Tertiary medical centers with 24/7 emergency services and interventional capabilities require high tube power, advanced cardiac gating, and comprehensive detector coverage for trauma and stroke protocols. China's public hospital networks under volume-based procurement reforms are consolidating scanner allocations across provincial health alliances.
- Diagnostic Centers:Specialized imaging facilities prioritize throughput optimization and rapid patient turnaround for elective screening volumes, particularly in India's urban private healthcare markets where out-of-pocket payment sensitivity demands competitive per-scan pricing.
- Research Institutions:University-affiliated hospitals and translational imaging centers drive early adoption of spectral and quantitative CT techniques.
- Outpatient Clinics:Limited-service settings concentrate on extremity and low-complexity head imaging with refurbished or entry-tier systems.
Hospital procurement commands premium system configurations and multi-year service捆绑. Diagnostic Centers are gaining share fastest as India's CDSCO streamlines licensing for standalone imaging facilities.
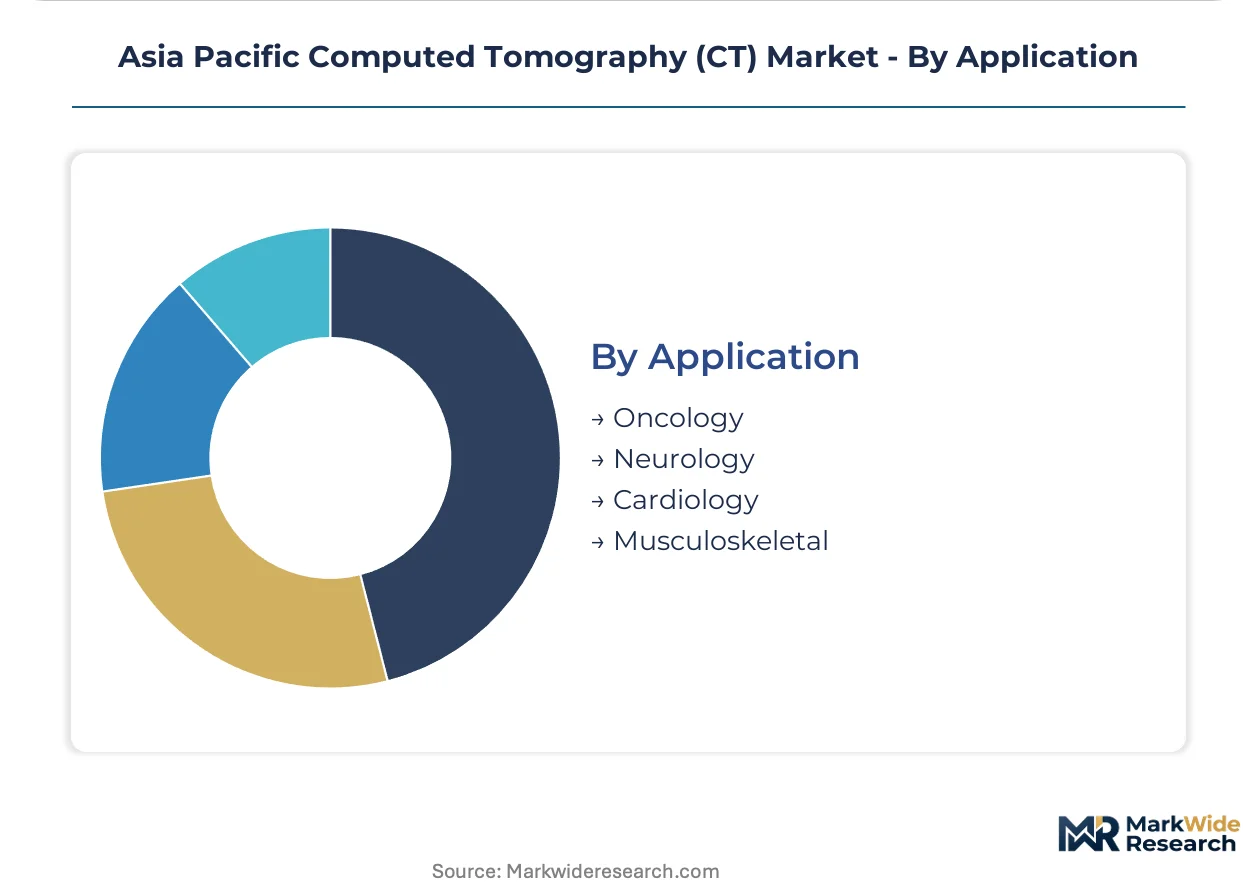
Application:
Clinical indication determines contrast protocol requirements, temporal resolution needs, and reimbursement dynamics.
- Oncology:Staging and treatment response monitoring drives demand for multi-phase contrast-enhanced protocols with large anatomical coverage, particularly across China's national cancer control program where screening volume targets mandate high-throughput scanner deployment. Low-dose lung cancer screening protocols in Japan and South Korea accelerate detector technology turnover.
- Neurology:Stroke imaging workflows require sub-minute acquisition-to-diagnosis intervals, favoring scanners with rapid reconstruction pipelines and automated perfusion analysis. Southeast Asian hospital networks are expanding dedicated neuro-CT capacity to manage hemorrhagic and ischemic cerebrovascular disease burdens.
- Cardiology:Coronary calcium scoring and CT angiography demand high temporal resolution and robust arrhythmia rejection algorithms.
- Musculoskeletal:Extremity and spine imaging tolerates longer acquisition times with lower tube power requirements.
Oncology applications anchor fixed-site scanner utilization rates across Asia Pacific. Cardiology is climbing the fastest as coronary CT angiography displaces invasive diagnostic catheterization in Japanese and Australian reimbursement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific CT scanner production concentrates in Japan, China, and South Korea, while consumption spreads across Australia's tertiary networks, India's private diagnostic chains, and Southeast Asia's expanding hospital infrastructure.
China
Volume-based procurement reforms are consolidating scanner allocations across provincial health alliances, with tier-one cities like Shanghai and Beijing driving multi-slice CT demand under centralized equipment mandates. NMPA tightened clinical evidence requirements for AI-enabled diagnostic software, filtering software vendors without hospital partnership networks. Yangtze River Delta medical centers are validating photon-counting systems for pediatric applications.
Japan
PMDA streamlined approval pathways for photon-counting detector systems, accelerating technology turnover in university hospitals where cumulative radiation liability shapes procurement. Cardiac and stroke imaging workflows command premium scanner specifications across Kanto region academic medical centers. Tokyo-based hospital networks are embedding AI-enhanced reconstruction into service contracts.
South Korea
National cancer screening programs are validating dose reduction claims from photon-counting detectors, creating replacement demand across Seoul Capital Area referral networks. MFDS alignment with international evidentiary standards is compressing approval timelines for next-generation platforms. Busan-Ulsan hospital clusters are expanding dedicated neuro-CT capacity.
Australia
Tertiary referral networks are early adopters of spectral CT techniques, with Sydney and Melbourne academic centers driving quantitative imaging validation. TGA monitoring of NMPA evidentiary standards is creating anticipatory compliance investments across regional R&D budgets. Western Australia mining corridor hospitals are deploying portable CT for emergency trauma protocols.
India
CDSCO alignment with BIS electrical safety standards extends product registration timelines, constraining supply responsiveness for non-domestic suppliers. Urban private diagnostic centers in Maharashtra and Karnataka prioritize throughput optimization for elective screening volumes. Delhi-NCR hospital networks are negotiating unbundled service contracts separately from equipment procurement.
Asia Pacific Computed Tomography (CT) Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning, while mid-tier regional specialists compete on localized imaging protocols and field service density. Market structure tilts toward consolidated vendor concentration among Japanese and German-origin OEMs with captive software analytics capabilities. Three archetypes dominate: full-system integrators with embedded AI platforms, regional service-heavy operators with dense Southeast Asian networks, and Chinese domestic suppliers competing on provincial procurement compliance. Competitive moves center on AI module partnerships and after-sales contract unbundling.
Within the full-system integrator tier, Siemens Healthineers and Canon Medical Systems exemplify divergent Asia Pacific strategies. Siemens leverages embedded software analytics to sustain recurring revenue across Japanese university hospital installed bases. Canon anchors regional positioning through dense field service networks in Thailand and Vietnam. GE Healthcare occupies a position bridging premium-tier technology with emerging market accessibility. Chinese domestic capability concentrates in Neusoft Medical Systems and Shenzhen Anke High-Tech, representing provincial procurement specialization.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Hitachi Healthcare Systems |
| Fujifilm Holdings Corporation |
| Neusoft Medical Systems Co. Ltd |
| Shenzhen Anke High-Tech Co. Ltd |
| Shimadzu Corporation |
| Others |
Pricing and Supply Chain Analysis
China's provincial health alliance procurement officers anchor pricing power through volume-based tender aggregation, compressing margins across photon-counting and digital detector tiers while elevating service contract economics as the residual profit pool.
Pricing Analysis
Margin tightening in premium scanner tiers reflects China's centralized procurement mandates stripping brand premiums from hardware transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector row count and AI module bundling, with provincial hospitals exhibiting acute price sensitivity while Japanese university centers prioritize dose-reduction specifications over acquisition cost. Cost-down pressure on mid-tier configurations accelerates because domestic Chinese OEMs compete on localized imaging protocols.
Supply Chain Analysis
Helium supply for superconducting magnet cooling rests on concentrated Qatari and Algerian extraction, with detector array fabrication drawing from Japanese and German semiconductor foundries. X-ray tube filament production sources from specialized tungsten processors in China and Austria, while scintillator crystal growth concentrates in Japanese and American specialty material houses. Single-source vulnerability in helium logistics threatens superconductive CT production economics. Distribution runs through regional OEM service depots with field engineer density determining contract win rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector manufacturing capacity constraints prop pricing across Asia Pacific, with qualified foundry slots booked through multi-year hospital validation cycles.
For Market Incumbents: Lock in photon-counting foundry partnerships through exclusive supply agreements before South Korean and Australian validation studies conclude. Deepen backward integration into scintillator crystal supply to defend margin position against Chinese domestic OEMs capturing provincial procurement volume. Prioritize AI-enhanced reconstruction subscription attach rates over hardware margin recovery. For New Entrants and Emerging Players: Portable CT systems for Indonesian and Philippine emergency networks represent the most penetrable white-space segment, with intraoperative neurosurgery applications underserved by incumbent field service density. Target unbundled remote monitoring contracts for established scanner fleets in Thai hospital groups with captive biomedical engineering capabilities. For Investors and Strategic Acquirers: The window for entry favors regional service-heavy operators with dense Southeast Asian networks and AI module partnerships. Long-term viability hinges on software analytics recurring revenue streams displacing transactional hardware economics. Watch NMPA harmonization with international AI evidentiary standards as the inflection signal for Chinese market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Foundry Partnership | Secures detector supply for PMDA-accelerated replacement cycles in Japanese academic centers. |
| AI-Enhanced Reconstruction Subscription | Shifts Siemens Healthineers revenue model toward recurring streams across installed base contracts. |
| Provincial Health Alliance Compliance | Enables Neusoft Medical Systems participation in China's volume-based procurement mandates. |
| Southeast Asian Field Service Expansion | Anchors Canon Medical Systems positioning through dense engineer networks in Thailand and Vietnam. |
| Helium Supply Diversification | Mitigates production risk for superconductive CT systems dependent on constrained cooling gas sourcing. |
Research Methodology
Regulatory filings from PMDA, NMPA, and MFDS, trade customs data for CT scanner imports, and hospital procurement databases formed the secondary backbone. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads validated installed base estimates and replacement cycle timing. Bottom-up and top-down triangulation reconciled vendor shipment data with national health infrastructure investment disclosures.
Bottom-up modeling segmented the market across product type, detector technology, end-user facility scale, and clinical application, with top-down validation against national healthcare expenditure trajectories. CAGRs derived from curve-fitting historical procurement volumes to projected health alliance equipment mandates and cancer screening program expansion timelines across the analysis window. Forecast inputs incorporated photon-counting validation study completion schedules and AI software evidentiary requirement evolution.
Several conditions sit outside the modeled scope, including abrupt helium supply disruptions, regulatory harmonization failures between PMDA and NMPA, and unforeseen reimbursement cuts affecting scanner utilization economics. Forecasts reflect documented assumptions regarding procurement reform implementation pacing and technology adoption S-curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Open System MRI Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Wireless Intraoral Camera Market