
 Canada Nuclear Imaging Market | 2026-2036
Canada Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Nuclear Imaging Market Outlook
The split between premium hybrid imaging systems and commodity gamma camera replacements is realigning procurement patterns across Canadian provinces. GE Healthcare dominates the high-end PET-CT segment through its installed base in Toronto and Montreal academic centers. Siemens Healthineers leverages its digital PET reconstruction platform to sustain pricing power in replacement cycles. Jubilant Radiopharma anchors the domestic radiopharmaceutical supply chain with its cyclotron network spanning Ontario, Quebec, and British Columbia.
Canada nuclear imaging encompasses diagnostic modalities that detect gamma-ray emissions from radiopharmaceutical tracers to visualize organ function, metabolic activity, and disease pathways at resolutions reaching sub-centimeter spatial accuracy. PET scanners and SPECT systems serve distinct clinical purposes: PET exploits positron-electron annihilation for quantitative metabolic mapping, while SPECT relies on direct gamma detection for broader anatomical coverage at lower tracer cost. Hybrid imaging technology leads capital expenditure, as PET-CT and PET-MRI fusion systems command premium placement in tertiary hospitals. Artificial Intelligence represents the fastest-expanding technology layer, with deep learning algorithms automating lesion detection and attenuation correction to reduce interpretation time.
Health Canada and the Canadian Nuclear Safety Commission jointly govern radiopharmaceutical manufacturing, distribution, and clinical use through licensing protocols that dictate tracer shelf life, transport containers, and waste disposal standards. The Canadian Association of Nuclear Medicine maintains practice guidelines that influence provincial reimbursement decisions and equipment procurement timelines. Stakeholders must monitor how Ontario's health technology assessment processes and Quebec's centralized radiopharmaceutical tendering reshape competitive access across Canada's two largest provincial markets.
Market Dynamics
Hybrid imaging system procurement across Canadian provinces is compressing replacement cycles as Ontario and Quebec health authorities prioritize quantitative metabolic mapping capabilities in tertiary centers.
Growth Catalysts
- Regulatory Modernization:Health Canada's streamlined radiopharmaceutical approval pathways are truncating time-to-market for novel diagnostic tracers.
- Oncology Precision Staging:PET-CT utilization is expanding across Canadian hospital oncology departments for tumor characterization and treatment monitoring.
- Provincial Budget Allocations:Ontario and Quebec health technology assessment processes are funding molecular imaging installations through centralized capital programs.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production relies on aging Canadian NRU reactor infrastructure and limited international supplier alternatives.
- Capital Intensity Barrier:PET-MRI hybrid systems require infrastructure investments exceeding standard imaging suite budgets, constraining community hospital access.
- Tracer Shelf-Life Constraints:Short half-lives of fluorine-18 and technetium-99m compounds necessitate cyclotron proximity, limiting rural service expansion.
Strategic Opportunities
- Artificial Intelligence Integration:Deep learning algorithms for automated lesion detection and attenuation correction are reducing interpretation bottlenecks in high-volume centers.
- British Columbia Expansion:Underpenetrated western provinces present installation growth potential as provincial health authorities evaluate hybrid imaging procurement.
- Digital PET Reconstruction:Advanced reconstruction platforms are enabling dose reduction protocols that lower operational costs per scan.
Industry Challenges
- Specialized Workforce Scarcity:Nuclear medicine technologist and radiopharmacist training programs are producing insufficient graduates to staff expanding cyclotron facilities.
- Legacy System Integration:PACS interoperability between SPECT archives and new PET-CT platforms is creating data migration complexity during hospital upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Nuclear Imaging Market |
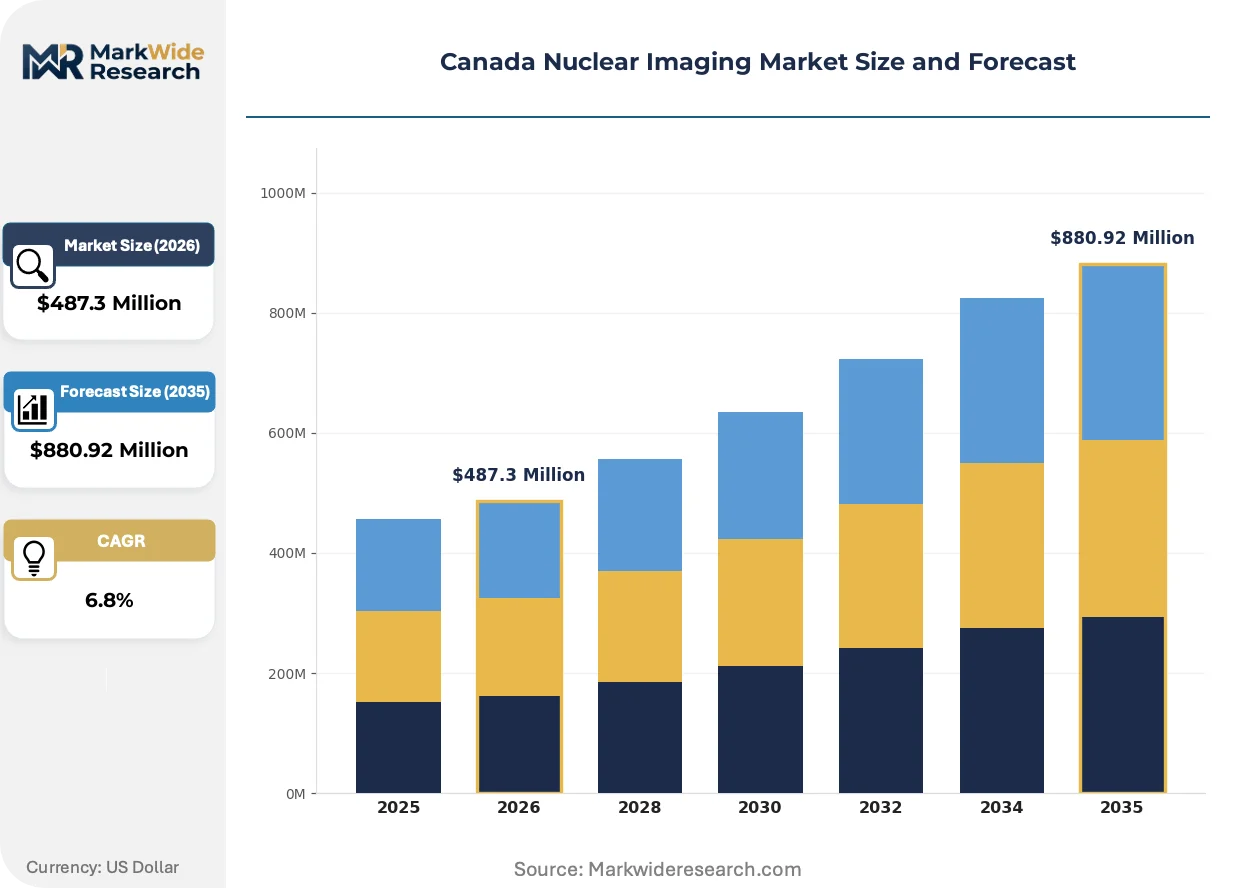
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, PET Scanners, SPECT Systems, Radiopharmaceuticals End User: Hospitals, Diagnostic Laboratories, Research Institutions, Specialty Clinics Application: Oncology, Cardiology, Neurology, Thyroid Disorders Technology: Hybrid Imaging, Digital Imaging, 3D Imaging, Artificial Intelligence |
| Companies Covered | Jubilant Radiopharma, Canon Medical Systems, GE Healthcare, Lantheus Holdings, Bracco Imaging, Siemens Healthineers, BWXT Medical, Nordion, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Nuclear Imaging Market Strategic Shifts
Artificial intelligence layers are penetrating Canadian nuclear imaging workflows at accelerating velocity, compressing scan interpretation timelines and enabling quantitative biomarker extraction from metabolic datasets.
Digital PET reconstruction platforms are rewriting how Canadian academic medical centers approach dose optimization and image quality tradeoffs. Siemens Healthineers' digital photon-counting architecture is penetrating replacement cycles at Toronto and Montreal tertiary sites. The technology is rewriting procurement specifications as Ontario's health technology assessment processes begin mandating dose-reduction capabilities in new system tenders.
Health Canada's regulatory modernization for radiopharmaceutical manufacturing is compressing approval timelines for novel diagnostic tracers. The Canadian Nuclear Safety Commission's updated licensing protocols are enabling cyclotron network expansion across provincial jurisdictions. British Columbia and Alberta health authorities are responding by evaluating decentralized tracer production models to reduce transport logistics constraints.
Provincial tendering consolidation is restructuring how equipment vendors access Canadian hospital procurement channels. Quebec's centralized radiopharmaceutical purchasing is displacing hospital-level contracting autonomy with multi-year supply agreements. The shift is most visible in Ontario, where Cancer Care Ontario's imaging procurement frameworks are standardizing equipment specifications across regional health networks.
Canada Nuclear Imaging Market Segmentation
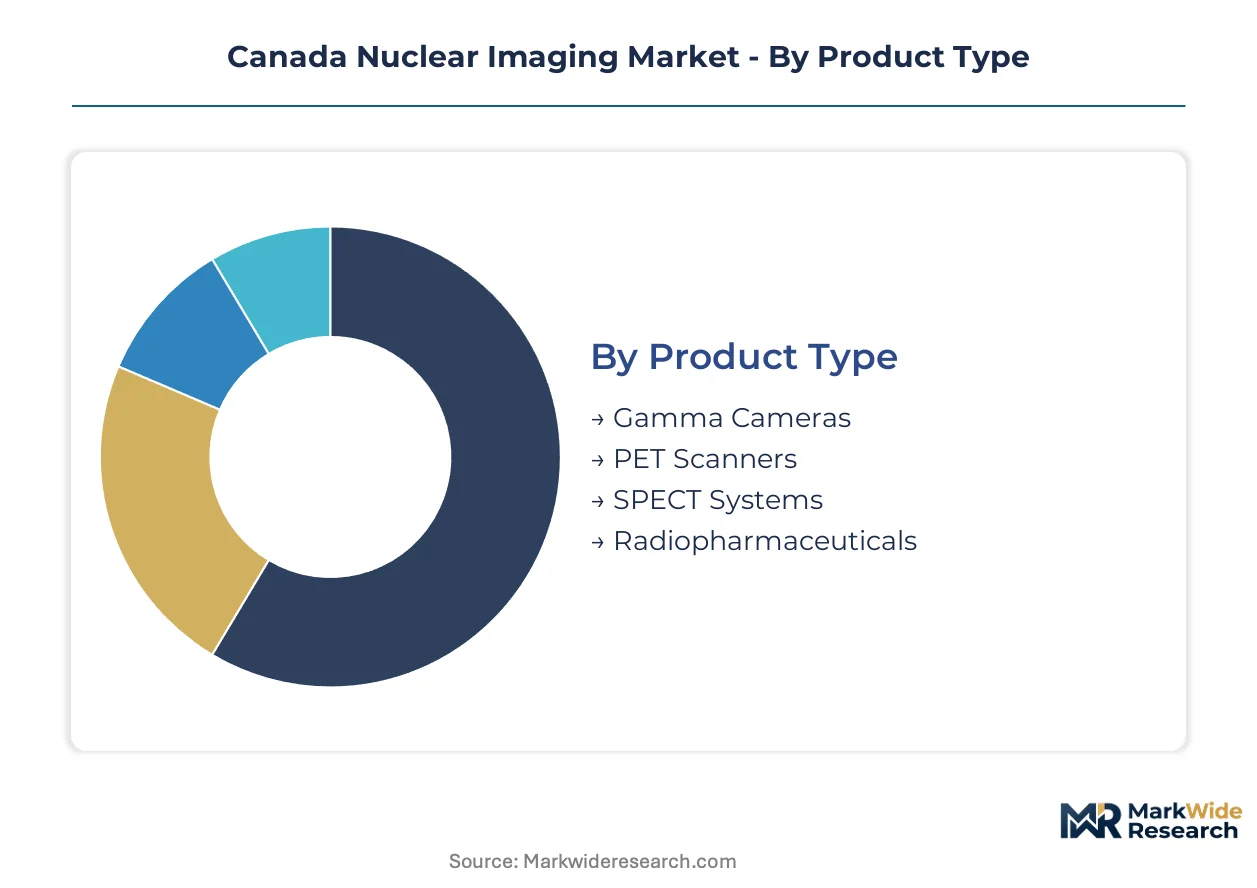
Segmentation in Canada's nuclear imaging market reveals how procurement power concentrates in hybrid imaging systems while tracer production networks dictate geographic service reach. Understanding these splits exposes where capital flows and where regulatory bottlenecks constrain expansion.
Product Type:
Supply concentration in cyclotron manufacturing and isotope logistics creates divergent margin structures across equipment versus consumable segments.
- PET Scanners:Positron emission tomography systems exploit positron-electron annihilation for quantitative metabolic mapping at sub-centimeter resolution. Demand clusters in Toronto and Montreal tertiary centers where Ontario and Quebec health authorities fund precision oncology staging programs.
- Radiopharmaceuticals:Diagnostic tracers including fluorine-18 and technetium-99m compounds require cyclotron proximity due to short half-lives. Jubilant Radiopharma's network spanning Ontario, Quebec, and British Columbia anchors domestic supply, constraining rural hospital access.
- SPECT Systems:Single photon emission computed tomography relies on direct gamma detection for broader anatomical coverage at lower operational cost per scan.
- Gamma Cameras:Conventional planar imaging devices serve routine cardiac and bone scans in community hospital settings where capital budgets limit hybrid system acquisition.
Today's leader: PET Scanners. Tomorrow's challenger: Radiopharmaceuticals.
End User:
Procurement authority shifts from hospital capital committees to provincial health technology assessment bodies as equipment costs escalate.
- Hospitals:Tertiary academic medical centers in Toronto, Montreal, and Vancouver concentrate PET-CT and PET-MRI installations. Cancer Care Ontario's imaging procurement frameworks standardize equipment specifications across regional health networks, compressing vendor negotiation leverage.
- Diagnostic Laboratories:Independent imaging centers face reimbursement pressure from provincial fee schedules while competing for hospital overflow volume.
- Research Institutions:University-affiliated cyclotron facilities drive tracer development and clinical trial recruitment.
- Specialty Clinics:Cardiology and oncology-focused outpatient centers concentrate SPECT utilization for routine monitoring protocols.
Procurement gravity rests with Hospitals. Research Institutions are gaining influence fastest.
Application:
Clinical utility varies sharply by disease area, with oncology commanding premium tracer allocation and interpretation expertise.
- Oncology:Tumor characterization, staging, and treatment response monitoring drive PET-CT utilization across Canadian cancer centers. Health Canada's streamlined radiopharmaceutical approvals are truncating time-to-market for novel diagnostic tracers targeting specific malignancies.
- Cardiology:Myocardial perfusion imaging sustains SPECT system demand in community settings where technetium-99m availability remains reliable.
- Neurology:Amyloid and tau imaging for Alzheimer's disease represents emerging demand as provincial formularies expand coverage.
- Thyroid Disorders:Iodine-131 uptake studies and ablation therapies concentrate in specialized nuclear medicine departments with radioisotope handling licenses.
Oncology dominates current volume. Neurology applications are climbing the fastest.
Technology:
Digital reconstruction platforms and AI layers are rewriting performance specifications in provincial tender documents.
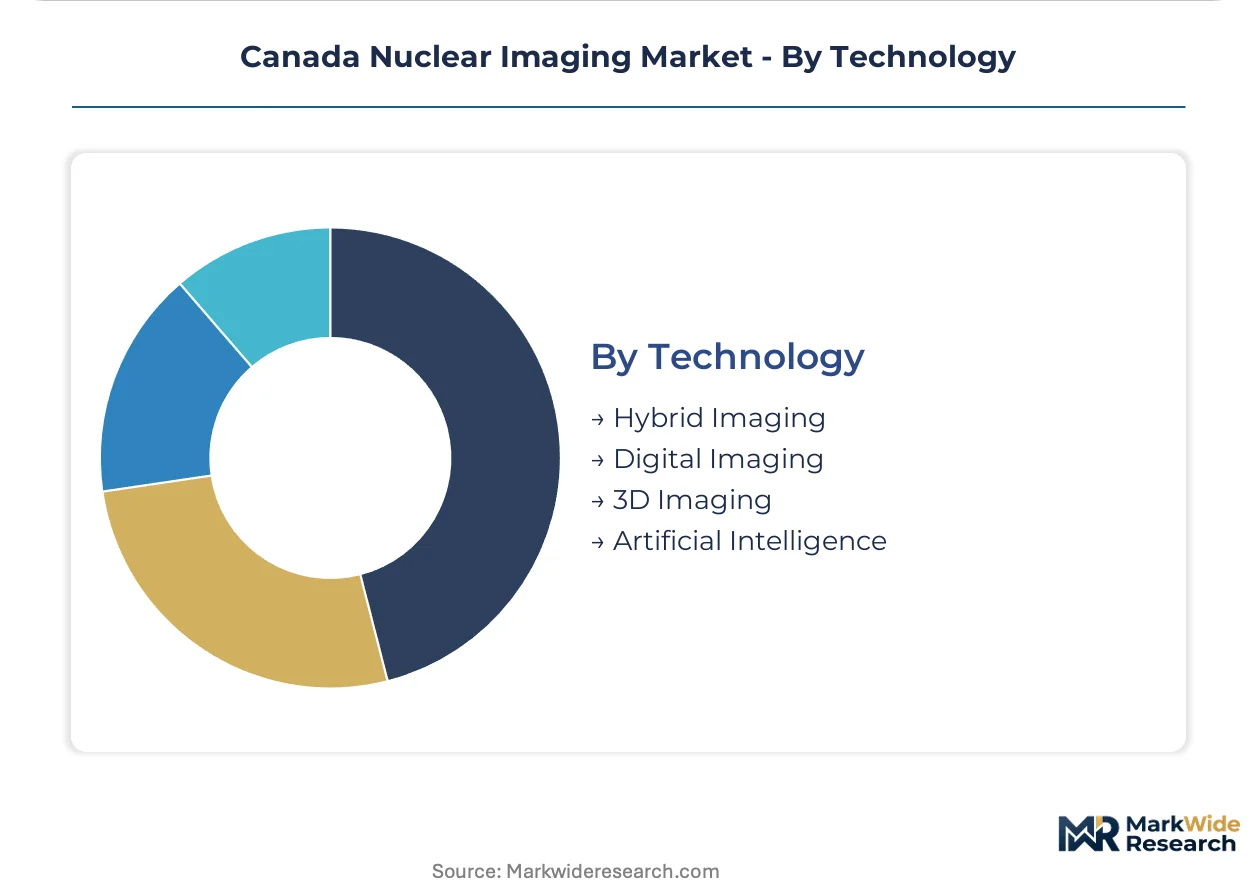
- Hybrid Imaging:PET-CT and PET-MRI fusion systems command premium placement in tertiary hospitals. Siemens Healthineers' digital photon-counting architecture penetrates replacement cycles at Toronto and Montreal sites as Ontario mandates dose-reduction capabilities.
- Artificial Intelligence:Deep learning algorithms automate lesion detection and attenuation correction, reducing interpretation bottlenecks in high-volume centers.
- Digital Imaging:Advanced reconstruction platforms enable dose reduction protocols that lower operational costs per scan.
- 3D Imaging:Tomographic reconstruction improves spatial resolution for small-lesion detection in oncology and neurology applications.
Hybrid Imaging holds installed base dominance. Artificial Intelligence represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's concentration of nuclear medicine technologists and radiopharmacists anchors Canada's imaging workforce, with specialized training programs at McMaster University and the University of Toronto feeding cyclotron facilities across the province.
Ontario
Cancer Care Ontario's imaging procurement frameworks standardize PET-CT specifications across regional health networks, compressing vendor negotiation leverage. Health Canada's streamlined radiopharmaceutical approvals truncate time-to-market for novel diagnostic tracers. Toronto's University Health Network and Sunnybrook Health Sciences Centre anchor the country's largest hybrid imaging installation base.
Quebec
Centralized radiopharmaceutical tendering displaces hospital-level contracting autonomy with multi-year supply agreements. The Canadian Nuclear Safety Commission's updated licensing protocols enable cyclotron network expansion across provincial jurisdictions. Montreal's McGill University Health Centre and CHUM consolidate PET-CT utilization for precision oncology staging.
British Columbia
Underpenetrated western markets present installation growth potential as provincial health authorities evaluate hybrid imaging procurement. Health Canada and the Canadian Nuclear Safety Commission jointly govern radiopharmaceutical manufacturing through licensing protocols. Vancouver Coastal Health's Lions Gate Hospital and Vancouver General Hospital concentrate SPECT capacity while PET-CT expansion proceeds.
Alberta
Decentralized tracer production models reduce transport logistics constraints for fluorine-18 compounds with short half-lives. Alberta Health Services' capital planning processes evaluate molecular imaging installations through centralized technology assessment. Calgary's Foothills Medical Centre and Edmonton's Cross Cancer Institute anchor diagnostic radiopharmaceutical utilization.
Canada Nuclear Imaging Market Competitive Environment
Top-tier vendors anchor the high-end PET-CT segment, while mid-tier specialists concentrate on SPECT replacements and gamma camera commoditization. The vendor base stratifies across three archetypes: integrated imaging conglomerates with cyclotron networks, equipment-only manufacturers competing on digital reconstruction platforms, and radiopharmaceutical pure-plays controlling tracer supply chains. Dominant competitive moves include strategic partnerships between equipment vendors and cyclotron operators, plus portfolio diversification into artificial intelligence layers for automated lesion detection.
Among North American radiopharmaceutical specialists, Jubilant Radiopharma and Lantheus Holdings represent the integrated supply chain archetype, anchoring domestic tracer production networks. Siemens Healthineers and GE Healthcare occupy positions within the premium-tier equipment segment, exemplifying the digital reconstruction platform strategy. These named entities illustrate how competitive positioning concentrates across distinct capability clusters rather than uniform market coverage.
| Leading Market Players |
|---|
| Jubilant Radiopharma |
| Canon Medical Systems |
| GE Healthcare |
| Lantheus Holdings |
| Bracco Imaging |
| Siemens Healthineers |
| BWXT Medical |
| Nordion |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Captive cyclotron networks anchor both supply security and pricing power across Canadian provinces, with Jubilant Radiopharma's integrated production-distribution infrastructure enabling premium tracer pricing while constraining third-party access. This vertical control compresses margins for independent imaging centers forced to absorb transport premiums for fluorine-18 compounds with sub-two-hour half-lives.
Pricing Analysis
Bundled service contracts dominate procurement, with Ontario's Cancer Care Ontario and Quebec's centralized tendering authorities negotiating multi-year agreements that wrap equipment, radiopharmaceutical supply, and maintenance into single-price arrangements. Price differentiation hinges on cyclotron proximity and Health Canada licensing tier, with rural hospitals facing 15-25% premiums for tracer delivery. Cost compression in SPECT segment intensifies as gamma camera commoditization accelerates replacement cycles. Community hospitals exhibit highest price sensitivity, while Toronto and Montreal academic centers prioritize quantitative metabolic mapping capabilities over unit economics.
Supply Chain Analysis
Regional distribution centers in Toronto, Montreal, and Vancouver form a hub-and-spoke pattern for radiopharmaceutical logistics, with cold-chain transport radiating to satellite hospitals within 150-kilometer catchment radii. Supply concentrates in Canada, USA, and Belgium for molybdenum-99 parent isotope production. Raw material dependencies include enriched uranium targets, specialized transport casks, and helium-3 for neutron detection. Single-source vulnerability runs through aging NRU reactor infrastructure at Chalk River. Distribution runs through provincial health authority tendering frameworks that consolidate hospital purchasing power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital PET reconstruction platforms and AI-augmented interpretation workflows, with dose-reduction protocols enabling premium pricing while lowering operational costs per scan.
For Market Incumbents: Anticipate regulatory modernization compressing tracer approval timelines by securing early Health Canada engagement for novel diagnostic compounds. Defend installed base position through backward integration into cyclotron capacity in British Columbia and Alberta, where provincial health authorities are evaluating decentralized production models. Prioritize Siemens Healthineers' digital photon-counting architecture as the reference standard in Ontario health technology assessment tenders. For New Entrants and Emerging Players: Telemedicine-integrated reporting platforms offer the lowest-friction entry vector, enabling remote interpretation services that bypass capital-intensive equipment procurement. White-space targets include amyloid imaging for Alzheimer's disease in neurology applications and community hospital SPECT replacement cycles in Saskatchewan and Manitoba. Pursue provincial radiopharmaceutical tendering participation through partnership with established cyclotron operators rather than greenfield facility investment. For Investors and Strategic Acquirers: Roll-up economics work for regional cyclotron networks because Health Canada's licensing protocols create regulatory moats that constrain new entrant supply capacity. Long-term viability favors integrated equipment-radiopharmaceutical platforms with recurring revenue streams over pure-play hardware vendors. Monitor British Columbia's hybrid imaging procurement decisions as the inflection signal for western market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Decentralized fluorine-18 production reduces transport logistics constraints for rural hospital access. |
| AI Companion Software Development | Deep learning algorithms for lesion detection differentiate vendor offerings in Ontario tender evaluations. |
| Digital PET Platform Migration | Photon-counting reconstruction enables dose-reduction protocols mandated by Cancer Care Ontario specifications. |
| Radiopharmaceutical Portfolio Diversification | Novel tau and amyloid tracers capture emerging neurology reimbursement expansion. |
| Provincial Tendering Participation | Multi-year supply agreements with Quebec's centralized purchasing displace hospital-level contracting autonomy. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down cyclotron capacity tracking forms the analytical core. Primary interviews with nuclear medicine technologists, radiopharmacists, hospital biomedical engineers, and provincial health authority procurement officers combined with secondary validation from Health Canada licensing databases, Canadian Nuclear Safety Commission regulatory filings, Cancer Care Ontario imaging frameworks, and Quebec centralized tendering records. Triangulation across equipment vendor shipment data and radiopharmaceutical production disclosures verified volume assumptions.
Input-output matrices map PET-CT installation rates against oncology staging protocol adoption, SPECT replacement cycles against technetium-99m supply reliability, and AI software penetration against interpretation bottleneck severity across the projection horizon. Segmentation dimensions include product type, end-user institution tier, clinical application, and technology layer. CAGRs derive from logistic adoption curves for hybrid imaging systems and linear extrapolation for mature gamma camera segments. Forecast inputs incorporate provincial health budget allocation patterns and Health Canada regulatory pipeline velocity.
The model assumes a particular technology adoption path; alternative pathways for PET-MRI fusion would alter the outlook if capital intensity barriers ease. Forecasts reflect documented assumptions regarding isotope supply continuity and provincial reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Global Refurbished Medical Imaging Equipment Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Italy Mammography Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market