
 Global Liquid Crystal Polymer (LCP) Films and Laminates Market | 2026-2036
Global Liquid Crystal Polymer (LCP) Films and Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Crystal Polymer (LCP) Films and Laminates Market Intelligence
Specialty resin distribution channels serving Asian electronics hubs is rewriting procurement geography for high-performance polymers. Celanese Corporation leverages backward integration into Vectra resin production to control raw material costs. Sumitomo Chemical Company anchors supply relationships with Japanese telecommunications equipment makers through dedicated film extrusion lines. Toray Industries Inc. dominates biaxial orientation technology for ultra-thin LCP substrates used in millimeter-wave applications.
Liquid Crystal Polymer films and laminates constitute thermotropic aromatic polyester materials processed into dimensionally stable sheets with dielectric constants below 3.0 and thermal decomposition thresholds exceeding 400 degrees Celsius, engineered primarily to enable high-frequency signal transmission with minimal loss in compact electronic assemblies. Coated films and metalized films capture widening margin pools as 5G infrastructure deployment demands precision surface metallization for antenna-in-package designs. Flexible printed circuits and semiconductor packaging applications lead volume consumption, while aerospace components represent a specialized segment where qualification timelines extend but contract values per kilogram run substantially higher.
The EPA governs per- and polyfluoroalkyl substance reporting that affects fluoropolymer alternatives including LCP formulations in US electronics manufacturing, while REACH registration requirements in the European Union impose full supply chain substance disclosure on polymer importers. China's GB standards administered by SAMR specify flame propagation limits for materials in telecommunications equipment, directly influencing laminate certification requirements for domestic 5G base station suppliers. Stakeholders must monitor evolving frequency allocations by national telecommunications regulators, as each spectrum band redesign demands recalibrated dielectric performance specifications that render existing film inventories technically obsolete.
Market Dynamics
Millimeter-wave spectrum allocation by national telecommunications regulators is forcing recalibration of dielectric specifications across LCP film inventories, rendering existing substrate certifications technically obsolete before depreciation cycles complete.
Growth Catalysts
- 5G Antenna Module Procurement:Electronics manufacturers in South Korea are expanding volume commitments for ultra-thin LCP films serving base station and handset antenna-in-package designs.
- REACH Compliance Disclosure:The European Union's tightening material disclosure requirements are accelerating supplier qualification timelines for polymer supply chains serving EU telecommunications equipment makers.
- Flexible Circuit Board Clustering:Fabrication concentration in China's Guangdong province sustains laminate consumption density unmatched by dispersed regional production.
Market Restraints
- Specialty Monomer Supply Concentration:Vectra-grade resin precursors rely on limited aromatic polyester production capacity concentrated in Japanese and US chemical complexes.
- Fluoropolymer Substitution Economics:Per- and polyfluoroalkyl substance alternatives face cost pressure from mature PTFE supply chains despite EPA reporting burdens on fluorinated formulations.
- Biaxial Orientation Equipment Scarcity:Ultra-thin substrate production requires proprietary tenter frame configurations with 18-24 month lead times from specialized machinery builders.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentive frameworks for telecommunications equipment create localized laminate demand as domestic 5G base station assembly scales.
- Aerospace Qualification Premium:Satellite and avionics applications extend contract values per kilogram substantially above consumer electronics benchmarks despite elongated certification timelines.
- Semiconductor Packaging Migration:Fan-out wafer-level packaging adoption in Taiwan and South Korea generates precision metallized film demand for redistribution layer substrates.
Industry Challenges
- Dielectric Characterization Talent Scarcity:Millimeter-wave testing expertise for thermal and electrical property validation at 28-39 GHz remains concentrated among Japanese and German metrology laboratories.
- Dual Certification Burden:SAMR flame propagation standards and FCC electromagnetic compatibility mandates impose parallel compliance tracks for suppliers serving both Chinese and North American telecommunications OEMs.
- Inventory Obsolescence Risk:Rapid spectrum band redesigns by national regulators strand film inventories calibrated to prior dielectric constant specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Crystal Polymer (LCP) Films and Laminates Market |
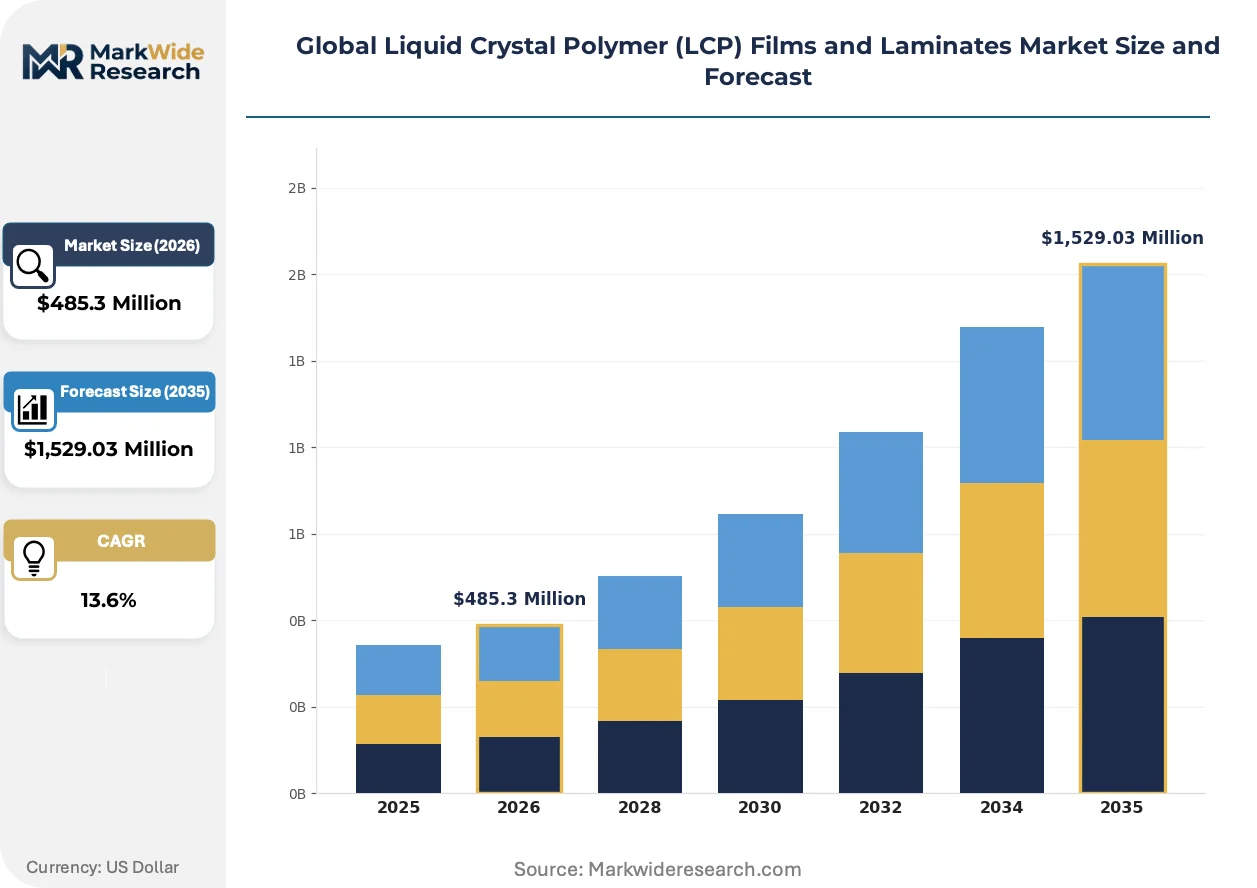
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,529.03 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncoated Films, Coated Films, Laminated Films, Printed Films, Metalized Films Application: High-Speed Circuits, Flexible Printed Circuits, Semiconductor Packaging, Medical Devices, Aerospace Components End User Industry: Consumer Electronics, Telecommunications, Automotive OEMs, Aerospace & Defense, Industrial Equipment Technology: Extrusion Coating, Cast Film Process, Orientation Technology, Surface Treatment, Lamination Techniques |
| Companies Covered | Celanese Corporation, Polyplastics Co. Ltd., Sumitomo Chemical Company, Kuraray Co. Ltd., Toray Industries Inc., Solvay, Rogers Corporation, Ueno Fine Chemicals Industry Ltd., Murata Manufacturing Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Crystal Polymer (LCP) Films and Laminates Market Strategic Shifts & Innovations
Process convergence between film extrusion and precision metallization is compressing substrate qualification timelines while fragmenting supplier capability requirements across historically distinct manufacturing steps.
Multi-layer LCP-copper laminate construction is hybridizing traditional flexible circuit fabrication with semiconductor packaging workflows. OSATs in Taiwan and South Korea are adopting these substrates for antenna-in-package modules at compressed development cycles. This convergence is collapsing the boundary between PCB substrate suppliers and wafer-level packaging material vendors.
ECHA's evolving REACH substance restrictions are extending disclosure obligations through polymer import supply chains into raw monomer sourcing. The regulation is forcing Japanese and US resin producers to document aromatic polyester precursor compositions previously treated as proprietary. European telecommunications equipment makers now require full substance inventories from Asian laminate converters.
Buyer consolidation among 5G infrastructure OEMs is compressing supplier negotiation leverage and extending payment terms. Tier-one telecommunications equipment manufacturers in South Korea and China are consolidating film procurement through designated converter relationships, displacing spot-market purchasing. This concentration is most visible in millimeter-wave antenna substrate contracts where technical qualification creates switching barriers.
Global Liquid Crystal Polymer (LCP) Films and Laminates Market Segmentation
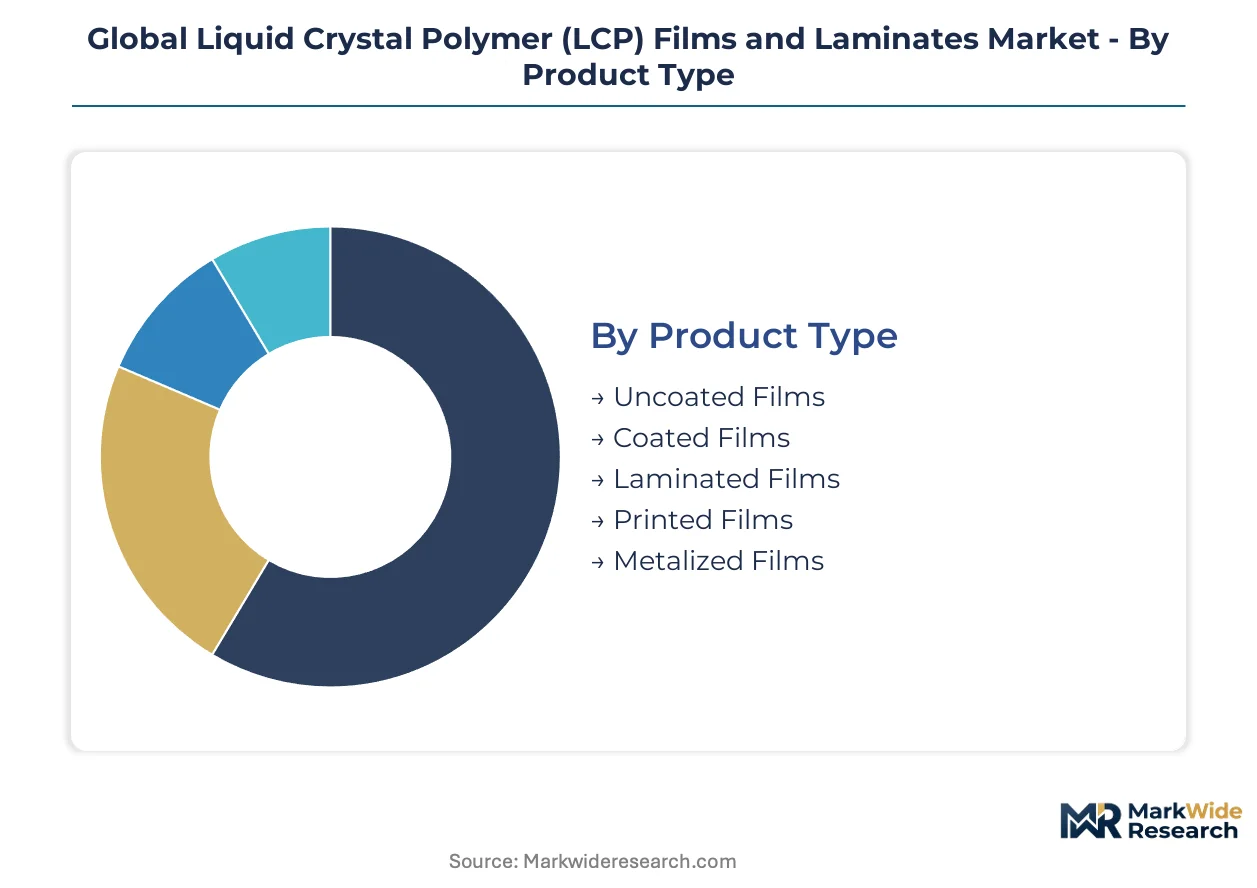
LCP films and laminates serve divergent performance requirements across electronics miniaturization, where dielectric precision and thermal stability command premium positioning. Segmentation reveals how substrate specifications align with end-use certification tiers and frequency band demands.
Product Type:
The use-case spectrum spans bare dielectric substrates through precision-metallized constructions for antenna integration.
- Uncoated Films:Base aromatic polyester substrates without surface modification, serving as feedstock for downstream converters. Demand concentrates in Japan and Germany where specialized coaters maintain captive film inventories for just-in-time metallization.
- Metalized Films:Sputtered or evaporated copper layers on ultra-thin LCP substrates enable antenna-in-package designs for 5G millimeter-wave modules. South Korean telecommunications equipment makers specify these constructions for base station phased arrays where signal loss tolerances tighten below 0.3 dB per centimeter.
- Coated Films:Surface-modified layers with adhesive or barrier properties for multi-material bonding.
- Laminated Films:Multi-layer constructions combining LCP with copper foil or polyimide for rigid-flex applications.
- Printed Films:Pattern-ready substrates with pre-applied conductive traces for rapid circuit prototyping.
Established volume favors uncoated films; emerging adoption favors metalized films.
Application:
Cost tier stratification separates commodity flexible circuits from qualification-heavy aerospace and medical segments.
- Flexible Printed Circuits:Single and multi-layer constructions for dynamic flexing applications in consumer electronics. China's Guangdong province fabrication clusters consume laminate volumes unmatched by dispersed regional production, driven by smartphone hinge module procurement from Shenzhen-based OEMs.
- Semiconductor Packaging:Redistribution layer substrates for fan-out wafer-level packaging in Taiwan and South Korea. OSATs specify ultra-low coefficient of thermal expansion films for chip-to-substrate interconnects where warpage control determines yield.
- High-Speed Circuits:Signal integrity-optimized substrates for data center interconnects.
- Medical Devices:Biocompatible laminates for implantable and diagnostic equipment with FDA and MDR qualification requirements.
- Aerospace Components:Radiation-resistant films for satellite systems where contract values per kilogram run substantially above consumer electronics benchmarks.
Volume concentration sits with flexible printed circuits; steepest expansion trajectory belongs to semiconductor packaging.
End User Industry:
Customer type differentiation separates high-volume electronics procurement from low-volume, high-specification aerospace contracting.
- Telecommunications:5G infrastructure OEMs in South Korea and China drive millimeter-wave substrate specifications through designated converter relationships. SAMR flame propagation standards and FCC electromagnetic compatibility mandates impose parallel compliance tracks for suppliers serving both markets.
- Consumer Electronics:Smartphone and wearable manufacturers specify ultra-thin laminates for compact antenna integration. Japanese resin producers anchor supply relationships through dedicated film extrusion lines serving this high-volume segment.
- Automotive OEMs:Radar and connectivity module substrates with AEC-Q200 qualification requirements.
- Aerospace & Defense:Satellite and avionics applications with elongated certification timelines but premium contract structures.
- Industrial Equipment:Process control and automation systems requiring chemical-resistant flexible circuits.
Procurement scale favors telecommunications; margin per kilogram favors aerospace applications.
Technology:
Supply concentration for proprietary equipment shapes competitive access to ultra-thin substrate production.
- Orientation Technology:Biaxial stretching processes controlling molecular alignment for dielectric anisotropy. Toray Industries dominates proprietary tenter frame configurations with 18-24 month lead times from specialized machinery builders in Japan and Germany.
- Extrusion Coating:Molten resin application onto carrier substrates for thickness uniformity below 25 micrometers. Celanese leverages backward integration into Vectra resin production to control raw material costs for this high-throughput process.
- Cast Film Process:Chill-roll solidification for thicker gauge films in industrial applications.
- Surface Treatment:Plasma or chemical etching for adhesion promotion prior to metallization.
- Lamination Techniques:Roll-to-roll bonding of dissimilar materials for hybrid substrate construction.
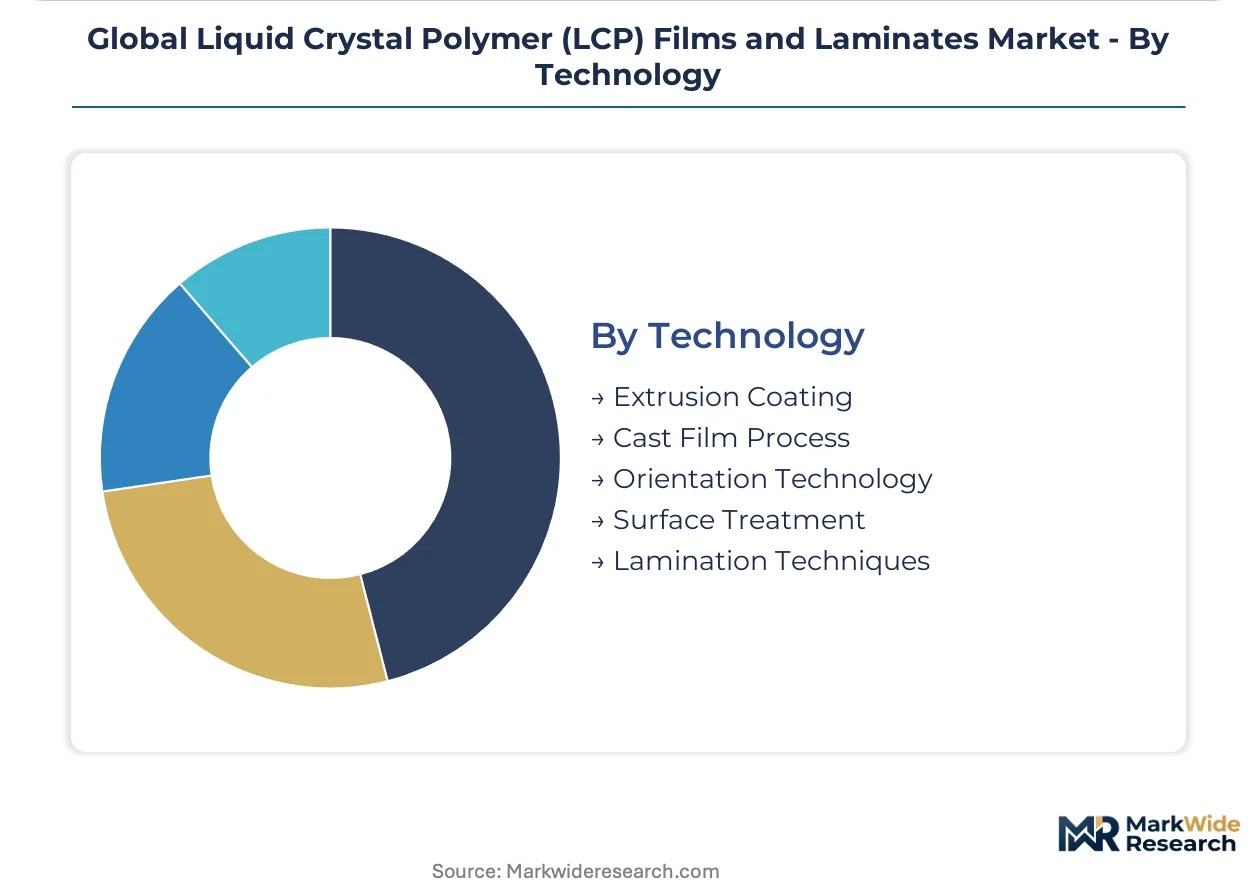
Process maturity favors extrusion coating; capability scarcity sits with orientation technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors East Asian polymer logistics, channeling aromatic polyester resins from Japanese chemical complexes to South Korean electronics manufacturers. This maritime infrastructure underwrites the region's dominance in millimeter-wave substrate procurement.
China
Guangdong province fabrication clusters drive laminate consumption density unmatched by dispersed regional production. SAMR administers GB standards specifying flame propagation limits for telecommunications equipment materials. Shenzhen-based OEMs procure ultra-thin laminates for smartphone hinge modules at volumes exceeding other Chinese cities.
South Korea
Electronics manufacturers expand volume commitments for ultra-thin LCP films serving base station and handset antenna-in-package designs. MFDS maintains medical device material regulations that create parallel compliance tracks for biocompatible laminate variants. Busan-Ulsan industrial corridor hosts dedicated converter relationships consolidating film procurement from designated suppliers.
Japan
METI oversees national technology roadmaps aligning aromatic polyester precursor production with 5G infrastructure export demand. JIS standards govern dimensional tolerances for ultra-thin substrates used in millimeter-wave applications. Nagoya chemical complexes concentrate Vectra-grade resin capacity with captive supply chains serving domestic film extrusion lines.
United States
EPA per- and polyfluoroalkyl substance reporting affects fluoropolymer alternatives including LCP formulations in domestic electronics manufacturing. FCC electromagnetic compatibility mandates impose certification requirements for antenna substrate suppliers serving North American telecommunications OEMs. Texas Gulf Coast petrochemical infrastructure supports aromatic polyester precursor imports from Asian resin producers.
Germany
ECHA REACH registration requirements impose full supply chain substance disclosure on polymer importers serving EU telecommunications equipment makers. KBA automotive regulations extend material qualification timelines for radar substrate applications in connected vehicle programs. Bavarian industrial regions host specialized coaters maintaining captive film inventories for just-in-time metallization.
Global Liquid Crystal Polymer (LCP) Films and Laminates Market Key Industry Players
On the supply side, the industry is consolidating around resin producers with backward integration into aromatic polyester precursor production and specialized film converters with proprietary orientation equipment. Three archetypes dominate: integrated resin-to-film manufacturers, dedicated extrusion specialists, and precision metallization service providers. Competitive dynamics center on capacity expansion for ultra-thin substrate production and strategic partnerships locking in antenna-in-package substrate qualification with 5G infrastructure OEMs.
Among Japanese chemical conglomerates, Toray Industries Inc., Sumitomo Chemical Company, and Kuraray Co. Ltd. occupy positions exemplifying the integrated resin-to-film archetype, leveraging captive precursor supply and proprietary tenter frame configurations. These companies anchor the premium substrate tier where technical qualification creates switching barriers against non-integrated competitors.
| Leading Market Players |
|---|
| Celanese Corporation |
| Polyplastics Co. Ltd. |
| Sumitomo Chemical Company |
| Kuraray Co. Ltd. |
| Toray Industries Inc. |
| Solvay |
| Rogers Corporation |
| Ueno Fine Chemicals Industry Ltd. |
| Murata Manufacturing Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Vectra-grade resin production concentrated in Nagoya chemical complexes and Texas Gulf Coast petrochemical infrastructure anchors margin capture at the precursor tier, forcing downstream film converters to absorb volatility while specialized metallization service providers extract premium positioning from antenna-in-package qualification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates millimeter-wave substrate certifications from flexible circuit laminates and uncoated film feedstock. Price differentiation rests on dielectric constant precision and SAMR flame propagation certification tiers. Cost compression in standard-grade laminates is intensifying because buyer consolidation among South Korean telecommunications OEMs extends payment terms. Consumer electronics procurement teams exhibit highest price sensitivity; aerospace satellite contractors accept substantial premiums for radiation-resistant qualifications.
Supply Chain Analysis
Hon Hai Precision Industry and Jabil Circuit hold concentrated capacity for antenna-in-package substrate lamination serving 5G infrastructure OEMs. Raw material flows draw from Japanese aromatic polyester precursor complexes, South Korean copper foil rolling mills, and German specialized machinery builders. Single-source vulnerability runs through proprietary tenter frame configurations with extended lead times from Japanese and German equipment suppliers. Distribution runs through designated converter relationships consolidating procurement from tier-one telecommunications equipment manufacturers in Busan-Ulsan and Shenzhen industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millimeter-wave testing expertise at 28-39 GHz remains locked within Japanese and German metrology laboratories, constraining competitive entry for substrate qualification and amplifying returns for incumbents with captive validation capabilities.
For Market Incumbents: Harden supply security through backward integration into Vectra resin production or captive precursor offtake agreements with Nagoya chemical complexes. Defend against fluoropolymer substitution by accelerating SAMR dual-certification pipelines that lock in Chinese 5G base station procurement. Channel control through designated converter relationships in the Busan-Ulsan corridor creates switching barriers against non-integrated competitors. For New Entrants and Emerging Players: Build out precision metallization capabilities targeting India's PLI scheme-aligned telecommunications equipment assembly, where domestic 5G base station scaling outpaces localized laminate supply. Focus initial qualification efforts on medical device biocompatible variants under MFDS regulations, a segment with elongated timelines but lower incumbent saturation than millimeter-wave antenna substrates. Partner with OSATs in Taiwan for fan-out wafer-level packaging redistribution layer substrate development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision coaters in Bavarian industrial regions holding captive film inventories for just-in-time metallization. Long-term viability hinges on exposure to semiconductor packaging migration rather than flexible circuit commoditization. Monitor ECHA REACH substance restriction evolution as an inflection signal; extended disclosure obligations through polymer import supply chains will force portfolio company restructuring or create distressed acquisition opportunities among non-compliant Asian laminate converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Celanese Corporation's captive Vectra supply controls raw material cost volatility for extrusion coating operations. |
| Millimeter-Wave Testing Laboratory Acquisition | Japanese and German metrology capability scarcity limits substrate qualification throughput for antenna-in-package designs. |
| Dual Certification Pipeline Investment | Parallel SAMR and FCC tracks unlock procurement access to both Chinese and North American telecommunications OEMs. |
| Precision Metallization Capacity Expansion | South Korean base station phased array demand specifies sputtered copper layers with signal loss tolerances below 0.3 dB per centimeter. |
| Aerospace Qualification Program | Satellite and avionics contract values per kilogram substantially exceed consumer electronics benchmarks despite elongated timelines. |
Research Approach
A standing panel of resin plant managers, telecommunications equipment procurement leads, flexible circuit fabrication engineers, and metrology laboratory directors provided ongoing calibration against secondary validation from customs trade data, SEC 10-K filings by listed chemical conglomerates, and JIS standards documentation. Bottom-up volume triangulation across Guangdong province fabrication clusters converged with top-down value estimation from aromatic polyester precursor production capacity.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated 5G infrastructure deployment assumptions over the analysis window. Segmentation dimensions modeled include product type, application tier, end-user industry, and technology process maturity. CAGRs derived from elasticity-adjusted volume forecasts incorporating dielectric specification recalibration frequency and inventory obsolescence risk curves specific to millimeter-wave spectrum allocation cycles.
Stress conditions across raw material cost volatility, REACH disclosure timeline acceleration, and biaxial orientation equipment lead time extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding telecommunications OEM consolidation trajectories and polymer supply chain regulatory evolution. Quarterly review of national spectrum allocation announcements and ECHA substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Alginate Films Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Jesmonite Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Non-Semiconductor Neon Market